
 Body Jewelry Market | 2026-2036
Body Jewelry Market Size, Share, and Industry Trends Forecast 2026-2036
Body Jewelry Market Insights
EU REACH nickel release restrictions is recalibrating material sourcing across the body jewelry supply chain. Body Vision Los Angeles (BVLA) anchors premium positioning through solid gold and platinum offerings manufactured in its Los Angeles facility. LeRoi leverages domestic titanium production to sustain compliance with evolving dermatological safety standards. Anatometal specializes in threadless implant-grade titanium systems, differentiating through precision machining capabilities.
Body jewelry comprises decorative and functional ornaments designed for insertion into pierced dermal tissue, typically fabricated from biocompatible metals meeting ASTM F136 implant specifications or precious alloys with defined purity grades. Its primary commercial purpose spans aesthetic self-expression, cultural identity signaling, and professional piercing aftercare. Gold and titanium materials command premium margin pools due to hypoallergenic certification requirements and extended wear durability. Stainless steel occupies volume leadership in entry-level segments, while minimalist styling is gaining fastest among professional demographics seeking workplace-appropriate designs.
FDA biocompatibility guidance, EU REACH nickel restrictions, and ASTM F136 implant standards collectively shape material eligibility and market access thresholds for body jewelry manufacturers. The EU Green Deal chemicals strategy is accelerating substitution away from cadmium-plated alloys and certain acrylic formulations. Stakeholders must monitor evolving dermatological patch-test data and regional substance restriction lists to anticipate the next wave of material compliance requirements.
Market Dynamics
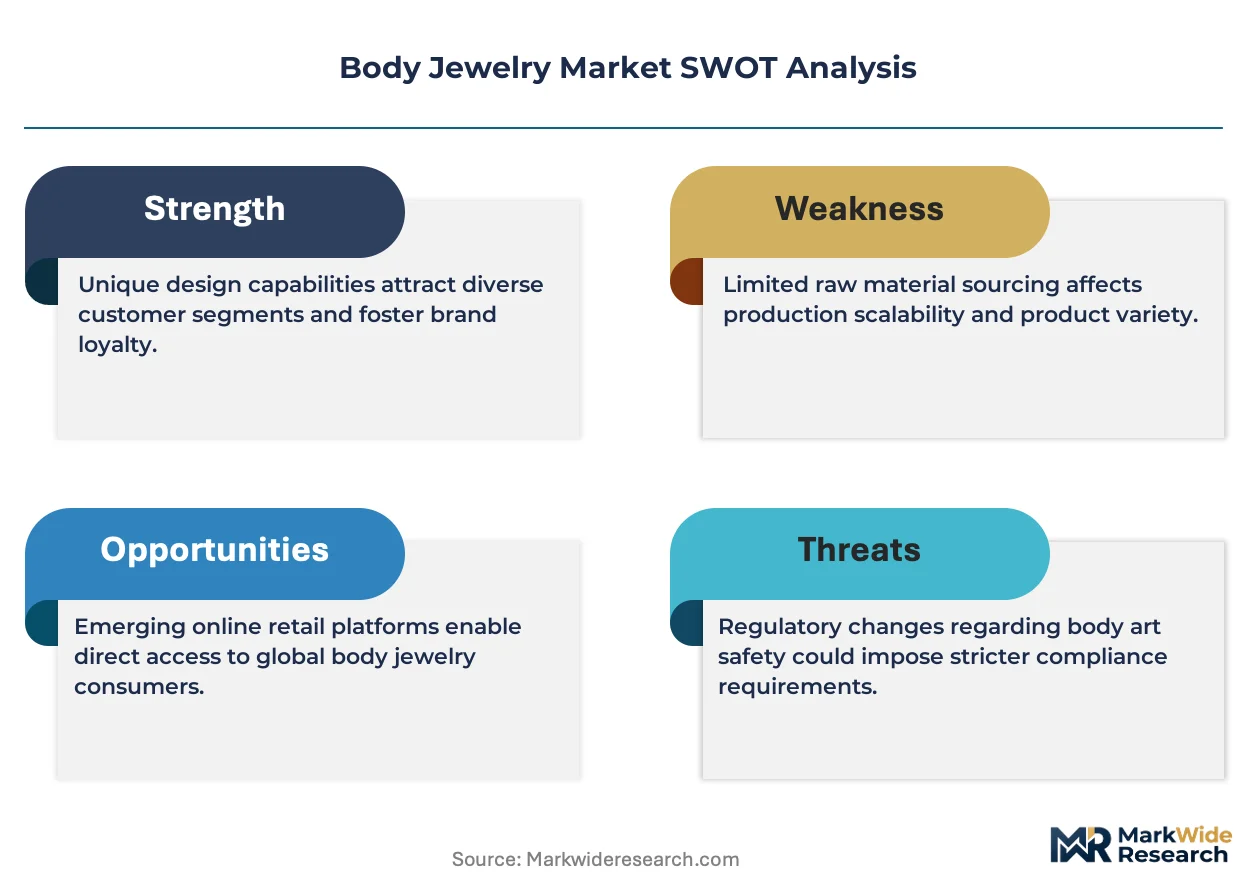
EU REACH nickel release thresholds are forcing material recalibration across the body jewelry supply chain, compressing margins for stainless steel producers while elevating titanium and solid gold sourcing premiums.
Growth Catalysts
- Gen Z and millennial consumer expansion:Professional piercing studios in California and New York metropolitan clusters report sustained demand for ASTM F136 implant-grade titanium systems.
- REACH compliance upgrades:ECHA's tightening nickel restrictions are accelerating substitution toward hypoallergenic alloys, expanding addressable market for certified biocompatible materials.
- Minimalist styling adoption:Workplace-appropriate designs are penetrating professional demographics previously excluded from visible body jewelry categories.
Market Restraints
- Titanium supply concentration:Domestic production capacity limits in the United States create dependency on specialized metallurgical suppliers with extended lead times.
- Precious metal input volatility:Gold and platinum price fluctuations compress margin pools for solid gold product lines manufactured in Los Angeles facilities.
- Technical limitation in acrylics:Certain acrylic formulations face substitution pressure under EU Green Deal chemicals strategy restrictions on cadmium-plated alternatives.
Strategic Opportunities
- Underpenetrated professional demographics:Healthcare and corporate sectors in the United States represent untapped demand for discreet, certification-backed implant-grade designs.
- Regulatory tailwind from FDA biocompatibility guidance:Evolving dermatological safety standards create competitive moats for manufacturers with pre-validated ASTM F136 documentation.
- Distribution innovation through direct-to-piercer channels:Bypassing traditional wholesale networks allows premium manufacturers to capture margin and control brand positioning.
Industry Challenges
- Precision machining talent scarcity:Threadless implant-grade titanium systems require specialized CNC programming expertise concentrated in limited geographic clusters.
- Certification timeline compression:ASTM F136 compliance documentation and dermatological patch-test validation create working capital intensity for new product launches.
- Supply chain reconfiguration friction:REACH-driven material substitution disrupts established supplier relationships and requires requalification of alloy sources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Body Jewelry Market |
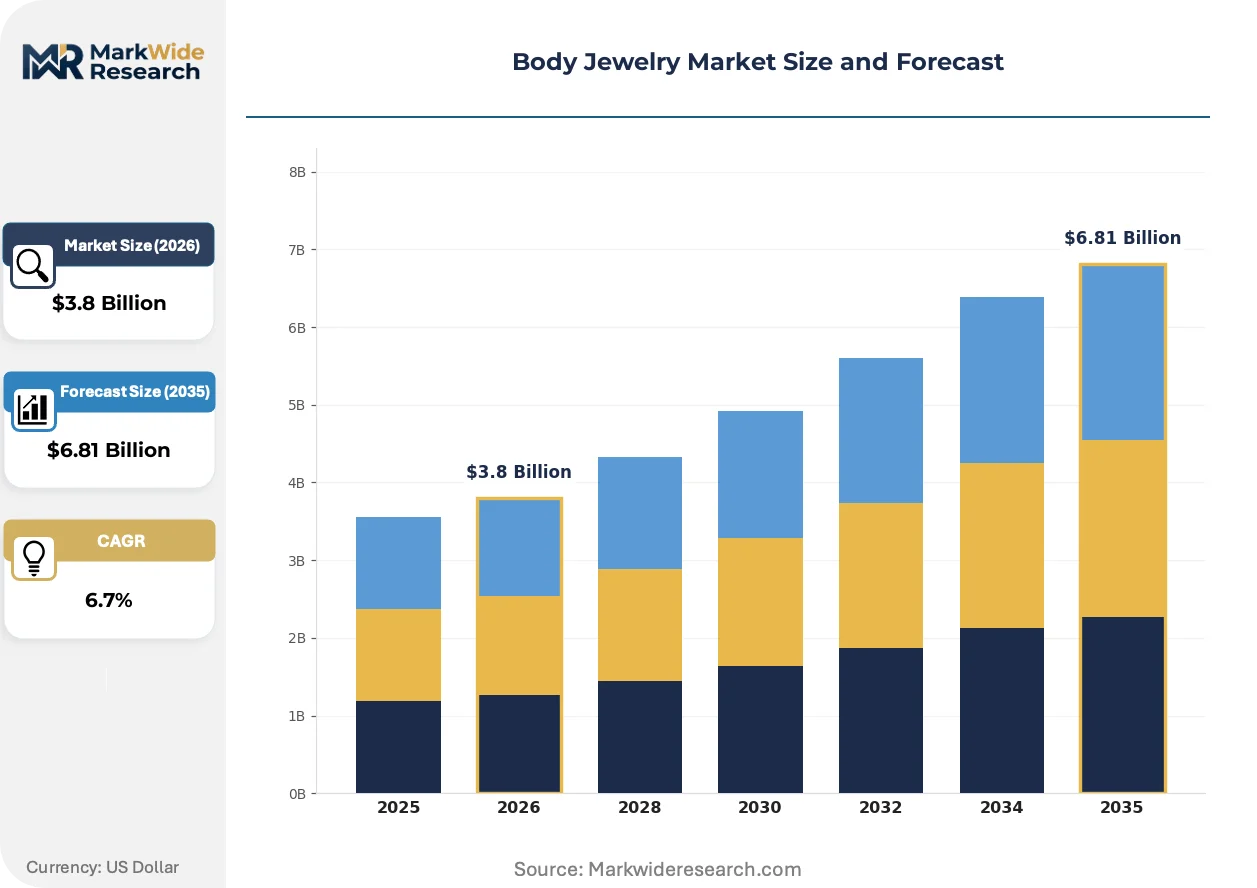
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rings, Barbells, Studs, Hoops Material: Gold, Silver, Stainless Steel, Acrylic Style: Gothic, Bohemian, Minimalist, Vintage End User: Women, Men, Teenagers, Others |
| Companies Covered | Body Vision Los Angeles (BVLA), LeRoi, Anatometal, Maria Tash, Invictus Body Jewelry, NeoMetal, Industrial Strength, Salamander Jewelry Factory, BodyCandy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Body Jewelry Market Trends and Innovations
Threadless jewelry systems are displacing traditional threaded designs across professional piercing studios, compressing aftercare complications while enabling faster installation protocols.
Implant-grade titanium is modularizing product architecture across the premium segment. Professional piercers in California and New York metropolitan clusters are adopting interchangeable end-and-post configurations at accelerating rates. This standardization is compressing inventory carrying costs for studios while enabling consumers to mix material grades across a single post base.
ECHA's REACH nickel restriction amendments are recalibrating material eligibility thresholds across European market access. Manufacturers serving EU distribution channels must revalidate alloy compositions against descending release limits. Solid gold and platinum offerings manufactured in domestic United States facilities are capturing displaced stainless steel volume as dermatological safety certification becomes non-negotiable.
Certification-driven preference shifts are restructuring procurement patterns among professional piercing studios. ASTM F136 documentation is displacing uncertified titanium claims as the primary vendor selection criterion. This behavioral change is most visible in United States metropolitan clusters where liability exposure and consumer litigation risk concentrate studio decision-making toward documented biocompatibility standards.
Body Jewelry Market Segmentation
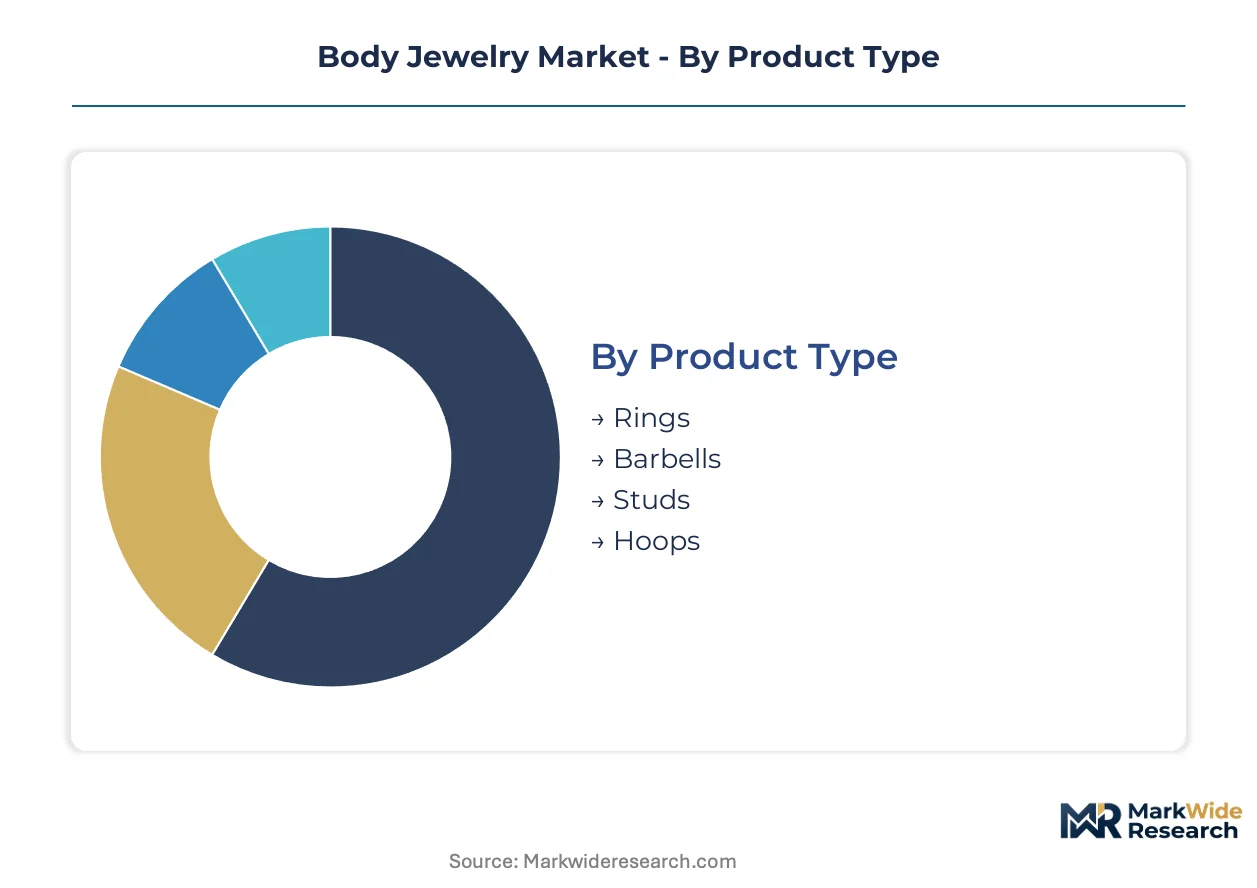
Material certification and piercing location dictate procurement patterns across body jewelry categories. Professional studios segment inventory by biocompatibility tier rather than aesthetic alone, reshaping how manufacturers align product architectures with end-use risk profiles.
Product Type:
Healing duration and placement vulnerability determine studio purchasing priorities across form factors.
- Rings:Continuous loop designs fabricated in ASTM F136 titanium or solid gold alloys for nasal, ear, and septum placements. California and New York metropolitan clusters report strongest demand for seamless hinge mechanisms that minimize tissue trauma during installation.
- Barbells:Straight and curved shafts with fixed or removable beads, dominating tongue, eyebrow, and industrial ear piercings. Threadless implant-grade systems from Los Angeles manufacturers are displacing traditional externally threaded variants in professional channels due to reduced aftercare complications.
- Studs:Post-and-backing configurations optimized for initial lobe and cartilage piercings.
- Hoops:Circular designs spanning captive bead rings to seamless segments for helix and daith applications.
Barbells lead on scale; threadless ring variants lead on momentum.
Material:
Regulatory compliance thresholds stratify sourcing costs and margin structures.
- Gold:14k and 18k alloys manufactured in domestic United States facilities, commanding premium positioning through hypoallergenic certification and nickel-free guarantees. REACH-driven substitution away from stainless steel is expanding addressable market for solid gold lines in European distribution channels.
- Titanium:ASTM F136 implant-grade specification dominating professional studio procurement, with threadless system architectures enabling modular end-and-post configurations. Domestic United States production capacity constraints create supply concentration risk for specialized metallurgical suppliers.
- Silver:Sterling alloys occupying mid-tier positioning between entry steel and premium titanium.
- Stainless Steel:Volume leadership in entry-level segments facing margin compression from descending nickel release thresholds.
- Acrylic:Polymer formulations facing substitution pressure under EU Green Deal chemicals strategy restrictions.
Stainless steel retains volume dominance; titanium climbs the fastest on certification tailwinds.
Style:
Workplace visibility constraints are rebalancing aesthetic preference distributions.
- Minimalist:Clean lines and reduced visual mass enabling professional demographic penetration previously excluded from visible body jewelry. Healthcare and corporate sectors in United States metropolitan clusters represent expanding demand for discreet, certification-backed implant-grade designs.
- Gothic:Dark metal finishes and ornate detailing concentrated in alternative fashion channels.
- Bohemian:Organic forms and mixed material layering targeting festival and lifestyle retail.
- Vintage:Antique-inspired motifs and filigree work appealing to heritage aesthetic segments.
Minimalist styling gains share fastest; Gothic retains niche loyalty in alternative channels.
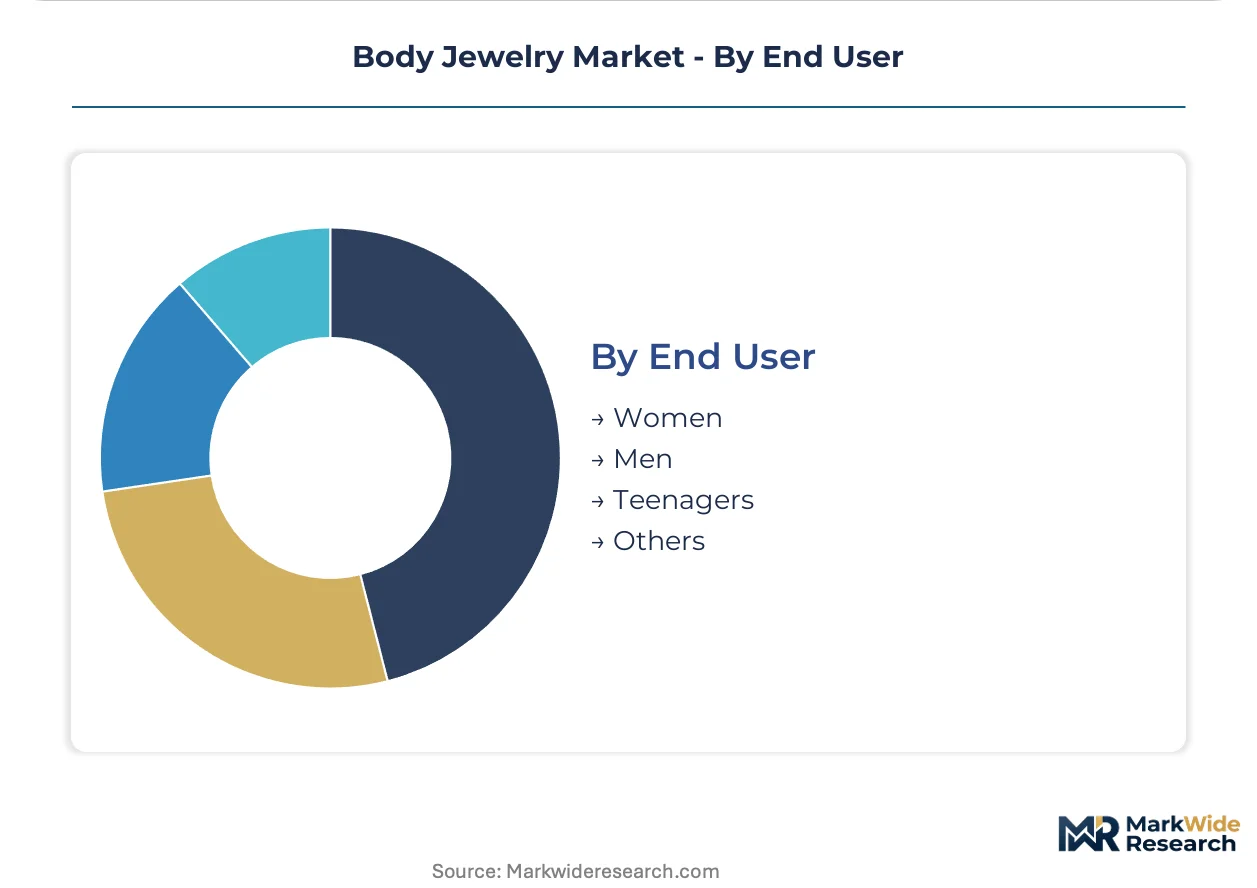
End User:
Piercing frequency and aftercare compliance vary sharply across demographic cohorts.
- Women:Multiple placement preferences spanning ear curation, nose, and navel segments, driving highest per-capita spend on modular threadless systems. United States professional studios report strongest repeat purchase rates from female clients seeking interchangeable end configurations.
- Teenagers:Initial piercing cohort with elevated aftercare support requirements and price sensitivity, concentrating demand in entry-level titanium and parental-accompanied studio visits.
- Men:Concentrated demand in ear and nasal placements with emerging interest in discreet workplace-appropriate designs.
- Others:Non-binary and gender-diverse consumers seeking inclusive sizing and neutral styling architectures.
Women lead on scale; teenagers lead on entry-point volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Body jewelry manufacturing traces its commercial lineage to Los Angeles and New York metropolitan clusters, where professional piercing studios first institutionalized ASTM F136 implant-grade standards in the 1990s. This certification-driven foundation spread to European markets through REACH compliance requirements, establishing regional specialization patterns that persist today.
United States
California and New York anchor domestic demand through concentrated professional piercing studio networks. FDA biocompatibility guidance shapes material eligibility for interstate commerce, particularly for titanium and solid gold imports. Los Angeles manufacturers supply threadless implant-grade systems to studios nationwide, with BVLA and Anatometal anchoring premium production capacity in the metropolitan cluster.
Germany
Professional piercing studios in Berlin and Munich drive premium-tier procurement of nickel-free alloys. ECHA REACH nickel release restrictions enforce descending thresholds that disqualify traditional stainless steel formulations. North Rhine-Westphalia's precision machining suppliers provide CNC capabilities for threadless jewelry architectures serving EU distribution channels.
United Kingdom
London's professional studio concentration sustains demand for ASTM F136-certified titanium systems. Trading Standards Institute enforcement of nickel safety regulations filters entry-level imports from non-compliant sources. The Southeast England logistics corridor handles re-export distribution to Commonwealth markets with aligned dermatological safety standards.
Japan
Tokyo and Osaka metropolitan areas host specialized piercing studios with exacting material documentation requirements. METI consumer safety standards parallel ASTM F136 specifications for implant-grade titanium acceptance. Kansai region fabricators supply precision-machined components for domestic threadless system assembly.
Australia
Sydney and Melbourne professional studios prioritize TGA-aligned biocompatibility certification for imported titanium and gold jewelry. State-level consumer protection regulations in New South Wales and Victoria enforce nickel release testing parallel to REACH thresholds. The country's piercing professional association maintains a preferred supplier registry favoring documented ASTM F136 compliance.
Body Jewelry Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-tier stratification, with ASTM F136 documentation separating implant-grade specialists from uncertified commodity suppliers. The vendor base concentrates among domestic United States fabricators and specialized European precision machinists, with limited Asian penetration in certified premium tiers. Three strategic archetypes dominate: Los Angeles-based solid gold specialists, domestic titanium implant-grade manufacturers, and European REACH-compliant precision engineers. Capacity expansion and direct-to-piercer distribution channel development constitute the dominant competitive moves, compressing traditional wholesale margin capture.
Among Los Angeles-based fabricators, Body Vision Los Angeles and Anatometal occupy positions within the premium certification tier, with LeRoi representing the domestic titanium production archetype. These entities exemplify the geographic clustering of ASTM F136-compliant manufacturing capacity, anchoring supply relationships with professional piercing studios that prioritize documented biocompatibility standards over price-based procurement.
| Leading Market Players |
|---|
| Body Vision Los Angeles (BVLA) |
| LeRoi |
| Anatometal |
| Maria Tash |
| Invictus Body Jewelry |
| NeoMetal |
| Industrial Strength |
| Salamander Jewelry Factory |
| BodyCandy |
| Others |
Pricing and Supply Chain Analysis
Captive titanium sourcing in domestic United States facilities anchors premium pricing power for ASTM F136-certified manufacturers, while outsourced precious metal procurement exposes solid gold producers to London Bullion Market Association price volatility. This integration asymmetry separates implant-grade specialists from commodity stainless steel suppliers facing REACH-driven margin compression.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and material pedigree. Price differentiation hinges on ASTM F136 documentation validity and nickel-release testing compliance, with European distribution channels commanding sourcing premiums. Cost compression in entry-level stainless steel tiers is intensifying because ECHA threshold tightening disqualifies legacy alloy formulations. Teenage first-time buyers exhibit highest price sensitivity; professional studio procurement committees prioritize certification-backed suppliers regardless of unit cost.
Supply Chain Analysis
Implant-grade titanium feedstock draws from domestic United States metallurgical suppliers, Italian precision-forging specialists, and Japanese electron-beam melting facilities. Raw material dependencies center on aerospace-grade titanium sponge, 14k and 18k gold bullion, and REACH-compliant nickel-free master alloys. Single-source vulnerability concentrates in domestic United States electron-beam melting capacity for ASTM F136-compliant bar stock. Distribution runs through direct-to-piercer channels, bypassing traditional wholesale networks and capturing margin at the studio level.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through regulatory ratcheting, with ECHA's descending nickel release thresholds converting compliance investment into durable competitive moats.
For Market Incumbents: Anticipate REACH alignment spreading to North American jurisdictions by pre-validating ASTM F136 documentation for cross-border recognition. Consolidate supplier relationships with domestic titanium producers before capacity constraints harden into allocation rationing. Certification investment in dermatological patch-test libraries represents the priority defensive lever against emerging low-cost Asian entrants. For New Entrants and Emerging Players: Threadless system architecture expertise offers entry into underpenetrated healthcare and corporate professional demographics seeking discreet implant-grade designs. White-space concentration sits in United States metropolitan clusters where liability exposure drives studio procurement toward documented biocompatibility standards. A piercer-education-first go-to-market angle builds brand credibility before product placement. For Investors and Strategic Acquirers: Roll-up economics work for precision-machining specialists with captive ASTM F136 documentation because certification timelines create acquisition premiums unavailable to de novo entrants. Target mid-cap fabricators with established Los Angeles or New York metropolitan cluster production footprints and pre-qualified European distribution channels. Watch ECHA enforcement intensity as the signal for accelerated substitution-driven volume inflection.| Strategic Initiative | Industry Significance |
|---|---|
| ASTM F136 Certification Investment | Documentation validity separates premium implant-grade suppliers from uncertified commodity competitors in professional studio procurement. |
| Direct-to-Piercer Channel Development | Bypassing wholesale networks captures margin and enables brand positioning control with California and New York metropolitan clusters. |
| Backward Integration into Titanium Sourcing | Captive supply of electron-beam melted bar stock insulates production from domestic United States metallurgical capacity constraints. |
| REACH Compliance Anticipation | Pre-validation against descending nickel release thresholds secures European market access before regulatory disqualification spreads. |
| Threadless System Architecture R&D | Modular end-and-post configurations reduce studio inventory carrying costs and accelerate consumer repeat purchase cycles. |
Research Methodology
Multiple input streams — professional piercing studio procurement managers, precision machining operations directors, and dermatological safety consultants — were reconciled against customs records, ASTM F136 certification registries, and ECHA substance restriction amendments. Secondary validation drew from FDA biocompatibility guidance documents, EU REACH nickel release testing protocols, and United States metropolitan cluster studio association membership directories. Bottom-up studio inventory analysis and top-down material flow triangulation anchored volume estimates across the projection horizon.
Data-stream reconciliation applied segmentation modeling across material certification tier, piercing placement category, and end-user demographic cohort. CAGRs were derived from install-base expansion rates and replacement cycle compression in professional studio channels. Industry-specific forecast inputs incorporated ECHA enforcement trajectory scenarios and domestic United States titanium production capacity utilization trends.
The model holds under stable regulatory enforcement intensity; deviation in ECHA nickel threshold acceleration or FDA biocompatibility guidance expansion would shift substitution timelines and certification premium durability. A small set of named triggers — REACH alignment in North American jurisdictions, titanium sponge export restrictions, and professional studio liability litigation frequency — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
3D Printing Jewelry Service Market
Jewelry
Pearl Jewelry Market
Jewelry
Diamond Jewelry Market
Jewelry
Demi-Fine Jewelry Market
Jewelry
Germany Luxury Jewelry Market
Jewelry
Colorful Gold Jewelry Market
Jewelry
Luxury Jewelry Market
Jewelry
Latin America Jewelry Market
Jewelry
Japan Jewellery Market
Jewelry
Jewellery Market
Jewelry
Global Costume Jewelry Market
Jewelry
Crystal Bracelets Market
Jewelry
Global Gems and Jewelry Market
Jewelry
Europe Luxury Jewelry Market
Jewelry
China Jewellery Market
Jewelry
Customized Jewelry Market