
 Europe Luxury Jewelry Market | 2026-2036
Europe Luxury Jewelry Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Luxury Jewelry Market Insights
Artisanal manufacturing is fragmenting across distributed ateliers and digital design platforms, replacing centralized production models. Cartier anchors its competitive edge through vertical control over gemological R&D and proprietary setting techniques. Boucheron differentiates via Paris-based haute joaillerie craftsmanship that resists mass replication. Van Cleef & Arpels leverages patented Mystery Set technology to sustain pricing power in ultra-high-end parures.
Europe luxury jewelry encompasses precious metal and gemstone adornments crafted to exceptional standards of design, metallurgical purity, and stone quality, typically employing 18-karat gold, platinum, or ethically sourced colored gemstones for personal ornamentation and wealth preservation. Necklaces and rings command the deepest margin pools due to stone intensity and ceremonial purchase occasions, while bracelets compete on stackable versatility and repeat purchase frequency. Gold dominates material value flows, though platinum gains traction among collectors seeking rarity differentiation beyond conventional yellow metal allocations.
REACH and the EU Green Deal impose traceability mandates on precious metal and gemstone supply chains, compelling maisons to document provenance from mine to finished piece. ECHA's evolving restrictions on hazardous substances in manufacturing processes shape finishing techniques and alloy compositions permitted within the single market. Stakeholders must monitor how CSRD disclosure requirements will expose sourcing practices to institutional and retail scrutiny alike.
Market Dynamics
REACH and the EU Green Deal are forcing European maisons to reconstruct supply chains from mine to atelier, with traceability mandates now determining competitive viability rather than optional differentiation.
Growth Catalysts
- High-Net-Worth Individual demand:Wealth concentration across Germany, France, and Switzerland is expanding the addressable base for haute joaillerie pieces above six-figure price points.
- CSRD disclosure requirements:Mandatory sustainability reporting is accelerating investment in blockchain-enabled provenance systems that command institutional buyer premiums.
- Heritage atelier clustering:Paris and Geneva concentrate irreplaceable craft capabilities that create natural barriers against mass-market replication.
Market Restraints
- Conflict mineral compliance costs:EU due diligence rules impose documentation burdens that disproportionately strain smaller independent workshops lacking dedicated compliance infrastructure.
- Gemstone supply concentration:Rough diamond and colored stone sourcing remains concentrated in limited jurisdictions, exposing margins to geopolitical disruption.
- Platinum price volatility:Industrial demand fluctuations for the metal create input cost instability that complicates long-term pricing for platinum-forward collections.
Strategic Opportunities
- Central and Eastern Europe penetration:Warsaw, Prague, and Budapest exhibit rising ultra-high-net-worth density with underdeveloped flagship retail presence relative to Western capitals.
- Digital-native secondary marketplaces:Certified pre-owned platforms are capturing younger collectors seeking vintage pieces with documented provenance at accessible entry points.
- EU circular economy incentives:Ecodesign for Sustainable Products Regulation frameworks reward recycled precious metal integration with streamlined market access.
Industry Challenges
- Master craftsperson succession:Traditional stone-setting and hand-engraving skills face generational transfer gaps as training periods extend beyond typical career-entry timelines.
- Multi-jurisdictional certification lag:Harmonization delays between national hallmarking authorities fragment product launch timelines across EU member states.
- Legacy inventory valuation:Pre-traceability-era stock requires expensive retrospective documentation to meet current retail disclosure standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Luxury Jewelry Market |
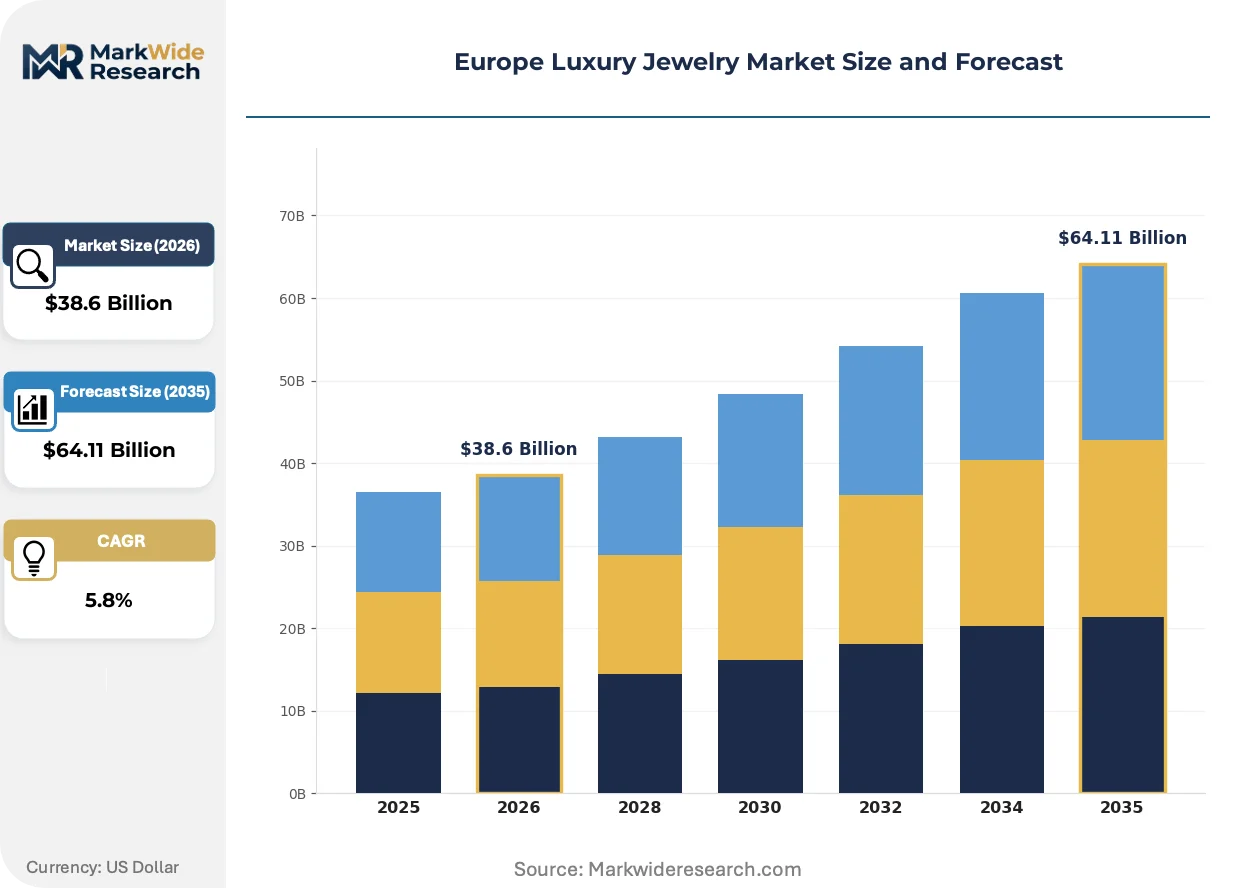
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $64.11 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Necklaces, Bracelets, Earrings, Rings Material: Gold, Platinum, Silver, Gemstones Customer Type: Affluent Consumers, High-Net-Worth Individuals, Collectors, Enthusiasts Sales Channel: Online Retail, Specialty Stores, Department Stores, Auction Houses |
| Companies Covered | Boucheron, Hermès, Cartier, Graff, Buccellati, Bulgari, Chopard, Louis Vuitton, Van Cleef & Arpels, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Luxury Jewelry Market Trends and Innovations
Blockchain-based provenance verification is restructuring how European maisons authenticate heritage and justify price premiums, compressing the information asymmetry that previously separated informed collectors from casual buyers.
Laser-inscribed diamond identification is rendering obsolete traditional paper-based certification that carried forgery vulnerabilities and transfer friction. Collectors across Geneva and London are now demanding microscopic engraving tied to immutable digital records. This shift is compressing resale value spreads between documented and undocumented stones.
REACH substance restrictions are forcing reformulation of traditional finishing alloys and surface treatments. ECHA's evolving hazardous substance lists are eliminating certain patina techniques and mercury-based gilding processes. Italian and French manufacturers are accelerating investment in electrolytic alternatives to maintain color range compliance.
Direct-to-collector digital channels are displacing traditional wholesale relationships with multi-brand retailers. Maisons are building proprietary client portals that bypass conventional distribution markups while capturing behavioral data for bespoke commissioning. This pattern is most visible in Scandinavian markets where digital purchasing comfort among ultra-high-net-worth demographics exceeds Southern European counterparts.
Europe Luxury Jewelry Market Segmentation
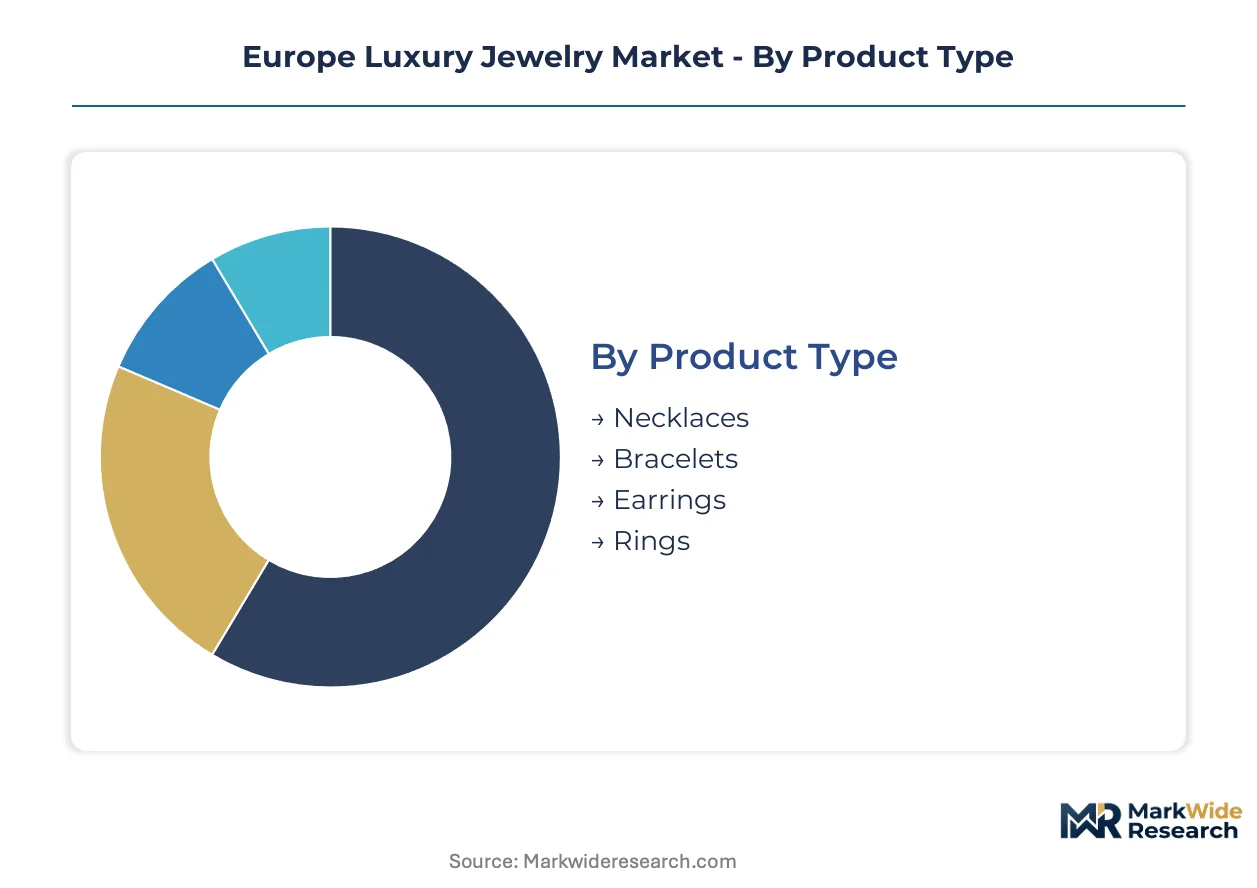
Segmentation reveals how European maisons allocate craft capacity and retail investment across distinct demand profiles. Material purity thresholds, ceremonial purchase occasions, and provenance verification requirements create natural partitions that shape pricing architecture and atelier specialization.
Product Type:
Occasion intensity and stone density determine margin capture across personal adornment categories.
- Necklaces:High carat-weight configurations and ceremonial associations with gala and bridal occasions concentrate margin in Paris and Geneva ateliers. German collectors drive demand for convertible day-to-evening designs with detachable pendants.
- Rings:Engagement and anniversary purchase occasions sustain the deepest customization pipelines, with Swiss maisons dominating platinum-forward bridal commissions. Hallmarking harmonization delays between France and Italy fragment multi-jurisdictional launch timelines for new setting techniques.
- Bracelets:Stackable versatility generates repeat purchase frequency among younger collectors in Scandinavian markets. Italian manufacturers lead flexible link construction for daily-wear gold chains.
- Earrings:Lightweight haute joaillerie pieces balance statement presence with wearability for extended events. London boutiques report strongest demand for convertible clip-to-pierced mechanisms.
Established volume favors rings; emerging adoption favors bracelets.
Material:
Scarcity gradients and regulatory traceability burdens stratify sourcing investment across precious substrates.
- Gold:Dominates value flows through 18-karat and 22-karat formulations, with Italian manufacturers processing the highest volumes of recycled feedstock under EU circular economy incentives. REACH documentation requirements now extend to artisanal mine sources in West Africa.
- Platinum:Rarity differentiation attracts collectors seeking portfolio diversification beyond yellow metal allocations. Industrial demand volatility from automotive catalyst markets complicates long-term pricing for Parisian platinum-forward collections.
- Silver:Entry-level positioning bridges aspirational consumers toward maisons' precious metal hierarchies. Spanish ateliers specialize in oxidized finishing techniques compliant with ECHA substance restrictions.
- Gemstones:Colored stone intensity commands parure pricing, with Burmese ruby and Colombian emerald provenance documentation now mandatory under EU Green Deal due diligence. Blockchain-enabled mine-to-retail tracking concentrates investment in Geneva trading houses.
Gold maintains volume leadership; platinum exhibits the steepest expansion trajectory among collectors.
Customer Type:
Wealth thresholds and purchase sophistication determine service model intensity from digital self-service to white-glove atelier commissioning.
- High-Net-Worth Individuals:Six-figure commissioning pipelines and multi-generational collection stewardship require dedicated clienteling teams. Swiss private banks coordinate jewelry acquisitions with wealth structuring for German and French family offices.
- Collectors:Auction participation and vintage provenance authentication demand specialized gemological advisory. Copenhagen and Amsterdam secondary marketplaces attract this segment with blockchain-documented heritage pieces.
- Affluent Consumers:Accessible entry points through signature collections and leather-goods adjacencies build brand relationship foundations. Italian maisons excel at convertible pieces that scale across occasion formality.
- Enthusiasts:Design education and craft transparency drive engagement through atelier visit programs and digital content. Scandinavian markets show highest digital-native purchasing comfort in this tier.
Affluent consumers provide volume base; High-Net-Worth Individuals deliver margin concentration.
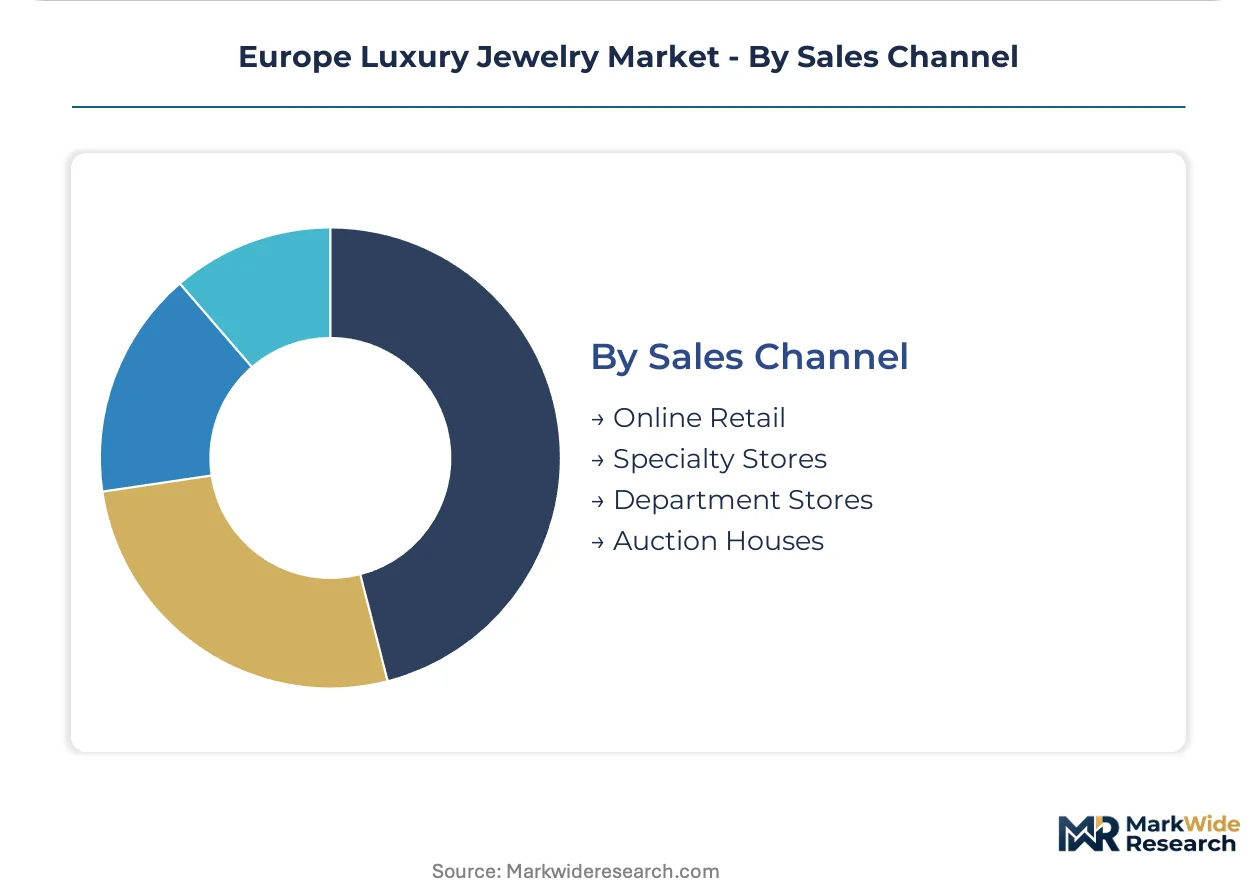
Sales Channel:
Touchpoint control and information asymmetry reduction reshape channel economics across physical and digital domains.
- Specialty Stores:Flagship retail on Place Vendôme and via Monte Napoleone concentrate irreplaceable brand storytelling and bespoke commissioning capabilities. Geneva boutiques capture cross-border traffic from collectors seeking Swiss hallmark prestige.
- Online Retail:Direct-to-collector portals bypass wholesale markups while capturing behavioral data for personalization. Nordic markets lead adoption of virtual try-on for high-value pieces.
- Auction Houses:Price discovery and liquidity provision for vintage provenance pieces attract institutional and family office sellers. Christie's and Sotheby's Geneva sales dominate colored stone record prices.
- Department Stores:Foot traffic and tourist exposure sustain accessible collections in London Harrods and Paris Galeries Lafayette concessions. Post-pandemic space rationalization has reduced dedicated jewelry square footage.
Specialty stores anchor prestige positioning; online retail gains share fastest among under-45 demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-Net-Worth Individuals concentrate disproportionately in Western European financial centers, driving commissioning pipelines for six-figure parures and multi-generational collection stewardship.
France
Parisian Place Vendôme ateliers command the densest heritage craft clustering in Europe, with haute joaillerie maisons sustaining irreplaceable stone-setting capabilities. REACH documentation requirements from ECHA now extend to artisanal gold sources in West African partner jurisdictions. The Île-de-France region concentrates flagship retail presence where cross-border collectors seek hallmark prestige.
Switzerland
Geneva trading houses dominate colored stone provenance verification through blockchain-enabled mine-to-retail tracking systems. Swiss private banks coordinate jewelry acquisitions with wealth structuring for German and French family offices. The Lake Geneva corridor anchors gemological R&D investment and platinum-forward bridal commissioning.
Germany
Wealth concentration in Frankfurt and Munich expands the addressable base for ceremonial purchase occasions above six-figure price points. CSRD disclosure requirements accelerate investment in recycled precious metal integration under EU circular economy incentives. Baden-Württemberg manufacturers specialize in convertible day-to-evening necklace designs with detachable pendants.
Italy
Milan and Vicenza ateliers process the highest volumes of recycled gold feedstock compliant with Ecodesign for Sustainable Products Regulation frameworks. Italian manufacturers lead flexible link construction for stackable bracelet collections targeting repeat purchase frequency. The Veneto region concentrates oxidized silver finishing techniques adapted to ECHA substance restrictions.
United Kingdom
London boutiques report strongest demand for convertible clip-to-pierced earring mechanisms among Middle Eastern collector traffic. Harrods and Mayfair concessions sustain accessible collection exposure despite post-pandemic department store space rationalization. British auction houses compete with Geneva for colored stone record price discovery.
Europe Luxury Jewelry Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where heritage atelier access and vertical gemological capabilities determine pricing power. The vendor base stratifies between Paris-Geneva heritage maisons with captive craft networks and Italian scale manufacturers with recycled metal integration advantages. Three archetypes dominate: vertically integrated haute joaillerie houses, flexible link construction specialists, and blockchain-provenance platform operators. Competitive moves concentrate on direct-to-collector digital portal development and atelier capacity expansion in Central European capitals.
Within the heritage maison tier, Cartier, Boucheron, and Van Cleef & Arpels exemplify how proprietary setting techniques and Paris-based craft concentration create natural barriers against mass-market replication. Cartier represents vertical integration into gemological R&D, Boucheron anchors haute joaillerie craftsmanship resistant to mechanization, and Van Cleef & Arpels occupies a position defined by patented Mystery Set technology in ultra-high-end parures. These three sit within a competitive set where traceability infrastructure and atelier succession planning now determine long-term positioning as much as design heritage.
| Leading Market Players |
|---|
| Boucheron |
| Hermès |
| Cartier |
| Graff |
| Buccellati |
| Bulgari |
| Chopard |
| Louis Vuitton |
| Van Cleef & Arpels |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Parisian stone-setting ateliers is compressing lead times for haute joaillerie commissions and amplifying pricing power for heritage maisons with captive craft networks. This utilization squeeze propagates through the value chain, forcing buyers into longer reservation queues and accepting steeper premiums for provenance-documented pieces.
Pricing Analysis
Cost-plus contracts indexed to London Bullion Market Association precious metal fixings dominate raw material procurement, with Italian manufacturers layering circular-economy recycled gold premiums atop base metal costs. Three-tier pricing structure across haute joaillerie, signature collections, and silver entry points separates commissioning pipelines by wealth threshold and service intensity. Price differentiation hinges on gemological certification grade and atelier provenance, with Swiss-hallmarked platinum pieces commanding sustained premiums over Italian-manufactured gold alternatives. Pricing pressure stems from EU Green Deal traceability documentation burdens that inflate compliance overhead for smaller workshops. Affluent consumers exhibit highest price sensitivity to entry-tier positioning, while High-Net-Worth Individuals demonstrate inelastic demand for six-figure parures with documented mine-to-retail chains.
Supply Chain Analysis
Export-control regimes restricting rough diamond flows through Kimberley Process certifications and EU conflict mineral due diligence are fragmenting traditional sourcing corridors into documented and undocumented supply tiers. Geographic supply concentration rests on Botswana and Russian rough diamond jurisdictions, Colombian emerald districts, and West African artisanal gold networks. Raw material dependencies center on platinum group metals from South African refineries, Burmese rubies subject to sanctions screening, and recycled gold feedstock processed through Italian Vicenza facilities. Supply chain risk concentrates in single-source vulnerability for master craftsperson capabilities concentrated in Geneva and Paris. Distribution runs through Place Vendôme flagship boutiques for prestige positioning, with direct-to-collector digital portals capturing growing share among Nordic ultra-high-net-worth demographics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting through blockchain-enabled provenance verification that transforms jewelry from opaque luxury goods into interoperable digital assets with transparent ownership histories. This shift restructures value capture toward ecosystem orchestrators controlling authentication infrastructure.
For Market Incumbents: Insulate haute joaillerie pricing power by capturing master craftsperson capacity through apprenticeship endowments and atelier acquisition in Geneva and Paris. Vertical integration into gemological R&D and proprietary setting techniques creates defensible moats against mechanized replication threats from additive manufacturing entrants.
For New Entrants and Emerging Players: Establish a beachhead in Central and Eastern European secondary marketplaces where Warsaw and Prague exhibit rising ultra-high-net-worth density with underdeveloped flagship retail presence. Digital-native certified pre-owned platforms offer the most penetrable entry vector, leveraging blockchain documentation to capture younger collectors seeking vintage provenance at accessible price points.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across traceability infrastructure and atelier succession planning as compliance and craft preservation costs compound. Long-term viability favors vertically integrated maisons with captive gemological capabilities and established blockchain provenance systems. The signal to watch is regulatory harmonization progress between French and Italian hallmarking authorities that would accelerate multi-jurisdictional product launch timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Integration | Cartier and Van Cleef & Arpels are deploying mine-to-retail tracking that compresses information asymmetry for collectors. |
| Atelier Capacity Expansion | Boucheron is extending Paris-based craft networks to resist generational skill transfer gaps in stone-setting. |
| Recycled Metal Feedstock Securement | Italian manufacturers are locking circular-economy gold supplies under Ecodesign for Sustainable Products Regulation incentives. |
| Direct-to-Collector Digital Portal Launch | Scandinavian-focused platforms are capturing behavioral data for bespoke commissioning while bypassing wholesale markups. |
| Central European Flagship Retail Entry | Heritage maisons are establishing presence in Warsaw and Budapest to capture rising ultra-high-net-worth density. |
Research Methodology
A spread of perspectives from haute joaillerie atelier directors, gemological laboratory executives, private bank wealth advisors, and ECHA regulatory compliance officers converged on the working assumptions driving supply chain and pricing dynamics. Primary fieldwork with Place Vendôme maisons and Geneva trading houses was cross-referenced against secondary validation from EU Green Deal implementation documents, ECHA substance restriction updates, Kimberley Process certification flows, and Swiss customs precious metal trade data. Bottom-up atelier capacity assessments and top-down wealth concentration metrics were triangulated to anchor segmentation sizing.
Demand-supply balance framing structured the analytical approach, with High-Net-Worth Individual wealth formation trajectories and master craftsperson succession pipelines modeled across the projection horizon. Segmentation dimensions included product type, material purity tier, customer wealth threshold, and sales channel control intensity, with additional granularity on provenance verification technology adoption. CAGRs were derived from compounding annual adjustments to base-year value flows, incorporating REACH compliance cost pass-through assumptions and circular-economy recycled metal penetration curves.
Sensitivities concentrate around EU Green Deal due diligence enforcement intensity and geopolitical disruption to Burmese ruby or Russian rough diamond flows. Forecasts reflect documented assumptions on atelier capacity constraints and blockchain provenance adoption curves. Material shifts in ECHA substance restriction scope or hallmarking harmonization timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Demi-Fine Jewelry Market
Jewelry
Global Gems and Jewelry Market
Jewelry
Jewellery Market
Jewelry
Asia-Pacific Luxury Jewelry Market
Jewelry
Luxury Fine Jewellery Market
Jewelry
Global Jewelry Market
Jewelry
Latin America Jewelry Market
Jewelry
South Korea Luxury Jewelry Market
Jewelry
Diamond Jewelry Market
Jewelry
3D Printing for Jewelry Market
Jewelry
China Jewellery Market
Jewelry
China Luxury Jewelry Market
Jewelry
Jewelry Cleaners Market
Jewelry
Leather Jewellery Box Market
Jewelry
Qatar Jewelry Market
Jewelry
3D Printing Jewelry Service Market