
 Bead Products Market | 2026-2036
Bead Products Market Size, Share, and Industry Trends Forecast 2026-2036
Bead Products Market Analysis
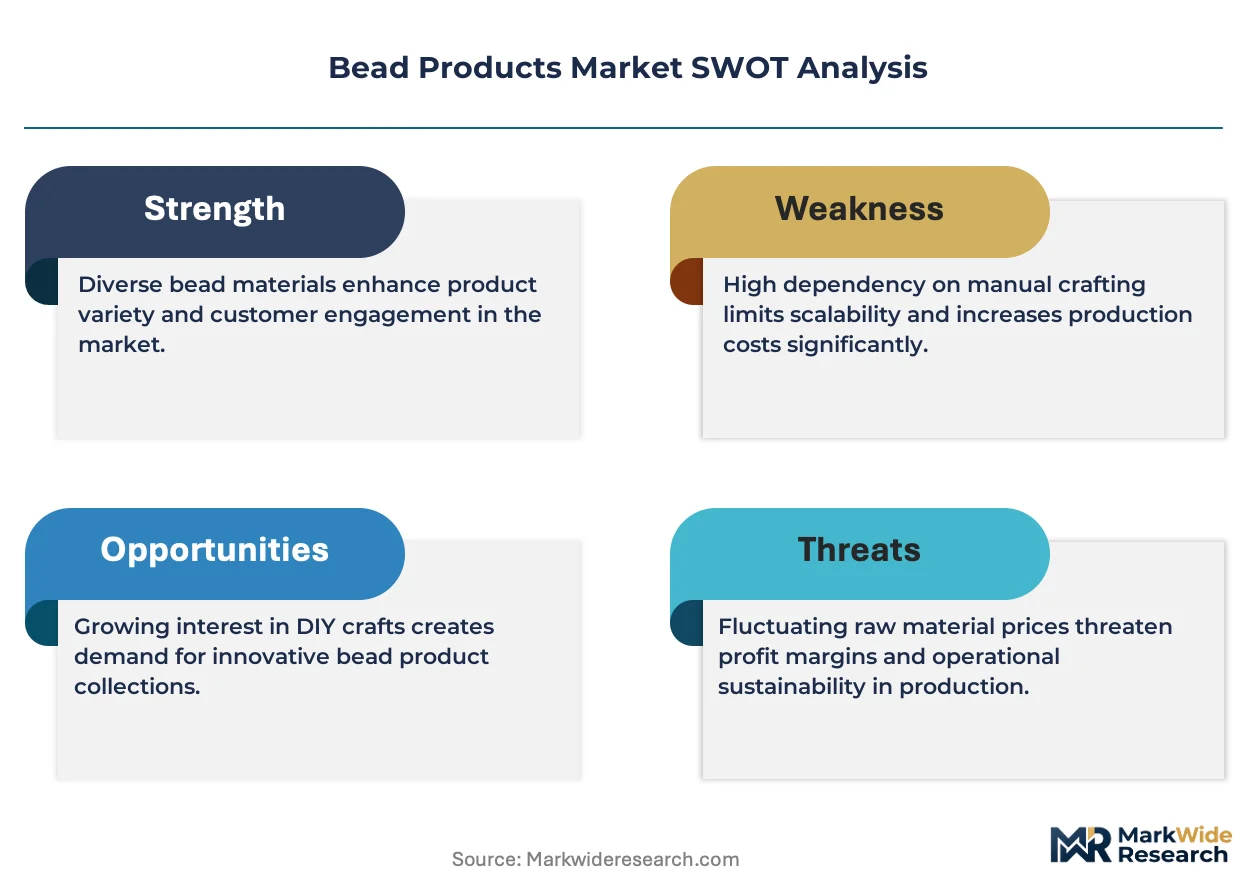
Subscription-based design software and digital pattern libraries is consolidating how bead manufacturers monetize customer relationships beyond physical SKU sales. MIYUKI Co., Ltd. leverages its proprietary cylinder-bead precision technology to dominate high-end weaving segments. PRECIOSA ORNELA anchors Central European supply chains through captive crystal production and heritage cutting methods. Fire Mountain Gems and Beads, Inc. competes on breadth, sustaining one of the deepest catalog assortments in North American distribution.
Bead products are small, perforated objects manufactured from glass, polymer, metal, or organic substrates, typically ranging from one millimeter to several centimeters in diameter, designed for threading, weaving, or surface adhesion in decorative and functional assemblies. Glass beads command premium positioning due to refractive clarity and kiln-firing durability, while plastic beads serve volume-driven educational toy and costume jewelry channels where unit economics favor injection-molded polypropylene and acrylic resins. Jewelry Making absorbs the largest value share across Application segments, though Wedding Decorations generates disproportionate margin contribution from seasonal bulk orders and custom color matching. Craft Enthusiasts represent the most fragmented End User category, creating pricing power challenges for brands without community-building platforms or tutorial content ecosystems.
FDA oversight applies to beads marketed as children's toys through small-parts testing protocols, while REACH and RoHS frameworks in Europe restrict heavy-metal content in surface coatings and base substrates. The EU Green Deal is forcing reformulation of plastic bead feedstocks toward bio-based or recycled-content alternatives, compressing margins for manufacturers without polymer R&D partnerships. Stakeholders must monitor evolving extended-producer-responsibility schemes and decide whether to absorb compliance costs or pass them through to price-sensitive craft retail channels.
Market Dynamics
EU Green Deal material standards are forcing wholesale reformulation of plastic bead feedstocks across European supply chains, compressing margins for manufacturers lacking polymer R&D partnerships while redirecting procurement toward bio-based alternatives.
Growth Catalysts
- REACH cadmium restrictions:Tightening heavy-metal limits across European coatings are accelerating substitution demand for certified glass and crystal substrates in jewelry applications.
- Zhejiang manufacturing clusters:Dense export infrastructure in China's eastern provinces enables rapid scale-up of precision-cut bead volumes for North American craft retailers.
- Digital pattern libraries:Subscription-based design software is consolidating manufacturer-customer relationships beyond transactional SKU sales into recurring revenue streams.
Market Restraints
- Petrochemical feedstock volatility:Acrylic and polypropylene resin costs fluctuate with crude oil indices, eroding unit economics for injection-molded educational toy beads.
- Central European supply concentration:Heritage crystal production in the Czech Republic and Austria creates single-point vulnerability for premium weaving segments dependent on captive cutting methods.
- Small-parts testing protocols:FDA oversight of children's toy applications imposes destructive sampling requirements that raise per-SKU compliance costs.
Strategic Opportunities
- Wedding decoration bulk orders:Seasonal custom color-matching contracts generate disproportionate margin contribution from event-planning channels in the United States and Canada.
- Extended producer responsibility schemes:EU packaging waste directives create first-mover advantage for manufacturers with closed-loop recycling infrastructure.
- Laser-guided precision cutting:Convergence of optical scanning and CNC machining is enabling micron-level tolerance beads for medical device and aerospace applications.
Industry Challenges
- Heritage craft skill attrition:Master bead-weaving techniques are disappearing as aging artisans retire without formal apprenticeship pipelines.
- Dual certification timelines:Simultaneous FDA small-parts and REACH heavy-metal approvals delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bead Products Market |
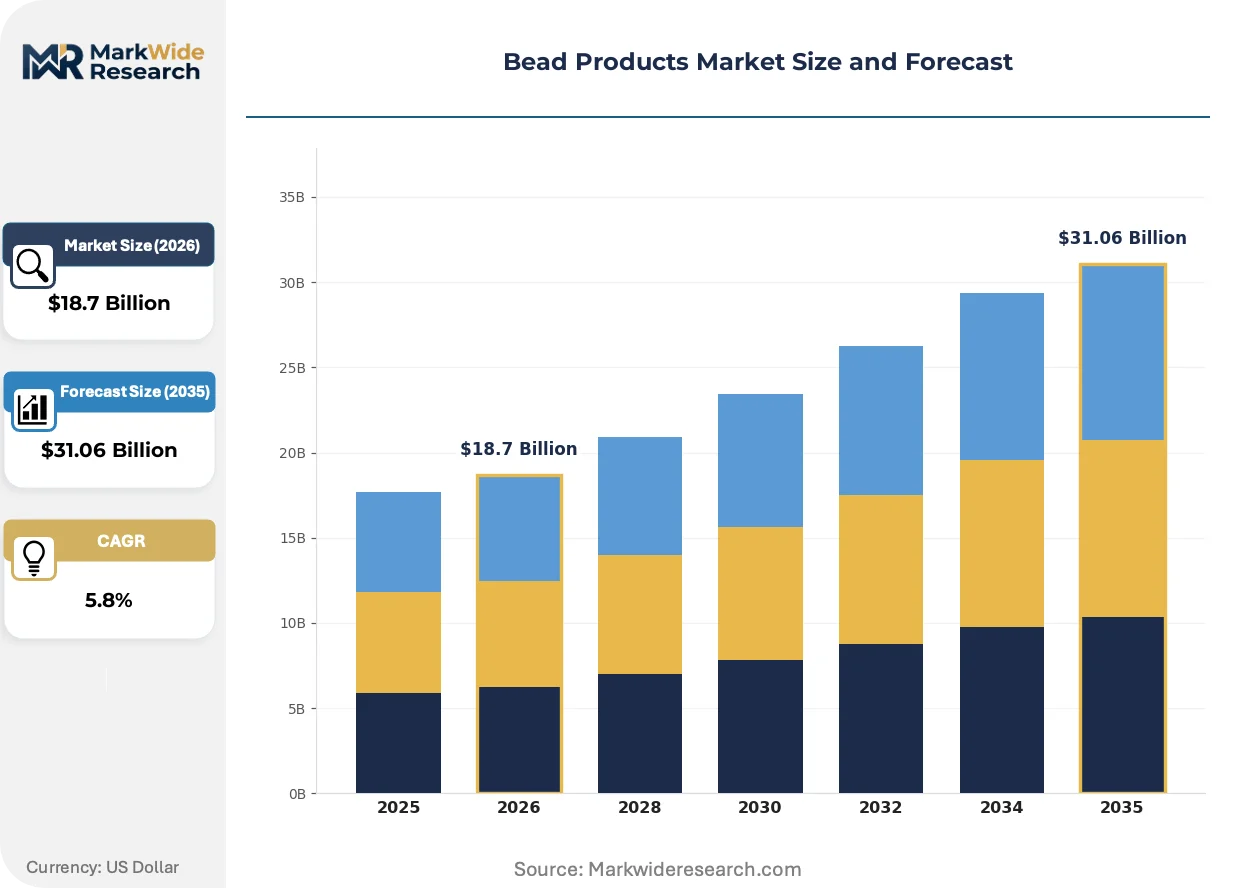
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Beads, Plastic Beads, Wooden Beads, Metal Beads End User: Craft Enthusiasts, Jewelry Designers, Educational Institutions, Retailers Application: Jewelry Making, Home Decor, Educational Toys, Wedding Decorations Distribution Channel: Online Retail, Specialty Stores, Craft Fairs, Wholesale Distributors |
| Companies Covered | MIYUKI Co., Ltd., Fire Mountain Gems and Beads, Inc., Swarovski Crystal Online AG, Wire and Cable Specialties, Inc., The Beadsmith, PRECIOSA ORNELA, John Bead Corporation, Eureka Crystal Beads LLC, TOHO Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bead Products Market Emerging Trajectories
Digital tooling and regulatory chemistry mandates are reshaping how bead manufacturers compete on speed, compliance depth, and customer lock-in beyond commodity bead production.
Laser-sintered polymer bead prototyping is absorbing traditional hand-carving workflows in bespoke jewelry studios. High-end designers in Milan and Tokyo are adopting desktop sintering units for same-day custom color batches. This distributed manufacturing capability is compressing lead times for limited-edition collections from weeks to hours.
EU Green Deal bio-based feedstock mandates are forcing reformulation of polypropylene and acrylic resins used in educational toy beads. Manufacturers without polymer R&D partnerships face margin compression or supplier switching costs. German and French distributors are now requiring mass-balance certification documentation for all plastic bead imports.
Craft retail buyers are consolidating vendor relationships around integrated tutorial-content ecosystems. Community-building platforms with embedded pattern libraries are displacing transactional wholesale catalogs. This behavioral shift concentrates purchasing power with MIYUKI and Fire Mountain Gems in North American and Japanese markets where maker education commands premium positioning.
Bead Products Market Segmentation
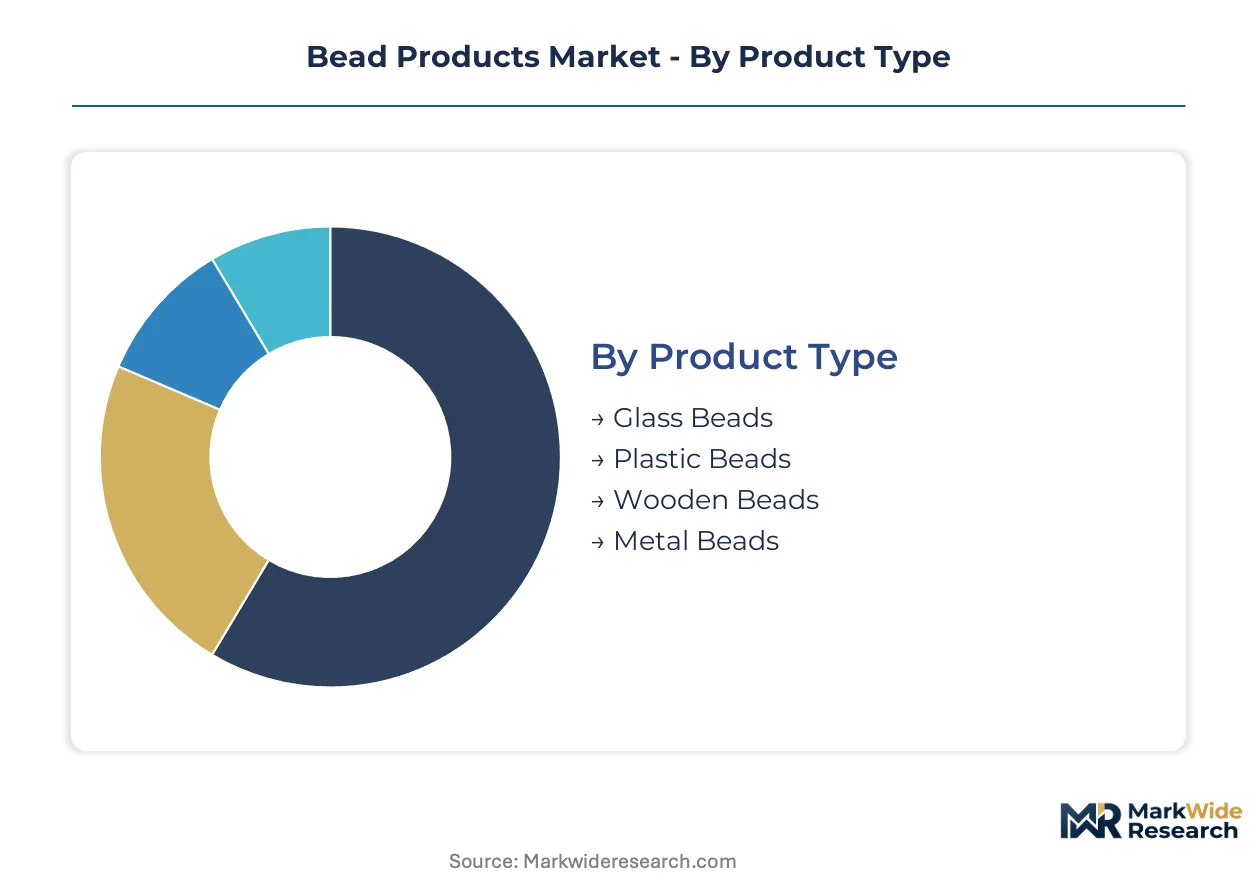
Bead product segmentation reveals divergent capital requirements across substrate technologies and channel economics. Manufacturers must align production infrastructure with specific segment margin profiles and compliance burdens.
Product Type:
Glass bead production demands the heaviest upfront investment in kiln infrastructure, precision cutting equipment, and refractory materials handling systems.
- Glass Beads:Kiln-fired silica formulations with refractive clarity specifications command premium positioning in jewelry applications. Zhejiang province manufacturers are absorbing capacity expansion for North American craft retail procurement amid REACH cadmium substitution demand.
- Plastic Beads:Injection-molded polypropylene and acrylic resins serve volume-driven educational toy channels where unit economics favor high-throughput extrusion. EU Green Deal bio-based feedstock mandates are compressing margins for manufacturers lacking polymer R&D partnerships.
- Wooden Beads:Lathe-turned hardwood and softwood substrates appeal to eco-conscious craft segments with lower tooling barriers.
- Metal Beads:Die-cast zinc alloys and plated substrates require electroplating compliance infrastructure for nickel restriction markets.
Glass Beads absorb the bulk of installed capacity; Plastic Beads is expanding most quickly.
End User:
Customer acquisition costs and retention mechanics vary sharply across professional, institutional, and hobbyist buyer pools.
- Craft Enthusiasts:Fragmented individual purchasers drive pricing power challenges without community platform lock-in. Fire Mountain Gems and MIYUKI concentrate share through tutorial-content ecosystems.
- Jewelry Designers:Bespoke collections demand precision-cut glass and crystal substrates with micron-level tolerance specifications. Milan and Tokyo studios are adopting laser-sintered prototyping for same-day custom color batches.
- Educational Institutions:Bulk procurement of non-toxic plastic beads for STEM and art curricula requires FDA small-parts certification.
- Retailers:Multi-channel distributors consolidate vendor relationships around integrated digital pattern libraries and subscription software.
Craft Enthusiasts represent the largest addressable pool; Jewelry Designers command the steepest expansion trajectory.
Application:
Seasonal demand patterns and margin contribution diverge substantially across decorative versus functional use cases.
- Jewelry Making:Threading and weaving assemblies absorb the largest value share across application segments. Heritage Czech crystal cutting methods anchor premium weaving supply chains.
- Wedding Decorations:Seasonal bulk orders with custom color matching generate disproportionate margin contribution from United States and Canada event-planning channels.
- Home Decor:Surface adhesion and textile embellishment applications favor larger-format beads with lower per-unit precision requirements.
- Educational Toys:Counting and sorting bead sets for early childhood development face FDA small-parts testing protocols with destructive sampling costs.
Jewelry Making dominates revenue concentration; Wedding Decorations posts the strongest margin profile.
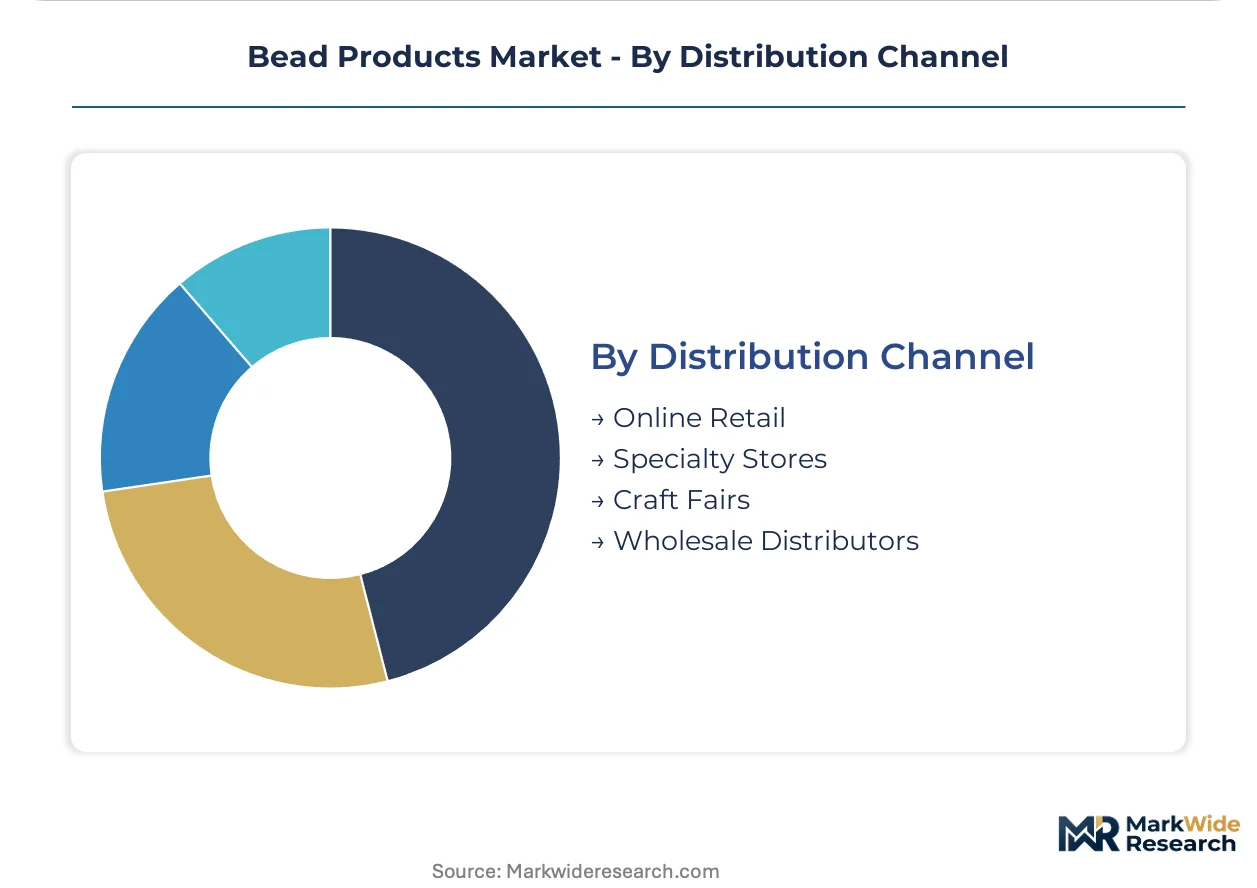
Distribution Channel:
Channel selection determines working capital intensity and customer data capture depth for bead manufacturers.
- Online Retail:Direct-to-consumer platforms enable subscription-based design software monetization beyond transactional SKU sales. Digital pattern libraries are consolidating manufacturer-customer relationships into recurring revenue streams.
- Specialty Stores:Curated brick-and-mortar assortments in craft-focused retail chains sustain premium positioning for precision-cut crystal products.
- Craft Fairs:Seasonal exhibition circuits provide tactile sampling opportunities for wooden and organic substrate beads.
- Wholesale Distributors:German and French distributors now require mass-balance certification documentation for all plastic bead imports under EU packaging waste directives.
Online Retail captures the fastest share gain; Wholesale Distributors maintain the deepest volume relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the bulk of global bead volume while North America and Europe absorb the highest-value consumption. This production-consumption asymmetry shapes trade flows, regulatory compliance burdens, and margin capture across geographies.
China
Zhejiang and Guangdong provinces export precision-cut glass beads to North American craft retailers under REACH-compliant cadmium-free specifications. MIIT industrial cluster policies subsidize kiln infrastructure upgrades in Yiwu and Chaozhou. Dense supplier networks in these eastern provinces enable rapid scale-up of custom color batches for wedding decoration orders.
United States
Wedding planners and jewelry designers drive seasonal demand for bespoke crystal and glass substrates. FDA small-parts testing protocols apply to educational toy bead imports, with destructive sampling requirements raising per-SKU compliance costs. Fire Mountain Gems anchors distribution through integrated tutorial-content platforms that consolidate craft enthusiast purchasing.
Germany
EU Green Deal bio-based feedstock mandates force reformulation of polypropylene beads for educational channels. ECHA REACH enforcement tightens nickel and cadmium restrictions in surface coatings. German distributors now require mass-balance certification documentation for all plastic bead imports under packaging waste directives.
Japan
Tokyo studios adopt laser-sintered prototyping for same-day custom jewelry collections. METI supports precision manufacturing technology diffusion to maintain competitive positioning in high-end weaving segments. MIYUKI Co., Ltd. leverages domestic cylinder-bead technology to dominate premium export markets.
Czech Republic
Heritage crystal cutting methods in Jablonec nad Nisou anchor European supply chains for premium weaving applications. PRECIOSA ORNELA maintains captive production infrastructure that creates single-point vulnerability for micron-tolerance bead segments. EMA and ECHA frameworks govern heavy-metal content in exported decorative substrates.
Bead Products Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the bead products market. Kiln-fired glass and crystal manufacturing demands substantial fixed-asset investment in refractory equipment, while polymer bead designers outsource injection molding to contract manufacturers. The vendor base stratifies into three archetypes: integrated crystal producers with captive cutting heritage, precision-technology specialists with proprietary cylinder-bead IP, and catalog-breadth distributors with community-platform lock-in. Competitive moves concentrate on M&A to secure raw material access and strategic partnerships to embed tutorial-content ecosystems.
Within the integrated heritage tier, PRECIOSA ORNELA exemplifies Central European supply concentration through captive production infrastructure. Among precision-technology specialists, MIYUKI Co., Ltd. and TOHO Co., Ltd. occupy positions defined by proprietary cylinder-bead manufacturing methods. Fire Mountain Gems and Beads, Inc. represents the catalog-breadth archetype, anchoring North American distribution through deep SKU assortments and maker-education platforms.
| Leading Market Players |
|---|
| MIYUKI Co., Ltd. |
| Fire Mountain Gems and Beads, Inc. |
| Swarovski Crystal Online AG |
| Wire and Cable Specialties, Inc. |
| The Beadsmith |
| PRECIOSA ORNELA |
| John Bead Corporation |
| Eureka Crystal Beads LLC |
| TOHO Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
EU Green Deal bio-based feedstock mandates gate qualified supply for European educational toy channels while compressing margins for manufacturers lacking polymer R&D partnerships, simultaneously creating premium-tier pricing access for REACH-certified glass and crystal substrate producers serving jewelry designers.
Pricing Analysis
Margin tightening in plastic bead tiers reflects petrochemical resin volatility and EU reformulation costs, while premium-mid-economy pricing differentiation separates kiln-fired glass from injection-molded alternatives. REACH cadmium-free certification and FDA small-parts testing grade quality tiers, with craft enthusiasts showing acute price sensitivity and wedding planners demonstrating inelastic demand for custom color matching.
Supply Chain Analysis
Master glass-cutting workforce availability in Jablonec nad Nisou and Yiwu constrains expansion of micron-tolerance bead capacity, as heritage artisan attrition outpaces CNC training pipelines. Silica sand, refractory kiln materials, and electroplated nickel feed Czech and Chinese production clusters, with single-source vulnerability in Central European crystal cutting creating distribution risk. Distribution runs through German mass-balance-certified wholesalers and Fire Mountain Gems' direct-to-craft-platform channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Captive kiln infrastructure and heritage cutting methods create structural supply constraints that prop pricing for precision glass and crystal segments, with EU regulatory chemistry mandates further tightening qualified supplier pools.
For Market Incumbents: Anticipate REACH nickel restriction expansion by securing electroplating compliance infrastructure ahead of ECHA enforcement waves, while absorbing polymer R&D partnerships to defend margin position against bio-based feedstock mandates. Vertical integration into Zhejiang kiln capacity buffers against Chinese export tariff exposure. For New Entrants and Emerging Players: FDA small-parts certification requirements in the United States open a window for laboratory-testing-service partnerships that accelerate market entry, with educational toy beads representing the most penetrable white-space segment. A go-to-market angle anchored in STEM curriculum-aligned color assortments bypasses entrenched craft-platform incumbents. For Investors and Strategic Acquirers: German distributor mass-balance documentation demands is the leading indicator that closed-loop recycling infrastructure will separate acquisition targets from stranded assets. Long-term viability favors cylinder-bead precision-technology specialists with proprietary IP moats, with METI-funded Japanese manufacturing diffusion serving as the inflection signal for premium weaving segment consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Polymer R&D Partnership | EU Green Deal compliance secures educational toy channel access against bio-based feedstock mandates. |
| Closed-Loop Recycling Infrastructure | Mass-balance certification captures German and French distributor procurement preference under packaging directives. |
| Laser-Guided Precision Cutting Investment | Micron-tolerance capability penetrates medical device and aerospace application adjacencies. |
| Tutorial-Content Platform Acquisition | Community lock-in consolidates craft enthusiast purchasing power against transactional wholesale catalogs. |
| Heritage Artisan Apprenticeship Pipeline | Jablonec nad Nisou cutting-method preservation defends Central European supply chain concentration. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted among jewelry designers, craft retail buyers, kiln operations managers, and polymer R&D directors validating demand assumptions. ECHA REACH substance restrictions, FDA small-parts testing protocols, and MIIT industrial cluster disclosures supplied regulatory boundary conditions. Bottom-up bead production capacity estimates triangulated against top-down wedding decoration and educational toy consumption forecasts.
Data-stream reconciliation across product type, end user archetype, application, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from Zhejiang export volume trajectories, seasonal wedding order patterns, and digital pattern library subscription growth curves, with laser-sintering adoption rates and bio-based resin penetration serving as technology-transition inputs.
Caveats apply where ECHA heavy-metal restriction expansion, FDA testing protocol revisions, or petrochemical feedstock price spikes could materially shift the outlook. Forecasts reflect assumptions about artisan workforce stability and Chinese export infrastructure continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Qatar Jewelry Market
Jewelry
Jewelry Cleaners Market
Jewelry
Jewellery Market
Jewelry
Global Body Piercing Jewelry Market
Jewelry
Europe Luxury Jewelry Market
Jewelry
South Korea Luxury Jewelry Market
Jewelry
Global Gems and Jewelry Market
Jewelry
Quartz Ring Market
Jewelry
Saudi Arabia Luxury Jewelry Market
Jewelry
Luxury Jewelry Market
Jewelry
Leather Jewellery Box Market
Jewelry
Global Costume Jewelry Market
Jewelry
Italy Luxury Jewelry Market
Jewelry
Japan Jewellery Market
Jewelry
Crystal Bracelets Market
Jewelry
Latin America Jewelry Market