
 Diamond Jewelry Market | 2026-2036
Diamond Jewelry Market Size, Share, and Industry Trends Forecast 2026-2036
Diamond Jewelry Market Intelligence
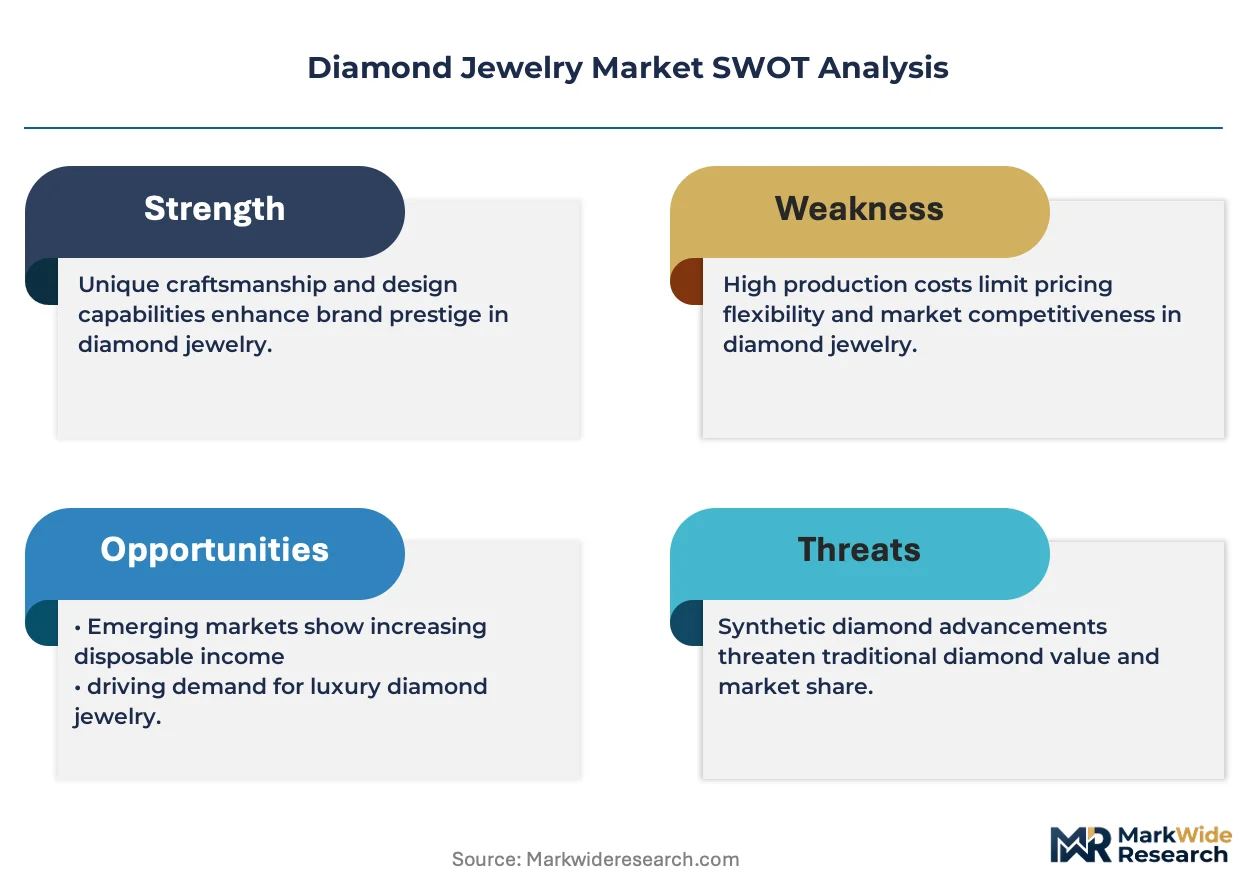
Bridal and ceremonial purchasing is realigning the end-use mix of the diamond jewelry industry, with luxury buyers and retail consumers diverging in preference toward certified natural stones versus lab-grown alternatives. Signet Jewelers leverages its extensive North American store network to dominate mid-market bridal transactions. Chow Tai Fook anchors Greater China demand through heritage gold-diamond fusion designs and retail density. De Beers plc competes across both natural and Lightbox lab-grown positioning, sustaining dual-brand manufacturing scale.
Diamond jewelry comprises ornamental pieces set with cut and polished diamonds, typically mounted in precious metals with clarity grades from Flawless to Included and carat weights spanning fractional points to ten-plus stones, serving personal adornment, wealth storage, and ceremonial commemoration. Rings and necklaces command the largest value share within product type segmentation, with bridal rings anchoring recurring demand and high-karat gold necklaces capturing gifting volume in Asian markets. Online retail and jewelry stores represent the primary sales channel split, where digital platforms extend reach to younger collectors while physical flagships preserve experiential luxury for high-value transactions.
The Federal Trade Commission enforces jewelry marketing guidelines in the United States, requiring clear distinction between natural and laboratory-created diamonds to prevent consumer deception. India's Bureau of Indian Standards mandates hallmarking for gold-diamond mountings, ensuring metal purity disclosure across domestic retail. The Gemological Institute of America and International Gemological Institute both operate grading standards that shape cross-border trade acceptability. Stakeholders must monitor evolving lab-grown disclosure mandates and metal sourcing traceability rules as these frameworks tighten across major consumer jurisdictions.
Market Dynamics
Bridal ceremonial demand and lab-grown diamond certification protocols are restructuring competitive positioning across retail channels, forcing natural stone suppliers to differentiate through provenance transparency while synthetic producers scale manufacturing capacity.
Growth Catalysts
- Federal Trade Commission disclosure mandates:The FTC's jewelry marketing guidelines in the United States require explicit labeling of laboratory-created diamonds, reducing consumer confusion and building trust in certified channels.
- India wedding-season purchasing:Urban wealth accumulation and seasonal ceremonial traditions concentrate volume in Mumbai, Delhi, and Bangalore retail corridors.
- High-pressure high-temperature synthesis:HPHT growth methods now yield gem-quality stones above two carats, expanding addressable occasions beyond fashion jewelry into bridal segments.
Market Restraints
- Natural rough supply concentration:Rough diamond extraction remains geographically concentrated in Botswana, Russia, and Canada, creating geopolitical and logistics vulnerability for polished goods pipelines.
- Energy-intensive synthesis costs:Chemical vapor deposition and HPHT processes require sustained electricity inputs that fluctuate with regional grid pricing, compressing margins for lab-grown producers.
- Metal price volatility:Gold and platinum alloy costs for mountings swing with commodity exchange rates, complicating inventory valuation and pricing stability for finished jewelry.
Strategic Opportunities
- Vietnam retail underpenetration:Ho Chi Minh City and Hanoi show rising disposable income with limited branded jewelry presence, creating first-mover positioning for heritage design houses.
- Blockchain provenance integration:Distributed ledger technology converging with GIA certification records enables immutable chain-of-custody documentation for natural stones.
- Bureau of Indian Standards hallmarking expansion:BIS mandatory purity disclosure for gold-diamond mountings is extending enforcement to tier-two cities, formalizing previously informal retail channels.
Industry Challenges
- Graduate gemologist scarcity:GIA-trained professionals capable of distinguishing advanced synthetics from naturals remain concentrated in established trading centers, constraining quality control scaling.
- Dual-inventory complexity:Retailers stocking both natural and lab-grown SKUs face SKU proliferation, divergent margin profiles, and staff training requirements across counter positions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diamond Jewelry Market |
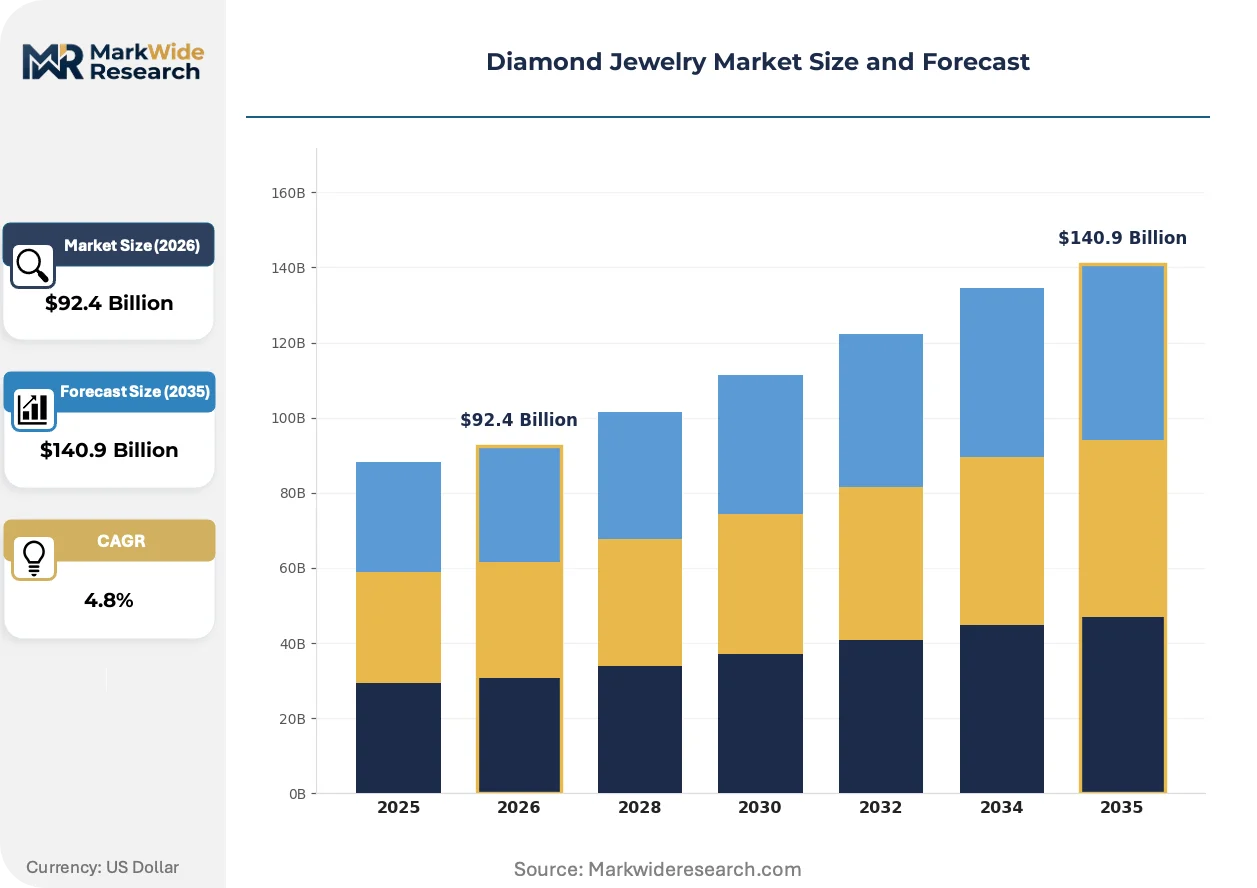
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $140.9 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rings, Necklaces, Earrings, Bracelets Material: Gold, Platinum, Silver, Titanium Customer Type: Luxury Buyers, Retail Consumers, Collectors, Gifting Sales Channel: Online Retail, Jewelry Stores, Auction Houses, Direct Sales |
| Companies Covered | Signet Jewelers, Chow Tai Fook, De Beers plc, Graff, Harry Winston, Tiffany & Co., Bulgari S.p.A., Van Cleef & Arpels, Cartier, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diamond Jewelry Market Strategic Shifts & Innovations
Diamond jewelry retail is experiencing technology-driven transparency demands, regulatory disclosure tightening, and channel preference fragmentation that collectively compress traditional intermediation layers.
Advanced spectroscopic detection equipment is unifying authentication workflows across wholesale trading floors. De Beers' DiamondView and similar instruments now scan parcels for synthetic inclusions within seconds. Major auction houses and tender houses in Antwerp and Dubai have adopted these systems for pre-sale screening. This unifying technology infrastructure is compressing transaction friction between miners, manufacturers, and retailers by reducing dispute resolution cycles.
The Gemological Institute of America's updated laboratory-grown diamond grading reports now include specific growth method identification. This regulatory-adjacent standard-setting creates bifurcated inventory management requirements for retailers carrying both categories. North American bridal specialists face the steepest compliance curve as FTC enforcement actions against misleading marketing intensify.
Younger collectors increasingly research certification parameters online before entering physical showrooms. Digital-native buyers in South Korea and the United States consult GIA report numbers via mobile applications, then visit flagships for tactile validation. This behavior compresses the traditional discovery-to-purchase timeline while elevating the importance of searchable digital inventory transparency.
Diamond Jewelry Market Segmentation
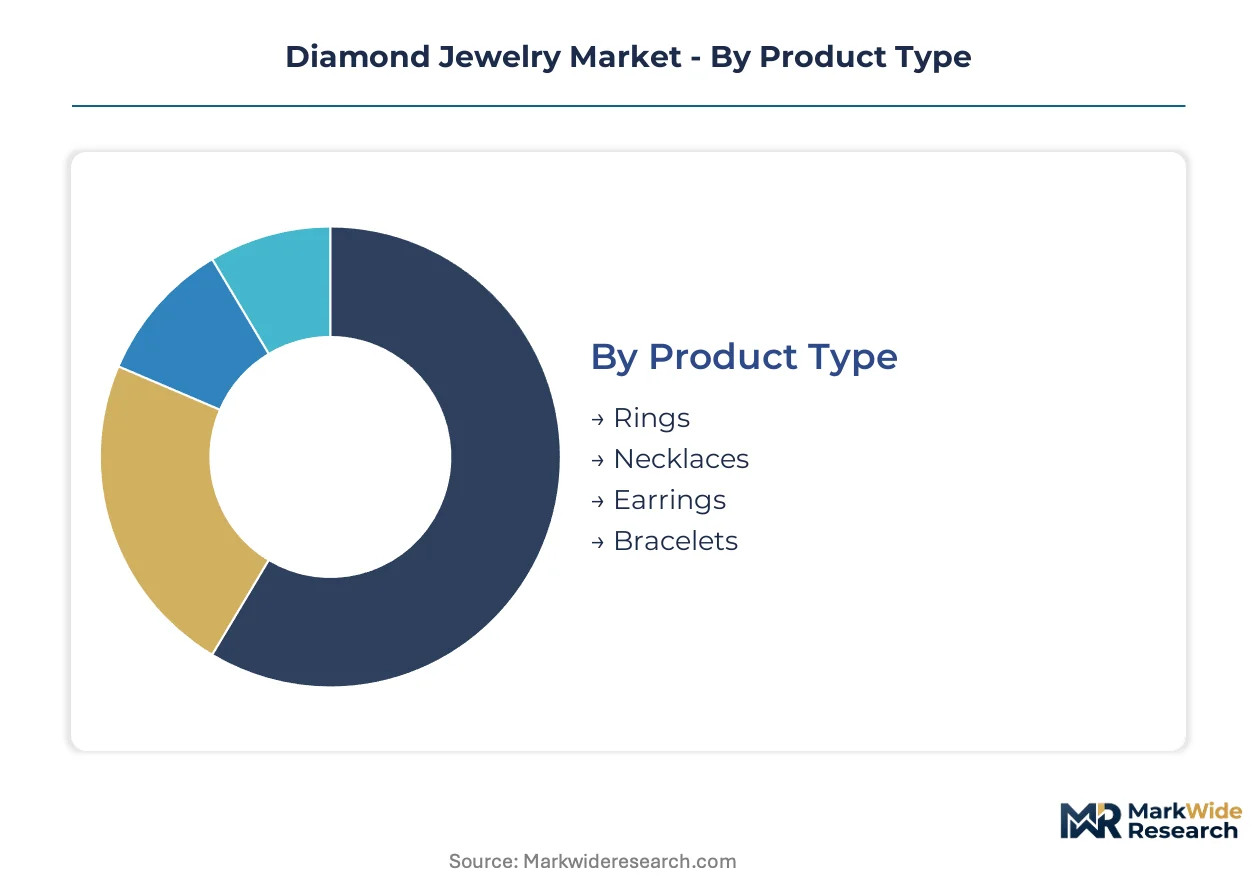
Diamond jewelry segmentation reveals how ceremonial purpose, metal preference, and purchase occasion split demand across distinct buyer journeys. Understanding these fault lines clarifies why bridal specialists, fashion retailers, and auction houses rarely compete directly despite selling identical gemstones.
Product Type:
Buyers differentiate by occasion permanence and visibility, with ceremonial commitment driving carat concentration and daily wearables prioritizing comfort settings.
- Rings:Solitaire and pavé settings in platinum or gold mountings dominate bridal registry purchases. India and the United States concentrate engagement and wedding band volume, with seasonal gifting in Mumbai and Delhi reinforcing fourth-quarter inventory cycles.
- Necklaces:Pendant and station designs featuring graduated diamonds capture ceremonial gifting demand across Greater China. High-karat gold chains with central stone settings anchor wedding dowry traditions in urban Indian households.
- Earrings:Stud and drop configurations serve fashion refresh cycles and milestone gifting occasions.
- Bracelets:Tennis and bangle styles with channel-set stones appeal to self-purchase collectors seeking stackable layering options.
Volume sits with rings; growth tilts toward necklaces.
Material:
Metal selection tracks wealth storage intent, with alloy purity and resale liquidity shaping buyer calculus across price tiers.
- Gold:18K and 22K yellow gold mountings dominate Asian bridal markets where metal content carries independent investment value. India's Bureau of Indian Standards hallmarking mandates now extend to tier-two cities, formalizing purity disclosure for diamond-gold fusion pieces.
- Platinum:950 purity white metal settings anchor North American and European bridal preferences, with density and hypoallergenic properties justifying premium positioning over white gold alternatives.
- Silver:Sterling mountings with cubic zirconia or small diamond accents capture entry-level fashion demand.
- Titanium:Lightweight gray metal with tension settings appeals to male buyers seeking contemporary industrial aesthetics in wedding bands.
Gold commands absolute volume; platinum captures value per gram.
Customer Type:
Purchase motivation separates transactional gift buyers from accumulation-oriented collectors and ceremonial commitment purchasers.
- Luxury Buyers:HNW individuals purchasing five-carat-plus stones with D-F color and IF-VVS clarity grades through private salons and auction channels. Provenance documentation and GIA certification non-negotiable; blockchain traceability emerging as table stakes.
- Retail Consumers:Mid-market bridal and anniversary purchasers selecting certified stones between 0.5 and 2.0 carats through national jewelry chains. FTC disclosure compliance on laboratory-grown alternatives shapes trust dynamics.
- Collectors:Repeat purchasers building themed portfolios around fancy colored diamonds or vintage cuts.
- Gifting:Occasional buyers acquiring standardized pieces for graduation, promotion, or holiday milestones.
Retail consumers generate transaction volume; luxury buyers concentrate profit pools.
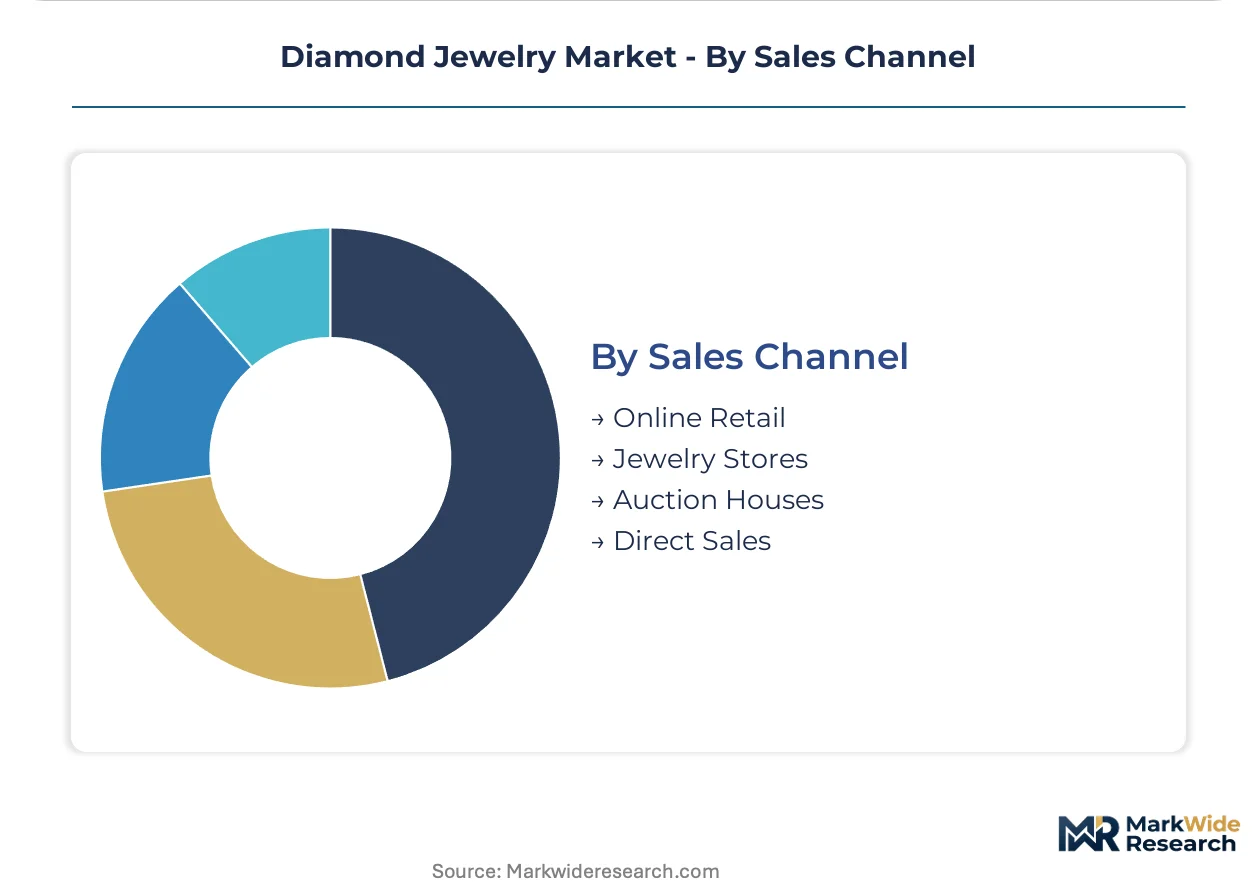
Sales Channel:
Channel preference fractures by age cohort and transaction size, with digital discovery now preceding most physical purchases above $5,000.
- Online Retail:Digital-native platforms with 360-degree imaging and virtual try-on capture younger collectors researching certification parameters before showroom visits. Mobile-accessible GIA report databases compress consideration timelines.
- Jewelry Stores:Flagship locations in Mumbai, New York, and London preserve tactile validation for high-value transactions, with bridal consultations requiring gemologist staff presence.
- Auction Houses:Christie's and Sotheby's tender rare stones above ten carats with documented provenance to institutional and family office bidders.
- Direct Sales:Manufacturer-owned showrooms and trunk shows bypass wholesale markups for educated repeat buyers.
Jewelry stores retain value share; online retail expands fastest by transaction count.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Surat Special Economic Zone drives diamond cutting and polishing concentration, with duty exemptions on rough imports attracting manufacturing investment. This tax-advantaged corridor anchors India's processing dominance while consumer demand clusters in metropolitan bridal markets.
India
Wedding-season purchasing and urban wealth accumulation concentrate volume in Mumbai, Delhi, and Bangalore retail corridors. The Bureau of Indian Standards mandates hallmarking for gold-diamond mountings, extending enforcement to tier-two cities. Surat SEZ processes over 90 percent of global rough diamonds through its cutting and polishing units.
United States
Bridal registry purchases and anniversary gifting sustain mid-market transaction density across national jewelry chains. The Federal Trade Commission enforces explicit labeling of laboratory-created diamonds, reducing consumer confusion in certified channels. New York's Diamond District and Los Angeles luxury corridors anchor wholesale trading and flagship retail respectively.
China
Greater China's demand for heritage gold-diamond fusion designs anchors ceremonial gifting volume through retail density in tier-one cities. The State Administration for Market Regulation oversees jewelry quality standards and disclosure requirements. Chow Tai Fook's Pearl River Delta and Yangtze River Delta store networks capture urban household wealth accumulation.
Belgium
Antwerp's diamond tender houses and spectroscopic screening infrastructure serve as the primary clearing node for rough-to-polished pipelines. EU REACH regulations and Kimberley Process certification requirements govern import documentation. The Antwerp World Diamond Centre cluster coordinates logistics for stones sourced from Botswana, Russia, and Canada.
United Arab Emirates
Dubai Multi Commodities Centre free zone attracts trading houses seeking zero-tax rough diamond transit and re-export positioning. The UAE Ministry of Economy implements Kimberley Process import verification for rough parcels. Dubai's Almas Tower cluster hosts De Beers and other major tender operations serving Gulf and South Asian buyers.
Diamond Jewelry Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with heritage houses commanding premium positioning while mid-market chains optimize store density. The vendor base concentrates around three strategic archetypes: vertically integrated miners with retail arms, multi-brand jewelry conglomerates, and independent heritage maisons. Consolidation pressures favor scale-driven players with captive rough supply or dense retail footprints. Competitive moves center on dual-brand natural-and-lab-grown portfolio construction and blockchain provenance integration.
Among North American retail conglomerates, Signet Jewelers occupies a position exemplifying mid-market bridal dominance through store network scale. Within the luxury heritage tier, Chow Tai Fook and De Beers plc represent contrasting archetypes: the former anchoring Greater China demand through gold-diamond fusion expertise, the latter sustaining dual-brand manufacturing across natural and synthetic positioning. These three entities illustrate how geographic specialization and supply chain configuration determine competitive differentiation.
| Leading Market Players |
|---|
| Signet Jewelers |
| Chow Tai Fook |
| De Beers plc |
| Graff |
| Harry Winston |
| Tiffany & Co. |
| Bulgari S.p.A. |
| Van Cleef & Arpels |
| Cartier |
| Others |
Cost & Logistics Intelligence
Bridal registry purchasers in North America and ceremonial gift buyers across Greater China anchor pricing power with certified natural stones, forcing retailers to absorb metal volatility through inventory hedging while synthetic producers compete on shorter fulfillment cycles.
Pricing Analysis
Short lead-time premiums attach to custom bridal settings with GIA-certified naturals, while spot inventory of standard carat weights trades at modest discounts. Three-tier pricing structure across heritage maisons, national chains, and digital-native platforms reflects brand equity and certification depth. Cost compression in lab-grown bridal tiers intensifies because HPHT producers scale two-carat-plus capacity. Retail consumers show highest price sensitivity; luxury buyers purchasing five-carat-plus stones through private salons demonstrate minimal elasticity.
Supply Chain Analysis
Freight costs from Antwerp tender houses to Surat cutting units and onward to Mumbai retail corridors shape working capital requirements for polished goods pipelines. Rough diamond extraction draws from Botswana, Russia, and Canada; polished manufacturing rests on Surat SEZ duty exemptions. Single-source vulnerability concentrates in Russian rough supply subject to trade restriction uncertainty. Distribution runs through Antwerp clearing nodes, Dubai free-zone transit, and direct manufacturer-to-retail channels for bridal specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where FTC disclosure mandates and BIS hallmarking extensions erect barrier-to-entry moats favoring scaled players with dedicated certification infrastructure.
For Market Incumbents: Lock in gemologist staffing density across counter positions to differentiate service quality as lab-grown detection complexity rises. Secure captive rough supply through long-term offtake agreements with De Beers or Alrosa to defend margin position against synthetic price erosion. Channel control through flagship expansion in tier-two Indian cities reinforces volume capture as BIS enforcement formalizes previously informal retail.
For New Entrants and Emerging Players: Digital-native collectors researching certification parameters via mobile applications represent the most penetrable buyer archetype before showroom visits. White-space targets include Vietnam's Ho Chi Minh City and Hanoi corridors with rising disposable income and limited branded jewelry presence. A direct-to-consumer platform with virtual try-on and searchable GIA report databases offers viable go-to-market positioning without legacy store overhead.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated mid-cap specialists with captive Surat manufacturing and established North American bridal retail footprints. Long-term viability hinges on dual-brand natural-and-lab-grown portfolio construction capability. Blockchain provenance integration adoption rates among heritage houses signal inflection toward transparency as table stakes.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Integration | Distributed ledger convergence with GIA records enables immutable chain-of-custody documentation for natural stones. |
| Dual-Brand Portfolio Construction | Natural and Lightbox lab-grown positioning allows De Beers to capture volume across diverging buyer preferences. |
| Surat SEZ Capacity Expansion | Duty exemptions on rough imports attract cutting and polishing investment anchoring India's processing dominance. |
| Gemologist Staffing Density Investment | GIA-trained professionals capable of distinguishing advanced synthetics remain concentrated in established trading centers. |
| Tier-Two India Retail Formalization | BIS hallmarking extension to secondary cities creates first-mover positioning for compliant national chains. |
Research Approach
Independent corroboration across polished goods traders, bridal retail operators, and certification laboratory executives underwrites the qualitative findings in this study. Primary interviews with GIA grading specialists, Surat SEZ manufacturing directors, Mumbai retail corridor managers, and Antwerp tender house operators combined with secondary validation from customs trade data, Bureau of Indian Standards enforcement records, and FTC disclosure enforcement actions. Bottom-up transaction volume estimates and top-down market sizing triangulate across the analysis window.
Historical reference periods anchored the forecast window to seasonal wedding-cycle purchasing patterns and metal price volatility regimes. Segmentation modeling incorporated product type, material alloy, customer archetype, and sales channel dimensions across the projection horizon. CAGRs derived from trend extrapolation of bridal registry density, urban wealth accumulation trajectories, and synthetic production capacity scaling. Industry-specific inputs included GIA report issuance rates, Surat SEZ rough import volumes, and FTC enforcement action frequency.
Revisions become necessary when regulatory disclosure mandates tighten beyond current FTC or BIS frameworks, or when geopolitical disruption severs Russian rough supply channels. Forecasts reflect assumptions about continued urbanization in Indian and Chinese metropolitan corridors and stable electricity pricing for HPHT synthesis operations. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Jewelry
Demi-Fine Jewelry Market
Jewelry
Jewellery Market
Jewelry
Bead Products Market
Jewelry
Imitation Jewelry Market
Jewelry
Japan Jewellery Market
Jewelry
Germany Luxury Jewelry Market
Jewelry
Smart Jewelry Market
Jewelry
South Korea Luxury Jewelry Market
Jewelry
Latin America Jewelry Market
Jewelry
Quartz Ring Market
Jewelry
Luxury Fine Jewellery Market
Jewelry
Customized Jewelry Market
Jewelry
Wedding Rings Market
Jewelry
3D Printing Jewelry Service Market
Jewelry
Crystal Bracelets Market
Jewelry
Canada Luxury Jewelry Market