
 Germany Data Center Market | 2026-2036
Germany Data Center Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Data Center Market Analysis
Financial services demand is recalibrating Germany's data center requirements as algorithmic trading and real-time risk analytics expand. CyrusOne leverages its Frankfurt campus infrastructure to anchor wholesale capacity for banking clients. Equinix competes through interconnection density at its Munich and Dusseldorf facilities. Noris Network differentiates via sovereign cloud specialization for public-sector workloads.
A data center constitutes a dedicated facility housing compute, storage, and networking equipment with controlled environmental parameters—typically maintaining temperatures between 18°C and 27°C and power densities exceeding 10 kW per rack—for processing, distributing, and archiving digital information. Colocation services capture the dominant revenue share as enterprises divest owned infrastructure. Edge computing deployments within the technology segment represent the fastest structural expansion, driven by latency-sensitive manufacturing automation in Bavaria and Baden-Württemberg. Green data centers command premium pricing through renewable power purchase agreements and liquid cooling architectures.
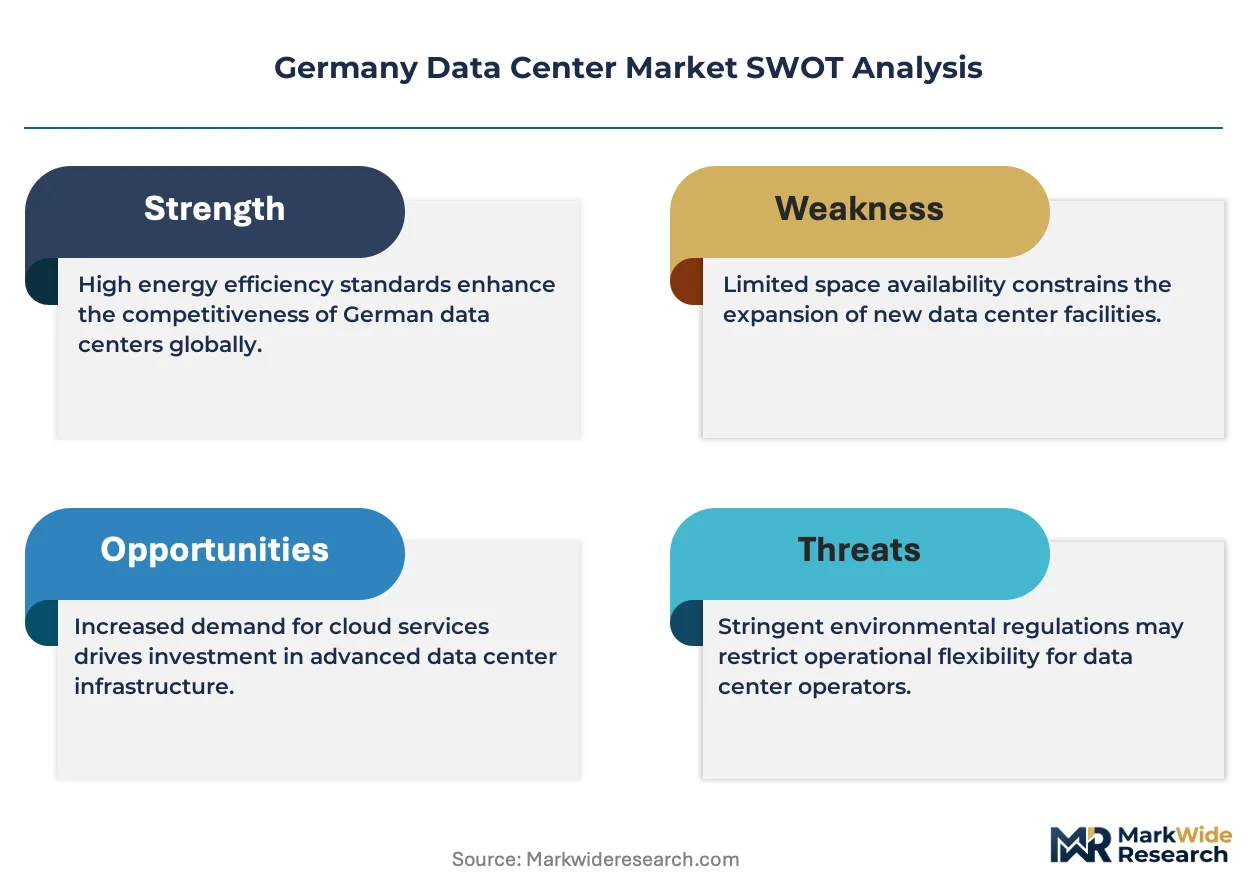
The Federal Network Agency (Bundesnetzagentur) enforces grid stability standards that constrain power allocation to new facilities in constrained regions. Germany's Energy Efficiency Act (EnEfG) mandates reporting thresholds and efficiency benchmarks that reshape facility design decisions. KBA building codes and DIN standards govern fire suppression and structural resilience for critical infrastructure. Stakeholders must monitor grid interconnection queue timelines and renewable energy certificate availability before committing capital to greenfield developments.
Market Dynamics
The Energy Efficiency Act (EnEfG) is compressing facility design timelines as operators retrofit existing assets and constrain new builds to sub-1.3 PUE thresholds before grid interconnection approval.
Growth Catalysts
- Algorithmic trading infrastructure:Frankfurt's banking concentration demands sub-10 millisecond latency for risk analytics, pulling wholesale capacity into the Rhine-Main corridor.
- EnEfG efficiency mandates:Regulatory pressure on power usage effectiveness accelerates liquid cooling retrofits and waste heat recovery installations.
- Baden-Württemberg manufacturing automation:Automotive and precision engineering clusters deploy edge nodes for real-time quality control and predictive maintenance.
Market Restraints
- Grid interconnection queues:Bundesnetzagentur stability protocols delay power allocation in Frankfurt and Munich metro zones by 18-36 months.
- Copper and electrical steel volatility:Transformer and busbar input costs swing with commodity markets, squeezing margins on fixed-price construction contracts.
- Land scarcity in Rhine-Main:Hyperscale campus expansion faces zoning restrictions and agricultural land preservation statutes in Hesse.
Strategic Opportunities
- Eastern Länder greenfield zones:Saxony and Brandenburg offer unconstrained grid capacity and lower land costs for 100MW+ campus developments.
- Waste heat district integration:Municipal heating network partnerships in Berlin and Hamburg monetize thermal output from high-density compute.
- Sovereign cloud specialization:Public-sector procurement rules favor domestic operators with certified data residency for federal and state workloads.
Industry Challenges
- Certified engineering talent scarcity:DIN-compliant electrical and mechanical specialists command premium wages, extending commissioning timelines.
- Legacy facility retrofit complexity:Older Frankfurt and Dusseldorf sites require structural reinforcement and cooling plant replacement to meet EnEfG thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Data Center Market |
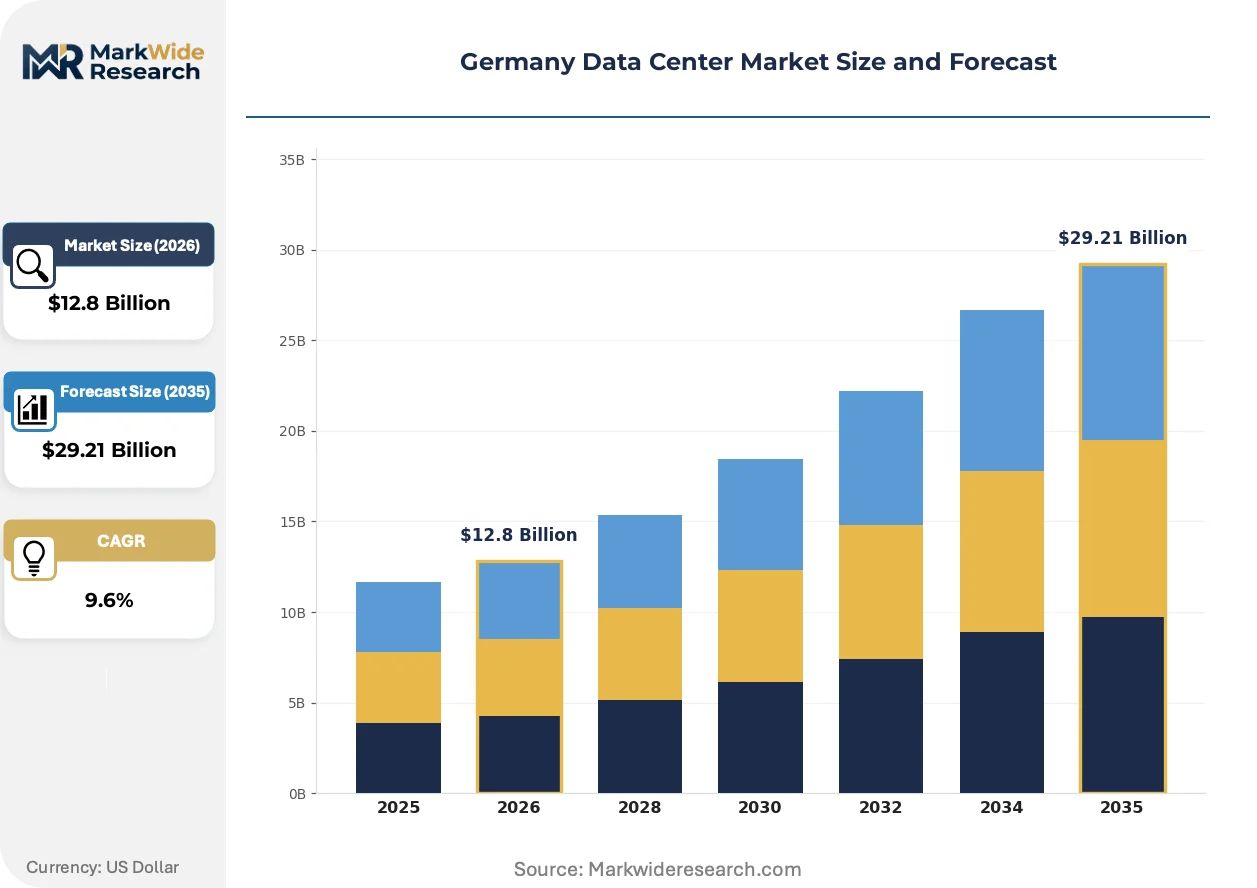
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $29.21 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colocation, Managed Hosting, Cloud Services, Dedicated Hosting End User: IT Companies, Financial Institutions, Retail Businesses, Government Agencies Service Type: Infrastructure-as-a-Service, Platform-as-a-Service, Software-as-a-Service, Storage-as-a-Service Technology: Virtualization, Edge Computing, Artificial Intelligence, Green Data Centers |
| Companies Covered | CyrusOne, VIRTUS Data Centres, Equinix, Telehouse, Noris Network, Digital Realty, Iron Mountain, nLighten, NTT DATA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Data Center Market Emerging Trajectories
Liquid cooling architectures and AI-optimized thermal management are displacing conventional air-handling units as rack densities exceed 30kW in financial services and research computing deployments.
Direct-to-chip liquid cooling is expanding into hyperscale and enterprise colocation facilities as thermal loads from GPU clusters render traditional CRAH units economically unviable. Operators in Frankfurt and Berlin are retrofitting existing white space with rear-door heat exchangers and immersion tanks to maintain service level agreements. This technology is expanding into secondary markets as Bavarian manufacturing campuses deploy edge nodes with sealed liquid loops for contamination-sensitive environments.
The Energy Efficiency Act (EnEfG) mandates annual power usage effectiveness reporting and establishes efficiency benchmarks that disqualify non-compliant facilities from public-sector contracts. Grid operators now require PUE documentation before granting medium-voltage interconnection approvals in constrained regions. Facility engineers respond by integrating real-time energy monitoring and automated workload placement to maintain continuous compliance.
Enterprise buyers are consolidating vendor relationships and demanding outcome-based contracts that bundle colocation, connectivity, and managed services under single accountability structures. Wholesale customers in banking and automotive sectors favor multi-year agreements with renewable energy guarantees over traditional space-and-power leases. This preference shift concentrates procurement authority among operators with vertically integrated sustainability credentials and direct utility partnerships.
Germany Data Center Market Segmentation
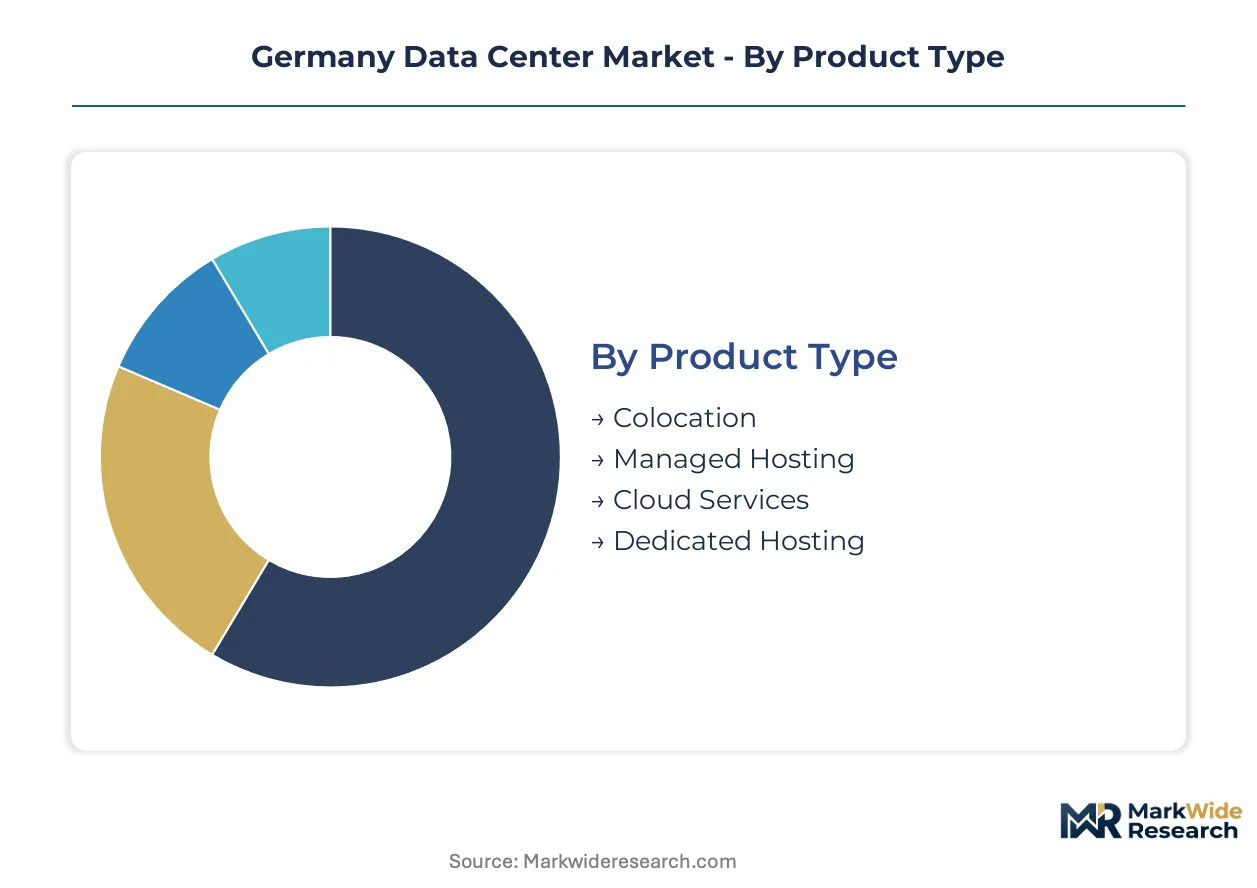
Segmentation in Germany's data center market reveals how regulatory pressure and workload specialization fragment procurement patterns. The Energy Efficiency Act creates divergent compliance costs across service tiers, while sovereign cloud mandates reshape public-sector vendor selection criteria.
Product Type:
Standardized wholesale contracts dominate at the commodity end, whereas customized multi-tenant configurations command premium positioning through liquid cooling integration and renewable energy guarantees.
- Colocation:Wholesale space-and-power agreements with standardized rack densities between 10-30kW per cabinet. Frankfurt's Rhine-Main corridor concentrates banking demand for sub-10 millisecond latency to trading venues, with CyrusOne and Equinix expanding campus footprints to capture this workflow.
- Managed Hosting:Operator-owned hardware with bundled remote hands and network management services. Bavarian automotive clusters deploy these configurations for ERP systems requiring DIN-compliant security certifications without internal data center operations.
- Cloud Services:On-demand compute and storage with API-driven provisioning.
- Dedicated Hosting:Single-tenant physical infrastructure with customized network segmentation.
Leading the category by volume: Colocation. Growing fastest: Cloud Services.
End User:
Procurement sophistication varies sharply — algorithmic trading desks demand microsecond-level SLAs while municipal agencies prioritize data residency certifications over performance metrics.
- IT Companies:SaaS providers and technology vendors building distributed application architectures. These buyers cluster in Berlin and Munich, driving demand for interconnection-rich facilities with direct cloud on-ramps to AWS, Azure, and Google Cloud.
- Financial Institutions:Banks, insurers, and asset managers with regulatory-mandated disaster recovery requirements. Frankfurt's BaFin-supervised entities require geographically separated active-active configurations, pulling capacity into Dusseldorf and Hamburg as secondary sites.
- Retail Businesses:E-commerce platforms and omnichannel operators.
- Government Agencies:Federal and state entities with sovereign cloud mandates.
Highest procurement volume: Financial Institutions. Steepest expansion trajectory: Government Agencies.
Service Type:
Margin structures compress toward infrastructure layers while platform and software tiers capture value through developer productivity tools and managed database services.
- Infrastructure-as-a-Service:Raw compute, storage, and network resources with self-service provisioning. Manufacturing automation in Baden-Württemberg deploys IaaS for burst capacity during production ramp-ups, avoiding capital-intensive owned infrastructure.
- Platform-as-a-Service:Managed runtime environments with automated scaling and CI/CD pipeline integration. Berlin's startup ecosystem concentrates demand here, favoring container orchestration and serverless architectures over virtual machine management.
- Software-as-a-Service:Application delivery through browser-based interfaces.
- Storage-as-a-Service:Object, block, and file storage with tiered durability guarantees.
Dominant revenue share: Infrastructure-as-a-Service. Climbing the fastest: Platform-as-a-Service.
Technology:
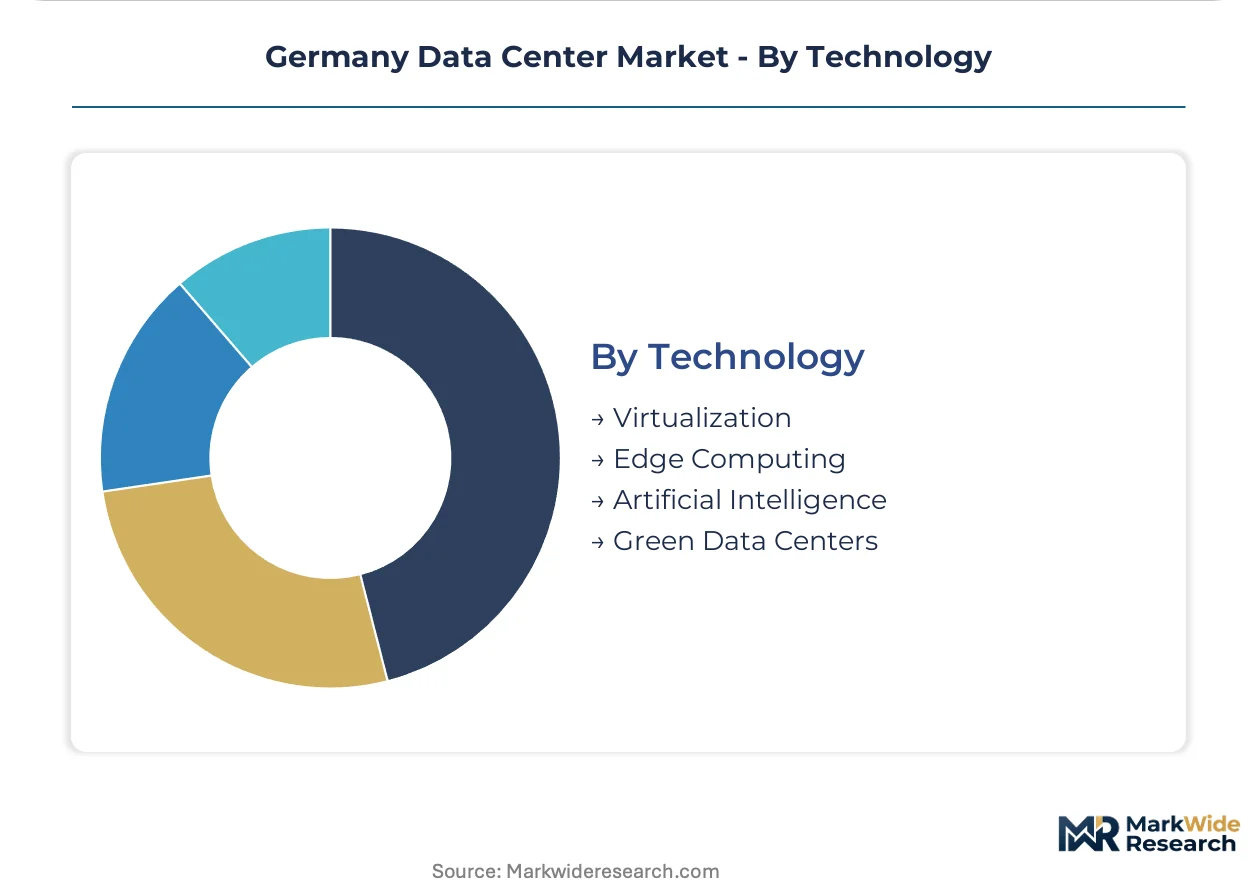
Legacy virtualization platforms face displacement pressure as AI training clusters and edge inference nodes demand specialized silicon and thermal architectures.
- Virtualization:Hypervisor-based server consolidation with resource pooling across physical hosts. Established Frankfurt facilities rely heavily on VMware and KVM deployments, though these face retrofit costs to accommodate GPU-heavy workloads.
- Edge Computing:Distributed processing nodes positioned proximate to data sources. Automotive quality control systems in Stuttgart deploy these for real-time defect detection, with sub-5 millisecond response requirements ruling out centralized cloud processing.
- Artificial Intelligence:GPU and TPU clusters for model training and inference.
- Green Data Centers:Facilities with PUE below 1.3 and renewable energy procurement.
Widest installed base: Virtualization. Gaining share fastest: Edge Computing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's data center capacity concentrates in western and southern Länder where financial services and manufacturing demand pull infrastructure investment, while eastern regions offer unconstrained expansion corridors for hyperscale campus development.
North Rhine-Westphalia
Düsseldorf's insurance sector and Cologne's media conglomerates drive colocation demand for disaster recovery and content delivery workloads. The state's building code authority enforces DIN 18095 fire resistance standards for critical infrastructure. Datacenter operators cluster along the Rhine corridor between Düsseldorf and Cologne, leveraging existing fiber networks and grid interconnection capacity.
Hesse
Frankfurt's position as Europe's primary financial hub generates sub-10 millisecond latency requirements for algorithmic trading and risk analytics platforms. The Federal Network Agency's grid stability protocols delay new power allocations by 18-36 months in the Rhine-Main metropolitan zone. CyrusOne and Equinix operate expanding campus facilities in Eschborn and Frankfurt's outskirts to capture wholesale banking demand.
Bavaria
Munich's technology sector and automotive engineering clusters deploy edge computing nodes for real-time manufacturing automation and quality control systems. The Bavarian State Ministry for Economic Affairs supports industrial digitalization through funding programs for smart factory infrastructure. Manufacturing campuses in Ingolstadt and Regensburg integrate on-premises edge nodes with centralized cloud resources for predictive maintenance workloads.
Baden-Württemberg
Stuttgart's precision engineering and automotive supply chains demand low-latency processing for computer vision-based defect detection on production lines. The state's environmental ministry applies stringent building efficiency standards that align with federal EnEfG mandates. Edge deployments in Böblingen and Mannheim serve Mittelstand manufacturers transitioning to Industry 4.0 automation architectures.
Berlin-Brandenburg
The capital region's startup ecosystem and public-sector data residency requirements attract sovereign cloud specialists and hyperscale greenfield developments. Brandenburg's unconstrained grid capacity and lower land costs enable 100MW+ campus construction outside Berlin's administrative boundary. NLighten and Noris Network target federal and state procurement opportunities through certified domestic facilities in the metropolitan periphery.
Germany Data Center Market Vendor Landscape
Top-tier vendors anchor wholesale and hyperscale capacity, while specialized regional operators capture sovereign and edge computing segments. The market exhibits tiered consolidation with international platforms controlling interconnection-rich metro facilities and domestic specialists securing public-sector contracts. Three archetypes dominate: global colocation platforms with multi-market footprints, sovereign cloud specialists emphasizing data residency certifications, and edge infrastructure providers targeting manufacturing automation. Capacity expansion and strategic partnerships constitute the dominant competitive vectors as operators secure renewable energy supply and district heating integration agreements.
Among international platform operators, CyrusOne and Equinix occupy positions exemplifying wholesale campus scale and interconnection density respectively. CyrusOne's Frankfurt infrastructure anchors banking sector demand through purpose-built facilities, while Equinix leverages Munich and Düsseldorf metro presence for enterprise connectivity requirements. Noris Network represents the sovereign specialization archetype, targeting federal procurement through certified domestic operations. These three entities illustrate how geographic footprint and certification positioning segment competitive access to distinct buyer categories across financial, enterprise, and public-sector verticals.
| Leading Market Players |
|---|
| CyrusOne |
| VIRTUS Data Centres |
| Equinix |
| Telehouse |
| Noris Network |
| Digital Realty |
| Iron Mountain |
| nLighten |
| NTT DATA |
| Others |
Supply Flow & Price Mechanics
Premium-mid-economy pricing differentiation across German data center tiers manifests in divergent supply chain configurations, with liquid-cooled sovereign facilities commanding renewable energy premiums while commodity colocation operators absorb transformer and copper volatility through fixed-price construction contracts.
Pricing Analysis
Short lead-time premiums for grid-interconnection-ready capacity in Frankfurt and Munich command significant markups over greenfield developments in Saxony and Brandenburg with 18-36 month queue timelines. Pricing stratifies across premium liquid-cooled sovereign tiers, standard air-cooled wholesale configurations, and economy remote-hands colocation based on PUE certification thresholds and data residency compliance. Cost compression in standard wholesale tiers is intensifying because copper and electrical steel input volatility squeezes margins on fixed-price EPC contracts. Banking and automotive verticals demonstrate lowest price sensitivity due to regulatory-mandated disaster recovery requirements, while retail and mid-market SaaS buyers negotiate aggressively on space-and-power rates.
Supply Chain Analysis
Regional distribution centers for critical power equipment cluster in the Netherlands, Germany, and Denmark to serve Rhine-Main and Berlin-Brandenburg construction corridors with compressed lead times. Transformer manufacturing draws from electrical steel mills in Japan, South Korea, and Germany, while liquid cooling components source from Taiwan and China. Single-source vulnerability in medium-voltage switchgear creates bottleneck risk for facilities targeting EnEfG compliance deadlines. Distribution runs through specialized critical infrastructure logistics providers with DIN-certified handling protocols rather than general freight networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's data center market operates as a cost-of-compliance story where the Energy Efficiency Act constructs a formidable barrier-to-entry moat, rewarding operators with certified PUE performance and established grid interconnection relationships while marginalizing sub-scale players unable to absorb retrofit capital requirements.
For Market Incumbents: Cement market position through accelerated liquid cooling retrofits in legacy Frankfurt and Düsseldorf facilities before EnEfG enforcement hardens, while securing long-term renewable power purchase agreements to lock in green premium pricing against emerging sovereign cloud specialists. Grid interconnection queue priority represents the critical defensive lever against hyperscale entrants with deeper balance sheets. For New Entrants and Emerging Players: Direct-to-sovereign-cloud procurement channels offer the most penetrable route, targeting federal and state agencies with certified domestic facilities in Berlin-Brandenburg's unconstrained grid zones where established operators lack data residency specialization. Municipal heating network partnerships in Hamburg and Berlin provide differentiated thermal monetization narratives for public-sector RFPs. For Investors and Strategic Acquirers: Re-rating potential sits with sovereign-specialist operators given public-sector procurement rule changes favoring certified domestic facilities, as federal workload migration accelerates. Long-term viability hinges on 100MW+ campus scalability in eastern Länder with direct utility partnerships. Watch EnEfG amendment timelines as the critical inflection signal for stranded asset risk in non-compliant legacy portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Retrofit Program | EnEfG compliance unlocks grid interconnection approvals in constrained Rhine-Main zones. |
| Renewable Power Purchase Agreement | Direct utility partnerships secure green energy premiums for banking and automotive contracts. |
| Waste Heat District Integration | Municipal heating network partnerships in Berlin monetize thermal output from GPU clusters. |
| Sovereign Cloud Certification | Bundescloud compliance opens federal procurement pipelines closed to international operators. |
| Eastern Länder Campus Expansion | Saxony and Brandenburg greenfield zones bypass 18-36 month grid queues plaguing western metros. |
Methodological Framework
Document review covered Bundesnetzagentur grid interconnection databases, EnEfG regulatory filings, and DIN standards documentation, complemented by interviews with data center engineering directors, utility interconnection planners, and federal procurement officers. Secondary validation drew from operator sustainability reports, renewable energy certificate registries, and municipal heating network integration case studies. Bottom-up capacity installation tracking and top-down infrastructure investment flow analysis were triangulated against disclosed PUE performance metrics.
Historical deployment patterns were cross-referenced against panel input from facility operators and EPC contractors to construct the analytical framework across the projection horizon. Segmentation dimensions modeled include service tier, end-user vertical, cooling architecture type, and regional grid constraint classification. CAGRs were derived from capacity pipeline analysis and power allocation approval timelines. Forecast inputs incorporated transformer lead time volatility and renewable energy procurement availability curves specific to German utility markets.
The model holds under stable EnEfG enforcement and grid stability protocol continuity; deviation in federal efficiency mandate amendments or accelerated interconnection queue processing would shift capacity deployment trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Malaysia Data Center Server Market
Data Center Infrastructure
Global Data Center Rack PDU Market
Data Center Infrastructure
Spain Data Center Physical Security Market
Data Center Infrastructure
Europe Containerized Data Center Market
Data Center Infrastructure
Russia Data Center Construction Market
Data Center Infrastructure
South Africa Data Center Physical Security Market
Data Center Infrastructure
Austria Data Center Physical Security Market
Data Center Infrastructure
Data Center UPS Market
Data Center Infrastructure
Data Center Infrastructure Management Market
Data Center Infrastructure
United Arab Emirates Data Center Power Market
Data Center Infrastructure
Middle East Data Center Power Market
Data Center Infrastructure
Taiwan Data Center Server Market
Data Center Infrastructure
Data Center Modeling and Simulation Tools Market
Data Center Infrastructure
Data Center Containment Solution Market
Data Center Infrastructure
Mexico Data Center Power Market
Data Center Infrastructure
Thailand Data Center Physical Security Market