
 Immunodeficient Mouse Models Market | 2026-2036
Immunodeficient Mouse Models Market Size, Share, and Industry Trends Forecast 2026-2036
Immunodeficient Mouse Models Market Insights
Aftermarket service revenue from model characterization and colony management is reconfiguring how suppliers capture lifetime value from research clients. Charles River Laboratories International Inc. leverages its global breeding infrastructure to sustain long-term contracts with multinational pharmaceutical sponsors. The Jackson Laboratory anchors academic demand through its repository of over 12,000 genetically defined strains. Biocytogen Co., Ltd. differentiates via proprietary humanized immune system platforms that command premium positioning in immuno-oncology workflows.
Immunodeficient mouse models are laboratory mice engineered with specific genetic mutations—such as Prkdcscid, Il2rgnull, or Rag1/2 knockout—that eliminate adaptive and/or innate immune function, enabling engraftment of human cells, tissues, or tumor xenografts for disease modeling and therapeutic testing. These models typically require maintenance in specialized pathogen-free facilities with controlled microbiome status to prevent opportunistic infections that would compromise experimental integrity. The NOD-scid IL2Rγnull (NSG) segment dominates high-value oncology applications due to superior human cell engraftment rates, while gene therapy applications represent the fastest-expanding demand pool as AAV and lentiviral vector developers require immunotolerant hosts for preclinical safety assessment. Contract research organizations now constitute a concentrated end user segment where procurement consolidates around vendors offering integrated in vivo pharmacology services alongside model supply.
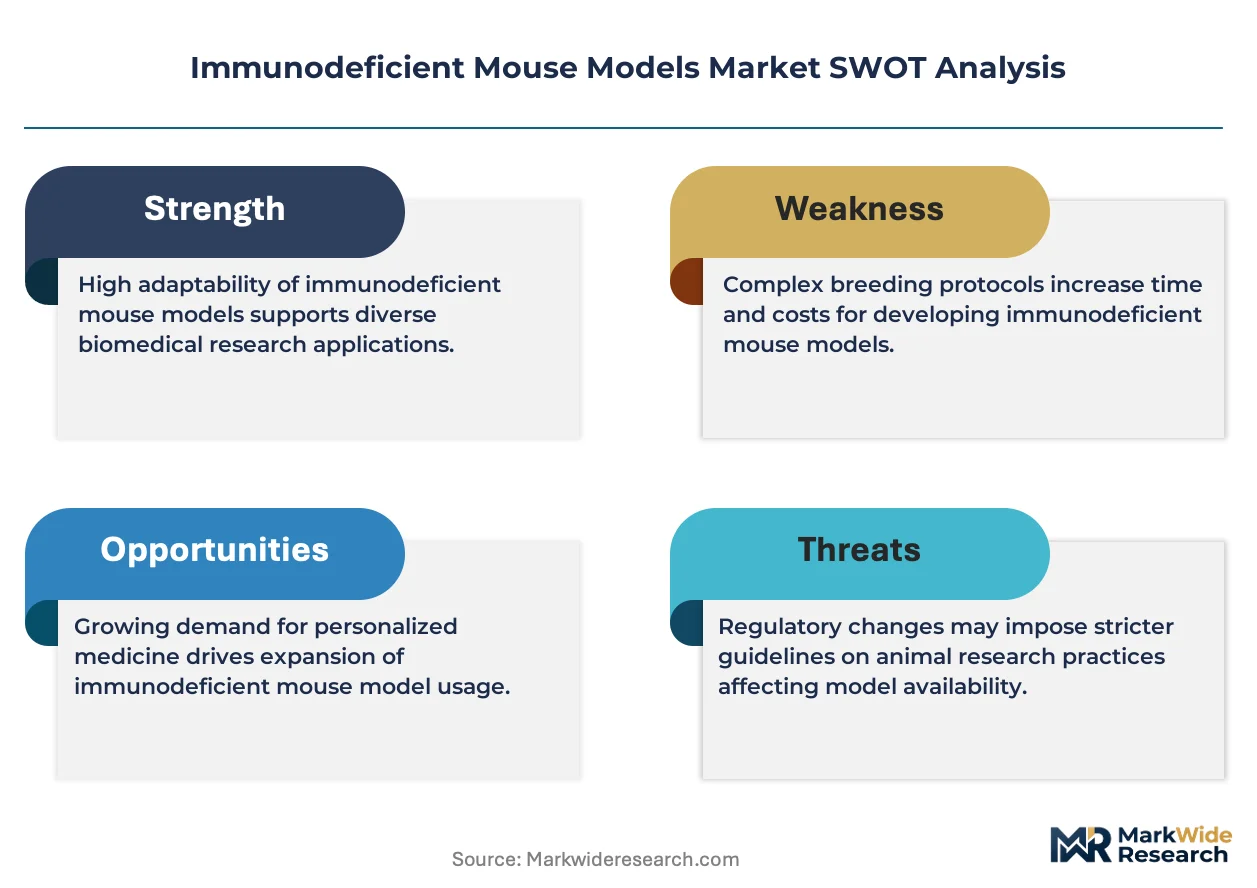
FDA guidance on xenograft model qualification for oncology drug development, combined with USDA Animal Welfare Act enforcement and AAALAC accreditation requirements, structures operational compliance costs and vendor selection criteria for US-based buyers. EMA's Committee for Medicinal Products for Human Use has issued reflection papers on the acceptability of humanized mouse data in marketing authorization applications, creating cross-Atlantic divergence in evidentiary standards. Stakeholders must monitor evolving regulatory convergence on humanized model validation protocols while building flexible breeding capacity that can pivot across application areas as therapeutic modalities fragment.
Market Dynamics
The FDA's Animal Rule pathway for biologics development is compressing validation timelines and forcing suppliers to pre-qualify model characterization data before sponsor engagement, reshaping how breeding operations align with downstream regulatory submissions.
Growth Catalysts
- Oncology Pipeline Expansion:Pharmaceutical companies now command the fastest-growing end user segment as immuno-oncology programs multiply, driving procurement of NSG and humanized immune system platforms for xenograft studies.
- Gene Therapy Vector Testing:AAV and lentiviral vector developers require immunotolerant hosts for preclinical safety assessment, creating sustained pull for Rag1/2 knockout and Il2rgnull models.
- US CRO Cluster Concentration:NCI-designated cancer centers and large contract research organization hubs in Boston, San Diego, and the Research Triangle Park concentrate demand and enable scale economies in colony management.
Market Restraints
- Specialized Facility Capex:Pathogen-free barrier facilities with controlled microbiome status require construction costs that exclude mid-tier academic labs from direct model ownership.
- Supplier Concentration Risk:The global breeding infrastructure consolidates around a handful of vendors with validated genetic repositories, creating single-source dependency for high-engraftment strains.
- USDA Animal Welfare Act Compliance:Enforcement actions and AAALAC accreditation audits impose recurring operational costs that compress margins for smaller breeding operations.
Strategic Opportunities
- Aftermarket Service Expansion:Model characterization and colony management contracts extend lifetime value capture beyond initial sales, with Charles River Laboratories International Inc. already structuring multi-year service agreements.
- EMA Reflection Paper Alignment:The Committee for Medicinal Products for Human Use guidance on humanized mouse data acceptability creates pathway clarity for European marketing authorization submissions.
- CRISPR-Engineered Strain Development:Rapid precision editing of immunodeficiency loci is compressing development timelines for next-generation models with tissue-specific humanization.
Industry Challenges
- Genetic Drift Monitoring:Maintaining strain fidelity across distributed breeding colonies requires continuous genotyping protocols that strain quality control budgets.
- Cross-Atlantic Validation Divergence:Evidentiary standards for humanized model data remain misaligned between FDA and EMA frameworks, forcing sponsors to duplicate studies.
- Microbiome Standardization:Opportunistic infection prevention demands rigorous vendor qualification that extends procurement cycles and complicates multi-site study design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immunodeficient Mouse Models Market |
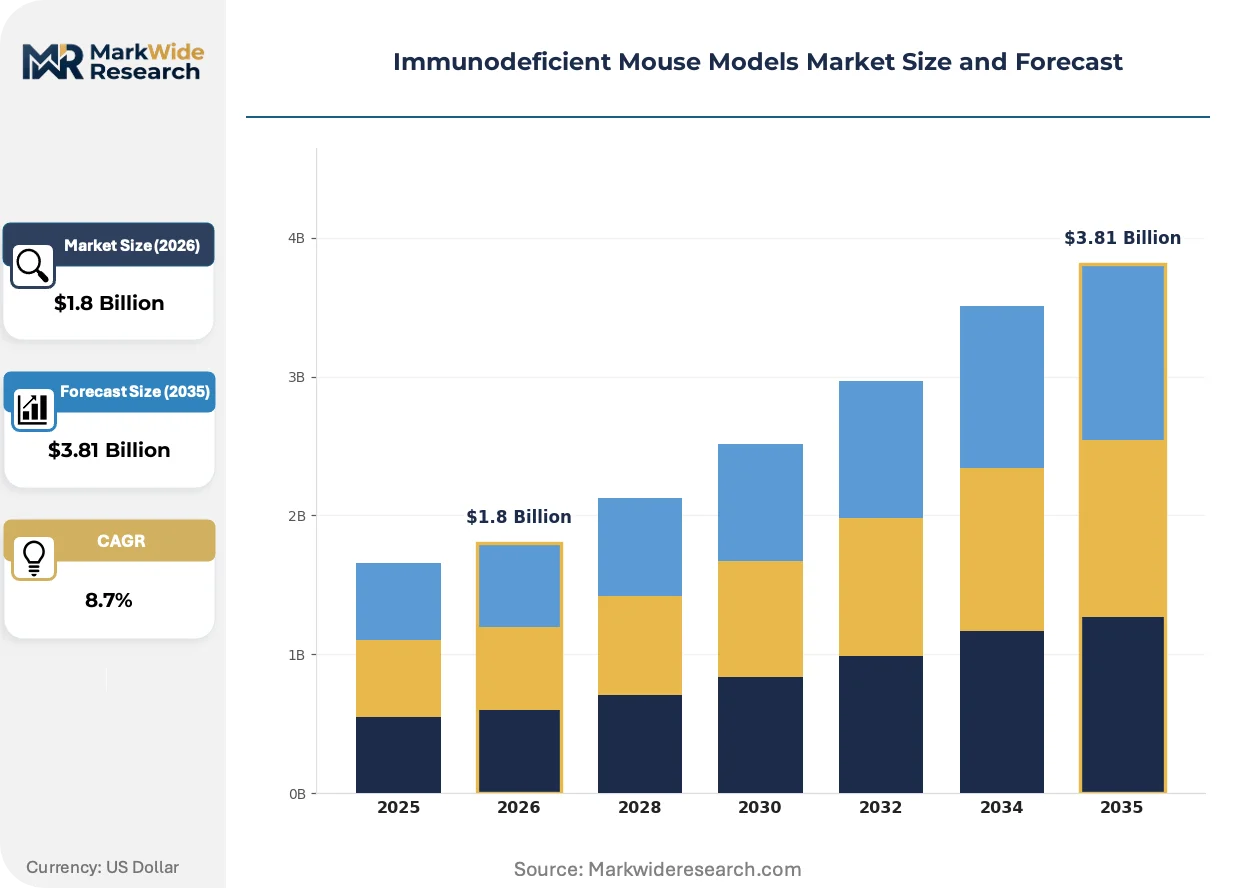
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Mouse Type: NOD, SCID, BALB/c, C57BL/6 Application: Oncology, Infectious Disease, Immunology, Gene Therapy End User: Academic Institutions, Pharmaceutical Companies, Contract Research Organizations, Biotech Firms Research Focus: Transplantation, Drug Development, Vaccine Research, Biomarker Discovery |
| Companies Covered | Charles River Laboratories International Inc., The Jackson Laboratory, Inotiv, Inc., Taconic Biosciences, Inc., Cyagen Biosciences Inc., Biocytogen Co., Ltd., GenOway, Crown Bioscience, Inc., GemPharmatech Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immunodeficient Mouse Models Market Trends and Innovations
In silico model development and digital twin technologies are beginning to reshape how sponsors design preclinical studies, compressing the traditional experimental iteration cycle before physical model deployment.
Digital pathology platforms integrating whole-slide imaging with AI-assisted tumor burden quantification are virtualizing the histopathology workflow that previously required manual scoring by veterinary pathologists. Large pharmaceutical sponsors now mandate these platforms for multi-site oncology studies to standardize readouts across CRO partners. This virtualization is compressing study report timelines and enabling real-time data sharing between sponsors and regulators.
REACH registration requirements for novel immunosuppressive compounds used in model maintenance are forcing European breeding facilities to substitute legacy reagents with compliant alternatives. The industrial consequence is reformulation of standard conditioning regimens for humanized mouse construction. Gene therapy applications face the steepest adaptation costs as myeloablative protocols require revalidation under the new substance restrictions.
Consolidated procurement through integrated in vivo pharmacology service contracts is displacing standalone model purchases among mid-cap biotechnology sponsors. CROs offering bundled colony management, study execution, and regulatory documentation now capture preference over specialized breeders. This pattern concentrates most visibly in the United States, where sponsor finance teams favor operational expenditure structures over capital-intensive internal vivarium investment.
Immunodeficient Mouse Models Market Segmentation
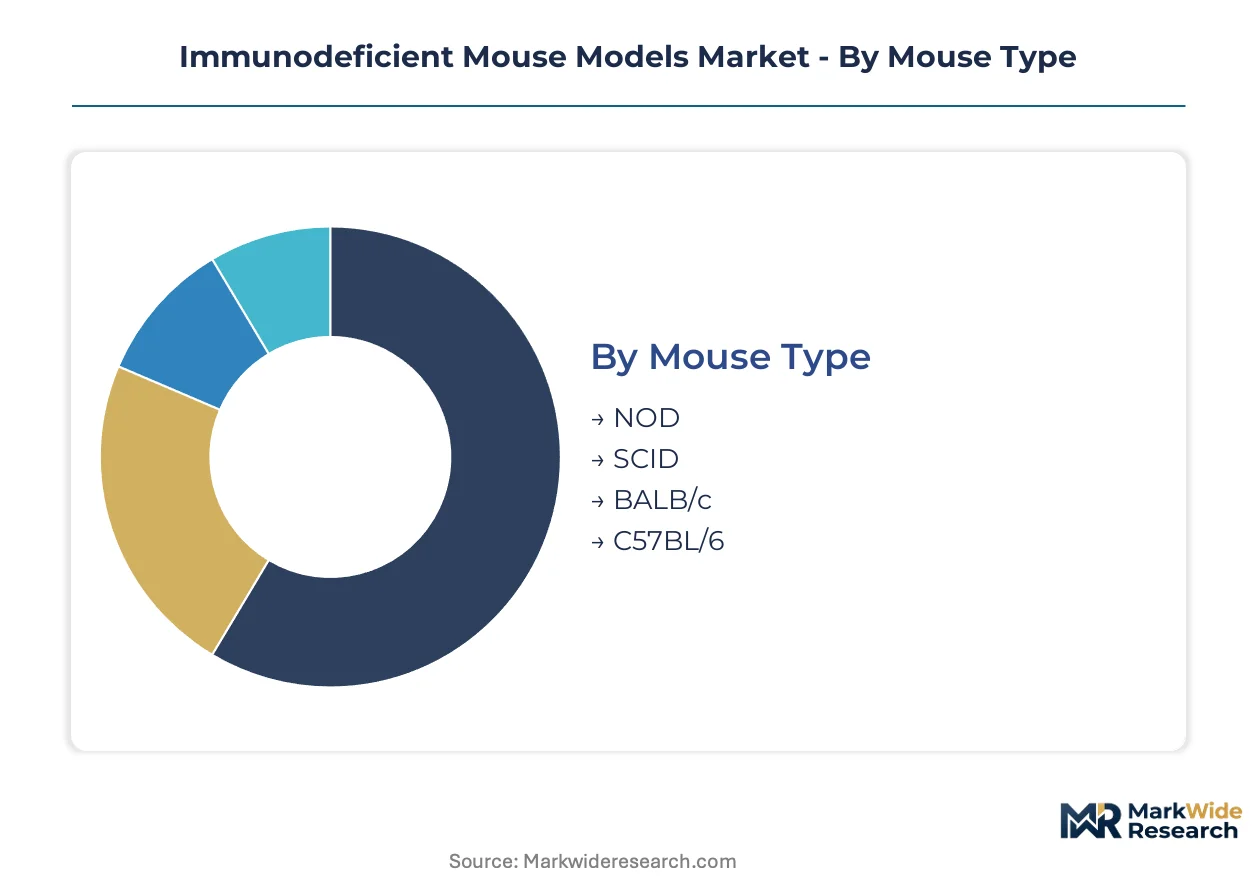
Immunodeficient mouse models fragment across genetic backgrounds, therapeutic applications, and procurement channels. Each segmentation axis reveals distinct value capture mechanisms and technical validation requirements that structure supplier positioning.
Mouse Type:
The genetic background spectrum spans mature commercial standards to emerging precision-engineered variants, with engraftment efficiency and immune system completeness determining price positioning.
- NOD:Non-obese diabetic backgrounds provide the foundational genetic chassis for super-immunodeficient derivatives. NCI-designated cancer centers in the United States concentrate procurement for humanized immune system construction.
- SCID:Severe combined immunodeficiency variants carry Prkdcscid mutations that eliminate adaptive immune function. Pharmaceutical sponsors in Boston and San Diego CRO clusters drive volume for xenograft oncology workflows.
- BALB/c:Inbred albino strain serves as immunocompetent reference and base for targeted immunodeficiency modifications. Academic repositories maintain legacy colonies for comparative immunology studies.
- C57BL/6:Black 6 background offers the most widely characterized mouse genome for CRISPR-edited immunodeficiency knock-ins. Gene therapy vector developers favor this chassis for AAV preclinical safety assessment.
NOD and SCID derivatives retain volume leadership across commercial breeding operations; C57BL/6-engineered variants hold the steepest expansion curve as precision editing tools mature.
Application:
Demand concentrates in therapeutic areas where human tissue engraftment provides irreplaceable pharmacodynamic insight, with modality-specific requirements shaping model specification.
- Oncology:Patient-derived xenograft and cell line-derived xenograft studies require NSG and NOG platforms with maximal human cell engraftment capacity. Large pharmaceutical sponsors now mandate humanized immune system models for immuno-oncology combination trials.
- Infectious Disease:Human pathogen susceptibility testing depends on strains with humanized cytokine loci to support myeloid lineage development. NIH and BARDA funding streams sustain academic and government laboratory demand.
- Immunology:Graft-versus-host disease modeling and human immune system development studies utilize partial immunodeficiency backgrounds. The Jackson Laboratory repository anchors strain distribution for basic research institutions.
- Gene Therapy:AAV and lentiviral vector biodistribution, shedding, and integration studies require immunotolerant hosts lacking adaptive and innate surveillance. FDA Animal Rule pathway submissions compress validation timelines for qualified model supply.
Oncology commands the largest procurement volumes; gene therapy applications are expanding most quickly as vector development pipelines deepen.
End User:
Customer segmentation reflects capital intensity gradients and outsourcing preferences, with procurement consolidation favoring integrated service providers over standalone breeders.
- Academic Institutions:University vivarium operations face barrier facility construction costs that exclude direct ownership of high-value immunodeficient strains. Core facility models and repository access agreements structure research access.
- Pharmaceutical Companies:Multinational sponsors now represent the fastest-growing demand pool as oncology and gene therapy pipelines multiply. Integrated in vivo pharmacology contracts displace standalone model purchases among mid-cap biotechnology firms.
- Contract Research Organizations:Charles River Laboratories International Inc. and similar vendors bundle colony management with study execution to capture long-term service revenue. CRO procurement concentrates in United States clusters where sponsor proximity enables real-time study oversight.
- Biotech Firms:Venture-backed developers prioritize operational expenditure structures over capital-intensive internal vivarium investment. Flexible breeding capacity agreements support pipeline-stage transitions from discovery to IND-enabling studies.
Contract research organizations retain volume leadership through bundled service capture; pharmaceutical companies are gaining share fastest as internal pipeline requirements scale.
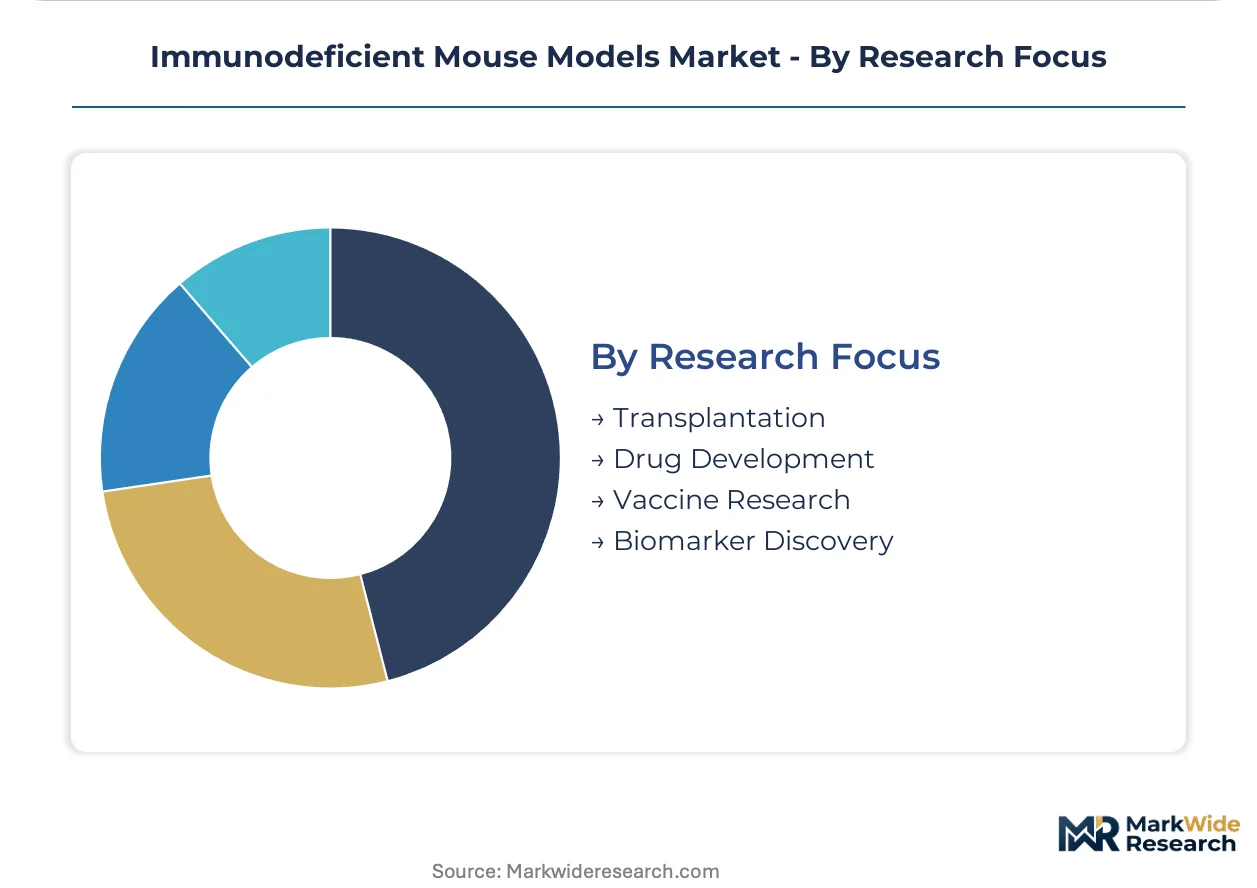
Research Focus:
Experimental objectives determine model specification depth, with regulatory submission requirements imposing qualification standards that stratify supplier tiers.
- Transplantation:Human hematopoietic stem cell engraftment and tissue xenotransplantation studies demand NSG and related platforms with IL2 receptor gamma chain deficiency. Conditioning regimen optimization remains a technical service differentiator.
- Drug Development:Efficacy and pharmacokinetic studies for oncology and immuno-oncology therapeutics require validated xenograft platforms with documented engraftment rates. FDA guidance on model qualification structures evidentiary requirements for IND submissions.
- Vaccine Research:Human immune system platforms enable assessment of vaccine immunogenicity in contexts approximating human responses. Emerging infectious disease preparedness programs sustain government laboratory demand.
- Biomarker Discovery:Patient-derived xenograft molecular profiling and circulating tumor DNA monitoring studies integrate humanized mouse platforms with companion diagnostic development. Biopharmaceutical sponsors fund these programs through translational medicine divisions.
Drug development applications retain volume leadership across commercial breeding operations; gene therapy-linked research focus areas hold the steepest expansion trajectory as vector modalities fragment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States show the lowest price elasticity as regulatory validation requirements override cost considerations, while European academic institutions exhibit the highest sensitivity due to fragmented procurement budgets. Asian markets demonstrate intermediate elasticity with volume-discount sensitivity dominating premium strain selection.
United States
NCI-designated cancer centers and Boston-San Diego CRO clusters drive concentrated demand for NSG platforms. FDA Animal Rule pathway requirements compress validation timelines and pre-qualify model characterization data. The Research Triangle Park concentration enables real-time sponsor oversight through proximity-based procurement.
Germany
Max Planck Institute networks and Helmholtz research centers sustain demand for genetically defined reference strains. REACH registration requirements for immunosuppressive conditioning reagents force protocol reformulation. The Munich-Heidelberg biotech corridor concentrates gene therapy vector developers requiring Rag1/2 knockout models.
China
Domestic pharmaceutical pipeline expansion and government-funded precision medicine initiatives accelerate humanized immune system platform adoption. NMPA alignment with international validation standards structures import substitution strategies. Shanghai and Suzhou biotech parks concentrate CRISPR-engineered strain development capabilities.
United Kingdom
Wellcome Trust and MRC funding streams anchor academic demand for The Jackson Laboratory repository access. MHRA convergence with EMA reflection papers on humanized model data acceptability clarifies marketing authorization pathways. The Cambridge-London corridor concentrates immuno-oncology biotech sponsors.
Japan
PMDA guidance on xenograft model qualification for oncology submissions structures evidentiary requirements for domestic sponsors. RIKEN and national university medical schools maintain specialized pathogen-free facilities. The Kansai biocluster around Osaka sustains demand for infectious disease humanization platforms.
Immunodeficient Mouse Models Market Competitive Landscape
Capability concentration sits with precision-engineering specialists; scale advantage sits with global breeding infrastructure operators. The market structures around three tiers: multinational integrated service providers, regional repository specialists, and emerging CRISPR-platform developers. Consolidation dynamics favor vendors bundling colony management with regulatory documentation services. Geographic expansion through distributed breeding networks and strategic technology licensing represent the dominant competitive moves.
Within the integrated service tier, Charles River Laboratories International Inc. exemplifies scale-driven positioning through multi-year pharmaceutical contracts. The Jackson Laboratory anchors academic demand archetypes through repository-scale genetic diversity. Biocytogen Co., Ltd. occupies the precision-engineering vector with proprietary humanization platforms commanding premium positioning in immuno-oncology workflows.
| Leading Market Players |
|---|
| Charles River Laboratories International Inc. |
| The Jackson Laboratory |
| Inotiv, Inc. |
| Taconic Biosciences, Inc. |
| Cyagen Biosciences Inc. |
| Biocytogen Co., Ltd. |
| GenOway |
| Crown Bioscience, Inc. |
| GemPharmatech Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Charles River Laboratories International Inc. and The Jackson Laboratory anchor the global breeding infrastructure, concentrating genetic repository control in the United States and channeling margin capture toward aftermarket characterization services and long-term colony management contracts. This upstream consolidation enables premium positioning for NSG and humanized immune system platforms while compressing pricing flexibility for mid-tier academic buyers lacking barrier facility capital.
Pricing Analysis
Aftermarket service revenue from model characterization and colony management drives lifetime value capture beyond initial strain sales. Three-tier pricing structure across premium, standard, and economy levels stratifies by engraftment efficiency documentation and AAALAC accreditation status. Pricing pressure stems from REACH registration compliance costs forcing European protocol reformulation. Academic institutions exhibit highest price sensitivity due to fragmented procurement budgets; pharmaceutical sponsors show lowest elasticity as FDA Animal Rule validation requirements override cost considerations.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from multinational CROs stabilize cash flow for specialized pathogen-free breeding operations. Production concentrates in the United States, China, and Germany. The supply chain draws from CRISPR-edited founder lines, human hematopoietic stem cell sourcing networks, and myeloablative conditioning reagents. Single-source vulnerability for high-engraftment NSG strains creates concentration risk. Distribution runs through integrated in vivo pharmacology service contracts displacing standalone model purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive positioning as humanized immune system interoperability becomes the decisive ecosystem battleground. CRISPR-engineered strain repositories and digital pathology integration are reshaping how sponsors lock in multi-year supplier relationships.
For Market Incumbents: Harden genetic repository control through continuous genotyping protocols that maintain strain fidelity across distributed colonies. Expand backward integration into CRISPR-edited founder line development to reduce dependency on external precision-engineering platforms. Biocytogen Co., Ltd. and similar precision-engineering specialists threaten premium positioning with proprietary humanization technologies.
For New Entrants and Emerging Players: Build out CRISPR-platform capabilities in tissue-specific humanization for gene therapy vector testing applications. Gene therapy represents the most penetrable demand pool as AAV and lentiviral developers require immunotolerant hosts with compressed validation timelines. Position through regulatory documentation bundling alongside model supply to capture sponsor preference.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed CRO platforms lacking precision-engineering capabilities but holding multinational pharmaceutical contracts. Long-term viability rests on CRISPR-edited strain pipelines and digital pathology integration depth. Watch for FDA-EMA convergence on humanized model validation protocols as inflection signal for cross-Atlantic service expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR-Engineered Strain Development | Precision editing of immunodeficiency loci compresses timelines for next-generation humanized platforms. |
| Aftermarket Service Expansion | Model characterization contracts extend lifetime value capture beyond initial sales to research clients. |
| Digital Pathology Integration | AI-assisted tumor burden quantification virtualizes histopathology workflows for multi-site oncology studies. |
| Regulatory Documentation Bundling | FDA Animal Rule pathway alignment pre-qualifies model data for sponsor IND submissions. |
| Geographic Breeding Network Expansion | Distributed pathogen-free facilities reduce logistics risk and enable real-time sponsor oversight. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, vivarium operations managers, and CRO procurement directors converged on the working assumptions underlying this analysis. Primary interviews with these stakeholders combined with secondary validation from FDA guidance documents, EMA reflection papers, AAALAC accreditation databases, and NCI funding disclosures. Bottom-up strain procurement volume estimates triangulated against top-down pharmaceutical R&D expenditure allocation.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling volume and value outputs through segmentation by mouse type, therapeutic application, end user archetype, and research focus area. CAGRs derived from regression analysis of historical procurement patterns and pipeline-stage transition rates. Gene therapy vector development timelines and immuno-oncology combination trial expansion served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by CRISPR-platform specialists or integrated digital pathology providers would shift outcomes. Macroeconomic contraction in pharmaceutical R&D budgets, regulatory divergence on humanized model validation, or breakthrough in silico model alternatives would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gene Editing & CRISPR
France Gene Editing Market
Gene Editing & CRISPR
Genetically Modified Animal Model Market
Gene Editing & CRISPR
Knockout Mice Model Market
Gene Editing & CRISPR
Cloning and Mutagenesis Market
Gene Editing & CRISPR
Genome Editing Market
Gene Editing & CRISPR
South Korea Gene Editing Market
Gene Editing & CRISPR
Rare NGR1 Fusion Market
Gene Editing & CRISPR
Japan Gene Editing Market
Gene Editing & CRISPR
Microbial Gene Editing Services Market
Gene Editing & CRISPR
CRISPR Genomic Cure Market
Gene Editing & CRISPR
Gene Editing Market
Gene Editing & CRISPR
Mutation Detection Kits in Genome Editing Market
Gene Editing & CRISPR
Global CRISPR and Cas Genes Market
Gene Editing & CRISPR
Italy Gene Editing Market
Gene Editing & CRISPR
Genome Engineering Market
Gene Editing & CRISPR
Global Plant Breeding and CRISPR Plant Market