
 US Hangover Cure Products Market | 2026-2036
US Hangover Cure Products Market Size, Share, and Industry Trends Forecast 2026-2036
US Hangover Cure Products Market Insights
NSF Certified for Sport and cGMP compliance is reorganizing competitive access in the US Hangover Cure Products Market, filtering out unqualified entrants before shelf placement begins. Liquid I.V., Inc. leverages its electrolyte hydration science to dominate pharmacy and convenience store channels nationwide. Flyby anchors its position through herbal extract formulations targeting liver support, while More Labs competes on effervescent delivery formats that accelerate absorption rates.
US hangover cure products comprise functional consumables engineered with electrolytes, vitamins, amino acids, and herbal extracts to mitigate alcohol-induced dehydration, inflammation, and nutrient depletion. These formulations typically specify active compound concentrations measured in milligrams per serving, with manufacturing processes requiring controlled temperature blending to preserve bioactive stability. Supplements and beverages currently occupy the largest margin pools due to repeat purchase frequency and brand loyalty, while powders represent the fastest-growing formulation as consumers prioritize portability and dose customization. Online retail channels extend reach into subscription models, though pharmacies retain higher trust conversion for first-time buyers seeking pharmacist validation.
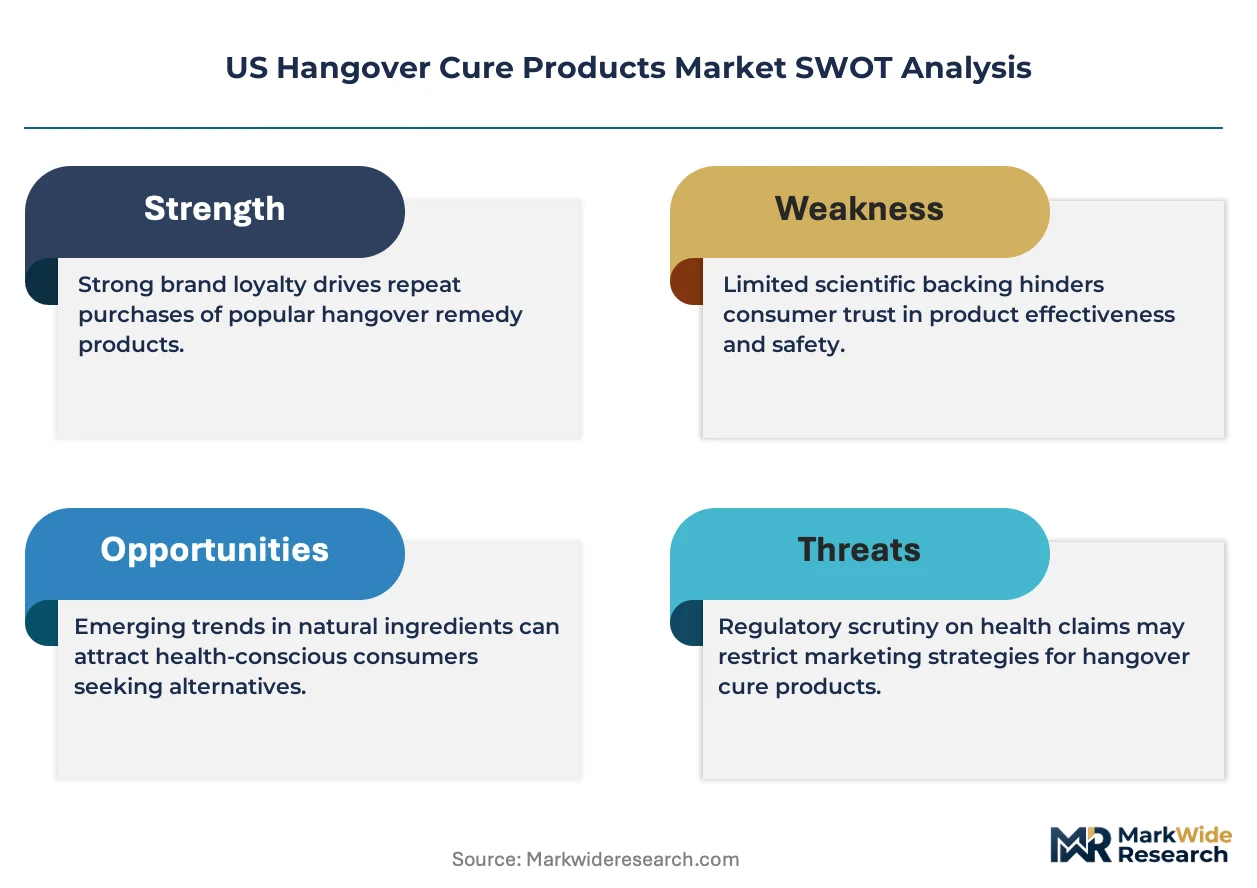
FDA oversees dietary supplement Good Manufacturing Practices while FTC enforces truth-in-advertising standards for hangover mitigation claims, collectively elevating compliance costs but protecting legitimate manufacturers from deceptive competitors. State-level alcohol beverage control boards in California, Texas, and New York impose additional layer restrictions on co-marketing with licensed liquor retailers. Stakeholders must monitor evolving NAD case precedents on health claim substantiation to preempt enforcement actions that could force formula reformulation or labeling overhauls.
Market Dynamics
FTC advertising substantiation enforcement is compressing marketing latitude for hangover mitigation claims, forcing manufacturers to restructure clinical validation pipelines and reformulate positioning strategies around FDA-compliant dietary supplement frameworks.
Growth Catalysts
- Urban hospitality corridor density:Young professionals in California, Texas, and New York now normalize pre-event and post-event recovery protocols as standard nightlife hygiene, creating habitual consumption patterns that sustain subscription revenue models.
- NSF Certified for Sport penetration:Athlete-adjacent positioning through third-party certification opens pharmacy and specialty retail placement previously blocked to unverified supplement entrants.
- cGMP compliance infrastructure:Contract manufacturers with FDA-audited facilities now offer turnkey production pathways that reduce capital barriers for formulation startups targeting effervescent and powder formats.
Market Restraints
- Ingredient cost volatility:N-acetylcysteine and dihydromyricetin supply concentrates in Chinese botanical extraction hubs, exposing margin compression from tariff fluctuations and shipping rate spikes.
- Regulatory friction:State alcohol beverage control boards in California, Texas, and New York restrict co-marketing with licensed liquor retailers, severing a natural point-of-sale channel for impulse purchase conversion.
- Clinical substantiation burden:NAD case precedents on health claim validation now require controlled human studies for hangover symptom relief assertions, elevating R&D spend thresholds beyond bootstrap capital capacity.
Strategic Opportunities
- Corporate wellness integration:Employer-sponsored programs in Austin, Nashville, and Miami now subsidize recovery supplements as productivity tools, opening B2B procurement channels with annual contract structures.
- Effervescent delivery convergence:Rapid-dissolve tablet technology paired with single-serve stick packaging addresses portability demands from festival attendees and business travelers seeking TSA-compliant formats.
- Subscription channel innovation:Direct-to-consumer platforms with predictive replenishment algorithms capture higher lifetime value through habit-formation data models that anticipate consumption cycles.
Industry Challenges
- Bioactive stability expertise:Formulation chemists with controlled-temperature blending specialization command premium compensation, constraining talent acquisition for mid-scale manufacturers scaling powder production lines.
- Labeling compliance timelines:FDA dietary supplement structure-function claim notifications require 30-day pre-market submission windows that delay seasonal campaign launches and influencer collaboration schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Hangover Cure Products Market |
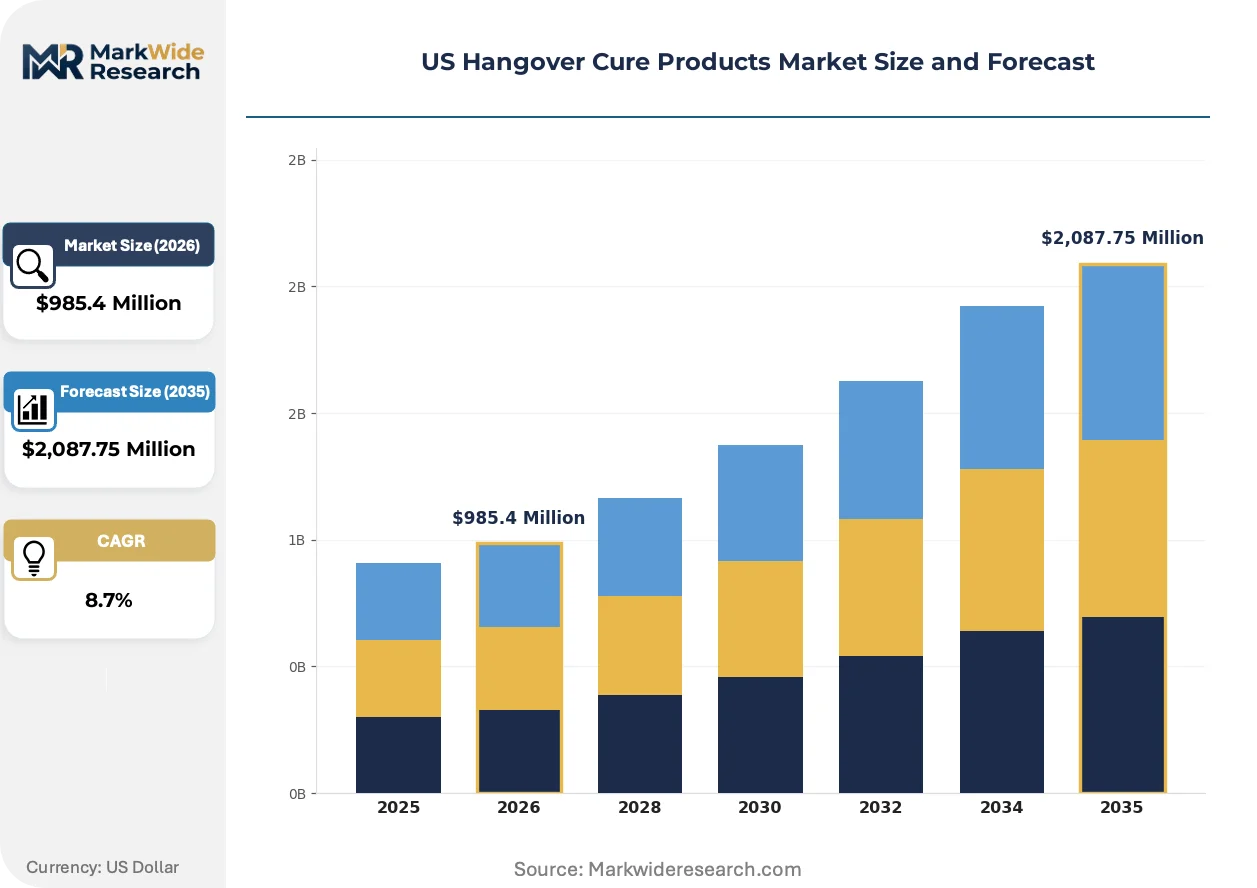
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $2,087.75 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Supplements, Beverages, Powders, Capsules Active Ingredient: Vitamins, Electrolytes, Herbal Extracts, Amino Acids Distribution Channel: Online Retail, Pharmacies, Supermarkets, Convenience Stores Formulation: Ready-to-Drink, Effervescent, Liquid, Solid |
| Companies Covered | Liquid I.V., Inc., Flyby, Abbott, Drinkwel, LLC, DOTSHOT, Rally Labs LLC, More Labs, No Days Wasted, Cheers Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Hangover Cure Products Market Trends and Innovations
Personalized hydration telemetry and rapid-absorption delivery formats are restructuring how consumers evaluate efficacy, shifting competitive advantage from ingredient lists to measurable physiological response verification.
Nanostructured liposomal encapsulation is fragmenting bioavailability benchmarks across the supplement category. This phospholipid-based delivery system protects active compounds from gastric degradation. Premium-positioned consumers in Manhattan and Los Angeles now demand pharmacokinetic data demonstrating 3-5x absorption improvement over standard formulations. The technology is fragmenting competitive positioning by creating a dual-tier market separated by clinical validation depth rather than ingredient composition alone.
FTC endorsement disclosure guidelines now mandate explicit material connection statements for influencer partnerships promoting hangover recovery outcomes. This policy compresses organic reach metrics for brands dependent on nightlife personality marketing. Supplement manufacturers with established pharmacy channel presence now redirect spend toward pharmacist education programs that bypass social platform algorithm restrictions.
Subscription bundling with adjacent wellness categories now displaces single-product trial purchases. Consumers in San Francisco and Chicago increasingly purchase hangover recovery as annual commitments paired with sleep support and hydration monitoring devices. This behavioral shift concentrates customer acquisition cost recovery into Q1, requiring manufacturers to restructure cash flow management and inventory forecasting models around predictable replenishment cadences rather than episodic demand spikes.
US Hangover Cure Products Market Segmentation
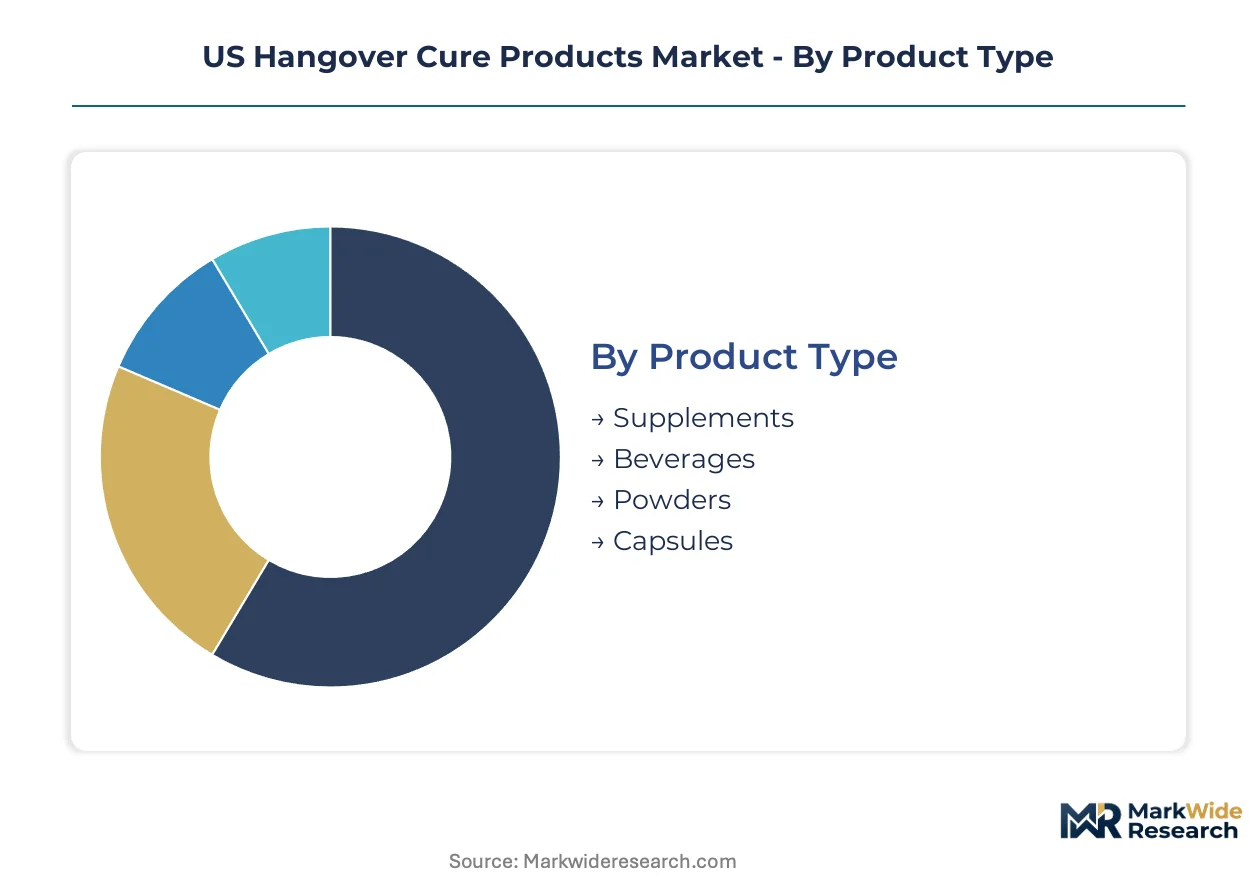
Product architecture in the US hangover cure market determines regulatory pathway, shelf placement, and repeat purchase economics. Formulation choices directly constrain which active compounds survive manufacturing and which distribution channels permit placement.
Product Type:
Supplements face the strongest substitution pressure from functional beverages that bypass pill fatigue and offer immediate consumption rituals.
- Supplements:Encapsulated or tableted formulations containing standardized extracts of milk thistle, N-acetylcysteine, and B-vitamin complexes. California and New York urban professionals favor these for pre-event dosing protocols that signal intentional self-care. FDA structure-function claim requirements limit hangover-specific marketing to qualified health statements.
- Beverages:Ready-to-drink formulations with electrolyte bases, often fortified with L-theanine or prickly pear extract. Texas convenience store chains stock these adjacent to energy drinks, capturing impulse purchases from festival attendees and sports spectators seeking immediate hydration.
- Powders:Single-serve stick packs enabling dose customization and TSA-compliant portability. Nashville and Miami corporate wellness programs distribute these through employer-subsidized vending.
- Capsules:Hard-shell gelatin or vegetable-derived delivery systems protecting acid-sensitive compounds from gastric degradation. Pharmacy channel placement requires cGMP documentation and lot-level traceability.
Supplements retain volume leadership; powders hold the steepest expansion curve.
Active Ingredient:
Cost tier stratification separates commodity vitamin blends from premium botanical extracts requiring specialized extraction infrastructure.
- Vitamins:B-complex formulations, particularly B1, B6, and B12, addressing alcohol-induced thiamine depletion. Mass-market positioning in supermarket channels competes primarily on unit price per serving.
- Electrolytes:Sodium, potassium, and magnesium salts formulated for rapid osmotic absorption. Manhattan and Los Angeles consumers demand pharmacokinetic data demonstrating superior bioavailability against sports drink substitutes.
- Herbal Extracts:Dihydromyricetin from Hovenia dulcis and silymarin from milk thistle, sourced predominantly through Chinese botanical extraction hubs. Tariff exposure and shipping rate volatility compress margins for formulations dependent on these inputs.
- Amino Acids:L-cysteine, L-glutamine, and taurine supporting glutathione synthesis and liver detoxification pathways. Athlete-adjacent positioning through NSF Certified for Sport opens specialty retail placement previously blocked to unverified entrants.
Electrolytes dominate unit volume; herbal extracts command the highest price per serving.
Distribution Channel:
Customer type divergence separates subscription-driven online purchasers from pharmacist-validated first-time buyers seeking professional endorsement.
- Online Retail:Direct-to-consumer platforms with predictive replenishment algorithms capturing lifetime value through habit-formation data models. FTC endorsement disclosure guidelines now mandate explicit material connection statements for influencer partnerships.
- Pharmacies:Chain and independent drugstores where pharmacist consultation drives trial conversion. California, Texas, and New York state alcohol beverage control boards restrict co-marketing with licensed liquor retailers, severing natural point-of-sale adjacencies.
- Supermarkets:Mass-market placement competing for shelf space against adjacent functional beverage categories. Seasonal campaign launches face FDA dietary supplement structure-function claim notification delays.
- Convenience Stores:Impulse-oriented stocking patterns targeting late-night and early-morning purchase occasions. Limited SKU depth favors established brands with national distribution infrastructure.
Online retail captures the highest growth velocity; pharmacies maintain superior trust conversion rates.
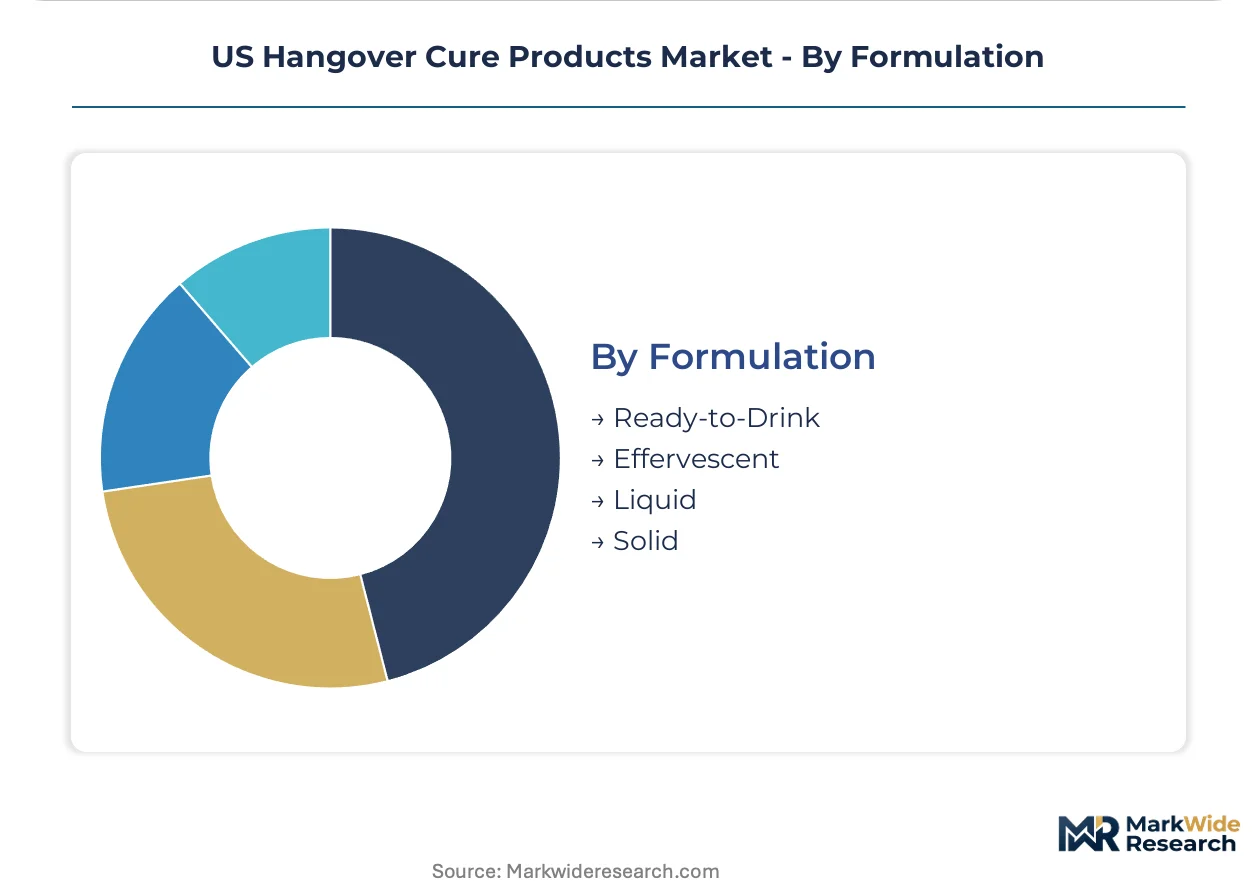
Formulation:
Maturity gradients separate established ready-to-drink formats from emerging effervescent technologies requiring specialized manufacturing equipment.
- Ready-to-Drink:Pre-mixed liquid formulations in aluminum cans or PET bottles. Shelf-stable processing requirements limit active compound selection to pH-tolerant molecules.
- Effervescent:Rapid-dissolve tablet technology producing carbonated solutions upon water contact. Contract manufacturers with FDA-audited facilities now offer turnkey production pathways reducing capital barriers for startups.
- Liquid:Concentrated tinctures or syrups requiring measured dosing. Bioactive stability expertise commands premium compensation, constraining talent acquisition for mid-scale manufacturers.
- Solid:Compressed tablets or gel capsules with extended release characteristics. Controlled-temperature blending preserves compound integrity through manufacturing.
Ready-to-Drink maintains category volume; effervescent formats are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Young professionals in dense urban hospitality corridors concentrate purchasing power across state-level markets where nightlife density and wellness culture intersect most intensely. State alcohol beverage control boards impose varying restrictions on retail placement and co-marketing activities. California, Texas, and New York anchor volume concentration while emerging metros in Tennessee and Florida accelerate per-capita adoption curves.
California
Bay Area and Los Angeles professionals normalize pre-event recovery protocols as standard nightlife hygiene, sustaining subscription revenue models through habitual consumption patterns. The state's Department of Alcoholic Beverage Control restricts co-marketing with licensed liquor retailers, severing natural point-of-sale adjacencies for impulse purchase conversion. San Francisco consumers increasingly bundle hangover recovery with sleep support and hydration monitoring devices through annual wellness commitments.
Texas
Austin's corporate wellness programs subsidize recovery supplements as productivity tools, opening B2B procurement channels with annual contract structures. State-level alcohol beverage control regulations limit shelf placement adjacent to licensed liquor retailers in Dallas and Houston convenience store chains. Festival attendees in Austin and sports spectators in Houston drive impulse purchases of ready-to-drink formulations stocked near energy drink categories.
New York
Manhattan consumers demand pharmacokinetic data demonstrating superior bioavailability, fragmenting competitive positioning toward clinical validation depth. New York State Liquor Authority restrictions on co-marketing with licensed retailers compress marketing latitude for hangover mitigation claims. Brooklyn and Manhattan pharmacy channels retain higher trust conversion for first-time buyers seeking pharmacist validation before trial.
Tennessee
Nashville's employer-subsidized vending programs distribute single-serve powder formats through corporate wellness infrastructure. State regulatory frameworks for dietary supplement retail remain less restrictive than coastal jurisdictions, enabling faster seasonal campaign launches. Music festival corridors in Middle Tennessee generate concentrated demand spikes requiring predictive inventory forecasting models.
Florida
Miami's hospitality sector integrates recovery protocols into employee wellness programs, normalizing consumption across service industry demographics. State alcohol beverage regulations permit broader retail placement flexibility than California or New York jurisdictions. South Florida's cruise ship and hospitality worker density creates concentrated B2B procurement opportunities with recurring contract structures.
US Hangover Cure Products Market Competitive Landscape
Player mix skews toward electrolyte hydration specialists and herbal extract formulators competing through differentiated delivery formats and certification credentials. The competitive structure fragments across three tiers: pharmacy-validated brands with NSF Certified for Sport credentials, direct-to-consumer specialists leveraging subscription algorithms, and convenience-store-oriented beverage formulators. Strategic moves concentrate on effervescent delivery technology licensing and cGMP contract manufacturing partnerships that reduce capital barriers for formulation startups.
Within the hydration science tier, Liquid I.V., Inc. and Abbott occupy positions exemplifying electrolyte-focused pharmacy channel penetration. Among herbal extract specialists, Flyby represents archetypal liver-support positioning through standardized botanical formulations. More Labs anchors the effervescent delivery vector with rapid-dissolve tablet technology. These three entities collectively illustrate how certification depth, absorption technology, and channel specialization fragment competitive access across the US market.
| Leading Market Players |
|---|
| Liquid I.V., Inc. |
| Flyby |
| Abbott |
| Drinkwel, LLC |
| DOTSHOT |
| Rally Labs LLC |
| More Labs |
| No Days Wasted |
| Cheers Health |
| Others |
Pricing and Supply Chain Analysis
N-acetylcysteine substitution for glutathione precursors is simultaneously relocating active ingredient sourcing toward Chinese botanical extraction hubs and compressing margin structures for mid-tier supplement manufacturers. This input shift forces formulators to absorb tariff volatility or reformulate around domestically produced amino acid alternatives.
Pricing Analysis
Cost-plus contracts with Chinese extraction suppliers index to shipping rate fluctuations and tariff schedules, creating margin unpredictability for herbal-dependent formulations. Three-tier pricing structure across premium, standard, and economy levels separates NSF Certified for Sport products from cGMP-compliant alternatives and unverified entrants. Cost compression in the standard tier is intensifying because contract manufacturers compete aggressively for pharmacy channel placement. Corporate wellness procurement teams exhibit lowest price sensitivity due to productivity-justified budgets, while convenience store impulse buyers demand sub-dollar unit economics.
Supply Chain Analysis
China anchors dihydromyricetin and silymarin extraction capacity, while India supplies pharmaceutical-grade amino acids and domestic US manufacturers dominate electrolyte compounding. Formulation draws from N-acetylcysteine, Hovenia dulcis extract, and liposomal phospholipid carriers as critical inputs. Single-source vulnerability concentrates in Hubei Province extraction facilities subject to environmental compliance shutdowns. Distribution runs through cGMP-certified contract manufacturers to pharmacy chains, direct-to-consumer platforms, and convenience store distributors with divergent lot-traceability requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity opens as personalized hydration telemetry and rapid-absorption delivery formats splinter consumer preference into micro-segments too small for mass-market incumbents to serve profitably.
For Market Incumbents: Compound pharmacy channel presence through NSF Certified for Sport expansion and cGMP contract manufacturing partnerships that lock out unqualified entrants. Defend against effervescent delivery specialists by acquiring rapid-dissolve tablet technology licenses before shelf placement standards tighten. Vertical integration into liposomal encapsulation production preserves bioavailability claims against generic substitutes. For New Entrants and Emerging Players: Differentiate on TSA-compliant single-serve powder formats targeting Nashville and Miami corporate wellness vending programs as the most penetrable white space. Bypass saturated California and New York pharmacy channels through employer-subsidized B2B procurement with annual contract structures. Lead with predictive replenishment algorithms that capture lifetime value before incumbents restructure subscription infrastructure. For Investors and Strategic Acquirers: The market sits at a certification-deepening phase that favors cGMP-compliant manufacturers with existing FDA-audited facility relationships. Long-term viability hinges on clinical validation depth rather than ingredient composition alone, positioning effervescent technology specialists and liposomal encapsulation patent-holders as attractive acquisition targets. Watch NAD case precedents on health claim substantiation as the inflection signal for forced reformulation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| NSF Certified for Sport Acquisition | Opens pharmacy placement previously blocked to unverified supplement entrants in California and Texas. |
| Effervescent Technology Licensing | Accelerates absorption claims that Manhattan consumers now demand with pharmacokinetic validation. |
| cGMP Contract Manufacturing Partnership | Reduces capital barriers for powder format startups targeting employer-subsidized corporate wellness channels. |
| Direct-to-Consumer Subscription Platform | Captures higher lifetime value through habit-formation data models anticipating consumption cycles. |
| Liposomal Encapsulation Patent Development | Creates bioavailability differentiation that premium-positioned Los Angeles consumers increasingly require. |
Research Methodology
The analysis maps supplements, beverages, powders, and effervescent delivery formats, each validated through formulation chemists, pharmacy category buyers, contract manufacturing executives, and corporate wellness program directors. Primary interviews with these stakeholders combined with secondary validation against FDA structure-function claim notifications, FTC NAD case precedents, NSF Certified for Sport databases, and state alcohol beverage control board filings. Bottom-up demand modeling triangulates against top-down market sizing across product type, active ingredient, distribution channel, and formulation dimensions.
Consistency checks validated volume and value outputs against retail audit data from pharmacy chains and direct-to-consumer subscription platforms. The analytical framework segments by product architecture, certification tier, and regional regulatory intensity across the modeling period. CAGRs derive from consumption pattern normalization in urban hospitality corridors and corporate wellness integration trajectories. Forecast inputs incorporate NSF certification penetration curves and cGMP facility capacity expansion timelines without year-specific milestones.
The analysis sits within stated boundaries; outcomes outside FDA dietary supplement framework stability or FTC enforcement intensity shifts would require recalibration. Forecasts reflect assumptions on habitual consumption pattern formation and employer subsidy durability. Recalibration cycles align with material shifts in NAD case precedent accumulation and state-level alcohol beverage control board co-marketing restriction evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Bone Supplements Market
Nutritional Supplements
Eggshell Membrane Powder Market
Nutritional Supplements
Prenatal Supplements Market
Nutritional Supplements
Middle East and Africa Nutricosmetics Market
Nutritional Supplements
France Whey Protein Market
Nutritional Supplements
Whey Hydrolysates Market
Nutritional Supplements
United States Vitamin D Supplements Market
Nutritional Supplements
Canada Whey Protein Market
Nutritional Supplements
Concentrate Protein Market
Nutritional Supplements
Ketogenic Diet Food Market
Nutritional Supplements
Arabinogalactan Powder Market
Nutritional Supplements
Astragalus Propinquus Market
Nutritional Supplements
Skin-Booster Beverages Market
Nutritional Supplements
Propolis Market
Nutritional Supplements
Vietnam Collagen Supplements Market
Nutritional Supplements
Marine Supplements Market