
 Australia Collagen Peptides Market | 2026-2036
Australia Collagen Peptides Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Collagen Peptides Market Insights
Premium-grade marine and grass-fed bovine sourcing is bifurcating the Australia collagen peptides landscape. GELITA Australia Pty. Ltd. anchors local manufacturing scale with its Ingleburn facility supplying hydrolyzed collagen across Asia-Pacific. The Collagen Co. differentiates through direct-to-consumer branding and flavor innovation. PB Leiner leverages its global gelatin heritage to compete on technical specifications for pharmaceutical-grade applications.
Collagen peptides are short-chain amino acid sequences derived from enzymatic hydrolysis of native collagen, typically comprising glycine-proline-hydroxyproline repeats with molecular weights below 10 kDa for optimal bioavailability; they function primarily as structural protein supplements supporting connective tissue integrity, skin elasticity, and joint recovery across nutraceutical and medical formulations. Hydrolyzed collagen dominates value generation due to its solubility and neutral sensory profile, while collagen supplements targeted at athletes represent the fastest-expanding application segment as protein fortification extends beyond whey into functional recovery products. Nutraceuticals remains the mature revenue base, though cosmetics-grade peptides command margin premiums through dermal bioactive positioning.
TGA's Listed Medicine framework and the Food Standards Australia New Zealand Code govern collagen peptide safety claims, manufacturing practice, and novel food approvals, with FSANZ Schedule 23 specifically regulating permitted sources and maximum usage levels in formulated supplementary sports foods. The Therapeutic Goods Advertising Code further constrains how brands communicate efficacy, pushing companies toward clinical substantiation investments. Stakeholders must monitor TGA's anticipated alignment with international pharmacopeial standards for collagen molecular weight verification as a determinant of competitive legitimacy.
Market Dynamics
TGA's tightening Listed Medicine framework is compressing formulation timelines and forcing brands toward clinical substantiation investments, bifurcating the market between substantiated premium positioning and commodity peptide sourcing.
Growth Catalysts
- Sports nutrition expansion:Athletes and fitness consumers in New South Wales and Victoria are adopting collagen peptides as recovery supplements, extending protein fortification beyond traditional whey isolates into functional sports foods.
- FSANZ Schedule 23 clarity:Permitted source specifications and maximum usage levels for formulated supplementary sports foods provide regulatory certainty that accelerates new product development cycles.
- Urban health clustering:Health-conscious populations concentrate in Sydney and Melbourne metropolitan zones, creating concentrated demand pockets that reward targeted distribution and localized marketing spend.
Market Restraints
- Marine raw material volatility:Wild-caught fish skin and scale supply from Australian and Southeast Asian fisheries faces seasonal fluctuation and quota constraints that compress margin stability for hydrolyzed collagen producers.
- Grass-fed bovine input concentration:Premium bovine peptide sourcing depends on captive relationships with Australian pastoral suppliers, creating bottleneck risk when drought conditions affect herd availability.
- TGA advertising code friction:Therapeutic Goods Advertising Code restrictions on efficacy claims limit direct-to-consumer messaging flexibility, forcing brands toward expensive clinical trial investments before market entry.
Strategic Opportunities
- Queensland and Western Australia penetration:Underdeveloped retail and pharmacy channels in Brisbane and Perth metropolitan areas present whitespace for brands with localized distribution partnerships.
- Cosmetics-grade peptide positioning:Dermal bioactive applications command margin premiums through topical and ingestible beauty convergence, with Australian consumers showing elevated willingness-to-pay for skin elasticity claims.
- Pharmaceutical-grade technical specifications:MFDS-aligned molecular weight verification standards create pathway for Australian manufacturers to supply regulated medical nutrition markets across Asia-Pacific.
Industry Challenges
- Peptide characterization expertise scarcity:Analytical chemistry talent capable of hydrolysis degree verification and molecular weight distribution profiling commands premium compensation, constraining quality control scaling.
- TGA alignment timeline uncertainty:Anticipated convergence with international pharmacopeial standards for collagen molecular weight verification creates compliance investment risk without confirmed implementation dates.
- Flavor masking R&D intensity:Neutral sensory profile requirements for sports nutrition applications demand ongoing formulation iteration as consumer palatability thresholds tighten.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Collagen Peptides Market |
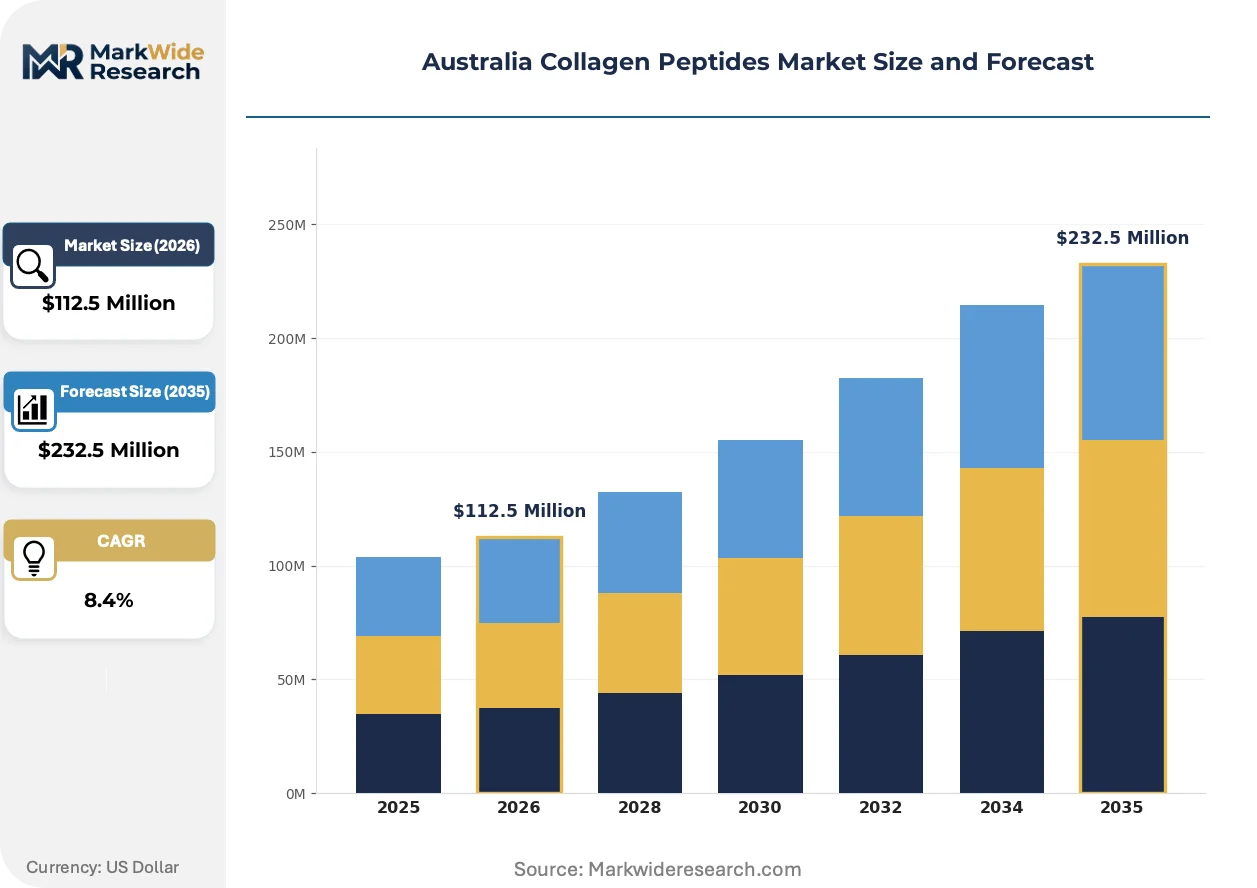
| Market Size in 2026 | $112.5 Million |
| Market Size in 2035 | $232.5 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed Collagen, Gelatin, Collagen Concentrates, Collagen Supplements Application: Nutraceuticals, Cosmetics, Medical, Food & Beverages End User: Health-Conscious Consumers, Athletes, Older Adults, Beauty Enthusiasts Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies |
| Companies Covered | The Collagen Co., PB Leiner, GELITA Australia Pty. Ltd., Collagen Australia Co., Vital Proteins AU, Rousselot, Holista Colltech Ltd., CollagenX, Nitta Gelatin Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Collagen Peptides Market Trends and Innovations
Enzymatic hydrolysis optimization and precision fermentation alternatives are reshaping production economics, while regulatory convergence pressures and channel fragmentation redefine competitive positioning across the value chain.
Precision fermentation-derived collagen alternatives are displacing traditional animal-sourced hydrolyzed peptides in premium cosmetic and vegan-positioned nutraceutical segments. Clean-label brands in Sydney and Melbourne are adopting these biomaterials despite unit cost premiums of 40-60 percent. This technology is displacing conventional marine and bovine supply relationships among millennial and Gen-Z consumer cohorts who prioritize ethical sourcing claims over price sensitivity.
TGA's anticipated alignment with European Pharmacopoeia and USP collagen monographs is compressing molecular weight verification tolerances from broad ranges to discrete thresholds. Manufacturers must invest in advanced chromatography and mass spectrometry capabilities to maintain Listed Medicine registrations. Pharmaceutical-grade peptide suppliers face the steepest compliance burden, with Ingleburn-based facilities accelerating capital deployment toward analytical infrastructure.
Subscription-direct models are fragmenting traditional pharmacy and specialty retail channels that historically dominated Australian collagen peptide distribution. Melbourne-headquartered digital-native brands are capturing recurring revenue through personalized dosing protocols and flavor curation. This shift concentrates customer data ownership with manufacturers while compressing wholesale margin pools for incumbent retail networks across New South Wales and Victoria.
Australia Collagen Peptides Market Segmentation
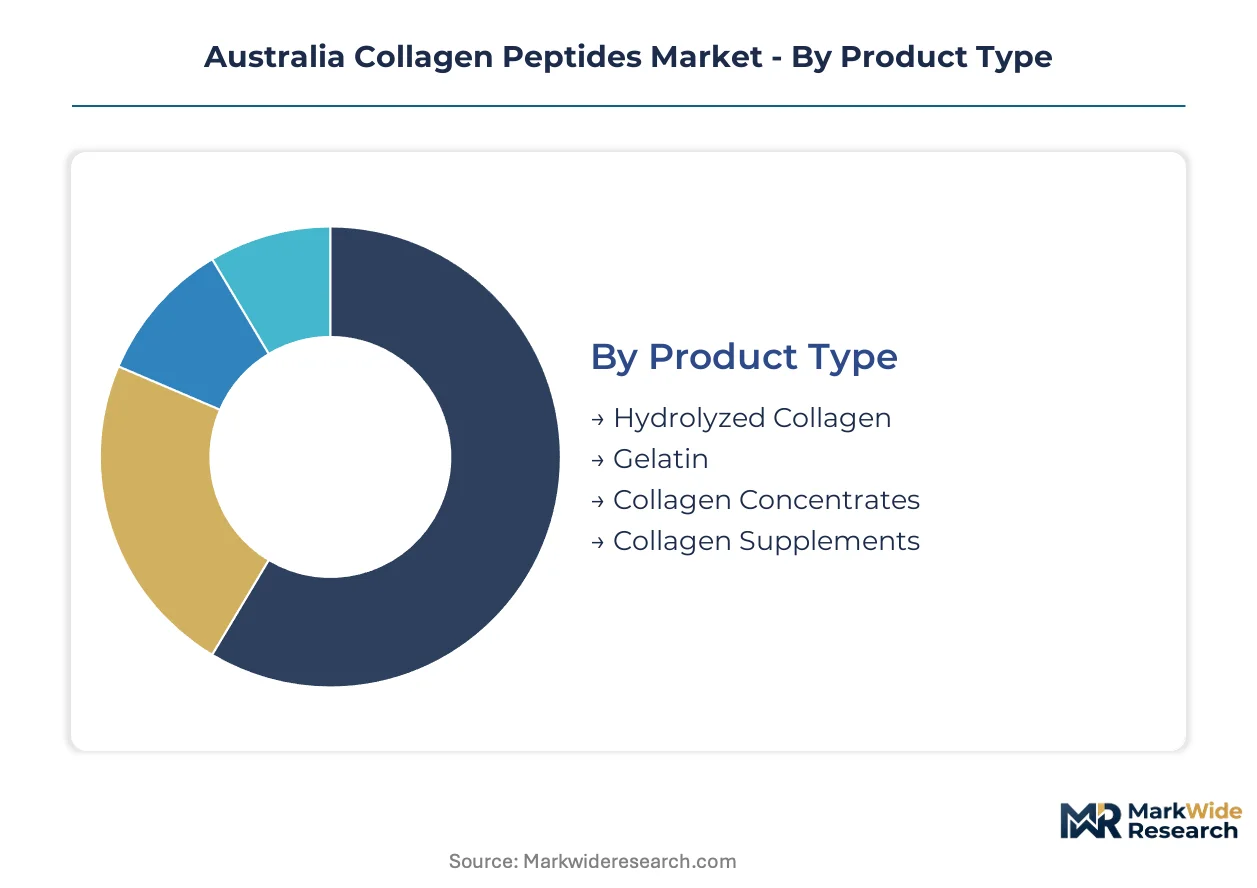
Collagen peptide segmentation in Australia reveals distinct margin architectures across product chemistry, end-use applications, and channel economics. Understanding where value concentrates within each dimension enables targeted resource allocation for manufacturers and brands navigating TGA's tightening compliance environment.
Product Type:
Margin pools concentrate in hydrolyzed collagen due to its solubility premium and neutral sensory profile that commands formulation flexibility across applications.
- Hydrolyzed Collagen:Enzymatically cleaved peptides with molecular weights below 10 kDa deliver optimal bioavailability for sports nutrition and medical nutrition applications. Demand clusters in New South Wales and Victoria where fitness consumers and aging populations drive recurring purchase behavior for recovery and joint health formulations.
- Gelatin:Partially hydrolyzed collagen with higher bloom strength specifications serves food matrix stabilization and soft-gel encapsulation. Pharmaceutical manufacturers in Sydney's industrial corridors source gelatin for capsule production, though thermal gelling properties limit its expansion into ready-to-drink formats where hydrolyzed alternatives dominate.
- Collagen Concentrates:Higher protein density liquid or paste formats targeting industrial-scale food fortification.
- Collagen Supplements:Finished-dose formats including tablets, capsules, and powders for direct consumer consumption.
The dominant share belongs to hydrolyzed collagen, while collagen supplements are gaining share fastest through direct-to-consumer subscription models.
Application:
Application-level profitability diverges sharply between mature nutraceutical volumes and emerging cosmetics-grade premiums.
- Nutraceuticals:Ingestible supplements for joint, bone, and gut health represent the established revenue base with standardized TGA Listed Medicine pathways. Melbourne and Sydney health food retailers stock extensive SKU ranges, though margin compression intensifies as private-label entrants proliferate.
- Cosmetics:Dermal bioactive peptides command substantial price premiums through topical and ingestible beauty convergence. Brisbane and Perth consumers demonstrate elevated willingness-to-pay for skin elasticity claims, creating whitespace for brands with clinical substantiation investments.
- Medical:Regulated medical nutrition and wound care applications requiring pharmaceutical-grade specifications.
- Food & Beverages:Functional fortification in ready-to-drink proteins, snack bars, and dairy alternatives.
Nutraceuticals retains volume leadership, yet cosmetics exhibits the steepest expansion trajectory as beauty-positioned peptides capture premium pricing.
End User:
User archetypes map directly to channel strategy and pricing architecture, with athletes and beauty enthusiasts driving premium tier development.
- Athletes:Competitive and recreational fitness consumers in Victoria's metropolitan training facilities adopt collagen for tendon recovery and protein diversification beyond whey isolates. Sports nutrition brands target this cohort through gym partnerships and event sponsorships with higher per-unit spending than general wellness consumers.
- Beauty Enthusiasts:Skincare-focused consumers prioritize ingestible and topical collagen for elasticity and hydration outcomes. Social media-driven discovery patterns concentrate in Sydney's eastern suburbs and Melbourne's inner north, where influencer marketing and subscription curation convert efficiently.
- Health-Conscious Consumers:Broad wellness-oriented purchasers seeking preventive health maintenance.
- Older Adults:Aging populations targeting joint mobility and bone density support.
Athletes generate the highest per-customer lifetime value, while beauty enthusiasts are scaling fastest through digital-native brand acquisition.
Distribution Channel:
Channel economics are fragmenting as direct-to-consumer models disintermediate traditional pharmacy and retail networks.
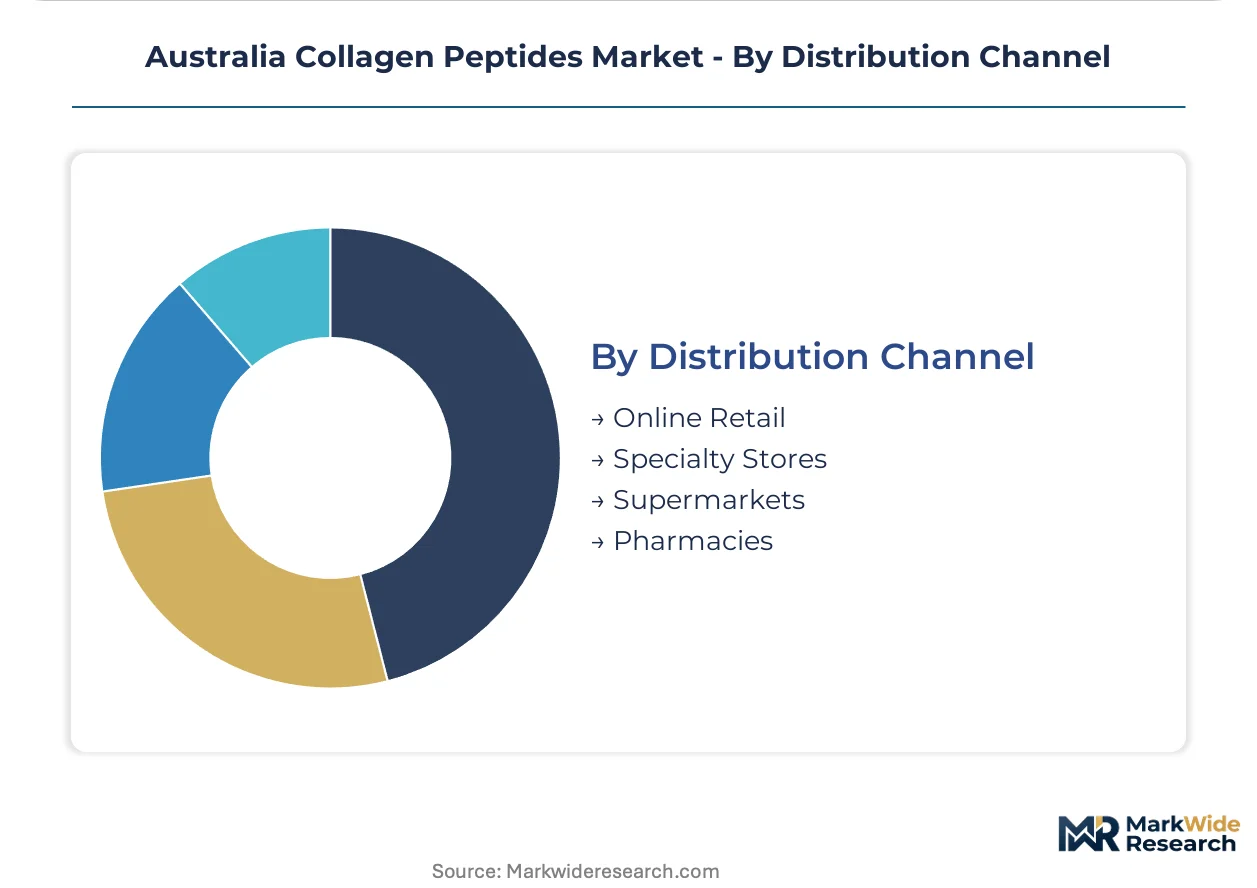
- Online Retail:Brand-owned websites and marketplace presence enable subscription mechanics and customer data ownership. Melbourne-headquartered digital natives capture recurring revenue through personalized dosing protocols, compressing wholesale margin pools for incumbent retail networks.
- Pharmacies:TGA Listed Medicine registration provides credibility and pharmacist recommendation access. Priceline and Chemist Warehouse chains across New South Wales maintain shelf presence for established brands, though traffic erosion to online alternatives accelerates.
- Specialty Stores:Health food and sports nutrition retailers with curated assortments and staff expertise.
- Supermarkets:Mass-market penetration through Coles and Woolworths for commoditized powder formats.
Pharmacies hold the largest existing footprint, yet online retail is expanding most quickly through subscription-direct models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia's collagen peptide trade flows reflect a net import position for finished nutraceuticals offset by growing hydrolyzed collagen exports to Southeast Asian markets. TGA's Listed Medicine framework and FSANZ Schedule 23 create regulatory moats that concentrate value-add processing within domestic boundaries. State-level demand patterns diverge sharply between coastal metropolitan health clusters and underdeveloped interior markets.
New South Wales
Sydney's eastern suburbs and inner west harbor Australia's densest concentration of beauty-positioned collagen consumers, with ingestible skincare subscriptions scaling fastest through influencer-driven discovery. TGA's Therapeutic Goods Advertising Code enforcement pressures brands toward clinical substantiation investments before pharmacist recommendation access at Priceline and Chemist Warehouse chains. The Ingleburn industrial corridor anchors GELITA Australia's hydrolyzed collagen manufacturing, supplying pharmaceutical-grade peptides across Asia-Pacific medical nutrition markets.
Victoria
Melbourne's fitness culture drives sports nutrition adoption among competitive athletes and recreational gym members seeking tendon recovery formulations beyond whey protein isolates. FSANZ Schedule 23 clarity on permitted sources for formulated supplementary sports foods accelerates local product development cycles for ready-to-drink collagen fortification. Digital-native brands headquartered in inner Melbourne capture recurring subscription revenue through personalized dosing protocols, compressing traditional pharmacy wholesale margins.
Queensland
Brisbane's emerging health-conscious demographics present whitespace for brands with localized distribution partnerships in underdeveloped retail and pharmacy channels. The state's tropical climate supports marine collagen raw material processing from wild-caught fisheries, though seasonal quota constraints create supply volatility. Gold Coast wellness tourism clusters generate concentrated demand for premium cosmetic-grade peptides targeting skin elasticity claims among interstate visitors.
Western Australia
Perth's geographic isolation from eastern manufacturing centers elevates logistics costs for finished collagen supplements, slowing mass-market penetration relative to coastal counterparts. The state's pastoral regions supply grass-fed bovine collagen inputs to premium peptide producers, with drought exposure creating herd availability bottlenecks. Local sports nutrition retailers in Fremantle and Subiaco curate specialized assortments for mining sector workers seeking joint health maintenance in physically demanding occupations.
Australia Collagen Peptides Market Competitive Landscape
Listed leaders compete with private specialists across manufacturing scale and direct-to-consumer branding dimensions, creating a bifurcated structure where technical specification providers vie with digital-native marketers for margin capture. The vendor base stratifies between global gelatin heritage players with pharmaceutical-grade capabilities, regional hydrolyzed collagen manufacturers serving Asia-Pacific export markets, and subscription-direct brands leveraging customer data ownership. Three archetypes dominate: technical specification suppliers, flavor-innovation marketers, and precision fermentation pioneers. Capacity expansion and clinical substantiation investments constitute the primary competitive moves as TGA compliance costs escalate.
Within the technical specification tier, GELITA Australia Pty. Ltd. anchors regional manufacturing scale from its Ingleburn facility, while PB Leiner occupies a position leveraging global gelatin heritage for pharmaceutical-grade applications. The direct-to-consumer archetype is exemplified by The Collagen Co., which represents flavor innovation and subscription mechanics targeting urban health clusters. These three entities collectively illustrate the strategic divergence between manufacturing-led and brand-led value capture models in TGA-regulated markets.
| Leading Market Players |
|---|
| The Collagen Co. |
| PB Leiner |
| GELITA Australia Pty. Ltd. |
| Collagen Australia Co. |
| Vital Proteins AU |
| Rousselot |
| Holista Colltech Ltd. |
| CollagenX |
| Nitta Gelatin Inc. |
| Others |
Pricing and Supply Chain Analysis
Precision fermentation-derived collagen alternatives are displacing conventional marine and bovine hydrolysates, simultaneously shifting raw material sourcing from Australian pastoral regions and Southeast Asian fisheries toward bioreactor facilities in South Korea and Singapore while compressing price premiums for traditional animal-sourced peptides. This substitution dynamic bifurcates procurement strategies between established manufacturers defending scale economies and clean-label brands absorbing 40-60 percent unit cost premiums for biomaterial positioning.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the Australian market. Pharmaceutical-grade peptide specifications command substantial premiums over nutraceutical grades due to TGA Listed Medicine compliance costs and molecular weight verification investments. Price differentiation rests on certification tier and volume scale, with subscription-direct brands capturing recurring revenue at lower per-unit prices than pharmacy wholesale channels. Cost compression in standard-grade hydrolyzed collagen is intensifying as private-label entrants proliferate through Coles and Woolworths distribution. Athletes and fitness consumers demonstrate lowest price sensitivity due to performance-driven purchasing, while general wellness buyers in supermarket channels exhibit highest elasticity.
Supply Chain Analysis
Container availability constraints on Southeast Asian trade lanes elevate inbound logistics costs for wild-caught fish skin and scale raw materials destined for Queensland processing facilities. Geographic supply concentration centers on Australia for grass-fed bovine inputs, Indonesia and Vietnam for marine collagen precursors, and South Korea for precision fermentation alternatives. Raw material dependencies include enzymatic hydrolysis catalysts, molecular weight filtration membranes, and pharmaceutical-grade packaging materials. Single-source vulnerability characterizes premium bovine peptide supply due to captive pastoral supplier relationships concentrated in drought-exposed regions. Distribution runs through direct-to-consumer subscription platforms, pharmacy chains, and specialty sports nutrition retailers with diverging margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
TGA's anticipated alignment with international pharmacopoeial standards for collagen molecular weight verification constitutes a regulatory inflection that will accelerate market consolidation around substantiated premium positioning and technical specification capabilities.
For Market Incumbents: Fortify analytical infrastructure investments at Ingleburn-scale manufacturing facilities to preempt compliance burdens from TGA's European Pharmacopoeia convergence. Secure captive supply relationships with Queensland marine processors and Victorian pastoral suppliers before drought cycles tighten herd availability. Defend subscription revenue pools through flavor innovation R&D and personalized dosing protocol development against digital-native entrants. For New Entrants and Emerging Players: TGA Listed Medicine fast-track pathways through clinical substantiation investments unlock pharmacist recommendation access at Priceline and Chemist Warehouse chains. Target Queensland and Western Australia metropolitan zones where retail channel underpenetration creates whitespace for localized distribution partnerships. Pursue cosmetics-grade peptide positioning through dermal bioactive claims with elevated Brisbane and Perth willingness-to-pay for skin elasticity outcomes. For Investors and Strategic Acquirers: The market sits at a pre-consolidation phase that favors analytical chemistry capability owners and direct-to-consumer data assets. Long-term viability over the next decade hinges on regulatory compliance infrastructure and customer data ownership rather than commodity peptide volume scale. Acquisition targets should demonstrate chromatography and mass spectrometry verification capabilities alongside recurring subscription revenue mechanics. The signal to watch is TGA's publication of definitive molecular weight threshold standards, which will determine competitive legitimacy and capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Substantiation Investment | TGA Listed Medicine registration enables pharmacist recommendation access at Chemist Warehouse and Priceline chains. |
| Backward Integration into Raw Material Supply | Captive relationships with Queensland marine processors and Victorian pastoral suppliers mitigate drought and quota volatility. |
| Analytical Infrastructure Deployment | Chromatography and mass spectrometry capabilities ensure compliance with anticipated European Pharmacopoeia molecular weight standards. |
| Direct-to-Consumer Subscription Launch | Melbourne-headquartered digital-native brands capture recurring revenue and customer data ownership compressing wholesale margins. |
| Cosmetics-Grade Peptide Positioning | Dermal bioactive applications command margin premiums through topical and ingestible beauty convergence in Sydney and Melbourne. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with sports nutrition brand managers, TGA regulatory affairs specialists, pharmaceutical procurement leads at Sydney hospital networks, and Queensland marine processing facility operators. Secondary validation incorporated TGA Listed Medicine registration databases, FSANZ Schedule 23 compliance filings, Australian Bureau of Agricultural and Resource Economics pastoral production statistics, and SEC disclosures from global gelatin heritage parents. Bottom-up demand modeling across athlete, beauty enthusiast, and aging consumer archetypes was triangulated against top-down hydrolyzed collagen production capacity assessments from Ingleburn-based facilities.
Across the analysis window, value and volume projections were derived through segmented modeling of product type chemistry, application-level margin architecture, and channel economics. Segmentation dimensions included hydrolyzed collagen versus gelatin versus concentrates, nutraceutical versus cosmetics versus medical applications, and online retail versus pharmacy versus specialty store distribution. CAGRs were computed from base year demand quantification and annual growth rate assumptions calibrated to TGA regulatory timeline uncertainty and precision fermentation adoption curves. Industry-specific forecast inputs incorporated enzymatic hydrolysis capacity expansion schedules and subscription-direct customer acquisition cost trajectories.
Decision-makers should treat outputs as directional under base assumptions of TGA regulatory convergence timing and precision fermentation cost reduction curves; material deviation would warrant model refresh. Specific risk factors include marine raw material quota constraints, drought-induced bovine herd contraction, and TGA advertising code enforcement intensity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Bone Broth Protein Powder Market
Nutritional Supplements
Oral Immunostimulant Market
Nutritional Supplements
Lactoferrin Supplements Market
Nutritional Supplements
Phytoestrogen Supplements Market
Nutritional Supplements
Calcium Market
Nutritional Supplements
China Collagen Peptides Market
Nutritional Supplements
Nutrient Dense Food Products Market
Nutritional Supplements
Middle East and Africa Nutricosmetics Market
Nutritional Supplements
North America Collagen Supplements Market
Nutritional Supplements
Micellar Casein Market
Nutritional Supplements
South America Omega-3 Products Market
Nutritional Supplements
Asia-Pacific Nutraceutical Excipients Market
Nutritional Supplements
Indonesia Beauty Supplements Market
Nutritional Supplements
Forskolin Market
Nutritional Supplements
Global Beta Glucan Market
Nutritional Supplements
Marine Collagen Market