
 Global Automotive Starter Motor Market | 2026-2036
Global Automotive Starter Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Starter Motor Market Intelligence
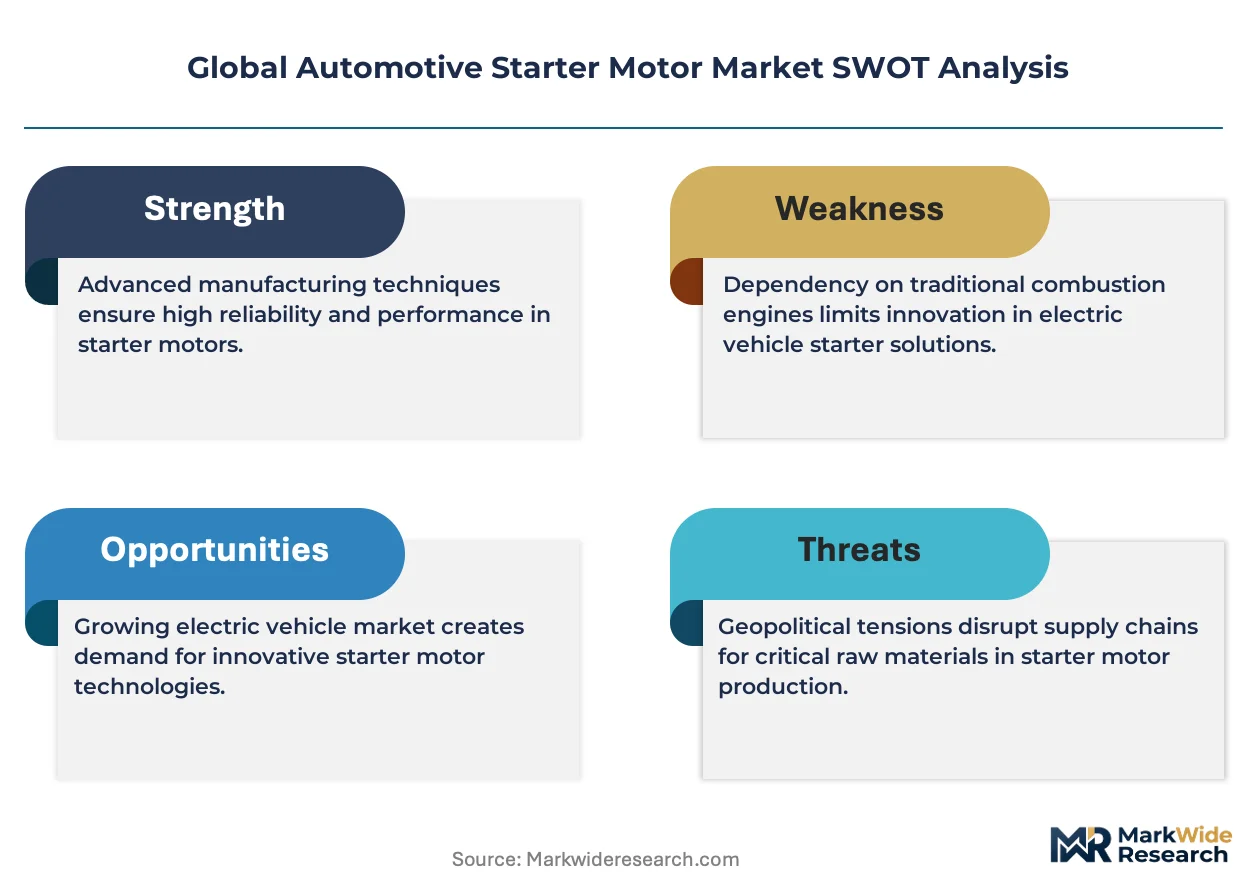
The United States Environmental Protection Agency's (EPA) latest vehicle emissions standards is realigning the cost-of-entry calculus for starter motor manufacturers. Bosch leverages its significant R&D investment in brushless motor technology to meet these new performance benchmarks. Meanwhile, Valeo sustains its market position through specialization in compact and efficient starter solutions for passenger vehicles. Denso Corporation competes on the basis of its extensive manufacturing scale and deep relationships with Japanese OEMs.
An automotive starter motor is a high-torque electric motor engineered to rotate an internal combustion engine's crankshaft. These devices typically operate on a 12-volt or 24-volt DC system to initiate the engine's combustion cycle. Brushless starter motors represent the fastest-growing product type, displacing traditional series wound designs due to higher efficiency. The passenger vehicles application remains the largest volume driver, while the aftermarket service providers channel accounts for a substantial share of replacement units.
Component compliance is governed by a patchwork of international standards, including the EU's REACH regulations on chemical substances and China's GB standards for automotive parts. These frameworks dictate material composition and testing protocols, directly influencing market access and supply chain choices for global manufacturers. Stakeholders must now decide whether to invest in flexible manufacturing for diverse regional standards or to engineer a single, globally compliant product platform.
Market Dynamics
The imperative to meet stringent global vehicle emission standards is the central force shaping the automotive starter motor market. This regulatory pressure compels a fundamental technology shift away from traditional designs toward more efficient, durable, and intelligent starter systems capable of supporting advanced engine functionalities like start-stop.
Growth Catalysts
- Regulatory Mandates:The European Union's Euro 7 framework and similar emissions regulations in other jurisdictions necessitate advanced starter technologies that can withstand frequent engine restarts in start-stop systems.
- Commercial Vehicle Demand:The global logistics and transportation sectors drive consistent demand for high-torque, durable 24-volt starter motors for new commercial trucks and replacement units for existing fleets.
- Aftermarket Expansion:A growing global vehicle parc, particularly in developing economies across Asia and Latin America, creates a substantial and continuous demand stream for replacement starter motors through aftermarket service channels.
Market Restraints
- Input Cost Volatility:Fluctuations in the price of key raw materials, including copper for windings and rare-earth metals for high-efficiency magnets, create margin pressure for manufacturers.
- BEV Substitution Threat:The long-term transition to battery electric vehicles (BEVs), which do not utilize a conventional starter motor, presents a structural threat to the market's addressable size.
- Technical Obsolescence:The rapid pace of powertrain innovation, including the rise of integrated starter-generators (ISGs) in hybrid systems, risks making standalone starter motor designs obsolete in certain vehicle segments.
Strategic Opportunities
- Mild-Hybrid Systems:Developing robust starter-generators for 48V mild-hybrid electric vehicles (MHEVs) opens a significant new product category that bridges internal combustion and full electrification.
- Emerging Market Aftermarket:Targeting the aftermarket for commercial vehicles and passenger cars in Southeast Asia and Africa provides access to a large, underpenetrated service and replacement market.
- Remanufacturing Programs:Expanding certified remanufacturing operations offers a cost-competitive and environmentally sustainable alternative to new units, appealing to fleet operators and budget-conscious consumers.
Industry Challenges
- Compliance Complexity:Navigating the patchwork of regional standards, from the EU's REACH chemical regulations to China's GB standards for automotive parts, requires significant investment in testing and validation.
- Supply Chain Resilience:Reducing dependence on geographically concentrated sources for critical components, such as microelectronics and specialized magnets, is a major operational challenge for global manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Starter Motor Market |
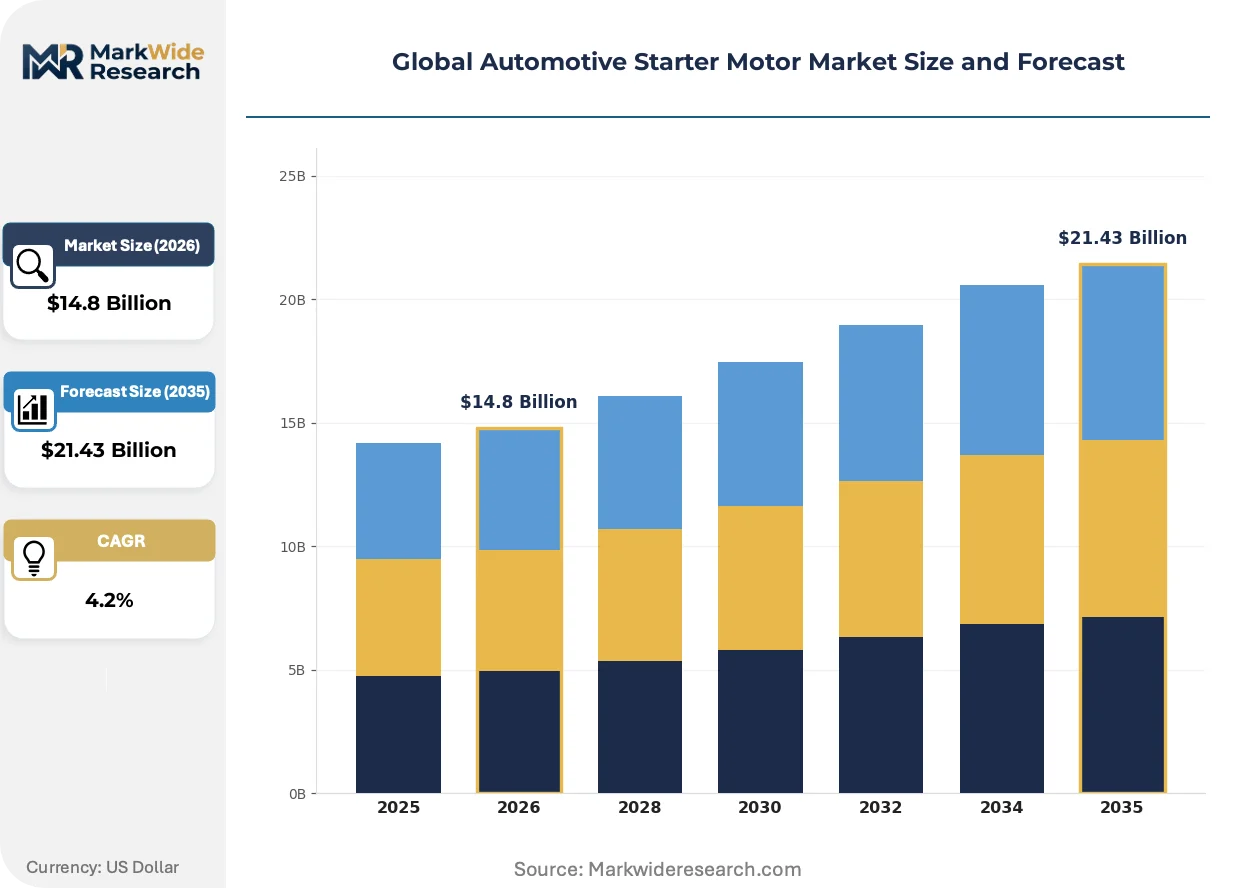
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $21.43 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Permanent Magnet Starter, Series Wound Starter, Planetary Gear Starter, Brushless Starter Motor Technology: Electromagnetic, Hydraulic, Pneumatic, Gear Reduction, Direct Drive Application: Passenger Vehicles, Commercial Trucks, Two-Wheelers, Construction Equipment, Marine Vehicles End User: OEMs, Aftermarket Service Providers, Vehicle Refurbishers, Specialty Vehicle Manufacturers |
| Companies Covered | Bosch, Denso Corporation, Valeo, BorgWarner, Mitsubishi Electric Corporation, Continental, Hitachi Astemo, Mitsuba Corporation, Delphi Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Starter Motor Market Strategic Shifts & Innovations
The market's evolution is driven by a convergence of efficiency mandates and material science advancements. This dynamic forces manufacturers to innovate beyond traditional motor designs, focusing on lighter, more powerful, and electronically controlled solutions to meet next-generation vehicle requirements.
Brushless DC motor technology provides higher operational efficiency and a longer service life by replacing mechanical brushes with electronic commutation. Passenger and light commercial vehicle segments are steadily adopting these more advanced starters to support demanding start-stop functionalities. This technology is absorbing the engineering resources and capital investment previously dedicated to refining older, series-wound starter designs.
New emissions rules from bodies like the United States Environmental Protection Agency (EPA) are reshaping performance requirements. These regulations promote engine start-stop systems to cut idling emissions, which in turn increases the duty cycle and durability demands placed on the starter motor. The commercial truck segment is most affected, compelling a move toward more robust starter designs engineered for extreme longevity and reliability.
A notable behavioral shift is occurring in the aftermarket, where large service chains and distributors are consolidating their purchasing. This trend favors suppliers who can offer broad product catalogs, certified remanufacturing options, and integrated logistics, disrupting traditional, fragmented distribution models. This consolidation of procurement is most visible in the mature automotive aftermarkets of North America and Europe.
Global Automotive Starter Motor Market Segmentation
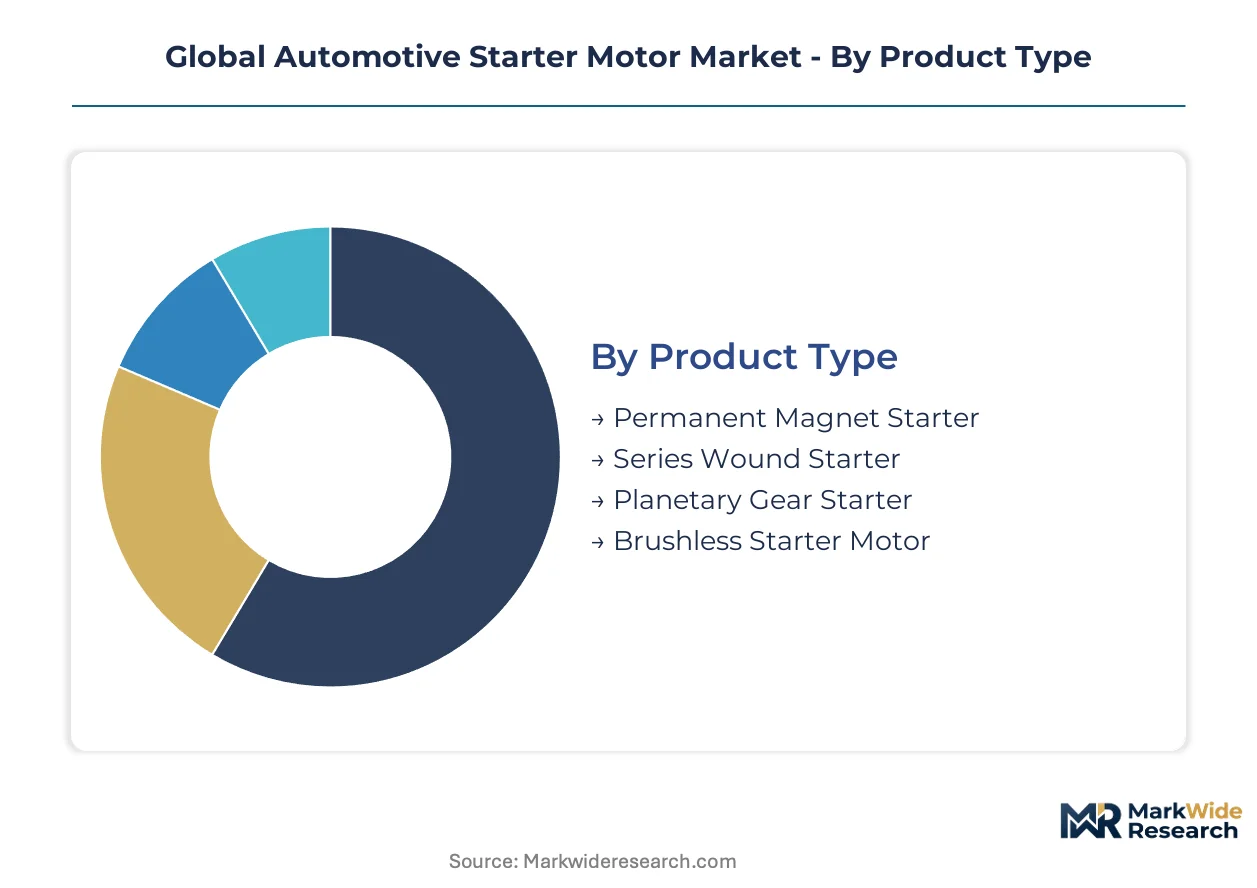
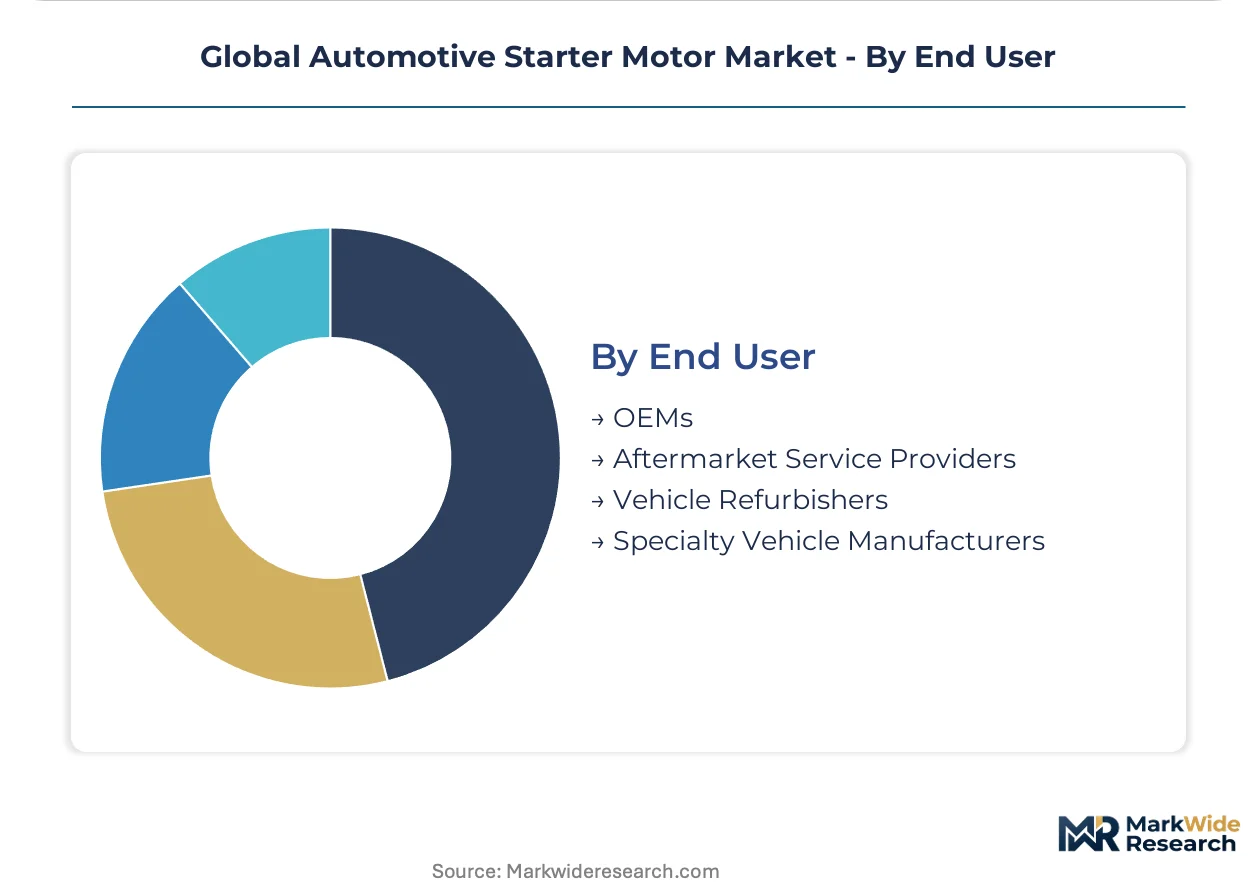
Market segmentation for automotive starter motors reveals distinct demand patterns influenced by vehicle types, technological advancements, and operational lifecycles. Different end-user groups and application sectors drive varied requirements for power output, durability, and integration capabilities. Understanding these segments is crucial for manufacturers to align product development and market strategies.
Product Type:
The upgrade cycle within automotive starter motors is heavily influenced by the underlying product technologies, dictating efficiency and durability benchmarks.
- Brushless Starter Motor:This advanced design replaces mechanical brushes with electronic commutation, offering superior efficiency, extended service life, and reduced maintenance requirements. Demand concentrates in passenger vehicles, particularly those equipped with start-stop systems, driven by stringent emissions regulations in Europe and North America.
- Planetary Gear Starter:These starters utilize a planetary gear set to multiply torque, allowing for a more compact and lighter unit capable of delivering high cranking power. Commercial trucks and heavy-duty vehicles globally drive significant demand for these robust, high-torque solutions.
- Permanent Magnet Starter:Featuring permanent magnets instead of field windings, these starters are compact and lightweight, offering reliable performance for smaller engines.
- Series Wound Starter:A traditional design that employs field windings in series with the armature, providing high starting torque but generally lower efficiency than modern alternatives.
Volume placements concentrate in Planetary Gear Starter designs; the faster expansion belongs to Brushless Starter Motor technology.
Technology:
Different vehicle applications often dictate the specific starter motor technology required to ensure optimal performance and seamless integration.
- Electromagnetic:This widely adopted technology uses an electromagnet (solenoid) to engage the starter pinion with the engine's flywheel, initiating the cranking process. Passenger vehicles across Asia and Europe largely utilize this cost-effective and proven technology.
- Gear Reduction:Incorporating a gear train between the motor and the pinion, this technology multiplies the motor's torque, enabling smaller, lighter motors to crank large engines efficiently. Commercial trucks and heavy equipment in North America frequently specify gear reduction starters for their reliability.
- Hydraulic:Specialized hydraulic systems provide high power density for very large engines or applications where electrical systems are impractical.
- Pneumatic:Air-powered starters are typically found in industrial or hazardous environments where electrical sparks are a safety concern.
- Direct Drive:A simpler design where the motor directly engages the flywheel, often found in older or less demanding engine applications.
Electromagnetic systems maintain broad adoption, while Gear Reduction technology exhibits a steepest expansion trajectory in heavy-duty segments.
Application:
The sheer volume of vehicles in distinct application segments drives specific design requirements and market dynamics for starter motors.
- Passenger Vehicles:This segment encompasses a vast range of cars and SUVs, requiring compact, quiet, and efficient starter motors capable of supporting frequent start-stop cycles. Global emissions frameworks, such as the EU's Euro 7, compel advanced starter integration in new passenger car models.
- Commercial Trucks:Heavy-duty commercial trucks demand robust, high-torque starter motors, often operating on 24-volt systems, engineered for extreme durability and reliability. The expanding logistics sector in China and India consistently drives demand for these powerful units.
- Two-Wheelers:Motorcycles, scooters, and other two-wheeled vehicles require compact and lightweight starter solutions, often prioritizing cost-effectiveness.
- Construction Equipment:Large engines in excavators, bulldozers, and loaders need extremely powerful and durable starters designed for harsh operating conditions.
- Marine Vehicles:Starter motors for boats and ships require specialized corrosion-resistant components and robust designs to withstand marine environments.
Passenger Vehicles represent the largest demand pool, with Commercial Trucks steadily gaining share in volume and value.
End User:
Supply concentration varies significantly across end-user segments, influenced by purchasing power and technical specifications.
- OEMs:Original Equipment Manufacturers purchase starter motors directly for integration into new vehicle production lines, requiring strict adherence to design specifications and just-in-time delivery. Japanese and German automotive OEMs maintain long-standing relationships with key starter motor suppliers.
- Aftermarket Service Providers:These entities supply replacement starter motors for vehicles already in operation, catering to repair shops, independent mechanics, and consumers. The growing vehicle parc in Brazil and Mexico sustains strong aftermarket demand.
- Vehicle Refurbishers:Companies specializing in reconditioning and reselling used vehicles often source refurbished or new starter motors for their inventory.
- Specialty Vehicle Manufacturers:Producers of custom vehicles, such as ambulances, recreational vehicles, or armored cars, require tailored starter motor solutions.
OEMs drive initial market volumes, while Aftermarket Service Providers show robust expansion due to vehicle longevity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The robust manufacturing hubs within China's special economic zones foster significant production and aftermarket demand for automotive starter motors. These zones attract substantial foreign investment and domestic production capabilities. This concentration directly influences global supply chains.
China
China's expanding logistics sector drives consistent demand for robust 24-volt starter motors in commercial trucks. The government's GB standards for automotive parts mandate strict material composition and testing protocols. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta lead global production volume.
Germany
German passenger vehicle manufacturers require advanced starter motors for frequent start-stop cycles. The EU's Euro 7 framework compels the adoption of highly efficient starter technologies. Automotive innovation hubs in Bavaria and Baden-Württemberg focus on brushless motor development.
United States
The United States market exhibits strong demand for both passenger vehicle and commercial truck starter motors. The EPA's latest vehicle emissions standards realign performance benchmarks for manufacturers. Automotive production centers in Michigan and the Southeast integrate advanced starter solutions.
Japan
Japanese OEMs drive significant initial market volumes for starter motors, particularly for passenger vehicles. The country's JIS standards influence component compliance and quality control for automotive parts. Major manufacturing concentrations in Aichi Prefecture support extensive supplier networks.
India
Growing vehicle parc in India fuels a substantial and continuous demand for replacement starter motors through aftermarket channels. The nation's Bharat Stage emission norms increasingly require more efficient starter solutions. Automotive clusters in Chennai and Pune are expanding local production capabilities.
Global Automotive Starter Motor Market Key Industry Players
Chinese producers anchor one tier of the market through high-volume, cost-effective manufacturing; German and Japanese specialists hold another through technology leadership and OEM integration. The market exhibits a tiered structure, with global players competing on innovation, while regional manufacturers focus on localized supply. Strategic archetypes include integrated OEM suppliers, aftermarket specialists, and technology-focused innovators. Companies are increasingly pursuing strategic partnerships and capacity expansion to secure market share.
Within the integrated OEM supplier archetype, Bosch, a German multinational engineering and technology company, represents a leader in advanced brushless motor technology. Japanese-based Denso Corporation exemplifies extensive manufacturing scale and deep relationships with Asian OEMs. French multinational Valeo occupies a position specializing in compact and efficient starter solutions for passenger vehicles. These entities navigate complex regulatory environments and evolving powertrain technologies.
| Leading Market Players |
|---|
| Bosch |
| Denso Corporation |
| Valeo |
| BorgWarner |
| Mitsubishi Electric Corporation |
| Continental |
| Hitachi Astemo |
| Mitsuba Corporation |
| Delphi Technologies |
| Others |
Cost & Logistics Intelligence
Original Equipment Manufacturers, particularly Japanese and German automotive OEMs, drive initial market pricing through stringent design specifications and long-term supply agreements. This concentration dictates a contract-based long-term offtake model for substantial volumes.
Pricing Analysis
Premium pricing for short lead times often applies to specialized components like brushless motors, while transactional spot inventory may see discounts. Contract-based long-term offtake models dominate OEM procurement, ensuring stable pricing for high-volume orders. Price differentiation stems from quality grade, certification level for Euro 7 compliance, and after-sales service bundling for aftermarket units. Pricing pressure stems from input cost volatility, particularly for copper and rare-earth metals. Aftermarket service providers in developing economies exhibit the highest price sensitivity, whereas German automotive OEMs prioritize performance over cost for advanced solutions.
Supply Chain Analysis
China's GB standards for automotive parts dictate material composition, influencing sourcing decisions and potentially local-content mandates. Geographic supply concentration for manufacturing centers on China, Japan, and Germany. The supply chain draws from critical raw materials such as copper for windings and rare-earth metals for high-efficiency magnets. A structural supply chain risk involves dependence on geographically concentrated sources for microelectronics and specialized magnets. Downstream distribution runs through direct channels to OEMs and consolidated large service chains for the aftermarket.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive starter motor market faces supply constraints, particularly for advanced brushless motor components, which props pricing for next-generation systems.
For Market Incumbents: Acquire advanced intellectual property in 48V mild-hybrid starter-generators to counter the BEV substitution threat. Invest in flexible manufacturing capabilities across diverse regions to meet varied regulatory standards and reduce supply chain risk. Deepen relationships with Japanese and German OEMs by co-developing next-generation starter solutions. Expand certified remanufacturing programs to capture aftermarket value and promote sustainability.
For New Entrants and Emerging Players: A price-point gap exists for cost-effective, high-durability starter motors in emerging markets. Target the aftermarket for commercial vehicles and passenger cars in Southeast Asia and Africa, which represents a large, underpenetrated service segment. Focus on developing robust 24-volt solutions for commercial trucks. Leverage certified remanufacturing programs as a go-to-market angle to offer budget-conscious alternatives.
For Investors and Strategic Acquirers: The window for entry favors specialists in 48V mild-hybrid electric vehicle (MHEV) systems and brushless motor technology. The market remains viable for the next 5-10 years due to the extensive internal combustion engine (ICE) vehicle parc. Target acquisition profiles include companies with strong R&D in integrated starter-generators or those with established manufacturing in China. The signal to watch is the accelerated decline in new ICE vehicle production volumes across major markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces manufacturing complexity and improves economies of scale for diverse vehicle models. |
| Manufacturing Footprint Expansion | Mitigates geopolitical supply risks and enhances regional market access for critical components. |
| Remanufacturing Program Development | Addresses growing aftermarket demand with cost-effective, environmentally sustainable replacement units. |
| Brushless Motor R&D Investment | Meets stringent emissions standards and supports advanced start-stop functionalities in passenger vehicles. |
| 48V MHEV System Integration | Captures new product category demand bridging internal combustion and full electrification. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary research involved interviews with OEM platform engineers, Tier 1 procurement managers, aftermarket distributors, and regulatory affairs specialists. This approach allowed for a robust bottom-up and top-down triangulation of market data. Secondary sources included vehicle production databases, IHS Markit registration data, government emissions reports, and industry association publications.
Market granularity was modeled across product type, technology, application, end user, and regional regulatory compliance dimensions. The analytical framework projected market development over the forecast period, deriving compound annual growth rates (CAGRs) from historical trends and anticipated technological shifts. Key industry-specific forecast inputs included global vehicle parc growth and the implementation timelines for new emission standards like Euro 7.
Underlying measurement precision varies by segment; passenger vehicles and commercial trucks carry tighter precision than others due to extensive data availability. Forecasts reflect assumptions regarding powertrain evolution and the enforcement of global emission standards. Risk factors such as the pace of battery electric vehicle adoption and raw material supply disruptions could revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Large Synchronous Motor Market
Electric Motor
Frameless Motor Market
Electric Motor
UK Solar E-Bike Market
Electric Motor
Global Automotive Odometer Stepping Motor Market
Electric Motor
Electric Vehicle Motor (EVM) Controller Market
Electric Motor
Motors for Robot Body and Robot Wheels Market
Electric Motor
Electric Vehicle Permanent Magnet Synchronous Motors Market
Electric Motor
Europe Electric Motors for Electric Vehicle Market
Electric Motor
Power Tool Lithium Battery Market
Electric Motor
Outboard Electric Motors Market
Electric Motor
Kayak Trolling Motor Market
Electric Motor
Global Automotive Heating Fan Motor Market
Electric Motor
Positive Displacement Motor Market
Electric Motor
Hub Drive Motor Market
Electric Motor
Global Vehicle Starter Motor Market
Electric Motor
Torque Motor Market