
 Canada Electric Motor for Electric Vehicle Market | 2026-2036
Canada Electric Motor for Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Electric Motor for Electric Vehicle Market Outlook
Commercial vehicle electrification is recalibrating procurement patterns among Canadian fleet operators and municipal transit authorities. Robert Bosch GmbH leverages its integrated powertrain electronics portfolio to serve both passenger and heavy-duty segments. Linamar anchors its position through Ontario-based manufacturing scale and proximity to Detroit Three assembly plants. Tesla Inc. competes by controlling its proprietary permanent magnet motor design and in-house rotor production for vehicles assembled at its Shanghai and Berlin facilities serving Canadian imports.
An electric motor for electric vehicle converts electrical energy into mechanical torque through electromagnetic induction, typically operating at voltages between 200 and 800 volts DC with peak efficiencies exceeding 95 percent. Permanent magnet synchronous motors dominate passenger car applications for their power density, while induction motors retain cost advantages in commercial vehicle platforms where continuous duty cycles predominate. The power output dimension stratifies across low-power urban two-wheelers and ultra-high-power long-haul trucks, with medium and high power brackets capturing the majority of current Canadian OEM procurement volume. Vehicle type segmentation reveals passenger cars as the established revenue base, though commercial vehicles and buses represent the fastest-expanding application set under federal and provincial fleet decarbonization programs.
Transport Canada enforces motor safety and electromagnetic compatibility standards under the Motor Vehicle Safety Regulations, while Environment and Climate Change Canada administers the federal zero-emission vehicle sales mandate that compels automaker electrification timelines. Health Canada coordinates with Innovation, Science and Economic Development Canada on rare earth supply chain traceability for permanent magnet sourcing. Stakeholders must monitor how forthcoming battery and critical mineral domestic content requirements under the United States-Mexico-Canada Agreement reshape motor supplier qualification criteria and cross-border component flows.
Market Dynamics
Federal zero-emission vehicle mandates are compressing automaker electrification timelines while Ontario's automotive corridor concentrates motor supplier investments near Windsor and Oshawa assembly plants.
Growth Catalysts
- Clean Vehicle Tax Credits:The Inflation Reduction Act's domestic content provisions are redirecting motor manufacturing investment toward North American supply chain qualification.
- Transit Fleet Decarbonization:Municipal bus procurement programs across Canadian provinces are expanding medium-duty motor demand beyond passenger car volumes.
- Rare Earth Processing:Saskatchewan's emerging critical mineral refining capacity is reducing permanent magnet import dependency for synchronous motor production.
Market Restraints
- Neodymium Price Volatility:Permanent magnet motor costs fluctuate with Chinese rare earth export quotas and processing concentration.
- Power Electronics Bottleneck:Silicon carbide inverter supply constraints limit high-efficiency motor system deployment in commercial vehicle platforms.
- Interprovincial Regulatory Friction:Quebec's distinct vehicle safety standards create compliance duplication for motor suppliers serving national OEM programs.
Strategic Opportunities
- Heavy-Duty Truck Electrification:Long-haul freight corridors between Calgary and Edmonton present untapped demand for ultra-high-power motor systems.
- Heat Pump Integration:Combined motor-thermal management systems for cold-climate EV operation represent a technology convergence opening for Ontario suppliers.
- Indigenous Procurement Mandates:Federal infrastructure programs with community benefit requirements are creating new distribution channels for regional motor assembly partnerships.
Industry Challenges
- Power Electronics Integration:Combining silicon carbide inverters with high-speed motor architectures requires scarce embedded systems engineering talent concentrated in Waterloo and Toronto.
- Homologation Timeline Compression:Transport Canada's Motor Vehicle Safety Regulations testing cycles for electromagnetic compatibility are extending product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Electric Motor for Electric Vehicle Market |
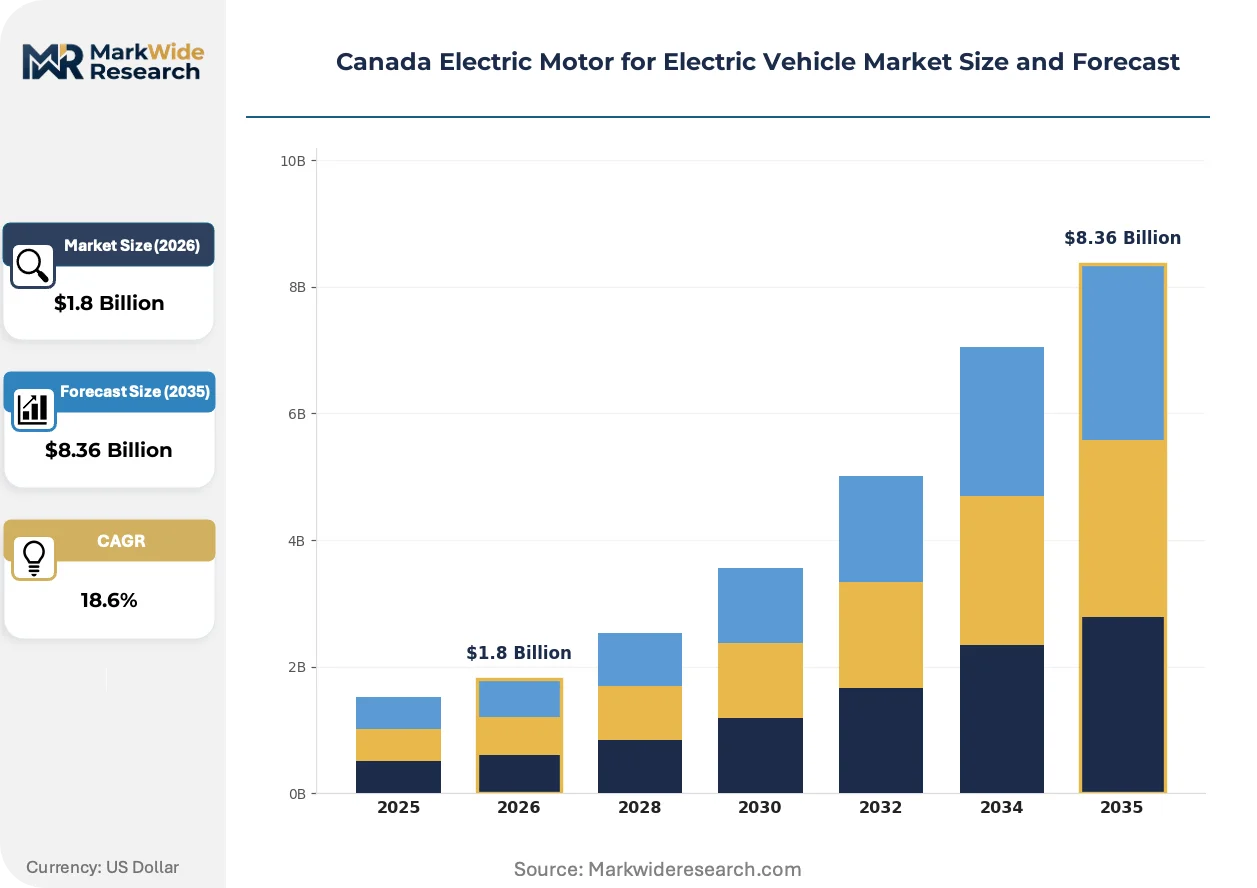
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Motor Type: AC Motor, DC Motor, Permanent Magnet Motor, Induction Motor Vehicle Type: Passenger Cars, Commercial Vehicles, Two-Wheelers, Buses Power Output: Low Power, Medium Power, High Power, Ultra High Power End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Tesla Inc., Robert Bosch GmbH, BorgWarner Inc., Denso Corporation, BYD Co. Ltd., BAIC Group Co., Ltd., Jing-Jin Electric Technologies Co., Ltd., General Motors, Linamar, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Electric Motor for Electric Vehicle Market Strategic Shifts
Electrification hardware is fragmenting across voltage architectures and thermal management approaches as Canadian OEMs diversify beyond single-platform strategies.
Hairpin winding technology is decentralizing motor manufacturing by enabling automated stator assembly at smaller production scales. Tier-2 suppliers in Ontario's Golden Horseshoe are adopting this copper forming process to serve regional EV startups without billion-unit volume commitments. The technology is decentralizing production geography away from centralized Asian motor foundries toward distributed North American supply nodes.
Environment and Climate Change Canada's federal zero-emission vehicle sales mandate is accelerating powertrain platform consolidation among domestic automakers. The regulation forces shared motor architectures across multiple vehicle segments to amortize electrification R&D costs. Commercial vehicle divisions are responding with flexible motor mounting systems compatible with both bus and medium-duty truck chassis.
Fleet operators are consolidating motor supplier relationships around integrated powertrain service agreements rather than component-only procurement. This bundling disrupts traditional tiered supplier hierarchies and compresses aftermarket parts margins. The pattern is most visible in municipal transit authorities across British Columbia and Ontario seeking single-source accountability for drivetrain performance.
Canada Electric Motor for Electric Vehicle Market Segmentation
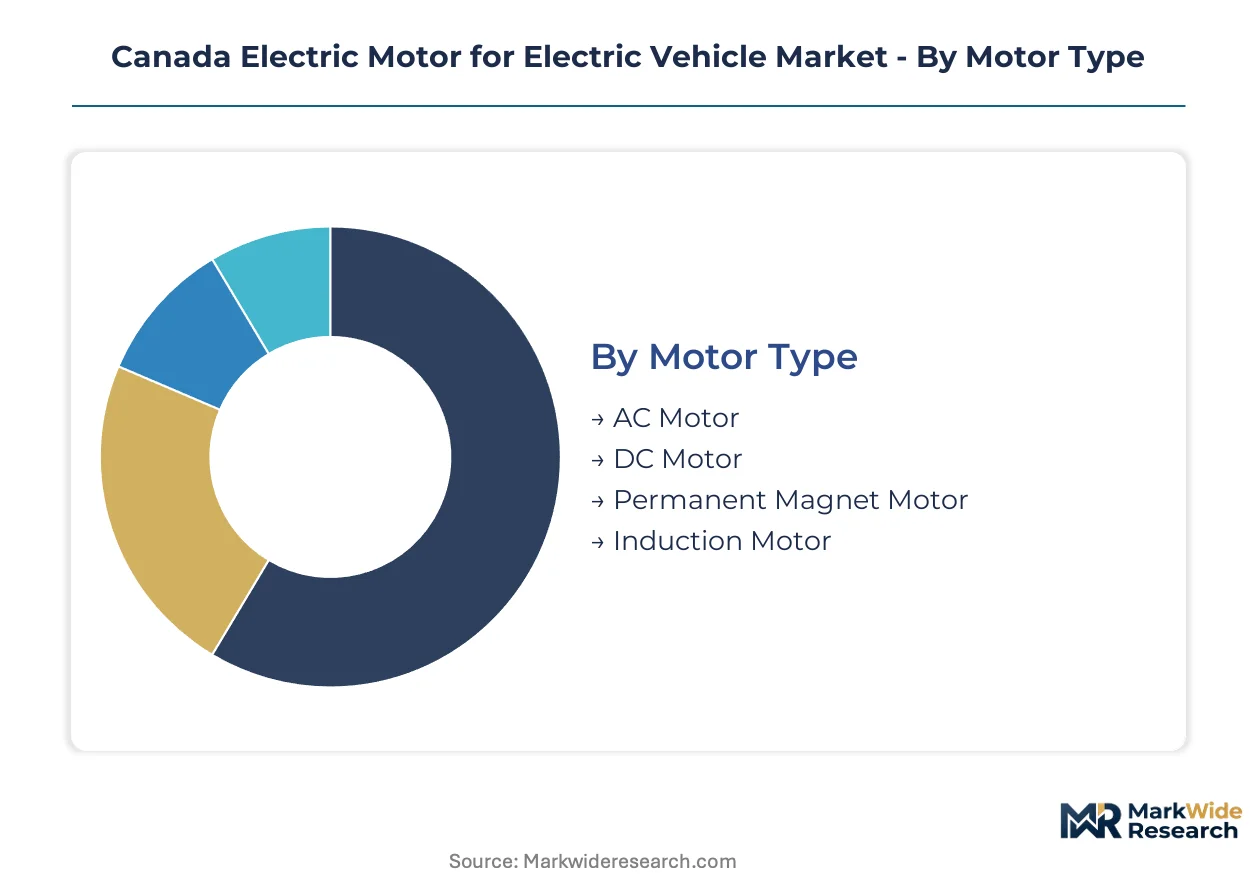
Segmentation in the Canada electric motor for electric vehicle market reveals how capital allocation, technical specifications, and procurement hierarchies shape supplier strategies. Each dimension carries distinct investment profiles and regulatory exposure that determine competitive positioning across Ontario's automotive corridor and emerging provincial markets.
Motor Type:
Permanent magnet synchronous architectures demand the heaviest upfront capital commitment due to rare earth magnet sourcing infrastructure and precision rotor assembly equipment.
- AC Motor:Synchronous and asynchronous alternating current designs serve commercial vehicle platforms requiring continuous duty cycles. Demand clusters in Ontario's transit bus procurement programs where operational longevity outweighs power density requirements.
- DC Motor:Brushed and brushless direct current configurations retain cost advantages in low-voltage auxiliary systems and aftermarket retrofits. Health Canada's electromagnetic compatibility standards impose additional certification burdens on DC architectures in passenger applications.
- Permanent Magnet Motor:Neodymium-iron-boron rotor assemblies deliver peak power density exceeding 95% efficiency at 200-800V DC operating ranges. Saskatchewan's emerging rare earth processing capacity is redirecting procurement toward domestic magnet sourcing for Windsor-Oshawa assembly supply.
- Induction Motor:Copper rotor or squirrel-cage designs eliminate rare earth dependency while sacrificing some torque density. Commercial vehicle operators across Alberta's freight corridors favor these architectures for total cost of ownership predictability amid mineral price volatility.
Most installed capacity flows through Permanent Magnet Motor configurations. Expansion is steepest in Induction Motor variants as fleet operators hedge against supply chain concentration.
Vehicle Type:
Volume concentration determines manufacturing scale economics, with passenger car platforms amortizing tooling investments across multi-year production commitments.
- Passenger Cars:Battery electric and plug-in hybrid platforms dominate motor procurement volume through Detroit Three assembly operations in Ontario. Federal zero-emission vehicle mandates compressing automaker timelines are forcing shared motor architectures across compact, mid-size, and luxury segments.
- Commercial Vehicles:Medium-duty delivery vans and heavy-duty freight trucks require modular motor mounting systems compatible with multiple chassis configurations. British Columbia's municipal fleet decarbonization programs are expanding procurement beyond traditional passenger car volumes.
- Two-Wheelers:Low-voltage hub motor and mid-drive configurations serve urban micromobility markets in Montreal and Vancouver. Quebec's distinct safety standards create homologation complexity for national distribution strategies.
- Buses:Transit authority specifications demand integrated powertrain service agreements rather than component-only procurement. Toronto and Vancouver metropolitan operators are consolidating supplier relationships around single-source drivetrain accountability.
Passenger Cars absorb the majority of production capacity. Buses are climbing the fastest as federal infrastructure programs accelerate municipal electrification timelines.
Power Output:
Manufacturing complexity escalates nonlinearly with power rating, as thermal management and high-voltage insulation requirements dominate capital expenditure decisions.
- Low Power:Sub-50kW architectures serve urban two-wheelers and auxiliary systems where packaging constraints override performance optimization. Vancouver's bike-share expansion and last-mile delivery electrification concentrate demand in this bracket.
- Medium Power:50-150kW synchronous motors power compact and mid-size passenger vehicles across Ontario assembly lines. Windsor suppliers are scaling hairpin winding automation to serve regional EV startups without billion-unit commitments.
- High Power:150-300kW systems dominate premium passenger cars and medium-duty commercial platforms. Silicon carbide inverter integration challenges limit deployment velocity as embedded systems engineering talent concentrates in Waterloo and Toronto.
- Ultra High Power:Exceeding 300kW for long-haul trucking and heavy freight applications, these architectures require liquid cooling systems and reinforced stator laminations. The Calgary-Edmonton freight corridor presents untapped demand as provincial zero-emission mandates extend to heavy-duty segments.
Medium Power brackets carry the greatest installed base. Ultra High Power systems are gaining share fastest as provincial regulations push beyond passenger car electrification.
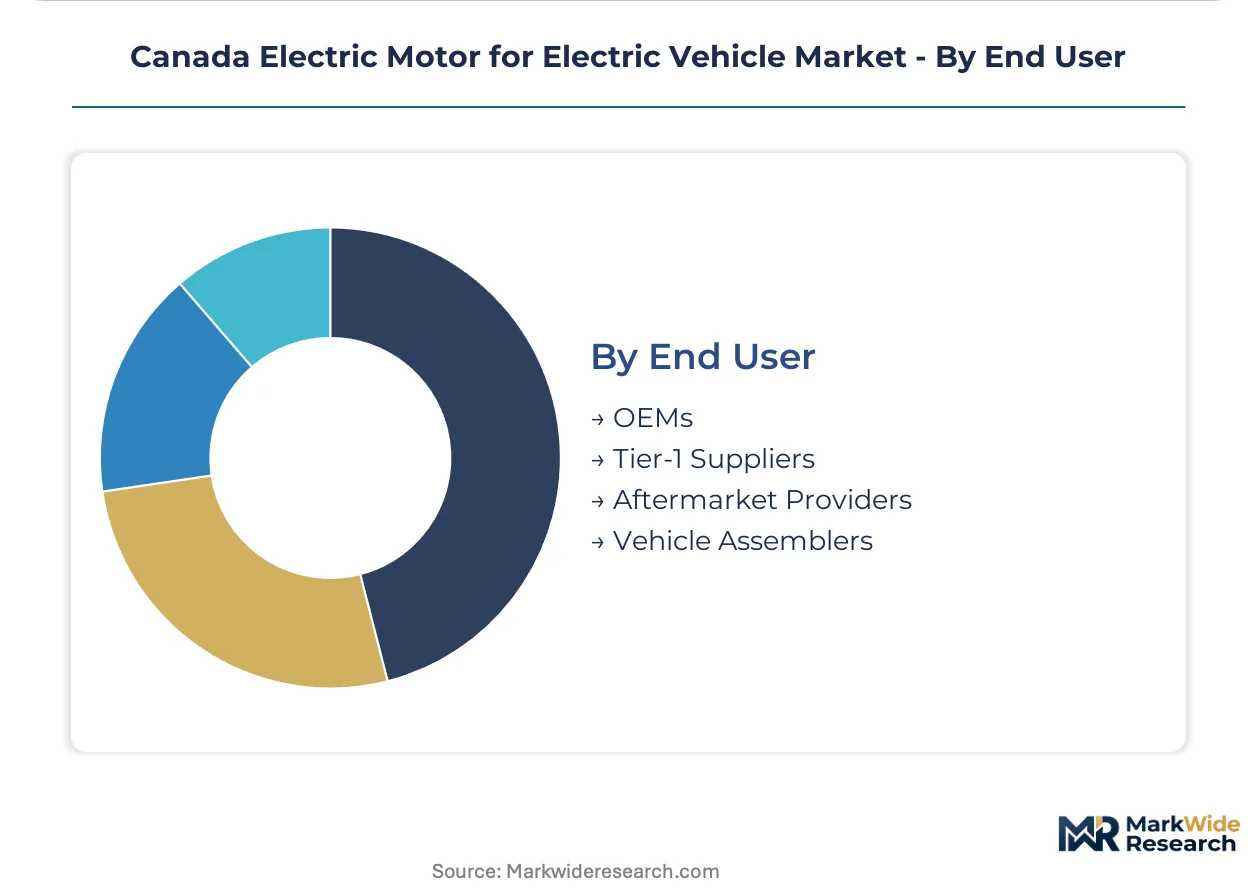
End User:
Procurement authority and technical integration responsibility vary sharply across the value chain, determining margin capture and aftermarket access.
- OEMs:Original equipment manufacturers specify motor architectures and control integration protocols for vehicle platforms assembled in Windsor and Oshawa. In-house powertrain divisions at major automakers are backward integrating into motor design to protect electrification intellectual property.
- Tier-1 Suppliers:Integrated powertrain specialists like Robert Bosch GmbH and Linamar deliver complete motor-inverter-gearbox assemblies. These suppliers anchor Ontario's automotive corridor through proximity to Detroit Three plants and Transport Canada certification facilities.
- Aftermarket Providers:Replacement motor and remanufacturing services target fleet operators seeking to extend vehicle service life. Single-source accountability trends in municipal transit are compressing aftermarket margins as operators consolidate around integrated service agreements.
- Vehicle Assemblers:Contract manufacturers and emerging EV startups without captive powertrain capabilities rely on outsourced motor supply. Ontario's Golden Horseshoe distributed production nodes are enabling smaller-scale procurement through hairpin winding automation adoption.
Tier-1 Suppliers channel the dominant share of production volume. OEMs are expanding their captive share fastest as platform consolidation accelerates under federal mandate pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration within Canada follows regulatory-arbitrage logic as provincial zero-emission mandates and tax credit structures create compliance-cost differentials for motor suppliers. Ontario's automotive corridor captures the majority of investment flows.
Ontario
Windsor and Oshawa anchor EV assembly and motor supplier clustering with the densest concentration of Detroit Three operations. Transport Canada's Motor Vehicle Safety Regulations enforcement creates homologation advantages for suppliers co-located with certification facilities. The Golden Horseshoe region hosts emerging hairpin winding automation adoption serving regional EV startups.
Quebec
Montreal's micromobility hub drives low-voltage hub motor demand for urban bike-share expansion. Distinct provincial vehicle safety standards create compliance duplication costs for national motor distribution strategies. Local procurement mandates under federal infrastructure programs channel assembly partnerships toward Indigenous community benefit requirements.
British Columbia
Vancouver metropolitan transit authorities consolidate supplier relationships around single-source drivetrain accountability for municipal bus fleets. Provincial fleet decarbonization programs expand medium-duty motor procurement beyond traditional passenger car volumes. The Pacific gateway position facilitates rare earth magnet import flows for synchronous motor production.
Alberta
The Calgary-Edmonton freight corridor presents untapped demand for ultra-high-power motor systems in long-haul trucking applications. Provincial zero-emission mandate extensions to heavy-duty segments accelerate commercial vehicle electrification timelines. Fleet operators favor induction motor architectures for total cost of ownership predictability amid mineral price volatility.
Saskatchewan
Emerging critical mineral refining capacity reduces permanent magnet import dependency for synchronous motor production. Rare earth processing infrastructure development redirects procurement toward domestic magnet sourcing for Windsor-Oshawa assembly supply. The province's resource extraction expertise transfers to downstream magnet alloy production.
Canada Electric Motor for Electric Vehicle Market Competitive Environment
Capacity expansion dominates the current landscape as suppliers scale hairpin winding automation to serve regional EV startups without billion-unit commitments. The market structure concentrates around integrated powertrain specialists and captive OEM divisions, with Tier-1 suppliers anchoring Ontario's automotive corridor through proximity to assembly plants. Three archetypes define competitive positioning: diversified global automotive suppliers with electronics integration capabilities, regional fabricators leveraging manufacturing scale near Detroit Three operations, and vertically integrated vehicle manufacturers controlling proprietary motor design. Geographic expansion and technology licensing represent the dominant competitive moves as suppliers seek USMCA domestic content qualification.
Within the diversified global supplier tier, Robert Bosch GmbH and Denso Corporation exemplify integrated powertrain electronics portfolios serving multiple vehicle segments. Among North American-based fabricators, Linamar occupies a position representing Ontario manufacturing scale and proximity-driven supply relationships. Tesla Inc. anchors the captive manufacturer archetype through proprietary permanent magnet motor design and in-house rotor production control.
| Leading Market Players |
|---|
| Tesla Inc. |
| Robert Bosch GmbH |
| BorgWarner Inc. |
| Denso Corporation |
| BYD Co. Ltd. |
| BAIC Group Co., Ltd. |
| Jing-Jin Electric Technologies Co., Ltd. |
| General Motors |
| Linamar |
| Others |
Value Chain & Pricing Dynamics
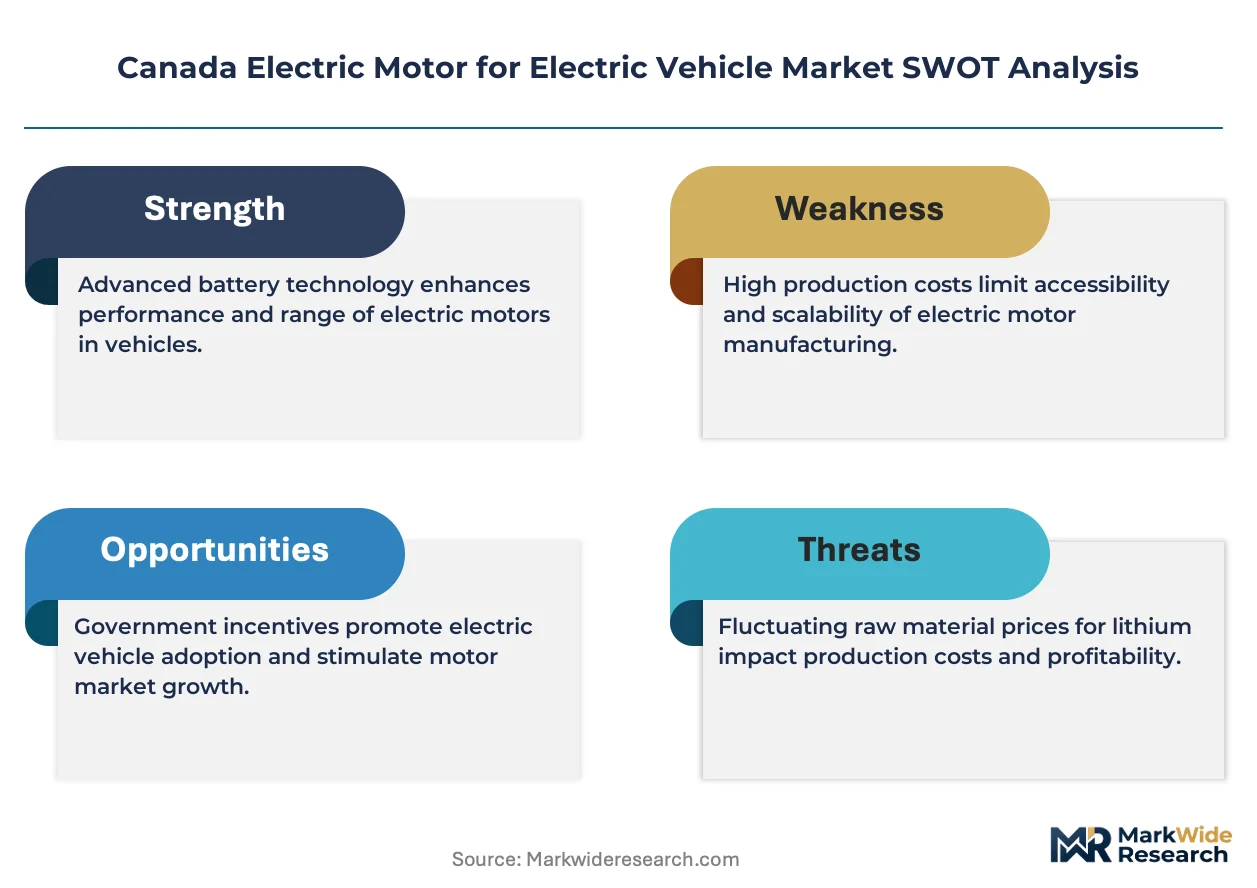
Neodymium price indices on the Shanghai Rare Earth Exchange cascade through Canadian motor manufacturing, compressing margins on permanent magnet synchronous architectures while amplifying cost advantages for induction motor alternatives in fleet procurement decisions.
Pricing Analysis
Distributor margins on integrated powertrain assemblies absorb the steepest compression as OEMs consolidate supplier relationships around single-source accountability. Three-tier pricing structure across premium high-efficiency synchronous motors, standard induction architectures, and economy remanufactured units stratifies procurement decisions. Cost compression in the medium-power bracket intensifies because silicon carbide inverter shortages force motor suppliers to absorb integration risk. Municipal transit authorities exhibit lowest price sensitivity due to federal infrastructure funding coverage, while regional EV startups face acute budget constraints.
Supply Chain Analysis
Dual-sourcing requirements from Transport Canada and major OEMs mandate multi-supplier qualification for rare earth magnet procurement, fragmenting order books across Chinese, Vietnamese, and emerging Saskatchewan processors. The supply chain draws from neodymium-iron-boron alloy production, copper winding stock, and silicon carbide substrate fabrication. Single-source vulnerability concentrates in Chinese rare earth processing concentration, creating tariff exposure under evolving USMCA domestic content rules. Distribution runs through Windsor-Oshawa assembly plant proximity networks, with tier-1 suppliers maintaining bonded inventory at OEM facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where fleet operators prioritize total cost of ownership predictability over upfront unit economics, redirecting procurement toward induction architectures and integrated service agreements.
For Market Incumbents: Anchor manufacturing scale through hairpin winding automation investments in Ontario's Golden Horseshoe to defend against emerging distributed production nodes. Backward integration into Saskatchewan rare earth processing protects magnet cost exposure. Consolidate aftermarket service relationships before municipal transit authorities complete single-source drivetrain vendor selection.
For New Entrants and Emerging Players: Heavy-duty freight operators along the Calgary-Edmonton corridor represent the most penetrable buyer archetype, with ultra-high-power motor demand outpacing established supplier capacity. Indigenous procurement mandates under federal infrastructure programs open partnership channels unavailable to incumbent tier-1 suppliers. Target integrated thermal management system bundling as the go-to-market angle, combining motor supply with cold-climate heat pump expertise.
For Investors and Strategic Acquirers: Asymmetric upside sits with Ontario-based tier-2 fabricators possessing hairpin winding automation and Transport Canada certification relationships, positioned for acquisition by global suppliers seeking USMCA domestic content qualification. Long-term viability hinges on rare earth supply chain decoupling from Chinese processing concentration. Watch Saskatchewan magnet alloy production timelines as the inflection signal for domestic sourcing economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Rare Earth Processing Investment | Saskatchewan refining capacity reduces import dependency for Windsor-Oshawa motor assembly supply chains. |
| Hairpin Winding Automation Scale-Up | Ontario tier-2 suppliers adopt copper forming processes to serve regional EV startups without billion-unit commitments. |
| Integrated Powertrain Service Agreements | Municipal transit authorities in British Columbia and Ontario consolidate supplier relationships around single-source accountability. |
| Silicon Carbide Inverter Integration | Waterloo-Toronto embedded systems engineering scarcity limits high-efficiency motor deployment velocity in commercial platforms. |
| Indigenous Procurement Partnerships | Federal infrastructure community benefit requirements channel assembly partnerships toward regional motor fabrication joint ventures. |
Study Parameters
Bottom-up vehicle production modeling reconciled against top-down motor supplier capacity tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, tier-1 supplier procurement directors, municipal transit fleet managers, and aftermarket remanufacturing operators combined with secondary validation from Transport Canada Motor Vehicle Safety Regulations filings, Environment and Climate Change Canada zero-emission vehicle sales data, IHS Markit vehicle production databases, and USMCA customs trade records. Triangulation across these sources ensures segmentation integrity across motor type, vehicle class, and power output dimensions.
Historical trendline analysis of electric vehicle registration patterns and motor procurement volumes established baseline growth trajectories across the projection horizon. The forecast framework segments by motor architecture, vehicle type, power output bracket, and end-user procurement authority, with CAGRs derived from elasticity modeling against federal mandate compliance timelines and provincial fleet decarbonization program commitments. Rare earth price volatility indices and silicon carbide inverter supply constraints feed into scenario-weighted output distributions.
Underlying measurement precision varies by segment; passenger car motor volumes carry tighter precision than emerging ultra-high-power commercial vehicle estimates due to production data availability. Forecasts reflect documented assumptions regarding USMCA domestic content rule evolution and Transport Canada electromagnetic compatibility testing cycle durations. Deviation in Saskatchewan rare earth processing facility commissioning timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Europe Electric Motor Market
Electric Motor
EV Traction Motor Market
Electric Motor
Starter Motor Market
Electric Motor
Traction Motors Market
Electric Motor
United States AC Motor Market
Electric Motor
Electric Motorcycle Market
Electric Motor
Electric Vehicle Motor Control Unit Market
Electric Motor
Automotive Electric Motors Market
Electric Motor
Electric Propulsion Systems Market
Electric Motor
Voice Coil Motor Market
Electric Motor
Kayak Trolling Motor Market
Electric Motor
Vibrator Motor Market
Electric Motor
Electric Vehicle Motor (EVM) Controller Market
Electric Motor
North America Alternating Current (AC) Motor Market
Electric Motor
Trolling Motor Market
Electric Motor
Global Electric Motor Market