
 Global Motor Soft Starter Market | 2026-2036
Global Motor Soft Starter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Motor Soft Starter Market Analysis
Industrial distribution channels is reconfiguring around direct OEM partnerships and authorized system integrator networks. Siemens AG leverages its factory automation footprint to bundle soft starters with variable frequency drives. ABB Ltd. anchors its position through medium-voltage specialization in mining and minerals processing. Schneider Electric SE competes on digital control integration with its EcoStruxure platform architecture.
A motor soft starter limits inrush current during motor startup through silicon-controlled rectifier phase-angle control, typically managing currents from two to eight times full-load amperage down to three to four times baseline. The device extends mechanical equipment life by reducing torque shock on couplings, gearboxes, and driven loads across industrial pump, fan, and compressor applications. Three-phase soft starters occupy the dominant product position due to universal deployment in industrial motor systems above fractional horsepower ratings. Digital control architectures represent the fastest-expanding segment as facilities prioritize remote diagnostics and predictive maintenance integration over relay-based legacy systems. Low-voltage ratings sustain the largest installed base, though medium-voltage units command premium positioning in heavy-process industries.
Regulatory frameworks including IEC 60947-4-2, NEMA ICS 2, and EU Ecodesign Directive shape product certification requirements and energy efficiency benchmarks across major supply regions. China's GB 14048.6 standard and India's BIS certification mandate local testing protocols that influence market access timelines for imported equipment. Stakeholders must monitor evolving harmonics emission limits and carbon border adjustment mechanisms as these frameworks increasingly determine specification criteria in cross-border procurement.
Market Dynamics
Digital control architectures are compressing replacement cycles across installed soft starter bases as facilities prioritize predictive maintenance integration over relay-based legacy protection systems.
Growth Catalysts
- IEC 60947-4-2 compliance mandates:European Union certification requirements are forcing motor protection upgrades in industrial corridors, redirecting manufacturer R&D budgets toward medium-voltage digital units.
- Water treatment infrastructure:Utilities across China's industrial corridor cities are expanding procurement of medium-voltage soft starters for pump station retrofits tied to state-backed modernization programs.
- Silicon-controlled rectifier phase-angle control:Advances in SCR technology enable precise inrush current management from eight times down to three times full-load amperage, extending mechanical equipment life in heavy-process applications.
Market Restraints
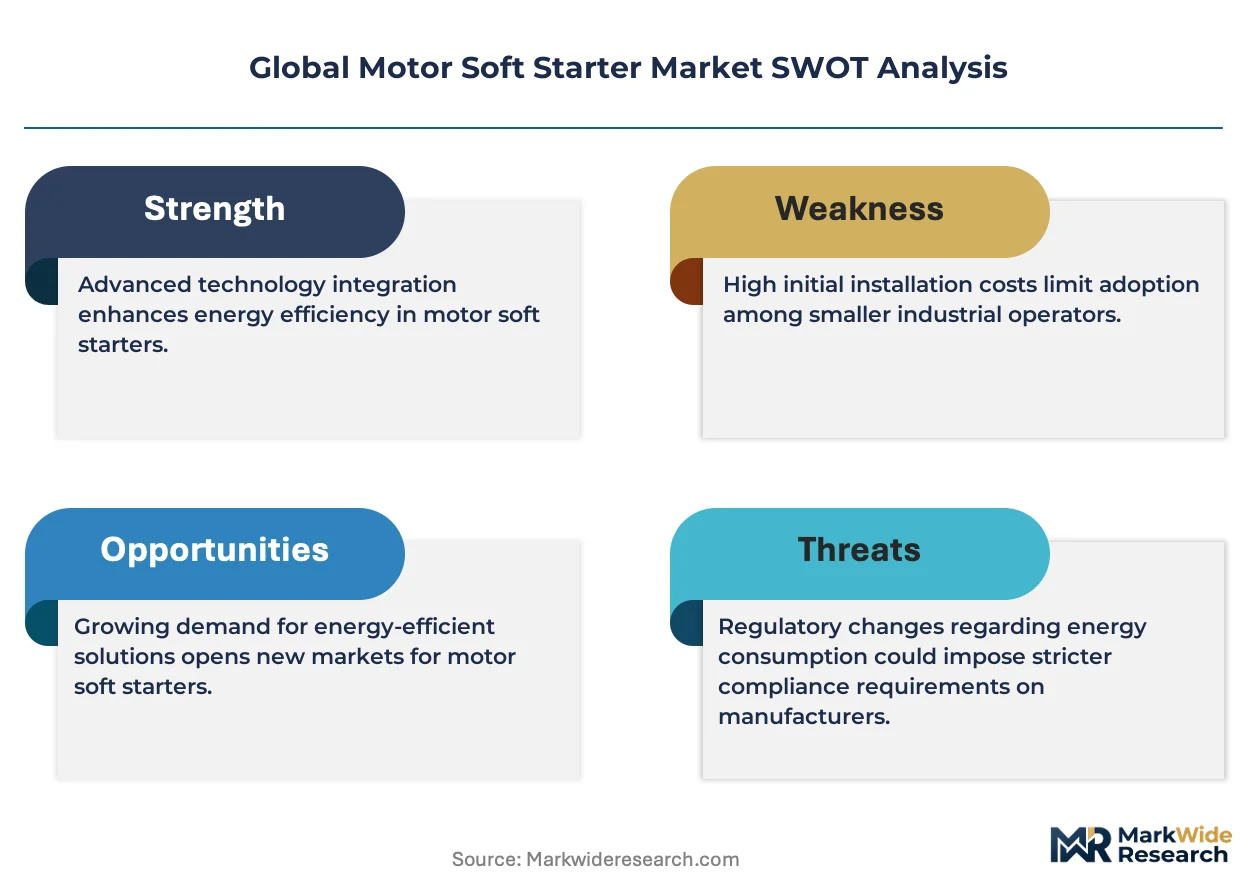
- Copper and silicon price volatility:Raw material input costs for power semiconductor components create margin pressure across low-voltage product lines.
- Supply concentration in East Asian foundries:Thyristor wafer fabrication concentrates in Taiwan and South Korea, exposing procurement timelines to geopolitical disruption risk.
- Variable frequency drive substitution:VFDs capture applications requiring speed control beyond soft starter torque management, compressing addressable market scope in fan and pump segments.
Strategic Opportunities
- India's BIS certification pathway:Local testing mandates for imported equipment create first-mover advantage for manufacturers establishing domestic assembly operations ahead of competitors.
- Carbon border adjustment mechanisms:Emerging EU trade instruments will favor energy-efficient motor starting solutions, privileging certified soft starters over direct-on-line alternatives in cross-border procurement.
- IIoT convergence with edge analytics:Integration of soft starter diagnostics with plant-wide asset management platforms opens recurring revenue streams through condition-monitoring subscriptions.
Industry Challenges
- Power electronics engineering scarcity:Specialized talent for medium-voltage SCR design and thermal management remains concentrated among aging workforce cohorts in Germany and Japan.
- Legacy system integration complexity:Retrofit installations in brownfield facilities demand custom mechanical adaptation and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Motor Soft Starter Market |
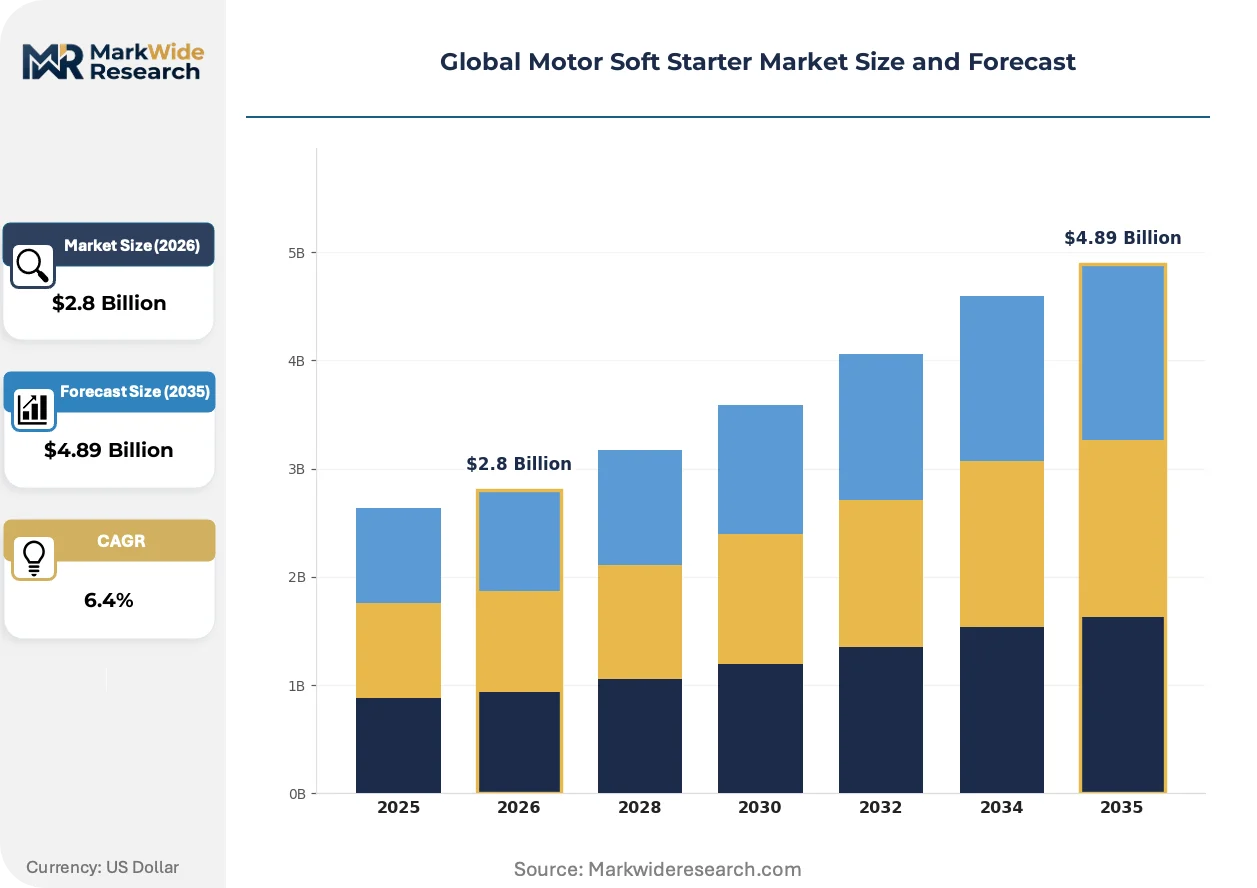
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Three-Phase Soft Starters, Single-Phase Soft Starters, Integrated Soft Starters, Modular Soft Starters End User: Manufacturing, HVAC, Mining, Water Treatment Voltage Rating: Low Voltage, Medium Voltage, High Voltage, Ultra High Voltage Control Type: Relay Control, Digital Control, PLC Control, Analog Control |
| Companies Covered | Siemens AG, ABB Ltd., Schneider Electric SE, Eaton Corporation PLC, Rockwell Automation Inc., Danfoss Group, WEG, Mitsubishi Electric Corporation, AuCom Electronics Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Motor Soft Starter Market Emerging Trajectories
Predictive maintenance integration is reshaping specification criteria as buyers prioritize remote diagnostics over basic motor protection, compressing the viable feature set for new product introductions.
Integrated soft starter-variable frequency drive hybrid units are rendering obsolete standalone relay-based starting systems in process industries requiring both torque control and operational speed flexibility. Mining and minerals processing operators in Australia and Chile are specifying these converged platforms for conveyor and crusher applications. The technology is rendering obsolete traditional procurement patterns that separated starting and speed control into distinct capital budgets.
EU Ecodesign Directive efficiency benchmarks are tightening minimum performance requirements for motor control equipment across member states, eliminating marginal products from commercial distribution. Industrial OEMs in Germany and Italy are redesigning motor control centers to preempt compliance gaps. Low-voltage soft starter portfolios face the most acute certification recertification pressure as the directive phases in through 2027.
Direct OEM partnership models are displacing traditional distributor stocking arrangements as manufacturers seek tighter specification control in project-based procurement. Authorized system integrator networks in China's Pearl River Delta and Yangtze River Delta manufacturing clusters are capturing specification influence previously held by electrical wholesalers. This channel restructuring concentrates margin capture with technical specialists capable of commissioning complex medium-voltage installations.
Global Motor Soft Starter Market Segmentation
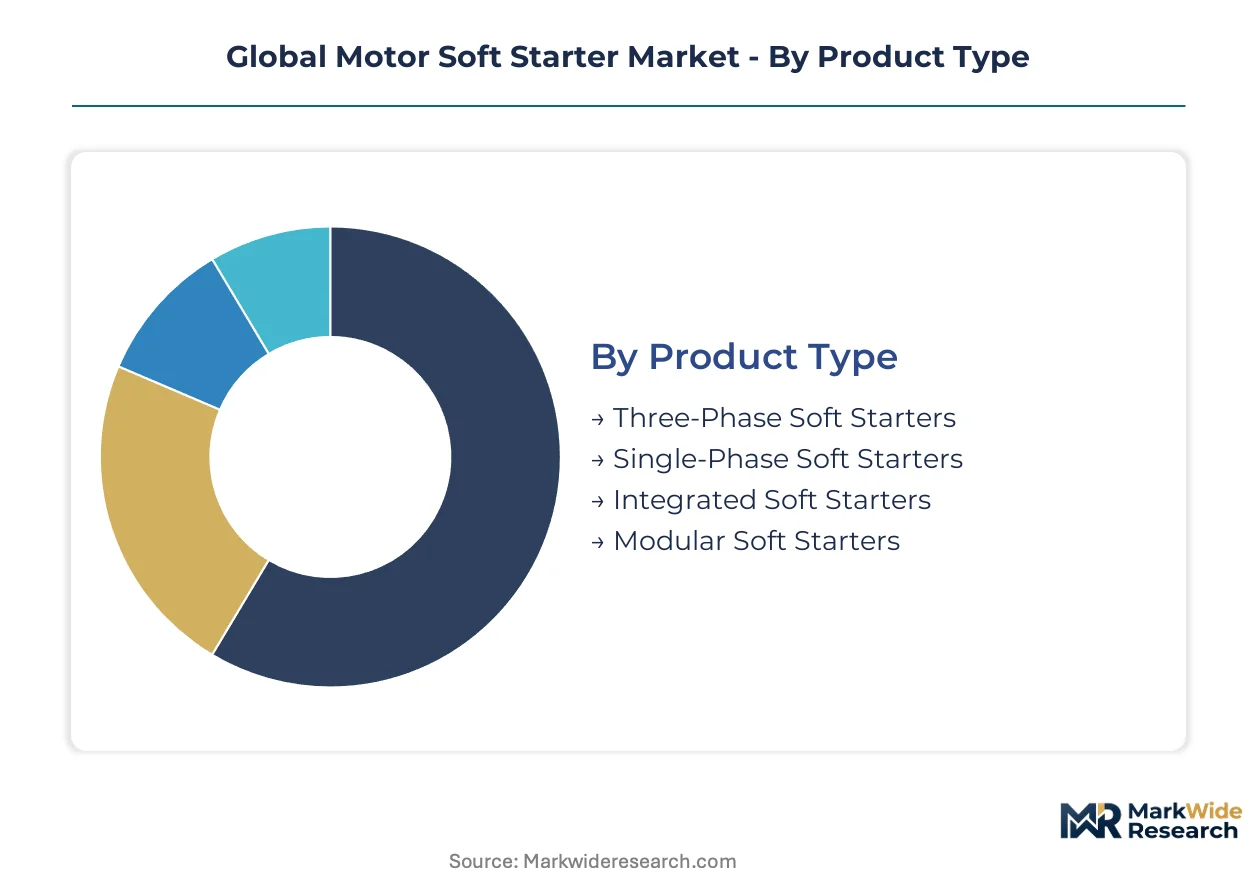
Segmentation reveals how procurement patterns diverge across technical specifications and operational contexts. Understanding these divisions clarifies where margin concentration and specification influence cluster in the motor soft starter landscape.
Product Type:
After-sales service intensity varies sharply by product architecture, with integrated platforms demanding embedded diagnostic support while modular units require field-assembly expertise.
- Three-Phase Soft Starters:These units manage silicon-controlled rectifier phase-angle control across industrial three-phase power systems. Demand clusters in China's manufacturing corridor cities where state-backed infrastructure modernization accelerates motor protection upgrades. IEC 60947-4-2 compliance mandates in the European Union redirect manufacturer R&D budgets toward digital variants of this dominant configuration.
- Integrated Soft Starters:Converged platforms combine soft starting with variable frequency drive functionality in unified enclosures. Mining operators in Australia and Chile specify these for conveyor applications requiring both torque control and operational speed flexibility.
- Single-Phase Soft Starters:Fractional horsepower applications in commercial HVAC systems deploy these compact units for pump and fan starting.
- Modular Soft Starters:Field-configurable architectures allow scaling across multiple motor ratings in distributed pump stations.
By volume, Three-Phase Soft Starters leads. By growth pace, Integrated Soft Starters is ahead.
End User:
Application environments dictate thermal management requirements, with heavy-process industries commanding premium specifications over commercial building systems.
- Water Treatment:Utilities expanding procurement of medium-voltage units for pump station retrofits drive specification intensity. China's state-backed infrastructure modernization accelerates motor protection upgrades across municipal and industrial water systems.
- Mining:Minerals processing operators anchor medium-voltage demand through conveyor and crusher applications requiring ruggedized SCR thermal management.
- Manufacturing:Industrial motor systems above fractional horsepower ratings deploy soft starters across assembly and process lines.
- HVAC:Commercial building automation integrates low-voltage units for fan and compressor starting in climate control systems.
By installed base, Manufacturing dominates. By specification premium, Mining commands the highest unit economics.
Voltage Rating:
Cost tiers stratify sharply around insulation systems and semiconductor packaging, with medium-voltage architectures requiring specialized engineering talent concentrated in Germany and Japan.
- Low Voltage:The largest installed base sustains this category across industrial and commercial applications. EU Ecodesign Directive efficiency benchmarks face the most acute certification recertification pressure as the directive phases in through 2027.
- Medium Voltage:Premium positioning in heavy-process industries commands specialized procurement channels. Water treatment utilities across China's industrial corridor cities are expanding procurement for pump station retrofits.
- High Voltage:Specialized mining and minerals processing applications require custom thermal management and isolation systems.
- Ultra High Voltage:Limited deployment in grid-scale pump stations and bulk material handling systems.
By unit shipments, Low Voltage outpaces all others. By margin contribution, Medium Voltage delivers superior returns.
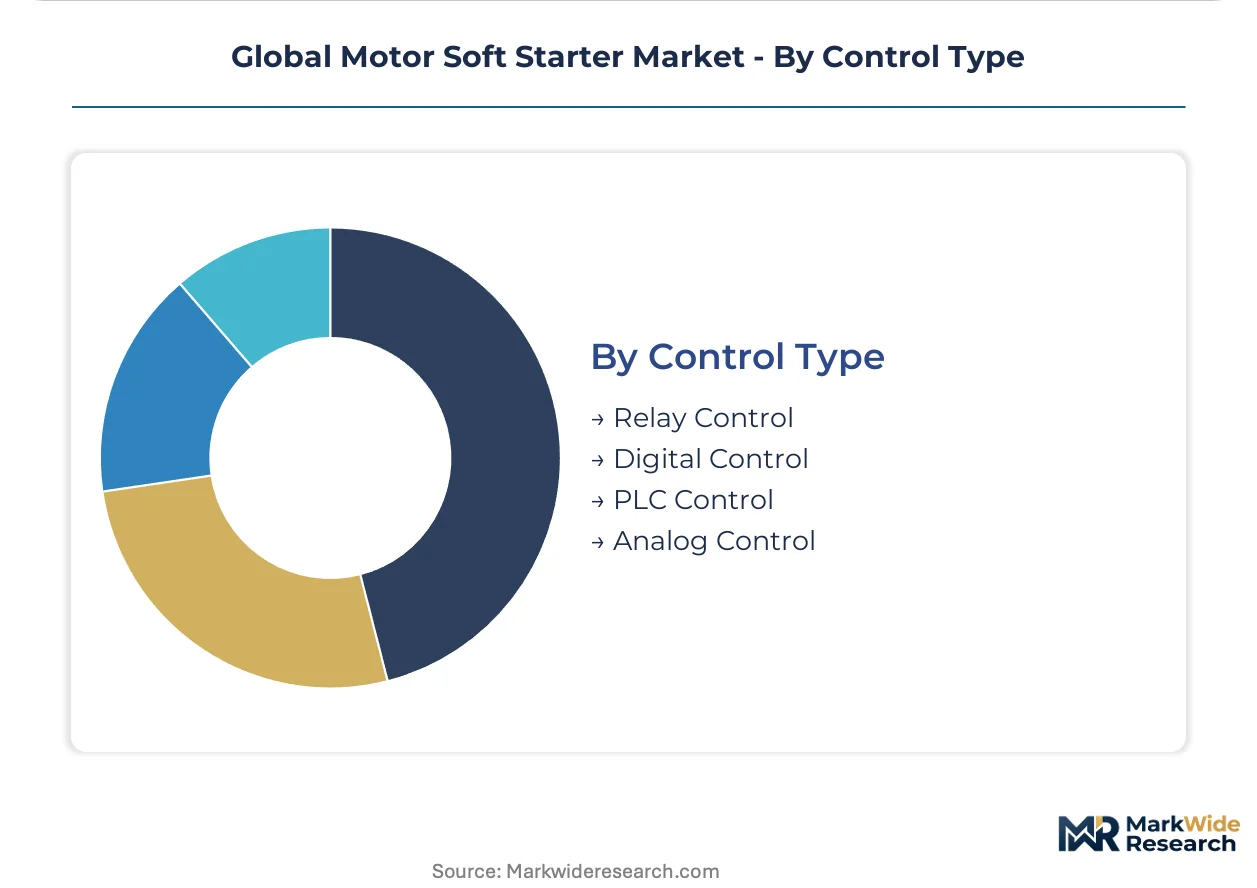
Control Type:
Customer technology maturity determines specification pathways, with digital-native facilities demanding predictive maintenance integration while legacy operations retain relay-based protection.
- Digital Control:Remote diagnostics and predictive maintenance integration compress replacement cycles across installed bases. Facilities prioritize these architectures over relay-based legacy protection systems.
- PLC Control:Plant-wide automation integration enables centralized motor management through existing distributed control infrastructure.
- Relay Control:Legacy installations in brownfield facilities demand custom mechanical adaptation and extended commissioning timelines.
- Analog Control:Cost-sensitive applications in developing markets retain these simplified architectures for basic motor protection.
By replacement velocity, Digital Control is expanding most quickly. By residual installed base, Relay Control retains significant presence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in German engineering corridors while volume manufacturing gravitates toward Chinese industrial clusters. This asymmetry shapes procurement patterns across voltage tiers and control architectures.
China
State-backed infrastructure modernization accelerates motor protection upgrades across manufacturing clusters in the Yangtze River Delta and Pearl River Delta. GB 14048.6 certification mandates local testing protocols that influence market access timelines for imported equipment. Water treatment utilities in Shanghai and Suzhou are expanding medium-voltage procurement for pump station retrofits.
Germany
EU Ecodesign Directive efficiency benchmarks eliminate marginal products from commercial distribution through 2027. IEC 60947-4-2 compliance requirements redirect manufacturer R&D budgets toward medium-voltage digital units. Industrial OEMs in Bavaria and Baden-Württemberg are redesigning motor control centers to preempt certification gaps.
United States
NEMA ICS 2 certification shapes product requirements across heavy-process industries in the Gulf Coast petrochemical corridor. FERC grid reliability standards influence specification criteria in utility-scale pump stations. Mining operators in Arizona and Nevada anchor medium-voltage demand through conveyor applications requiring ruggedized thermal management.
India
BIS certification mandates for imported equipment create first-mover advantage for manufacturers establishing domestic assembly operations. The PLI scheme incentivizes local production of power electronics components. Industrial corridors in Maharashtra and Gujarat are capturing specification influence through authorized system integrator networks.
Australia
Mining and minerals processing operators in Western Australia and Queensland specify converged soft starter-VFD platforms for bulk material handling. TGA-equivalent electrical safety standards govern equipment certification for underground deployment. Remote site logistics compress commissioning timelines and favor pre-integrated control architectures.
Global Motor Soft Starter Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream on semiconductor and thermal management technologies. The vendor base organizes around three strategic archetypes: diversified automation conglomerates bundling soft starters with drives, medium-voltage specialists anchoring mining and heavy-process verticals, and digital-native challengers converging edge analytics with motor protection. Dominant competitive moves include direct OEM partnership models displacing distributor stocking arrangements, and IIoT convergence opening recurring revenue streams through condition-monitoring subscriptions.
Among European-based diversified industrials, Siemens AG and ABB Ltd. exemplify platform-integration archetypes spanning factory automation through utility-scale infrastructure. Schneider Electric SE represents the digital control convergence vector, anchoring specification influence through integrated architecture plays. These three entities collectively illustrate how vendor positioning stratifies between bundled system sales and standalone component supply.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd. |
| Schneider Electric SE |
| Eaton Corporation PLC |
| Rockwell Automation Inc. |
| Danfoss Group |
| WEG |
| Mitsubishi Electric Corporation |
| AuCom Electronics Ltd |
| Others |
Supply Flow & Price Mechanics
Thyristor wafer fabrication concentrates in Taiwan and South Korea, anchoring margin capture downstream with manufacturers possessing captive semiconductor supply or long-term foundry agreements. This upstream concentration forces pricing discipline across voltage tiers, as SCR component costs transmit directly to medium-voltage unit economics.
Pricing Analysis
Configured-to-order pricing for medium-voltage mining applications commands substantial premiums over standard low-voltage catalog pricing. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales bundling intensity. Cost compression in low-voltage lines is intensifying because copper and silicon price volatility erodes fixed-margin contracts. Municipal water utilities exhibit highest price sensitivity, while mining operators in Australia and Chile accept premium positioning for ruggedized thermal management specifications.
Supply Chain Analysis
Foundry capacity at TSMC and Samsung Electronics anchors thyristor production, with power semiconductor packaging concentrated in Malaysia and Vietnam. Raw material flows draw from Chilean copper cathode, Mongolian rare earth processing, and German silicon wafer polishing. Single-source vulnerability in East Asian foundry networks exposes procurement timelines to geopolitical disruption risk. Distribution runs through authorized system integrator networks in China's Pearl River Delta and direct OEM partnerships displacing traditional electrical wholesaler stocking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards specialized engineering talent for medium-voltage SCR thermal management that remains concentrated among aging workforce cohorts in Germany and Japan. This capability scarcity creates defensive moats for incumbents while raising barriers for new entrants lacking access to experienced power electronics design teams.
For Market Incumbents: Harden medium-voltage digital R&D pipelines against variable frequency drive substitution by converging soft starter functionality with edge analytics platforms. Secure backward integration into thyristor wafer supply through long-term foundry agreements or captive packaging operations in Southeast Asia. Channel control through direct OEM partnerships in China's Yangtze River Delta manufacturing clusters protects specification influence from distributor disintermediation. For New Entrants and Emerging Players: Pursue India's BIS certification pathway by establishing domestic assembly operations ahead of competitors, capturing first-mover advantage as local testing mandates delay imported equipment timelines. Target water treatment utilities in China's industrial corridor cities where state-backed infrastructure modernization accelerates procurement cycles. Lead with IIoT-enabled condition-monitoring subscriptions that open recurring revenue streams distinct from transactional equipment sales. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial automation platforms seeking add-on acquisitions to complete motor control portfolios. Long-term viability hinges on digital control architecture capabilities and authorized system integrator network density across Asia-Pacific manufacturing clusters. Watch for carbon border adjustment mechanism implementation signals from EU trade authorities as inflection indicators privileging certified soft starters over direct-on-line alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thyristor Supply | Captive semiconductor sourcing insulates margin pressure from East Asian foundry concentration. |
| IIoT Platform Convergence | Edge analytics integration with EcoStruxure-type architectures opens recurring condition-monitoring revenue. |
| Direct OEM Partnership Expansion | Specification control in China's manufacturing clusters displaces distributor influence. |
| Medium-Voltage Certification Investment | IEC 60947-4-2 compliance redirects R&D budgets toward premium mining and water treatment segments. |
| Authorized System Integrator Network Buildout | Technical commissioning capability in Pearl River Delta captures project-based procurement margin. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads across industrial motor control installations, and secondary validation through IEC certification databases, customs trade records, SEC 10-K filings, and power electronics component import registries. Bottom-up unit shipment estimates triangulated against top-down voltage tier spending analysis.
Forecast inputs considered silicon-controlled rectifier technology advancement curves, EU Ecodesign Directive phase-in schedules, and China's state-backed infrastructure modernization program commitments across the projection horizon. Segmentation modeling spanned product architecture, voltage rating, control type, and end-use industry vertical. CAGRs derived from regression analysis of replacement cycle compression and greenfield installation patterns.
Sensitivities concentrate around thyristor wafer supply disruption, copper price volatility, and carbon border adjustment mechanism implementation timing. Forecasts reflect assumptions regarding IEC 60947-4-2 compliance adoption rates and IIoT platform penetration in brownfield facilities. Quarterly review of foundry utilization rates, EU regulatory filing timelines, and Chinese municipal water infrastructure tender announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Asia-Pacific AC Electric Motor Market
Electric Motor
Global Electric Motors for Electric Vehicle Market
Electric Motor
Electric Drives Market
Electric Motor
Europe Automotive Torque Actuator Motor Market
Electric Motor
Automotive Hub Motors Market
Electric Motor
Starter Motor Market
Electric Motor
Electric Vehicle Flat Wire Motor Market
Electric Motor
Electric Trolling Motors Market
Electric Motor
Automotive Blower Motor Market
Electric Motor
Canada Electric Motor for Electric Vehicle Market
Electric Motor
Automotive Electric Commutators Market
Electric Motor
Australia Solar E-Bike Market
Electric Motor
Global EV Motor Controller Market
Electric Motor
Voice Coil Motor Market
Electric Motor
Automotive Induction Motors Market
Electric Motor
Global Hub Motors Market