
 France Alternating Current (AC) Motor Market | 2026-2036
France Alternating Current (AC) Motor Market Size, Share, and Industry Trends Forecast 2026-2036
France Alternating Current (AC) Motor Market Insights
France is reconfiguring its industrial motor supply base around energy-transition mandates and reshoring incentives. Siemens AG leverages deep integration with French automotive OEMs to anchor its position in precision servo motor lines. ABB Ltd sustains technology leadership through advanced digital monitoring platforms embedded across its induction motor portfolio. Bosch Group competes aggressively on manufacturing scale, operating dedicated production lines serving both domestic HVAC and export machinery channels.
An alternating current motor converts electrical energy into mechanical rotation through electromagnetic induction, typically operating at frequencies of 50 Hz in France with squirrel-cage or wound-rotor architectures determining torque characteristics. These machines drive compressors, conveyor systems, and pump networks across French industrial zones. Induction motors occupy the mature volume tier where price competition compresses margins, while servo motors capture premium positioning in robotics and CNC applications demanding precise positional feedback. The 20+ HP power rating segment concentrates value in heavy-process industries, whereas fractional HP units fragment across appliance and light commercial uses.
ANSM oversees medical device motor safety where AC drives power diagnostic equipment, while the EU Ecodesign Directive and CE marking framework mandate minimum efficiency tiers that filter non-compliant imports from French distribution channels. The EU Green Deal's industrial decarbonization targets further redirect procurement toward IE4 and IE5 efficiency classes. Stakeholders must monitor how France's national carbon border adjustment mechanisms reshape sourcing economics for imported motor components and raw magnetic materials.
Market Dynamics
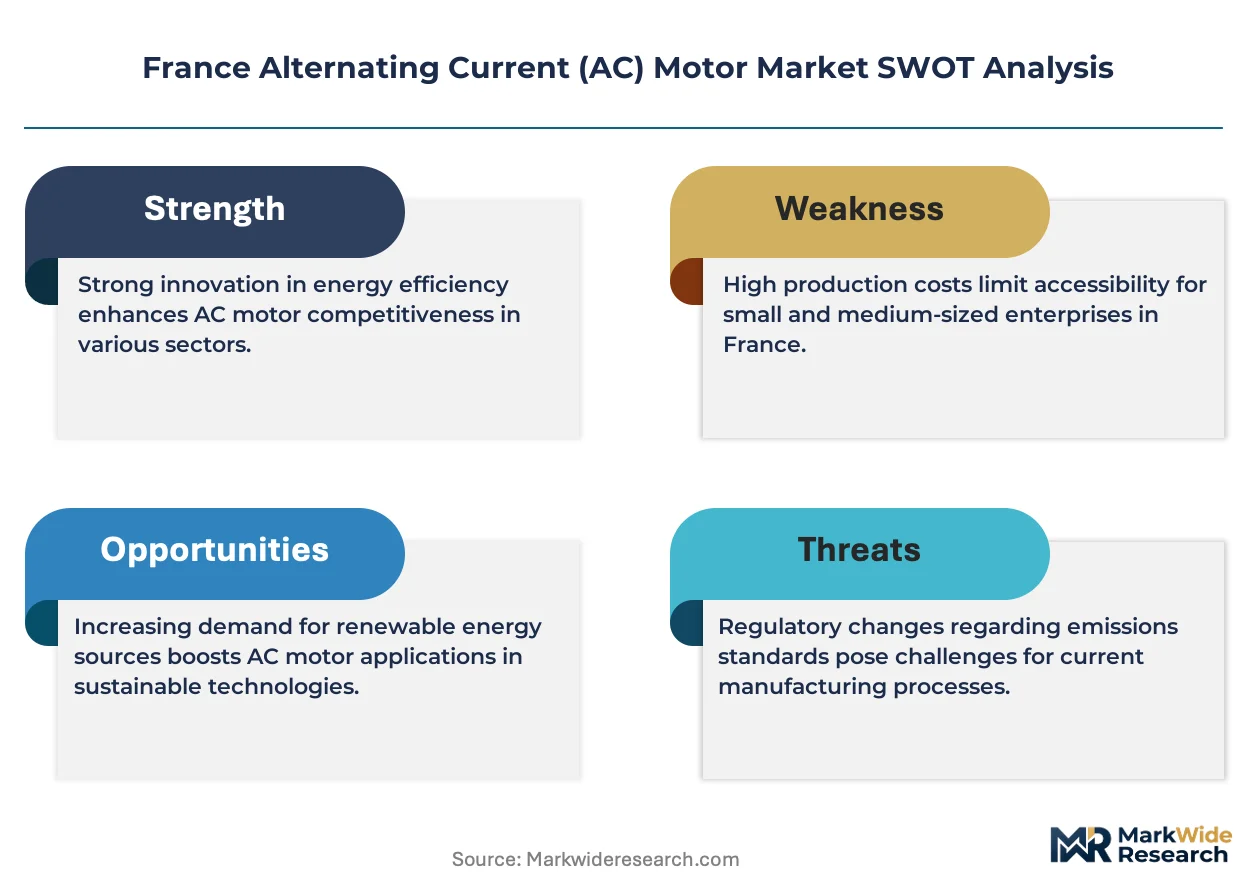
France's AC motor market is restructuring around the EU Ecodesign Directive's tightening efficiency tiers, which are systematically filtering non-compliant imports from distribution channels while redirecting procurement toward premium IE4 and IE5 motor classes.
Growth Catalysts
- Automotive electrification mandates:French OEM powertrain programs are accelerating AC motor integration into electric vehicle drivetrains, creating concentrated demand for high-torque synchronous architectures.
- EU Green Deal industrial decarbonization:The framework's binding emissions targets are forcing heavy-process industries in Île-de-France and Auvergne-Rhône-Alpes to replace legacy motor fleets with energy-efficient alternatives.
- Reshoring incentives:France's national manufacturing support schemes are attracting motor production capacity back to domestic facilities, shortening supply chains for critical industrial machinery applications.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings embedded in permanent magnet synchronous motors compress margins for manufacturers dependent on Chinese raw material supply.
- Technical limitation in high-speed applications:Induction motor rotor bar designs face thermal dissipation ceilings above 15,000 RPM, ceding ground to specialized PM machines in aerospace and precision tooling.
- Regulatory friction from CE marking complexity:The EU's harmonized efficiency testing protocols create compliance bottlenecks for smaller motor importers unfamiliar with IEC 60034-30-1 certification pathways.
Strategic Opportunities
- Underpenetrated Occitania industrial corridor:Chemical and food processing clusters around Toulouse and Montpellier remain below national averages for IE3+ motor penetration, presenting retrofit volume.
- Technology convergence of motors and power electronics:Integrated motor-drive systems combining variable frequency drives with permanent magnet machines are capturing premium positioning in robotics and CNC equipment.
- Regulatory tailwind from France's carbon border adjustment:The national mechanism is reshaping sourcing economics to favor domestic and near-EU motor component suppliers over Asian imports.
Industry Challenges
- Skill gap in high-efficiency motor servicing:Maintenance technicians trained on legacy induction architectures lack diagnostic capabilities for encoder-equipped servo systems and integrated drive-motor platforms.
- Certification timeline compression:ANSM medical device motor approvals and EU Ecodesign conformity assessments now run in parallel, straining engineering resources at multi-sector motor suppliers.
- Integration complexity with legacy control systems:New IE4/IE5 motors often require incompatible variable frequency drives, forcing costly rip-and-replace scenarios in established industrial facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Alternating Current (AC) Motor Market |
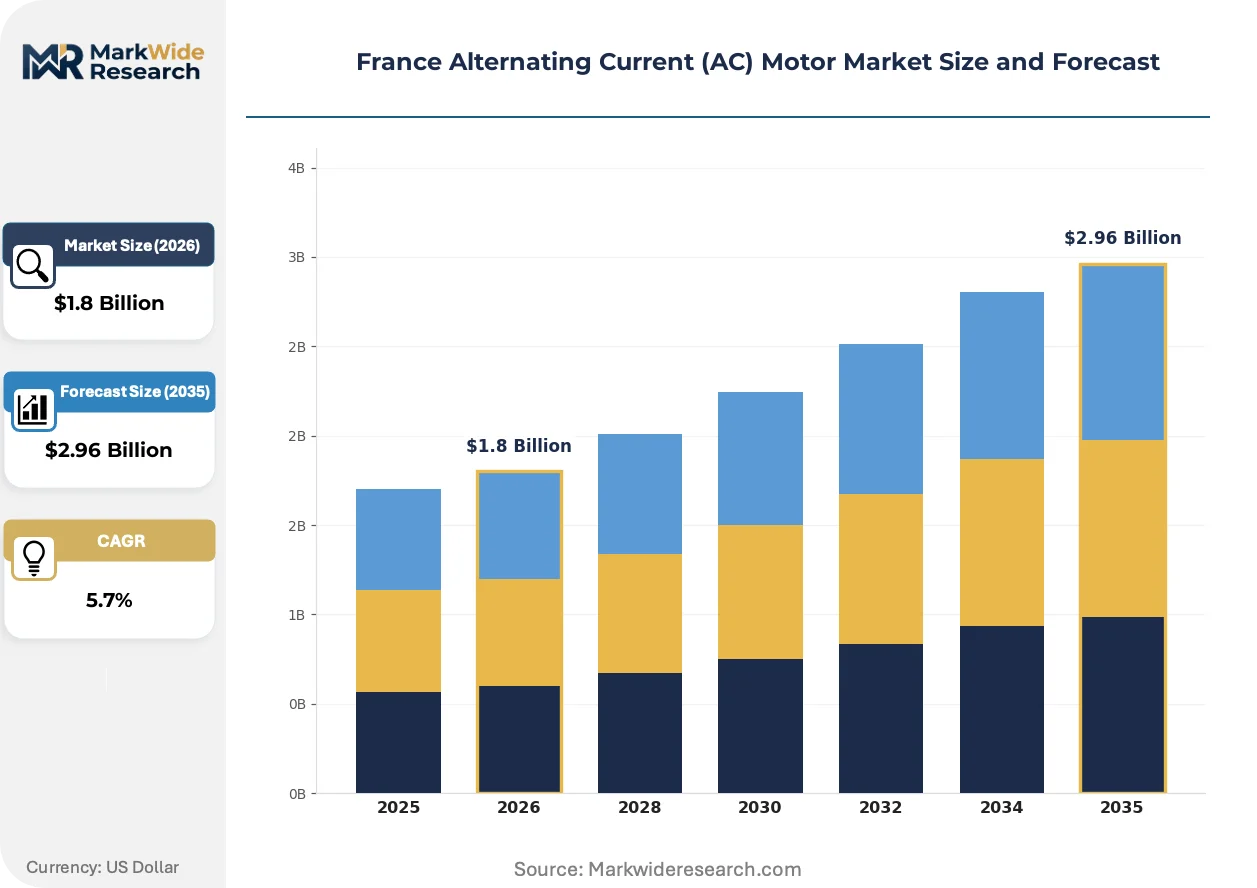
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Induction, Synchronous, Universal, Servo Application: Industrial Machinery, HVAC Systems, Pumps, Fans Power Rating: Fractional HP, 1-5 HP, 5-20 HP, 20+ HP End User: Manufacturing, Agriculture, Transportation, Construction |
| Companies Covered | Siemens AG, ABB Ltd, Rockwell Automation Inc., Nidec Corporation, Johnson Electric, Bosch Group, Danfoss Group, Toshiba Corporation, LG Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Alternating Current (AC) Motor Market Trends and Innovations
Permanent magnet synchronous motor architectures are collapsing the traditional performance gap with induction machines while digital monitoring platforms rewrite aftermarket value capture. Three forces are actively restructuring competitive positioning in French industrial motor supply.
Samarium-cobalt and ferrite-assisted magnet topologies are collapsing the cost-performance tradeoff that historically favored induction motors in mid-power ranges. Automotive suppliers in the Paris-Saclay cluster are adopting these materials at accelerated pace for traction applications. The technology is collapsing induction motor incumbency in 5-50 HP process equipment where efficiency premiums now justify magnet material costs.
The EU Ecodesign Directive's 2025 efficiency tier escalation is mandating IE4 minimums for motors 0.75-375 kW across member states. French industrial buyers face compressed replacement cycles for installed IE2 and IE3 fleets. The regulation most affects pump and compressor OEMs serving water treatment and HVAC verticals, which are now redesigning around permanent magnet and synchronous reluctance platforms.
Buyers in French automotive and aerospace supply chains are consolidating vendor relationships around full-lifecycle service contracts rather than transactional motor purchases. Distributors in the Lyon-Grenoble industrial axis are responding with predictive maintenance subscriptions bundled into equipment financing. This pattern concentrates procurement authority at plant engineering directors who prioritize uptime guarantees over unit capital cost.
France Alternating Current (AC) Motor Market Segmentation
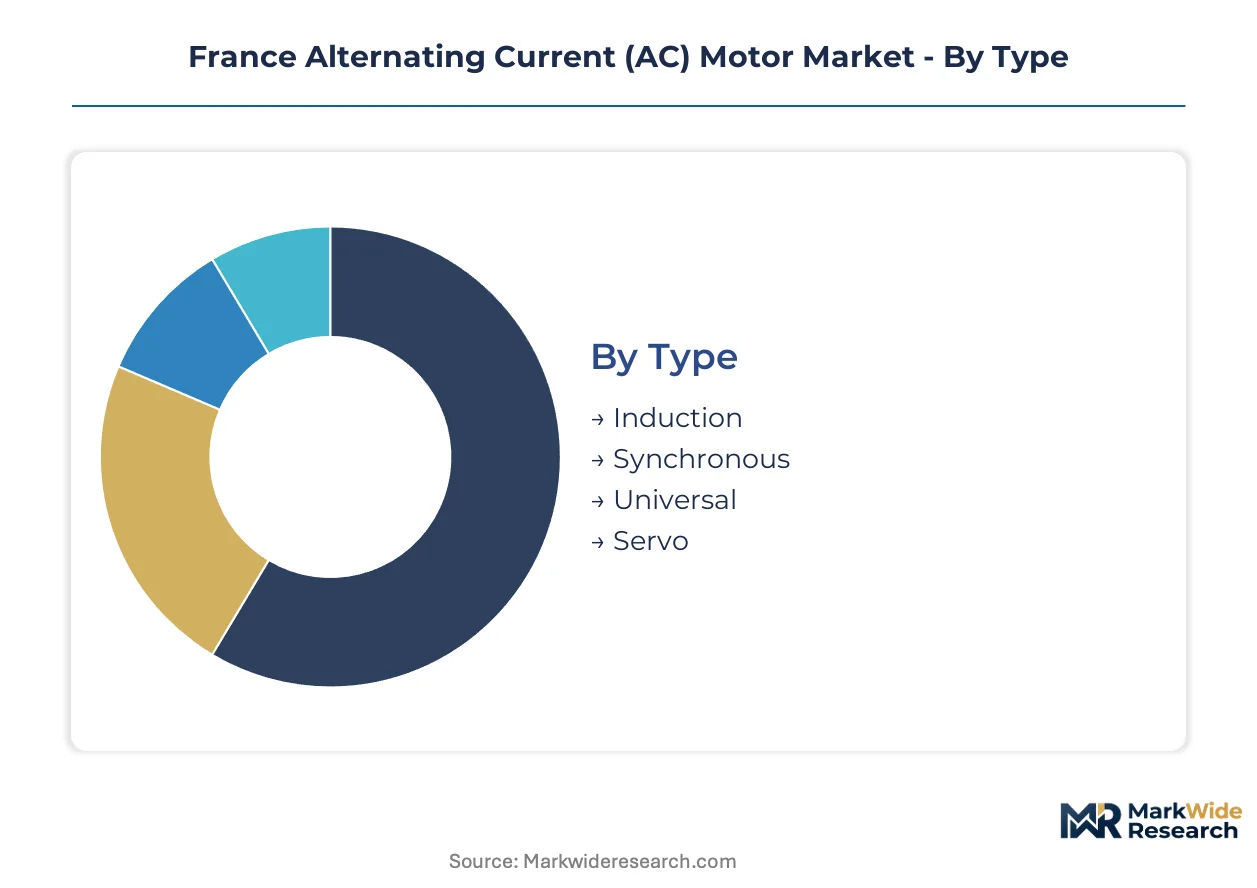
Segmentation in the French AC motor market reveals divergent service intensity patterns across motor architectures. Maintenance complexity and lifecycle support requirements vary dramatically between commodity induction units and precision servo systems, reshaping vendor-customer relationships and margin capture opportunities.
Type:
After-sales-service intensity escalates sharply from basic induction repairs to complex servo recalibration contracts, with synchronous and servo architectures demanding specialized technician networks that only a few suppliers maintain nationwide.
- Induction:Squirrel-cage and wound-rotor designs dominate mature industrial infrastructure across Île-de-France manufacturing corridors. Standardized maintenance protocols and abundant spare parts availability support low-touch service models, though IE4 efficiency upgrades now require drive compatibility assessments.
- Synchronous:Permanent magnet and reluctance variants capture premium positioning in automotive electrification programs around Paris-Saclay. Precision torque control requirements and thermal management complexity drive multi-year service agreements with OEM engineering teams.
- Universal:Series-wound commutator motors serve portable power tools and domestic appliances where cost minimization overrides efficiency concerns. Limited service infrastructure exists given disposable replacement economics.
- Servo:Closed-loop positioning systems with integrated encoders demand factory-authorized calibration networks concentrated around Lyon-Grenoble robotics clusters. Encoder drift correction and drive parameter optimization sustain recurring revenue streams for specialized distributors.
By volume, Induction leads. By growth pace, Servo is ahead.
Application:
Application segmentation maps directly to France's industrial geography, with HVAC concentration in urban building stock and process machinery clustering around chemical and automotive production zones.
- Industrial Machinery:Conveyor systems, presses, and machine tools in Auvergne-Rhône-Alpes manufacturing basins require ruggedized motor architectures with predictive vibration monitoring. The EU Green Deal's binding emissions targets are forcing replacement of legacy IE2 fleets in heavy-process industries.
- HVAC Systems:Chillers, air handlers, and heat pumps across commercial building portfolios in Paris and Marseille metropolitan areas drive seasonal demand spikes. F-Gas Regulation compliance and building energy renovation mandates accelerate variable-speed drive integration.
- Pumps:Water treatment infrastructure and agricultural irrigation networks in Occitania deploy submersible and surface-mounted configurations. Efficiency tier upgrades face capital constraint barriers in municipal procurement cycles.
- Fans:Ventilation and exhaust systems in mining and tunneling operations demand explosion-proof enclosures and high-starting-torque designs. Niche certification requirements limit supplier participation.
Industrial Machinery captures the largest installed base. HVAC Systems show the steepest expansion trajectory driven by building decarbonization mandates.
Power Rating:
Power rating segmentation correlates with customer procurement sophistication, with fractional HP buyers prioritizing first cost and 20+ HP purchasers negotiating total cost of ownership frameworks.
- Fractional HP:Sub-kilowatt motors power domestic appliances and light commercial equipment where standardization enables mass production economics. Appliance OEMs in northern France consolidate volumes around platform motor designs.
- 1-5 HP:Mid-range induction units serve pump and fan OEMs in water treatment and building services verticals. IE3 minimum efficiency regulations now filter non-compliant imports from distribution channels.
- 5-20 HP:Process equipment in food and chemical processing demands enhanced thermal management and bearing longevity. Synchronous reluctance platforms are displacing induction incumbency in this bracket.
- 20+ HP:Heavy-process industries in Île-de-France concentrate value concentration, with permanent magnet synchronous architectures capturing share in compressor and extruder applications. Capital project cycles extend replacement timelines despite efficiency incentives.
Fractional HP units fragment across thousands of appliance installations. The 20+ HP segment commands premium positioning through engineering-intensive sales cycles.
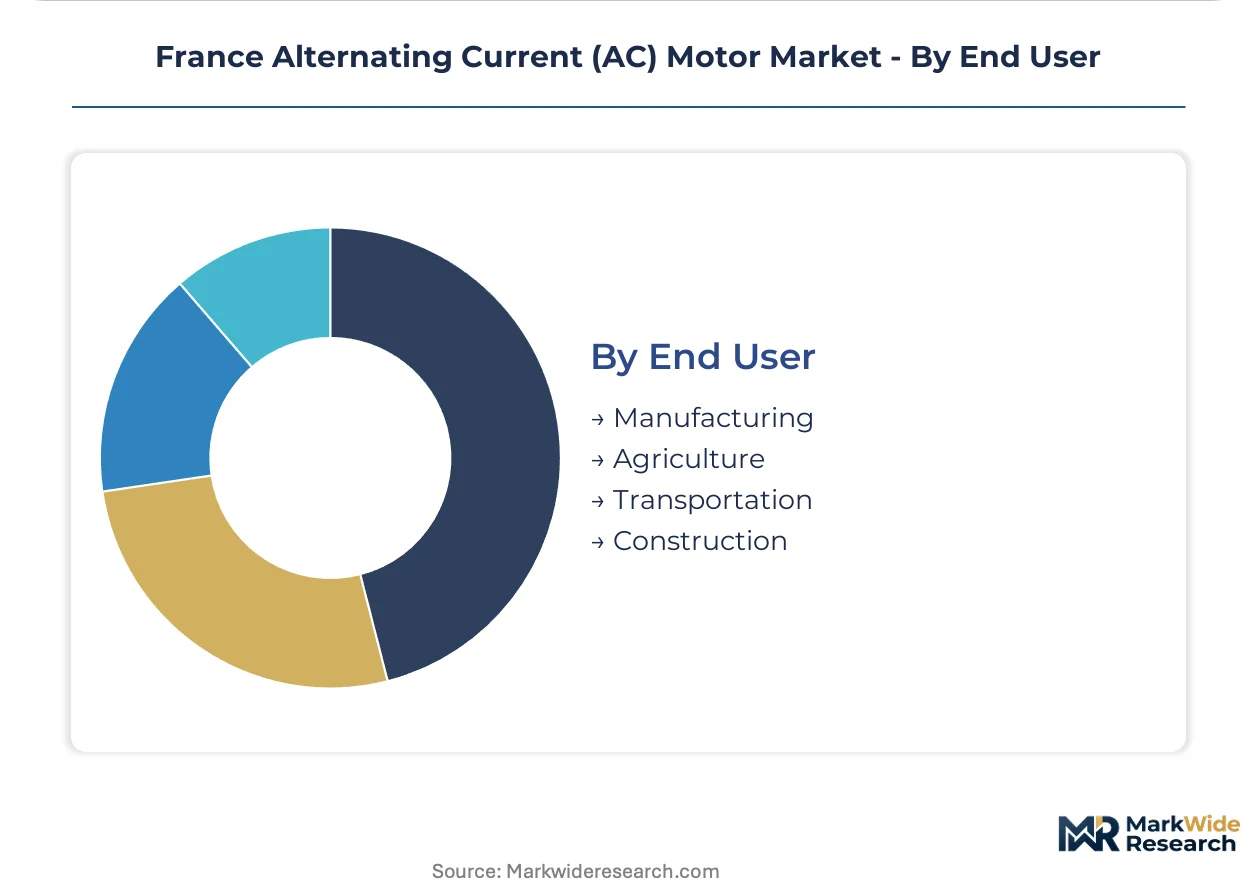
End User:
End user segmentation exposes divergent regulatory exposure and replacement cycle dynamics, with manufacturing and transportation facing the most aggressive efficiency mandates.
- Manufacturing:Automotive, aerospace, and general industrial facilities across Grand Est and Hauts-de-France anchor demand for servo and precision synchronous systems. Reshoring incentives are attracting motor production capacity back to domestic suppliers serving these clusters.
- Agriculture:Irrigation pumps and grain handling equipment in Nouvelle-Aquitaine and Provence-Alpes-Côte d'Azur operate under capital constraints that delay IE3+ upgrades. Cooperative purchasing structures concentrate negotiation leverage.
- Transportation:Railway traction and electric vehicle powertrain programs drive high-torque synchronous motor development in Paris-Saclay automotive electrification corridors. ANSM medical device motor safety requirements add compliance layers for diagnostic equipment motors.
- Construction:Cranes, hoists, and concrete processing equipment demand high-starting-torque wound-rotor designs with severe-duty enclosures. Project-based procurement creates demand lumpiness.
Manufacturing dominates absolute motor consumption. Transportation is climbing the fastest as electrification programs scale production volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across France's AC motor market diverge sharply between industrial heartlands and peripheral zones. Île-de-France concentrates high-specification servo demand from automotive electrification programs, while southern regions lag in efficiency-tier adoption despite substantial installed base.
Île-de-France
Paris-Saclay automotive electrification corridors and Roissy-Charles de Gaulle logistics hubs drive concentrated demand for permanent magnet synchronous traction motors. The EU Ecodesign Directive's 2025 efficiency tier escalation accelerates IE4 motor procurement across compressed air and pump OEMs. Heavy-process industries in the Plaine Saint-Denis industrial zone are retrofitting legacy IE2 fleets ahead of binding decarbonization deadlines.
Auvergne-Rhône-Alpes
Robotics clusters around Lyon and Grenoble sustain premium positioning for closed-loop servo systems with integrated encoder feedback. CE marking harmonization under IEC 60034-30-1 creates compliance bottlenecks for smaller motor importers serving regional machine tool builders. Saint-Étienne's historical manufacturing base is transitioning from commodity induction units to synchronous reluctance platforms for food processing equipment.
Occitanie
Chemical and food processing installations around Toulouse and Montpellier remain below national averages for IE3+ motor penetration, presenting retrofit volume for efficiency upgrade programs. The F-Gas Regulation drives variable-speed drive integration in cold chain infrastructure across the region's agricultural processing sector. Airbus supply chain concentration in Toulouse-Blagnac anchors demand for precision motion control in aerospace component manufacturing.
Hauts-de-France
Reshoring incentives under France's national manufacturing support schemes attract motor production capacity to serve automotive and general industrial facilities across Grand Est-adjacent corridors. The region's steel and materials processing heritage sustains demand for 20+ HP wound-rotor designs in heavy-load applications. Lille's logistics automation sector is adopting integrated motor-drive systems for conveyor and sortation equipment.
Provence-Alpes-Côte d'Azur
Marseille metropolitan area HVAC refurbishment programs accelerate variable-speed compressor motor replacement under building energy renovation mandates. Port infrastructure and maritime service clusters sustain niche demand for severe-duty enclosed motors in corrosive environments. Sophia Antipolis technology park concentrates R&D procurement for high-efficiency motor prototypes in clean energy applications.
France Alternating Current (AC) Motor Market Competitive Landscape
Capability concentration sits with precision servo and integrated drive-motor specialists; scale advantage sits with diversified electromechanical conglomerates serving commodity induction volumes. The vendor base stratifies across three tiers: multinational technology leaders with full-lifecycle service platforms, regional specialists in niche efficiency classes, and price-competitive fabricators focused on fractional HP appliance motors. Dominant competitive moves include strategic partnerships between motor OEMs and power electronics suppliers, plus selective backward integration into magnetic material sourcing.
Within the multinational technology tier, Siemens AG and ABB Ltd exemplify divergent strategic positioning. The German engineering group anchors its French presence through deep integration with domestic automotive OEM powertrain programs. The Swiss-Swedish industrial group sustains technology leadership through digital monitoring platforms embedded across its motor portfolio. Bosch Group occupies a distinct position at the scale-driven end, leveraging dedicated production lines serving both domestic HVAC channels and export machinery markets. These three entities collectively represent the capability-scale spectrum defining competitive dynamics in French industrial motor supply.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd |
| Rockwell Automation Inc. |
| Nidec Corporation |
| Johnson Electric |
| Bosch Group |
| Danfoss Group |
| Toshiba Corporation |
| LG Electronics |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in European rare earth magnet processing facilities is compressing margins for permanent magnet synchronous motor manufacturers while simultaneously elevating pricing power among domestic induction motor producers serving Île-de-France industrial corridors. This utilization asymmetry between magnet-dependent and magnet-free architectures is bifurcating procurement strategies across French automotive and process equipment OEMs.
Pricing Analysis
Long-term offtake agreements dominate procurement for 20+ HP industrial motors serving heavy-process industries, while spot-market transactions govern fractional HP appliance motor volumes. Three-tier pricing structure across premium IE5 servo systems, standard IE4 induction units, and economy IE3 legacy replacements reflects certification-grade differentiation rather than brand positioning alone. Cost compression in mid-power synchronous reluctance platforms is intensifying because samarium-cobalt alternatives are collapsing the traditional induction cost advantage. Municipal water treatment authorities exhibit highest price sensitivity due to capital-constrained procurement cycles, whereas aerospace suppliers around Toulouse-Blagnac prioritize lifecycle cost frameworks over unit acquisition expense.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for French motor manufacturers dependent on neodymium and dysprosium inputs. Magnet raw materials draw primarily from Chinese separation facilities, with secondary processing concentrated in Japan and Germany, while copper windings and electrical steel source from domestic ArcelorMittal mills and German ThyssenKrupp operations. Single-source vulnerability in rare earth oxide supply is forcing ABB and Siemens to qualify alternative ferrite-assisted magnet formulations. Distribution runs through authorized distributor networks in Lyon-Grenoble and direct OEM relationships for automotive electrification programs around Paris-Saclay.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's AC motor market is approaching a platform-economics inflection where integrated motor-drive systems are collapsing the traditional separation between powertrain hardware and control software ecosystems. Interoperability standards emerging from EU Ecodesign Directive harmonization are enabling predictive maintenance platforms to capture recurring revenue streams previously isolated to equipment sales.
For Market Incumbents: Entrench position by deepening backward integration into magnetic material sourcing partnerships with European rare earth processors, insulating against Chinese supply volatility. Accelerate certification investment in IE5 efficiency classes ahead of anticipated EU tier escalations. Channel control through captive service networks in Auvergne-Rhône-Alpes robotics clusters represents the critical defensive lever against emerging integrated-drive specialists.
For New Entrants and Emerging Players: Pursue white-space opportunity in Occitania's underpenetrated chemical processing corridor where IE3+ retrofit cycles lag national averages by several replacement periods. Target municipal water treatment authorities in Nouvelle-Aquitaine with efficiency-as-a-service financing models that bypass capital budget constraints. A go-to-market angle bundling predictive maintenance subscriptions with equipment leasing addresses procurement authority concentration at plant engineering directors.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among servo motor specialists with factory-authorized calibration networks concentrated around Lyon-Grenoble. Long-term viability over the coming decade hinges on exposure to automotive electrification programs and industrial decarbonization mandates rather than commodity induction volumes. Acquisition targets should demonstrate captive relationships with Paris-Saclay automotive OEMs or Airbus supply chain certification. The signal to monitor is carbon border adjustment mechanism implementation tightening, which would structurally advantage domestic and near-EU component suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnetic Materials | Captive rare earth supply insulates Siemens and ABB against Chinese price volatility and export restriction risk. |
| Integrated Motor-Drive Platform Development | Combining variable frequency drives with permanent magnet machines captures premium positioning in robotics and CNC equipment. |
| IE5 Efficiency Certification Investment | Early compliance with anticipated EU Ecodesign tier escalations locks out non-compliant imports from distribution channels. |
| Predictive Maintenance Service Launch | Subscriptions bundled into equipment financing concentrate procurement authority at uptime-focused plant engineering directors. |
| Occitania Regional Expansion | Chemical and food processing clusters around Toulouse present retrofit volume below national IE3+ penetration averages. |
Research Methodology
Cross-validation between primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and distribution channel partners anchors the qualitative findings in operational reality. Secondary validation draws from EU Ecodesign Directive filings, ANSM medical device registration databases, SEC 10-K disclosures of listed motor manufacturers, and French customs trade data on magnetic material imports. Bottom-up motor shipment estimates by power rating and architecture triangulate against top-down industrial production indices for automotive, aerospace, and process equipment verticals.
Calibration against historical efficiency regulation adoption curves and automotive electrification program timelines shapes the projection framework across the analysis window. Segmentation dimensions modeled include motor type, power rating tier, end-use application, and regional industrial cluster. CAGRs derive from regression analysis of replacement cycle compression under binding decarbonization targets and reshoring incentive uptake rates. Industry-specific inputs incorporate rare earth magnet price elasticity coefficients and IE4/IE5 motor penetration trajectories in comparable EU member states.
Sensitivities concentrate around carbon border adjustment implementation timing, rare earth supply disruption scenarios, and automotive OEM powertrain platform standardization decisions. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and industrial capital expenditure recovery patterns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Global Two Wheeler Hub Motor Market
Electric Motor
Vibrator Motor Market
Electric Motor
Global Electric Motors for Electric Vehicle Market
Electric Motor
Intelligent Motor Control Market
Electric Motor
Global Automotive Heating Fan Motor Market
Electric Motor
EV Traction Motor Control Unit Market
Electric Motor
High Speed Motor Market
Electric Motor
Automotive Electric Commutators Market
Electric Motor
Motor Gear Unit Market
Electric Motor
Automotive Electric Motors Market
Electric Motor
Garden Tool Lithium Battery Market
Electric Motor
United States AC Motor Market
Electric Motor
Torque Motor Market
Electric Motor
Automotive Traction Motor Market
Electric Motor
Global Vehicle Starter Motor Market
Electric Motor
Global Electric Motor Market