
 Two Wheeler Electric Starter Magnet Market | 2026-2036
Two Wheeler Electric Starter Magnet Market Size, Share, and Industry Trends Forecast 2026-2036
Two Wheeler Electric Starter Magnet Market Analytics
Motorcycle electrification is shifting the buyer composition toward OEMs with electrification roadmaps. Denso Corporation leverages its integrated motor-starter architecture to capture premium motorcycle platform contracts. Bosch Group sustains scale advantages through automated ferrite magnet winding lines serving European scooter manufacturers. Mitsubishi Electric Corporation anchors its position in Japanese kei-class two-wheeler electrification programs.
Two wheeler electric starter magnets are compact rare-earth or ferrite-based magnetic assemblies, typically rated for 12V systems with pull-in torque between 0.8 Nm and 2.5 Nm, that convert electrical current into rotational force for internal combustion engine cranking. Permanent magnet starter configurations dominate volume production for motorcycles and scooters due to lower part count and reduced maintenance, while hybrid starter designs are gaining share in stop-start equipped commuter bikes where torque density requirements exceed conventional electromagnetic limits. Electromagnetic variants retain aftermarket relevance for legacy repair shops servicing carbureted two-wheeler fleets across South Asia and Southeast Asia.
India's BIS mandates starter motor efficiency labeling under automotive component standards, while China's GB standards govern neodymium content disclosure in exported magnet assemblies. The EU F-Gas Regulation indirectly pressures starter magnet thermal tolerance specifications as refrigerant transitions alter under-seat thermal profiles in scooter architectures. Stakeholders must monitor rare-earth export licensing shifts and decide between ferrite cost stability versus neodymium performance premiums before platform commitments lock in.
Market Dynamics
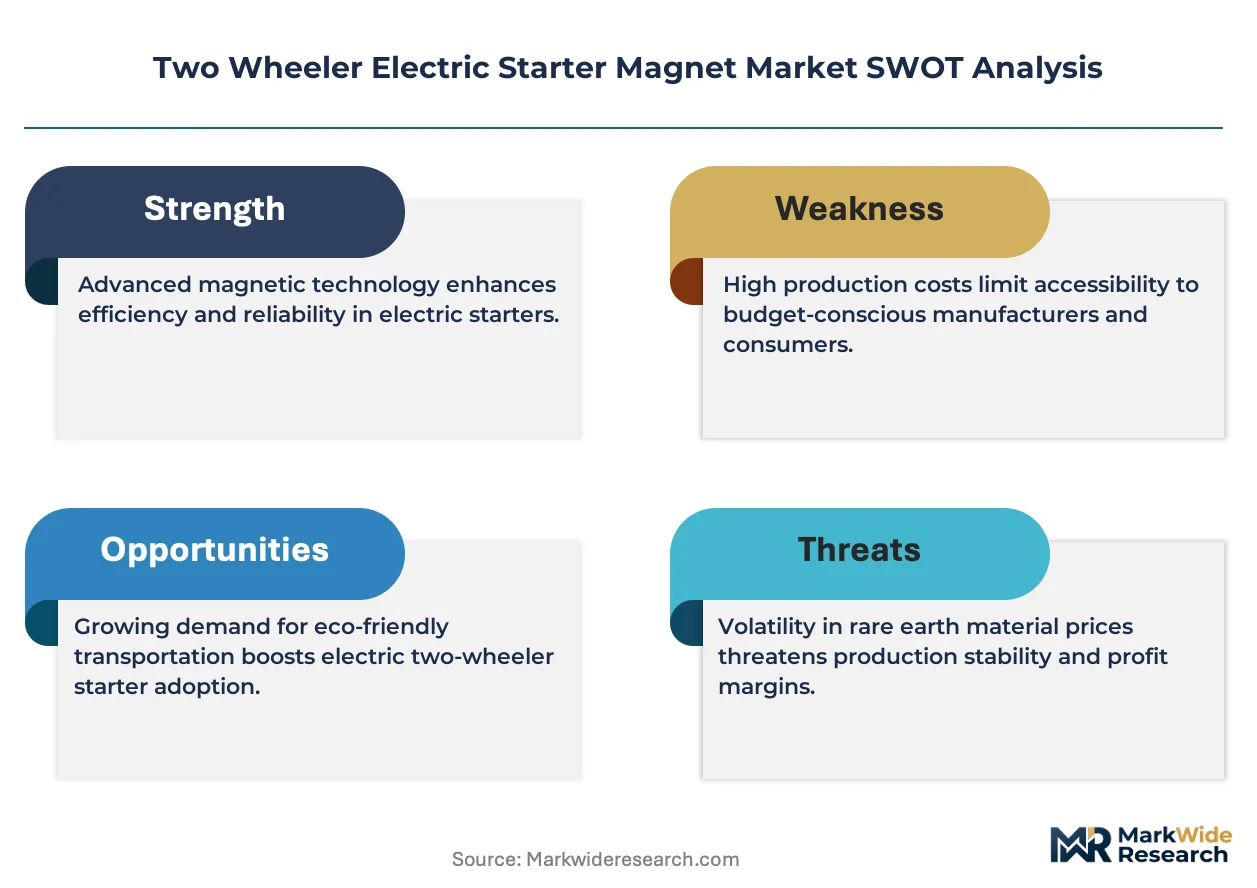
Rare-earth processing concentration in China is forcing motorcycle OEMs to redesign starter magnet specifications around dual-sourcing ferrite alternatives, compressing neodymium dependency timelines before electrification mandates lock in platform architectures.
Growth Catalysts
- India's BIS efficiency labeling mandate:Motorcycle manufacturers must now certify starter motor performance tiers, accelerating OEM demand for magnet assemblies that meet stricter pull-in torque thresholds.
- Stop-start commuter bike proliferation:Hybrid starter configurations are penetrating 125cc-150cc scooter segments as torque density requirements exceed conventional electromagnetic limits.
- Vietnam aftermarket fleet expansion:Carbureted two-wheeler density in Ho Chi Minh City and Hanoi corridors sustains replacement demand for electromagnetic starter variants.
Market Restraints
- Neodymium oxide price volatility:China's export licensing fluctuations for rare-earth concentrates inject margin uncertainty into permanent magnet starter production.
- Ferrite magnet torque ceiling:Sintered ferrite assemblies cannot achieve the 2.0+ Nm pull-in thresholds required for larger displacement motorcycle engines.
- EU F-Gas thermal tolerance cascade:Refrigerant transitions in scooter under-seat compartments force magnet insulation upgrades without commensurate pricing power.
Strategic Opportunities
- Indonesia's 2040 electrification roadmap:Archipelago logistics constraints favor compact starter-motor integration with hub-mounted electric drive units.
- Integrated motor-starter architectures:Convergence of cranking and generation functions into single magnet assemblies reduces part count for premium motorcycle platforms.
- Thailand BOI incentive alignment:Board of Investment tax privileges for EV component manufacturing attract magnet winding facility investment.
Industry Challenges
- Rare-earth metallurgist scarcity:Neodymium-iron-boron sintering expertise concentrates in Chinese and Japanese supplier bases, constraining geographic diversification.
- GB standards compliance timeline:China's mandatory neodymium content disclosure for exported magnet assemblies extends certification cycles by 8-14 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Two Wheeler Electric Starter Magnet Market |
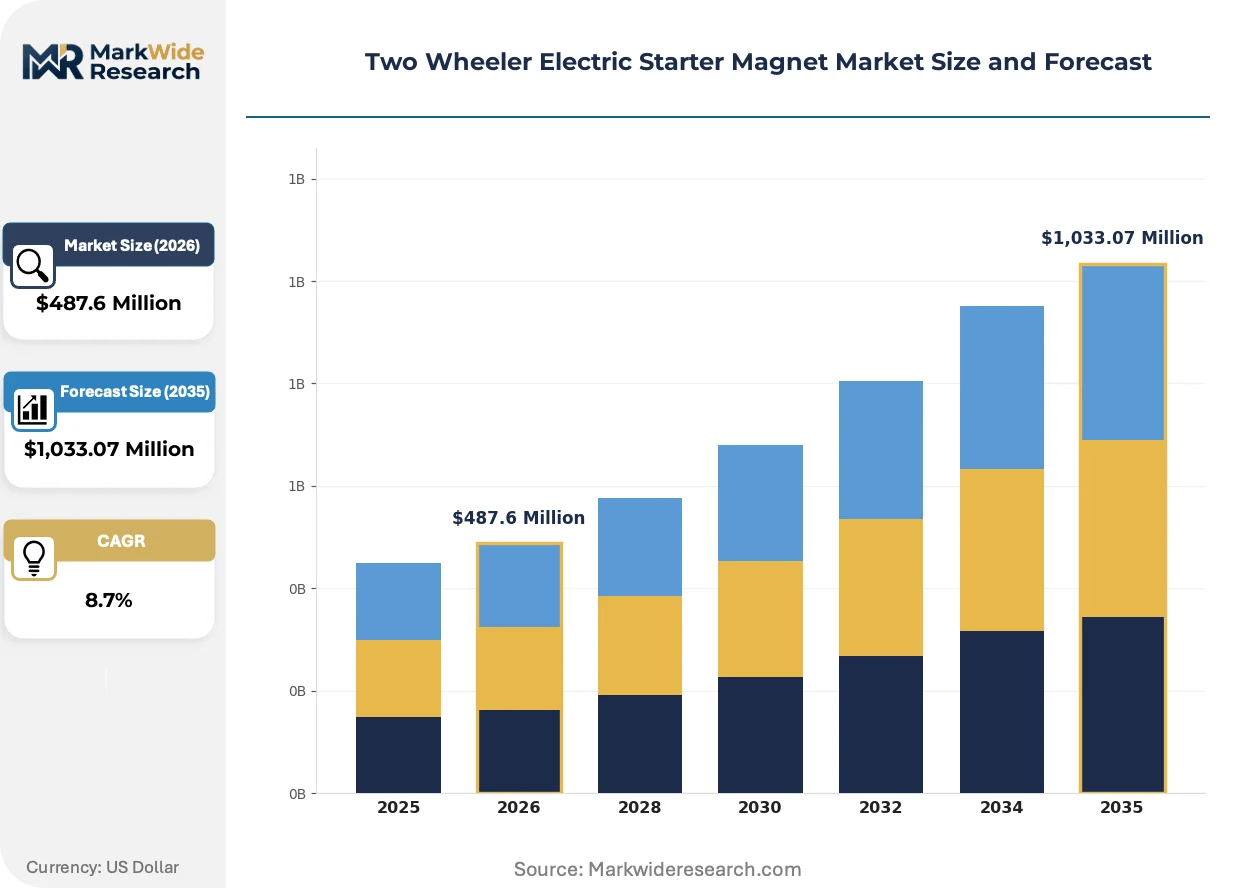
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Permanent Magnet, Electromagnetic, Hybrid Starter, Custom Solutions Distribution Channel: Direct Sales, Wholesalers, E-Commerce, Retail Stores End User: OEMs, Aftermarket Providers, Dealers, Repair Shops Application: Motorcycles, Scooters, ATVs, E-Bikes |
| Companies Covered | Denso Corporation, Bosch Group, Mitsubishi Electric Corporation, Mitsuba Corporation, Hitachi Astemo, Valeo, Lucas TVS, BorgWarner Inc., Prestolite Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Two Wheeler Electric Starter Magnet Market Evolving Landscape
Magnet material science and thermal management engineering are converging to redefine starter motor performance benchmarks, with OEMs now specifying magnet assemblies against combined electrical-mechanical stress profiles rather than isolated torque metrics.
Bonded neodymium injection molding is rewriting cost-performance tradeoffs for mid-displacement motorcycle platforms. Indonesian and Thai scooter manufacturers are adopting these magnets at 15-20% lower assembly cost than sintered alternatives. The technology is compressing the historical ferrite-neodymium price gap while maintaining torque density adequate for 110cc-125cc engine cranking cycles.
China's GB standards for rare-earth content disclosure are tightening traceability requirements across exported magnet assemblies. Motorcycle OEMs must now document supply chain provenance through smelter and separator stages. European scooter manufacturers are responding by qualifying secondary ferrite suppliers in India and Vietnam to reduce documentation burden.
Aftermarket procurement is fragmenting toward specialized e-commerce channels serving independent repair shops. Vietnamese and Bangladeshi distributors are bypassing traditional tiered supply structures to source electromagnetic starter variants directly from Chinese winding facilities. This channel compression is most visible in Dhaka and Chittagong, where carbureted fleet density sustains legacy starter repair volumes despite OEM electrification roadmaps.
Two Wheeler Electric Starter Magnet Market Segmentation
Starter magnet procurement patterns diverge sharply between OEM platform engineering and aftermarket repair economics. Material selection, torque specifications, and supply chain traceability requirements reshape segment boundaries as electrification mandates tighten across Asia.
Product Type:
Supply concentration in Chinese neodymium processing forces motorcycle OEMs to qualify dual-source magnet architectures before platform lock-in.
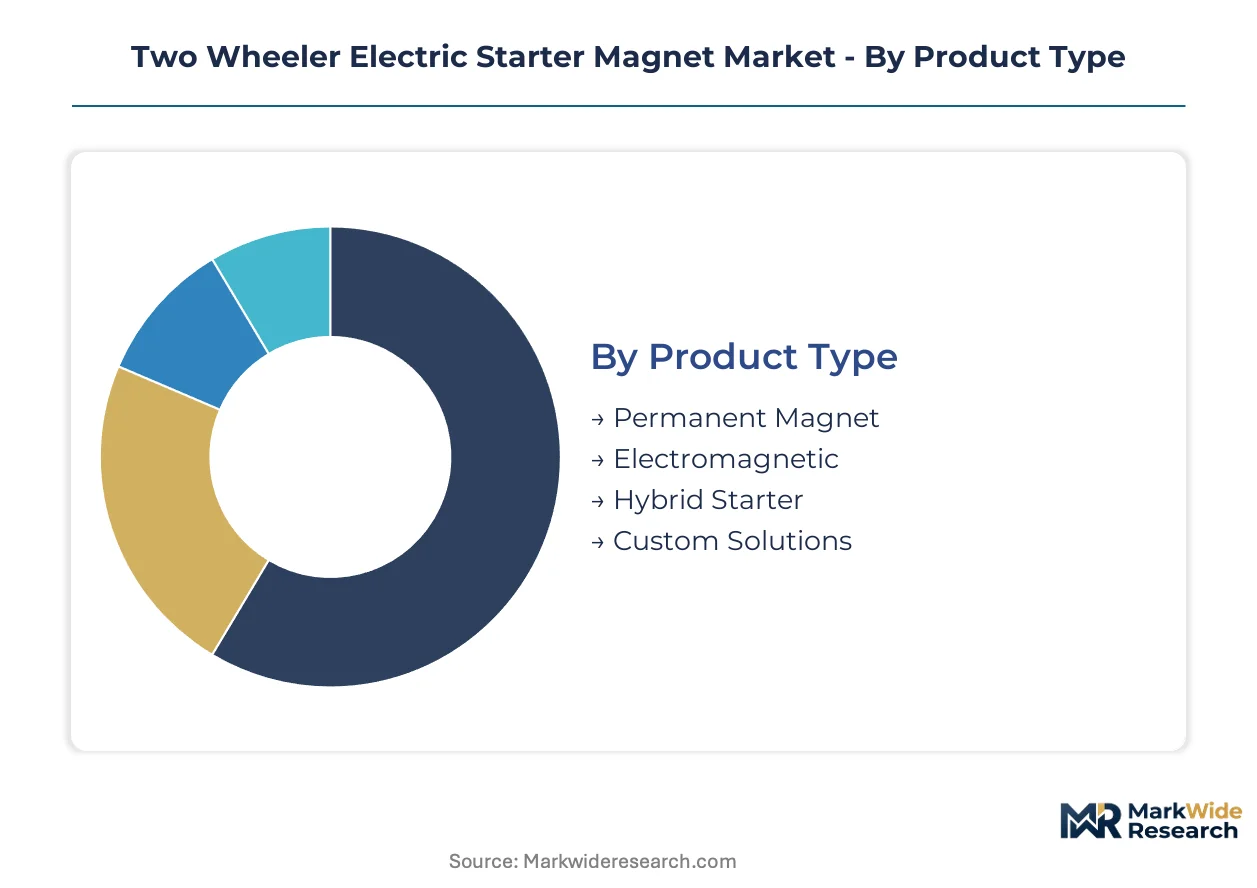
- Permanent Magnet:Rare-earth or ferrite-based assemblies with fixed magnetic fields eliminate field coil windings, reducing part count for high-volume scooter production. Denso Corporation and Bosch Group anchor procurement for Japanese and European OEM platforms requiring 0.8-2.5 Nm pull-in torque ranges. India's BIS efficiency labeling mandates favor permanent magnet configurations for 110cc-150cc commuter segments where certification thresholds are tightening.
- Electromagnetic:Field coil designs using copper windings and soft iron cores retain magnetic flexibility across variable voltage conditions. Carbureted fleet density in Vietnam and Bangladesh sustains replacement demand through specialized e-commerce channels serving independent repair shops. These variants tolerate voltage fluctuation in aging electrical systems common across South Asian aftermarket corridors.
- Hybrid Starter:Combines permanent magnet torque density with electromagnetic control precision for stop-start commuter bikes. Mitsubishi Electric Corporation supplies Japanese kei-class electrification programs where thermal cycling demands exceed conventional limits.
- Custom Solutions:Application-specific magnet geometries for integrated motor-starter architectures in premium motorcycle platforms. Hub-mounted electric drive integration in Indonesia favors compact custom assemblies.
Permanent magnet configurations absorb the bulk of installed capacity; hybrid starter designs are expanding most quickly as stop-start mandates penetrate 125cc-150cc segments.
Distribution Channel:
Channel economics fragment along OEM direct procurement versus aftermarket repair urgency, with digital platforms compressing traditional tiered structures.
- Direct Sales:Long-term supply agreements between magnet winders and motorcycle OEMs lock in volume commitments before platform development cycles. China's GB standards compliance extends certification timelines, favoring direct relationships with documented smelter provenance.
- Wholesalers:Regional distributors aggregate demand across multiple OEM service networks and independent repair chains. Thailand's Board of Investment incentives attract magnet winding facility investment serving ASEAN wholesale corridors.
- E-Commerce:Specialized platforms bypass traditional tiers to connect Vietnamese and Bangladeshi repair shops directly with Chinese winding facilities. Dhaka and Chittagong carbureted fleet density sustains legacy starter volumes through compressed procurement channels.
- Retail Stores:Counter sales serve emergency replacement needs for commuter bike operators in Ho Chi Minh City and Hanoi corridors where downtime carries income loss.
Direct sales channels capture OEM platform volume; e-commerce routes are gaining share fastest in aftermarket fragmentation.
End User:
Buyer composition shifts toward OEMs with electrification roadmaps as aftermarket repair economics face platform obsolescence pressure.
- OEMs:Motorcycle manufacturers specify magnet assemblies against combined electrical-mechanical stress profiles rather than isolated torque metrics. Integrated motor-starter architectures reduce part count for premium platforms.
- Aftermarket Providers:Independent distributors stock electromagnetic variants for legacy carbureted fleets across South Asia. Inventory management balances declining repair volumes against electrification transition timelines.
- Dealers:Authorized service networks source OEM-certified magnet assemblies for warranty-compliant repairs. India's BIS efficiency labeling mandates documentation through dealer channels.
- Repair Shops:Independent mechanics in Vietnamese and Bangladeshi urban corridors source electromagnetic starters through e-commerce platforms. Technical expertise concentrates on carbureted system diagnostics as electrification skills lag.
OEMs command the largest procurement volumes; repair shops are fragmenting fastest toward direct digital sourcing.
Application:
Vehicle architecture determines magnet thermal tolerance specifications and torque density requirements across displacement categories.
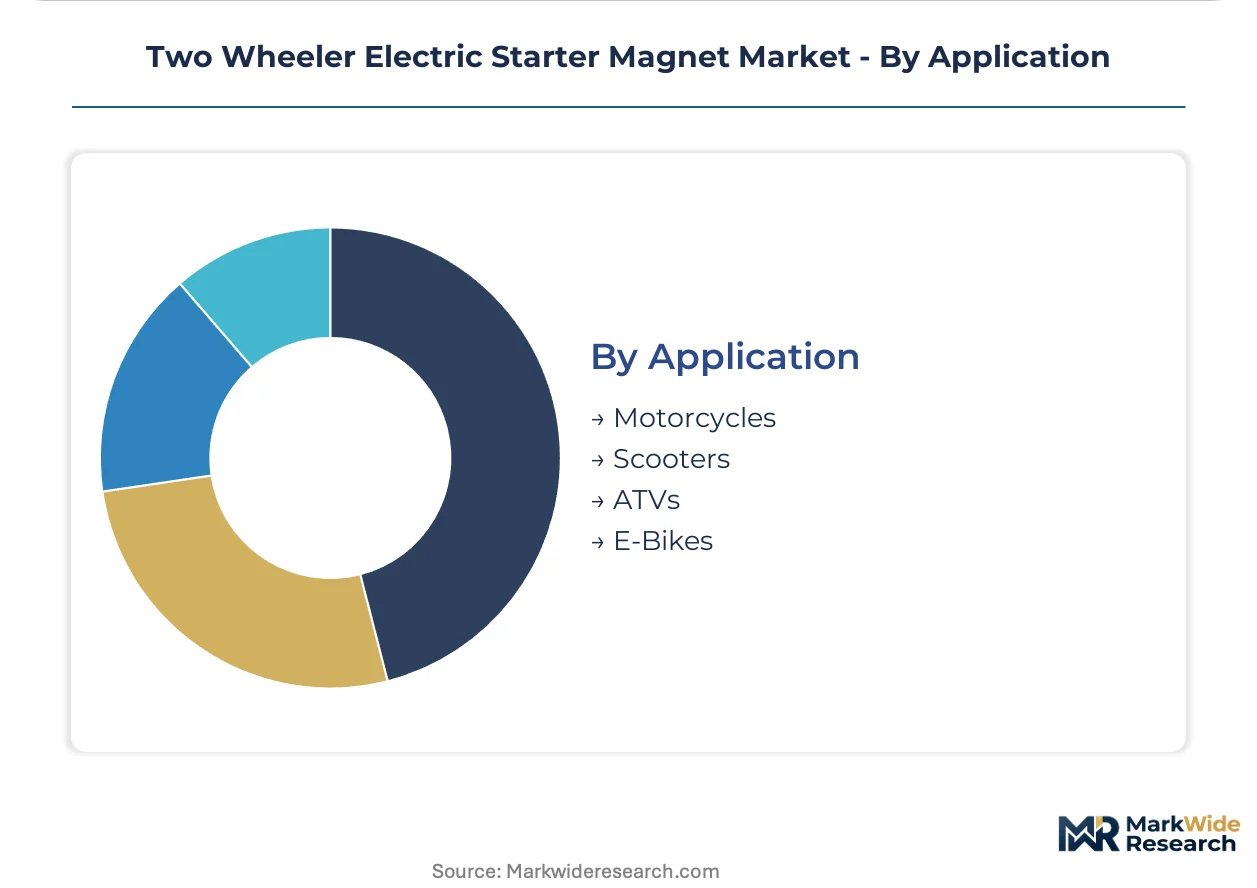
- Motorcycles:Larger displacement engines demand 2.0+ Nm pull-in thresholds that sintered ferrite assemblies cannot achieve, forcing neodymium dependency or hybrid configurations. EU F-Gas refrigerant transitions alter under-seat thermal profiles in scooter architectures, forcing insulation upgrades.
- Scooters:110cc-125cc segments adopt bonded neodymium injection molding at 15-20% lower assembly cost than sintered alternatives. Indonesian and Thai manufacturers compress the historical ferrite-neodymium price gap while maintaining adequate cranking torque.
- ATVs:Off-road duty cycles expose magnet assemblies to vibration and contamination loads requiring sealed housing designs. Aftermarket replacement demand concentrates in North American and Australian recreational vehicle markets.
- E-Bikes:Hub motor integration eliminates separate starter functions, displacing traditional magnet assemblies in pure electric platforms. Indonesia's 2040 electrification roadmap favors compact starter-motor integration with hub-mounted drive units for hybrid architectures.
Motorcycle applications dominate current procurement scale; e-bike electrification is displacing starter magnet demand fastest in pure electric transition zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's Board of Investment tax privileges attract magnet winding facility investment serving ASEAN supply corridors, concentrating production capacity near Bangkok and the Eastern Economic Corridor.
China
Neodymium processing dominance in Jiangxi and Inner Mongolia forces motorcycle OEMs to redesign starter magnet specifications around dual-sourcing timelines. GB standards mandate rare-earth content disclosure for exported magnet assemblies, extending certification cycles. Suzhou and Ningbo industrial clusters host sintering facilities supplying Denso Corporation and Bosch Group procurement networks.
India
BIS efficiency labeling mandates accelerate OEM demand for magnet assemblies meeting stricter pull-in torque thresholds in 110cc-150cc commuter segments. The PLI scheme for automotive components incentivizes domestic magnet winding capacity expansion. Chennai and Pune manufacturing corridors concentrate Denso Corporation and Lucas TVS production facilities serving Hero MotoCorp and TVS Motor platform contracts.
Vietnam
Carbureted two-wheeler density in Ho Chi Minh City and Hanoi corridors sustains replacement demand for electromagnetic starter variants through compressed e-commerce procurement channels. The country's national automotive regulator enforces component safety standards aligning with ASEAN harmonized regulations. Da Nang and Hai Phong logistics hubs facilitate direct sourcing from Chinese winding facilities bypassing traditional tiered distributors.
Indonesia
Archipelago logistics constraints under the 2040 electrification roadmap favor compact starter-motor integration with hub-mounted electric drive units. Ministry of Industry regulations promote local content requirements for EV component manufacturing. Bekasi and Karawang industrial zones concentrate scooter assembly operations adopting bonded neodymium injection molding at lower assembly cost than sintered alternatives.
Japan
Kei-class two-wheeler electrification programs anchor Mitsubishi Electric Corporation supply positions for hybrid starter configurations. METI carbon neutrality roadmaps tighten thermal tolerance specifications for magnet assemblies. Hamamatsu and Yokohama precision manufacturing clusters specialize in custom magnet geometries for integrated motor-starter architectures in premium motorcycle platforms.
Two Wheeler Electric Starter Magnet Market Competitive Landscape
Top-tier vendors anchor integrated motor-starter architectures, while mid-scale specialists occupy ferrite and bonded neodymium niches. The vendor base separates into three functional tiers: multinational Tier-1s with OEM platform engineering relationships, regional magnet winders serving aftermarket procurement, and material-science specialists advancing injection-molding processes. Dominant competitive moves include backward integration into rare-earth sourcing and strategic partnerships for dual-source ferrite qualification.
Among Japanese Tier-1 suppliers, Denso Corporation, Mitsubishi Electric Corporation, and Hitachi Astemo exemplify the integrated-systems archetype. Denso Corporation represents the consolidated motor-starter architecture approach. Mitsubishi Electric Corporation occupies a position within kei-class electrification program supply. Hitachi Astemo sits within the premium motorcycle platform tier. Bosch Group, Valeo, and BorgWarner Inc. anchor European and North American OEM relationships. Lucas TVS exemplifies regional aftermarket specialization. Mitsuba Corporation and Prestolite Electric represent mid-scale electromagnetic variant production.
| Leading Market Players |
|---|
| Denso Corporation |
| Bosch Group |
| Mitsubishi Electric Corporation |
| Mitsuba Corporation |
| Hitachi Astemo |
| Valeo |
| Lucas TVS |
| BorgWarner Inc. |
| Prestolite Electric |
| Others |
Value Network & Pricing Analysis
Neodymium oxide spot pricing cascades through three downstream tiers before reaching motorcycle OEM procurement desks. Chinese export licensing fluctuations inject volatility into permanent magnet starter assemblies, compressing margins for suppliers locked into long-term platform contracts while rewarding spot-market players with inventory flexibility.
Pricing Analysis
Short lead-time premiums of 15-25% apply to bonded neodymium injection molding orders under 8-week delivery windows. Pricing stratifies across sintered neodymium, bonded neodymium, and ferrite magnet tiers, with certification grade under India's BIS efficiency labeling and China's GB standards disclosure requirements driving 12-18% spreads within each material class. Cost compression in ferrite alternatives is intensifying because Indonesian and Thai scooter manufacturers are qualifying dual-source specifications ahead of platform lock-in. Aftermarket repair shops through Vietnamese e-commerce channels exhibit highest price sensitivity, while Japanese kei-class OEMs demonstrate lowest sensitivity due to integrated motor-starter architecture premiums.
Supply Chain Analysis
Single-source vulnerability sits with Chinese neodymium processing concentration in Jiangxi and Inner Mongolia provinces. Raw material flows draw from Australian rare-earth concentrates, Chinese separation facilities, and Japanese sintering expertise for high-performance grades. Tariff exposure on exported magnet assemblies extends certification cycles and inflates landed costs for European scooter manufacturers. Distribution runs through Bangkok-based winding facilities serving ASEAN wholesale corridors, with direct e-commerce channels compressing traditional tiered structures in Vietnamese and Bangladeshi aftermarket zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over neodymium sourcing or ferrite qualification timelines determines platform contract viability. Players are pursuing backward integration into rare-earth supply chains to defend margin positions against Chinese export licensing volatility.
For Market Incumbents: Extend dual-source ferrite qualification programs before electrification mandates lock in permanent magnet architectures. Denso Corporation and Bosch Group should deepen captive supply of bonded neodymium injection molding capacity to offset sintered rare-earth dependency. India's PLI scheme for automotive components offers a channel to anchor domestic winding facilities ahead of BIS efficiency tier tightening. For New Entrants and Emerging Players: Begin with bonded neodymium injection molding supply to Indonesian and Thai scooter manufacturers where assembly cost advantages of 15-20% against sintered alternatives create immediate procurement traction. Target aftermarket electromagnetic starter variants through specialized e-commerce platforms serving Dhaka and Chittagong carbureted fleet corridors. A direct-sourcing go-to-market angle bypassing traditional tiered distributors captures repair shop loyalty through compressed lead times. For Investors and Strategic Acquirers: China's GB standards compliance timeline extension is the leading indicator that documentation-heavy export-oriented suppliers will face working capital strain. Long-term viability favors mid-scale magnet winders with proven dual-source qualification capabilities across ferrite and bonded neodymium technologies. Acquisition targets should demonstrate established relationships with Indian PLI beneficiaries or Thai BOI incentive recipients. The signal to watch is Indonesian Ministry of Industry local content requirement enforcement for EV component manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Source Ferrite Qualification | Reduces neodymium dependency exposure before platform architecture lock-in across ASEAN OEM platforms. |
| Bonded Neodymium Injection Molding Scale-Up | Captures Indonesian and Thai scooter manufacturer procurement through 15-20% assembly cost advantage. |
| Integrated Motor-Starter Architecture Development | Consolidates Denso Corporation and Mitsubishi Electric Corporation positions in Japanese kei-class electrification programs. |
| E-Commerce Channel Direct Sourcing | Compresses procurement tiers for Vietnamese and Bangladeshi aftermarket electromagnetic starter demand. |
| Thailand BOI Magnet Winding Facility Investment | Positions production capacity within ASEAN supply corridors serving India BIS-mandated efficiency tier growth. |
Research Methodology
Trade databases, automotive component customs records, and rare-earth export licensing filings formed the secondary backbone for supply-side calibration. Primary interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributor operations heads, and magnet winding facility technical directors combined with secondary validation to triangulate demand patterns. Bottom-up assessment of individual motorcycle and scooter platform magnet content requirements reconciled against top-down rare-earth processing capacity estimates.
Bottom-up modeling of platform-specific magnet specifications across displacement categories and thermal tolerance requirements anchored volume projections over the analysis window. Segmentation dimensions included product type, distribution channel, end user archetype, and application category with regional regulatory cluster overlays. CAGRs derived from fitted growth curves applied to base-year installed capacity estimates, incorporating stop-start penetration rates and electrification transition timelines as motorcycle-specific forecast inputs.
Underlying measurement precision varies by segment; OEM direct sales channels carry tighter precision than fragmented aftermarket e-commerce estimates. Forecasts reflect assumptions around Chinese export licensing stability, Indian BIS enforcement timelines, and Indonesian electrification roadmap adherence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Motor
Global Electric Motor Market
Electric Motor
Automotive Heater Fan Motor Market
Electric Motor
Electric Vehicle Traction Motor Core Market
Electric Motor
APAC Electric Drives Market
Electric Motor
Automotive Power Steering Motor Market
Electric Motor
Motorcycle Lead Acid Battery Market
Electric Motor
Traction Motors Market
Electric Motor
Automotive Wiper Motor Market
Electric Motor
Automotive Torque Actuator Motor Market
Electric Motor
High Speed Motor Market
Electric Motor
EV Traction Motor Market
Electric Motor
Automotive Seat Motor Market
Electric Motor
Global Automotive Odometer Stepping Motor Market
Electric Motor
Intelligent Motor Control Market
Electric Motor
Voice Coil Motor Market
Electric Motor
UK Solar E-Bike Market