
 Latin America Mobile Gaming Market | 2026-2036
Latin America Mobile Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Mobile Gaming Market Foresight
Young adult casual players is reorganizing the Latin America mobile gaming revenue mix as this cohort surpasses teen engagement in session frequency and in-app purchase conversion. Tapps Games leverages hyper-casual production pipelines to dominate Brazil's free-to-play charts with rapid prototyping cycles. HyperBeard, Inc. sustains genre loyalty through narrative-driven simulation titles that anchor female-skewing demographics across Mexico and Chile. Activision Publishing, Inc. competes on brand equity by extending Call of Duty Mobile's esports infrastructure into São Paulo and Buenos Aires server clusters.
Latin America mobile gaming encompasses interactive entertainment software distributed through native application stores and cloud-streaming layers, optimized for ARM-based chipsets and touch-interface input with sub-50ms latency thresholds for real-time multiplayer synchronization. The primary commercial purpose centers on monetizing attention through frictionless micro-transaction architectures integrated with regional digital wallets and carrier billing. Android occupies the structural core due to its 85%-plus device share across the region, though iOS commands disproportionate average revenue per user in metropolitan Brazil and Mexico City. Ad-supported monetization leads volume metrics while in-app purchases concentrate margin pools among strategy and simulation genres where progression mechanics incentivize repeat spending.
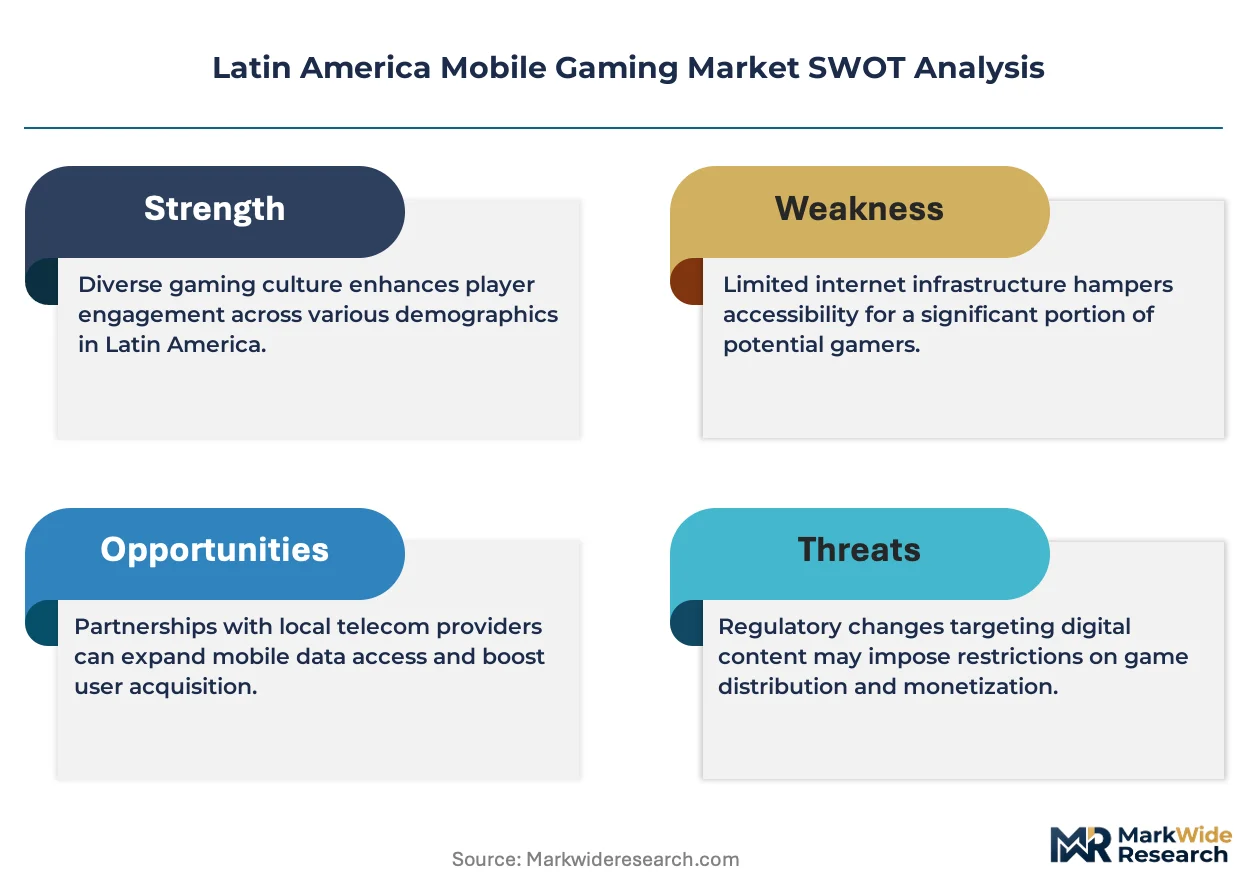
Brazil's ANATEL enforces content rating protocols through its juvenile protection framework, while Mexico's COFEPRIS extends consumer protection standards to digital goods transactions including refund eligibility for minors. GDPR-aligned privacy legislation emerging across Argentina and Chile is forcing publishers to restructure first-party data collection and consent management for targeted advertising. Stakeholders must monitor how regional data-localization mandates and app-store fee disputes reshape distribution economics and developer net revenue retention.
Market Dynamics
ANATEL's 5G spectrum auctions in Brazil have compressed latency thresholds below 30 milliseconds, enabling real-time multiplayer synchronization that was previously impossible on 4G infrastructure. This technical inflection is restructuring monetization mechanics as fintech-wallet integrations penetrate Android ecosystems across São Paulo and Mexico City.
Growth Catalysts
- 5G Infrastructure Deployment:ANATEL's spectrum reforms and tower-sharing mandates in Brazil are expanding addressable audiences for synchronous multiplayer titles. Urban corridors in São Paulo and Rio de Janeiro now support sub-20ms latency thresholds.
- Fintech-Wallet Integration:PIX instant-payment rails and OXXO cash-to-digital conversion networks are reducing friction in micro-transaction flows. Mexico's unbanked population is accessing in-app purchases through carrier billing.
- Hyper-Casual Production Pipelines:Rapid prototyping cycles measured in weeks are flooding free-to-play charts with low-CPI acquisition titles. Brazilian studios are compressing development costs through asset-marketplace reuse.
Market Restraints
- Device Fragmentation Costs:Android's 85%-plus share spans chipsets from MediaTek Helio to Qualcomm Snapdragon 8 series. QA matrices balloon as developers optimize touch-response curves across 200-plus screen configurations.
- Data-Localization Mandates:Argentina's draft cloud-computing regulations and Brazil's LGPD enforcement are forcing server infrastructure replication. Hosting costs multiply as publishers maintain São Paulo, Bogotá, and Mexico City clusters.
- Ad-Network Concentration:Meta Audience Network and Google AdMob capture 70-plus percent of programmatic inventory. CPM compression intensifies as mediation layers fail to diversify demand sources.
Strategic Opportunities
- Colombia's Secondary Cities:Medellín and Cali exhibit smartphone penetration gaps of 15-plus points versus Bogotá. Localized Spanish voice-acting and peso-denominated pricing can unlock latent demand.
- Esports Infrastructure Extension:Buenos Aires server clusters and São Paulo arena partnerships are creating sponsorship inventory. Brand equity from PC/console franchises transfers to mobile viewership.
- GDPR-Aligned Consent Frameworks:Chile's data-protection bill and Argentina's draft legislation are mandating first-party data strategies. Publishers with robust consent-management platforms gain targeting precision as third-party cookies deprecate.
Industry Challenges
- Live-Ops Talent Scarcity:Economists and behavioral psychologists capable of designing progression mechanics are concentrated in São Paulo and Mexico City. Regional studios compete for the same 200-plus specialized profiles.
- Content-Rating Fragmentation:Brazil's juvenile protection framework, Mexico's COFEPRIS standards, and Chile's emerging classification requirements demand parallel submission workflows. Localization delays extend time-to-market by 4-8 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Mobile Gaming Market |
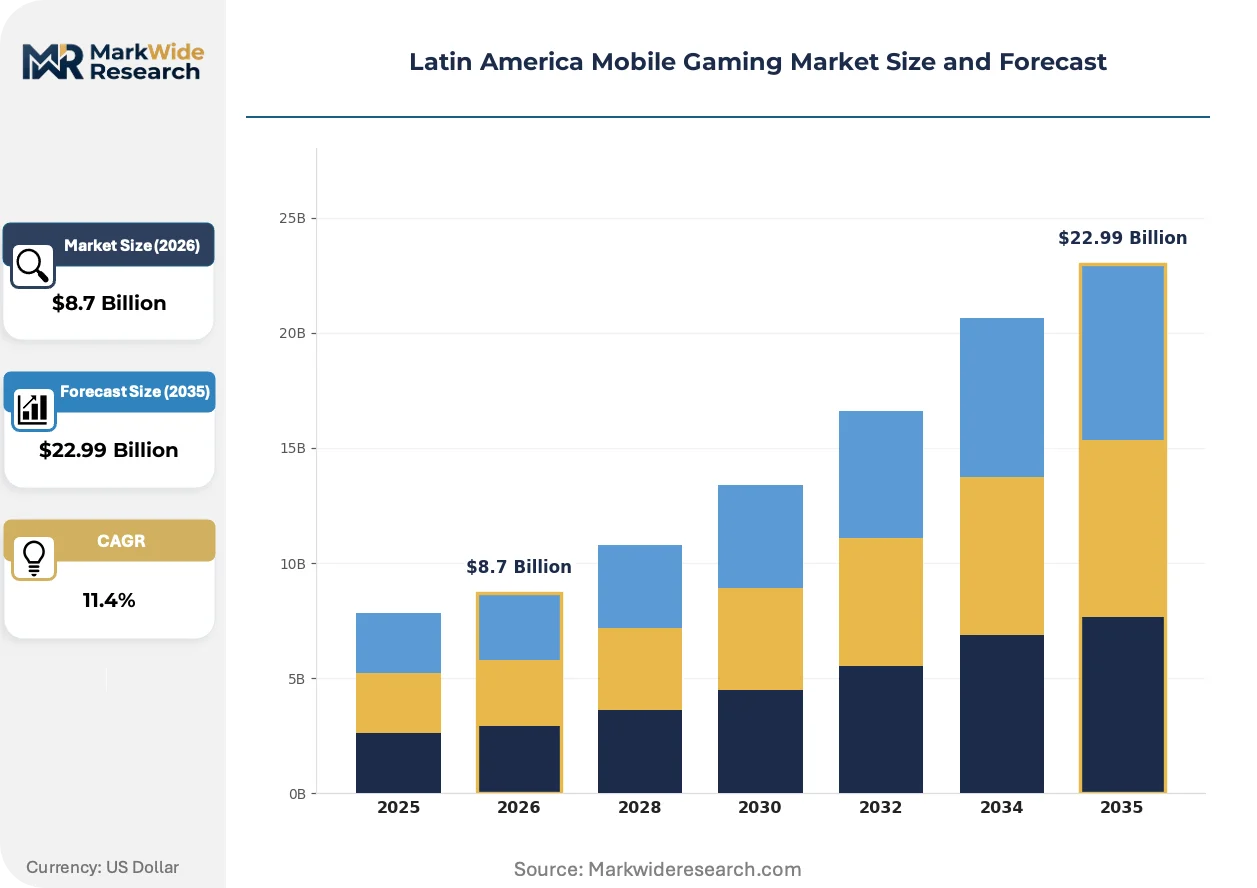
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Android, iOS, Windows Phone, Others Game Genre: Action, Puzzle, Strategy, Simulation Monetization Model: In-App Purchases, Subscription, Premium, Ad-Supported Player Demographics: Teens, Adults, Casual Gamers, Hardcore Gamers |
| Companies Covered | TFG Games, Focka Games, Tapps Games, WASHAWASHA SA DE CV, Media Design and Creative Entertainment, Dynamic Games, HyperBeard, Inc, Activision Publishing, Inc., PlayKids Inc, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Mobile Gaming Market Shifts & Advancements
Cloud-streaming layers are decoupling processing from device capability, reshaping how publishers think about minimum viable hardware. Three technical and behavioral shifts are restructuring competitive positioning.
Edge-computing nodes deployed by regional carriers are fragmenting the traditional app-store distribution model. Mid-core publishers in Mexico City are piloting instant-play demos that stream 500MB-plus assets without store installation. This architecture compresses user-acquisition costs by eliminating download-abandonment friction.
COFEPRIS is extending consumer-protection standards to digital-goods transactions, mandating refund eligibility for minors and clear disclosure of randomized-reward mechanics. Publishers operating in Mexico must restructure loot-box interfaces and maintain auditable transaction logs. Strategy and simulation genres with heavy gacha mechanics face the steepest compliance redesigns.
Session-behavior data reveals casual adult gamers in Brazil's urban corridors are surpassing teen cohorts in weekly session frequency. Hyper-casual studios are pivoting production slates toward match-3 and narrative simulation formats. Chile's female-skewing demographics are driving this portfolio rotation most visibly.
Latin America Mobile Gaming Market Segmentation
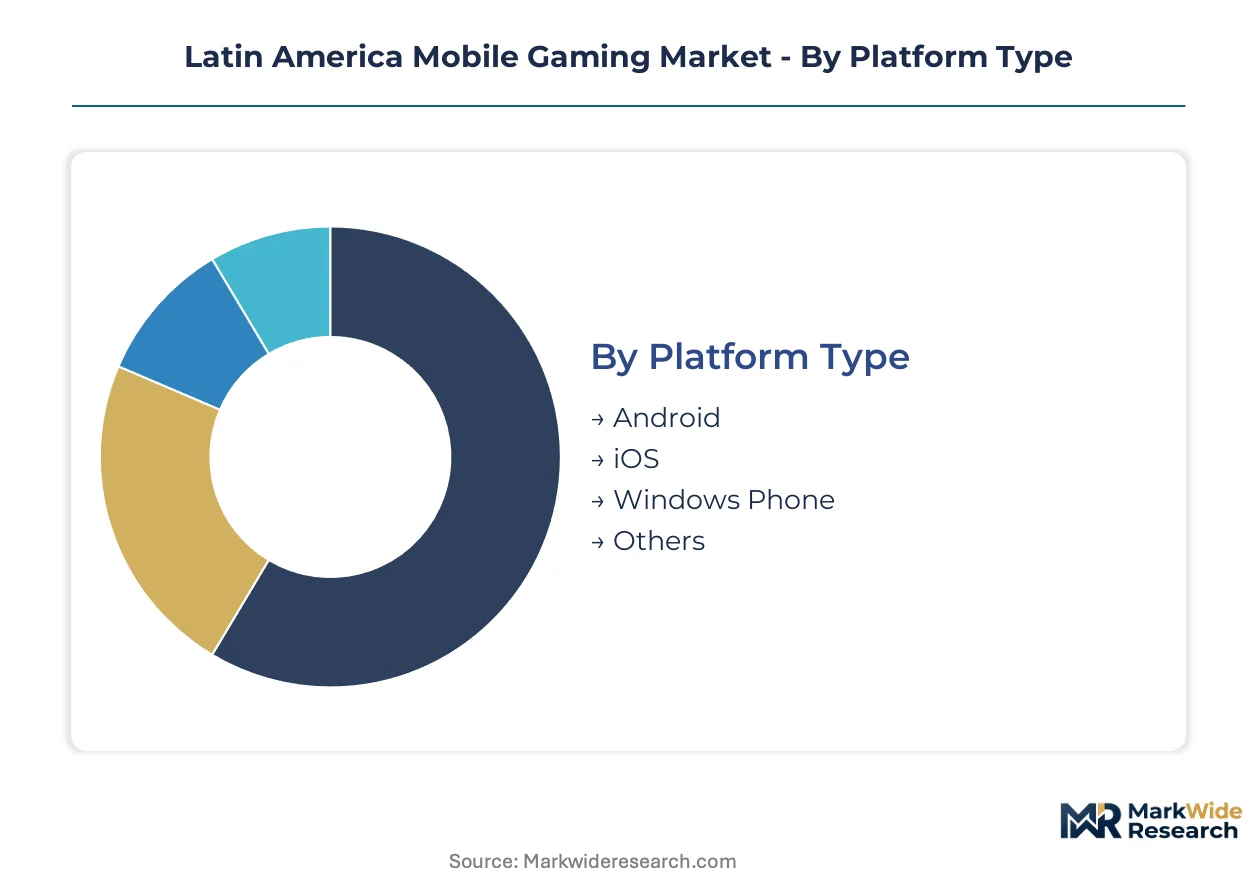
Platform and genre boundaries in Latin America mobile gaming are dissolving as cloud-streaming architectures compress hardware requirements. Publishers now segment audiences by payment behavior and session patterns rather than device specifications alone.
Platform Type:
Substitute pressure from browser-based instant-play formats threatens native app dominance most acutely on low-end Android devices where storage constraints drive uninstall rates.
- Android:ARM-based chipsets from MediaTek Helio through Qualcomm Snapdragon 8 series power 85-plus percent of regional devices. São Paulo and Mexico City developers optimize touch-response curves across 200-plus screen configurations while PIX and OXXO integrations monetize the unbanked through carrier billing.
- iOS:Apple's A-series and M-series silicon deliver disproportionate average revenue per user in metropolitan Brazil and Mexico City. Premium device concentration among urban professionals sustains higher in-app purchase conversion for strategy and simulation titles.
- Windows Phone:Legacy install base persists in enterprise-issued devices across Colombian banking and logistics sectors. Minimal active development targets this remnant cohort.
- Others:KaiOS and proprietary feature-phone operating systems capture rural Brazilian markets with 2G-dependent hardware. HTML5 wrappers enable basic puzzle and trivia formats.
Android retains volume leadership; iOS holds the steepest expansion curve in revenue-per-user metrics.
Game Genre:
Cost-tier stratification separates quick-prototype hyper-casual production from narrative-heavy simulation development requiring specialized live-ops talent.
- Action:First-person shooters and battle royale titles demand sub-20ms latency thresholds that ANATEL's 5G spectrum reforms now enable in São Paulo and Rio de Janeiro. Call of Duty Mobile's esports infrastructure anchors this segment's monetization through seasonal battle passes.
- Puzzle:Match-3 and word-game formats dominate Brazil's free-to-play charts with rapid asset-marketplace reuse compressing development cycles. Adult casual gamers in urban corridors surpass teen cohorts in weekly session frequency.
- Strategy:4X and gacha mechanics face COFEPRIS compliance redesigns for randomized-reward disclosure. Progression systems require behavioral psychologist expertise concentrated in São Paulo and Mexico City.
- Simulation:Narrative-driven life and farming simulations anchor female-skewing demographics across Mexico and Chile. HyperBeard's production pipelines demonstrate genre loyalty through character-driven content updates.
Puzzle titles command the widest audience reach; action games are climbing the fastest in monetization depth per engaged user.
Monetization Model:
Margin concentration diverges sharply between ad-supported volume plays and in-app purchase margin pools, with subscription models emerging as a hybrid alternative.
- In-App Purchases:Micro-transaction architectures integrated with regional digital wallets dominate strategy and simulation genres. Brazil's fintech-wallet penetration enables frictionless progression acceleration.
- Subscription:Apple Arcade and Google Play Pass offer curated libraries appealing to data-conscious parents under Brazil's juvenile protection framework. Recurring revenue reduces customer acquisition cost volatility.
- Premium:Upfront payment models concentrate in narrative-heavy indie titles from Argentine and Chilean studios. Limited addressable audience constrains scale.
- Ad-Supported:Meta Audience Network and Google AdMob capture 70-plus percent of programmatic inventory across hyper-casual titles. CPM compression intensifies as mediation layers fail to diversify demand sources.
Ad-supported formats retain volume leadership; subscription models hold the steepest expansion curve as privacy legislation restricts targeted advertising.
Player Demographics:
Application-specific engagement patterns separate session-frequency leaders from monetization-concentrated hardcore cohorts.
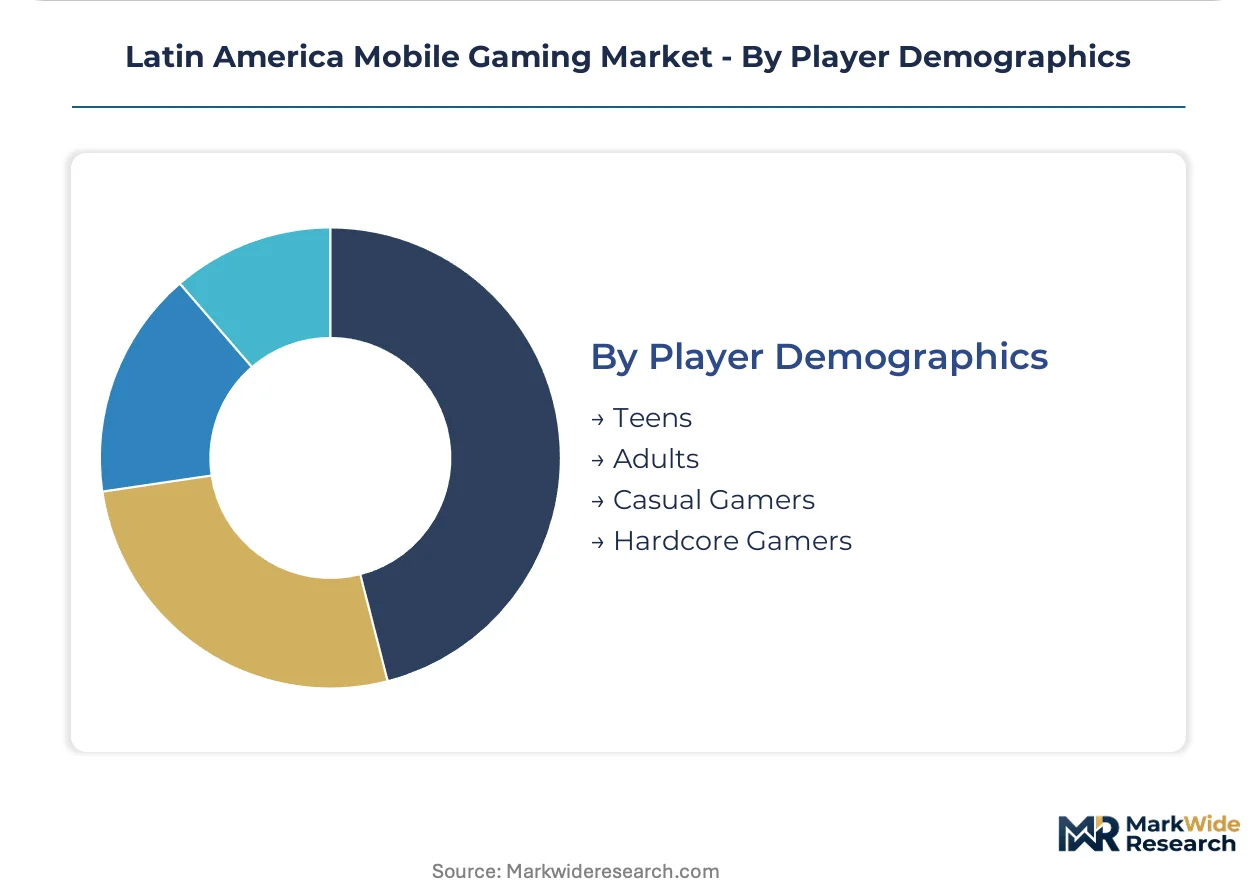
- Teens:Social multiplayer and battle royale titles drive peak concurrent users during after-school hours. Parental oversight under Brazil's ANATEL content rating protocols limits unsupervised spending.
- Adults:Casual adult gamers represent the fastest-expanding buyer archetype as smartphone penetration deepens. Weekly session frequency now surpasses teen engagement in Brazil's urban corridors.
- Casual Gamers:Fragmented play patterns favor hyper-casual and puzzle formats with minimal tutorial friction. Tapps Games leverages rapid prototyping cycles to dominate free-to-play charts.
- Hardcore Gamers:Esports infrastructure extension into São Paulo and Buenos Aires server clusters sustains competitive multiplayer investment. High lifetime value justifies dedicated live-ops support.
Casual gamers retain volume leadership; adult demographics hold the steepest expansion curve in purchasing conversion rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Development studios cluster in São Paulo, Mexico City, and Buenos Aires, with infrastructure investments from Brazil's ANATEL and Mexico's telecommunications reforms compressing latency thresholds for synchronous multiplayer titles.
Brazil
PIX instant-payment integration and 5G spectrum auctions from ANATEL are restructuring monetization mechanics for Android ecosystems. São Paulo hosts the densest concentration of hyper-casual studios, where Tapps Games leverages rapid prototyping cycles measured in weeks. Rio de Janeiro server clusters now support sub-20ms latency thresholds that enable real-time battle royale synchronization.
Mexico
COFEPRIS consumer-protection standards for digital-goods transactions are mandating refund eligibility and randomized-reward disclosure. Mexico City anchors narrative-driven simulation development targeting female-skewing demographics across the capital. OXXO cash-to-digital conversion networks are reducing friction for unbanked populations accessing in-app purchases.
Argentina
Draft cloud-computing regulations and GDPR-aligned privacy legislation are forcing server infrastructure replication and first-party data strategies. Buenos Aires server clusters support esports infrastructure extension for competitive multiplayer titles. Local studios concentrate on premium narrative-heavy indie formats with limited addressable audience scale.
Chile
Data-protection bills are mandating consent-management platforms as third-party cookies deprecate. Santiago-based publishers gain targeting precision through robust first-party data collection. Female-skewing demographics in urban corridors are driving portfolio rotation toward match-3 and life simulation genres.
Colombia
Medellín and Cali exhibit smartphone penetration gaps of 15-plus points versus Bogotá, creating latent demand for localized Spanish voice-acting and peso-denominated pricing. Carrier billing penetration enables monetization of unbanked populations in secondary cities. Bogotá server clusters complete the regional infrastructure triangle with São Paulo and Mexico City.
Latin America Mobile Gaming Market Competitive Landscape
Concentration sits with hyper-casual production pipelines and narrative-driven simulation specialists that dominate distinct monetization archetypes. The vendor base spans rapid-prototype studios with compressed development cycles and character-driven content houses requiring specialized live-ops talent. Three archetypes define competitive positioning: volume-driven hyper-casual publishers, narrative-anchored simulation developers, and brand-equity extensions from PC or console franchises. Dominant competitive moves include fintech-wallet integration partnerships and esports infrastructure extension into regional server clusters.
Within the hyper-casual tier, Tapps Games and Dynamic Games exemplify rapid-prototype production models that flood free-to-play charts with low-CPI acquisition titles. Among narrative-driven specialists, HyperBeard, Inc. occupies a position anchored in character-driven content updates that sustain genre loyalty. Activision Publishing, Inc. represents the brand-equity extension archetype, leveraging established franchises to compete on esports infrastructure and seasonal battle-pass monetization in metropolitan Brazil and Mexico City.
| Leading Market Players |
|---|
| TFG Games |
| Focka Games |
| Tapps Games |
| WASHAWASHA SA DE CV |
| Media Design and Creative Entertainment |
| Dynamic Games |
| HyperBeard, Inc |
| Activision Publishing, Inc. |
| PlayKids Inc |
| Others |
Supply & Pricing Matrix
Asset-marketplace reuse in São Paulo and Mexico City studios compresses development costs through standardized 2D sprites and modular UI kits, concentrating production scale among hyper-casual publishers while establishing price floors that exclude premium narrative development. This scale dynamic funnels margin toward rapid-prototype houses and fragments supply capacity for live-ops talent across Brazil, Mexico, and Argentina.
Pricing Analysis
Volume-discount tiering structures separate hyper-casual CPI acquisition models from premium in-app purchase conversion rates. Three-tier pricing stratification across whale-accelerated progression, mid-tier battle-pass subscribers, and ad-supported free players reflects platform-specific ARPU divergence. Pricing pressure stems from CPM compression across Meta Audience Network and Google AdMob mediation layers. Casual adult gamers in Brazil's urban corridors demonstrate lowest price sensitivity for progression acceleration, while unbanked populations in Colombian secondary cities face highest friction thresholds.
Supply Chain Analysis
Inventory compression in cloud-rendered asset pipelines reduces lead times for instant-play demos below traditional app-store submission cycles. Development talent concentrates in São Paulo, Mexico City, and Buenos Aires, with behavioral economist expertise tethered to São Paulo's live-ops cluster. Raw material dependencies span Unity and Unreal engine licensing, cloud compute from AWS and Azure regional nodes, and fintech API integrations for PIX and OXXO rails. Single-source vulnerability sits with Meta Audience Network's programmatic dominance. Distribution runs through Google Play Store and Apple App Store, with edge-computing nodes fragmenting traditional installation models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in Latin America mobile gaming rests on 5G infrastructure penetration compressing latency thresholds for synchronous multiplayer titles. PIX and OXXO fintech integration extends addressable audiences into unbanked populations across Brazil and Mexico.
For Market Incumbents: Secure live-ops talent pipelines in São Paulo and Mexico City through specialized behavioral economist recruitment before regional competition intensifies. Lock in exclusive fintech-wallet integration partnerships with PIX and OXXO networks to defend transaction-flow capture. Capacity addition in Buenos Aires server clusters anchors esports infrastructure extension against emerging cloud-streaming substitutes. For New Entrants and Emerging Players: ANATEL content rating fast-track protocols in Brazil offer regulatory arbitrage against slower COFEPRIS submission timelines in Mexico. White-space concentration sits in Colombia's secondary cities—Medellín and Cali exhibit smartphone penetration gaps of 15-plus points versus Bogotá. Localized Spanish voice-acting and peso-denominated pricing unlock latent demand. Go-to-market angle: carrier-billing partnerships with regional telecommunications providers bypass fintech-wallet dependency for unbanked acquisition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors studios with first-party data infrastructure under GDPR-aligned consent frameworks. Long-term viability across the projection horizon rests on esports infrastructure ownership and cloud-streaming distribution patents. Acquisition target archetype: narrative-driven simulation developers with female-skewing demographic lock-in and established live-ops cadence. Signal to watch: ANATEL spectrum auction outcomes determining São Paulo latency thresholds for battle royale synchronization.| Strategic Initiative | Industry Significance |
|---|---|
| Fintech-Wallet Integration Partnership | PIX and OXXO rails reduce transaction friction for unbanked populations in Brazil and Mexico. |
| Esports Infrastructure Extension | Buenos Aires and São Paulo server clusters create sponsorship inventory for brand-equity franchises. |
| First-Party Data Platform Investment | GDPR-aligned consent frameworks gain targeting precision as third-party cookies deprecate across Chile and Argentina. |
| Hyper-Casual Production Pipeline Acquisition | Rapid prototyping cycles measured in weeks dominate Brazil's free-to-play charts with low-CPI acquisition. |
| Cloud-Streaming Distribution Patent | Edge-computing nodes fragment traditional app-store models through instant-play demo architectures. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, App Annie mobile intelligence data, ANATEL spectrum auction disclosures, and COFEPRIS regulatory bulletins. Primary interviews engaged game studio executives, live-ops product managers, fintech partnership leads, and cloud infrastructure engineers across São Paulo, Mexico City, and Buenos Aires. Bottom-up triangulation across platform-specific revenue estimates and top-down validation against regional digital entertainment spending aggregates anchor quantitative outputs.
Segmentation dimensions modeled include platform type, game genre, monetization model, and player demographic archetypes across the analysis window. CAGRs derive from installed base projections for 5G-enabled devices, fintech-wallet penetration curves, and session-frequency trends among casual adult gamers. Forecast inputs incorporate ANATEL infrastructure rollout timelines and COFEPRIS compliance cost assumptions for randomized-reward mechanics.
Decision-makers should treat outputs as directional under assumptions of sustained PIX adoption velocity and stable carrier-billing economics; material deviation in telecommunications investment cycles or data-localization enforcement would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Gaming Chair Market
Gaming
Asia-Pacific Video Game Software Market
Gaming
China Gaming Headsets Market
Gaming
Virtual Reality (VR) in Gaming Market
Gaming
Slot Machine Market
Gaming
Gaming Hardware Market
Gaming
Japan Virtual Reality Gaming Market
Gaming
Australia Gaming Accessories Market
Gaming
Saudi Arabia Entertainment and Amusement Market
Gaming
Asia-Pacific in-Game Advertising Market
Gaming
Africa Gaming Market
Gaming
Advanced Digital Gaming Market
Gaming
Global Casino and Gaming Market
Gaming
Arcade Cabinet Market
Gaming
LAMEA in-Game Advertising Market
Gaming
Mobile MOBA Games Market