
 Global Delivery Takeaway Food Market | 2026-2036
Global Delivery Takeaway Food Market Size, Share, and Industry Trends Forecast 2026-2036
Global Delivery Takeaway Food Market Analysis
The split between premium chef-curated offerings and mass-market commodity meals is hardening across platform economics. DoorDash leverages its suburban US density to sustain delivery-time advantages in lower-income zip codes. Meituan anchors the Chinese market through in-house logistics networks that control rider allocation algorithms.
Delivery takeaway food encompasses prepared meals ordered through digital interfaces and transported from restaurant kitchens to consumer locations, typically maintaining temperature thresholds above 60°C for hot items through insulated packaging or heated transport compartments. The service exists to bridge spatial separation between food production and consumption without on-premise dining infrastructure. Express delivery commands the highest frequency among service types due to impulse-driven lunch and dinner occasions, while contactless delivery retains structural importance in healthcare-adjacent and immunocompromised customer segments. Platform dynamics concentrate margin pools around mobile apps, where push-notification engagement and habitual interface design drive reorder rates above browser-based alternatives.
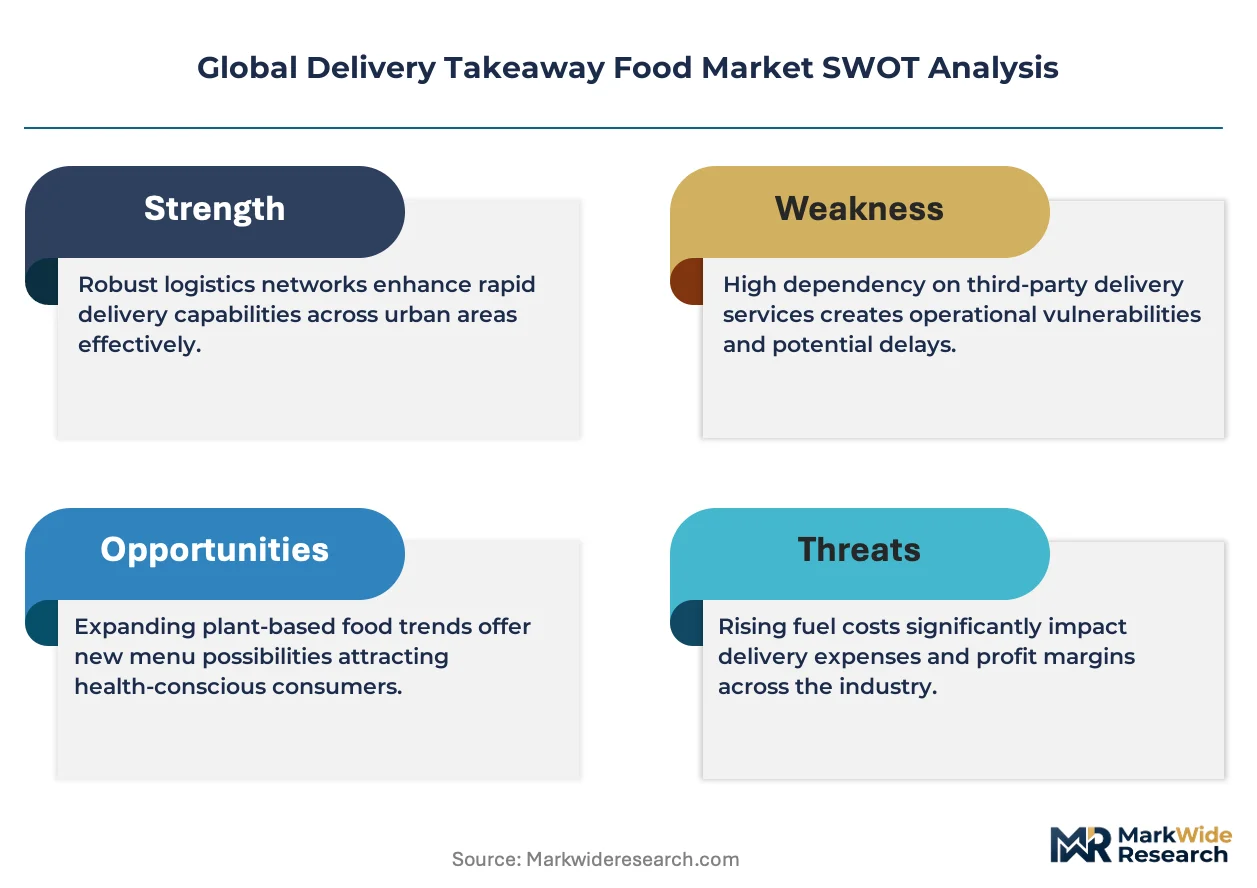
The FDA oversees platform food safety in the United States through the Food Code and retail food protection guidelines, while the EU's General Food Law and national hygiene regulators such as France's DGCCRF impose traceability obligations on cross-border delivery operations. China's SAMR enforces real-name restaurant verification and rider labor classification rules that reshape platform cost structures. Stakeholders must monitor how gig-economy reclassification rulings across multiple jurisdictions alter last-mile labor costs and platform fee structures.
Market Dynamics
Platform-mediated food delivery is consolidating around algorithmic rider allocation and real-time kitchen monitoring as China's SAMR traceability mandates force infrastructure upgrades across operator networks.
Growth Catalysts
- Corporate catering contracts:Hybrid work stabilization drives recurring B2B meal programs with predictable order volumes and negotiated platform fee structures.
- India's metropolitan corridors:Urban density above 15,000 persons per square kilometer combined with smartphone penetration exceeding 75% creates favorable unit economics for aggregator models.
- Real-time kitchen monitoring:IoT temperature sensors and video verification systems satisfy SAMR food safety traceability requirements while reducing insurance premiums for platform partners.
Market Restraints
- Gig-economy reclassification rulings:Jurisdictional shifts toward employee-status classification for riders in the EU and select US states compress platform margins by 15-30 percentage points on labor costs.
- Insulated packaging input volatility:Expanded polystyrene and plant-based fiber thermal containers face petroleum and pulp price swings that destabilize per-unit packaging economics.
- Cross-border traceability fragmentation:Divergent national implementations of EU General Food Law and FDA Food Code requirements create compliance overhead for multinational platform operators.
Strategic Opportunities
- Healthcare-adjacent contactless delivery:Immunocompromised patient segments and hospital campus contracts retain structural demand for zero-touch handoff protocols and sealed packaging verification.
- Suburban US density gaps:Lower-income zip codes with household formation growth above urban cores present first-mover advantages for logistics networks optimizing delivery-time algorithms.
- EU Green Deal packaging mandates:Compulsory reduction of single-use plastics by 2030 accelerates demand for reusable container deposit systems and return-logistics infrastructure.
Industry Challenges
- Rider retention and safety certification:High-turnover gig workforce requires continuous food handler credentialing and road safety training that strains platform operational bandwidth.
- Legacy POS integration complexity:Independent restaurants operate fragmented kitchen display systems that resist API standardization, delaying real-time inventory synchronization with platform demand forecasting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Delivery Takeaway Food Market |
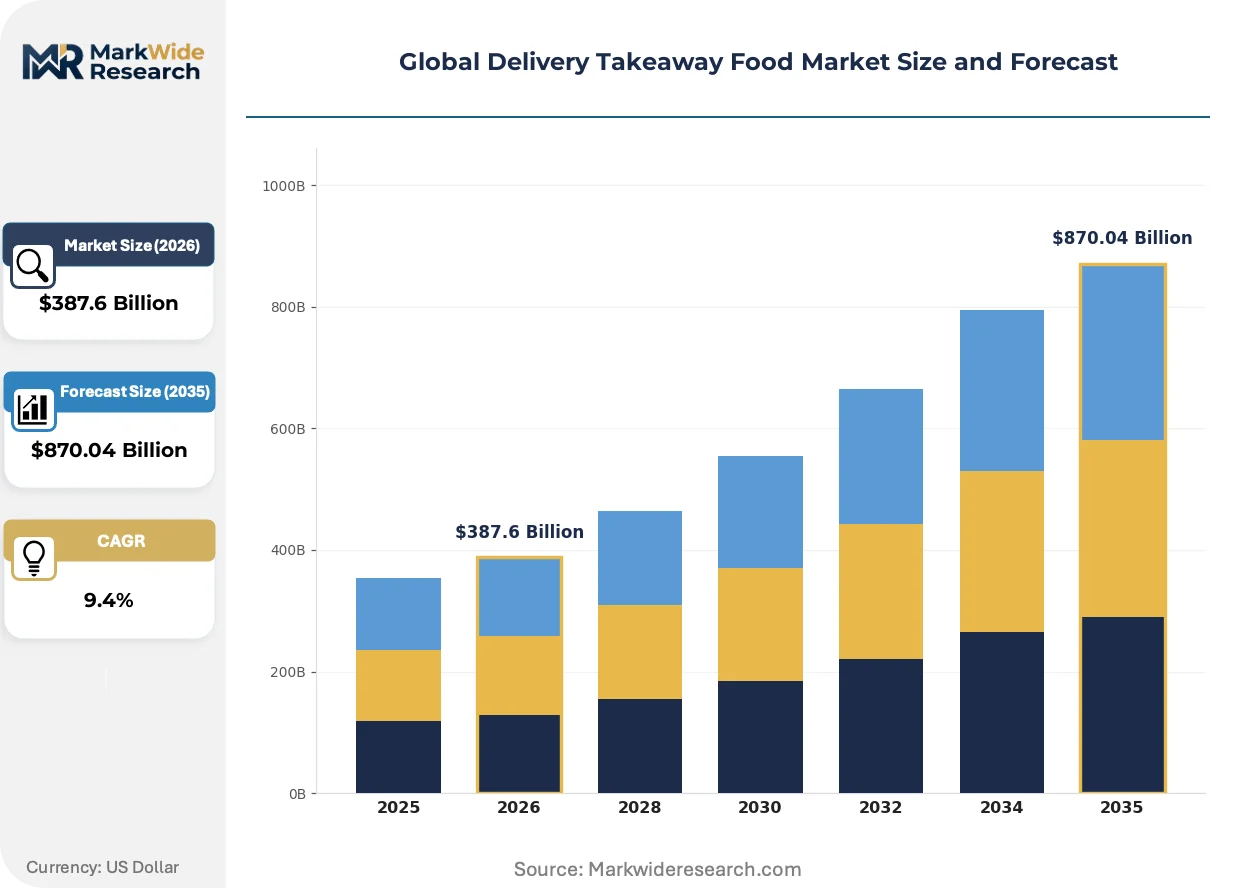
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $870.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pizza, Sushi, Burgers, Salads Service Type: Express Delivery, Scheduled Delivery, Contactless Delivery, Takeaway Customer Type: Individuals, Families, Corporate Clients, Students Platform: Mobile Apps, Websites, Third-party Services, Direct Orders |
| Companies Covered | DoorDash Inc, Uber Technologies Inc, Meituan, Delivery Hero SE, Just Eat Takeaway.com N.V., Ele.me, Deliveroo, Zomato, Grubhub, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Delivery Takeaway Food Market Emerging Trajectories
Artificial intelligence and predictive logistics are compressing delivery windows while regulatory pressure on packaging waste forces material science innovation across the value chain.
Dynamic pricing algorithms paired with demand-heat mapping are rewriting how platforms allocate kitchen capacity and rider fleets during peak meal occasions. Quick-service chains in dense East Asian metros deploy these systems to shave average delivery times below 25 minutes. The compression of fulfillment windows is eroding the competitive moat of premium-positioned dark kitchen operators.
China's SAMR enforcement of real-name restaurant verification and rider labor classification rules is mandating platform investment in compliance infrastructure. The industrial consequence shifts cost structures toward fixed regulatory technology spend rather than variable gig labor pools. Cross-border operators entering the Chinese market must build localized legal entities and captive logistics networks to satisfy these requirements.
Subscription-based meal plans are displacing impulse-driven single orders among urban professional households in North American and European metros. These recurring revenue arrangements reduce customer acquisition costs for platforms while locking in predictable demand for partner restaurants. The behavioral shift is most visible in post-pandemic hybrid work patterns where employees seek automated lunch solutions for office days.
Global Delivery Takeaway Food Market Segmentation
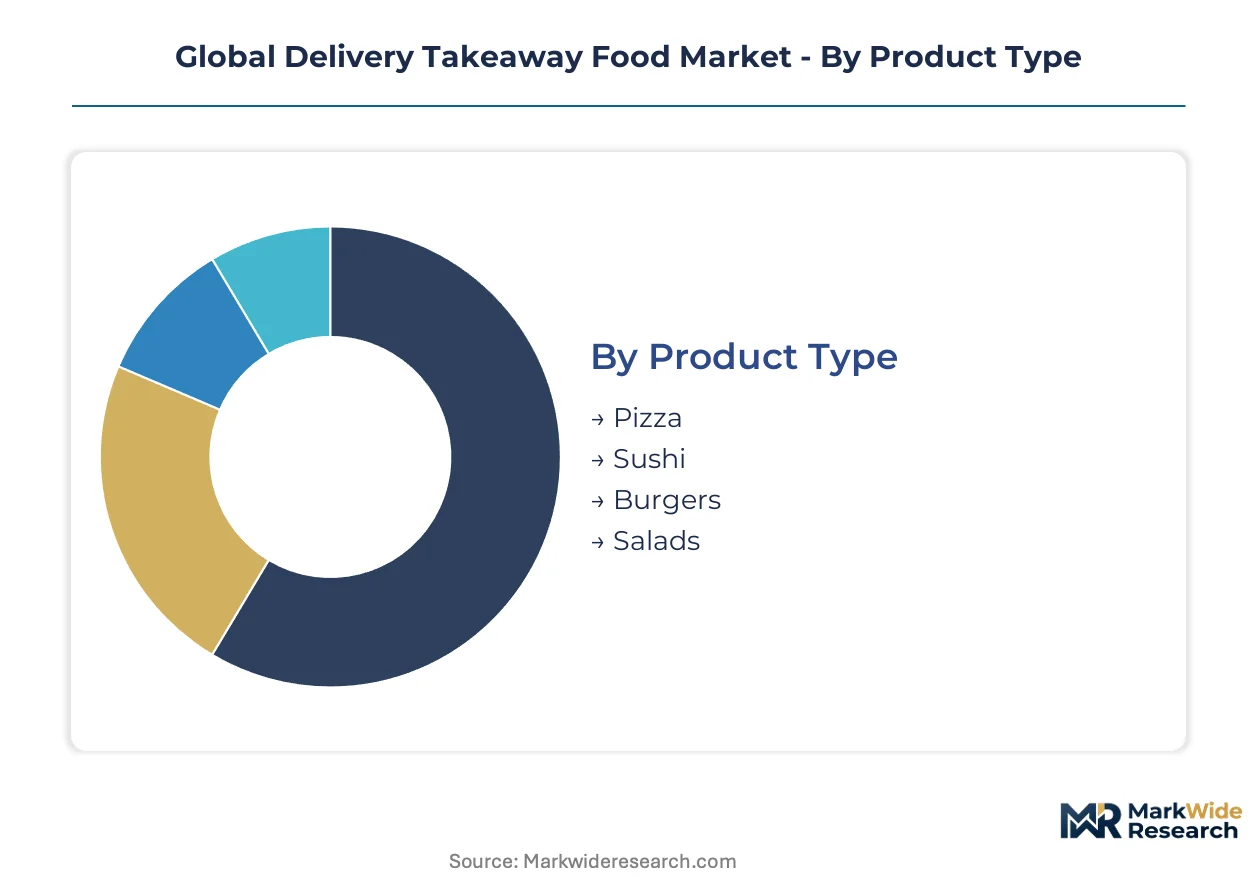
Segmentation in delivery takeaway food reveals how platform economics concentrate margin pools around specific consumption occasions and ordering interfaces. Understanding these splits enables operators to allocate kitchen capacity and rider fleets toward the highest-frequency, lowest-churn customer profiles.
Product Type:
Pizza and sushi dominate premium transaction values while burgers and salads anchor mass-market volume throughput across aggregator platforms.
- Pizza:High-heat retention above 60°C through insulated packaging makes pizza structurally suited to extended delivery windows. Demand concentrates in suburban US corridors where household formation rates exceed urban cores, driven by family-sized order values and predictable weekend occasion clustering.
- Sushi:Cold-chain integrity requirements below 4°C for raw fish segments impose specialized logistics costs and shorter fulfillment windows. Premium positioning in metropolitan Japan and coastal US cities sustains per-unit margins despite higher packaging and rider training overhead.
- Burgers:Quick-service standardization enables rapid kitchen throughput and algorithmic demand forecasting at scale.
- Salads:Health-positioned offerings attract corporate catering contracts with recurring weekday demand patterns.
Mature deployment sits with pizza. Newer deployment is concentrated in salads.
Service Type:
Speed tiering separates impulse-driven occasions from planned consumption, with contactless protocols retaining structural importance in healthcare-adjacent segments.
- Express Delivery:Sub-30-minute fulfillment windows dominate lunch and dinner impulse occasions through algorithmic rider allocation and real-time kitchen monitoring. India's metropolitan corridors with urban density above 15,000 persons per square kilometer generate favorable unit economics for this segment.
- Scheduled Delivery:Pre-booked windows reduce peak-load rider costs and enable batch routing optimization for corporate meal programs.
- Contactless Delivery:Zero-touch handoff protocols satisfy immunocompromised patient segments and hospital campus contracts with sealed packaging verification requirements.
- Takeaway:Customer-collection models eliminate last-mile labor costs entirely, preserving margin for price-sensitive independent restaurants.
Express delivery commands the steepest expansion trajectory as platform algorithms compress fulfillment windows. Scheduled delivery is gaining share fastest among hybrid work corporate contracts.
Customer Type:
Behavioral segmentation tracks how hybrid work stabilization and student density reshape recurring revenue predictability across platform partner restaurants.
- Individuals:Single-serve orders drive highest frequency through mobile app push-notification engagement and habitual interface design.
- Families:Multi-portion baskets elevate average order values but concentrate demand in weekend windows with lower rider utilization efficiency.
- Corporate Clients:B2B meal programs with negotiated platform fee structures generate predictable volume that reduces kitchen capacity planning variance for partner restaurants.
- Students:Price-sensitive clustering around university campuses in India and Southeast Asia creates dense delivery zones with favorable per-drop economics.
Corporate clients anchor stable revenue pools. Students are expanding most quickly as smartphone penetration climbs across emerging metropolitan corridors.
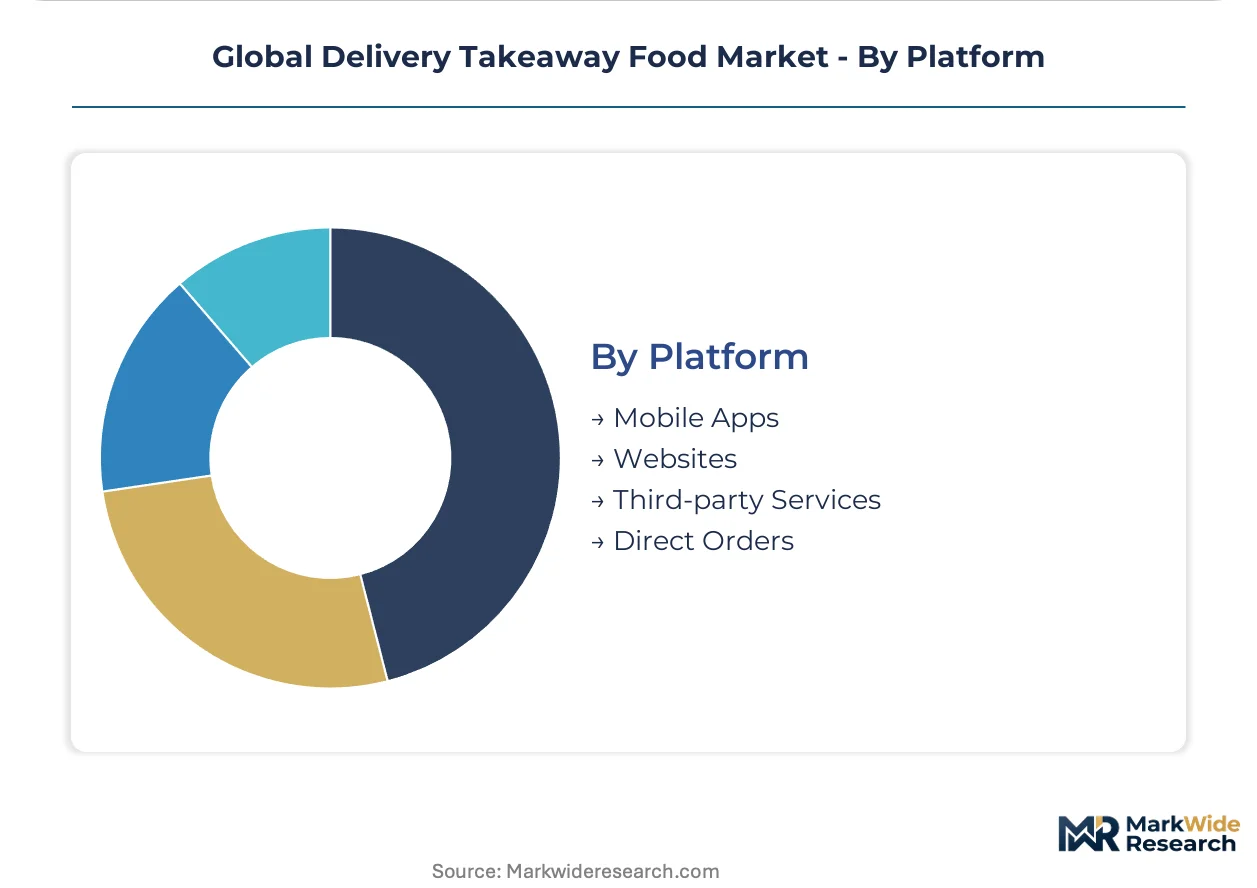
Platform:
Interface selection determines customer acquisition costs and reorder rates, with mobile-native design capturing habitual engagement loops.
- Mobile Apps:Push-notification engagement and stored payment credentials drive reorder rates above browser-based alternatives through reduced friction at checkout.
- Websites:Desktop ordering retains importance for corporate catering administrators managing multi-person meal programs with invoice reconciliation requirements.
- Third-party Services:Aggregator platforms concentrate demand forecasting data and rider fleet optimization across thousands of partner restaurants.
- Direct Orders:Restaurant-owned channels bypass platform commission structures but require independent customer acquisition investment and captive logistics buildout.
Third-party services dominate volume concentration. Direct orders are climbing the fastest among premium chef-curated operators seeking margin defense.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Pudong corridor anchors the densest food delivery logistics networks globally, with rider allocation algorithms optimized for urban density exceeding 20,000 persons per square kilometer. Platform operators across four continents are replicating this cluster's real-time kitchen monitoring infrastructure to satisfy tightening traceability mandates.
United States
Suburban household formation in Texas and Florida metros outpaces urban cores, creating delivery-time arbitrage opportunities in lower-income zip codes. The FDA's Food Code enforcement through state retail food protection guidelines imposes temperature documentation requirements on interstate platform operations. DoorDash leverages proprietary logistics density in Atlanta and Phoenix exurbs to sustain sub-30-minute fulfillment windows where competitor networks remain sparse.
China
Meituan's captive logistics networks control rider allocation algorithms across 2,800 county-level districts, generating data moats unavailable to asset-light competitors. SAMR's real-name restaurant verification and labor classification rules mandate fixed compliance technology spend rather than variable gig labor pools. The Yangtze River Delta corridor concentrates dark kitchen deployments in Suzhou and Hangzhou, where industrial real estate costs remain below Shanghai core levels.
India
Smartphone penetration above 75% in Mumbai, Bangalore, and Delhi-NCR corridors enables aggregator models with favorable per-drop economics at urban densities above 15,000 persons per square kilometer. FSSAI's tightening food safety licensing for cloud kitchens forces platform partners toward centralized commissary models. Zomato and Swiggy compete for student clusters around Pune and Hyderabad university campuses, where price-sensitive demand generates predictable weekday lunch volumes.
Germany
Delivery Hero's Berlin headquarters anchors pan-European technology development for algorithmic demand forecasting. The EU Green Deal's 2030 single-use plastic reduction mandates accelerate reusable container deposit system pilots in Hamburg and Munich. DGCCRF traceability inspections on cross-border delivery operations create compliance overhead that favors established platforms with dedicated legal entities over market entrants.
United Kingdom
Deliveroo's London-centric rider fleet optimization targets corporate catering contracts stabilizing around hybrid work patterns in the Square Mile and Canary Wharf. The Competition and Markets Authority's scrutiny of platform commission structures pressures fee negotiations with independent restaurants in Manchester and Birmingham clusters. Contactless delivery protocols retain structural importance in National Health Service campus contracts across the Greater London Authority boundary.
Global Delivery Takeaway Food Market Vendor Landscape
Capital-heavy logistics operators compete with asset-light marketplace designers across divergent margin structures. The vendor base concentrates around three strategic archetypes: captive fleet operators owning rider allocation algorithms, aggregator platforms outsourcing last-mile labor to gig networks, and restaurant-owned direct channels bypassing commission structures. Consolidation pressure intensifies as scale advantages in demand data and kitchen capacity planning widen performance gaps between tier-one and regional operators. Dominant competitive moves include geographic market entry through acquisition and backward integration into dark kitchen real estate.
Among US-based technology platforms, DoorDash Inc and Uber Technologies Inc occupy positions as scale-driven logistics architects, while China's Meituan exemplifies the captive fleet archetype through in-house rider networks. Delivery Hero SE anchors European marketplace aggregation across multiple continental markets. These three entities represent contrasting capital deployment strategies: technology-heavy algorithm development, labor-heavy operational control, and M&A-heavy geographic expansion.
| Leading Market Players |
|---|
| DoorDash Inc |
| Uber Technologies Inc |
| Meituan |
| Delivery Hero SE |
| Just Eat Takeaway.com N.V. |
| Ele.me |
| Deliveroo |
| Zomato |
| Grubhub |
| Others |
Supply Flow & Price Mechanics
Rider concentration in China's Yangtze River Delta corridor anchors labor-cost differentials that widen pricing-tier spreads between premium chef-curated offerings and mass-market commodity meals across platform networks.
Pricing Analysis
Throughput-based pricing anchors platform commission structures, with per-order fees scaling downward for high-volume corporate catering contracts that guarantee predictable demand. Price differentiation separates premium dark kitchen operators with real-time kitchen monitoring certification from unverified independent restaurants competing on delivery subsidies. Pricing pressure stems from gig-economy reclassification rulings in the EU and select US states that compress platform margins on labor costs. Students and price-sensitive consumers in India's metropolitan corridors exhibit highest price elasticity, while corporate clients with negotiated B2B arrangements demonstrate lowest sensitivity.
Supply Chain Analysis
Reverse-logistics infrastructure for reusable container deposit systems under the EU Green Deal is reshaping last-mile material flows as platforms pilot return-loop networks in Hamburg and Munich. Expanded polystyrene and plant-based fiber thermal packaging production concentrates in China, Germany, and the United States, drawing from petroleum derivatives and pulp commodities that face price volatility. Single-source vulnerability in insulated packaging inputs creates margin destabilization risk when petroleum or pulp markets fluctuate. Distribution runs through aggregator platform networks that consolidate demand forecasting and rider fleet optimization across thousands of partner restaurants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The delivery takeaway food market sits in a technology-transition phase as artificial intelligence and predictive logistics displace legacy demand-heat mapping systems that relied on static historical patterns.
For Market Incumbents: Extend algorithmic rider allocation investments to defend against asset-light marketplace entrants exploiting suburban US density gaps. Build backward integration into dark kitchen real estate in lower-cost industrial zones to offset rising regulatory technology spend mandated by SAMR traceability rules. Prioritize API standardization partnerships with legacy POS vendors to reduce kitchen display system fragmentation.
For New Entrants and Emerging Players: Begin with healthcare-adjacent contactless delivery segments where zero-touch handoff protocols and sealed packaging verification create defensible moats against established platforms. Target immunocompromised patient populations and hospital campus contracts in the United Kingdom and Germany where structural demand retains premium pricing power. Deploy subscription-based meal plan go-to-market angles to lock in recurring revenue and reduce customer acquisition costs.
For Investors and Strategic Acquirers: Re-rating potential sits with captive fleet operators given SAMR labor classification mandates that force fixed compliance infrastructure spend. Long-term viability favors platforms with in-house logistics networks and localized legal entities in China over asset-light marketplace models. Monitor gig-economy reclassification rulings across EU member states and US jurisdictions as the primary inflection indicator for margin compression trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Kitchen Monitoring Deployment | SAMR traceability mandates force IoT sensor investments that reduce insurance premiums for verified partners. |
| Reusable Container Deposit System | EU Green Deal packaging mandates accelerate return-logistics infrastructure pilots in Hamburg and Munich corridors. |
| Corporate Catering Contract Expansion | Hybrid work stabilization drives recurring B2B revenue with negotiated fee structures and predictable volume. |
| Suburban Density Network Buildout | Texas and Florida household formation outpaces urban cores, creating delivery-time arbitrage opportunities. |
| Algorithmic Rider Allocation Upgrade | Dynamic pricing paired with demand-heat mapping compresses fulfillment windows below 25 minutes in dense metros. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across platform operations directors, restaurant supply chain managers, rider fleet coordinators, and food safety compliance officers. FDA Food Code documentation, SAMR enforcement bulletins, EU General Food Law implementations, and FSSAI licensing databases provided regulatory boundary conditions. Bottom-up restaurant count and order frequency estimates triangulated against top-down platform revenue disclosures and regional smartphone penetration benchmarks.
Granularity-level modeling distinguished express delivery from scheduled and contactless service types, with segmentation across pizza, sushi, burger, and salad product categories plus individual, family, corporate, and student customer archetypes. CAGRs derived from logistic adoption curves applied to urban density and smartphone penetration thresholds across the projection horizon. Forecast inputs incorporated SAMR compliance cost trajectories, EU Green Deal packaging transition timelines, and gig-economy reclassification probability assessments.
Underlying measurement precision varies by segment; corporate catering and express delivery carry tighter precision than emerging contactless protocols. Forecasts reflect documented assumptions on hybrid work stabilization rates and regulatory enforcement intensity. Practitioners should monitor SAMR real-name verification rollout pace and EU member state gig reclassification court rulings for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
International Food Subscription Box Service Market
Food Service
Europe Cloud Kitchen Market
Food Service
Smart Food Logistics Market
Food Service
Commercial Deep Fryer Parts and Accessories Market
Food Service
Airport Quick Service Restaurants Market
Food Service
Restaurant Takeout Market
Food Service
Stirrers Market
Food Service
Commercial Kitchen Appliances Market
Food Service
Meal Voucher Market
Food Service
Portable Buffet and Drop-In Ranges Market
Food Service
Global Online Food Delivery Services Market
Food Service
Foodservice Coffee Market
Food Service
Europe Smokeless Indoor Grills Market
Food Service
Lunch Takeout Market
Food Service
Vietnam Food Service Market
Food Service
Light Meal Market