
 Automated Optical Inspection (AOI) System Market | 2026-2036
Automated Optical Inspection (AOI) System Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Optical Inspection (AOI) System Market Analysis
The direct sales channel is narrowing as Japanese and Korean equipment makers tighten distributor relationships in Southeast Asia. Koh Young Technology leverages its 3D solder paste inspection dominance to control high-mix PCB assembly lines across Vietnam and Malaysia. Cognex Corporation sustains North American brand loyalty through deep software integration with factory MES platforms. Omron Corporation competes aggressively on price-performance ratios for mid-tier automotive electronics suppliers in Mexico and Eastern Europe.
An automated optical inspection system deploys high-resolution cameras, structured lighting arrays, and machine-vision algorithms to detect surface defects, dimensional deviations, and component placement errors on printed circuit boards, semiconductor wafers, and assembled electronics at throughput rates exceeding 100 cm² per second. Its primary industrial purpose is to replace manual visual inspection with repeatable, traceable quality gates that reduce escape rates in high-volume electronics manufacturing. Three-dimensional inspection commands the widest margin pools as advanced packaging and flip-chip architectures proliferate, while two-dimensional systems remain entrenched in cost-sensitive consumer electronics lines. Contract manufacturers represent the fastest-growing end-user category as EMS providers like Foxconn and Jabil internalize quality control to satisfy OEM liability terms.
The U.S. FDA regulates AOI systems deployed in medical device manufacturing through 21 CFR Part 820 quality system requirements, while the EPA's electronics waste rules indirectly shape refurbishment and rework inspection demand. China's SAMR enforces GB/T standards for SMT equipment safety and electromagnetic compatibility, creating certification barriers for non-domestic suppliers. REACH and RoHS in Europe restrict hazardous substances in inspected assemblies, pushing manufacturers toward contaminant-detection capabilities. Stakeholders must monitor how dual-use export controls on advanced semiconductor equipment redirect AOI procurement flows toward politically aligned manufacturing jurisdictions.
Market Dynamics
Sub-5nm semiconductor node migration is compressing defect tolerance thresholds below 50 nanometers, forcing fabs to retire 2D inspection architectures in favor of multi-angle 3D reconstruction systems that capture coplanarity errors in advanced packaging.
Growth Catalysts
- RoHS contaminant mandates:Europe's hazardous substance restrictions now require trace-level detection of lead and cadmium in solder joints, pushing EMS providers toward hyperspectral AOI configurations.
- Flip-chip proliferation:High-density interconnect architectures in AI accelerators and mobile processors demand sub-micron placement verification that only 3D tomographic inspection can deliver.
- Taiwan fab concentration:TSMC and Samsung Foundry capacity expansions in Hsinchu and Pyeongtaek are absorbing 40% of new high-speed AOI deployments for wafer-level packaging.
Market Restraints
- CMOS sensor supply choke:Sony and ON Semiconductor dominate high-speed image sensor fabrication, creating 16-24 week lead times for 25-megapixel inspection cameras.
- GB/T certification friction:China's electromagnetic compatibility testing for SMT equipment adds 4-6 months to market entry for non-domestic suppliers.
- Technical ceiling at 3nm:Current optical resolution limits near 193nm wavelength boundaries force reliance on slower electron-beam sampling for critical dimension verification.
Strategic Opportunities
- Vietnam EMS migration:Foxconn and Luxshare expansions in Bac Ninh and Hai Phong are greenfield sites lacking legacy inspection infrastructure, opening full-fleet replacement cycles.
- AI-driven false-positive reduction:Convolutional neural networks trained on defect libraries are collapsing rework rates in high-mix PCB lines, differentiating premium system tiers.
- India PLI scheme:Production-linked incentives for electronics manufacturing are attracting component suppliers that require entry-level 2D inspection for mobile phone subassemblies.
Industry Challenges
- Machine-vision engineer scarcity:Programming complex inspection recipes for heterogeneous component mixes requires specialized optical physics expertise concentrated in Taiwan and South Korea.
- Legacy MES integration:Brownfield automotive plants in Mexico and Eastern Europe run 1990s-era manufacturing execution systems that resist API connectivity with modern AOI data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Optical Inspection (AOI) System Market |
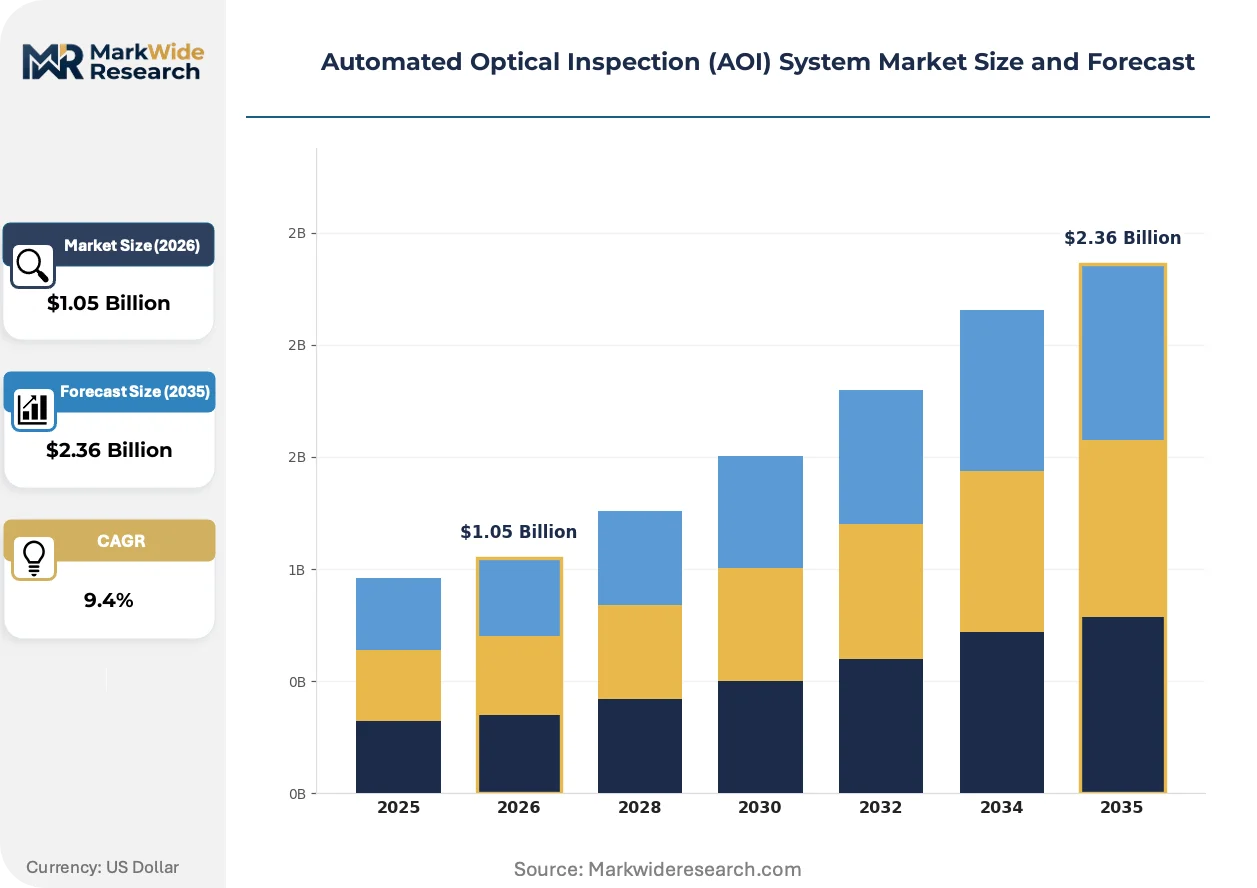
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: 2D Inspection, 3D Inspection, X-Ray Inspection, Laser Inspection Application: Electronics Manufacturing, Semiconductor Production, Automotive Assembly, PCB Inspection End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Contract Manufacturers Component: Cameras, Lighting Systems, Software, Conveyors |
| Companies Covered | Camtek, Saki Corporation, Koh Young Technology, Cognex Corporation, Nordson YESTECH, Test Research, Viscom, KLA Corporation, Omron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Optical Inspection (AOI) System Market Emerging Trajectories
Computational imaging and edge-AI inference are collapsing the traditional trade-off between inspection throughput and defect sensitivity that has governed equipment procurement decisions for two decades.
Structured-light phase-shifting profilometry is collapsing the cost premium between 2D and 3D inspection systems. Mid-tier EMS providers in Malaysia and Thailand are adopting this technology for automotive camera module assemblies where coplanarity tolerances now sit below 10 microns. Equipment vendors are responding with modular hardware platforms that upgrade existing 2D gantries rather than requiring full replacement.
REACH substance restrictions are extending disclosure requirements to the full bill of materials in inspected assemblies. German automotive suppliers now demand AOI systems with integrated material verification cameras that cross-reference component markings against SCIP database entries. This is compressing sales cycles for inspection vendors lacking built-in regulatory compliance modules.
Consolidated procurement by mega-EMS providers is displacing distributor networks with direct equipment leasing arrangements. Foxconn and Jabil now negotiate enterprise-wide frame agreements that bundle hardware, software licenses, and predictive maintenance into per-inspection-unit pricing. This model is concentrating vendor selection authority at headquarters level in Taipei and Milwaukee rather than individual plant managers.
Automated Optical Inspection (AOI) System Market Segmentation
AOI system procurement patterns diverge sharply across technology tiers and end-user categories, with after-sales service intensity varying from predictive maintenance contracts in high-volume semiconductor fabs to break-fix arrangements in cost-sensitive PCB shops. Understanding these structural differences clarifies where vendor margins concentrate and which segments justify dedicated sales engineering resources.
Technology:
After-sales service intensity escalates dramatically with system complexity, as 3D tomographic platforms require quarterly calibration protocols and dedicated field service engineers while 2D systems operate with minimal vendor intervention.
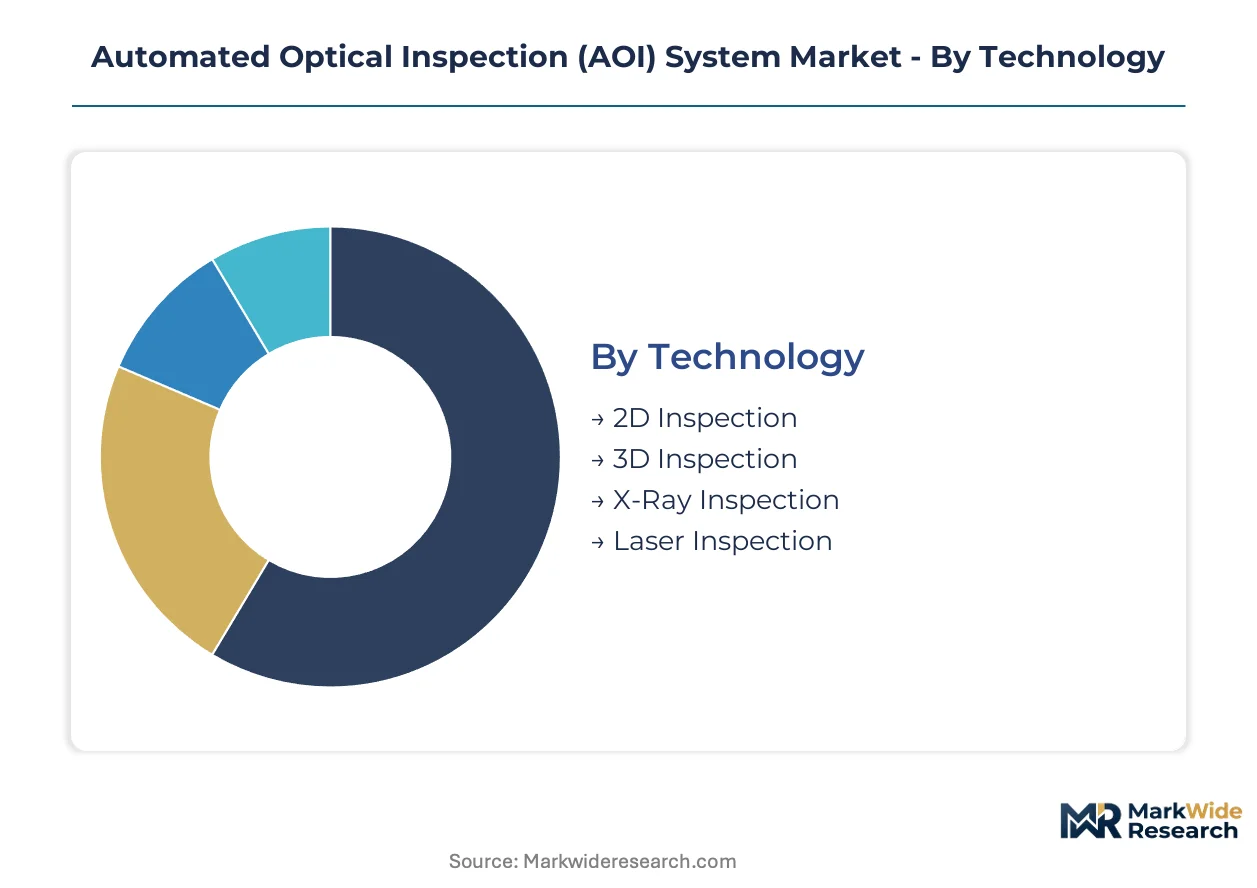
- 2D Inspection:Planar imaging systems using single-camera top-down capture dominate high-volume consumer electronics lines where defect libraries are standardized. Demand concentrates in Vietnam and Malaysia contract manufacturing clusters serving mobile phone assembly, constrained by margin pressure that limits upgrade budgets.
- 3D Inspection:Multi-angle structured-light systems reconstruct coplanarity and volumetric solder joint profiles through phase-shifting profilometry. Taiwan and South Korea semiconductor fabs absorb the majority of deployments as flip-chip packaging densities exceed 2D resolution limits.
- X-Ray Inspection:Penetrating radiation systems reveal hidden solder voids and BGA ball integrity beneath opaque components.
- Laser Inspection:Triangulation-based dimensional verification systems measure component height and warpage with sub-micron precision.
3D Inspection holds the largest share; momentum sits with X-Ray Inspection as advanced packaging architectures proliferate.
Application:
Cost tier stratification separates capital-intensive semiconductor wafer inspection from mid-tier automotive electronics and entry-level consumer PCB verification.
- Electronics Manufacturing:High-mix PCB assembly lines in Mexico and Eastern Europe deploy configurable AOI platforms with rapid recipe changeover capabilities. Tier-1 automotive suppliers in Germany drive specification tightening as camera module tolerances compress below 10 microns.
- Semiconductor Production:Wafer-level and advanced packaging inspection demands sub-50 nanometer defect detection using multi-sensor fusion architectures. Hsinchu and Pyeongtaek fab expansions absorb premium system capacity as node migration accelerates.
- Automotive Assembly:Electric vehicle power electronics and ADAS sensor modules require contaminant-free solder joints traceable through production records.
- PCB Inspection:Bare board and assembled PCB verification remains the volume foundation for entry-level 2D system deployments.
Electronics Manufacturing holds the largest share; momentum sits with Semiconductor Production.
End User:
Customer type determines procurement authority concentration, from centralized enterprise frame agreements at mega-EMS providers to distributed plant-level purchasing at fragmented Tier-1 suppliers.
- OEMs:Original equipment manufacturers in medical devices and aerospace verticals specify inspection protocols that cascade down supply chains through qualified vendor lists. FDA 21 CFR Part 820 compliance requirements in the US impose documentation burdens that favor established vendors with regulatory submission experience.
- Contract Manufacturers:Foxconn, Jabil, and Luxshare negotiate bundled hardware-software-maintenance contracts with per-inspection-unit pricing. These enterprise agreements are displacing traditional distributor relationships across Vietnam and India greenfield facilities.
- Tier-1 Suppliers:Component and subsystem providers serving automotive and industrial OEMs.
- Aftermarket Providers:Refurbishment and repair operations for warranty returns and electronics waste recovery.
OEMs hold the largest share; Contract Manufacturers are climbing the fastest.
Component:
Supply concentration in image sensors and specialized optics creates procurement risk that shapes system vendor sourcing strategies and inventory positioning.
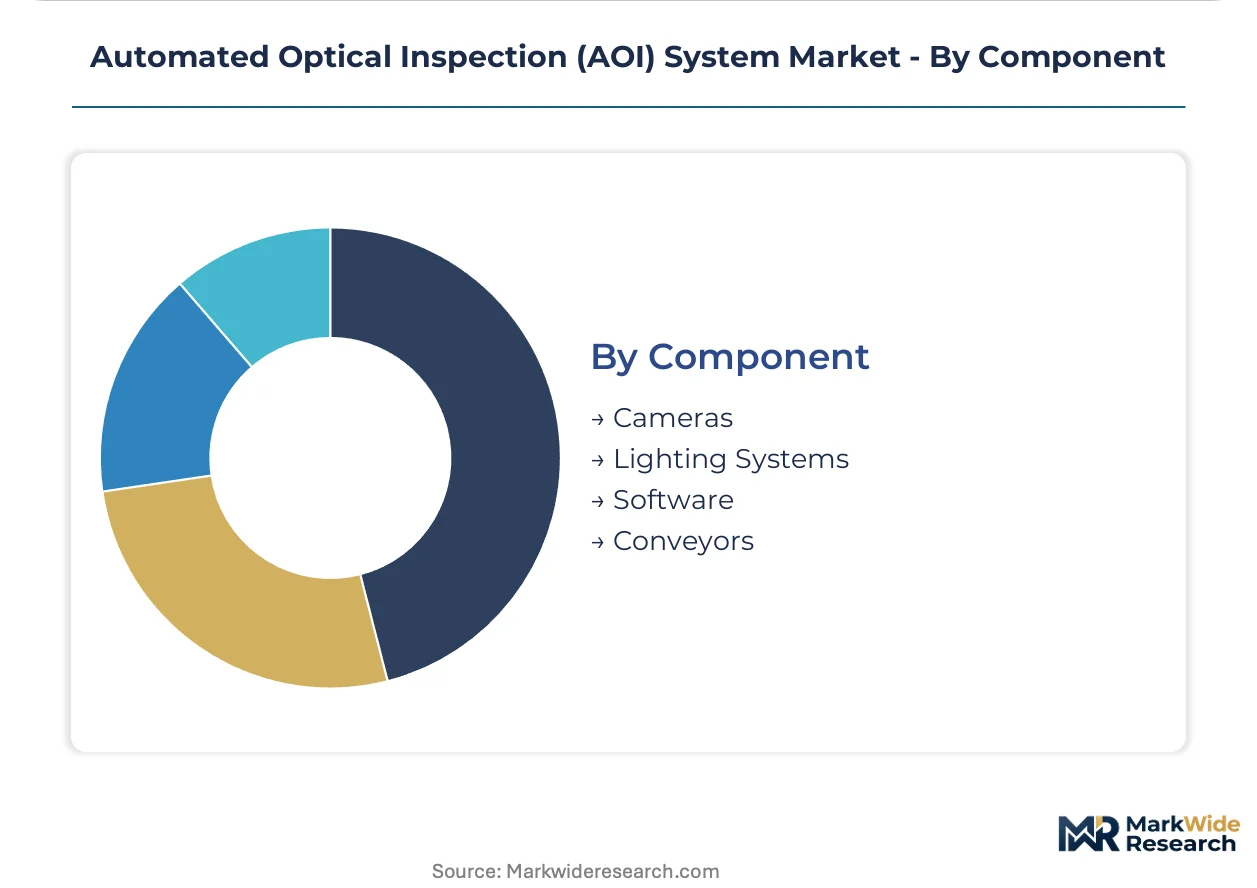
- Cameras:High-speed CMOS sensors from Sony and ON Semiconductor face 16-24 week lead times for 25-megapixel inspection variants. System vendors in Taiwan and Japan maintain strategic buffer stocks to mitigate delivery risk for semiconductor fab orders.
- Software:Machine-vision algorithms and MES integration layers differentiate vendor offerings and command recurring license revenue streams. Convolutional neural networks for false-positive reduction represent the primary competitive battleground.
- Lighting Systems:Structured LED arrays and programmable illumination controllers.
- Conveyors:Precision motion platforms and board handling mechanisms.
Cameras hold the largest share; momentum sits with Software.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR's GB/T certification requirements for SMT equipment create the primary regulatory friction shaping cross-border equipment flows into China. East Asian manufacturing clusters absorb the majority of high-speed 3D inspection deployments as semiconductor node migration accelerates below 5nm.
Taiwan
TSMC's Hsinchu fab expansions drive 40% of new wafer-level packaging inspection capacity. The National Development Council's semiconductor subsidy programs accelerate capital equipment depreciation schedules. Taichung and Tainan science parks concentrate multi-sensor fusion architectures for sub-50 nanometer defect detection.
South Korea
Samsung Foundry's Pyeongtaek complex commands premium 3D tomographic systems for flip-chip verification. MFDS medical device regulations cascade inspection protocol requirements through component supply chains. Suwon and Yongin electronics corridors host dedicated machine-vision engineering talent pools concentrated in two conglomerate ecosystems.
China
GB standards for electromagnetic compatibility add 4-6 months to market entry for non-domestic AOI suppliers. MIIT's dual carbon goals tighten energy efficiency requirements for inspection line operations. Suzhou and Shenzhen contract manufacturing clusters internalize quality control to satisfy Apple and NVIDIA supply chain liability terms.
Vietnam
Foxconn and Luxshare greenfield expansions in Bac Ninh and Hai Phong lack legacy inspection infrastructure. The Ministry of Industry and Trade's electronics manufacturing incentives attract EMS providers requiring full-fleet equipment deployments. Hai Phong port logistics corridors enable just-in-time component supply for high-mix PCB assembly lines.
Germany
REACH substance disclosure requirements extend to full bill-of-materials verification in automotive camera module assemblies. KBA automotive regulations tighten coplanarity tolerances below 10 microns for ADAS sensor production. Bavaria and Baden-Württemberg automotive supplier clusters drive specification tightening through qualified vendor list protocols.
Automated Optical Inspection (AOI) System Market Vendor Landscape
Specialized 3D inspection architects and diversified machine-vision conglomerates split the market along technology depth versus breadth vectors. The vendor base concentrates in three tiers: premium-tier semiconductor fab specialists, mid-tier automotive electronics suppliers, and cost-optimized consumer PCB assemblers. Dominant competitive moves include enterprise-wide frame agreements that bundle hardware-software-maintenance into per-inspection-unit pricing, and modular hardware platforms that upgrade existing 2D gantries rather than requiring full replacement.
Among Asia-Pacific equipment specialists, Koh Young Technology and Saki Corporation exemplify the 3D solder paste inspection archetype that controls high-mix PCB assembly lines across Southeast Asian contract manufacturing clusters. Cognex Corporation anchors the North American machine-vision segment through software integration capabilities with factory MES platforms. These three entities represent contrasting geographic and technological positioning strategies within a market where procurement authority concentrates at headquarters level in Taipei and Milwaukee.
| Leading Market Players |
|---|
| Camtek |
| Saki Corporation |
| Koh Young Technology |
| Cognex Corporation |
| Nordson YESTECH |
| Test Research |
| Viscom |
| KLA Corporation |
| Omron Corporation |
| Others |
Supply Flow & Price Mechanics
Hai Phong port logistics corridors transmit freight cost volatility directly into equipment landed costs, amplifying the spread between configured-to-order 3D systems and standard 2D platforms while concentrating vendor pricing power around semiconductor fab clusters in Taiwan and South Korea.
Pricing Analysis
The customization-premium spread separates semiconductor-grade 3D tomographic systems from entry-level 2D PCB inspection lines by a factor reflecting software integration depth and calibration protocol intensity. Pricing stratifies across premium, standard, and economy tiers anchored by after-sales service bundling, MES connectivity certification, and field engineer deployment guarantees. Cost compression in the 2D tier is intensifying because Vietnamese contract manufacturers negotiate enterprise frame agreements with per-inspection-unit pricing. Tier-1 automotive electronics suppliers in Germany exhibit the lowest price sensitivity due to qualified vendor list protocols that prioritize traceability over capital expenditure.
Supply Chain Analysis
Foxconn, Jabil, and Luxshare concentration in Bac Ninh and Hai Phong absorbs inspection equipment flows at volumes that reshape upstream component procurement. Sony and ON Semiconductor fabrication in Japan and the USA supplies high-speed CMOS sensors that feed from 16-24 week lead time schedules. Distribution runs through direct vendor-to-CM relationships displacing traditional distributor networks across Southeast Asia. Single-source vulnerability in 25-megapixel inspection camera sensors creates procurement risk that Taiwanese system vendors mitigate through strategic buffer stocks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through FDA 21 CFR Part 820 and China's GB/T certification requirements erects switching costs that protect incumbent positions against modular hardware disruptors.
For Market Incumbents: Harden software integration layers with factory MES platforms to deepen switching costs that lock out modular hardware challengers. Expand captive field service engineer pools in Taiwan and South Korea to defend against emerging Chinese equipment vendors exploiting GB/T certification shortcuts. Vertical integration into high-speed CMOS sensor buffer stocks mitigates Sony supply choke vulnerability. For New Entrants and Emerging Players: Build out AI-driven false-positive reduction software modules that differentiate against legacy rule-based inspection libraries in high-mix PCB lines. Target India's PLI scheme electronics manufacturing clusters where entry-level 2D inspection demand outpaces established vendor service capacity. Pursue software-first go-to-market positioning that bypasses capital-intensive hardware fabrication barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified machine-vision conglomerates seeking to divest non-core inspection divisions amid semiconductor fab capital intensity focus. Long-term viability centers on 3D tomographic architectures as flip-chip packaging proliferates in AI accelerators. Monitor TSMC and Samsung Foundry capex announcement velocity as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Hardware Platform Development | Enables 2D-to-3D gantry upgrades that capture mid-tier EMS budget cycles in Malaysia and Thailand. |
| AI-Driven Defect Library Training | Convolutional neural networks collapse rework rates that differentiate premium tiers from rule-based competitors. |
| Enterprise Frame Agreement Negotiation | Foxconn and Jabil consolidate procurement authority at headquarters level in Taipei and Milwaukee. |
| Regulatory Compliance Module Integration | REACH and SCIP database connectivity compresses sales cycles for German automotive supplier qualified vendor lists. |
| Strategic Component Buffer Stocking | Taiwanese vendors mitigate Sony CMOS sensor lead time risk to secure semiconductor fab order commitments. |
Methodological Framework
A standing panel of semiconductor fab equipment procurement managers, EMS quality directors, machine-vision software engineers, and automotive Tier 1 supplier manufacturing heads provided ongoing calibration against secondary validation from SEC equipment vendor filings, SEMI industry association reports, customs trade data for SMT equipment flows, and FDA 510(k) submission databases. Bottom-up unit deployment estimates triangulated against top-down fab capacity expansion announcements.
Scenario-bracketing framed analytical outputs across the projection horizon, modeling technology segmentation by 2D planar, 3D structured-light, and X-ray penetrating architectures alongside application splits across semiconductor production, electronics manufacturing, and automotive assembly. End-user dimensions captured OEM, contract manufacturer, and Tier 1 supplier procurement authority concentration. CAGRs derived from equipment deployment velocity tied to TSMC and Samsung Foundry node migration timelines and Vietnam greenfield facility commissioning schedules.
Practitioners should monitor CMOS sensor lead time normalization, GB/T certification processing velocity, and Foxconn frame agreement renegotiation cycles for early signals of vendor margin compression or procurement authority redistribution. Quarterly review of semiconductor fab capex guidance and EMS greenfield facility announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Indoor Air Quality Multi-Pollutant Sensor Calibration Test Equipment Market
Test and Measurement
Ground Resistance Testers Market
Test and Measurement
Tensile Testing Machine Market
Test and Measurement
Bursting Strength Tester Market
Test and Measurement
Global Reflux Testing Products Market
Test and Measurement
Automated Optical Inspection Market
Test and Measurement
Photometer and Calorimeter Market
Test and Measurement
Semiconductor Metrology and Inspection Market
Test and Measurement
Battery CT Inspection Market
Test and Measurement
India Electrical Testing Services Market
Test and Measurement
Electronic Test Instrument Market
Test and Measurement
Asia-Pacific Laser Interferometer Market
Test and Measurement
Pump Testers Market
Test and Measurement
Continuous Level Measurement Market
Test and Measurement
Structure Tester Market
Test and Measurement
Calibration Solutions Market