
 Africa CNG and LPG Vehicle Market | 2026-2036
Africa CNG and LPG Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Africa CNG and LPG Vehicle Market Outlook
The Africa CNG and LPG vehicle market is restructuring around a sharp split between premium OEM-built dual-fuel systems and commodity retrofit kits assembled from imported components. AB Volvo dominates the premium segment with factory-integrated CNG powertrains for heavy-duty logistics routes. Tata Motors Limited competes through cost-optimized LPG conversions for commercial three-wheelers in East African cities. MAN Truck & Bus anchors the middle tier with modular CNG bus platforms that balance compliance and capital outlay.
CNG and LPG vehicles are internal combustion engine platforms modified to burn compressed natural gas or liquefied petroleum gas through dedicated fuel injection and storage systems, typically operating at pressures of 200-250 bar for CNG or utilizing cryogenic tanks for LPG, with the primary purpose of reducing particulate emissions and fuel expenditure in high-mileage operations. The passenger car segment remains nascent due to sparse retail refueling, while commercial trucks generate the dominant revenue pool through long-haul freight contracts. Three-wheelers represent the fastest-expanding category as informal transport operators seek LPG alternatives to volatile gasoline pricing.
South Africa's National Regulator for Compulsory Specifications enforces pressure vessel standards for onboard gas storage, while Nigeria's Department of Petroleum Resources governs conversion workshop licensing and cylinder recertification cycles. Kenya's Energy and Petroleum Regulatory Authority sets LPG dispensing protocols that directly shape station rollout economics. Fleet operators must monitor how these overlapping regimes affect cross-border vehicle resale values and conversion warranty validity.
Market Dynamics
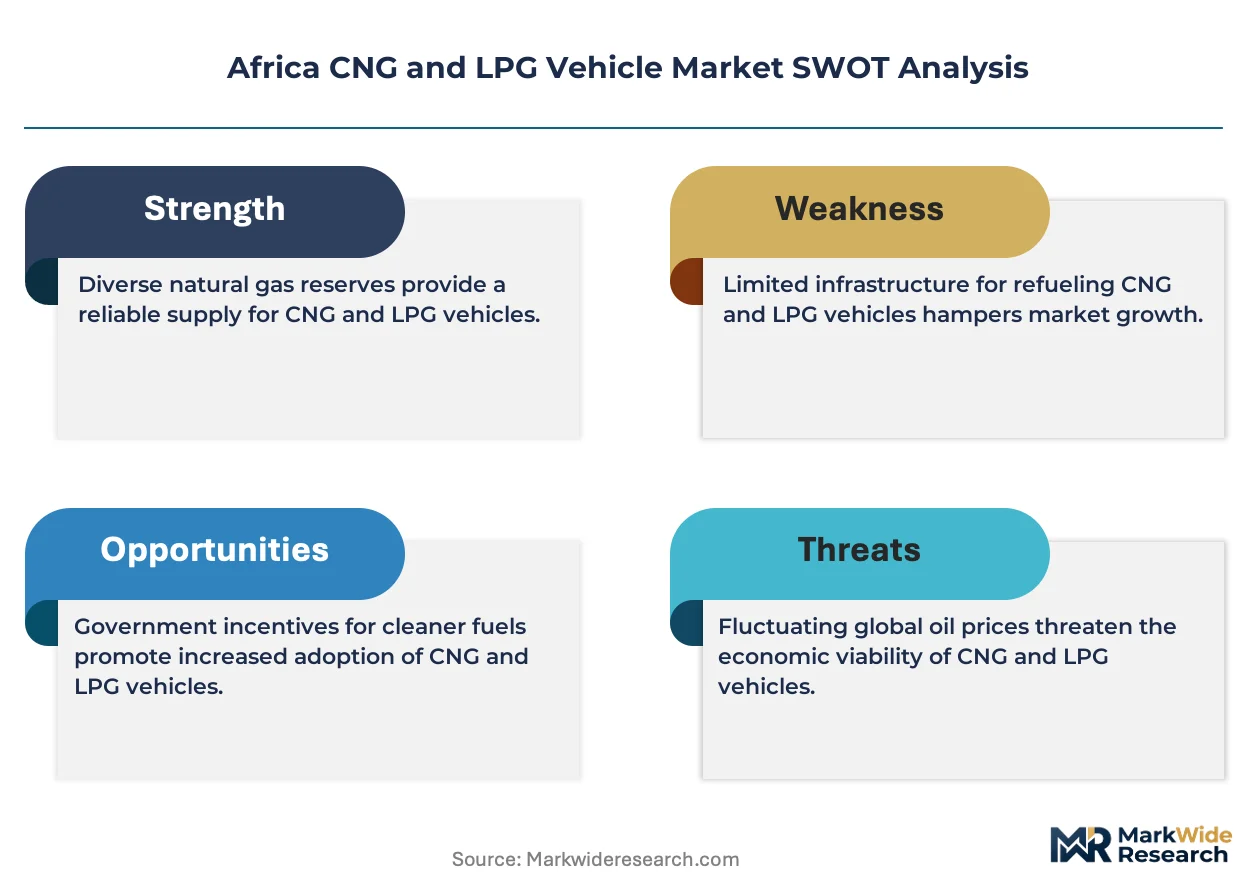
The Africa CNG and LPG vehicle market is bifurcating around refueling infrastructure density, with urban corridors attracting fleet conversions while rural operators remain locked out by station scarcity and cylinder recertification backlogs.
Growth Catalysts
- Nigeria's LPG expansion policy:The Department of Petroleum Resources has accelerated cylinder manufacturing licensing, cutting import dependency for conversion kits in Lagos and Port Harcourt corridors.
- Carbon tax incentives:South Africa's Department of Transport cleaner fuel vehicle rebates under its carbon tax regime are compressing payback periods for heavy-duty CNG bus operators.
- Three-wheeler LPG retrofit demand:Informal transport operators in Nairobi and Dar es Salaam are driving fastest-category growth as gasoline price volatility erodes profit margins.
Market Restraints
- Steel cylinder input volatility:Type-2 composite cylinder costs fluctuate with global carbon fiber supply, squeezing conversion workshop margins in import-dependent markets.
- Cross-border regulatory friction:Kenya's Energy and Petroleum Regulatory Authority LPG dispensing protocols conflict with Tanzanian pressure vessel standards, fragmenting East African fleet resale values.
- Electric bus substitution:Battery-electric pilot programs in Cape Town and Johannesburg are capturing municipal procurement budgets that previously targeted CNG platforms.
Strategic Opportunities
- Ethiopia's underpenetrated corridor:Addis Ababa's formalizing minibus sector presents first-mover conversion potential before LPG infrastructure matures.
- Biogas-CNG hybrid systems:Agricultural waste-to-fuel digestion technology convergence offers captive fuel production for sugar estate haulage fleets in KwaZulu-Natal.
- Mobile refueling units:Skid-mounted LPG dispensing systems are opening informal settlement routes where fixed station economics fail.
Industry Challenges
- Certified installer scarcity:South Africa's National Regulator for Compulsory Specifications pressure vessel certification backlog exceeds eighteen months, throttling conversion throughput.
- Legacy diesel fleet integration:Engine control module reprogramming complexity for Euro III-era trucks is forcing operators into premature asset retirement rather than CNG retrofit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa CNG and LPG Vehicle Market |
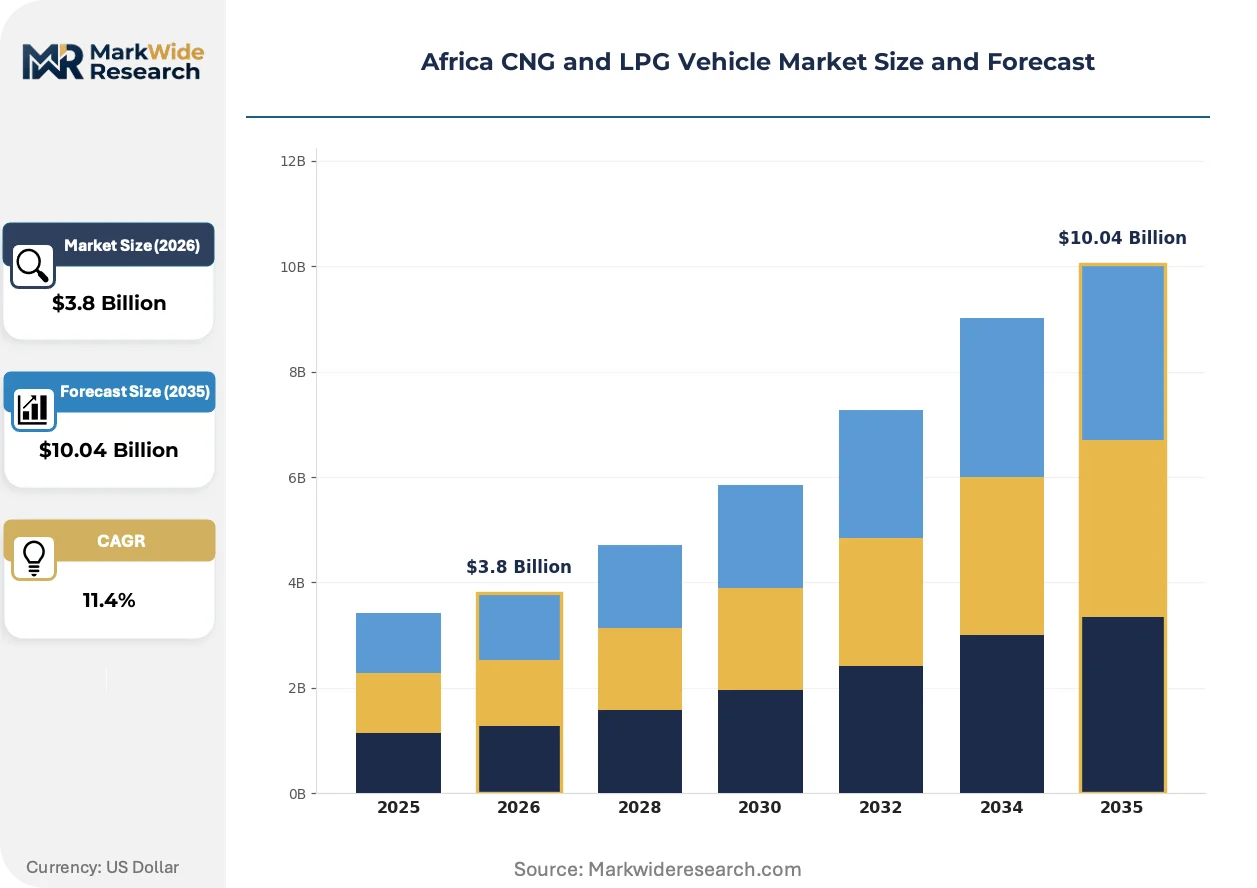
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: CNG, LPG, Biogas, Hydrogen Vehicle Type: Passenger Cars, Commercial Trucks, Buses, Three-Wheelers End User: Public Transport, Logistics Companies, Private Fleet, Ride-Sharing Services Application: Urban Transport, Freight Transportation, Emergency Services, Waste Collection |
| Companies Covered | AB Volvo, Ford Motor Company, Tata Motors Limited, MAN Truck & Bus, Volkswagen AG, Hyundai Motor Company, Suzuki Motor Corporation, Scania AB, IVECO S.p.A, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa CNG and LPG Vehicle Market Strategic Shifts
Technology trajectories in the Africa CNG and LPG vehicle market are compressing around dual-fuel system reliability and digital fuel monitoring, with operators demanding real-time consumption transparency to justify conversion capital.
Sequential gas injection systems with dedicated ECU mapping are overtaking conventional mixer-based conversions in Nigerian heavy-duty applications. Lagos-based logistics fleets are adopting these systems at accelerating pace as cylinder recertification intervals extend. The technology is overtaking carbureted retrofits in the premium conversion tier, compressing warranty claim rates and reshaping workshop capability requirements.
South Africa's carbon tax regime amendments are tightening emissions benchmarking for commercial vehicle operators. The industrial consequence is accelerated depreciation of unconverted diesel assets in corporate fleets. Heavy-duty bus procurement in Gauteng province is most affected, with state-owned transport entities now mandating factory-integrated CNG powertrains in new tenders.
Fleet procurement patterns are consolidating around total cost of ownership contracting rather than upfront vehicle acquisition. Long-haul freight operators in the Durban-Johannesburg corridor are shifting to fuel-inclusive lease structures where conversion risk transfers to specialist lessors. This restructuring is most visible among refrigerated transport verticals where fuel cost precision determines contract profitability.
Africa CNG and LPG Vehicle Market Segmentation
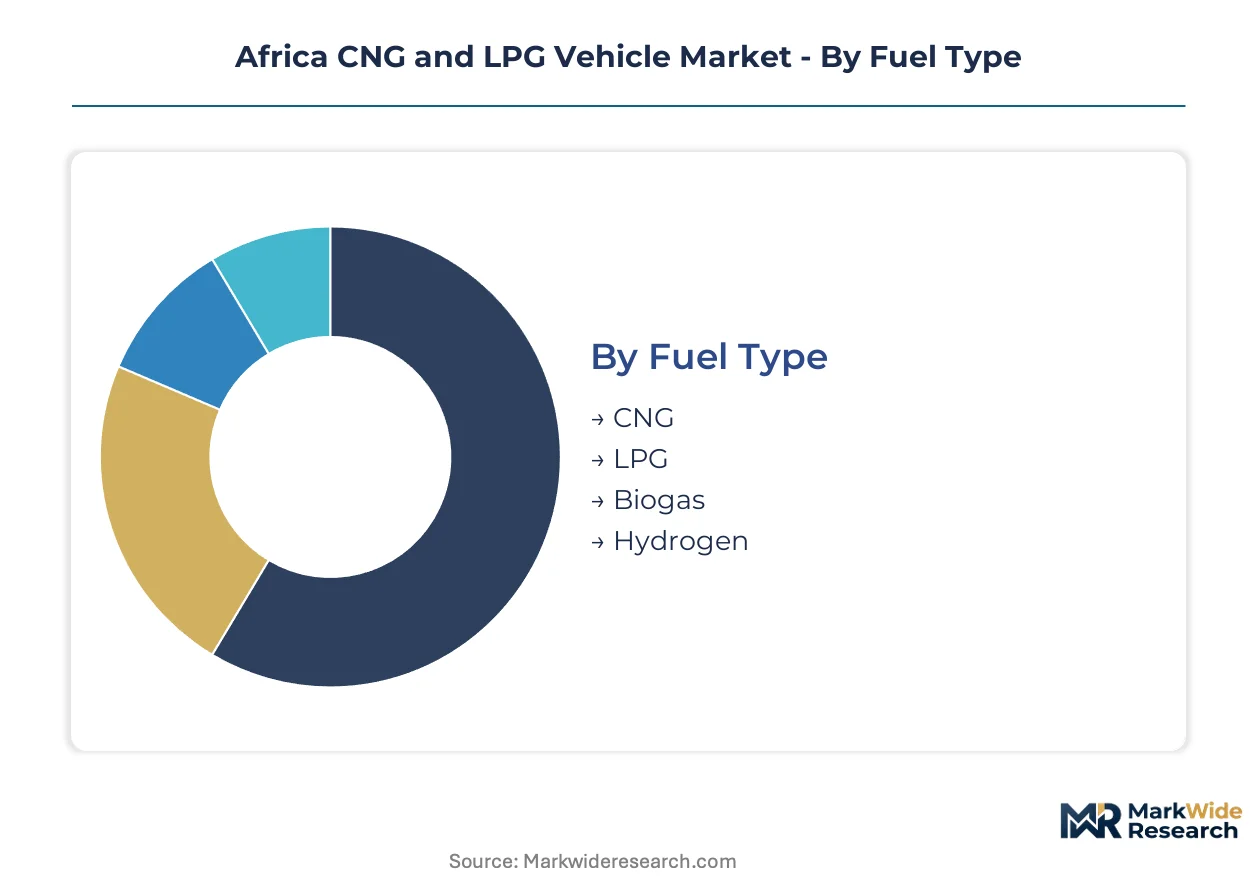
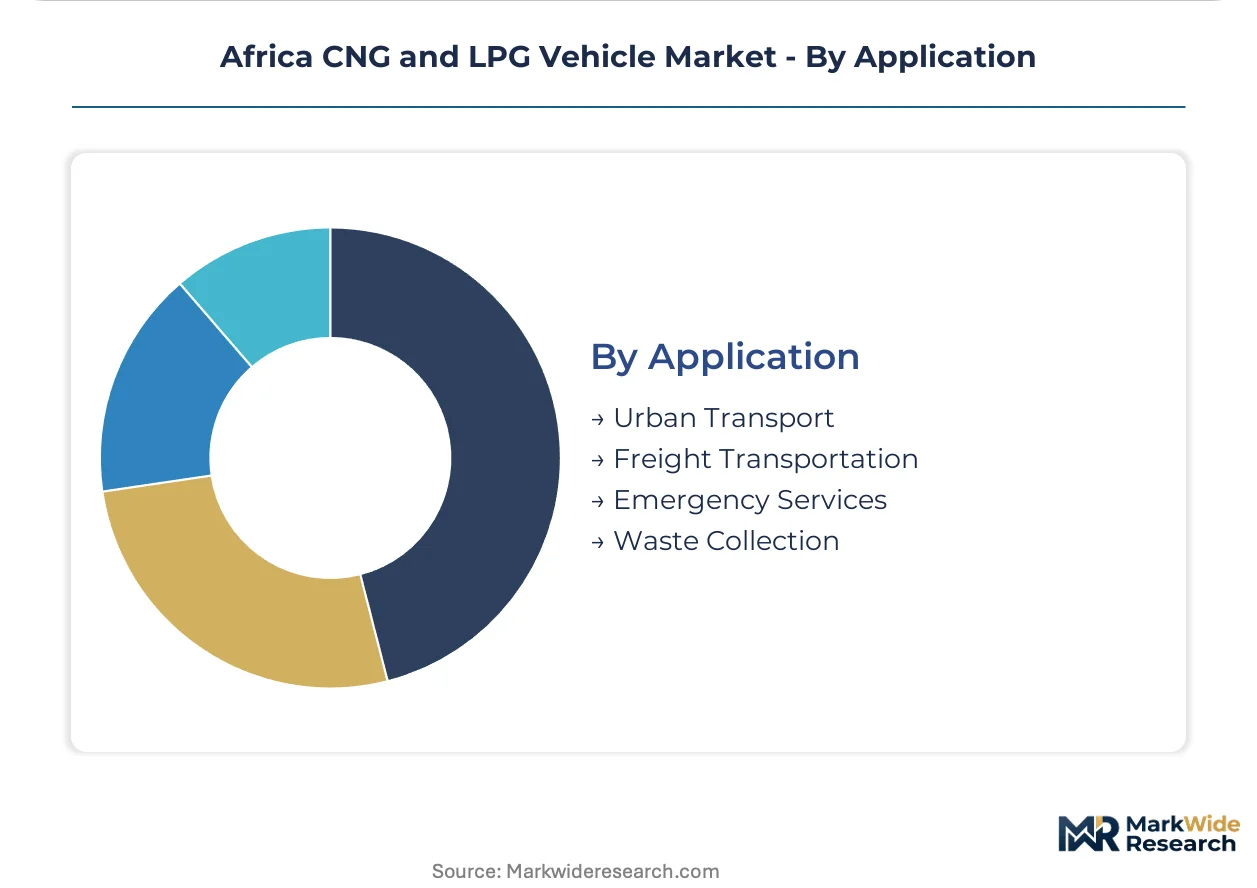
Segmentation in the Africa CNG and LPG vehicle market reveals how fuel infrastructure, fleet economics, and regulatory pressure concentrate demand across distinct operational profiles. Understanding these splits exposes where conversion capital flows and where station rollout economics determine viability.
Fuel Type:
The volume-premium split separates established hydrocarbon fuels from emerging alternatives, with infrastructure maturity dictating deployment pace and capital intensity.
- CNG:Compressed natural gas systems operate at 200-250 bar through Type-2 composite cylinders, dominating heavy-duty logistics in South Africa's carbon-tax-regulated corridors where factory-integrated powertrains command fleet procurement. Municipal bus tenders in Gauteng now mandate CNG for new heavy-duty acquisitions.
- LPG:Liquefied petroleum gas utilizes cryogenic or pressurized storage at lower pressures, capturing three-wheeler retrofits in Nairobi and Dar es Salaam where informal operators seek refuge from gasoline price volatility. Port Harcourt's expanding cylinder manufacturing capacity is compressing conversion kit costs.
- Biogas:Agricultural waste-to-fuel digestion systems offer captive production for sugar estate haulage in KwaZulu-Natal, though scale constraints limit deployment beyond estate boundaries.
- Hydrogen:Fuel cell platforms remain pre-commercial across African markets, with pilot activity concentrated in South African mining corridors testing platinum-catalyzed applications.
Today's leader: LPG. Tomorrow's challenger: Biogas.
Vehicle Type:
Application intensity and daily mileage separate segments where fuel cost precision justifies conversion investment from those where sparse retail infrastructure blocks adoption.
- Commercial Trucks:Long-haul freight contracts in the Durban-Johannesburg corridor generate dominant revenue pools through fuel-inclusive lease structures where conversion risk transfers to specialist lessors. Refrigerated transport verticals demand total cost of ownership precision.
- Three-Wheelers:Informal transport operators across East African cities are expanding most quickly as LPG retrofit kits undercut gasoline operating economics. Dar es Salaam's boda-boda associations are driving fastest-category growth through collective procurement.
- Buses:Public transport fleets in Lagos and Nairobi are converting diesel platforms to cut operating costs, though electric bus pilots in Cape Town and Johannesburg are capturing municipal budgets previously targeting CNG.
- Passenger Cars:Sparse retail refueling infrastructure keeps this segment nascent, with adoption limited to dual-fuel OEM models in South Africa's premium urban corridors.
Revenue concentrates in trucks. Volume expansion belongs to three-wheelers.
End User:
Procurement sophistication and balance sheet capacity determine whether operators absorb conversion risk or delegate it through lease structures and service contracts.
- Logistics Companies:Corporate refrigerated transport operators in the Durban-Johannesburg corridor are shifting to fuel-inclusive lease structures where conversion risk transfers to specialist lessors. Contract profitability hinges on fuel cost precision.
- Public Transport:State-owned entities in Gauteng province now mandate factory-integrated CNG powertrains in new tenders, accelerated by South Africa's carbon tax regime amendments tightening emissions benchmarking.
- Private Fleet:Small and mid-sized operators face certified installer scarcity, with South Africa's National Regulator for Compulsory Specifications pressure vessel certification backlog exceeding eighteen months.
- Ride-Sharing Services:Platform-mediated driver networks in Lagos and Nairobi are experimenting with LPG conversions through association-level procurement, though individual drivers lack capital for upfront conversion costs.
Institutional procurement dominates. Informal aggregation is emerging.
Application:
Route predictability and depot return patterns dictate whether fixed station economics or mobile refueling solutions prove viable for each operational model.
- Freight Transportation:Long-haul corridors with established station density attract CNG conversion investment, while cross-border routes face regulatory fragmentation between Kenyan and Tanzanian pressure vessel standards.
- Urban Transport:Fixed-route bus operations in Lagos and Nairobi support dedicated depot refueling infrastructure, enabling fleet-wide conversion programs with centralized cylinder recertification.
- Waste Collection:Municipal fleets with return-to-depot patterns are piloting CNG conversions in South African metros, though procurement budgets face competition from electric alternatives.
- Emergency Services:Reliability requirements and unpredictable routing keep this segment diesel-dependent, with conversion interest limited to non-critical support vehicles.
Depot-captive routes lead. Variable routing lags.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nigeria's LPG corridor expansion outpaces South Africa's carbon-tax-driven CNG procurement, while East African three-wheeler conversions accelerate fastest in informal transport clusters.
Nigeria
Lagos and Port Harcourt logistics operators are converting diesel trucks to LPG as cylinder manufacturing licensing accelerates under Department of Petroleum Resources oversight. The DPR's streamlined conversion workshop certification is cutting import dependency for retrofit kits. The Lagos-Ibadan freight corridor now hosts the densest LPG refueling station network outside South Africa.
South Africa
Gauteng province's municipal bus tenders now mandate factory-integrated CNG powertrains under carbon tax regime amendments tightening commercial vehicle emissions benchmarking. The National Regulator for Compulsory Specifications enforces Type-2 composite cylinder standards that exceed eighteen-month certification backlogs. Durban-Johannesburg refrigerated transport fleets are shifting to fuel-inclusive lease structures with specialist lessors.
Kenya
Nairobi's matatu associations are piloting collective LPG procurement for diesel platform conversions as gasoline price volatility erodes operator margins. The Energy and Petroleum Regulatory Authority sets dispensing protocols that shape station rollout economics in the capital corridor. Eastleigh and Industrial Area transport hubs are emerging as conversion workshop clusters serving boda-boda and tuk-tuk networks.
Tanzania
Dar es Salaam's boda-boda cooperatives are driving fastest-category three-wheeler LPG retrofit demand through association-level kit procurement. Pressure vessel standards diverge from Kenyan protocols, fragmenting cross-border fleet resale values. The Ubungo and Temeke municipal zones concentrate informal settlement mobile refueling unit deployment where fixed station economics fail.
Ethiopia
Addis Ababa's formalizing minibus sector presents first-mover conversion potential before LPG infrastructure matures beyond pilot depot installations. The Ministry of Transport's draft clean fuel vehicle guidelines are awaiting finalization to unlock fleet procurement incentives. Merkato and Meskel Square transport terminals are emerging as early adopter clusters for LPG retrofit trials.
Africa CNG and LPG Vehicle Market Competitive Environment
Top-tier vendors anchor factory-integrated CNG powertrains for heavy-duty logistics, while mid-tier assemblers compete on cost-optimized LPG conversions for commercial three-wheelers. The market structure bifurcates around premium OEM-built dual-fuel systems versus commodity retrofit kits assembled from imported components. Three strategic archetypes dominate: European heavy-duty specialists with modular bus platforms, Asian volume manufacturers with conversion-optimized small commercial vehicles, and regional kit integrators with localized cylinder recertification capabilities. Competitive moves concentrate on strategic partnerships with conversion workshop networks and geographic expansion through fleet lessor alliances.
Within the premium-tier OEM segment, AB Volvo and MAN Truck & Bus occupy positions exemplifying factory-integrated CNG powertrain architecture for carbon-tax-regulated corridors. Tata Motors Limited sits within the volume-manufacturer archetype, representing cost-optimized LPG conversion platforms for East African three-wheeler markets. These three entities collectively illustrate how competitive positioning splits between compliance-driven heavy-duty procurement and price-sensitive informal transport retrofit demand.
| Leading Market Players |
|---|
| AB Volvo |
| Ford Motor Company |
| Tata Motors Limited |
| MAN Truck & Bus |
| Volkswagen AG |
| Hyundai Motor Company |
| Suzuki Motor Corporation |
| Scania AB |
| IVECO S.p.A |
| Others |
Value Chain & Pricing Dynamics
Carbon fiber composite pricing indices cascade through Type-2 cylinder manufacturing costs, compressing conversion workshop margins in import-dependent African markets while Nigerian domestic cylinder licensing reshapes price floors for LPG retrofit kits.
Pricing Analysis
Capacity additions in Nigeria are reshaping price floors for LPG conversion kits as Port Harcourt cylinder manufacturing expands. Three-tier pricing structure across premium OEM-integrated, certified aftermarket, and informal workshop tiers separates factory CNG powertrains from commodity retrofit assemblies. Price differentiation centers on certification grade under South Africa's National Regulator for Compulsory Specifications and volume scale of fleet procurement. Pricing pressure stems from steel and carbon fiber input volatility squeezing workshop margins. Informal three-wheeler operators exhibit highest price sensitivity, while refrigerated logistics fleets in the Durban-Johannesburg corridor absorb premium tier costs for total cost of ownership precision.
Supply Chain Analysis
Type-2 composite cylinder supply rests on Chinese and South Korean specialty manufacturers, with carbon fiber feedstock anchored in Japanese and European precursor production. Steel cylinder fabrication draws from Indian and Turkish metalworking centers serving Nigerian and Kenyan conversion markets. ECU mapping hardware and sequential injection components source from German and Italian automotive electronics specialists. Single-source vulnerability concentrates in carbon fiber supply for premium CNG storage systems. Distribution runs through regional conversion workshop networks certified under national pressure vessel regimes, with Lagos, Nairobi, and Johannesburg anchoring kit assembly and installer training clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on cylinder manufacturing localization compressing import dependency and carbon tax incentives elevating premium-tier procurement in South African corridors.
For Market Incumbents: Deploy certification capacity expansion to capture the eighteen-month backlog in South Africa's pressure vessel installer pipeline. Secure backward integration into Nigerian cylinder manufacturing through licensing partnerships with Port Harcourt fabricators. Battery-electric bus pilots in Cape Town and Johannesburg threaten CNG platform procurement budgets; anchor fleet relationships through fuel-inclusive lease structures that transfer conversion risk. For New Entrants and Emerging Players: Enter via mobile refueling unit deployment in Dar es Salaam's informal settlement corridors where fixed station economics fail. Target Ethiopia's underpenetrated minibus sector before LPG infrastructure matures beyond pilot installations. Association-level procurement through boda-boda cooperatives offers the most penetrable channel structure, with collective kit buying circumventing individual operator capital constraints. For Investors and Strategic Acquirers: Asymmetric upside sits with regional conversion workshop networks possessing certified installer capacity and established fleet lessor alliances. Long-term viability favors entities controlling both cylinder supply and downstream installation certification across multiple national regulatory regimes. Watch biogas-CNG hybrid pilot outcomes in KwaZulu-Natal agricultural corridors as inflection indicator for captive fuel production models.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cylinder Manufacturing | Port Harcourt licensing expansion cuts import dependency for Nigerian conversion workshops. |
| Certified Installer Network Expansion | South Africa's eighteen-month NRCS backlog creates scarcity premium for approved workshops. |
| Mobile Refueling Unit Deployment | Skid-mounted LPG systems unlock informal settlement routes in Dar es Salaam's Ubungo zone. |
| Fuel-Inclusive Lease Structuring | Durban-Johannesburg refrigerated fleets transfer conversion risk to specialist lessors. |
| Biogas-CNG Hybrid Pilot Development | KwaZulu-Natal sugar estate digestion trials test captive agricultural waste-to-fuel production. |
Study Parameters
Multiple input streams — fleet operator interviews, conversion workshop site assessments, regulatory filing analysis, and trade flow databases — were reconciled to construct market estimates. Primary discussions engaged logistics procurement managers, transport association leaders, cylinder manufacturing technical directors, and national petroleum regulatory officials across Nigeria, South Africa, Kenya, and Tanzania. Secondary validation drew from Department of Petroleum Resources licensing records, National Regulator for Compulsory Specifications certification databases, Energy and Petroleum Regulatory Authority dispensing protocol documents, and vehicle registration data from national transport authorities. Bottom-up triangulation of conversion kit shipments and top-down reconciliation of fleet procurement budgets anchored volume estimates.
Data-stream reconciliation across the projection horizon applied segment-specific growth drivers to each fuel type, vehicle category, and end-user archetype. The analytical framework modeled CNG and LPG adoption separately through infrastructure density thresholds, carbon tax incentive elasticity, and gasoline price volatility exposure. Vehicle segmentation incorporated daily mileage intensity, depot return patterns, and cross-border regulatory compatibility. CAGRs were derived from infrastructure rollout timelines, fleet replacement cycles, and policy implementation pacing rather than extrapolation of historical trends.
Inputs from national petroleum regulators and transport department officials were available through the study window; gaps in informal sector operator financial records introduce uncertainty bands around three-wheeler retrofit volume estimates. Forecasts reflect documented assumptions regarding cylinder manufacturing localization pace and carbon tax regime amendment implementation. Regulatory protocol divergence between Kenyan and Tanzanian pressure vessel standards, electric bus pilot budget capture, and biogas digestion technology cost curves constitute specific revision triggers. A small set of infrastructure deployment milestones and policy finalization events warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuel Vehicles
Fuel Cell Vehicle (FCV) Market
Alternative Fuel Vehicles
Global Green Vehicles Market
Alternative Fuel Vehicles
China Zero Emission Vehicle Market
Alternative Fuel Vehicles
CNG Tanks Market
Alternative Fuel Vehicles
Japan Next Generation Vehicle Market
Alternative Fuel Vehicles
Zero Emission Vehicle Market
Alternative Fuel Vehicles
Fuel Caddy Market
Alternative Fuel Vehicles
CNG Vehicles Market
Alternative Fuel Vehicles
Flex-Fuel Vehicle Market
Alternative Fuel Vehicles
Hydrogen Fuel Vehicle Market
Alternative Fuel Vehicles
Alternative Fuel Vehicle (AFV) Market
Alternative Fuel Vehicles
India CNG Vehicles Market
Alternative Fuel Vehicles
Automotive Gas Cylinder Market
Alternative Fuel Vehicles
Dual Fuel Engine Market
Alternative Fuel Vehicles
Hydrogen Internal Combustion Engine (ICE) Market
Alternative Fuel Vehicles
UK New Energy Vehicle TIC Services Market