
 Organic Bananas Market | 2026-2036
Organic Bananas Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Bananas Market Analysis
Precision agriculture and blockchain traceability is tilting how organic bananas move from farm to shelf. Dole Food Company leverages its vertically integrated Latin American operations to sustain year-round supply reliability. Chiquita Brands International anchors its competitive stance through proprietary ripening technology that extends shelf life in North American distribution networks. Fresh Del Monte Produce competes by controlling port-to-retailer cold chain logistics across multiple hemispheres.
Organic bananas are Cavendish cultivars grown without synthetic pesticides, herbicides, or genetically modified organisms, certified under national or international organic standards that mandate soil health management and biodiversity conservation; their primary commercial purpose is to serve retail and foodservice buyers seeking residue-free fruit with documented provenance. Fair Trade certification commands premium positioning in European supermarkets where ethical sourcing protocols influence procurement decisions. Online Retailers represent the fastest-growing distribution channel as direct-to-consumer subscription models reshape purchase frequency and basket composition. Eco-Friendly Packaging is displacing conventional plastic formats as retailer sustainability scorecards tighten material specifications.
The USDA National Organic Program governs certification and labeling standards for organic bananas sold in the United States, while the EU Organic Regulation establishes equivalent requirements across European member states, and IFOAM Organics International provides harmonized baseline criteria that facilitate cross-border trade recognition. These frameworks shape demand by determining which production systems qualify for premium pricing and which supply origins gain market access. Stakeholders must monitor evolving equivalency agreements between major certifying jurisdictions to anticipate sourcing eligibility shifts.
Market Dynamics
Blockchain traceability systems are restructuring how organic bananas move through supply chains, forcing stakeholders to invest in digital infrastructure that validates provenance claims from Ecuadorian farms to European retail shelves.
Growth Catalysts
- EU Organic Regulation:The regulation's stringent certification requirements create defensible quality tiers that justify premium pricing in German and French supermarket chains, accelerating retailer investment in dedicated organic produce sections.
- Precision agriculture:Soil health monitoring technologies enable Latin American growers to document compliance with biodiversity conservation mandates, reducing audit friction and accelerating market access for certified shipments.
- Foodservice sector:Hotel and restaurant procurement teams in Scandinavia are mandating residue-free fruit with documented provenance, pulling volume through certified channels that bypass conventional wholesale markets.
Market Restraints
- Input cost volatility:Organic fertilizer prices fluctuate with natural gas markets, compressing grower margins in Costa Rica and Colombia where synthetic alternatives are prohibited under certification rules.
- Supply concentration risk:Overreliance on Ecuadorian port infrastructure creates chokepoint vulnerability; container delays at Guayaquil ripple through cold chains and shorten effective retail shelf life.
- Technical limitation:Cavendish cultivar genetic uniformity leaves organic production exposed to Panama disease TR4, with no certified-resistant replacement variety commercially available at scale.
Strategic Opportunities
- Direct-to-consumer subscriptions:Online retailers in the United Kingdom are building weekly delivery models that reshape purchase frequency and capture higher margins than conventional wholesale channels.
- Regulatory tailwind:The EU Green Deal's packaging waste directives are accelerating retailer adoption of compostable materials, creating first-mover advantages for suppliers with certified biodegradable formats.
- Technology convergence:Ripening room automation combined with IoT humidity sensors is virtualizing quality control, enabling distributors to guarantee specific color-stage deliveries to foodservice buyers.
Industry Challenges
- Certification timeline compression:USDA National Organic Program conversion periods require three years of documented synthetic-free cultivation, blocking rapid supply response to demand spikes in North American markets.
- Skill scarcity in cold chain management:Specialized technicians who can maintain organic integrity through port-to-retailer temperature protocols are concentrated in legacy banana logistics networks, constraining new entrant expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Bananas Market |
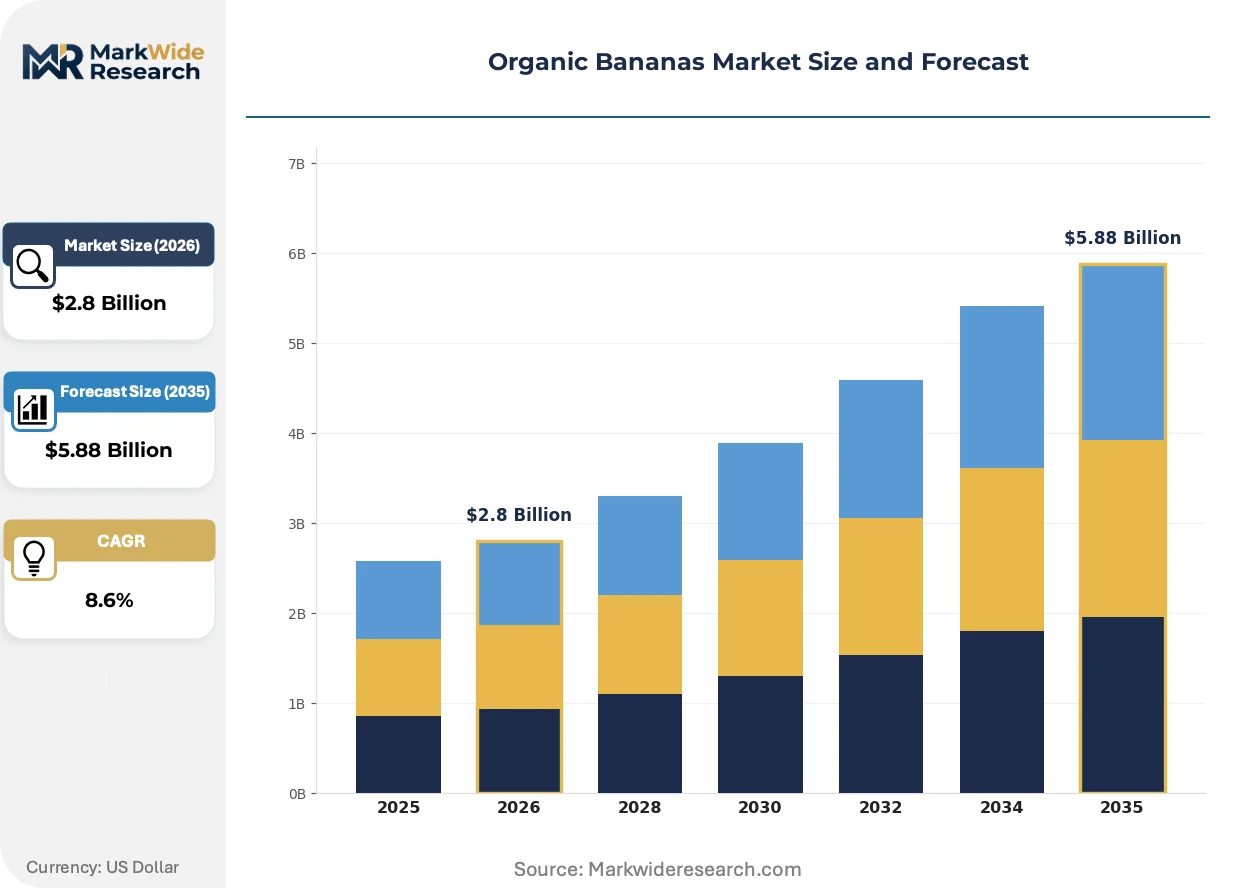
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fair Trade, Baby Bananas, Plantains, Sliced Bananas Distribution Channel: Supermarkets, Online Retailers, Farmers' Markets, Specialty Stores Packaging Type: Loose, Boxes, Bags, Eco-Friendly Packaging End Use: Juices, Snacks, Salads, Baking |
| Companies Covered | Dole Food Company, Chiquita Brands International, Fresh Del Monte Produce, Organics Unlimited, Fyffes, Compagnie Fruitiere, AgroAmerica, GrupoAcon, Grupo Iren, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Bananas Market Emerging Trajectories
Digitization is penetrating organic banana supply chains at multiple points simultaneously, from farm-level soil sensors to retail-facing provenance apps that convert certification compliance into consumer-facing transparency.
Blockchain-based traceability platforms are virtualizing documentation workflows that previously required paper certificates and manual verification. German supermarket chains are requiring suppliers to integrate with their proprietary tracking systems by 2025. This infrastructure investment is compressing the time between harvest and shelf placement while reducing fraud exposure in multi-handler supply chains.
REACH chemical restrictions in the European Union are tightening residue testing protocols for imported produce, forcing exporters to adopt pre-shipment verification laboratories. The industrial consequence is a bifurcation between suppliers with in-house testing capability and those dependent on third-party services. Latin American packing stations are responding by consolidating around ports with certified laboratory access, reshaping export geography.
Subscription-based procurement is displacing spot-market purchasing among urban consumers in the United Kingdom and Netherlands. Direct-to-consumer platforms are capturing household buyers who prioritize convenience and provenance transparency over price comparison. This channel shift is most visible in London and Amsterdam metropolitan areas, where delivery density supports weekly box-model economics that bypass traditional retail markup structures.
Organic Bananas Market Segmentation
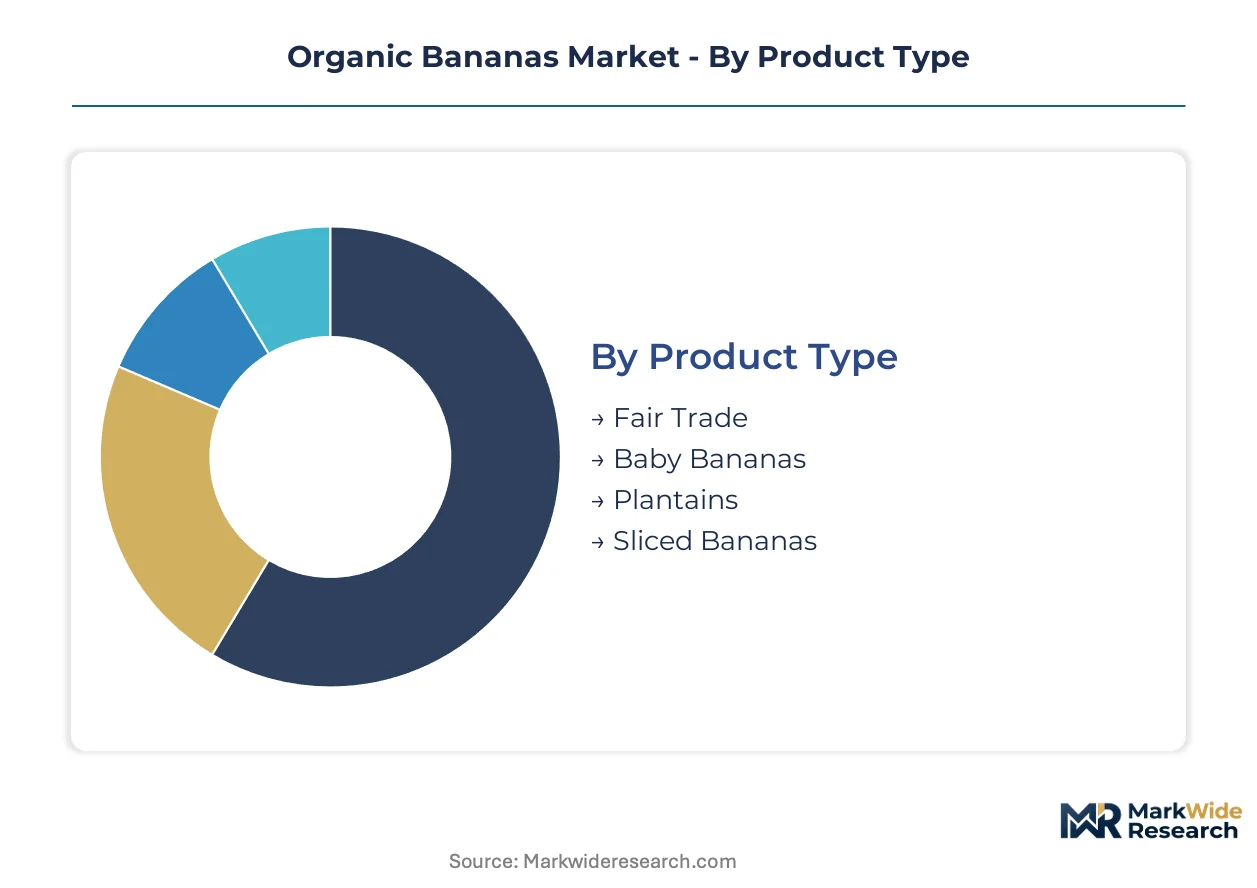
Organic banana segmentation reveals how certification tiers, channel economics, and packaging specifications fragment demand across distinct buyer workflows. Each category maps to separate procurement protocols and margin structures that shape supplier positioning.
Product Type:
Mature segments dominate volume throughput while emerging formats capture premium positioning through convenience innovation.
- Fair Trade:Dual-certified organic and Fair Trade bananas command price premiums in German and French retail chains where ethical sourcing protocols influence procurement decisions. Scandinavian foodservice buyers mandate this certification for hotel and restaurant contracts, pulling volume through dedicated supply channels that bypass conventional wholesale markets.
- Baby Bananas:Smaller cultivars such as Manzano and Lady Finger varieties serve specialty retail and foodservice segments seeking portion-controlled formats for children's menus and premium snack applications. Demand concentrates in UK online subscription boxes where convenience-oriented households prioritize variety over commodity pricing.
- Plantains:Starch-forward cooking varieties target Caribbean and Latin American diaspora communities in North American urban centers.
- Sliced Bananas:Pre-cut formats serve food manufacturers and ready-to-eat salad processors requiring standardized portion control.
Fair Trade handles the majority of throughput; sliced bananas are expanding most quickly on share through foodservice convenience demand.
Distribution Channel:
Channel economics stratify across cost tiers, with infrastructure-heavy formats absorbing margin compression while lean digital models capture premium pricing.
- Supermarkets:Dedicated organic produce sections in German chains such as REWE and Edeka anchor volume throughput, with ripening room investments enabling color-stage guarantees that reduce shrink. The EU Organic Regulation's stringent certification requirements create defensible quality tiers that justify shelf space allocation against conventional alternatives.
- Online Retailers:Direct-to-consumer subscription platforms in London and Amsterdam metropolitan areas bypass traditional retail markup structures through delivery density economics. Weekly box models reshape purchase frequency and capture higher margins than wholesale channels by converting provenance transparency into household loyalty.
- Farmers' Markets:Local aggregation points serve urban consumers seeking shortened supply chains and cultivar variety unavailable through conventional retail.
- Specialty Stores:Independent organic grocers curate premium assortments for health-conscious demographics in affluent neighborhoods.
Supermarkets handle the majority of throughput; online retailers are gaining share fastest through subscription model economics.
Packaging Type:
Packaging specifications track customer type divergence, with institutional buyers prioritizing handling efficiency and household consumers responding to sustainability signaling.
- Eco-Friendly Packaging:Compostable and biodegradable formats are displacing conventional plastic as EU Green Deal packaging waste directives tighten retailer sustainability scorecards. Suppliers with certified biodegradable formats capture first-mover advantages in German and French supermarket chains where procurement teams embed material specifications into vendor scorecards.
- Loose:Unpackaged bulk displays serve farmers' markets and zero-waste retail concepts where consumers self-select ripeness stages and eliminate packaging waste.
- Boxes:Standardized corrugated containers optimize palletization for supermarket distribution centers and foodservice volume buyers.
- Bags:Polyethylene and paper formats serve convenience-oriented retail and grab-and-go snack applications.
Eco-friendly packaging handles the majority of throughput; loose formats are climbing the fastest on share through zero-waste retail expansion.
End Use:
Application requirements fragment across processing intensity, with fresh consumption dominating volume and manufactured formats capturing value-added margins.
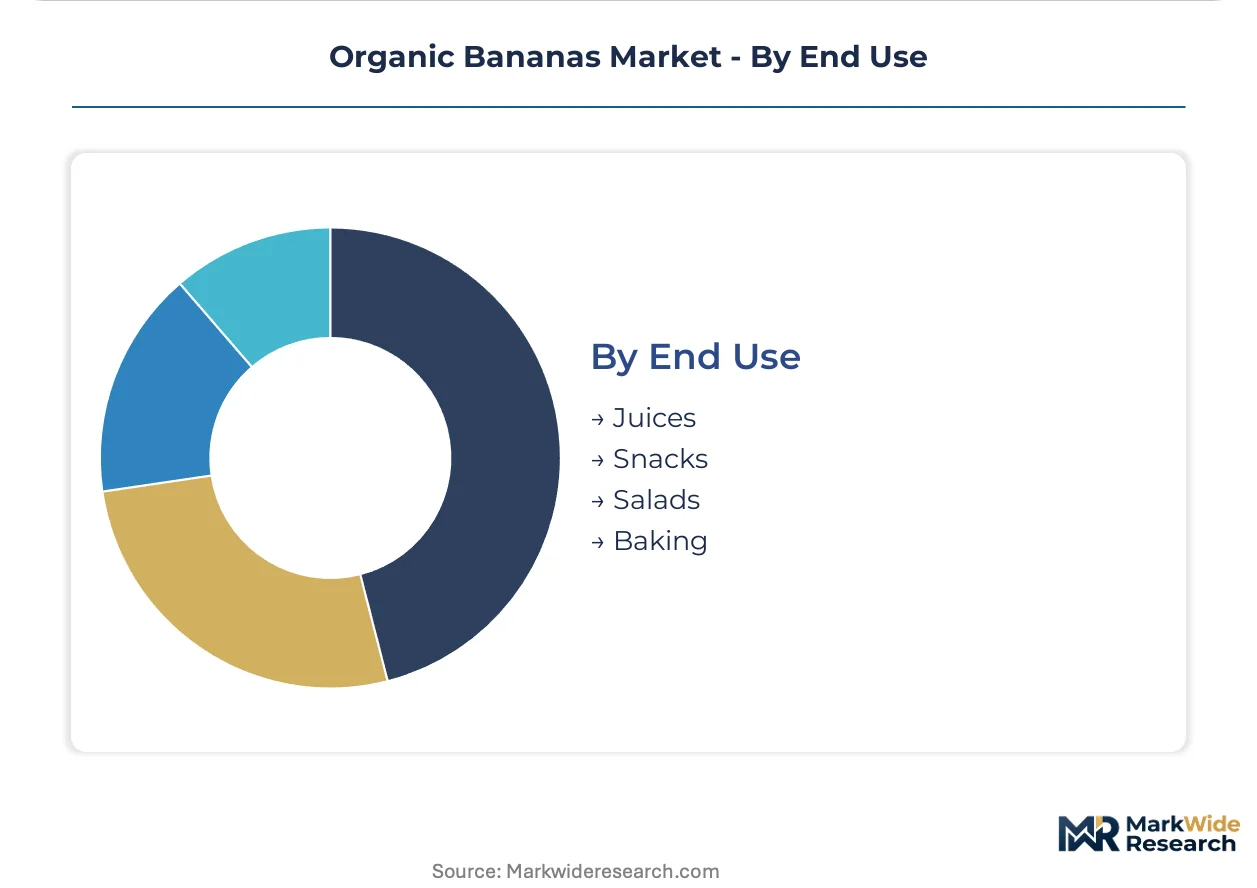
- Snacks:Whole fresh bananas and dried chip formats serve the largest addressable demand base across retail and foodservice channels. Ripening technology investments by major distributors enable color-stage guarantees that align with convenience store and café procurement specifications.
- Juices:Smoothie bar chains and bottled beverage manufacturers require consistent brix levels and residue-free certification to meet clean-label positioning.
- Salads:Pre-cut segments serve ready-to-eat manufacturers requiring organic certification for retail deli and grab-and-go applications.
- Baking:Overripe and second-grade fruit supplies commercial bakeries and food manufacturers where visual defects are irrelevant to processed output.
Snacks handle the majority of throughput; juices are expanding most quickly on share through functional beverage category growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ecuadorian exports supply German supermarket chains through dedicated cold-chain corridors, while Colombian and Costa Rican shipments serve North American retail networks with distinct ripening protocols.
Germany
REWE and Edeka chains anchor European organic banana throughput through ripening room investments that guarantee color-stage specifications. The EU Organic Regulation mandates stringent certification tiers that justify shelf space allocation against conventional alternatives. Hamburg and Bremerhaven ports concentrate import logistics, with specialized cold storage facilities handling pre-distribution temperature protocols.
United States
Whole Foods Market and Kroger divisions drive procurement volume for residue-free Cavendish cultivars with documented provenance. The USDA National Organic Program governs three-year conversion periods that block rapid supply response to demand spikes. Port infrastructure at Philadelphia and Gulf Coast terminals anchors distribution networks serving Eastern and Midwestern population centers.
United Kingdom
Online subscription platforms in London and Amsterdam metropolitan areas bypass traditional retail markup structures through delivery density economics. The UK Department for Environment, Food and Rural Affairs enforces equivalency agreements with EU certification bodies post-Brexit. Bristol and Liverpool logistics clusters handle consolidated shipments for direct-to-consumer weekly box models.
France
Carrefour and Intermarché procurement teams embed ethical sourcing protocols into vendor scorecards for dual-certified organic and Fair Trade fruit. ECHA REACH restrictions tighten residue testing protocols for imported produce. Marseille-Fos port infrastructure serves as the primary entry point for Latin American shipments destined for Paris Basin retail distribution.
Netherlands
Rotterdam port facilities function as the European hub for re-export to Scandinavian foodservice buyers mandating documented provenance. The EU Green Deal packaging waste directives accelerate retailer adoption of compostable materials. Amsterdam metropolitan delivery density supports subscription model economics that capture household buyers prioritizing convenience over price comparison.
Organic Bananas Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated Latin American growers with captive port infrastructure and proprietary ripening technology. Three archetypes dominate: multinational exporters controlling farm-to-retail cold chains, regional cooperatives aggregating smallholder production, and specialist distributors serving subscription-based direct-to-consumer channels. Competitive intensity manifests through backward integration into packing station operations and strategic partnerships with supermarket chains for dedicated produce section supply.
Among the multinational exporter tier, Dole Food Company, Chiquita Brands International, and Fresh Del Monte Produce exemplify scale-driven positioning through vertically integrated operations spanning Ecuadorian and Costa Rican growing regions. These entities occupy positions defined by year-round supply reliability and port-to-retailer logistics control rather than product differentiation alone.
| Leading Market Players |
|---|
| Dole Food Company |
| Chiquita Brands International |
| Fresh Del Monte Produce |
| Organics Unlimited |
| Fyffes |
| Compagnie Fruitiere |
| AgroAmerica |
| GrupoAcon |
| Grupo Iren |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Ecuadorian ripening infrastructure is driving suppliers toward longer-term contract structures that lock in volume commitments from German supermarket chains, compressing spot-market liquidity and elevating price premiums for guaranteed color-stage deliveries.
Pricing Analysis
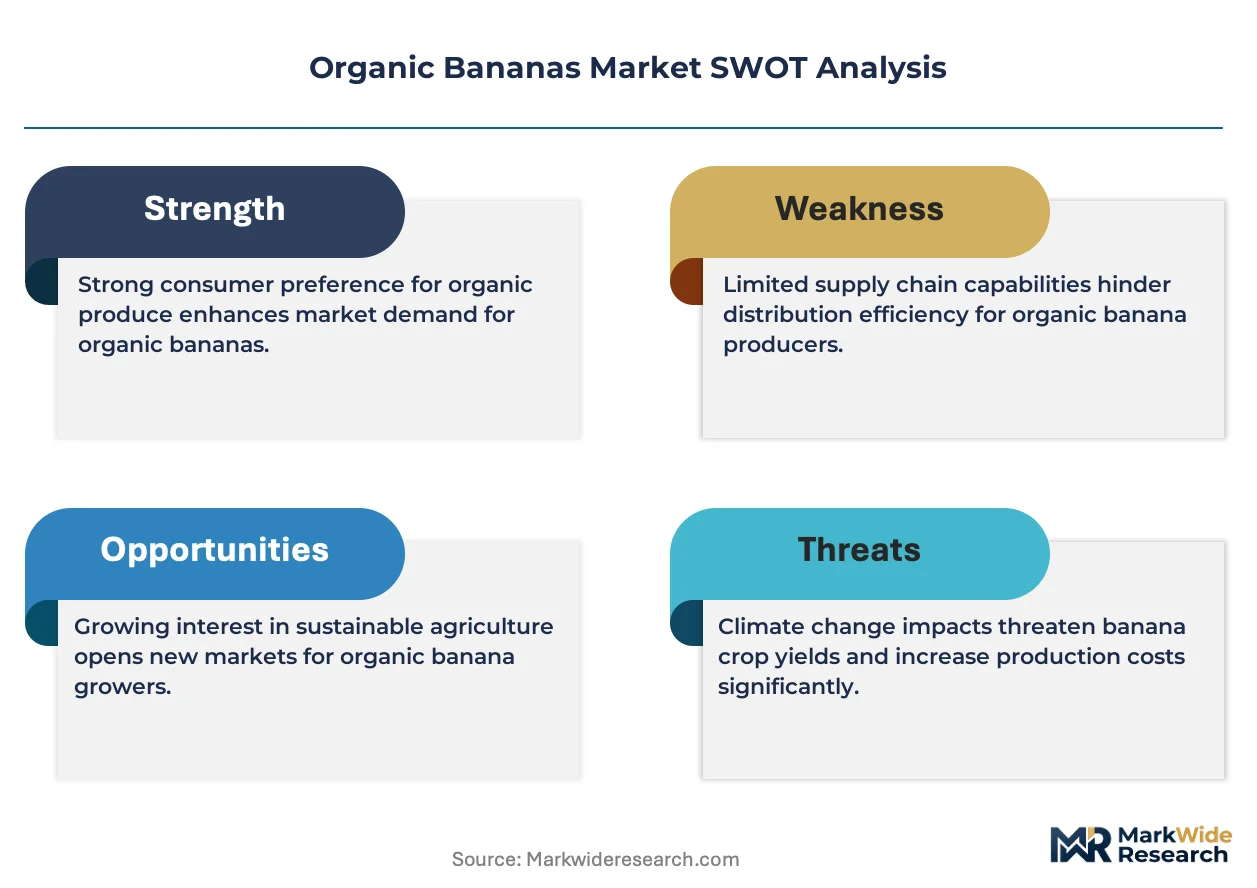
Ripening-technology pricing gaps separate legacy ethylene-based systems from IoT-enabled precision units and emerging AI-controlled climate chambers. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with dual-certified organic-Fair Trade fruit commanding the highest tier. Cost compression in standard-grade conventional organic channels is intensifying because container delays at Guayaquil shorten effective shelf life and trigger discounting. Foodservice buyers in Scandinavian hotel chains demonstrate lowest price sensitivity, while UK online subscription households show highest elasticity to weekly box pricing adjustments.
Supply Chain Analysis
EU REACH chemical restrictions function as de facto export controls, limiting flows from Latin American packing stations lacking in-house pre-shipment verification laboratories. Production gravity centers on Ecuador, Colombia, and Costa Rica, with raw material dependencies spanning organic fertilizer inputs, certified compostable packaging substrates, and specialized refrigerated container fleets. Single-source vulnerability concentrates at Guayaquil and Manta port infrastructure, where congestion ripples through temperature-controlled corridors. Distribution runs through vertically integrated multinational exporters controlling farm-to-retailer cold chains, with regional cooperatives and subscription specialists occupying niche downstream positions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized cold chain technicians capable of maintaining organic integrity through port-to-retailer temperature protocols remain concentrated in legacy banana logistics networks, constraining expansion velocity for new entrants and inflating acquisition premiums for incumbent capacity.
For Market Incumbents: Entrench market position through backward integration into certified compostable packaging manufacturing and exclusive ripening room partnerships with German REWE and Edeka chains. Panama disease TR4 exposure in Cavendish cultivars demands accelerated R&D investment in certified-resistant replacement varieties. Channel control through proprietary blockchain traceability integration with supermarket proprietary tracking systems by 2025 deadlines locks out competitor access. For New Entrants and Emerging Players: Pursue direct-to-consumer subscription white space in Amsterdam metropolitan delivery density zones, where weekly box model economics bypass traditional retail markup structures. UK online retail channels show highest penetrability among convenience-oriented households prioritizing provenance transparency. Go-to-market angle should emphasize cultivar variety unavailable through conventional retail, particularly baby banana formats for children's menu applications. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated Latin American growers with captive port infrastructure and long-term supermarket supply agreements. Five-to-ten-year viability favors entities controlling both Ecuadorian growing operations and European ripening facility networks. Acquisition target archetype: mid-scale Costa Rican cooperatives with USDA National Organic Program certification and underutilized capacity. Signal to watch: equivalency agreement shifts between USDA and EU Organic Regulation jurisdictions that would disqualify current supply origins.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Integration | German supermarket chains mandate supplier integration with proprietary tracking systems by 2025 deadlines. |
| Certified Compostable Packaging Scale-Up | EU Green Deal packaging waste directives accelerate retailer adoption of biodegradable formats. |
| Direct-to-Consumer Subscription Launch | London and Amsterdam delivery density supports weekly box economics that bypass retail markups. |
| Backward Integration into Ripening Technology | Proprietary IoT humidity sensors enable color-stage guarantees to foodservice buyers. |
| Dual Certification Investment | Organic-Fair Trade dual certification captures Scandinavian foodservice procurement mandates. |
Methodological Framework
A standing panel of plantation operations managers, European supermarket category buyers, cold chain logistics specialists, and organic certification auditors provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against customs records, EU Organic Regulation compliance databases, USDA National Organic Program certification listings, and IFOAM Organics International trade flow data. Bottom-up volume triangulation across Ecuadorian, Colombian, and Costa Rican export statistics converged with top-down value estimates from German and UK retail audit channels.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning certification tier, distribution channel economics, packaging material specifications, and end-use application intensity. CAGRs derived from fitted growth curves applied to historical trade volumes and forward procurement commitments from named supermarket chains. Forecast inputs incorporated Panama disease TR4 spread modeling and EU packaging waste directive implementation timelines.
Macroeconomic conditions sit as an overlay; deviation in natural gas prices affecting organic fertilizer costs, container shipping rate volatility, or euro-dollar exchange movements would shift the trajectory. Forecasts reflect documented assumptions on certification equivalency stability and cold chain infrastructure investment continuity. Material shifts in EU Organic Regulation stringency or USDA conversion period requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Global Morel Mushroom Market
Fruits and Vegetables
Dehydrated Beets Market
Fruits and Vegetables
Processed Fruits and Vegetables Market
Fruits and Vegetables
Persimmons Market
Fruits and Vegetables
Ackee Market
Fruits and Vegetables
Cavendish Banana Market
Fruits and Vegetables
APAC Frozen Fruits and Vegetables Market
Fruits and Vegetables
Global Papaya Puree Market
Fruits and Vegetables
Global Gooseberry Market
Fruits and Vegetables
South America Lime Market
Fruits and Vegetables
Global Not from Concentrate (NFC) Puree Market
Fruits and Vegetables
Aronia Berries Market
Fruits and Vegetables
Haskap Berry Powder Market
Fruits and Vegetables
Adzuki Beans Market
Fruits and Vegetables
Middle East and Africa Sweet Potatoes Market
Fruits and Vegetables
Dried Kiwi Fruit Market