
 Turkish Figs Market | 2026-2036
Turkish Figs Market Size, Share, and Industry Trends Forecast 2026-2036
Turkish Figs Market Outlook
Organic certification tier is collapsing the gap between commodity dried figs and premium export grades. Tariş leverages cooperative-scale drying infrastructure across the Aegean region. Ören Tarım anchors its position through backward integration into orchard management and controlled-atmosphere storage. BirDem Gida differentiates via specialized organic processing lines that target allergen-free certification standards.
Turkish figs comprise Ficus carica L. cultivars—principally Sarılop and Bursa Siyahı varieties—dried to moisture specifications between 20-24 percent for export stability and shelf-life extension in ambient supply chains. The product serves as a natural sweetener alternative and texture ingredient across industrial food manufacturing. Dried figs dominate volume throughput due to year-round shipping feasibility and concentrated sugar profiles suited to baking and confectionery applications. Organic figs command expanding shelf space in European supermarket chains as clean-label procurement intensifies. Fresh figs remain seasonally constrained but capture premium pricing through air-freight programs to Northern European markets.
Turkish Food Codex regulations administered by the Ministry of Agriculture and Forestry govern pesticide residue limits and export hygiene standards for fig shipments. EU REACH compliance and organic equivalency agreements negotiated with the European Commission determine market access terms for Turkish exporters. BIS certification requirements affect containerized shipments entering Indian ports. Stakeholders must monitor evolving EU deforestation-free supply chain regulations and their documentation burdens on Mediterranean dried fruit exporters.
Market Dynamics
Organic certification tier is collapsing the gap between commodity dried figs and premium export grades, forcing Aegean producers to upgrade drying infrastructure and traceability systems to capture clean-label premiums in Northern European retail.
Growth Catalysts
- EU Organic Equivalency:Negotiated agreements with the European Commission accelerate market access for Turkish exporters holding certified status, reducing border inspection delays and tariff friction.
- Clean-Label Procurement:European supermarket chains now mandate pesticide residue documentation and allergen-free processing lines, pulling Turkish processors toward higher-margin certification tiers.
- Aegean Cluster Concentration:Proximity to Izmir port infrastructure and established cooperative drying networks in Aydin province compress logistics costs for containerized shipments to Rotterdam and Hamburg.
Market Restraints
- Input Cost Volatility:Sulfur and energy inputs for controlled-atmosphere storage fluctuate with natural gas pricing, squeezing margin predictability for mid-scale processors.
- Supply Concentration Risk:Overreliance on Sarılop cultivar monoculture in coastal Aegean zones creates vulnerability to climate stress and pest pressure.
- EU Deforestation Documentation:Emerging supply chain traceability requirements impose new administrative burdens on smallholder-dominated production bases.
Strategic Opportunities
- Indian Port Expansion:BIS certification pathways for containerized fig shipments remain underpenetrated relative to Middle Eastern competitors, offering first-mover positioning.
- Air-Freight Fresh Programs:Seasonal premium capture through direct cargo links to Northern European markets bypasses commoditized dried-fig channels.
- Allergen-Free Processing:Specialized lines targeting nut-free and gluten-free certification standards open shelf space in health-food retail segments.
Industry Challenges
- Certification Timeline Compression:Turkish Food Codex alignment with EU organic standards requires multi-year orchard conversion periods, locking capital in non-revenue-generating transitions.
- Skill Gap in Traceability Systems:Blockchain and GPS-based supply chain documentation demand digital literacy absent in traditional cooperative management structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkish Figs Market |
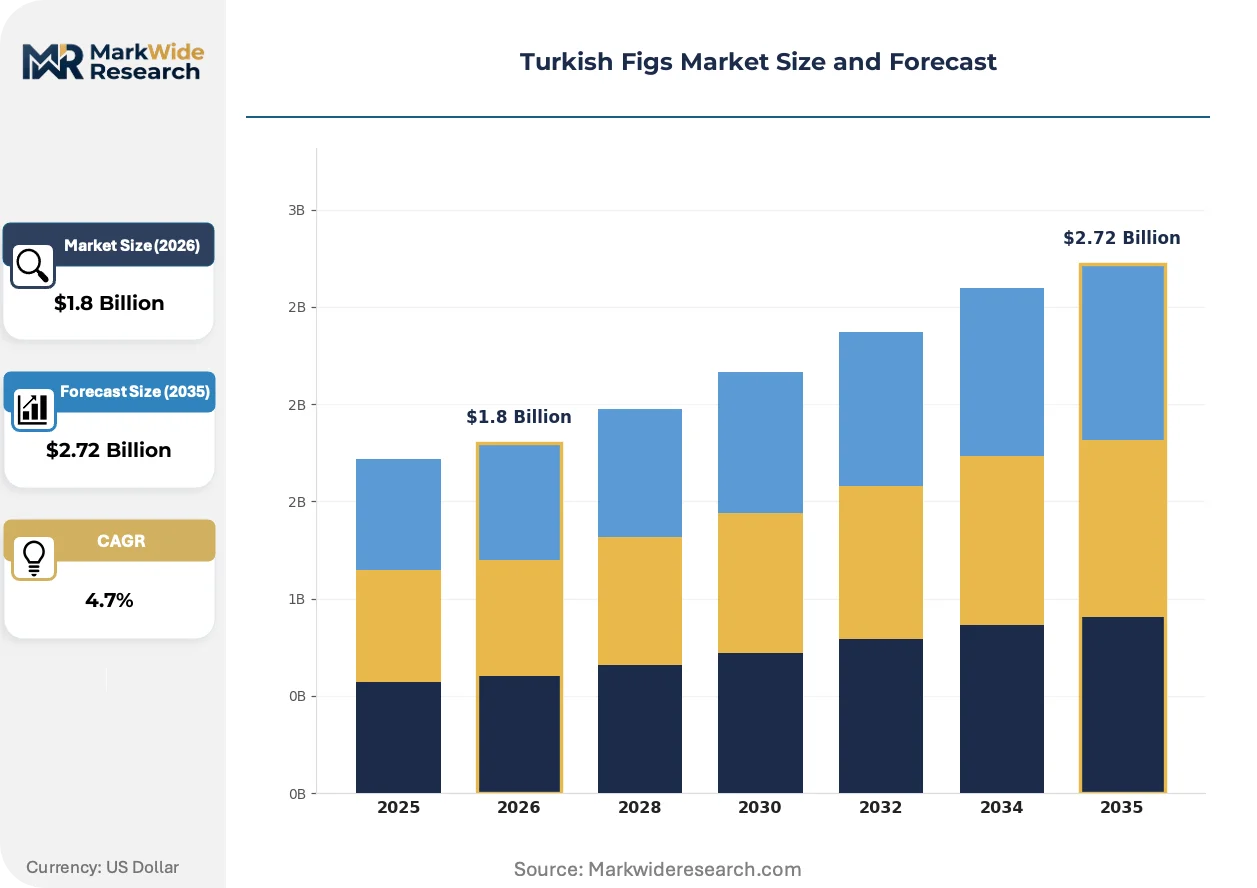
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Figs, Dried Figs, Processed Figs, Organic Figs Use Case: Baking, Snacking, Confectionery, Culinary Applications Distribution Channel: Supermarkets, Online Retail, Local Markets, Wholesale Packaging Type: Bags, Boxes, Bulk Containers, Retail Packs |
| Companies Covered | Ören Tarım, Tariş, TARIS, BirDem Gida, Malatya Pazarı, Anatolia, Malatya Apricot, Yıldız Entegre, Alara Agri, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkish Figs Market Strategic Shifts
Solar-powered drying infrastructure and precision moisture control are reshaping how Aegean processors balance energy costs with export-grade quality consistency.
Controlled-atmosphere storage with nitrogen flushing is supplanting traditional sulfur-dioxide treatment for color retention and shelf-life extension. German and Dutch organic retailers now specify residue-free processing protocols, compressing demand for conventional chemically-treated grades. This shift forces Turkish cooperatives to retrofit drying facilities or lose access to premium shelf space.
EU deforestation-free supply chain regulations administered by the European Commission now require geolocation documentation for orchard plots exceeding defined thresholds. Turkish exporters must map smallholder supplier networks and submit polygon coordinates to customs authorities. Processors with backward integration into orchard management capture compliance advantages over pure-trading intermediaries.
Direct procurement contracts between Aegean cooperatives and Northern European supermarket chains are displacing layered broker networks that historically aggregated fragmented smallholder output. Retail buyers now demand lot-level traceability and pesticide test certificates before tender acceptance. This pattern concentrates in German and Swiss markets where clean-label penetration runs deepest.
Turkish Figs Market Segmentation
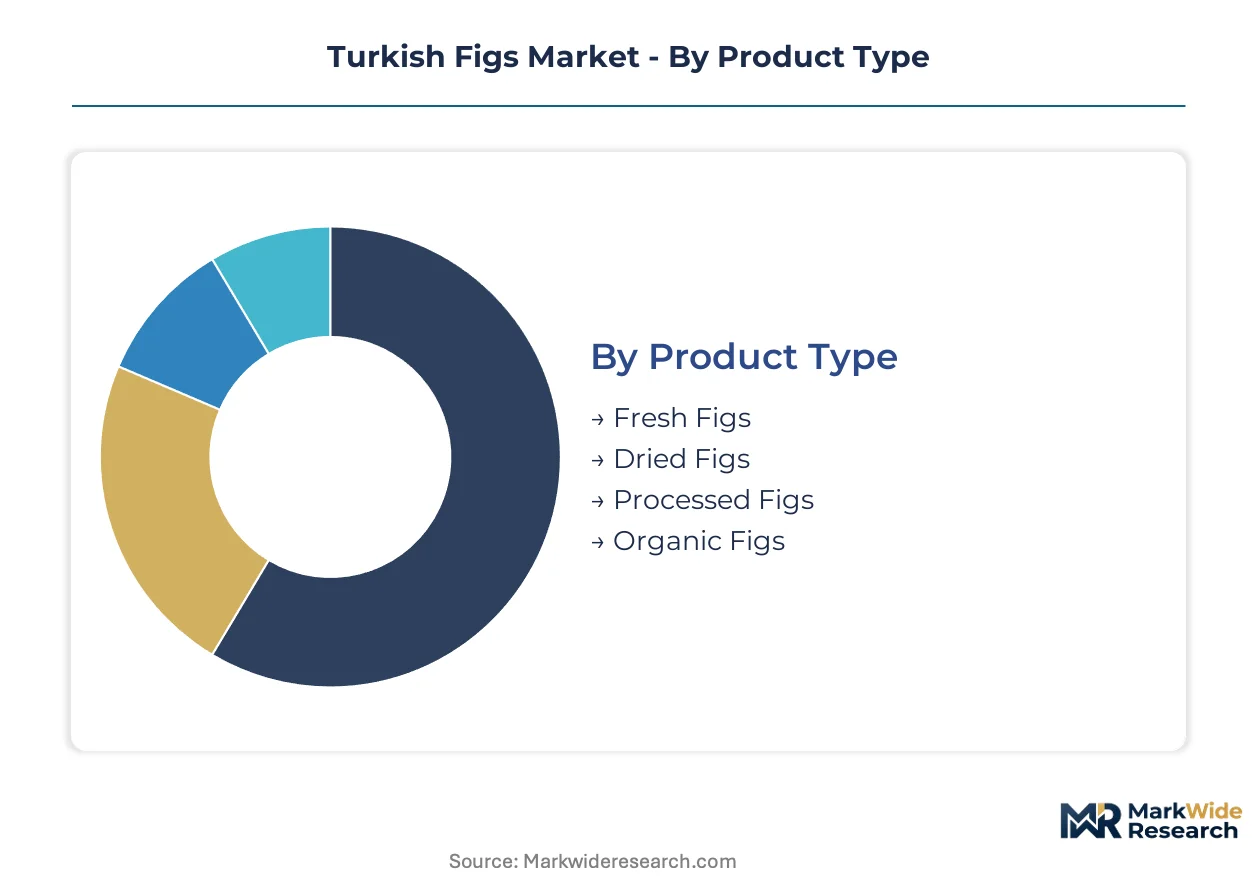
Margin pools in Turkish figs concentrate where certification tiers and shelf-life extension intersect. Processors capture value by matching product form to channel-specific handling requirements and consumer occasion.
Product Type:
Highest margins flow to segments where Aegean cooperative infrastructure and controlled-atmosphere storage create defensible quality tiers.
- Dried Figs:Moisture-calibrated to 20-24 percent for ambient supply chain stability and year-round shipping feasibility. Demand concentrates in Northern European industrial baking and confectionery manufacturing where concentrated sugar profiles reduce formulation costs. The Sarılop cultivar dominates this segment through cooperative-scale drying networks in Aydın province.
- Organic Figs:Certified production under Turkish Food Codex alignment with EU organic standards commands clean-label premiums in German and Swiss supermarket chains. Aegean producers pursuing EU equivalency status capture expanding shelf space as residue-free procurement protocols intensify across health-food retail.
- Fresh Figs:Seasonally constrained harvests of Bursa Siyahı and Sarılop varieties move through air-freight programs to capture premium pricing in Northern European markets during limited windows.
- Processed Figs:Paste, concentrate, and ingredient forms serve industrial food manufacturing with standardized specifications for texture and sweetness modulation.
The dominant share belongs to Dried Figs, while Organic Figs is closing the gap fastest.
Use Case:
Application-driven demand splits between industrial-scale ingredient procurement and direct-to-consumer snacking formats with divergent quality thresholds.
- Baking:Industrial manufacturers in Germany and the Netherlands specify moisture content and sulfur residue limits for dried fig integration into fruit breads and pastry fillings. Clean-label reformulation is pulling procurement toward organic-certified supply.
- Snacking:Retail-packaged dried figs for health-conscious consumers concentrate in supermarket private-label programs and organic specialty channels across Switzerland and Austria.
- Confectionery:Chocolate enrobing and fig-based energy bar production demand calibrated sweetness levels and consistent texture profiles from Aegean processors.
- Culinary Applications:Restaurant and foodservice procurement of fresh and semi-dried forms remains concentrated in domestic Turkish and Middle Eastern markets with limited export penetration.
Baking commands the largest volume throughput, though Snacking is expanding most quickly as portion-controlled packaging gains traction.
Distribution Channel:
Channel selection determines documentation burdens and margin capture, with direct retail relationships compressing broker layers that historically aggregated fragmented smallholder output.
- Supermarkets:German and Swiss chains now mandate lot-level traceability, pesticide test certificates, and geolocation documentation under emerging EU deforestation-free regulations. Backward-integrated processors with captive orchard networks capture compliance advantages.
- Wholesale:Rotterdam and Hamburg port-facing traders aggregate containerized shipments for redistribution across European industrial buyers, prioritizing volume throughput over certification premiums.
- Online Retail:Direct-to-consumer platforms for organic and specialty fig products remain underdeveloped relative to Middle Eastern competitor penetration.
- Local Markets:Domestic Turkish consumption of fresh and dried figs flows through bazaar networks and municipal markets with minimal processing or packaging value-add.
Supermarkets extract the steepest compliance requirements, while Wholesale retains the deepest volume concentration.
Packaging Type:
Packaging investment separates commodity handlers from premium-positioned processors targeting retail-facing shelf presence.
- Retail Packs:Vacuum-sealed and nitrogen-flushed formats with clean-label branding capture premium positioning in Swiss and German organic retail. Residue-free processing protocols specified by Dutch retailers favor this packaging tier.
- Bulk Containers:Industrial-scale shipments to confectionery and baking manufacturers prioritize cost efficiency over shelf presentation, with flexitank and drum formats dominating Rotterdam-bound volumes.
- Bags:Intermediate formats for club stores and discount retail chains balance unit economics with basic barrier protection.
- Boxes:Gift-oriented and seasonal presentation packaging serves Middle Eastern export markets with cultural gifting traditions around dried fruit.
Retail Packs generate the highest per-kilogram margins, though Bulk Containers move the greatest absolute tonnage through Izmir port infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orchard concentration along Turkey's Aegean coast concentrates export capacity within a narrow corridor between Izmir and Aydin provinces. This geographic clustering shapes competitive dynamics across European, Middle Eastern, and Asian destination markets.
Germany
Clean-label procurement from REWE and EDEKA chains drives residue-free specification adoption. EFSA pesticide residue protocols determine border inspection intensity for Izmir-port shipments. Hamburg port-facing traders aggregate containerized volumes for redistribution across Central European industrial bakers.
Netherlands
Rotterdam's cold-storage infrastructure enables year-round inventory positioning for Northern European confectionery manufacturers. EU REACH compliance documentation accompanies every bulk shipment through Dutch customs. The port's fig-import throughput concentrates in industrial-grade dried formats for chocolate enrobing applications.
Switzerland
Swissmedic-aligned organic standards exceed baseline EU requirements, filtering Turkish suppliers through stricter certification tiers. Migros and Coop chains mandate geolocation documentation under emerging deforestation-free procurement rules. Basel-based traders specialize in premium retail-pack formats for Alpine health-food segments.
India
BIS certification requirements for containerized dried fruit shipments create compliance bottlenecks at Mumbai and Chennai ports. FSSAI food safety standards govern pesticide residue thresholds for Turkish fig imports. The underpenetrated market offers positioning advantages over Middle Eastern competitors already established in Gulf trade routes.
United Kingdom
Post-Brexit UKCA marking requirements diverge from EU organic equivalency agreements, forcing dual-track certification for Turkish exporters. Sainsbury's and Waitrose chains maintain clean-label procurement standards mirroring continental European specifications. Felixstowe port handling fees compress margins on lower-volume specialty shipments.
Turkish Figs Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Turkish figs sector. Cooperative-scale drying infrastructure dominates volume throughput, while backward-integrated orchard operators capture premium-tier margins through traceability advantages. The vendor base separates into three strategic archetypes: Aegean cooperatives with shared processing assets, vertically integrated agribusinesses with captive orchard networks, and specialized organic processors with allergen-free certification capabilities. Competitive moves concentrate on EU organic equivalency acquisition and controlled-atmosphere storage capacity expansion.
Among cooperative-scale operators, Tariş exemplifies the Aegean cluster model with shared infrastructure across Aydin province. Ören Tarım occupies a position within the backward-integrated tier, anchoring quality control through in-house orchard management. BirDem Gida represents the specialization vector, targeting allergen-free processing standards for health-food retail penetration.
| Leading Market Players |
|---|
| Ören Tarım |
| Tariş |
| TARIS |
| BirDem Gida |
| Malatya Pazarı |
| Anatolia |
| Malatya Apricot |
| Yıldız Entegre |
| Alara Agri |
| Others |
Value Chain & Pricing Dynamics
Forty-five-day container lead times from Izmir to Rotterdam compress working capital cycles for Aegean processors while amplifying price volatility exposure to sulfur and natural gas input swings. This inventory velocity concentrates margin control among cooperative-scale operators with captive drying infrastructure, leaving smaller traders exposed to spot-price squeezes during harvest compression.
Pricing Analysis
Turkish Food Codex alignment with EU organic standards dictates the pricing tier structure across the Turkish figs sector. Three-tier pricing structure across premium organic, standard dried, and commodity bulk levels segments buyers by certification burden and residue documentation requirements. Price differentiation stems from EU organic equivalency status and controlled-atmosphere storage capacity, with German supermarket chains paying clean-label premiums while Rotterdam wholesale buyers prioritize volume scale over certification. Cost compression in mid-tier dried figs is intensifying because sulfur-dioxide treatment faces displacement by nitrogen-flushing protocols demanded by Dutch retailers. Industrial baking manufacturers in Germany exhibit highest price sensitivity due to formulation cost pressures, whereas Swiss health-food retailers show least sensitivity given Swissmedic-aligned quality mandates.
Supply Chain Analysis
Strait of Gibraltar transit underwrites year-round ambient shipping feasibility for Turkish dried figs bound for Northern European markets. Geographic supply concentration centers on Turkey, with secondary processing nodes in Germany and the Netherlands for retail repackaging. Raw material dependencies draw from Aegean coastal orchard networks, sulfur inputs for traditional color retention, and natural gas feeds for controlled-atmosphere nitrogen systems. Single-source vulnerability runs through Sarılop cultivar monoculture concentration in Aydın province, exposing yield stability to climate stress events. Distribution runs through Rotterdam and Hamburg port-facing traders for industrial bulk, with direct cooperative-to-supermarket contracts displacing layered broker networks in premium retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification-as-a-service offerings for smallholder orchard mapping and EU deforestation documentation represent a recurring-revenue layer expanding faster than commodity dried fig throughput. These compliance services capture margin from regulatory burden escalation without exposure to agricultural yield volatility.
For Market Incumbents: Compound backward integration into orchard management to capture geolocation documentation advantages under emerging EU deforestation regulations. Invest in solar-powered drying retrofit capacity to offset natural gas price volatility squeezing mid-tier processors. Prioritize allergen-free processing line certification to defend shelf space against emerging Turkish competitors targeting Swiss health-food retail. For New Entrants and Emerging Players: Anchor in Indian port expansion opportunities where BIS certification pathways remain underpenetrated relative to Middle Eastern competitors established in Gulf trade routes. Target air-freight fresh fig programs to Northern European markets during seasonal windows bypassing commoditized dried channels. Pursue direct-to-consumer online retail positioning for organic specialty formats where competitor penetration lags. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because compliance infrastructure advantages compound faster than production scale in an increasingly documentation-intensive trade environment. Acquisition target archetype: Aegean cooperatives with captive orchard networks and existing EU organic equivalency status. Watch for Turkish Food Codex enforcement intensity as inflection indicator signaling margin compression or expansion for certified versus conventional tiers.| Strategic Initiative | Industry Significance |
|---|---|
| EU Organic Equivalency Acquisition | Secures Rotterdam and Hamburg port priority handling under negotiated European Commission agreements. |
| Controlled-Atmosphere Storage Expansion | Captures nitrogen-flushing premiums from Dutch retailers phasing out sulfur-dioxide protocols. |
| Smallholder Traceability System Deployment | Satisfies EU deforestation geolocation mandates ahead of cooperative competitors. |
| Air-Freight Fresh Program Development | Bypasses commoditized dried channels through direct cargo links to German supermarket chains. |
| Allergen-Free Processing Certification | Opens Migros and Coop shelf space in Swiss health-food retail segments. |
Study Parameters
Initial hypotheses were tested against primary input from Aegean cooperative managers, Turkish Ministry of Agriculture inspectors, Rotterdam port logistics coordinators, German supermarket category buyers, and Swiss health-food retail procurement leads and refined through secondary validation. Bottom-up triangulation drew from Turkish customs export records, EU REACH compliance filings, FSSAI import documentation for Indian port entries, and Aegean agricultural cooperative financial disclosures. Top-down cross-checks incorporated European Commission trade statistics and UN Comtrade dried fruit flow data.
Variance decomposition across product type, certification tier, distribution channel, and regional destination clusters shaped the analytical framework over the projection horizon. CAGRs were derived from segmented volume trajectory modeling incorporating orchard conversion timelines, EU organic equivalency approval velocities, and air-freight capacity expansion schedules. Industry-specific forecast inputs included Turkish Food Codex regulatory alignment progress and EU deforestation regulation implementation phasing.
Material uncertainties — climate stress impacts on Sarılop yields, natural gas price volatility affecting controlled-atmosphere storage economics, and EU-Turkey organic equivalency renegotiation outcomes — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as EU deforestation documentation enforcement thresholds and Indian BIS certification pathway accessibility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Japan Avocado Market
Fruits and Vegetables
Egypt Fruits and Vegetables Market
Fruits and Vegetables
Europe Stone Fruits Market
Fruits and Vegetables
Persimmons Market
Fruits and Vegetables
North Africa Table Olives Market
Fruits and Vegetables
Dehydrated Green Beans Market
Fruits and Vegetables
Dried Berries Market
Fruits and Vegetables
Asia Pacific Lime Market
Fruits and Vegetables
Rosehip Market
Fruits and Vegetables
Apple Concentrate Market
Fruits and Vegetables
Freeze-Dried Fruit Powder Market
Fruits and Vegetables
Asia-Pacific Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Fresh Lemons Market
Fruits and Vegetables
Global Dehydrated Onion Flakes Market
Fruits and Vegetables
Brazil Fruits and Vegetables Market
Fruits and Vegetables
Morocco Fruits and Vegetables Market