
 Dried Berries Market | 2026-2036
Dried Berries Market Size, Share, and Industry Trends Forecast 2026-2036
Dried Berries Market Analysis
Freeze-dried strawberry powder is consolidating share from air-dried alternatives in premium baking applications due to superior color retention and solubility. Ocean Spray Cranberries Inc. leverages its cooperative structure to control raw cranberry supply across Wisconsin and Massachusetts growing regions. Graceland Fruit Inc. specializes in infused-dried technology that extends shelf life without sulfites. Sun-Maid Growers of California anchors retail visibility through dominant shelf placement in US supermarket dried fruit aisles.
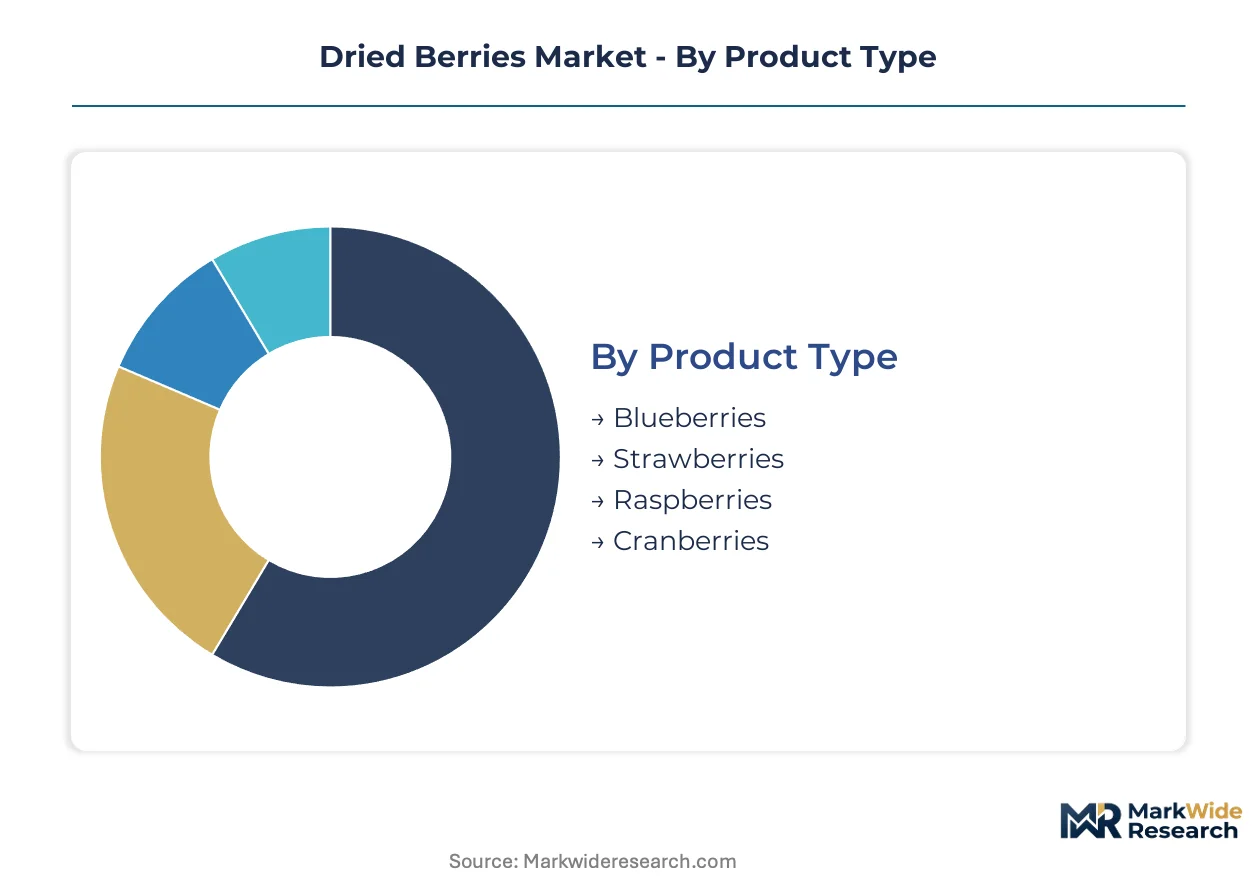
Dried berries constitute dehydrated or lyophilized fruit with moisture content typically reduced below 20 percent, preserving anthocyanins and fiber for year-round ingredient use in formulated foods. The product type dimension shows cranberries occupying the largest volume share due to established juice industry spillover, while blueberries command premium pricing in functional snack positioning. Pouch packaging for the snacks end-use segment is expanding fastest as single-serve portability aligns with on-premise consumption trends.
USDA organic certification and FDA food safety modernization requirements shape processing investments for domestic suppliers, while EU EFSA health claim regulations constrain how European marketers position antioxidant benefits on packaging. BIS quality standards in India create compliance barriers for imported dried berry entrants seeking shelf space in organized retail. Stakeholders must monitor evolving front-of-pack labeling rules across multiple jurisdictions to anticipate reformulation and packaging redesign cycles.
Market Dynamics
Freeze-drying technology adoption is compressing processing timelines and reshaping competitive positioning between regional suppliers and multinational ingredient houses. The EU Green Deal sustainability requirements are forcing capital redeployment across drying facilities.
Growth Catalysts
- Clean-label procurement mandates:Snack manufacturers are expanding dried berry sourcing for formulations free from artificial preservatives. Infused-dried technology enables sulfite-free shelf life extension.
- Functional snacking pivot:European consumers are prioritizing anthocyanin-rich formats. Germany concentrates demand for premium positioning in on-the-go pouches.
- EU Green Deal compliance:Agricultural processing standards across member states are tightening carbon footprint disclosures. Suppliers investing in renewable energy drying secure preferential retailer access.
Market Restraints
- Input cost volatility:Fresh berry procurement faces climate-driven harvest variability. Wisconsin and Massachusetts cranberry growing regions experience concentrated weather risk.
- Regulatory friction:EFSA health claim regulations constrain antioxidant benefit messaging on European packaging. Marketers must reformulate label claims to comply.
- Substitution pressure:Air-dried alternatives retain cost advantage in commodity baking applications. Price-sensitive buyers in industrial channels resist freeze-dried premiums.
Strategic Opportunities
- Underpenetrated organic segments:USDA organic certification creates differentiation in North American retail. Processors capturing certified supply chains command shelf placement premiums.
- Emerging beverage applications:Soluble berry powders are penetrating ready-to-drink formulations. Freeze-dried strawberry powder offers superior dispersion in functional drinks.
- Channel innovation:Direct-to-manufacturer platforms are compressing traditional distributor margins. Ingredient houses are building captive portals for bakery and confectionery procurement.
Industry Challenges
- Skill scarcity in lyophilization operations:Freeze-drying expertise concentrates among legacy equipment specialists. Facilities face recruitment bottlenecks for process engineers.
- Compliance timeline compression:FDA food safety modernization requirements demand HACCP documentation upgrades. Small processors struggle with validation costs.
- Supply chain reconfiguration friction:BIS quality standards in India create testing delays for imported entrants. Organized retail gatekeepers enforce extended certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dried Berries Market |
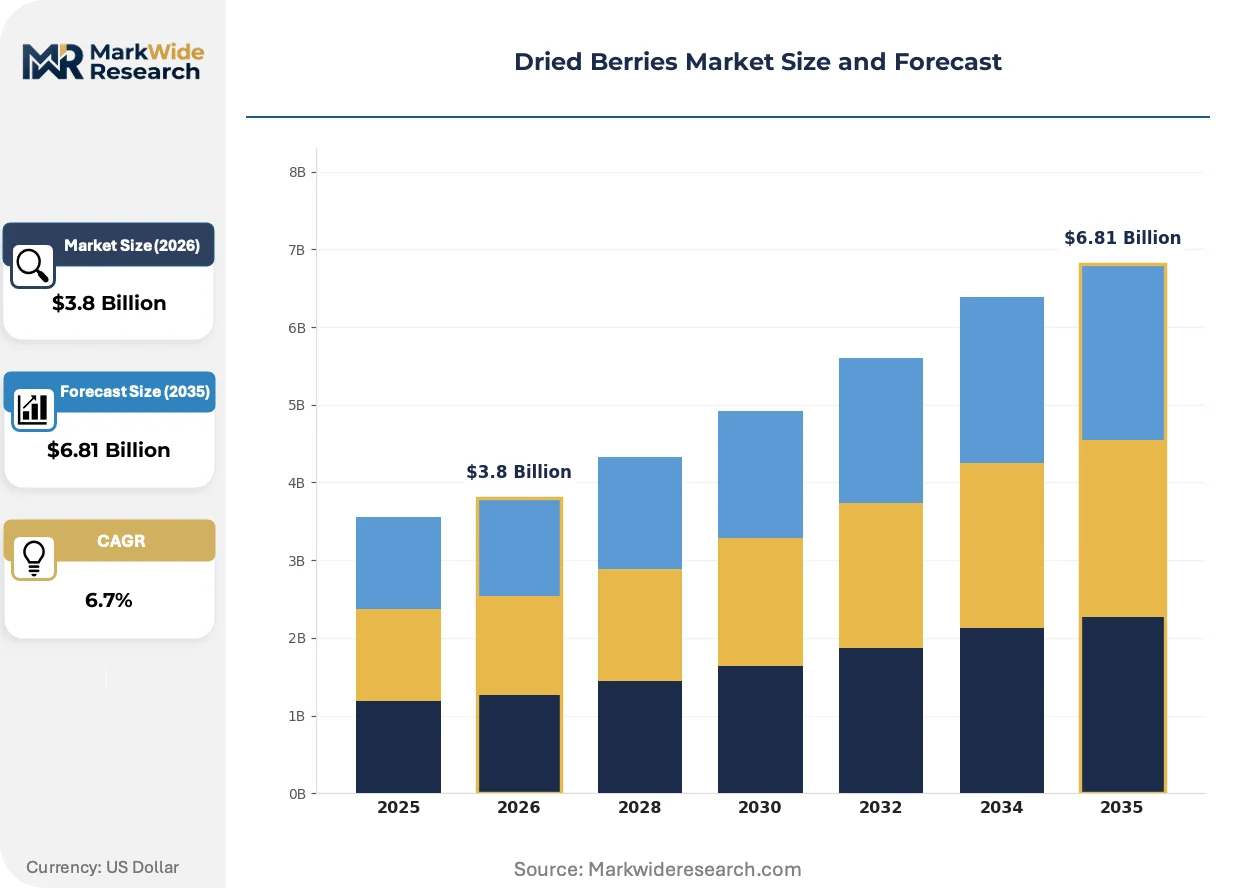
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blueberries, Strawberries, Raspberries, Cranberries End Use: Baking, Snacks, Breakfast Cereals, Food Preservation Packaging Type: Bags, Jars, Pouches, Bulk Containers Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Stores |
| Companies Covered | Ocean Spray Cranberries Inc., Graceland Fruit Inc., Del Monte Foods Inc., Dole Packaged Food LLC, Bergin Fruit and Nut Company, Sun-Maid Growers of California, Naturipe Farms LLC, Lion Raisins Inc., Traina Foods Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dried Berries Market Emerging Trajectories
Processing technology convergence and front-of-pack labeling evolution are forcing simultaneous investment across equipment and packaging design. Suppliers must synchronize capital cycles to maintain commercial relevance.
Freeze-drying equipment with integrated nitrogen flushing is electrifying color retention benchmarks in premium strawberry applications. Artisan bakeries and clean-label confectioners are adopting the technology at accelerated cadence. This capability compression is enabling domestic processors to challenge imported ingredient dominance in formulated foods.
EU EFSA health claim enforcement is tightening substantiation requirements for antioxidant positioning on berry packaging. The industrial consequence is reformulation toward provable nutrient content rather than implied wellness benefits. German and French marketers are most affected, pivoting toward fiber and mineral claims with established dossiers.
Single-serve pouch specifications are displacing bulk formats in workplace and travel consumption occasions. Convenience retailers are expanding chilled grab-and-go sets with resealable dried berry SKUs. This channel rotation is most visible in German convenience store networks and US airport retail clusters.
Dried Berries Market Segmentation
Product differentiation across drying technologies and consumption occasions fragments the competitive landscape. Procurement patterns diverge sharply between industrial ingredient buyers and retail-facing brands.
Product Type:
Freeze-dried formats command premium positioning in standalone snacking, while air-dried variants embed cost-effectively into processed foods.
- Cranberries:Dehydrated fruit with moisture content reduced below 20 percent, preserving anthocyanins and fiber for year-round ingredient use. Wisconsin and Massachusetts growing regions anchor supply; juice industry spillover volumes sustain cost advantages in commodity channels.
- Blueberries:Lyophilized or infused-dried berries retaining polyphenol density for functional positioning. Germany concentrates demand for premium antioxidant claims in on-the-go formats constrained by EFSA substantiation rules.
- Strawberries:Freeze-dried powder variants displace air-dried alternatives in baking applications through superior color retention and solubility.
- Raspberries:Niche premium tier with limited harvest windows driving price volatility and concentrated sourcing from Pacific Northwest growers.
Volume placements concentrate in cranberries; the faster expansion belongs to blueberries.
End Use:
Application maturity separates established industrial channels from emerging functional formats reshaping procurement specifications.
- Snacks:Single-serve pouch formats align with workplace and travel consumption trends. German convenience retailers and US airport retail clusters are expanding chilled grab-and-go sets with resealable SKUs.
- Baking:Freeze-dried strawberry powder penetration accelerates in artisan and clean-label confectionery segments. Domestic processors challenge imported ingredient dominance through integrated nitrogen flushing equipment.
- Breakfast Cereals:Air-dried berries retain cost advantage in mass-market formulations where price-sensitive buyers resist freeze-dried premiums.
- Food Preservation:Traditional sulfite-based methods face displacement from infused-dried technology enabling clean-label shelf life extension.
Established placements dominate baking; snack applications are climbing the fastest.
Packaging Type:
Format selection tracks channel requirements and consumption occasion fragmentation across retail and foodservice.
- Pouches:Resealable single-serve specifications displace bulk formats in on-premise consumption. Convenience retailers prioritize portability in German networks.
- Bags:Standard retail format for household pantry stocking with limited differentiation beyond weight tiers.
- Jars:Premium visibility format for health store and specialty retail channels emphasizing ingredient transparency.
- Bulk Containers:Industrial procurement channel for bakery and confectionery manufacturers with validated HACCP documentation.
Household bags retain volume leadership; pouches show the steepest expansion trajectory.
Distribution Channel:
Channel control determines margin capture and brand positioning autonomy for processors of varying scale.
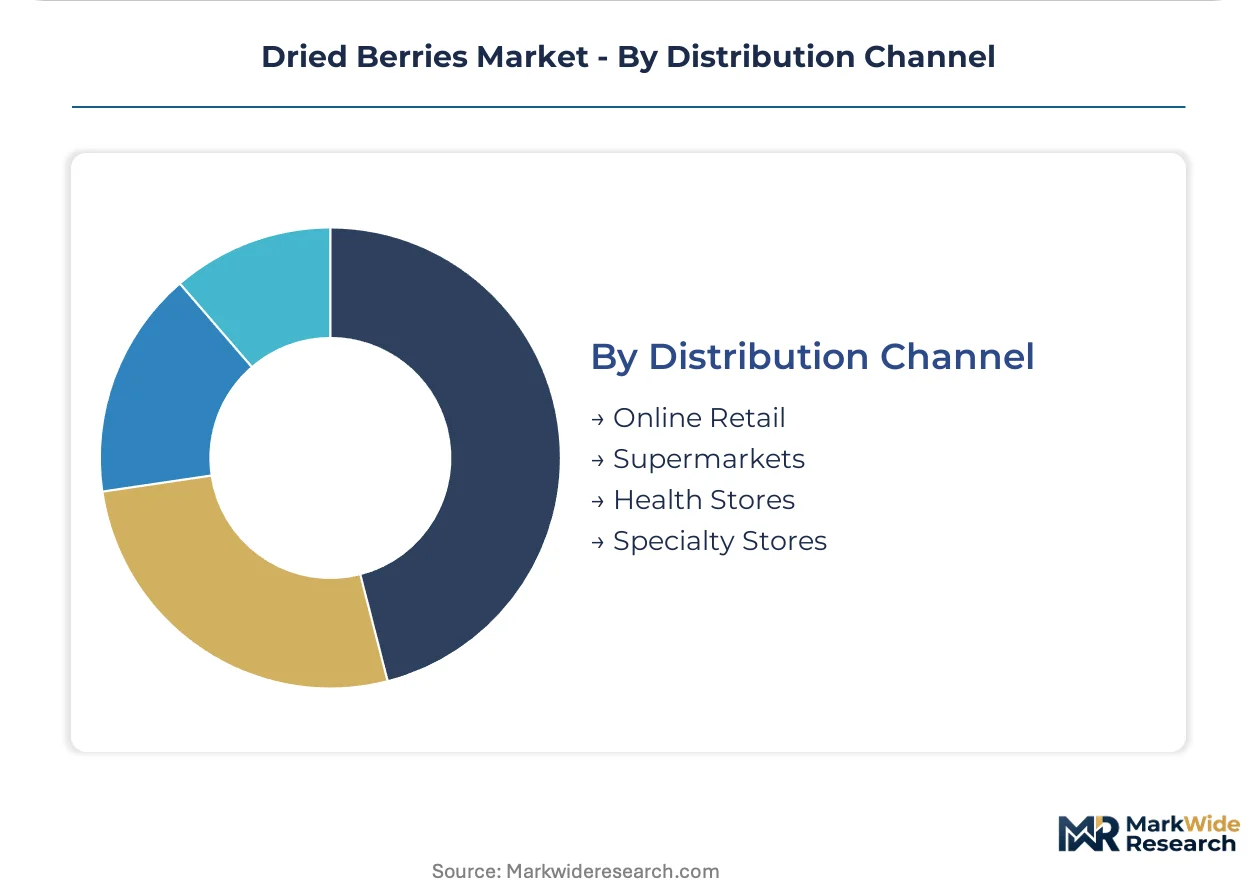
- Supermarkets:Dominant shelf placement in US dried fruit aisles anchors retail visibility. Sun-Maid Growers leverages cooperative scale for category captaincy.
- Online Retail:Direct-to-manufacturer platforms compress traditional distributor margins. Ingredient houses build captive portals for bakery and confectionery procurement.
- Health Stores:USDA organic certification creates differentiation and commands shelf placement premiums in North American natural channel.
- Specialty Stores:Curated assortments for premium positioning with limited volume but high basket attachment rates.
Supermarket placements hold volume concentration; online channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates European demand for premium dried berry formats as functional snacking pivots accelerate. The United States anchors North American procurement through cooperative supply structures and dominant retail shelf placement. China, India, and Brazil represent emerging volume frontiers with diverging regulatory and infrastructure maturity.
United States
Wisconsin and Massachusetts cranberry growing regions supply raw material to juice industry spillover channels. FDA food safety modernization requirements demand HACCP documentation upgrades from domestic processors. California's Central Valley hosts Sun-Maid Growers cooperative infrastructure controlling supermarket dried fruit aisle visibility.
Germany
Convenience retailers in German networks are expanding chilled grab-and-go sets with resealable dried berry SKUs. EU EFSA health claim regulations constrain antioxidant benefit messaging on packaging, forcing reformulation toward fiber claims. Berlin-Brandenburg logistics clusters handle distribution for on-the-go pouch formats across German-speaking markets.
China
Domestic freeze-drying equipment adoption is compressing processing timelines for strawberry powder applications. SAMR food safety standards and GB quality benchmarks create compliance barriers for imported entrants. Yangtze River Delta manufacturing zones host capacity expansion for nitrogen-flushing technology in premium baking ingredient production.
India
Organized retail gatekeepers in Mumbai and Delhi enforce extended BIS quality standard certification cycles for imported dried berries. FSSAI labeling requirements and DGFT import procedures shape market entry timelines. Maharashtra's Pune-Nashik corridor concentrates domestic processing investment for sulfite-free shelf life extension technologies.
Brazil
São Paulo-based food manufacturers are sourcing air-dried alternatives for cost-sensitive commodity baking applications. ANVISA health claim regulations limit functional positioning on berry packaging compared to North American standards. Minas Gerais agricultural clusters supply domestic raw material with limited lyophilization infrastructure.
Dried Berries Market Vendor Landscape
Capacity expansion dominates the current landscape as suppliers deploy freeze-drying equipment with integrated nitrogen flushing. The vendor base separates into three tiers: multinational ingredient houses with captive supply chains, regional cooperative structures controlling raw material access, and specialized technology licensors. Strategic archetypes include upstream-integrated berry growers, equipment-forward processors, and private-label contract manufacturers. M&A activity and direct-to-manufacturer platform development represent the dominant competitive vectors reshaping margin capture.
Among cooperative-structured suppliers, Ocean Spray Cranberries Inc. and Sun-Maid Growers of California exemplify the upstream-integrated archetype through grower-owned governance models. Graceland Fruit Inc. occupies a position within the technology-specialist tier, representing infused-drying capability without sulfite dependency. These three entities anchor distinct competitive positions: raw material control, retail shelf dominance, and clean-label processing innovation respectively.
| Leading Market Players |
|---|
| Ocean Spray Cranberries Inc. |
| Graceland Fruit Inc. |
| Del Monte Foods Inc. |
| Dole Packaged Food LLC |
| Bergin Fruit and Nut Company |
| Sun-Maid Growers of California |
| Naturipe Farms LLC |
| Lion Raisins Inc. |
| Traina Foods Inc. |
| Others |
Supply Flow & Price Mechanics
Fresh berry procurement costs cascade through three distinct pricing tiers as Wisconsin and Massachusetts cranberry harvests feed commodity channels while Pacific Northwest blueberries command premiums in German functional snacking markets. EU Green Deal carbon disclosure mandates add compliance premiums to freeze-dried formats, compressing margins for processors without renewable energy drying infrastructure.
Pricing Analysis
Volume placements concentrate in air-dried cranberries where juice industry spillover sustains cost advantages, while freeze-dried strawberry powder captures margin premiums through superior color retention in artisan baking. Three-tier pricing structure across premium, standard, and economy levels separates USDA organic certified supply from conventional grades and commodity spot volumes. Cost compression in standard tiers intensifies because air-dried alternatives resist freeze-dried premiums in price-sensitive industrial channels. Commodity baking buyers exhibit highest price sensitivity; clean-label confectioners show lowest sensitivity to organic certification premiums.
Supply Chain Analysis
Transoceanic freight differentials between Pacific Northwest raspberry growers and Yangtze River Delta freeze-drying facilities compress processor margins on niche premium tiers. Raw material sourcing draws from Wisconsin cranberry bogs, California Central Valley strawberry fields, and Chilean blueberry orchards during counter-seasonal windows. Single-source vulnerability concentrates in lyophilization equipment supply anchored by legacy German and Japanese specialists. Distribution runs through cooperative-owned infrastructure dominating US supermarket dried fruit aisles alongside direct-to-manufacturer platforms eroding traditional distributor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal compliance timelines are forcing capital-intensive facility upgrades that weaker regional processors cannot finance, accelerating consolidation toward cooperative-scale entities with captive renewable energy infrastructure.
For Market Incumbents: Cement raw material control through cooperative governance structures insulating Wisconsin and Massachusetts cranberry supply from climate-driven harvest volatility. Prioritize nitrogen-flushing equipment deployment to defend against domestic processors challenging imported ingredient dominance in premium baking channels. FDA food safety modernization requirements demand HACCP documentation upgrades that smaller competitors cannot validate, creating acquisition opportunities for compliant facilities. For New Entrants and Emerging Players: Infused-dried technology without sulfite dependency offers entry into clean-label shelf life extension segments where Graceland Fruit Inc. currently holds technology-specialist positioning. White-space availability concentrates in organic-certified supply chains commanding shelf placement premiums in North American natural channels. Target direct-to-manufacturer platform development for bakery and confectionery procurement compression, bypassing traditional distributor markups entirely. For Investors and Strategic Acquirers: Distressed-cycle entries favor equipment-forward processors in India facing BIS quality standard certification delays that organized retail gatekeepers enforce. Long-term viability centers on facilities with integrated renewable energy drying securing preferential EU retailer access under tightening carbon footprint disclosure rules. Watch for FDA validation cost exhaustion among small US processors as inflection indicator for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Freeze-Drying Capacity Expansion | Nitrogen-flushing equipment electrifies color retention benchmarks challenging imported ingredient dominance. |
| Backward Integration into Berry Orchards | Ocean Spray's cooperative structure controls Wisconsin and Massachusetts raw cranberry supply against climate volatility. |
| EU Green Deal Compliance Investment | Renewable energy drying infrastructure secures preferential retailer access under tightening carbon disclosure rules. |
| Direct-to-Manufacturer Platform Launch | Ingredient houses bypass traditional distributor margins through captive portals for bakery procurement. |
| USDA Organic Certification Program | Certified supply chains command shelf placement premiums in North American natural retail channels. |
Methodological Framework
Document review covered FDA food safety modernization guidance, EU EFSA health claim substantiation dossiers, and BIS quality standard specifications for India, complemented by interviews with freeze-drying equipment specialists, cooperative procurement directors, and clean-label confectionery brand managers. Secondary validation drew from USDA organic certification databases, customs trade records for dried fruit imports, and SEC filings from publicly traded food processors. Bottom-up volume estimates triangulated against top-down market sizing from identified value chain participants.
Output specifications tracked freeze-dried versus air-dried technology splits, organic versus conventional certification tiers, and pouch versus bulk packaging format shares across the analysis window. Modeled segmentation spanned product type, end-use application, packaging configuration, and distribution channel dimensions. CAGRs derived from historical shipment data cross-referenced with processor capacity expansion announcements and retailer SKU proliferation rates. Forecast inputs incorporated EU Green Deal implementation timelines and SAMR food safety standard evolution for China market entry assessment.
Forecast precision tightens around the base case; tail outcomes carry wider variance under climate-driven harvest variability in concentrated growing regions and regulatory timeline slippage for EFSA health claim reformulation requirements. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
North America Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Europe Olive Market
Fruits and Vegetables
Turkish Figs Market
Fruits and Vegetables
Middle East and Africa Sweet Potatoes Market
Fruits and Vegetables
Lycopene Market
Fruits and Vegetables
Cavendish Banana Market
Fruits and Vegetables
United States Guacamole Market
Fruits and Vegetables
Bahrain Fruits and Vegetables Market
Fruits and Vegetables
Europe Blueberry Market
Fruits and Vegetables
Celery Juice Market
Fruits and Vegetables
North America Olive Market
Fruits and Vegetables
Global Morel Mushroom Market
Fruits and Vegetables
Aubergine Market
Fruits and Vegetables
Button Mushroom Products Market
Fruits and Vegetables
Global Orange Market
Fruits and Vegetables
Starchy Roots Market