
 Surimi by-Product Market | 2026-2036
Surimi by-Product Market Size, Share, and Industry Trends Forecast 2026-2036
Surimi by-Product Market Analytics
Modular portion packs and ingredient bundling for foodservice distributors is expanding buyer flexibility across the surimi by-product value chain. Maruha Nichiro Corporation leverages its integrated Pacific Rim processing network to secure raw material flows. Nippon Suisan Kaisha anchors quality differentiation through stringent cold-chain protocols. Thai Union Group PCL competes on scale in Southeast Asian snack ingredient supply.
Surimi by-product denotes the residual protein-rich material—myofibrillar fractions, connective tissue, and minced flesh—recovered after primary surimi extraction from Alaska pollock, Pacific whiting, or tropical threadfin bream, typically containing 10-15% protein and repurposed for fishmeal, pet food, or hydrolyzed flavor bases. Its commercial purpose centers on maximizing extractive yield from trawl-caught whitefish while reducing seafood processing waste streams. Fish paste applications lead volume absorption due to entrenched demand in East Asian culinary manufacturing, while seafood snacks represent the fastest-expanding margin pool as convenience formats proliferate in Asian retail channels. Plant proteins within raw material sourcing show structural momentum as blend formulations reduce species dependency.
FDA seafood HACCP regulations and Japan's Fisheries Agency sanitation standards govern import eligibility and processing facility certification for surimi-derived ingredients entering North American and Japanese markets. EU REACH and EFSA frameworks constrain chemical additive profiles in by-product hydrolysates destined for European pet food and feed compounders. Stakeholders must monitor evolving traceability mandates and alternative protein blending ratios to preserve market access.
Market Dynamics
Japan's Fisheries Agency traceability mandates and cold-chain technology investments are tightening quality benchmarks across the surimi by-product value chain, forcing processors to upgrade facility certification and documentation protocols to maintain market access.
Growth Catalysts
- Aquaculture feed substitution:Fishmeal replacement accelerates in Southeast Asian aquaculture operations as surimi-derived protein fractions offer cost-competitive amino acid profiles for shrimp and finfish feed formulations.
- FDA seafood HACCP:Harmonized import standards between US and Japanese regulators reduce duplicative testing burdens, streamlining cross-border ingredient flows for qualified processors.
- Enzymatic hydrolysis:Protease-based recovery systems extract higher-value flavor base compounds from residual connective tissue, expanding margin capture beyond commodity fishmeal applications.
Market Restraints
- Raw material concentration:Alaska pollock and Pacific whiting stocks face seasonal quota variability, concentrating supply risk among North Pacific trawl operators.
- EU REACH compliance costs:Chemical additive profiling requirements for hydrolysate exports impose analytical testing burdens that exclude smaller Southeast Asian processors from European pet food supply chains.
- Plant protein substitution:Pea and soy protein isolates gain formulation share in snack manufacturing, compressing demand elasticity for surimi-derived binders in mid-tier product segments.
Strategic Opportunities
- Indonesian snack manufacturing:Underpenetrated processing capacity in Surabaya and Medan clusters offers first-mover positioning for modular ingredient bundling to regional distributors.
- Thai Union cold-chain partnerships:Third-party logistics integration with established seafood networks reduces capex barriers for new entrants seeking ASEAN market access.
- Dual carbon goals:China's MEE waste-to-resource incentives align with circular economy positioning for protein recovery operations, opening state-backed procurement channels.
Industry Challenges
- HACCP auditor scarcity:Certified seafood sanitation assessors remain concentrated in Japan and Thailand, creating facility certification bottlenecks for Vietnamese and Indonesian greenfield projects.
- Legacy ERP integration:Lot-level traceability software deployment conflicts with existing inventory management systems, forcing parallel operational workflows during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surimi by-Product Market |
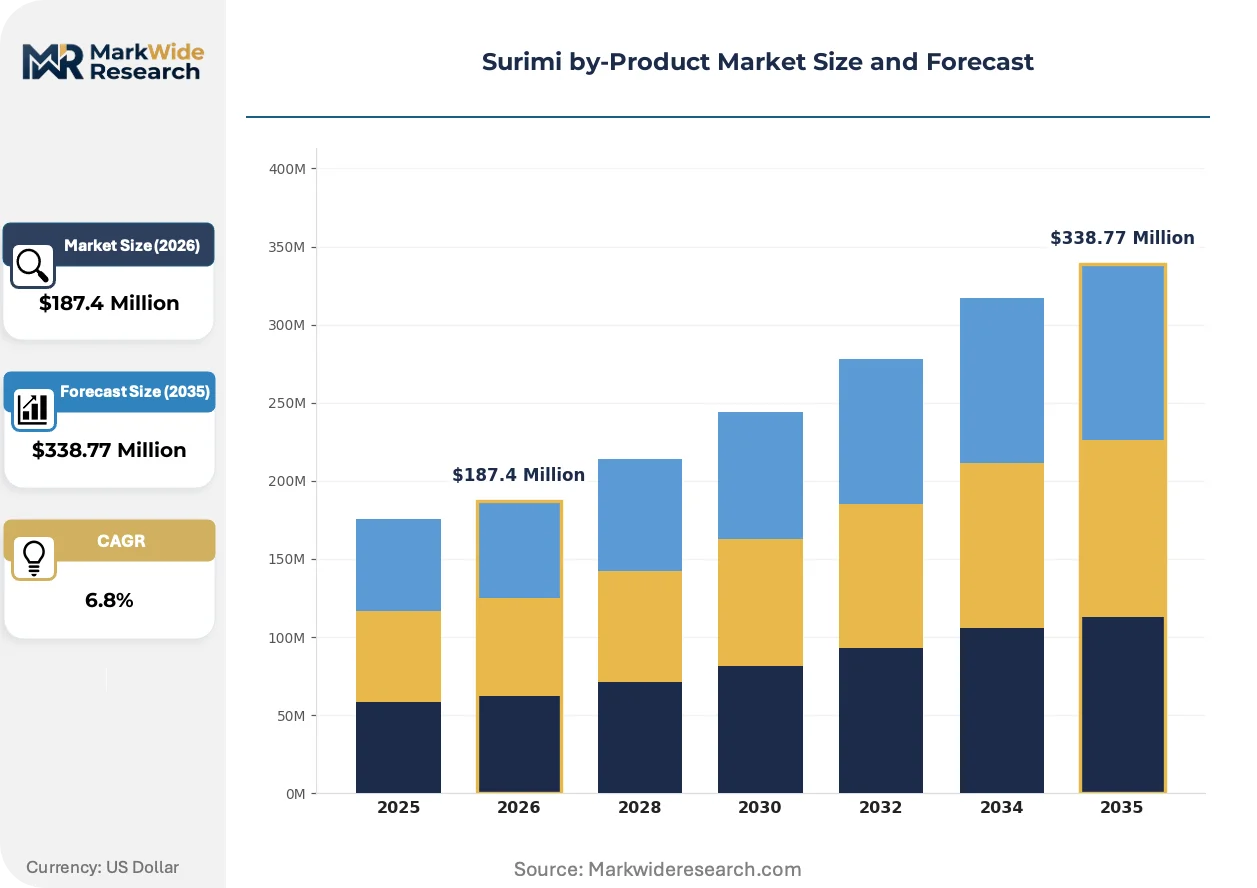
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surimi Fillets, Fish Paste, Seafood Snacks, Imitation Crab Raw Material: Fish, Crustaceans, Marine Ingredients, Plant Proteins Application: Food Processing, Culinary Uses, Snack Manufacturing, Restaurant Supply Distribution Channel: Wholesale, Retail, E-commerce, Foodservice |
| Companies Covered | Maruha Nichiro Corporation, Nippon Suisan Kaisha, Ltd., Thai Union Group PCL, HAI THANH CO., LTD, MEENA Brand Surimi, APITOON GROUP, Starfish Co., Ltd., Zhejiang Longsheng Aquatic Products Co., Ltd., SEAPRIMEXCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surimi by-Product Market Evolving Landscape
Active recovery technologies and regulatory digitization are compressing processing timelines while fragmenting buyer procurement patterns across the surimi by-product value chain.
Membrane filtration systems for protein fractionation are overtaking traditional centrifugal separation in premium hydrolysate production. Thai and Vietnamese processors deploy ceramic ultrafiltration modules to isolate myofibrillar proteins for high-margin flavor base applications. This technology is overtaking conventional drum-drying methods by reducing thermal degradation and enabling cold-chain preservation of functional protein properties.
Japan's Fisheries Agency electronic traceability mandates require blockchain-anchored catch documentation for all imported surimi-derived ingredients entering Japanese food manufacturing channels. Processors must integrate vessel monitoring system data with lot-level laboratory analysis to satisfy sanitation certificate requirements. Southeast Asian exporters with existing HACCP certification face accelerated compliance timelines as the 2025 implementation window contracts.
Ingredient bundling contracts now consolidate surimi by-product procurement with primary surimi volumes, compressing spot market liquidity for standalone residual material purchases. Foodservice distributors in Bangkok and Ho Chi Minh City negotiate modular portion packs combining protein fractions, hydrolysates, and flavor bases under single-source agreements. This procurement consolidation is most visible in Thailand where integrated processors leverage scale advantages to disaggregate smaller independent traders from mid-tier snack manufacturer accounts.
Surimi by-Product Market Segmentation
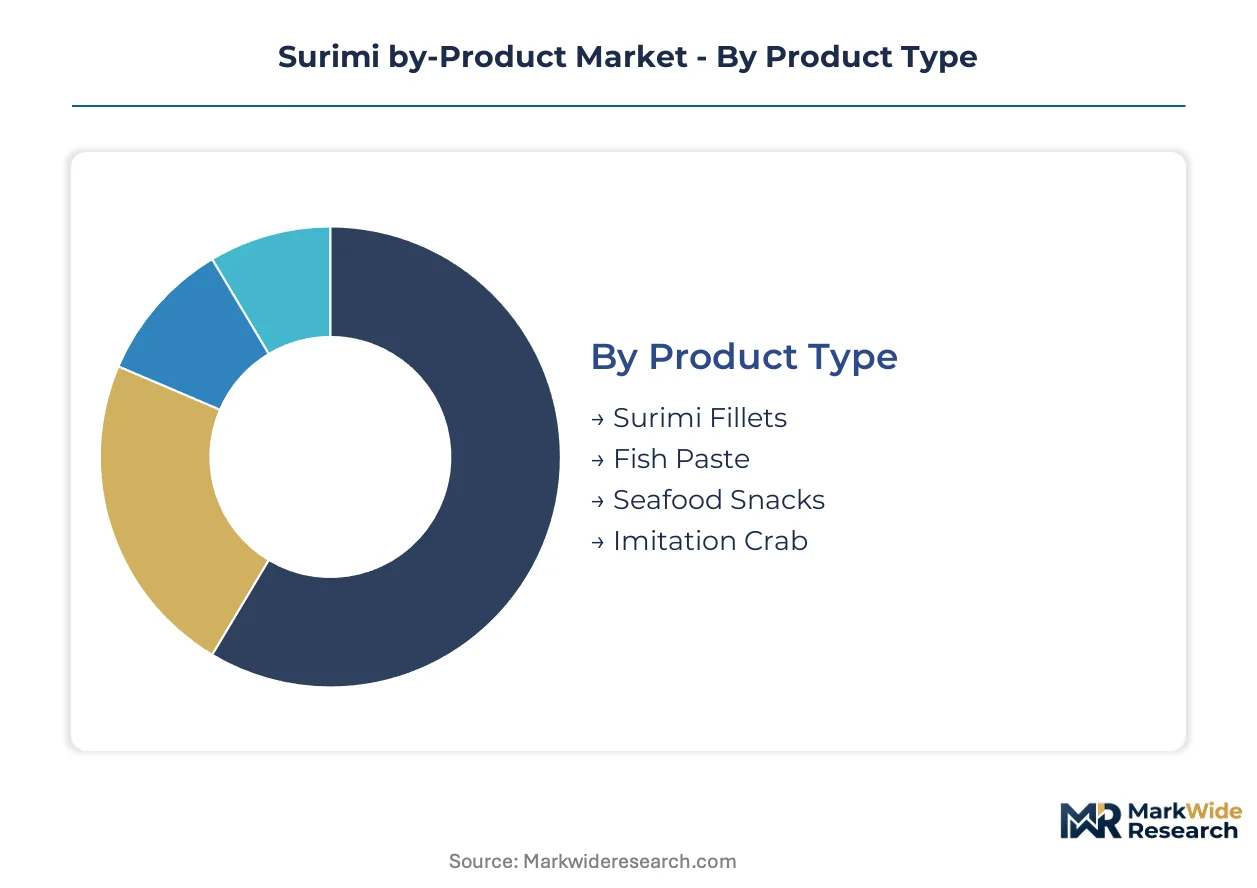
Segmentation in the surimi by-product market tracks how residual protein fractions flow into distinct value chains. Product type and raw material sourcing determine margin capture, while application and channel choices shape procurement consolidation patterns across Southeast Asian processing clusters.
Product Type:
Functional protein specifications define how residual surimi material commands price premiums across manufacturing tiers.
- Fish Paste:Myofibrillar protein concentrates with 10-15% residual moisture content serve as binding agents in East Asian surimi-based food manufacturing. Demand concentrates in Japan and South Korea where traditional kamaboko production maintains steady offtake from Hokkaido and Busan processing facilities.
- Seafood Snacks:Dehydrated and flavored protein strips target convenience retail channels with higher margin capture than commodity fishmeal. Thailand and Vietnam absorb expanding volumes as 7-Eleven and Lawson formats proliferate frozen and shelf-stable snack SKUs.
- Surimi Fillets:Residual minced flesh reformed into structured protein blocks for secondary processing applications.
- Imitation Crab:Flaked and colored surimi derivatives for foodservice and retail seafood salad manufacturing.
Fish paste leads on scale; seafood snacks lead on momentum.
Raw Material:
Species dependency and blend flexibility are reshaping procurement risk profiles across Pacific Rim supply chains.
- Fish:Alaska pollock and Pacific whiting myofibrillar fractions dominate protein recovery yields with superior gel-forming properties. North Pacific trawl quotas from the Bering Sea and Gulf of Alaska concentrate supply risk among seasonal catcher-processor fleets.
- Plant Proteins:Pea and soy isolates enter hybrid formulations to reduce species dependency and stabilize input costs. Indonesian and Thai snack manufacturers blend 15-30% plant fractions to hedge against pollock price volatility while maintaining texture specifications.
- Crustaceans:Shrimp and crab processing residuals with distinct flavor profiles for premium hydrolysate applications.
- Marine Ingredients:Seaweed extracts and fish oil co-products for nutritional fortification in pet food and aquafeed.
Fish raw materials anchor volume throughput; plant proteins are climbing the fastest as formulation flexibility gains priority.
Application:
End-use specifications fragment buyer requirements across industrial, commercial, and retail channels.
- Food Processing:Bulk protein fractions and hydrolysates for surimi block manufacturing and flavor base compounding. Japanese and Thai integrated processors consume the largest volumes under long-term procurement contracts with cold-chain guarantees.
- Snack Manufacturing:Dehydrated strips, puffed textures, and seasoned formats for branded convenience retail. Vietnam's Da Nang and Indonesia's Surabaya clusters show steepest expansion trajectory as domestic consumption and export demand converge.
- Culinary Uses:Traditional fish paste preparations for restaurant and home cooking applications in East Asian markets.
- Restaurant Supply:Portion-controlled protein packs for foodservice distributors in Bangkok and Ho Chi Minh City.
Food processing leads on scale; snack manufacturing leads on momentum.
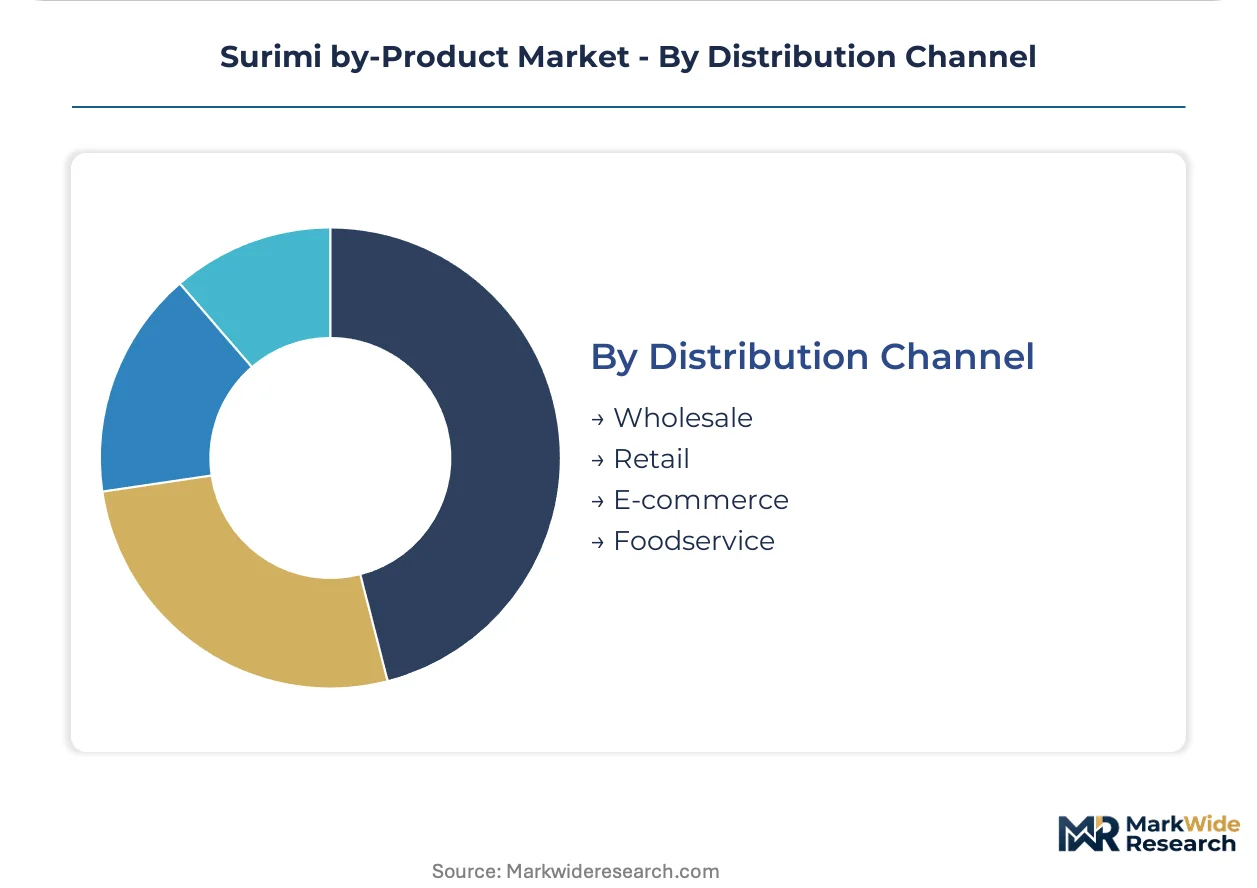
Distribution Channel:
Channel configuration determines working capital intensity and traceability documentation burdens for residual material flows.
- Wholesale:Containerized bulk shipments of dried fishmeal and protein concentrates to aquafeed compounders and pet food manufacturers. Thai Union and Maruha Nichiro leverage established cold-chain networks to aggregate volumes from multiple processing sites.
- Foodservice:Modular ingredient bundling combining protein fractions, hydrolysates, and flavor bases under single-source agreements. Bangkok and Ho Chi Minh City distributors negotiate consolidated procurement to reduce transaction costs for mid-tier snack manufacturers.
- Retail:Packaged consumer formats through supermarket and convenience store channels.
- E-commerce:Direct-to-manufacturer platforms for specialty hydrolysates and small-batch protein fractions.
Wholesale leads on scale; foodservice leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Surimi by-product processing originated in Japan during the 1960s as industrial-scale fish paste manufacturing consolidated around Hokkaido and Kyushu. The technology subsequently migrated to Southeast Asia during the 1990s, establishing Thailand and Vietnam as secondary processing centers. Today, residual protein recovery operations span the Pacific Rim with distinct regulatory and infrastructure profiles.
Japan
Traditional kamaboko manufacturers in Hokkaido and Nagasaki prefectures sustain steady demand for myofibrillar protein concentrates. Japan's Fisheries Agency enforces electronic traceability mandates requiring blockchain-anchored catch documentation for all imported surimi-derived ingredients. Cold-chain technology investments concentrate in the Chubu region around Nagoya, where integrated processors upgrade facility certification to maintain sanitation certificate compliance.
Thailand
Snack manufacturing expansion in Bangkok and Samut Sakhon provinces drives accelerating absorption of dehydrated protein strips for convenience retail formats. The country's national food and drug regulator aligns with FDA seafood HACCP standards to streamline export eligibility to North American markets. Thai Union Group PCL anchors scale advantages in the Eastern Economic Corridor, consolidating procurement volumes from multiple processing sites under single-source distribution agreements.
Vietnam
Aquaculture feed compounders in Da Nang and Ho Chi Minh City clusters substitute surimi-derived protein fractions for fishmeal in shrimp and finfish formulations. The Ministry of Agriculture and Rural Development implements traceability protocols for seafood exports that parallel Japanese sanitation benchmarks. Processing capacity expansion in the Mekong Delta region attracts third-party logistics integration with established cold-chain networks.
Indonesia
Underpenetrated snack manufacturing infrastructure in Surabaya and Medan offers positioning opportunities for modular ingredient bundling to regional distributors. The Ministry of Environment and Forestry promotes waste-to-resource incentives that align with circular economy positioning for protein recovery operations. Domestic consumption growth and export demand convergence accelerate capacity deployment in Java and Sumatra processing clusters.
China
State-backed procurement channels open through the Ministry of Ecology and Environment's dual carbon goals, which incentivize protein recovery from seafood processing waste streams. Yangtze River Delta processors in Zhejiang province deploy membrane filtration systems to isolate functional proteins for high-margin hydrolysate applications. Zhejiang Longsheng Aquatic Products Co., Ltd. exemplifies regional scale in residual material valorization.
Surimi by-Product Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade and cold-chain capability dimensions. The market structures around three tiers: integrated Pacific Rim conglomerates with captive raw material flows, Southeast Asian scale processors competing on volume aggregation, and regional specialists focused on single-product hydrolysate or snack ingredient niches. Dominant competitive moves include strategic partnerships with third-party logistics providers and backward integration into trawl-catcher operations to secure pollock and whiting supply quotas.
Among Japanese integrated conglomerates, Maruha Nichiro Corporation and Nippon Suisan Kaisha, Ltd. exemplify the premium-tier archetype through established cold-chain protocols and facility certification density. Thai Union Group PCL anchors the Southeast Asian scale vector, occupying a position that leverages distribution network consolidation to disaggregate smaller independent traders. These three entities represent distinct strategic postures: Japanese players emphasize quality differentiation and traceability compliance, while the Thai incumbent competes on procurement bundling and regional market access.
| Leading Market Players |
|---|
| Maruha Nichiro Corporation |
| Nippon Suisan Kaisha, Ltd. |
| Thai Union Group PCL |
| HAI THANH CO., LTD |
| MEENA Brand Surimi |
| APITOON GROUP |
| Starfish Co., Ltd. |
| Zhejiang Longsheng Aquatic Products Co., Ltd. |
| SEAPRIMEXCO |
| Others |
Value Network & Pricing Analysis
Japanese Fisheries Agency electronic traceability mandates are compressing procurement timelines for Southeast Asian processors, forcing facility certification upgrades that concentrate pricing power among cold-chain-capable suppliers while marginalizing uncertified traders.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by HACCP certification grade and cold-chain integrity. Premium tiers command spreads based on blockchain-anchored documentation and Nagoya-region processing, while economy tiers face compression from plant protein substitution in Indonesian snack formulations. Thai Union's procurement bundling is accelerating price erosion among standalone residual material traders. Aquafeed compounders in Da Nang exhibit highest price sensitivity; Japanese kamaboko manufacturers show lowest elasticity due to specification lock-in.
Supply Chain Analysis
Japan's domestic-content requirements for traceability documentation are reshaping sourcing patterns across Pacific Rim networks. Raw material flows concentrate in Thailand, Vietnam, and Indonesia where processing clusters feed from Alaska pollock and Pacific whiting quotas. Membrane filtration equipment, ceramic ultrafiltration modules, and blockchain traceability software constitute critical input dependencies. Single-source vulnerability runs through North Pacific trawl operator concentration for whitefish quotas. Distribution runs through Thai Union and Maruha Nichiro's integrated cold-chain networks to Bangkok and Ho Chi Minh City foodservice distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as aquaculture feed substitution creates durable offtake for protein recovery operations across Southeast Asian processing clusters.
For Market Incumbents: Hedge pollock quota volatility through backward integration into tropical threadfin bream sourcing from Indonesian waters. Deepen cold-chain partnerships with third-party logistics providers in Vietnam's Mekong Delta to preempt certification bottlenecks. Plant protein substitution in mid-tier snack segments demands accelerated enzymatic hydrolysis R&D to capture flavor base premiums. For New Entrants and Emerging Players: Direct-to-manufacturer e-commerce platforms for specialty hydrolysates offer lowest barrier entry into surimi by-product value chains. Surabaya and Medan snack manufacturing clusters present underpenetrated demand for modular ingredient bundling. Target Indonesian domestic consumption growth through waste-to-resource positioning aligned with Ministry of Environment and Forestry incentives. For Investors and Strategic Acquirers: Asymmetric upside sits with Southeast Asian scale processors possessing HACCP certification density and Thai Union distribution access. Five-to-ten year viability rests on aquaculture feed formulation permanence and circular economy policy tailwinds. Monitor China's MEE dual carbon procurement channel openings as inflection signal for state-backed volume commitments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Trawl Operations | Secures Alaska pollock and Pacific whiting quotas against seasonal variability. |
| Cold-Chain Partnership Expansion | Integrates third-party logistics with Nagoya and Bangkok facility networks. |
| Enzymatic Hydrolysis Scale-Up | Extracts premium flavor bases from residual connective tissue for Japanese food manufacturers. |
| Blockchain Traceability Deployment | Satisfies Japan's Fisheries Agency electronic documentation mandates for import eligibility. |
| Modular Ingredient Bundling | Consolidates protein fractions, hydrolysates, and flavor bases for Ho Chi Minh City distributors. |
Research Methodology
Multiple input streams — executive interviews with seafood processing plant managers, regulatory affairs specialists at Japan's Fisheries Agency, procurement leads at Thai aquafeed compounders, and Bangkok foodservice distributors — were reconciled against customs trade data, SEC filings from Maruha Nichiro and Nippon Suisan Kaisha, and Japanese sanitation certificate databases. Secondary validation drew from Thailand's FDA alignment documentation, Vietnam's Ministry of Agriculture traceability protocols, and Indonesian Ministry of Environment circular economy filings. Bottom-up volume aggregation across processing clusters was cross-checked against top-down market sizing from trade flow analysis.
Historical production volumes from Hokkaido, Nagasaki, and Chubu region facilities were benchmarked against panel input from Southeast Asian scale processors to anchor growth assumptions across the projection horizon. Segmentation modeling tracked product type, raw material sourcing, application end-use, and distribution channel dimensions. CAGRs were derived from elasticity-adjusted demand curves for aquafeed substitution rates and snack manufacturing expansion trajectories. Forecast inputs incorporated membrane filtration adoption curves and blockchain traceability compliance timelines.
The model assumes a particular technology adoption path; alternative pathways for ceramic ultrafiltration and enzymatic recovery systems would alter the outlook if cost curves shift faster than baseline assumptions. Forecasts reflect documented assumptions about Japanese regulatory enforcement intensity and Southeast Asian cold-chain infrastructure buildout. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Canned Salmon Market
Seafood
Asia Pacific Canned Seafood Market
Seafood
United States Seafood Market
Seafood
Tuna Market
Seafood
Global Frozen and Canned Seafood Market
Seafood
Global Commercial Fishing Market
Seafood
Food Clamshells Market
Seafood
Trout Market
Seafood
Fish Nutrition Market
Seafood
Organic Shrimp Market
Seafood
Seafood Processing Market
Seafood
Tuna and Algae Omega-3 Market
Seafood
Crustacean Market
Seafood
United States Salmon Market
Seafood
Dried Scallop Market
Seafood
Organic Salmon Market