
 Surimi Market | 2026-2036
Surimi Market Size, Share, and Industry Trends Forecast 2026-2036
Surimi Market Analysis
Aftermarket service revenue in surimi processing equipment is reshaping how capital deployment flows across the value chain. Maruha Nichiro Group leverages integrated cold-chain logistics to sustain premium positioning in Japanese retail channels. Viciunai Group anchors European supply through specialized frozen-surimi production at scale in Lithuania. Sugiyo competes on technology leadership in automated surimi washing and refining systems for Asian processors.
Surimi denotes a mechanically deboned fish paste, typically containing 15-20% protein with moisture content held below 80%, produced through repeated washing of minced white fish flesh to remove fat and soluble proteins before cryoprotectant addition and frozen storage. Its primary commercial purpose centers on forming the protein base for crab-flavored seafood sticks, kamaboko, and other textured analogues that substitute higher-cost shellfish and finfish in prepared foods. Frozen Surimi occupies the dominant margin pool as the foundational input for downstream food manufacturing, while Surimi-based Snacks represent the fastest-growing application as convenience-oriented retail formats expand in urban Asian markets. Restaurants and Retail Chains diverge in procurement patterns, with foodservice operators demanding higher gel-strength grades for visible texture in finished dishes.
FDA regulations in the United States govern surimi labeling under seafood hazard analysis protocols, while Japan's Food Sanitation Act enforces additive limits and microbiological standards for domestic kamaboko production. The EU's EFSA reviews fish protein imports under combined food safety and illegal, unreported, and unregulated fishing traceability requirements. Stakeholders must monitor evolving cold-chain energy costs and shifting whitefish raw-material access as Arctic and North Pacific quota negotiations redefine supply security.
Market Dynamics
Arctic and North Pacific quota negotiations are restructuring whitefish raw-material access, forcing processors to rebuild supply security around alternative species and geographic sourcing clusters.
Growth Catalysts
- Japan's Food Sanitation Act enforcement:Domestic kamaboko manufacturers face additive limits and microbiological standards that elevate quality premiums for certified surimi imports.
- Thailand coastal processing clusters:Expanded cold-chain infrastructure enables export-grade frozen surimi output to reach Asian retail and foodservice channels at scale.
- Automated surimi washing systems:Technology leadership in refining equipment reduces labor intensity and improves protein recovery rates for mid-sized processors.
Market Restraints
- Whitefish quota volatility:Alaska pollock and Pacific whiting TAC reductions in the Bering Sea and Gulf of Alaska concentrate supply risk among Arctic-dependent processors.
- Energy cost escalation:Frozen surimi production requires continuous sub-zero storage and transport, exposing margins to electricity and diesel price spikes in coastal processing zones.
- Plant-based seafood analogues:Pea and soy protein extrusion technologies are capturing shelf space in European and North American retail, pressuring surimi's cost-positioning in lower-grade applications.
Strategic Opportunities
- Indonesia domestic market penetration:Urban convenience retail expansion in Jakarta and Surabaya creates demand for surimi-based snack formats with localized flavor profiles.
- EU IUU fishing traceability integration:EFSA import review protocols favor processors with documented chain-of-custody systems, creating competitive separation for compliant suppliers.
- E-commerce frozen food channels:Direct-to-consumer cold-chain logistics in South Korea and Japan enable premium surimi product discovery outside traditional wholesale structures.
Industry Challenges
- Skilled technician scarcity:Automated refining system operation and cryoprotectant formulation require specialized training that outpaces vocational program output in Southeast Asian processing hubs.
- Multi-jurisdiction certification timelines:Simultaneous FDA seafood HACCP, Japan Food Sanitation Act, and EU EFSA compliance creates documentation bottlenecks for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surimi Market |
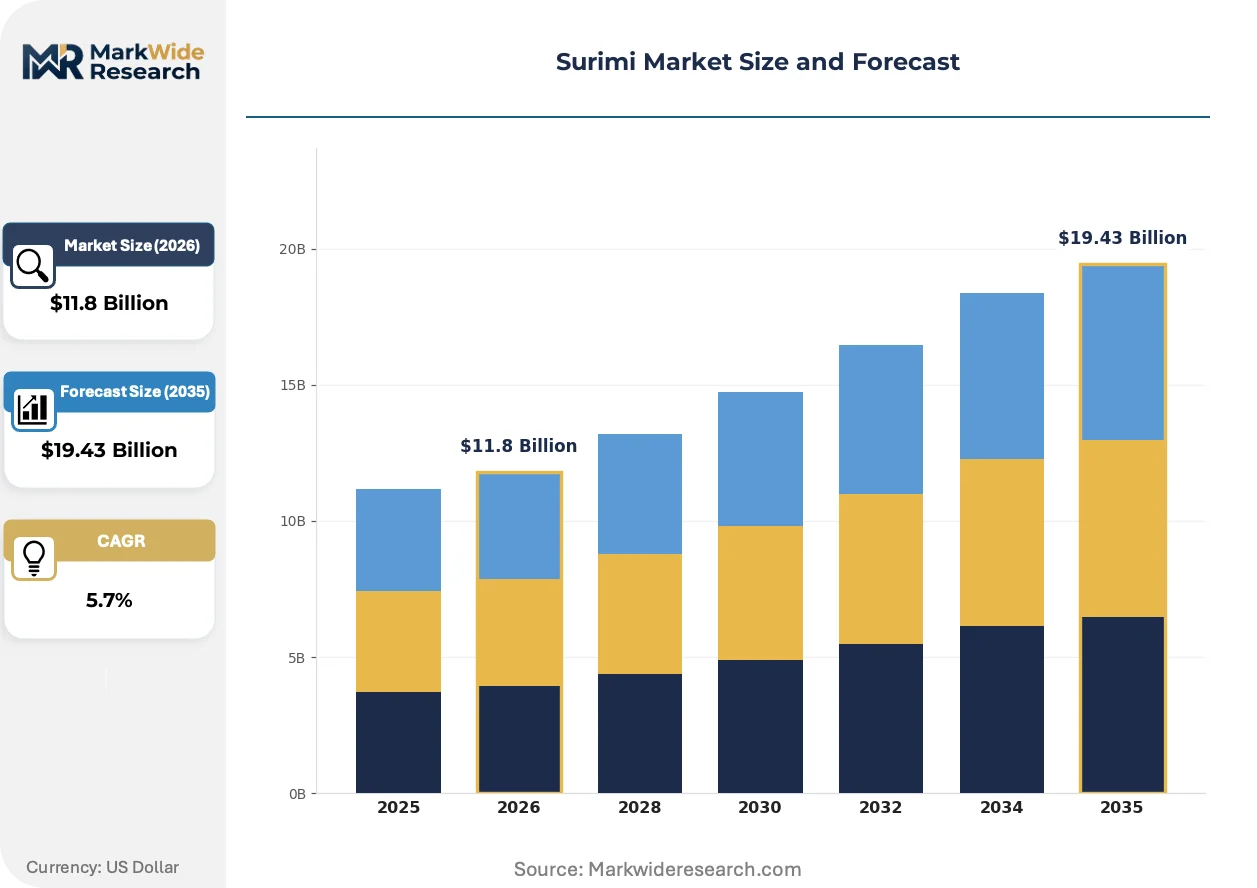
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $19.43 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Surimi, Fresh Surimi, Surimi Seafood, Surimi-based Snacks End User: Restaurants, Retail Chains, Food Processing, Supermarkets Application: Seafood Products, Soup Additives, Fillings, Fried Food Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | Starfish Co., Ltd., Viciunai Group, HAI THANH CO., LTD, Maruha Nichiro Group, Trans-Ocean Products, MEENA Brand Surimi, Java Seafood, Sugiyo, APITOON GROUP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surimi Market Emerging Trajectories
Processing technology convergence and regulatory traceability mandates are compressing traditional competitive advantages in species access and scale economies, rewarding agile supply chain reconfiguration.
High-pressure processing (HPP) technology is collapsing the shelf-life limitations that previously constrained fresh surimi distribution. Japanese retail chains and premium foodservice operators in Osaka and Tokyo are adopting HPP-treated products for chilled-case positioning. The technology is collapsing the historical trade-off between extended distribution reach and texture quality retention.
EFSA's combined food safety and IUU fishing traceability requirements are reshaping import documentation burdens. European processors must now integrate vessel monitoring data and catch certificates into standard customs filings. Frozen surimi shipments from non-EU origins face extended clearance protocols, pushing buyers toward pre-certified supply partnerships.
Urban Asian convenience retail formats are fragmenting procurement authority away from centralized wholesale markets. Retail chains in Bangkok, Seoul, and Singapore now specify gel-strength grades and additive profiles directly with processors. This channel compression is visible most acutely in Thailand, where 7-Eleven and Lawson expansion drives demand for individually portioned surimi snack products with 90-day frozen shelf life.
Surimi Market Segmentation
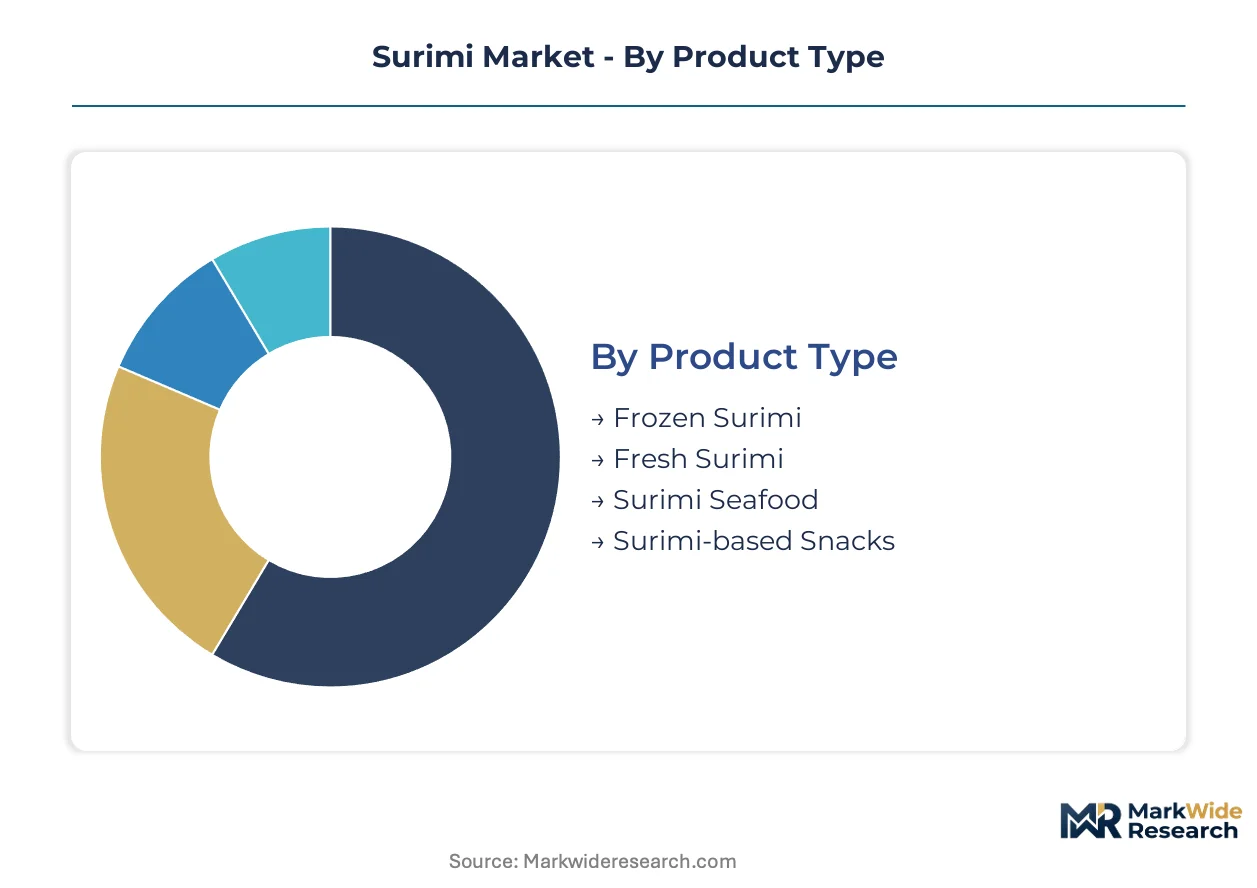
Surimi segmentation reflects divergent cold-chain economics and texture specifications across downstream channels. Product form and end-use application determine margin capture, with frozen formats commanding infrastructure premiums and fresh variants requiring proximity to processing clusters.
Product Type:
Use-case spectrum spans industrial ingredient supply through finished consumer formats, with protein stability requirements dictating commercial viability across each tier.
- Frozen Surimi:Mechanically deboned fish paste stabilized with cryoprotectants at sub-zero temperatures, typically holding 15-20% protein with moisture below 80%. Demand concentrates in Japanese and Thai food manufacturing corridors where extended distribution reach supports kamaboko and seafood analogue production at scale.
- Surimi-based Snacks:Individually portioned retail formats including crab-flavored sticks and fried bites targeting convenience retail in Bangkok, Seoul, and Singapore. This segment is expanding most quickly as urban Asian retail chains specify direct procurement relationships with localized flavor profiles.
- Fresh Surimi:Unfrozen paste distributed within limited radius of processing facilities, favored by premium foodservice operators in Osaka and Tokyo for texture-critical applications. High-pressure processing technology is collapsing traditional shelf-life constraints.
- Surimi Seafood:Finished analogue products including crab sticks and lobster-flavored pieces ready for foodservice or retail preparation. European buyers prioritize EFSA-compliant chain-of-custody documentation for import clearance.
Established volume favors Frozen Surimi; emerging adoption favors Surimi-based Snacks.
End User:
Procurement authority fragments across centralized wholesale structures and direct processor relationships, with specification intensity varying by operational scale.
- Food Processing:Industrial buyers in Thailand and Japan scale procurement for value-added seafood analogue manufacturing, demanding certified gel-strength grades and additive compliance under Japan's Food Sanitation Act.
- Restaurants:Foodservice operators specify higher gel-strength surimi for visible texture in finished dishes, with premium positioning in Japanese and South Korean urban markets driving quality premiums.
- Retail Chains:Bangkok, Seoul, and Singapore-based chains now specify additive profiles and portion formats directly, bypassing traditional wholesale layers for frozen snack procurement.
- Supermarkets:Conventional retail channels in Indonesia and Malaysia stock standardized grades for household preparation, with e-commerce frozen food platforms penetrating South Korea and Japan.
Direct specification authority concentrates in Food Processing; channel compression accelerates fastest in Retail Chains.
Application:
Functional requirements range from structural protein base to flavor carrier, with thermal processing demands shaping ingredient selection.
- Seafood Products:Crab-flavored sticks, kamaboko, and textured analogues substituting higher-cost shellfish and finfish in prepared foods. Japanese retail channels sustain premium positioning through integrated cold-chain logistics.
- Fried Food:Tempura and breaded applications in Southeast Asian foodservice, where oil absorption rates and structural integrity during high-temperature processing determine procurement decisions.
- Soup Additives:Textured inclusions for miso and hot-pot preparations, requiring moisture retention and gel stability through extended simmering.
- Fillings:Processed surimi incorporated into dumplings, buns, and stuffed preparations across Chinese and Southeast Asian manufacturing.
Texture visibility drives premium capture in Seafood Products; operational versatility expands fastest in Fried Food.
Distribution Channel:
Cold-chain reliability and documentation burden reshape route-to-market economics, with compliance capabilities filtering supplier access.
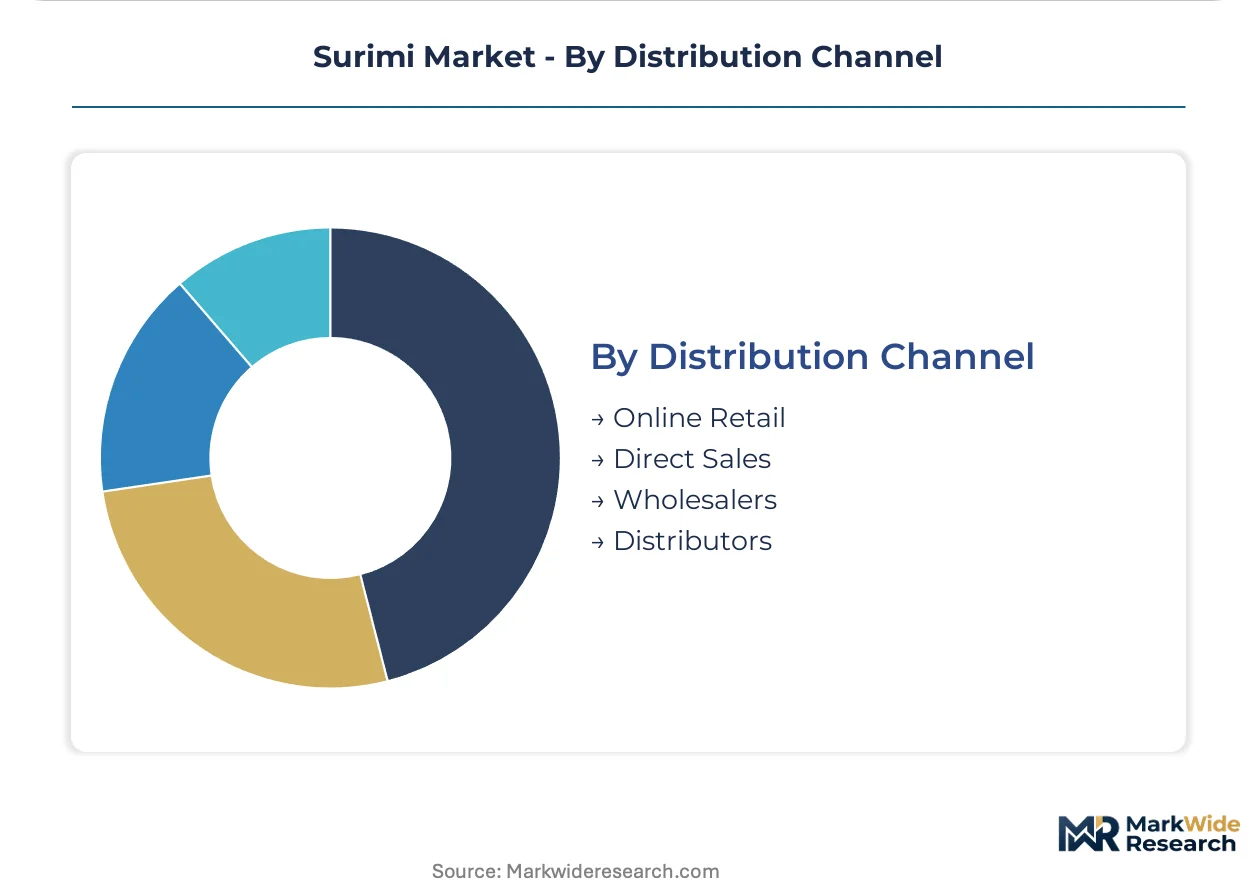
- Direct Sales:Processor-to-manufacturer relationships dominating Japanese and Thai industrial procurement, enabling customized gel-strength specifications and certified additive profiles.
- Wholesalers:Traditional centralized markets in Jakarta and Surabaya handling volume distribution for domestic Indonesian food manufacturing, with cold-chain capacity expansion enabling export-grade throughput.
- Distributors:Specialized frozen food logistics providers integrating EFSA vessel monitoring and catch certificate documentation for European market access.
- Online Retail:Direct-to-consumer platforms in South Korea and Japan leveraging last-mile cold-chain infrastructure for premium product discovery outside wholesale structures.
Documentation integration favors Distributors; margin capture shifts fastest toward Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Whitefish processing clusters concentrate in coastal zones with established cold-chain infrastructure and proximate access to quota-managed fisheries. Japan and Thailand anchor industrial capacity for frozen surimi production, while emerging processing hubs in Indonesia and Vietnam reshape procurement geography for Asian retail channels.
Japan
Domestic kamaboko manufacturers drive certified surimi imports under Food Sanitation Act enforcement. METI oversees additive limits and microbiological standards that elevate quality premiums for compliant suppliers. Osaka and Tokyo foodservice operators sustain demand for high gel-strength grades in premium positioning.
Thailand
Coastal processing clusters scale export-grade frozen surimi output through expanded cold-chain capacity. Bangkok-based retail chains including 7-Eleven and Lawson specify direct procurement relationships for individually portioned snack products. Chonburi and Samut Sakhon provinces concentrate automated refining system deployment.
Indonesia
Urban convenience retail expansion in Jakarta and Surabaya creates surimi-based snack demand with localized flavor profiles. The country's national food safety regulator enforces standards for imported fish protein inputs. Java Seafood and domestic processors build capacity to serve domestic manufacturing corridors.
South Korea
E-commerce frozen food channels enable premium surimi product discovery outside traditional wholesale structures. MFDS maintains strict labeling and cold-chain documentation requirements for imported seafood analogues. Busan-Ulsan processing zones integrate vessel monitoring data for EU-aligned export compliance.
Lithuania
Viciunai Group anchors European supply through specialized frozen-surimi production serving continental retail and foodservice. EFSA import review protocols favor processors with documented chain-of-custody systems. Klaipėda port infrastructure supports Baltic Sea distribution networks for compliant shipments.
Surimi Market Vendor Landscape
Integrated seafood conglomerates and specialized surimi processors split the market between scale-driven supply security and technology-focused refining efficiency. The structure rewards backward integration into quota-access arrangements and cold-chain logistics control. Two dominant competitive moves concentrate supply partnerships with retail chains and certification pre-alignment for multi-jurisdiction market access.
Within the integrated conglomerate tier, Maruha Nichiro Group and Viciunai Group exemplify archetypes combining captive fleet access with retail channel integration. Sugiyo occupies a position representing technology-led equipment and refining system specialization for mid-sized Asian processors. Starfish Co., Ltd. sits within the regional specialist category serving domestic Japanese kamaboko manufacturing with proximity-dependent fresh surimi distribution.
| Leading Market Players |
|---|
| Starfish Co., Ltd. |
| Viciunai Group |
| HAI THANH CO., LTD |
| Maruha Nichiro Group |
| Trans-Ocean Products |
| MEENA Brand Surimi |
| Java Seafood |
| Sugiyo |
| APITOON GROUP |
| Others |
Supply Flow & Price Mechanics
Chonburi and Samut Sakhon provinces concentrate automated refining capacity that feeds pricing power downstream to Bangkok-based retail chains specifying direct procurement relationships. Cold-chain infrastructure expansion in Thailand's coastal processing clusters compresses margin capture for intermediaries while elevating processor leverage over gel-strength grade premiums.
Pricing Analysis
Japan's Food Sanitation Act dictates the pricing tier structure across certified import grades, with additive-compliant surimi commanding premiums over standard frozen paste. Three-tier pricing structure across premium certified, standard industrial, and economy ungraded levels separates foodservice operators demanding visible texture from mass-market snack manufacturers. Cost compression in economy tiers is intensifying because plant-based analogues capture shelf space in European retail. Retail chains in Bangkok and Seoul exhibit highest price sensitivity due to direct specification authority, while Japanese kamaboko manufacturers show lowest sensitivity given regulatory compliance requirements.
Supply Chain Analysis
Alaska pollock and Pacific whiting landings from the Bering Sea and Gulf of Alaska anchor raw-material flows for Arctic-dependent processors, with secondary sourcing from Russian Far East fisheries. Frozen surimi production draws from cryoprotectant formulations, specialized refining equipment, and continuous sub-zero storage infrastructure. Single-source vulnerability concentrates in quota-managed whitefish species where TAC reductions restructure access rights. Distribution runs through processor-to-manufacturer direct sales dominating Japanese and Thai industrial procurement, with specialized frozen food logistics providers integrating EFSA documentation for European market clearance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Urban convenience retail fragmentation across Jakarta, Bangkok, and Seoul creates niche entry points for processors capable of localized flavor development and direct chain relationships.
For Market Incumbents: Build regulatory certification moats through simultaneous FDA seafood HACCP, Japan Food Sanitation Act, and EU EFSA pre-alignment to compress competitor entry timelines. Expand captive cold-chain logistics control in Thailand's coastal provinces to defend margin position against energy cost escalation. Counter plant-based analogue substitution threat by elevating gel-strength grade differentiation in premium foodservice channels. For New Entrants and Emerging Players: Build out Indonesia domestic market penetration targeting Jakarta and Surabaya convenience retail expansion with localized surimi-based snack formats. Indonesia's urban retail corridor represents the most penetrable geography given nascent processor competition and growing demand for individually portioned products. Pursue direct specification relationships with 7-Eleven and Lawson expansion teams rather than wholesale market entry. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among processors with integrated cold-chain logistics and multi-jurisdiction certification pre-alignment serving Japanese retail channels. Long-term viability over a five-to-ten year horizon favors acquisition targets combining automated refining technology with documented chain-of-custody systems for EFSA compliance. Monitor Arctic and North Pacific quota negotiation outcomes as the critical inflection signal for raw-material access security.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Certification Pre-Alignment | Simultaneous FDA, Japan Food Sanitation Act, and EU EFSA compliance compresses rival entry timelines. |
| Automated Refining System Deployment | Sugiyo's technology leadership in washing equipment reduces labor intensity for mid-sized processors. |
| Direct Retail Chain Partnership | Bangkok-based 7-Eleven and Lawson expansion enables bypass of traditional wholesale margin layers. |
| Cold-Chain Infrastructure Expansion | Chonburi and Samut Sakhon capacity buildout supports export-grade frozen surimi output at scale. |
| High-Pressure Processing Adoption | HPP technology collapses shelf-life constraints for fresh surimi distribution in Osaka and Tokyo. |
Methodological Framework
Cross-validation between primary interviews with seafood processing executives, cold-chain logistics operators, and retail procurement managers and secondary sources including Japan's Ministry of Health, Labour and Welfare filings, FDA seafood HACCP guidance documents, and EFSA import review protocols anchors the qualitative findings. Bottom-up demand modeling from food manufacturer procurement patterns triangulates against top-down trade flow analysis across the analysis window.
Calibration against historical volume trajectories and regulatory shift impacts shaped the analytical framework across product type, end user, application, and distribution channel segmentation dimensions. CAGRs were derived through trend extrapolation adjusted for whitefish quota volatility and cold-chain energy cost trajectories. Forecast inputs incorporated automated refining equipment adoption curves and urban convenience retail expansion rates in Southeast Asian markets.
Stress conditions across Arctic quota reductions, diesel price spikes in coastal processing zones, and plant-based analogue substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement continuity and cold-chain infrastructure investment flows. Cross-checking against Japanese and Thai customs trade statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Seafood Processing Market
Seafood
Organic Salmon Market
Seafood
Global Seafood Market
Seafood
North America Frozen Seafood Market
Seafood
Dry-Packaged Scallops Market
Seafood
Fish Meal and Fish Oil Market
Seafood
Fried Dace with Salted Black Beans Market
Seafood
Tuna Fish Market
Seafood
Global Frozen and Canned Seafood Market
Seafood
Haddock Market
Seafood
North America Salmon Market
Seafood
Asia Pacific Canned Seafood Market
Seafood
Tuna Market
Seafood
Vietnam Pangasius (Basa) Market
Seafood
United States Salmon Market
Seafood
Asian Sea Bass Market