
 Canned Fishery Product Market | 2026-2036
Canned Fishery Product Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Fishery Product Market Insights
Plant-based protein alternatives and recyclable aluminum substrates are shifting traditional cost structures in shelf-stable seafood. Thai Union Group PCL leverages vertical integration from vessel to shelf across Thai and Indonesian waters. StarKist Co. sustains brand dominance through retail channel control in North American supermarkets. Bumble Bee Foods, LLC anchors its position via specialized pole-and-line tuna sourcing programs.
Canned fishery products comprise thermally processed fish preserved in hermetically sealed containers, typically achieving commercial sterility through retort processing at temperatures exceeding 116 degrees Celsius to ensure shelf stability without refrigeration. These products serve as protein-dense meal solutions for foodservice operators and retail consumers requiring extended storage capability. Tuna commands the dominant volume position across product types due to established consumer familiarity and versatile application profiles. Pouch packaging represents the fastest-expanding format as brands seek to reduce shipping weights and appeal to on-the-go consumption patterns. Metal tin containers retain the largest margin pool through economies of scale in existing filling lines and established recycling infrastructure.
FDA seafood Hazard Analysis Critical Control Point regulations govern product safety and import screening for US-bound canned fish, while EU Green Deal sustainability criteria and EFSA contaminant thresholds shape European market access requirements. Thailand's Department of Fisheries and CDSCO-aligned export protocols in India impose additional traceability and residue-testing burdens on Asian processors. Stakeholders must monitor evolving extended producer responsibility mandates for packaging materials and verify that supplier certification portfolios cover both food safety and emerging carbon-accounting standards.
Market Dynamics
EU Green Deal fisheries certification requirements are tightening traceability mandates across Southeast Asian processing clusters, forcing processors to reconfigure supplier auditing systems and carbon-accounting protocols.
Growth Catalysts
- Retail Pantry Stocking:Urban households in Bangkok and Manila are maintaining larger shelf-stable protein inventories. This pattern elevates baseline consumption frequency for canned tuna and mackerel.
- EU Green Deal Compliance:Sustainability-linked procurement mandates from European retailers are creating preferential market access for certified pole-and-line operations. Thai processors with Marine Stewardship Council chain of custody gain shelf placement advantages.
- Pouch Format Conversion:Retort pouch technology reduces shipping weights by 40 percent versus metal tins. Foodservice distributors and convenience retailers are accelerating format transitions.
Market Restraints
- Skipjack Price Volatility:Raw material costs fluctuate with Western and Central Pacific Fisheries Commission quota adjustments. Processors lack pricing power to pass through input spikes.
- Thai-Indonesian Supply Concentration:Over 60 percent of global canning capacity sits in Samut Sakhon and Bitung clusters. Geopolitical or disease disruptions in these corridors cascade immediately.
- Aluminum Tariff Friction:US Section 232 duties on imported can sheet elevate packaging costs for North American-bound production. Alternative substrate qualification timelines extend 18-24 months.
Strategic Opportunities
- Vietnamese Processing Expansion:Binh Dinh and Khanh Hoa provinces offer underutilized cold-chain infrastructure and lower labor arbitrage. EU-recognised competent authority status creates export pathway.
- Plant-Based Blends:Pea-protein and algae-extract formulations targeting flexitarian households open shelf-space adjacent to conventional seafood. Retailers seek category growth without species substitution.
- Extended Producer Responsibility:EU Packaging and Packaging Waste Regulation mandates shift cost burden to producers. Early compliance investments secure recycling infrastructure partnerships.
Industry Challenges
- Traceability System Integration:Blockchain-enabled catch documentation must interface with legacy ERP platforms at multi-site processors. Data standardisation across vessel monitoring systems remains incomplete.
- Retort Technician Shortage:Thermal process validation and container closure integrity testing require specialised expertise. Training pipelines have not kept pace with capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canned Fishery Product Market |
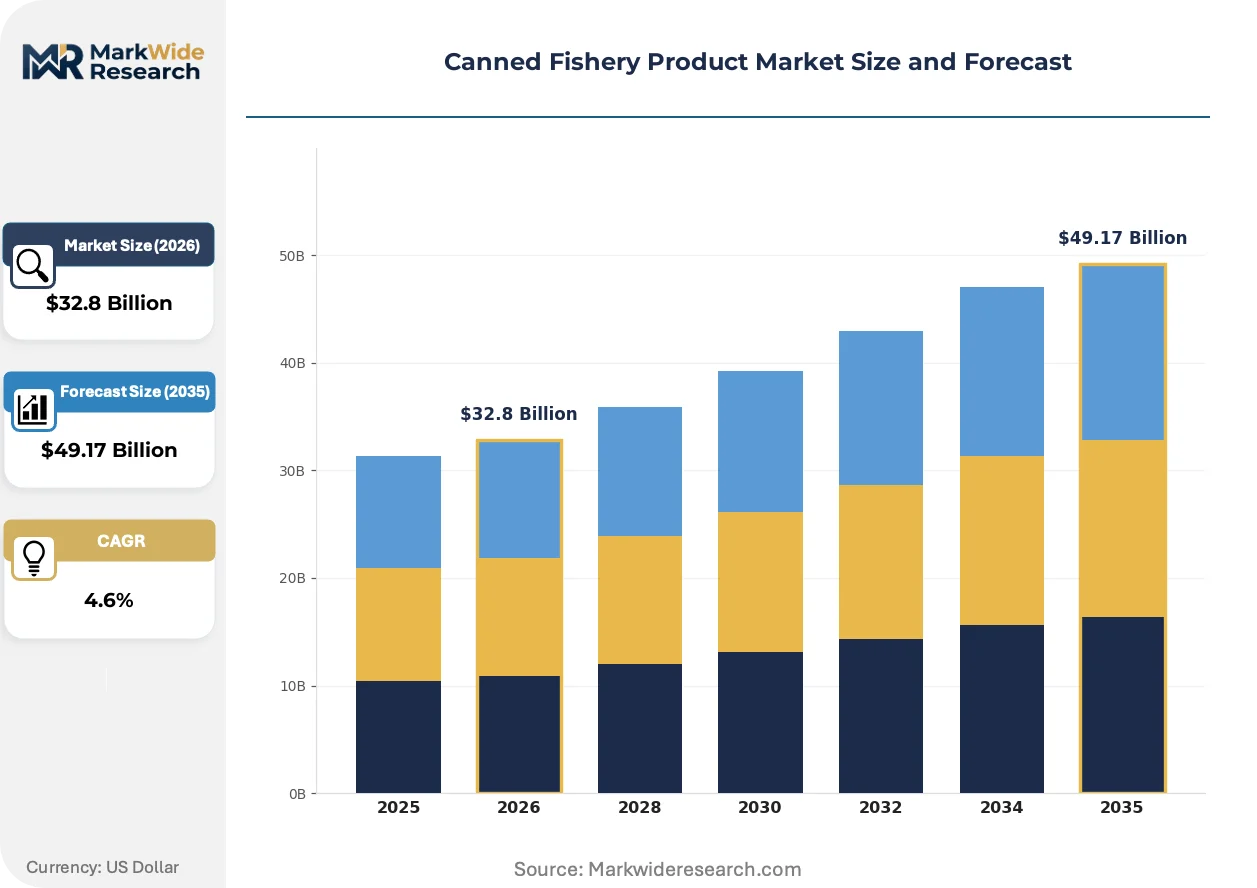
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $49.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tuna, Salmon, Sardines, Mackerel Packaging Type: Metal Tin, Glass Jar, Pouch, Plastic Container Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Shops End User: Households, Restaurants, Food Manufacturers, Catering Services |
| Companies Covered | Thai Union Group PCL, StarKist Co., Bumble Bee Foods, LLC, Trident Seafoods Corporation, Maruha Nichiro Corporation, Century Pacific Foods Inc., Bolton Group, Dongwon Enterprises Co. Ltd., American Tuna Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Fishery Product Market Trends and Innovations
Active packaging formats and digital traceability layers are compressing traditional quality-assurance timelines while expanding the addressable market for shelf-stable seafood beyond conventional retail channels.
Retort pouch technology is expanding into ambient seafood segments previously dominated by cylindrical metal containers. Convenience retailers and airline catering buyers are adopting the format for reduced logistics cost and improved cube utilisation. The shift is compressing capital requirements for new market entrants while fragmenting the supplier base beyond traditional can-making conglomerates.
EU Green Deal sustainability criteria are reshaping import eligibility for Thai and Philippine processors. EFSA contaminant thresholds for methylmercury and histamine now trigger automatic border rejection protocols. Premium private-label suppliers are responding with vessel-level digital monitoring and pre-export laboratory certification.
Urban household pantry rotation patterns are shortening repurchase cycles for shelf-stable protein. Direct-to-pantry subscription models from ASEAN-based processors are bypassing traditional wholesale distribution in Singapore and Hong Kong. The channel shift is most visible among dual-income households seeking meal-kit integration with existing inventory.
Canned Fishery Product Market Segmentation
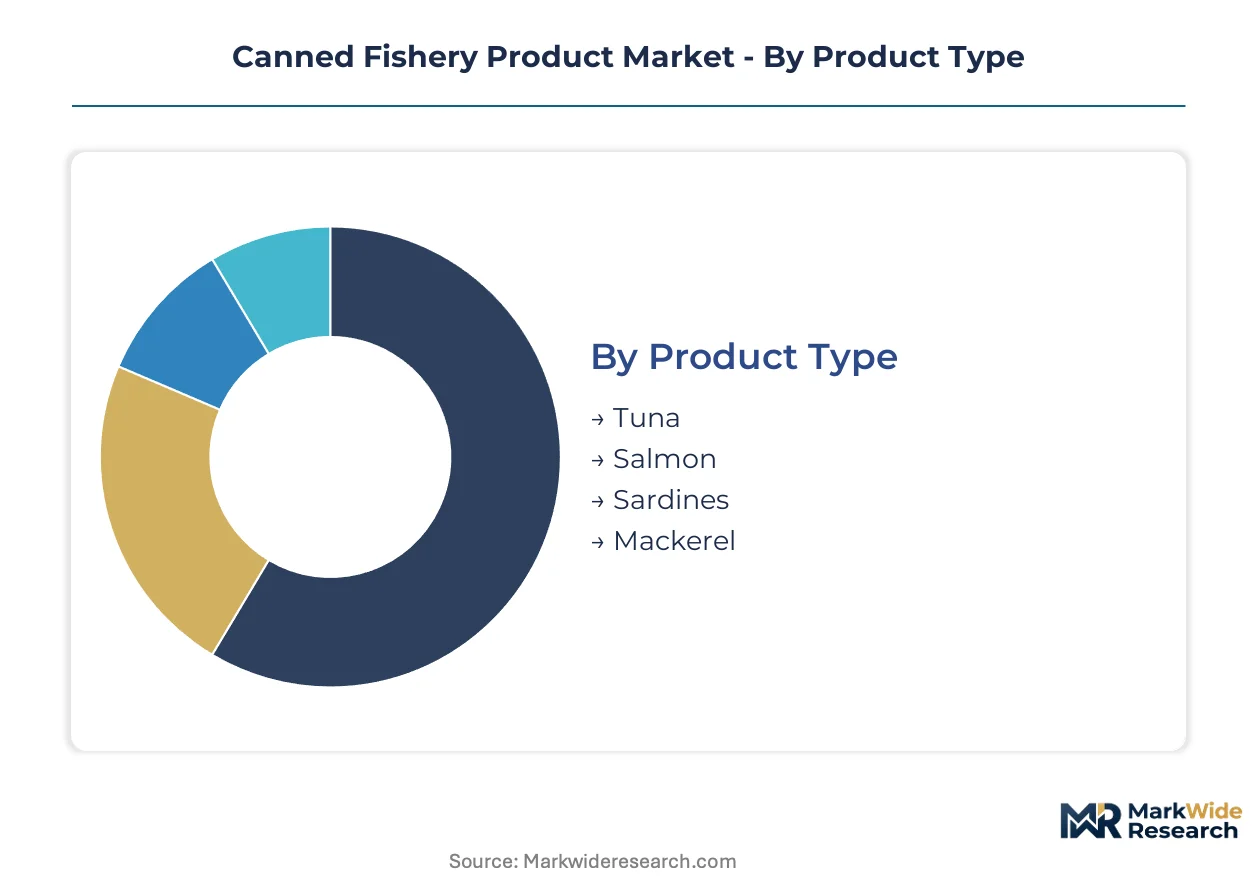
Segmentation in the canned fishery product market reveals how processing technology, packaging substrate, and channel access create distinct margin pools. Each dimension carries different regulatory burdens and capital intensity thresholds that reshape competitive positioning.
Product Type:
Integration depth varies sharply across species — tuna functions as a standalone commodity with established futures pricing, while salmon and mackerel increasingly embed into prepared meal systems.
- Tuna:Skipjack and yellowfin species dominate volume through retort processing at 116°C+ for commercial sterility. Bangkok and Manila households stock tuna as baseline protein, with EU Green Deal certification now filtering import eligibility.
- Salmon:Higher oil content demands modified thermal profiles to prevent lipid oxidation. Demand concentrates in Japanese and South Korean retail channels where premium positioning justifies cost premiums over tuna.
- Sardines:Smaller fish enable whole-body processing with minimal waste. Portuguese and Spanish canneries anchor European supply.
- Mackerel:Seasonal catch patterns require flexible canning line scheduling. Southeast Asian processors blend mackerel into mixed-species formulations for foodservice.
Tuna leads volumes today; salmon is gaining share fastest through premium positioning in East Asian markets.
Packaging Type:
Cost tier separation drives format selection — metal substrates anchor economy production while flexible materials capture logistics savings.
- Metal Tin:Three-piece and two-piece drawn cans retain dominant recycling infrastructure and filling line amortization across Thai and Indonesian facilities. Established collection systems in Germany and Japan sustain circular economy claims.
- Pouch:Retortable multilayer films reduce shipping weights substantially versus cylindrical containers. Convenience retailers in Singapore and Hong Kong accelerate adoption for reduced shelf footprint.
- Glass Jar:Premium visual presentation supports specialty positioning in Mediterranean markets. Higher breakage rates limit foodservice penetration.
- Plastic Container:Thermoformed PP and PET structures target refrigerated adjacent positioning. EFSA migration testing requirements constrain European deployment.
Metal tin leads volumes today; pouch is climbing the fastest through format conversion in ASEAN retail channels.
Distribution Channel:
Customer type fragmentation separates stock-up purchasing from immediate consumption missions.
- Supermarkets:Hypermarket and supermarket chains in Thailand and the Philippines control primary shelf placement negotiations. Thai Union and StarKist maintain dedicated category management teams for reset coordination.
- Online Retail:Direct-to-pantry subscription models bypass traditional wholesale distribution in Singapore and Hong Kong urban corridors. Cold-chain handoff requirements limit ambient product expansion.
- Convenience Stores:7-Eleven and FamilyMart networks in Taiwan and Japan drive single-serve pouch adoption. Limited shelf space favors high-velocity SKUs.
- Specialty Shops:Marine Stewardship Council-certified product lines anchor premium positioning in European organic retail. Smaller case quantities elevate per-unit logistics costs.
Supermarkets lead volumes today; online retail is expanding most quickly through pantry subscription models.
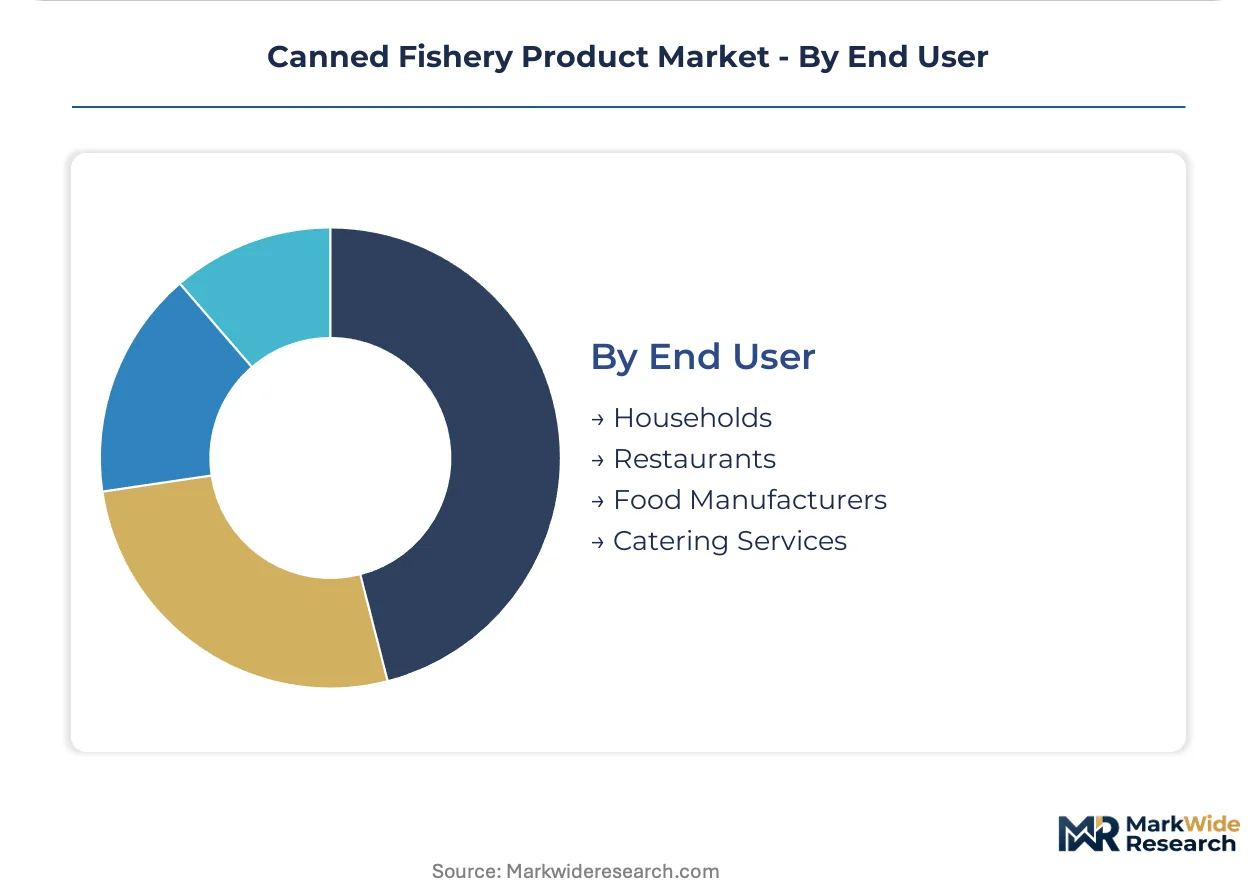
End User:
Application maturity separates established institutional procurement from emerging prepared food integration.
- Households:Dual-income urban families in Bangkok and Jakarta rotate canned protein through meal-kit assembly. Repurchase cycles compress as pantry management apps proliferate.
- Restaurants:QSR chains in the Philippines incorporate canned tuna into localized menu formulations. Consistent portion control outweighs fresh alternative price premiums.
- Food Manufacturers:Processors of frozen pizza and sandwich fillings source canned fish as input commodity. Bumble Bee's pole-and-line programs align with downstream ESG reporting requirements.
- Catering Services:Airline and institutional catering buyers adopt pouch formats for reduced galley storage volume. Retort pouch cube utilization improves load factors.
Households lead volumes today; food manufacturers are gaining share fastest through ingredient-system integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Samut Sakhon anchors the global processing footprint for shelf-stable seafood, with Bangkok and Manila households driving baseline consumption patterns across Southeast Asian urban corridors.
Thailand
Bangkok metropolitan households maintain elevated pantry inventories of skipjack and mackerel as baseline protein security. The Department of Fisheries enforces EU-recognised competent authority protocols for export eligibility. Samut Sakhon processing clusters handle the majority of global canning volume, with retort line operators investing in Marine Stewardship Council chain-of-custody certification to secure European retail placement.
Philippines
Manila and Cebu urban corridors exhibit compressed repurchase cycles for canned tuna through meal-kit integration and pantry management applications. The Bureau of Fisheries and Aquatic Resources implements vessel monitoring system mandates for export-oriented fleets. General Santos City in Mindanao functions as the primary landing and primary processing hub, with canneries consolidating pole-and-line catch documentation for EU Green Deal compliance.
United States
American households stock shelf-stable protein for emergency preparedness and convenience meal assembly. FDA seafood Hazard Analysis Critical Control Point regulations govern import screening and thermal process validation for retort operations. California and Washington State host the primary import distribution infrastructure, with Long Beach and Tacoma ports handling bulk inbound shipments from Southeast Asian processors.
Indonesia
Jakarta and Surabaya urban consumers rotate canned fish through daily meal preparation, elevating baseline consumption frequency. The Ministry of Marine Affairs and Fisheries administers catch documentation schemes aligned with Western and Central Pacific Fisheries Commission quotas. Bitung in North Sulawesi operates as the secondary global canning concentration, with processors facing raw material price volatility tied to regional quota adjustments.
Vietnam
Ho Chi Minh City and Hanoi households are expanding pantry stocking behavior for shelf-stable protein amid urban income growth. CDSCO-aligned export protocols require residue testing and traceability documentation for EU-bound shipments. Binh Dinh and Khanh Hoa provinces offer underutilised cold-chain infrastructure, with processors seeking to diversify beyond Thai-Indonesian supply concentration risks.
Canned Fishery Product Market Competitive Landscape
Backward integration into vessel operations dominates the current landscape, with processors securing captive supply of pole-and-line and purse-seine catch. The vendor base concentrates around vertically integrated Southeast Asian conglomerates and brand-dominant North American marketers. Three archetypes define positioning: Asian processors controlling supply chains from catch to shelf, brand marketers relying on contract manufacturing arrangements, and sustainability-certified specialists serving European premium channels. Competitive moves centre on certification portfolio expansion and pouch format conversion investments.
Within the integrated processor tier, Thai Union Group PCL exemplifies vessel-to-shelf control across Thai and Indonesian waters. StarKist Co. occupies a position as the dominant brand marketer in North American supermarket channels. Bumble Bee Foods, LLC represents the sustainability-specialist archetype through its pole-and-line sourcing programs. These three entities illustrate the structural divergence between supply-chain control and brand-channel dominance in shelf-stable seafood.
| Leading Market Players |
|---|
| Thai Union Group PCL |
| StarKist Co. |
| Bumble Bee Foods, LLC |
| Trident Seafoods Corporation |
| Maruha Nichiro Corporation |
| Century Pacific Foods Inc. |
| Bolton Group |
| Dongwon Enterprises Co. Ltd. |
| American Tuna Inc. |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal procurement mandates from European retailers are forcing Southeast Asian processors to absorb certification and carbon-accounting costs that cannot be fully passed downstream, compressing margins at the canning line while elevating entry barriers for uncertified competitors.
Pricing Analysis
Input-cost pass-through from skipjack tuna futures and aluminum can sheet tariffs operates imperfectly in this market. Three-tier pricing structure across Marine Stewardship Council-certified premium, standard commercial, and private-label economy levels reflects certification investment recovery. Pricing pressure stems from Western and Central Pacific Fisheries Commission quota volatility that processors cannot hedge fully. Food manufacturers exhibit highest price sensitivity due to ingredient-system commoditization, while European specialty shops accept premiums for chain-of-custody documentation.
Supply Chain Analysis
Direct-to-retail channels handle hyperscale supermarket demand through Thai Union and StarKist category management teams, while foodservice distributors source through regional consolidation points. Raw material supply concentrates in Thailand, Indonesia, and the Philippines, with over sixty percent of global canning capacity anchored in Samut Sakhon and Bitung clusters. The supply chain draws from skipjack and yellowfin tuna stocks, aluminum can sheet, and multilayer retort films. Single-source vulnerability in Thai-Indonesian processing corridors presents acute disruption risk from geopolitical or disease events. Distribution runs through supermarket chains, online pantry subscriptions, and convenience retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
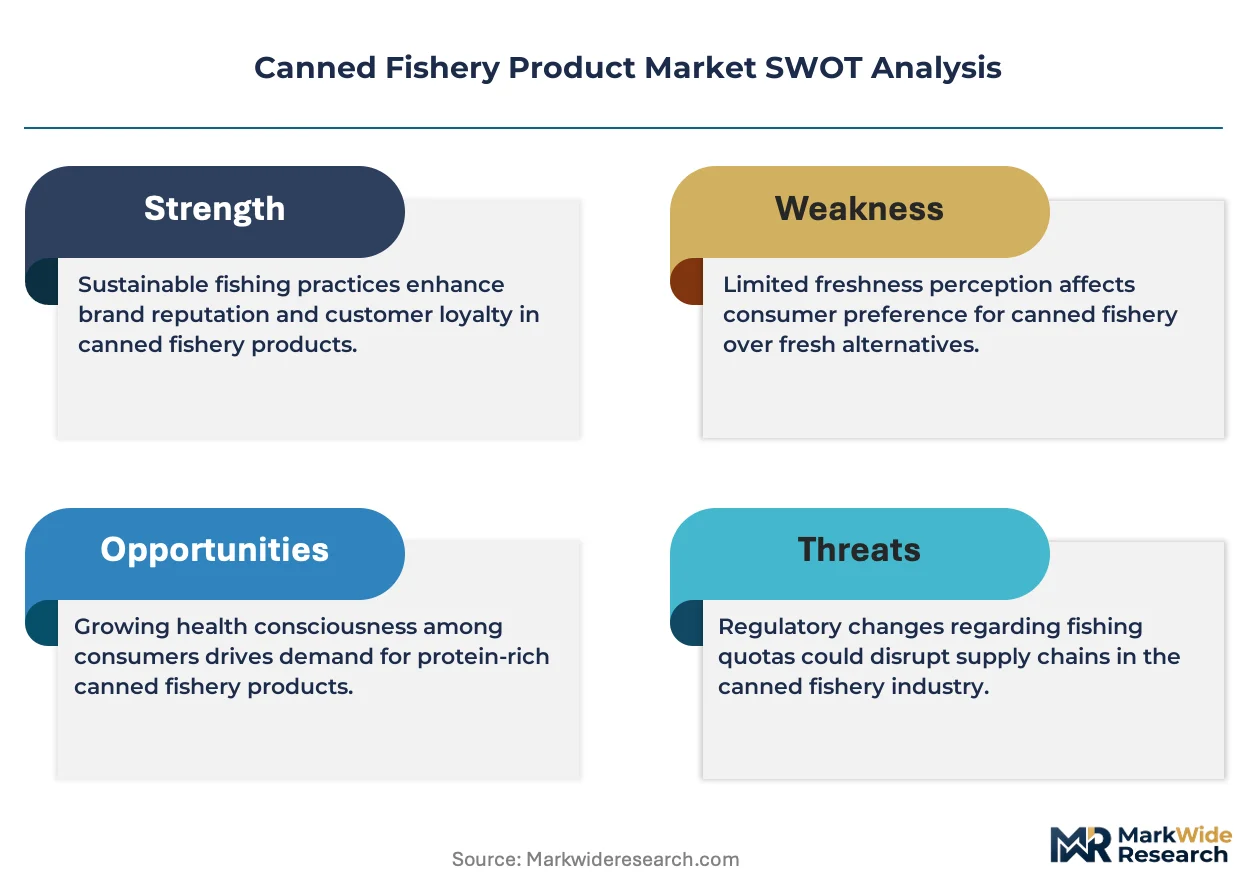
This market functions as a regulatory compounder where EU Green Deal fisheries certification requirements tighten continuously, mandating vessel-level traceability and carbon accounting that reward early compliance investments with preferential shelf placement.
For Market Incumbents: Deepen backward integration into pole-and-line vessel operations to secure captive supply and satisfy European retailer sustainability mandates. Expand Marine Stewardship Council chain-of-custody certification across Indonesian facilities to defend against Vietnamese processing expansion. Retort technician training pipelines must accelerate to match capacity expansion timelines and prevent thermal process validation bottlenecks.
For New Entrants and Emerging Players: EU Green Deal compliance requirements in Europe open a window for Vietnamese processors with CDSCO-aligned export protocols and underutilized cold-chain infrastructure in Binh Dinh and Khanh Hoa provinces. Target food manufacturer ingredient-system procurement where ESG reporting requirements favor certified pole-and-line sourcing. Plant-based protein blends adjacent to conventional seafood offer white-space positioning without direct species substitution competition.
For Investors and Strategic Acquirers: Asymmetric upside sits with sustainability-certified specialists serving European premium channels, where regulatory tightening compounds competitive moats. Long-term viability favors processors with vessel-to-shelf control and diversified geography beyond Thai-Indonesian concentration. Monitor Western and Central Pacific Fisheries Commission quota adjustment announcements as inflection indicators for raw material cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Pole-and-Line Certification Investment | Marine Stewardship Council chain-of-custody unlocks EU Green Deal-compliant retail placement in European supermarkets. |
| Retort Pouch Format Conversion | Multilayer film technology reduces shipping weights forty percent versus metal tins for convenience retail channels. |
| Vietnamese Processing Expansion | Binh Dinh and Khanh Hoa provinces offer EU-recognized competent authority status and labor arbitrage advantages. |
| Blockchain Traceability Integration | Vessel-level digital monitoring satisfies EFSA contaminant threshold documentation and automatic border rejection protocols. |
| Extended Producer Responsibility Compliance | EU Packaging and Packaging Waste Regulation mandates secure recycling infrastructure partnerships and cost burden positioning. |
Research Methodology
Multiple input streams — regulatory filing analysis, trade customs databases, and processor production disclosures — were reconciled through bottom-up and top-down triangulation. Primary interviews with cannery operations directors, European retail category buyers, foodservice procurement managers, and vessel monitoring system technology providers were validated against secondary sources including FDA seafood HACCP guidance documents, EU Green Deal fisheries criteria, Western and Central Pacific Fisheries Commission quota records, and Thai Department of Fisheries export protocols.
Historical volume trajectories were cross-referenced against expert panel inputs to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled include product type, packaging substrate, distribution channel, and end-user application, with species-specific thermal processing requirements and certification tier penetration as industry-specific forecast inputs. CAGRs were derived through regression analysis of baseline consumption patterns and regulatory compliance cost trajectories.
Revisions become necessary when Western and Central Pacific Fisheries Commission quota adjustments, EU EFSA contaminant threshold modifications, or aluminum tariff regime changes materialize beyond modeled assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Seafood
Alaskan Salmon Market
Seafood
Crustacean Market
Seafood
China Crustaceans Market
Seafood
Seafood Takeout Market
Seafood
Trout Market
Seafood
Canned Sardines Market
Seafood
Asia-Pacific Seafood Market
Seafood
Surimi Market
Seafood
Sardine and Anchovy Umami Concentrate Systems Market
Seafood
Fish & Shrimp, Fish Feed & Shrimp Feed and Additives Market
Seafood
Krill Meal Market
Seafood
Tinned Fish Market
Seafood
Oyster Market
Seafood
North America Tuna Market
Seafood
Organic Seafood Market
Seafood
Fish Meal Market