
 Infused Dried Fruits Market | 2026-2036
Infused Dried Fruits Market Size, Share, and Industry Trends Forecast 2026-2036
Infused Dried Fruits Market Analysis
The capital-intensity divergence between integrated processors and toll-drying operators is redrawing competitive boundaries in infused dried fruits. Olam International leverages backward integration into tropical fruit sourcing to sustain margin control across volatile harvest cycles. Graceland Fruit Inc. anchors its position through proprietary osmotic infusion technology that extends shelf stability without synthetic additives.
Infused dried fruits are fresh or dehydrated fruits impregnated with concentrated sugar solutions, fruit juices, or functional syrups through vacuum or atmospheric infusion, typically achieving moisture levels of 15-25% and water activity below 0.65 for ambient stability. These products serve as shelf-stable ingredients in bakery, confectionery, snack, and foodservice channels requiring consistent flavor delivery and textural integrity. Whole and slice formats dominate current volume, while powder forms are gaining traction in beverage and nutritional applications where solubility and dispersion matter. Sweet-flavor profiles occupy the largest revenue share, though spicy and tangy variants are expanding fastest in Asian and Latin American markets as snack palates diversify.
FDA oversight of added-sugar labeling and EFSA guidance on acrylamide in thermally processed foods shape formulation choices and process validation requirements for exporters targeting North America and Europe. The EU Green Deal and associated Farm-to-Fork strategy pressure suppliers to document sustainable water use in fruit cultivation and energy efficiency in dehydration operations. Stakeholders must monitor evolving front-of-pack warning label regimes in key export markets and decide whether to invest in localized infusion capacity or deepen toll-manufacturing partnerships.
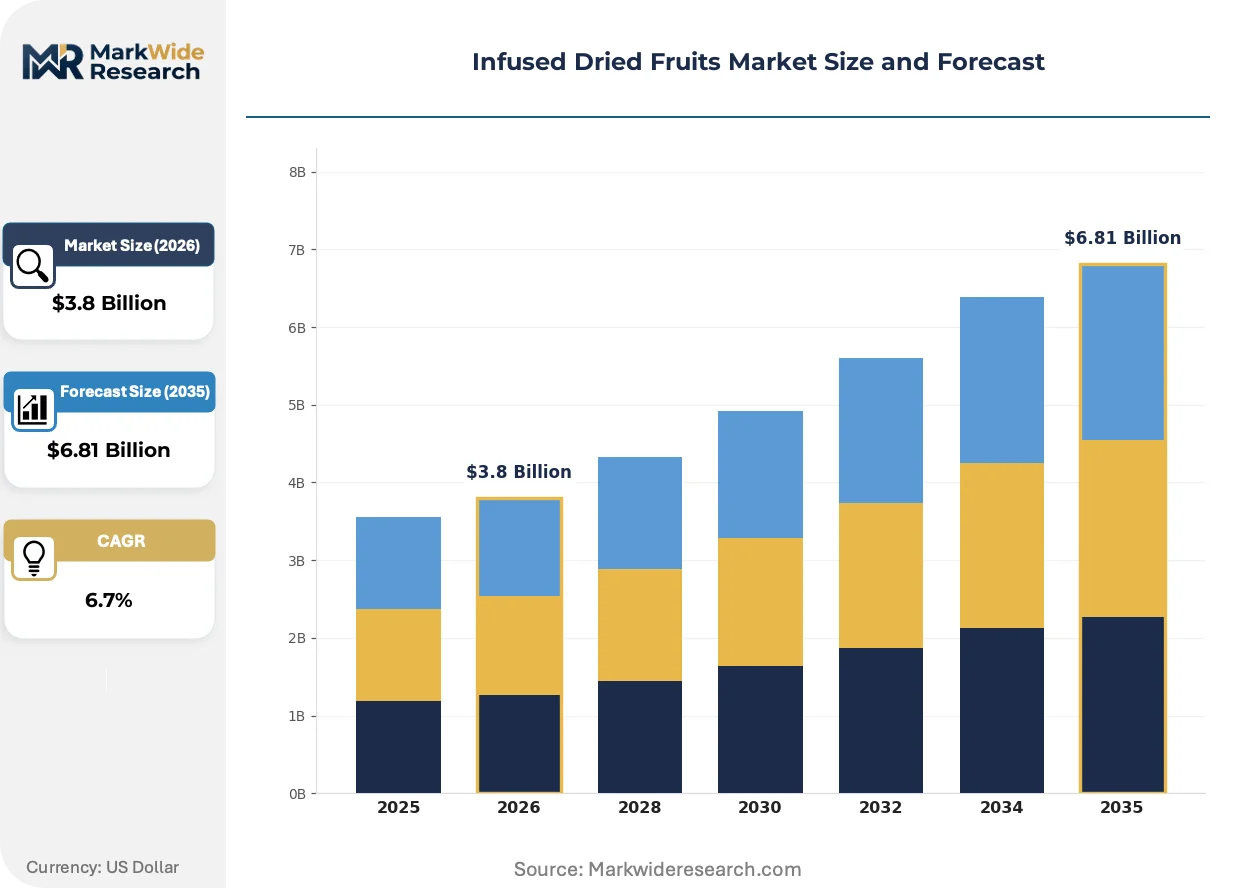
Market Dynamics
Clean-label mandates under FDA and EFSA frameworks are compressing formulation flexibility while rewarding processors who master reduced-sugar infusion chemistry. This regulatory tightening is simultaneously elevating capital barriers and creating tiered competitive access based on technical compliance depth.
Growth Catalysts
- EFSA Acrylamide Guidance:Thermally processed food categories face stricter formation limits, pulling processors toward vacuum infusion technologies that operate at lower temperatures while maintaining flavor penetration.
- Beverage Fortification:Powdered infused fruit formats are capturing new volume in functional drink applications where solubility and clean-label positioning intersect with consumer preference for natural sweetening systems.
- Thailand Mango Concentration:Proximity to raw material sourcing clusters in Southeast Asia is enabling toll-drying operators to offer competitive unit economics for North American private-label programs.
Market Restraints
- Input Cost Volatility:Cane sugar and concentrated fruit juice prices fluctuate with Brazilian harvest cycles and ethanol policy shifts, compressing margin predictability for non-integrated processors.
- Tropical Sourcing Concentration:Philippine and Thai pineapple supply dominance creates single-origin exposure that amplifies climate and logistics disruption risk during monsoon seasons.
- Moisture Specification Limits:Water activity thresholds below 0.65 for ambient stability require precise process control that smaller toll operators struggle to validate consistently.
Strategic Opportunities
- India Organized Retail Expansion:Modern trade penetration in tier-two cities is creating shelf-space availability for premium pouch formats previously confined to metro markets.
- EU Green Deal Alignment:Farm-to-Fork documentation requirements favor suppliers with verified sustainable water use in cultivation and renewable energy in dehydration operations.
- Spicy-Tangy Flavor Platforms:Asian and Latin American palate diversification is opening formulation white space beyond traditional sweet profiles for snack and confectionery channels.
Industry Challenges
- Process Validation Talent:Scarcity of technicians trained in osmotic infusion parameter optimization and water activity measurement is constraining quality consistency at mid-scale facilities.
- Dual Certification Timelines:Simultaneous FDA facility registration and EFSA third-party audit requirements extend market entry timelines by eight to fourteen months for new export-oriented processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infused Dried Fruits Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Apple, Mango, Pineapple, Coconut Form: Whole, Slices, Chunks, Powder Flavor Profile: Spicy, Sweet, Savory, Tangy Packaging Type: Bulk, Retail Packs, Vacuum-Sealed, Pouches |
| Companies Covered | Olam International, Del Monte Foods Inc., Sun-Maid Growers of California, Graceland Fruit Inc., Eden Foods Inc., Sunbeam Foods Pty Ltd., Berry Ltd., Paradise Fruits, Mercer Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infused Dried Fruits Market Emerging Trajectories
Pulse-drying and microwave-assisted dehydration are compressing thermal exposure windows while preserving volatile aromatic compounds. These hardware shifts are redrawing process economics and enabling new product texture profiles.
Pulse-drying technology uses rapid intermittent heat application to reduce moisture without the prolonged thermal exposure that drives Maillard browning and acrylamide formation. Bakery and cereal manufacturers in Germany and the Netherlands are adopting pulse-dried infused fruits at accelerated procurement cycles. This hardware shift is displacing conventional forced-air tunnel systems in premium ingredient specifications where color retention and flavor clarity command price premiums.
EFSA's evolving front-of-pack nutritional scoring frameworks are pressuring added-sugar disclosure granularity in composite products containing infused fruit inclusions. Processors must now segment sugar contributions between naturally occurring fruit sugars and infused concentrated syrups for accurate Nutri-Score calculation. Confectionery applications targeting French and Belgian retail channels are most affected, with reformulation timelines compressing to maintain shelf placement.
Direct-procurement relationships between snack food manufacturers and integrated tropical processors are shortening traditional three-tier distribution chains. Large North American trail-mix brands now contract directly with Philippine and Costa Rican drying facilities for specified brix levels and slice geometry. This channel disintermediation is most visible in the United States convenience-store channel where pouch-format velocity data drives rapid supplier switching.
Infused Dried Fruits Market Segmentation
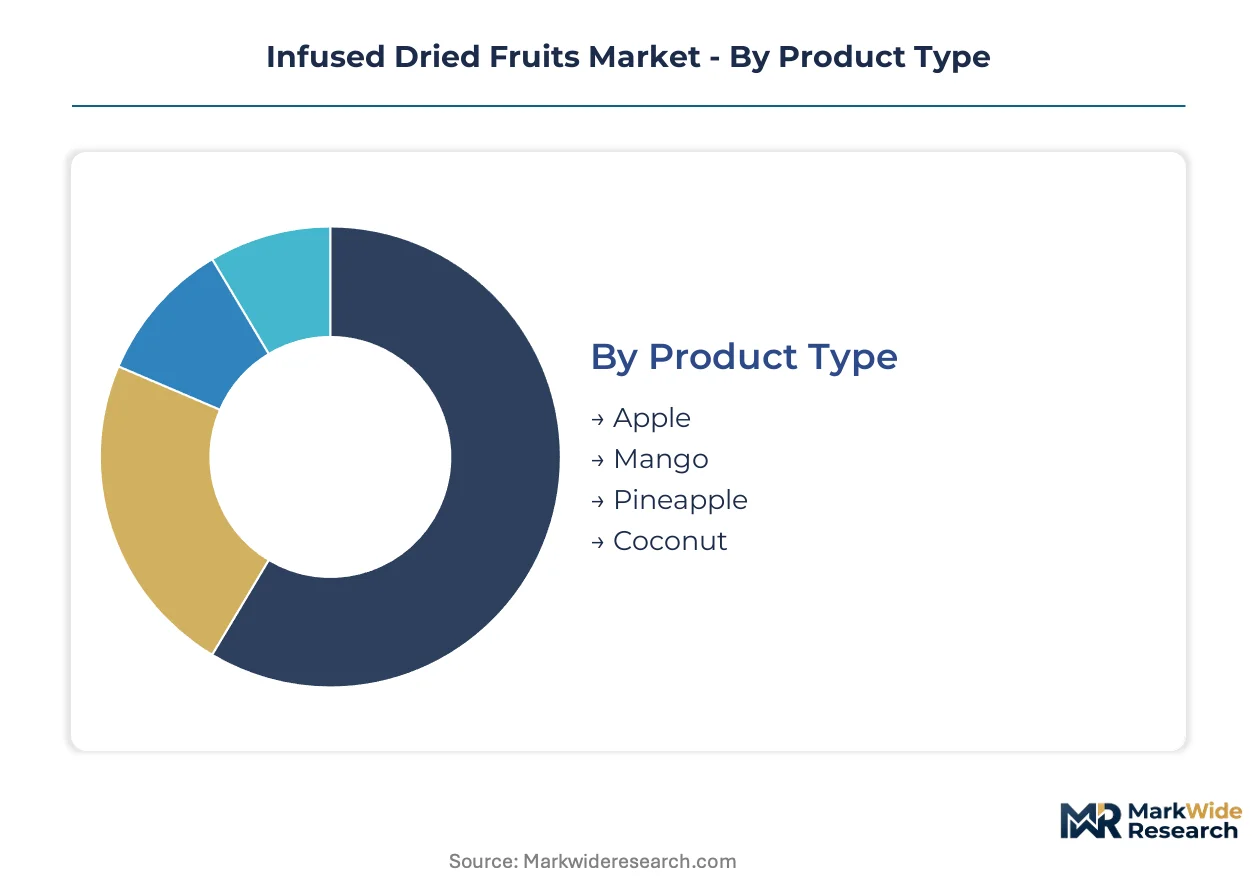
Segmentation in infused dried fruits determines which processing specifications unlock access to premium bakery contracts versus commodity snack channels. Product type and form choices cascade through flavor formulation, packaging investment, and regulatory compliance requirements.
Product Type:
Mango and pineapple shipments flow predominantly through North American retail and European industrial bakery channels, while apple and coconut serve distinct cost-tier and application segments with different margin structures.
- Mango:Vacuum-infusion processing achieves 18-22 brix penetration for consistent sweetness delivery. North American trail-mix manufacturers specify Philippine Carabao and Thai Nam Dok Mai varieties for color uniformity and fiber texture in premium pouch formats.
- Pineapple:Core-origin slices from Costa Rican and Thai processors dominate foodservice dessert applications where moisture retention and structural integrity under thermal stress matter. EFSA acrylamide guidance favors lower-temperature infusion protocols for this thermally sensitive fruit.
- Apple:Domestic sourcing in Washington and New York State supports clean-label positioning for US cereal and granola channels without tropical import documentation burdens.
- Coconut:Philippine and Indonesian desiccated grades serve confectionery fat-reduction formulations where water activity below 0.60 prevents rancidity in chocolate enrobing applications.
By volume, pineapple leads industrial procurement. By growth pace, mango is ahead.
Form:
Form selection drives equipment amortization schedules and dictates which end-use categories remain accessible—whole fruit requires sorting and grading infrastructure that powder production bypasses entirely.
- Slices:Standardized 8-12mm thickness enables automated bakery line feeding without jamming. German and Dutch cereal manufacturers specify pulse-dried slices for color retention in extended shelf-life applications.
- Powder:Soluble formats capture functional beverage fortification where clean-label natural sweetening displaces synthetic alternatives. Particle size distribution below 200 mesh ensures dispersion stability in ready-to-drink formulations.
- Whole:Premium gifting and specialty retail channels in Japan and South Korea demand intact fruit morphology for visual appeal in seasonal packaging.
- Chunks:Intermediate size grading serves snack bar manufacturers requiring textural contrast without whole-fruit handling complexity.
Slices command the widest channel coverage. Powder is expanding most quickly in beverage applications.
Flavor Profile:
Flavor positioning separates heritage European and North American markets from emerging Asian and Latin American growth corridors, with formulation chemistry varying significantly across thermal and ambient infusion methods.
- Sweet:Traditional sucrose and concentrated fruit juice infusions maintain dominance in children's snacking and breakfast cereal inclusions where palatability testing favors familiar profiles.
- Spicy:Chili-lime and tamarind-chile coatings gain traction in Mexican and Thai retail channels where adult snacking occasions favor complex heat-sweet balance.
- Tangy:Citric acid and natural vinegar-based infusions target sour candy alternatives in South Korean and Vietnamese convenience stores.
- Savory:Salt and umami-forward formulations remain niche, primarily serving Japanese otsumami drinking snack traditions.
Sweet formulations lead by revenue contribution. Spicy variants show the steepest expansion trajectory in emerging markets.
Packaging Type:
Packaging investment separates integrated processors with in-house forming capacity from toll operators dependent on third-party converters, directly affecting margin capture and customer switching costs.
- Retail Packs:Stand-up pouches with resealable zippers dominate US convenience channel velocity, with print minimums of 50,000 units forcing smaller processors toward toll-manufacturing partnerships.
- Vacuum-Sealed:Oxygen exclusion extends ambient shelf stability to 18-24 months for export shipments to Middle Eastern and African markets where cold chain reliability varies.
- Bulk:Foodservice and industrial bakery procurement relies on 10-25kg multilayer bags with nitrogen flushing for ingredient-scale handling efficiency.
- Pouches:Single-serve formats capture vending and airline catering channels where portion control and moisture barrier performance justify per-unit premium.
Bulk shipments lead by tonnage. Retail packs are gaining share fastest in modern trade expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium retail pouches in the United States command price premiums that Philippine toll-drying operators cannot replicate, creating a structural margin asymmetry between consumption markets and processing clusters.
United States
Convenience-channel velocity data drives rapid supplier switching for trail-mix and cereal inclusion procurement. FDA added-sugar labeling mandates compress formulation flexibility for domestic snack manufacturers. California's Central Valley hosts Sun-Maid Growers' processing infrastructure serving North American private-label programs.
Germany
Pulse-dried slice specifications from Dutch and German cereal manufacturers accelerate procurement cycles for color-retentive ingredients. EFSA acrylamide guidance pulls processors toward lower-temperature vacuum infusion protocols. Hamburg's port logistics cluster facilitates bulk ingredient flows from Southeast Asian drying facilities.
Thailand
Proximity to Nam Dok Mai mango sourcing clusters enables toll-drying operators to offer competitive unit economics for North American programs. The country's national food safety regulator enforces export-grade dehydration standards for EU-bound shipments. Bangkok-adjacent processing zones concentrate vacuum-infusion capacity serving Japanese and South Korean whole-fruit demand.
Philippines
Carabao mango and pineapple supply dominance creates single-origin exposure that amplifies climate disruption risk during monsoon seasons. Bureau of Plant Industry export phytosanitary certification timelines extend by 30-45 days during peak harvest periods. Davao Region drying facilities anchor direct-procurement relationships with North American trail-mix brands.
India
Modern trade penetration in tier-two cities creates shelf-space availability for premium pouch formats previously confined to metro markets. FSSAI clean-label enforcement tightens additive disclosure requirements for domestic snack manufacturers. Maharashtra's organized retail corridor in Mumbai-Pune drives velocity data for resealable zipper pouch adoption.
Infused Dried Fruits Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with proprietary osmotic infusion specialists commanding premium ingredient specifications while toll-drying operators compete on unit economics for private-label volume. The market exhibits tiered access based on backward integration depth and regulatory compliance certification. Three archetypes dominate: integrated tropical processors with captive sourcing, technology-anchored infusion specialists, and scale-driven toll operators. Competitive moves concentrate on direct-procurement relationship building and capacity expansion in Southeast Asian sourcing clusters.
Within the integrated processor tier, Olam International exemplifies backward integration into tropical fruit sourcing to sustain margin control across volatile harvest cycles. Graceland Fruit Inc. occupies a position as a technology-anchored specialist through proprietary shelf-stability extension without synthetic additives. Sun-Maid Growers of California represents the domestic-sourcing archetype leveraging Washington and New York State apple procurement for clean-label cereal channel positioning.
| Leading Market Players |
|---|
| Olam International |
| Del Monte Foods Inc. |
| Sun-Maid Growers of California |
| Graceland Fruit Inc. |
| Eden Foods Inc. |
| Sunbeam Foods Pty Ltd. |
| Berry Ltd. |
| Paradise Fruits |
| Mercer Foods |
| Others |
Supply Flow & Price Mechanics
Thirty-to-forty-five-day export phytosanitary certification timelines during Philippine and Thai peak harvests concentrate inventory risk at origin, compressing processor pricing power while amplifying spot-market volatility for non-integrated buyers. This lead-time band ties directly to monsoon-season logistics disruptions and FDA facility registration requirements that extend supplier qualification windows for North American procurement.
Pricing Analysis
Configured-to-order pricing for specified brix levels and slice geometry commands a premium spread over standard bulk grades, with vacuum-infusion protocols and pulse-dried color retention specifications driving differentiation. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth—FDA-registered and EFSA-third-party-audited facilities capture ingredient premiums from German and Dutch cereal manufacturers, while toll-drying operators compete on unit economics for private-label volume. Pricing pressure stems from Brazilian cane sugar and ethanol policy volatility that compresses margin predictability for non-integrated processors. Private-label trail-mix manufacturers exhibit highest price sensitivity, whereas premium bakery channels prioritize specification compliance over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate among integrated processors with captive Philippine and Thai sourcing, while just-in-time procurement characterizes North American snack manufacturers dependent on toll-drying spot contracts. Supply concentrates in the Philippines for Carabao mango and Costa Rica for pineapple core-origin slices, with Thai Nam Dok Mai varieties anchoring Southeast Asian export flows. Raw material dependencies center on cane sugar, concentrated fruit juices, and multilayer packaging films with nitrogen-flushing specifications. Single-origin exposure amplifies climate disruption risk during monsoon seasons. Distribution runs through direct-procurement relationships that disintermediate traditional three-tier channels for large North American trail-mix brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-procurement platform economics are disintermediating traditional distribution tiers, with EFSA acrylamide guidance and FDA added-sugar labeling creating interoperability requirements that favor processors with dual-certification infrastructure.
For Market Incumbents: Compound defensive positioning through backward integration into Nam Dok Mai and Carabao mango sourcing clusters and proprietary osmotic infusion technology investment that extends shelf stability without synthetic additives. Emerging toll-drying operators with Thailand-based unit economics threaten margin capture in private-label channels. Dual certification depth serves as the priority lever for maintaining premium ingredient specifications. For New Entrants and Emerging Players: FDA facility registration fast-track through third-party audit preparation services opens white-space access for mid-scale Philippine and Thai toll-drying facilities seeking North American direct-procurement relationships. India's tier-two city modern trade expansion presents the most penetrable geography for premium pouch format introduction. Clean-label reduced-sugar infusion chemistry offers a differentiated go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agribusiness conglomerates with underutilized dehydration assets in Southeast Asian sourcing clusters. Long-term viability hinges on water-use documentation for EU Green Deal alignment and renewable energy integration in dehydration operations. Watch for EFSA front-of-pack nutritional scoring framework implementation as inflection indicator for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tropical Sourcing | Olam International's captive Philippine and Thai supply secures margin control across volatile harvest cycles. |
| Proprietary Vacuum-Infusion Technology Investment | Graceland Fruit Inc.'s osmotic shelf-stability extension commands premium bakery specifications without synthetic additives. |
| Dual Certification Infrastructure Buildout | Simultaneous FDA registration and EFSA third-party audit capability extends market entry timelines but locks in tiered competitive access. |
| Pulse-Drying Capacity Expansion | German and Dutch cereal manufacturers accelerate procurement cycles for color-retentive ingredients with reduced acrylamide formation. |
| Direct-Procurement Relationship Formation | North American trail-mix brands contract specified brix levels and slice geometry, displacing traditional distribution intermediaries. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with fruit processors, procurement managers at snack food manufacturers, regulatory affairs specialists, and toll-drying operators; and secondary validation through FDA facility registration databases, EFSA third-party audit records, customs and trade flow documentation, and Bureau of Plant Industry export certification timelines. Bottom-up triangulation across processor capacity assessments and top-down demand validation from bakery, confectionery, and foodservice channel procurement patterns anchored volume and value estimates.
Across the analysis window, the forecasting framework modeled segmentation dimensions including fruit type, form specification, flavor profile positioning, and packaging format tier, with regional regulatory cluster effects incorporated for FDA, EFSA, and FSSAI jurisdictions. CAGRs were derived from trend extrapolation calibrated to historical procurement cycle data and clean-label reformulation timelines. Industry-specific forecast inputs encompassed Brazilian ethanol policy shifts and EU Green Deal water-use documentation requirements.
Underlying assumptions cover sustained modern trade penetration in Indian tier-two cities and continued EFSA acrylamide guidance enforcement, with deviation risk concentrated in Philippine and Thai monsoon disruption severity and cane sugar price volatility. Revision becomes warranted when FDA added-sugar labeling granularity requirements or EU front-of-pack scoring framework implementations cross enforcement thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Butterfly Pea Flowers Market
Fruits and Vegetables
Fruit and Vegetable Pieces and Powders Market
Fruits and Vegetables
Mexico Lime Market
Fruits and Vegetables
Pea Flakes Market
Fruits and Vegetables
United Arab Emirates Fruits and Vegetables Market
Fruits and Vegetables
Freeze Dried Fruits and Vegetables Market
Fruits and Vegetables
Kiwi Fruit Market
Fruits and Vegetables
Ackee Market
Fruits and Vegetables
Dehydrated Beets Market
Fruits and Vegetables
Global Avocado Market
Fruits and Vegetables
Dragon Fruit Powder Market
Fruits and Vegetables
Tunisia Fruit and Vegetable Market
Fruits and Vegetables
Global Shiitake Mushroom Market
Fruits and Vegetables
Asia-Pacific Sweet Potatoes Market
Fruits and Vegetables
Avocado-Based Products Market
Fruits and Vegetables
Processed Fruits and Vegetables Market