
 Football Shoes Market | 2026-2036
Football Shoes Market Size, Share, and Industry Trends Forecast 2026-2036
Football Shoes Market Intelligence
The channel dominance of multi-brand sporting goods retailers is narrowing as top brands expand their direct-to-consumer platforms. Nike Inc. leverages its digital ecosystem to build direct customer relationships and capture higher margins. Adidas AG competes aggressively with its own extensive online and physical retail store footprint. PUMA SE differentiates through targeted collaborations and strong brand positioning in specific European and Latin American markets.
Football shoes are footwear engineered specifically for playing football on various surfaces. They feature distinct stud patterns, such as bladed or conical studs, on the outsole to provide essential grip, traction, and stability during play. The Firm Ground product type continues to command the largest market share due to its versatility across most natural grass pitches. Within materials, advanced Synthetic options are gaining share over traditional Leather due to lower weight, improved water resistance, and greater design flexibility.
Product composition is governed by material and chemical regulations, such as the EU's REACH framework, which restricts certain substances in consumer goods. In parallel, manufacturers must adhere to national product safety standards, including China's GB standards, impacting market access and design choices. Stakeholder success will hinge on navigating the shift toward sustainable materials while managing complex, multi-regional supply chain logistics.
Market Dynamics
The central dynamic shaping the football shoe market is the convergence of sustainability mandates with material science innovation. This forces manufacturers to balance the technical performance demands of athletes with growing regulatory pressures, such as the EU Green Deal, which prioritize recycled content and chemical safety.
Growth Catalysts
- Expanding Women's Football:The rapid professionalization and growing viewership of women's football leagues globally are creating a dedicated and expanding consumer segment for female-specific footwear designs and marketing campaigns.
- Sustainability Mandates:Regulatory frameworks like the EU Green Deal are compelling brands to invest in recycled and bio-based materials, which in turn opens up new product categories marketed on their environmental credentials.
- Material Innovation:The development of advanced synthetic textiles offers performance benefits over traditional leather, including lower weight, improved water resistance, and enhanced durability, prompting more frequent consumer upgrade cycles.
Market Restraints
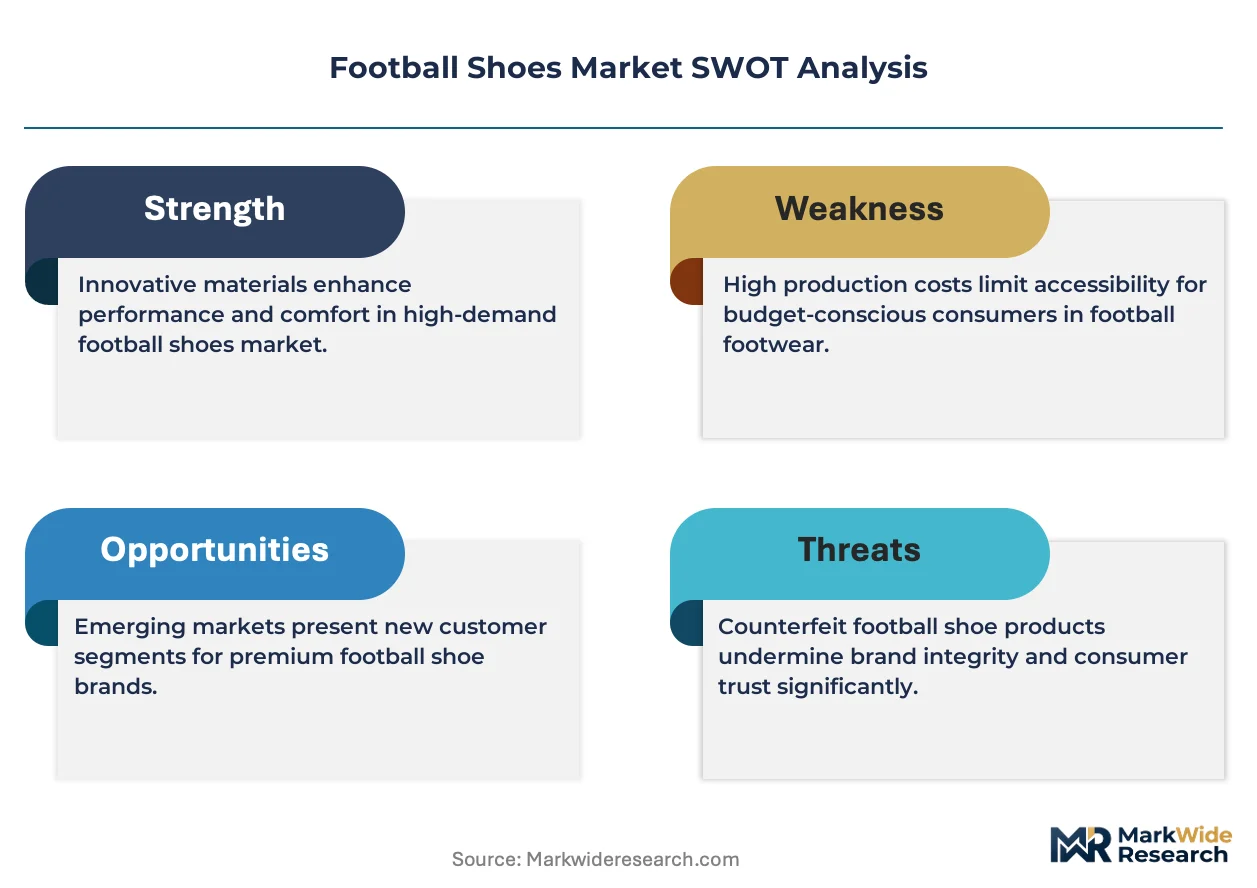
- Input Cost Volatility:Manufacturers face unpredictable costs for high-grade recycled polymers and specialized synthetic materials, which can compress profit margins or necessitate price increases that deter budget-conscious consumers.
- Counterfeit Products:The proliferation of counterfeit football shoes, particularly in emerging markets across Asia and Latin America, erodes brand equity and siphons revenue from legitimate manufacturers.
- Regulatory Compliance Costs:Adherence to stringent chemical regulations like the EU's REACH framework increases R&D and supply chain auditing costs, creating a barrier for smaller brands and new market entrants.
Strategic Opportunities
- Smart Shoe Integration:Embedding lightweight sensors and connectivity hardware into footwear allows for the capture of performance data, creating an opportunity to enter the high-margin sports analytics and connected fitness markets.
- Niche Surface Specialization:There is an opportunity to develop and market highly specialized footwear for alternative football formats, such as shoes with unique traction patterns for artificial turf, futsal courts, or beach soccer.
- Hyper-Personalization via DTC:Direct-to-consumer channels enable brands to offer customized footwear based on player foot scans, aesthetic preferences, and specific performance needs, creating a premium, high-margin service.
Industry Challenges
- Multi-Regional Regulatory Navigation:Manufacturers face significant operational complexity in designing and sourcing products that simultaneously comply with divergent standards, such as the EU's REACH and China's GB standards for consumer goods.
- Intellectual Property Protection:The rapid pace of design innovation makes it challenging to protect unique outsole patterns, upper technologies, and other proprietary features from fast-follower imitation and patent infringement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Football Shoes Market |
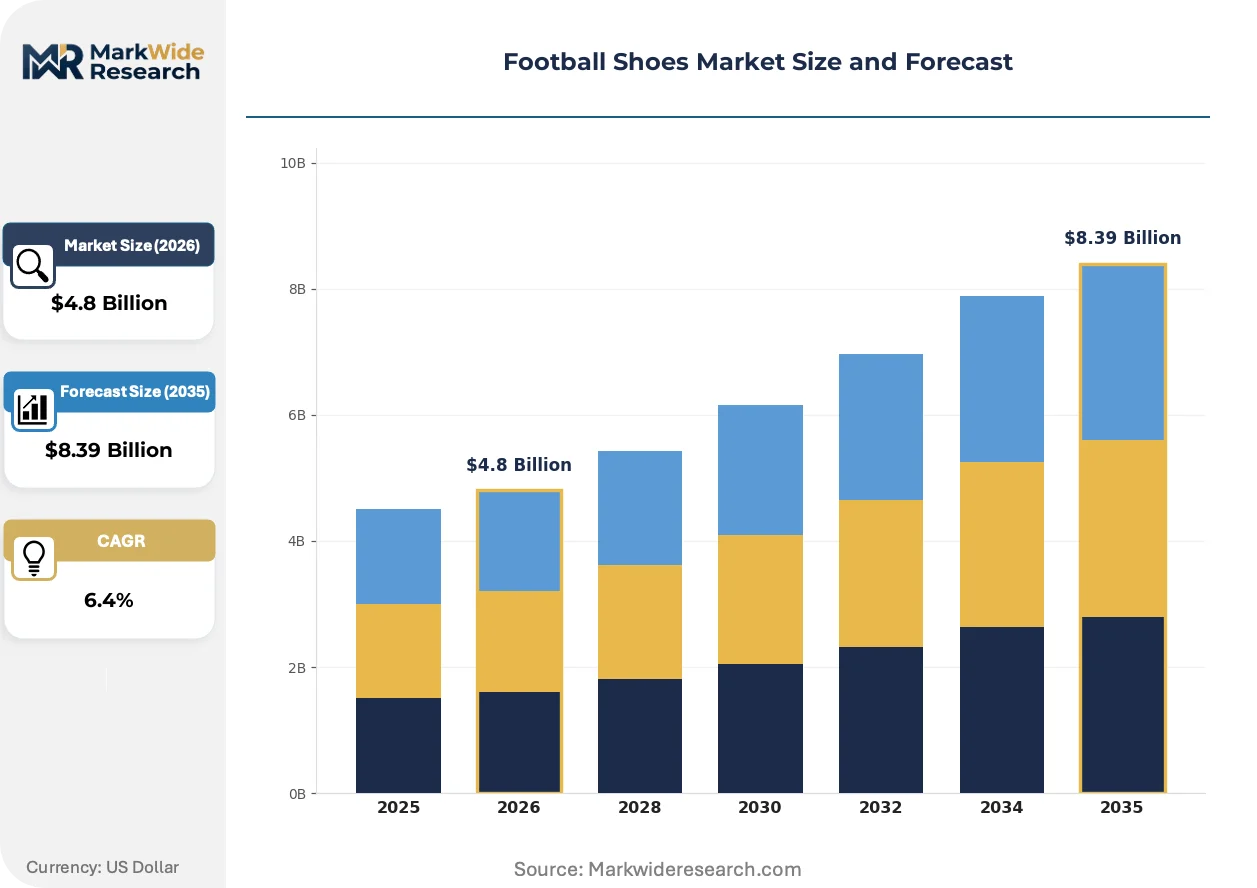
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Firm Ground, Soft Ground, Artificial Ground, Turf End User: Men, Women, Kids, Professional Players Material: Leather, Synthetic, Mesh, Rubber Price Tier: Premium, Mid-range, Budget, Discounted |
| Companies Covered | Nike Inc., Adidas AG, PUMA SE, Under Armour Inc., ASICS Corporation, New Balance Athletics Inc., Mizuno Corporation, Decathlon SA, JOMA SPORT SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Football Shoes Market Strategic Shifts & Innovations
Material science advancements are fundamentally altering product composition in the football shoe market. The industry is navigating a path where innovation in synthetics and bio-polymers must satisfy both elite athletic performance requirements and increasingly strict environmental and chemical safety regulations from multiple jurisdictions.
Advanced recycled synthetics, often derived from post-consumer plastics, provide a lightweight and durable alternative to virgin materials. This technology is being adopted by environmentally conscious consumers and professional clubs seeking to improve their sustainability profiles. The mainstreaming of these materials is rendering obsolete the long-held assumption that top-tier performance is exclusively linked to virgin petroleum-based synthetics or premium leathers.
The EU's REACH framework directly governs the chemical composition of consumer products sold within the bloc. This regulation compels footwear manufacturers to rigorously audit their supply chains and reformulate materials to eliminate restricted substances from dyes, adhesives, and polymers. The synthetic leather and plastics segments are most affected, forcing a pivot toward certified suppliers who can guarantee compliance.
A clear behavioral shift toward brand-owned digital platforms is changing how consumers purchase football shoes. This movement is diminishing the historical dominance of multi-brand sporting goods retailers as major brands build direct relationships with customers through their own e-commerce sites and apps. This trend is most advanced in North America and Western Europe, where brand loyalty and digital infrastructure facilitate direct-to-consumer sales.
Football Shoes Market Segmentation
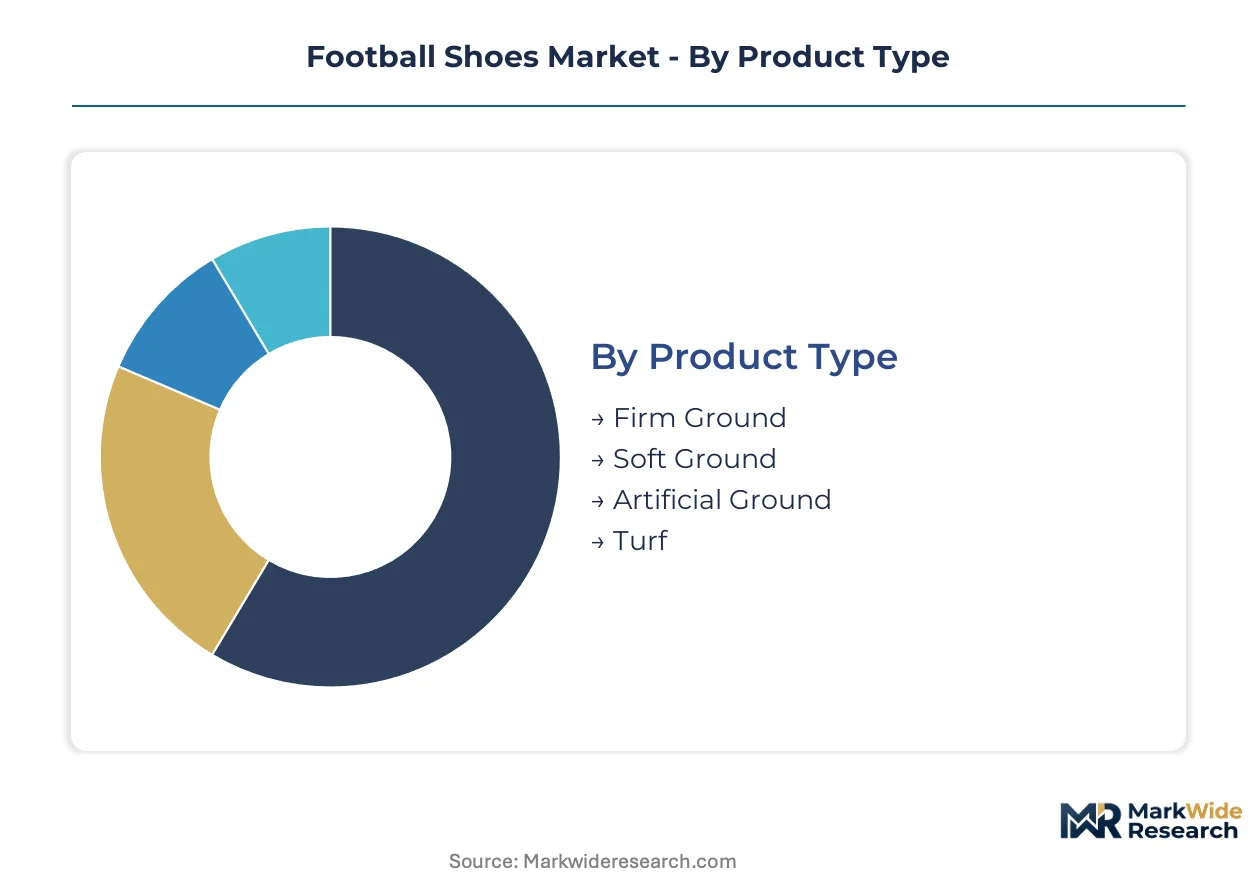
The football shoes market segmentation reflects diverse player needs and evolving product lifecycles. Understanding these segments is crucial for manufacturers to align product development with specific consumer demands and regional preferences. Material innovation and regulatory compliance significantly influence product offerings across different tiers.
Product Type:
Product types exhibit varying replacement cycles, with high-performance specialized boots often having shorter lifespans due to intense usage. Versatile options typically see longer retention periods.
- Firm Ground:This product type features conical or bladed studs optimized for natural grass pitches that are dry or slightly damp. Firm Ground boots command the largest market share globally due to their versatility and widespread use in football-centric nations such as Brazil and across Europe.
- Soft Ground:These boots incorporate longer, often detachable metal studs designed for maximum grip on wet, muddy natural grass surfaces. Demand for Soft Ground footwear concentrates in regions with heavy rainfall and traditional grass pitches, including parts of the UK and Northern Europe.
- Artificial Ground:This category includes footwear with multiple, shorter conical studs specifically engineered for optimal traction on synthetic turf fields. Artificial Ground shoes are gaining traction in urban areas and countries with extensive artificial pitch infrastructure, like parts of Germany and the Netherlands.
- Turf:Turf shoes feature a high density of small rubber studs or nubs, providing grip and cushioning on older artificial turf surfaces or indoor courts.
Firm Ground footwear anchors the volume base while Artificial Ground solutions gain share at the steepest rate.
End User:
End-user segmentation highlights distinct performance requirements and purchasing motivations across different player demographics.
- Men:This segment represents the largest consumer group, demanding a wide array of performance features, advanced technologies, and diverse aesthetic options. Demand for men's football shoes is globally distributed, driven by high participation rates in organized leagues and casual play.
- Women:This segment requires footwear designed with specific anatomical considerations, including narrower fits and lower ankle collars. The expanding professionalization of women's football leagues in Europe and North America is driving dedicated product development and marketing efforts for female players.
- Kids:Children's football shoes prioritize durability, comfort, and safety features to support growing feet and withstand frequent play. This segment sees consistent demand from youth sports programs worldwide.
- Professional Players:This highly specialized segment demands custom-fit, lightweight, and technologically advanced boots for peak performance at elite competitive levels.
The Men's segment forms the largest consumer cohort, while the Women's segment shows significant expansion.
Material:
Material choices directly impact a shoe's performance characteristics, durability, and compliance with environmental regulations.
- Leather:Traditional leather football shoes, often kangaroo or calfskin, offer superior touch, comfort, and a custom-forming fit over time. Demand for leather boots persists in markets valuing classic feel and natural material properties, particularly in South America and some European countries.
- Synthetic:Advanced synthetic materials provide lightweight construction, improved water resistance, and greater design flexibility compared to traditional leather. These materials are increasingly adopted in response to sustainability mandates like the EU Green Deal and consumer demand for high-performance, lower-maintenance options.
- Mesh:Mesh materials are used primarily in the upper construction for enhanced breathability and reduced weight, contributing to a lighter and more comfortable boot.
- Rubber:Rubber compounds are foundational for outsoles, providing essential grip, traction, and durability across various playing surfaces.
Synthetic materials are rapidly innovating, while Leather remains a foundational choice for specific player preferences.
Price Tier:
Price tiers reflect varying levels of technology integration, material quality, and brand positioning, catering to different consumer budgets.
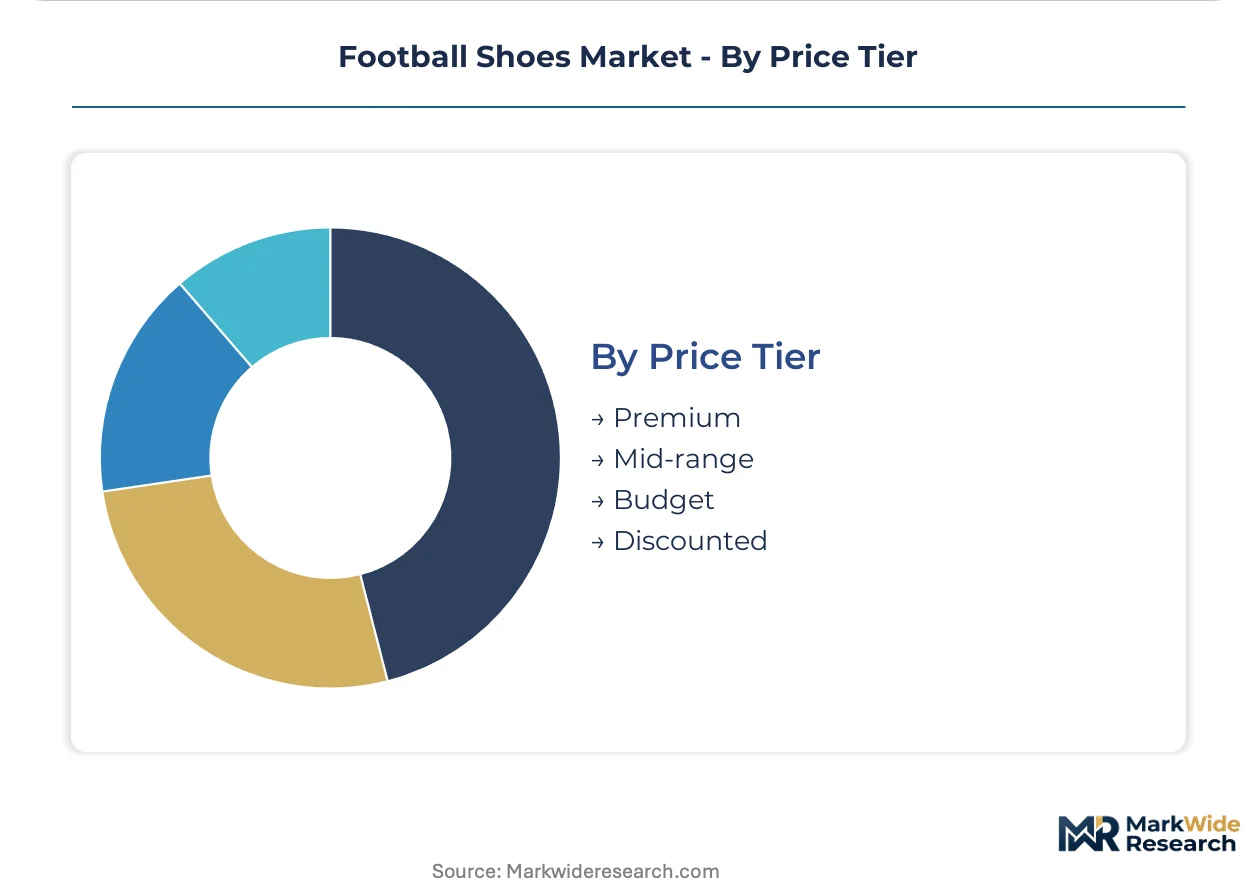
- Premium:Premium football shoes incorporate cutting-edge materials, advanced soleplate designs, and integrated performance technologies for elite-level play. This tier targets professional athletes and affluent amateur players in markets like Western Europe and North America.
- Mid-range:Mid-range options offer a balance of performance features and affordability, making them suitable for regular club and amateur players. This tier captures a significant global consumer base, driven by widespread participation in organized football.
- Budget:Budget-friendly football shoes provide essential functionality and durability for casual players or those with limited spending capacity.
- Discounted:This tier includes older models, clearance items, or promotional stock offered at reduced prices to clear inventory and attract price-sensitive consumers.
The Premium segment drives brand perception, while the Mid-range segment captures the largest consumer base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for football shoes exhibits regional asymmetry, with premium products commanding higher margins in Western Europe compared to more price-sensitive markets in Latin America. Manufacturers adapt product strategies to cater to these divergent economic landscapes. This differentiation impacts material selection and brand positioning across major markets.
Brazil
Demand for Firm Ground boots and traditional leather persists across the country's vast football-playing population. The ANVISA regulatory body ensures product safety and material compliance for all footwear sold. Production and distribution hubs in São Paulo cater to the country's extensive football culture, driving significant volume.
Germany
Artificial Ground solutions are gaining traction due to extensive synthetic pitch infrastructure in urban areas. Compliance with the EU Green Deal drives adoption of recycled materials and sustainable manufacturing practices. The Ruhr region's sporting goods industry focuses on performance innovation and sustainability in footwear design.
United Kingdom
Soft Ground footwear sees consistent demand due to prevalent wet, muddy conditions on natural grass pitches. REACH regulations significantly influence chemical safety standards for all imported and manufactured boots. Manchester and London serve as key retail and marketing centers for major brands, impacting consumer trends.
United States
The expanding women's football segment creates new demand for female-specific designs and marketing campaigns. Consumer Product Safety Commission (CPSC) standards ensure footwear safety and material compliance across all product tiers. Portland, Oregon, functions as a major design and innovation hub for leading athletic brands.
China
GB standards dictate product composition and safety requirements for market access and domestic sales. The dual carbon goals encourage sustainable manufacturing practices in footwear production, impacting material sourcing. Guangzhou and Dongguan are significant manufacturing clusters for athletic footwear, including football shoes, serving both local and export markets.
Football Shoes Market Key Industry Players
Global brand leaders and agile niche specialists split the football shoes market, reflecting varying competitive strategies. The market exhibits a tiered structure, with a few dominant players controlling significant share, while numerous smaller brands target specific segments. Major brands focus on technology licensing and direct-to-consumer platform expansion. Niche players often pursue strategic partnerships and portfolio diversification to gain market traction.
Within the global brand leader archetype, Nike Inc. and Adidas AG exemplify extensive market reach and diversified product portfolios, leveraging their strong brand equity. PUMA SE also sits within this tier, known for its strategic collaborations and strong brand positioning in specific European and Latin American markets, differentiating its offerings. These companies leverage their established distribution networks and digital direct-to-consumer platforms to maintain their competitive positions. Their strategies often involve continuous innovation in material science, performance features, and targeted marketing campaigns to engage diverse consumer segments.
| Leading Market Players |
|---|
| Nike Inc. |
| Adidas AG |
| PUMA SE |
| Under Armour Inc. |
| ASICS Corporation |
| New Balance Athletics Inc. |
| Mizuno Corporation |
| Decathlon SA |
| JOMA SPORT SA |
| Others |
Cost & Logistics Intelligence
Asia-Europe maritime routes' cost dynamics directly influence supply concentration from manufacturing hubs and subsequent price differentiation across global football shoe markets. Unpredictable freight costs impact brand margins and consumer pricing.
Pricing Analysis
Custom-configured football shoes command a premium over standard, mass-produced models, reflecting a per-unit transactional pricing model. Price differentiation stems from brand equity and the integration of advanced performance technologies. Pricing softness arises from input cost volatility for specialized synthetic materials, which brands must absorb or pass on. Budget-conscious consumers exhibit the highest price sensitivity, while professional players prioritize performance regardless of cost.
Supply Chain Analysis
The upstream supply of specialized synthetic textiles and recycled polymers forms the foundation of football shoe manufacturing. Production concentrates across Asia, notably in China, Vietnam, and Indonesia, which source essential rubber compounds for outsoles. Commodity price volatility for these advanced materials presents a significant supply chain risk. Distribution runs through a dual model, balancing established multi-brand sporting goods retailers with expanding direct-to-consumer digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The football shoes market is experiencing an early-cycle expansion story, primarily driven by the professionalization and growing viewership of women's football leagues globally. This creates new demand for specialized footwear designs.
For Market Incumbents: Insulate core market share by deepening direct-to-consumer relationships through digital ecosystem expansion. Invest significantly in intellectual property protection to counter the threat of counterfeit products, particularly in emerging markets. Leverage R&D in advanced recycled synthetic materials to meet sustainability mandates and differentiate product lines. Consolidate supply chain partnerships to manage input cost volatility effectively.
For New Entrants and Emerging Players: Highly specialized footwear for alternative football formats represents a penetrable entry point, particularly for Artificial Ground solutions in urban areas. Hyper-personalization via direct-to-consumer channels offers a premium, high-margin service based on player foot scans. Target specific European and Latin American markets with unique traction patterns for futsal or beach soccer. A collaboration-driven go-to-market strategy can build rapid brand recognition.
For Investors and Strategic Acquirers: Agile niche specialists with strong intellectual property in material science offer attractive long-term acquisition prospects over the next 5-10 years. These targets often possess expertise in bio-polymers or smart shoe integration. Focus on companies demonstrating robust compliance with multi-regional regulatory frameworks, such as REACH and GB standards. A signal to watch is the accelerated adoption rate of recycled content in professional-grade footwear.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Direct-to-Consumer Channels | This move captures higher margins and builds direct customer relationships for Nike Inc. |
| Invest in Sustainable Material R&D | This meets EU Green Deal mandates and attracts environmentally conscious consumers. |
| Develop Niche Surface Footwear | This addresses specialized player needs for artificial turf and futsal courts. |
| Enhance Intellectual Property Protection | This safeguards unique outsole patterns and upper technologies from imitation. |
| Integrate Smart Shoe Technology | This creates new revenue streams in sports analytics and connected fitness markets. |
Research Approach
A standing panel of footwear R&D directors, brand managers, retail buyers, and professional athletes provided ongoing calibration for market sizing. This approach combined primary interviews with extensive secondary validation from company 10-K filings, sports industry reports, and regulatory body publications. Bottom-up and top-down triangulation ensured robust data points across all segments.
Scenario-bracketing techniques defined the plausible range of outcomes for the football shoes market across the analysis window. The analytical framework modeled segmentation dimensions including product type, end user, material, price tier, and regional regulatory compliance. Compound annual growth rates were derived from historical growth patterns and projected adoption rates. Athlete participation rates served as a key forecast input.
Macroeconomic conditions sit as an overlay; deviation in global GDP growth or consumer spending would shift the trajectory of market expansion. Forecasts reflect assumptions regarding input cost volatility and evolving regulatory landscapes. Cross-checking against industry association reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Asia Pacific Footwear Market
Footwear
Protective Footwear Market
Footwear
Global Men Leather Shoes Market
Footwear
Shoe Insoles Market
Footwear
Women's Luxury Footwear Market
Footwear
Snow Boots for Women Market
Footwear
UK Lifestyle Sneakers Market
Footwear
Lace Up Boots Market
Footwear
Leather Footwear Market
Footwear
Driving Footwear Market
Footwear
Waterproof Sneakers Market
Footwear
North America Athletic Footwear Market
Footwear
Sneaker Boots Market
Footwear
Europe Footwear Market
Footwear
Sustainable Footwear Market
Footwear
Leather Sneakers Market