
 Europe Footwear Market | 2026-2036
Europe Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Footwear Market Intelligence
A capital-intensity divergence between automated manufacturing scale and artisan craft capacity is rotating competitive advantage toward firms that control both ends of the production spectrum. Adidas AG leverages robotic knitting and 3D-printed midsole platforms to compress lead times. PUMA SE anchors its position through sportstyle crossovers that blur athletic and casual boundaries. KERING sustains ultra-premium pricing via controlled leather tannery networks and limited-batch artisan workshops.
Europe footwear comprises finished goods engineered from leather, synthetic polymers, rubber compounds, or textile uppers, assembled through cementing, stitching, or injection molding to provide biomechanical support, weather protection, and aesthetic expression for consumer and professional use. Athletic shoes lead volume throughput as performance running and court sports categories absorb technical innovation investments, while boots command margin concentration in workwear and outdoor sub-segments where waterproof membrane integration and certified safety toe caps justify price premiums. Material segmentation shows leather retaining dominance in formal and luxury tiers despite synthetic alternatives gaining share in vegan-certified and recycled-content product lines.
REACH restricts chemical inputs in adhesives and dyes across EU manufacturing, while the EU Green Deal's circular economy action plan pressures brands to design for disassembly and incorporate post-consumer recycled content. ECHA substance evaluations and national extended producer responsibility schemes in France and Italy are tightening end-of-life collection obligations. Stakeholders must monitor how digital product passport requirements under the Ecodesign for Sustainable Products Regulation reshape supply chain transparency demands and supplier qualification criteria.
Market Dynamics
REACH chemical restrictions and EU Green Deal circularity mandates are compressing material choices while digital product passport requirements under the Ecodesign for Sustainable Products Regulation force supply chain transparency investments that favor integrated manufacturers over fragmented supplier networks.
Growth Catalysts
- Performance Running Demand:Fitness-conscious consumers in Germany, France, and Italy are absorbing technical innovation investments in energy-return foams and carbon-fiber plates, expanding the premium athletic segment.
- REACH-Driven Material Innovation:Restrictions on chromium VI in leather tanning and phthalates in synthetic uppers are accelerating bio-based polyurethane and mycelium leather adoption among compliant suppliers.
- Extended Producer Responsibility Schemes:France and Italy's mandatory end-of-life collection obligations are creating closed-loop feedstock streams that reduce virgin material costs for participating brands.
Market Restraints
- Raw Material Concentration:European tanneries depend on hides from Brazil and Argentina, exposing margins to livestock disease outbreaks and export tariff volatility.
- Energy Cost Structure:Injection molding and vulcanization processes require natural gas-intensive curing, linking production economics to EU carbon pricing and pipeline supply disruptions.
- Substitution Threat from Secondhand:Resale platforms like Vestiaire Collective and Vinted are capturing wallet share in fashion footwear, compressing new-unit demand in the 18-35 demographic.
Strategic Opportunities
- Eastern European Manufacturing:Romania and Portugal offer untapped artisan capacity with lower labor costs than Italy, enabling near-shored premium production for German and French brands.
- Digital Product Passport Mandate:The Ecodesign for Sustainable Products Regulation creates first-mover advantage for firms that deploy blockchain traceability before the 2027 enforcement window.
- 3D-Printed Customization Convergence:Combining robotic knitting with foot-scanning retail kiosks enables made-to-measure athletic shoes at mass-market price points.
Industry Challenges
- Certification Timeline Compression:ECHA substance evaluations and CE marking updates for safety footwear require 12-18 month requalification cycles that delay product launches.
- Legacy ERP Integration:Digital product passport data standards are forcing mid-tier manufacturers to replace decades-old inventory systems with API-connected traceability platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Footwear Market |
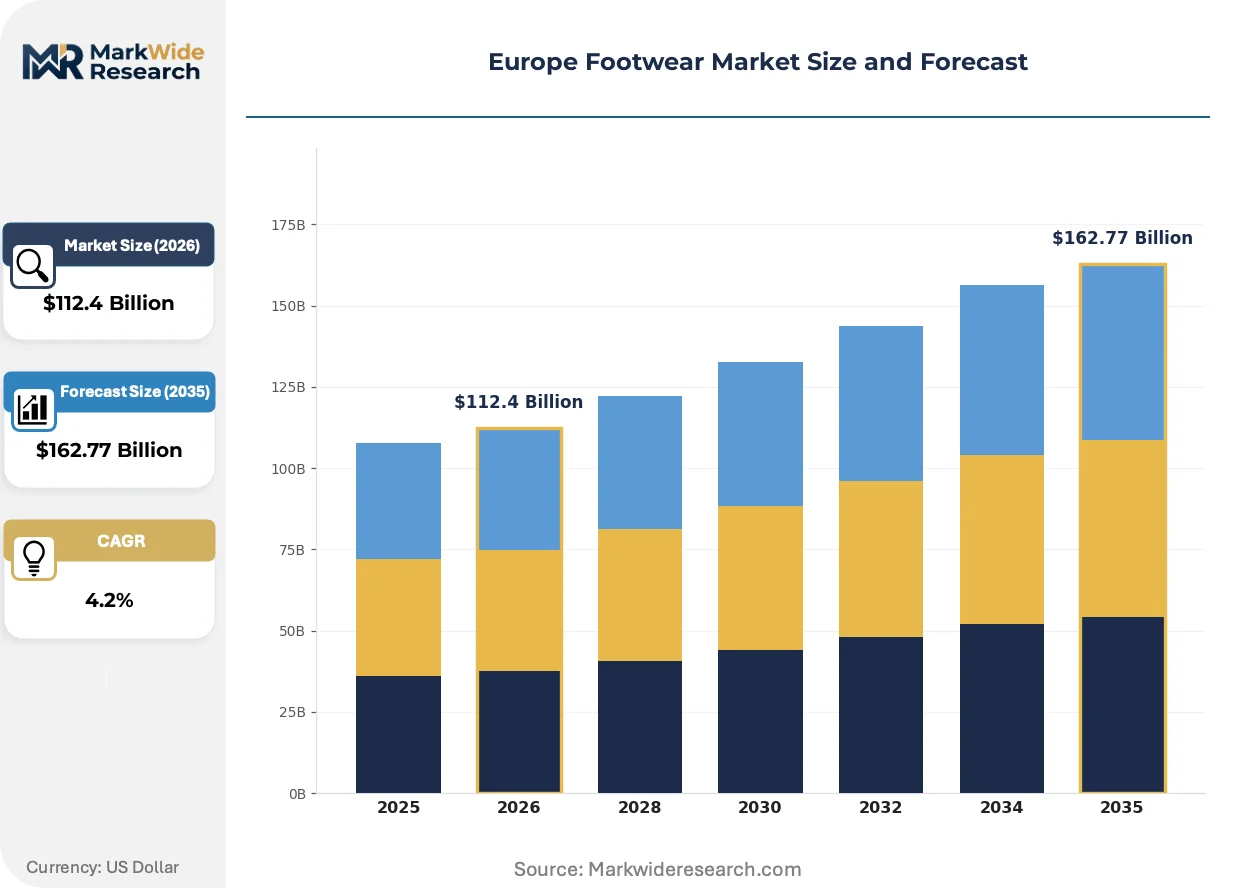
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $162.77 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Casual Shoes, Athletic Shoes, Formal Shoes, Boots Material: Leather, Synthetic, Rubber, Textile End User: Men, Women, Children, Unisex Distribution Channel: Online, Specialty Stores, Department Stores, Discount Stores |
| Companies Covered | Nike, Inc., Adidas AG, PUMA SE, New Balance Athletics Inc., ASICS Corporation, Under Armour, Inc., Skechers USA, Inc., Wolverine Worldwide, Inc., KERING, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Footwear Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory data mandates are converging to reshape how footwear is designed, manufactured, and sold across European markets. Three developments dominate the transformation.
Biodegradable midsole foams derived from algae and castor oil are decomposing the petroleum-dependent cushioning supply chain. Performance running brands in Germany and France are adopting these materials for 2026 product lines. The shift is compressing reliance on ethylene-vinyl acetate suppliers and creating captive feedstock partnerships with agricultural processors.
The EU Green Deal's circular economy action plan is mandating design-for-disassembly standards that require separable sole-upper constructions and recycled content minimums. Footwear manufacturers must now engineer adhesives that bond durably yet release cleanly for material recovery. Italian luxury houses and Portuguese contract manufacturers are investing in solvent-free cementing technologies to maintain access to the single market.
Direct-to-consumer subscription models for athletic shoe replacement are disrupting traditional retail replenishment cycles. German and Dutch consumers are adopting quarterly delivery programs that bundle wear-tracking apps with automatic sizing adjustments. This pattern concentrates demand forecasting accuracy requirements on brands while reducing wholesale margin leakage to multi-brand retailers.
Europe Footwear Market Segmentation
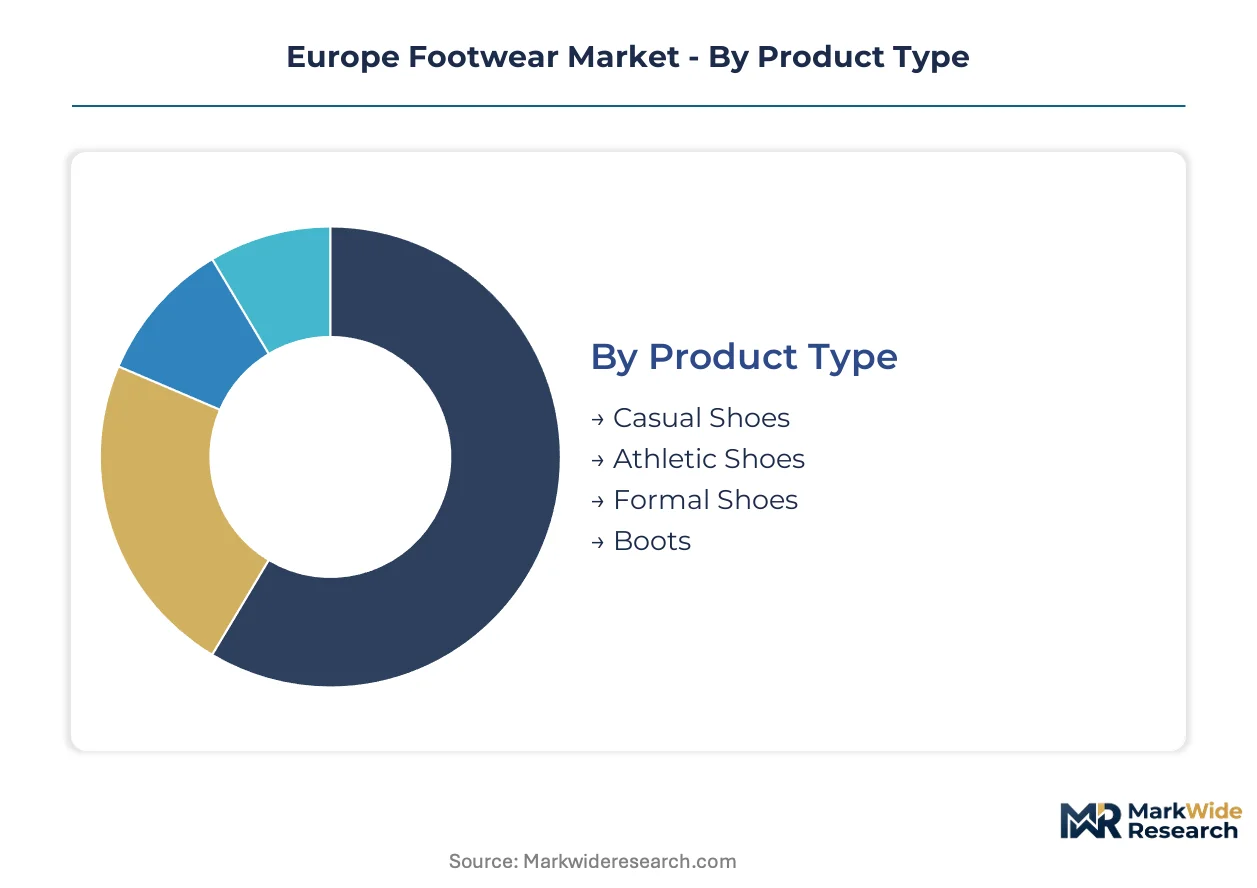
Footwear segmentation in Europe reflects divergent compliance burdens and margin structures across product categories. Material sourcing restrictions under REACH and the EU Green Deal create asymmetric cost pressures that reshape competitive positioning within each segment tier.
Product Type:
REACH chemical restrictions and CE marking requirements for safety certification create divergent regulatory loads across footwear categories, with performance and protective segments facing the steepest compliance investments.
- Athletic Shoes:Engineered with energy-return foams, carbon-fiber plates, and engineered mesh uppers for biomechanical performance. Demand concentrates in Germany and France where fitness-conscious consumers absorb technical innovation investments; REACH-compliant bio-based midsole materials are displacing petroleum-dependent ethylene-vinyl acetate.
- Boots:Constructed with waterproof membrane integration, certified safety toe caps, and vulcanized rubber outsoles for workwear and outdoor applications. Italian and German industrial safety regulations mandate CE marking updates that compress certification timelines; price premiums justify margin concentration in this segment.
- Casual Shoes:Blends athletic and formal design elements with cemented or stitched constructions for everyday wear.
- Formal Shoes:Leather-dominant constructions with Blake or Goodyear welted soles for professional and ceremonial occasions.
Athletic shoes handle the majority of throughput; boots are expanding most quickly on share as safety certification requirements tighten across European workplaces.
Material:
Cost tier differentiation separates premium natural inputs from mass-market synthetics, with circular economy mandates forcing material innovation investments that favor integrated tanneries and polymer compounders.
- Leather:Full-grain and corrected-grain hides processed through chrome or vegetable tanning for durability and aesthetic aging. Italian luxury houses sustain ultra-premium pricing via controlled tannery networks; ECHA restrictions on chromium VI accelerate solvent-free tanning adoption.
- Synthetic:Polyurethane, polyester, and recycled polymer constructions offering vegan certification and design flexibility. Portuguese and Romanian contract manufacturers absorb the fastest volume growth as brands seek REACH-compliant alternatives to leather; mycelium and bio-based polyurethane adoption climbs.
- Rubber:Natural and synthetic rubber compounds vulcanized for outsole traction and weather resistance.
- Textile:Woven and knitted natural or synthetic fiber uppers for breathability and lightweight performance.
Synthetic materials are gaining share fastest as vegan certification and recycled-content mandates reshape procurement patterns; leather retains dominance in formal and luxury tiers despite regulatory compression.
End User:
Application-driven segmentation concentrates demand forecasting requirements on gender-specific sizing architectures and children's replacement cycles.
- Women:Fashion-forward and performance-oriented constructions spanning athletic, casual, and formal categories. German and French consumers drive premium segment absorption; direct-to-consumer subscription models for athletic replacement concentrate in this demographic.
- Men:Workwear, performance athletic, and formal segments with longer replacement cycles and safety certification requirements. Italian and German safety footwear demand anchors volume in boots and protective categories.
- Children:Rapid size-turnover segments with growth-accommodating designs and durability constraints.
- Unisex:Neutral sizing architectures spanning casual and athletic categories with simplified inventory management.
Women's segments handle the majority of fashion footwear throughput; children's categories show the steepest expansion trajectory as replacement frequency outpaces adult demographics.
Distribution Channel:
Customer type and geography combine to fragment channel power, with digital-native consumers in Northern Europe diverging from tactile-preference shoppers in Southern markets.
- Online:Direct-to-consumer platforms and marketplace aggregators with algorithmic personalization and subscription replenishment. German and Dutch consumers adopt quarterly delivery programs with wear-tracking apps; digital product passport requirements favor API-connected inventory systems.
- Specialty Stores:Single-brand flagships and multi-brand athletic retailers with technical fitting services and localized assortment curation. Italian and French premium positioning depends on controlled retail environments.
- Department Stores:Multi-category retail environments with seasonal promotional calendars and broad demographic reach.
- Discount Stores:Price-focused channels with limited assortment depth and high inventory velocity.
Online channels are gaining share fastest as subscription models and digital passport compliance reshape fulfillment economics; specialty stores retain margin concentration in premium and performance segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across European markets, with German and French consumers absorbing premium athletic pricing while Southern European buyers prioritize value-tier casual footwear and resist subscription model premiums.
Germany
Performance running and industrial safety footwear absorb the highest per-capita spending in Europe, driven by fitness culture and workplace protection mandates. The EU Green Deal's extended producer responsibility scheme requires brands to finance end-of-life collection infrastructure. Bavaria's manufacturing corridor hosts automated production facilities serving both domestic demand and export markets.
France
Luxury fashion houses and athletic sportstyle crossovers capture disproportionate margin concentration in Paris and Lyon metropolitan markets. ANSM enforces REACH compliance timelines for chemical inputs in leather tanning that compress product development cycles. The Île-de-France region concentrates flagship retail environments where controlled brand presentation sustains ultra-premium pricing.
Italy
Artisan leather workshops in Tuscany and Veneto anchor global supply chains for Blake and Goodyear welted formal footwear. ECHA restrictions on chromium VI accelerate solvent-free tanning adoption among tanneries clustered around Arzignano. Lombardy hosts the densest concentration of luxury brand headquarters coordinating controlled leather sourcing networks.
United Kingdom
Direct-to-consumer subscription models and resale platform adoption run highest in London and Southeast England, compressing traditional wholesale channel power. The UK's post-Brexit regulatory divergence from REACH creates dual compliance burdens for manufacturers serving both markets. The Midlands retains contract manufacturing capacity for safety and workwear boots serving domestic industrial demand.
Spain
Value-tier casual and children's footwear segments show resilient volume throughput despite price sensitivity among consumers in Madrid and Barcelona. The EU Ecodesign for Sustainable Products Regulation's digital passport requirements pressure Iberian manufacturers to upgrade traceability systems. Catalonia's textile industrial base supplies knitted uppers to brands seeking near-shored synthetic material alternatives.
Europe Footwear Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrating in automated manufacturing and controlled retail distribution while artisan capacity remains geographically fragmented. The market structure rewards players that command both robotic production scale and heritage craft credibility. Three archetypes dominate: global athletic brands with materials science pipelines, luxury houses with captive tannery networks, and contract manufacturers with flexible regional capacity. Competitive moves center on M&A for digital fit technologies and strategic partnerships with bio-based material suppliers.
Within the integrated athletic tier, Adidas AG and Nike, Inc. occupy positions defined by automated knitting platforms and energy-return foam development pipelines. PUMA SE exemplifies the sportstyle crossover archetype that merges performance credibility with lifestyle distribution. KERING anchors the ultra-premium luxury tier through controlled supply chain architecture and limited-batch production discipline.
| Leading Market Players |
|---|
| Nike, Inc. |
| Adidas AG |
| PUMA SE |
| New Balance Athletics Inc. |
| ASICS Corporation |
| Under Armour, Inc. |
| Skechers USA, Inc. |
| Wolverine Worldwide, Inc. |
| KERING |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day raw hide curing cycles compress margin recovery windows for tanneries exposed to Brazilian livestock volatility, concentrating pricing power among vertically integrated luxury houses while fragmenting it across synthetic-dependent contract manufacturers. REACH compliance costs and EU carbon pricing on natural gas-intensive vulcanization processes feed directly into tiered margin structures that separate automated scale players from artisan workshops.
Pricing Analysis
After-sales service revenue through subscription-based athletic shoe replacement programs is emerging as the dominant lifetime value driver for direct-to-consumer brands. Three-tier pricing structure across premium performance, standard sportstyle, and economy casual levels stratifies according to certification grade and energy-return foam content. Pricing pressure stems from resale platform capture of fashion footwear wallet share among younger demographics. Mass-market synthetic tiers exhibit highest price sensitivity; ultra-premium leather segments anchored by Italian artisan networks show lowest elasticity.
Supply Chain Analysis
Strategic stockpiling of hides from Brazil and Argentina dominates tannery procurement strategies, contrasting with just-in-time synthetic polymer flows from Portuguese and Romanian compounders. Raw material dependencies center on chromium-tanned hides, bio-based polyurethane feedstocks, and vulcanized rubber compounds. Tariff exposure on South American hide exports creates structural margin vulnerability. Distribution runs through integrated brand flagships in Paris and Milan alongside algorithmic direct-to-consumer platforms serving Northern European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in the compliance-driven material innovation space, as REACH restrictions and digital passport mandates create capability gaps that specialist suppliers can exploit. Subscription model disruption and resale platform growth fragment traditional channel control, opening niches for agile positioning.
For Market Incumbents: Shield market position by deepening captive control over solvent-free tannery networks before ECHA chromium VI restrictions tighten further, and accelerate API-connected inventory system deployment to capture digital product passport first-mover advantage against mid-tier competitors. Regulatory compliance investments and traceability infrastructure serve as the priority defensive levers. For New Entrants and Emerging Players: Differentiate on mycelium leather and bio-based polyurethane formulations to capture vegan-certified white space in German and French premium athletic segments, and deploy foot-scanning retail kiosk partnerships as the go-to-market angle for made-to-measure positioning. Eastern European contract manufacturing capacity in Romania offers the most penetrable near-shore entry point. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory compliance burdens and digital passport infrastructure costs will compress mid-tier manufacturer margins, creating acquisition targets among distressed artisan workshops and legacy ERP-dependent suppliers. Watch for ECHA substance evaluation acceleration as the inflection signal indicating certification timeline compression severity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tannery Networks | Captive hide sourcing from Arzignano clusters insulates margins from Brazilian tariff volatility. |
| Digital Product Passport Deployment | Blockchain traceability platforms secure EU market access before Ecodesign enforcement windows. |
| Subscription Model Launch | Quarterly replenishment programs with German wear-tracking apps concentrate demand forecasting accuracy. |
| Bio-Based Material Partnership | Algae and castor oil foam feedstock agreements displace petroleum-dependent EVA suppliers. |
| Eastern European Capacity Expansion | Portuguese and Romanian artisan workshops enable near-shored premium production at labor cost advantage. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with brand sourcing directors, tannery technical managers, retail category buyers, and regulatory compliance officers, validated against secondary sources including ECHA substance evaluation databases, EU Green Deal circular economy action plan filings, customs trade data on hide imports, and SEC footwear sector disclosures. Bottom-up volume modeling triangulated with top-down market sizing across the analysis window.
Across the projection horizon, analytical frameworks modeled segmentation dimensions spanning product type, material composition, end-user demographic, and distribution channel architecture. CAGRs derived from regression analysis against fitness participation rates, regulatory compliance cost indices, and synthetic material substitution curves. Forecast inputs incorporated REACH restriction implementation timelines and extended producer responsibility scheme participation rates.
Material uncertainties — livestock disease outbreaks in South America, EU carbon pricing acceleration, and digital passport standard finalization — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory enforcement consistency and consumer subscription adoption elasticity. Revision becomes warranted when bio-based material cost parity thresholds cross decisive levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Slip on Shoes Market
Footwear
Global Espadrille Flats Market
Footwear
Barefoot Shoes Market
Footwear
Tennis Shoes Market
Footwear
Second Hand Designer Shoes Market
Footwear
Water Shoes Market
Footwear
OEM Shoe Manufacturer Service Market
Footwear
Leather Sneakers Market
Footwear
South America Athletic Footwear Market
Footwear
Europe Barefoot Shoes Market
Footwear
Formal Shoes Market
Footwear
Casual Shoes Market
Footwear
UK Lifestyle Sneakers Market
Footwear
PU Sole (Footwear Polyurethane) Market
Footwear
Sneakers Market
Footwear
Cowgirl Boots Market