
 Protective Footwear Market | 2026-2036
Protective Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Protective Footwear Market Outlook
EU PPE Regulation 2016/425 is consolidating demand around certified European manufacturers as importers face steeper conformity assessment costs. Honeywell International Inc. leverages its global distribution network to sustain defense and industrial channel dominance. Wolverine World Wide Inc. anchors North American work-boot retail through specialized brand portfolios. Bata Corporation dominates emerging-market procurement through vertically integrated rubber processing in Asia and Africa.
Protective footwear encompasses safety-engineered boots and shoes designed with reinforced toe caps, puncture-resistant midsoles, and slip-resistant outsoles to shield workers from impact, compression, and electrical hazards in occupational environments. Steel-toe boots incorporate alloy or composite reinforcement meeting ASTM F2413 impact standards, while manufacturing processes include direct-attach, cement, and welt construction methods varying in durability and cost. Steel-toe boots occupy the largest volume share across construction and heavy manufacturing end users. Composite materials in safety footwear are gaining fastest as metal-free designs satisfy electrical hazard and airport security requirements. Leather commands premium pricing in oil and gas applications where flame resistance and longevity outweigh synthetic alternatives.
OSHA 29 CFR 1910.136 mandates protective footwear in US workplaces with foot injury hazards, while EU PPE Regulation 2016/425 requires CE marking and notified body involvement for Category III safety boots. ISO 20345 governs international performance benchmarks for safety footwear, creating harmonization pressure for exporters serving multiple jurisdictions. Stakeholders must monitor evolving state-level US procurement rules and EU ecodesign requirements affecting material recyclability and chemical content disclosures.
Market Dynamics
EU PPE Regulation 2016/425 is consolidating procurement around certified manufacturers as importers absorb steeper conformity assessment costs, while construction sector safety mandates accelerate replacement cycles for worn safety boots.
Growth Catalysts
- OSHA 29 CFR 1910.136:Federal mandates require protective footwear in workplaces with foot injury hazards, compelling employer-funded equipment programs across manufacturing and logistics facilities.
- Composite material substitution:Metal-free safety footwear satisfies electrical hazard and airport security requirements, expanding addressable demand from energy utilities and transportation screening personnel.
- German industrial union agreements:Collective bargaining mandates for employer-provided protective equipment upgrades are compressing replacement timelines and elevating specification standards.
Market Restraints
- Natural rubber price volatility:Southeast Asian supply disruptions and climate-induced harvest variability compress margins for manufacturers dependent on latex-based soling compounds.
- CE marking conformity costs:EU PPE Regulation 2016/425 requires notified body involvement for Category III safety boots, creating capital barriers for smaller importers seeking European market access.
- Synthetic leather performance gaps:Petroleum-based alternatives fail to match genuine leather's flame resistance and break-in durability, limiting substitution in oil and gas applications.
Strategic Opportunities
- India's construction acceleration:Infrastructure investment and urbanization are expanding the addressable base for steel-toe and puncture-resistant boot procurement.
- Ecodesign requirements:EU material recyclability and chemical content disclosure rules favor manufacturers with closed-loop production capabilities and transparent supply chains.
- Direct-to-industrial digital platforms:Bulk procurement portals are disintermediating traditional safety distributors, enabling volume pricing and specification customization for large contractors.
Industry Challenges
- ISO 20345 harmonization complexity:Exporters serving multiple jurisdictions face conflicting national deviations from international performance benchmarks, extending certification timelines.
- Skilled pattern engineering shortage:Last-making and biomechanical fit expertise is aging out of European and North American manufacturing bases faster than training pipelines replenish.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protective Footwear Market |
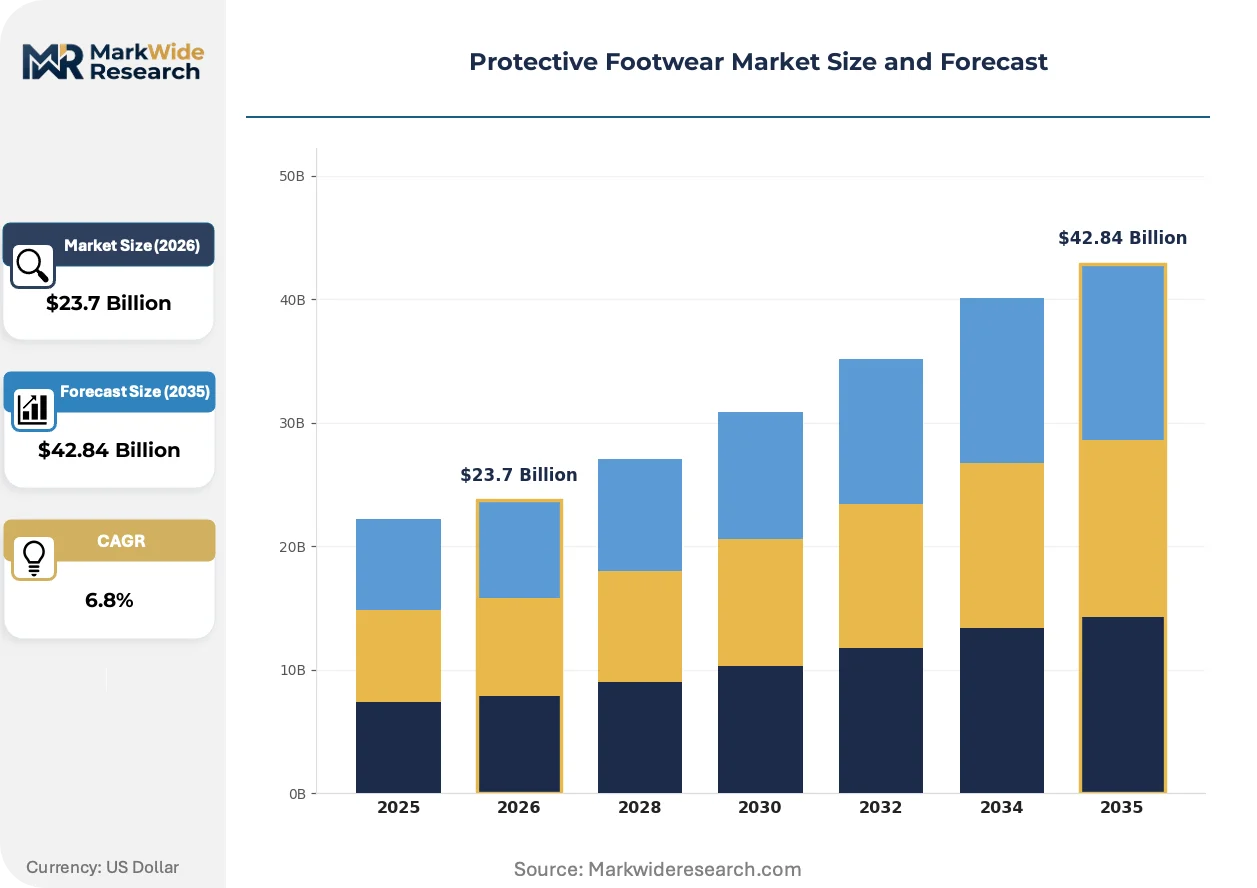
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel-Toe Boots, Waterproof Shoes, Insulated Footwear, Slip-Resistant Shoes Material: Leather, Rubber, Composite, Synthetic End User: Construction, Manufacturing, Agriculture, Oil & Gas Application: Industrial Work, Outdoor Activities, Hospitality, Healthcare |
| Companies Covered | Honeywell International Inc., Wolverine World Wide Inc., VF Corporation, Bata Corporation, Dunlop Protective Footwear, Protective Industrial Products, Inc., Uvex Group, ELTEN GmbH, Cofra SRL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protective Footwear Market Strategic Shifts
Material science advances and regulatory stringency are compressing product development cycles while elevating performance thresholds for impact resistance, chemical protection, and wearer comfort.
3D-printed midsole lattice structures are modularizing comfort customization across industrial safety footwear. Mining and heavy manufacturing operators are piloting scan-to-fit programs that generate site-specific cushioning geometries. This distributed manufacturing approach is modularizing regional production economics and reducing finished goods inventory exposure.
EU PPE Regulation 2016/425 is tightening chemical substance restrictions and post-market surveillance obligations for imported safety boots. Manufacturers must now maintain technical documentation for ten years and submit to random conformity verification. Asian exporters are responding by relocating testing capabilities to European notified bodies and pre-certifying product families.
Specification-driven purchasing is displacing brand-loyal procurement among large construction contractors and energy utilities. Safety managers now lead centralized buying committees that prioritize certified performance data over historical supplier relationships. This shift is most pronounced in Germany and the Netherlands, where industrial insurance frameworks reward documented compliance with reduced premium structures.
Protective Footwear Market Segmentation
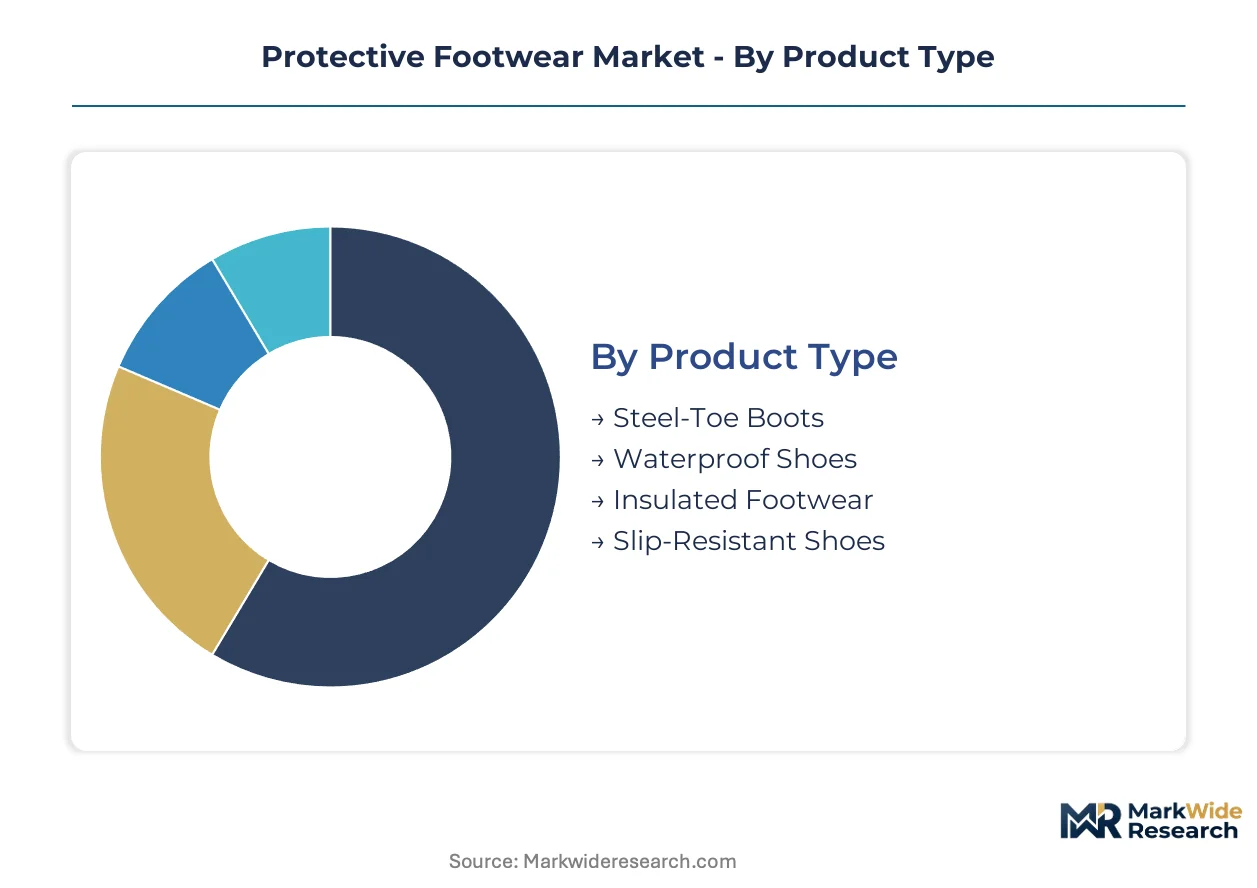
Segmentation in protective footwear reveals how safety specifications diverge across hazard profiles and procurement budgets. Each dimension—product construction, material chemistry, end-use environment, and application setting—creates distinct competitive arenas with different margin structures and certification requirements.
Product Type:
Supply concentration in steel-toe manufacturing centers on foundries with ASTM F2413 certification capabilities, while composite alternatives require specialized molding equipment that limits producer pools.
- Steel-Toe Boots:Alloy or composite-reinforced toe caps meeting impact and compression standards dominate construction and heavy manufacturing procurement. German industrial buyers specify these for employer-mandated equipment upgrades under collective agreements. Today's leader: Steel-Toe Boots. Tomorrow's challenger: Insulated Footwear.
- Waterproof Shoes:Membrane-lined constructions with sealed seams protect against liquid penetration in wet industrial environments. Demand concentrates in UK and Netherlands food processing facilities where hygiene protocols require washable protective equipment.
- Insulated Footwear:Thinsulate or wool-lined boots rated for cold-weather operations serve oil field workers in Alberta and North Dakota. Thermal protection specifications are tightening as energy utilities extend winter maintenance windows.
- Slip-Resistant Shoes:Specialized outsole compounds with coefficient-of-friction ratings above 0.5 target hospitality and healthcare floors where grease and fluid hazards persist.
Composite toe configurations are gaining specification share where electrical hazard and metal-detector compatibility matter.
Material:
Cost tiers separate full-grain leather command positions from synthetic alternatives competing on unit economics in high-turnover environments.
- Leather:Full-grain hides with flame-resistant tanning dominate oil and gas applications where break-in durability and spark protection justify premium positioning. Norwegian offshore operators specify vegetable-tanned variants for chemical resistance.
- Composite:Fiberglass and carbon-fiber toe caps plus non-metallic midsoles satisfy electrical hazard and airport security requirements. Energy utilities in Texas and aviation ground crews at Heathrow drive replacement demand.
- Rubber:Natural and synthetic latex soling compounds provide puncture resistance and chemical protection in agriculture and mining settings.
- Synthetic:Polyurethane and PVC constructions serve budget-conscious institutional buyers with shorter replacement cycles.
Leather retains pricing power in premium oil and gas procurement. Composite materials are climbing the fastest as metal-free designs expand addressable demand.
End User:
Volume concentration tracks construction acceleration in India and Germany, while oil and gas maintains specification intensity despite cyclical headcount fluctuations.
- Construction:Steel-toe and puncture-resistant boots constitute the largest procurement category as contractors enforce stricter site safety protocols. Indian infrastructure investment and German union-mandated equipment upgrades compress replacement timelines.
- Manufacturing:Assembly line and heavy machinery operations require impact-rated footwear with static-dissipative properties for electronics production.
- Agriculture:Chemical-resistant rubber boots and waterproof constructions protect against pesticide exposure and wet field conditions.
- Oil & Gas:Flame-resistant leather and metatarsal guards address spark, crush, and chemical splash hazards in upstream and downstream operations.
Construction drives current volume. Oil and gas sustains margin concentration through specification intensity.
Application:
Customer type differentiation separates specification-driven industrial procurement from comfort-prioritized service sector purchasing.
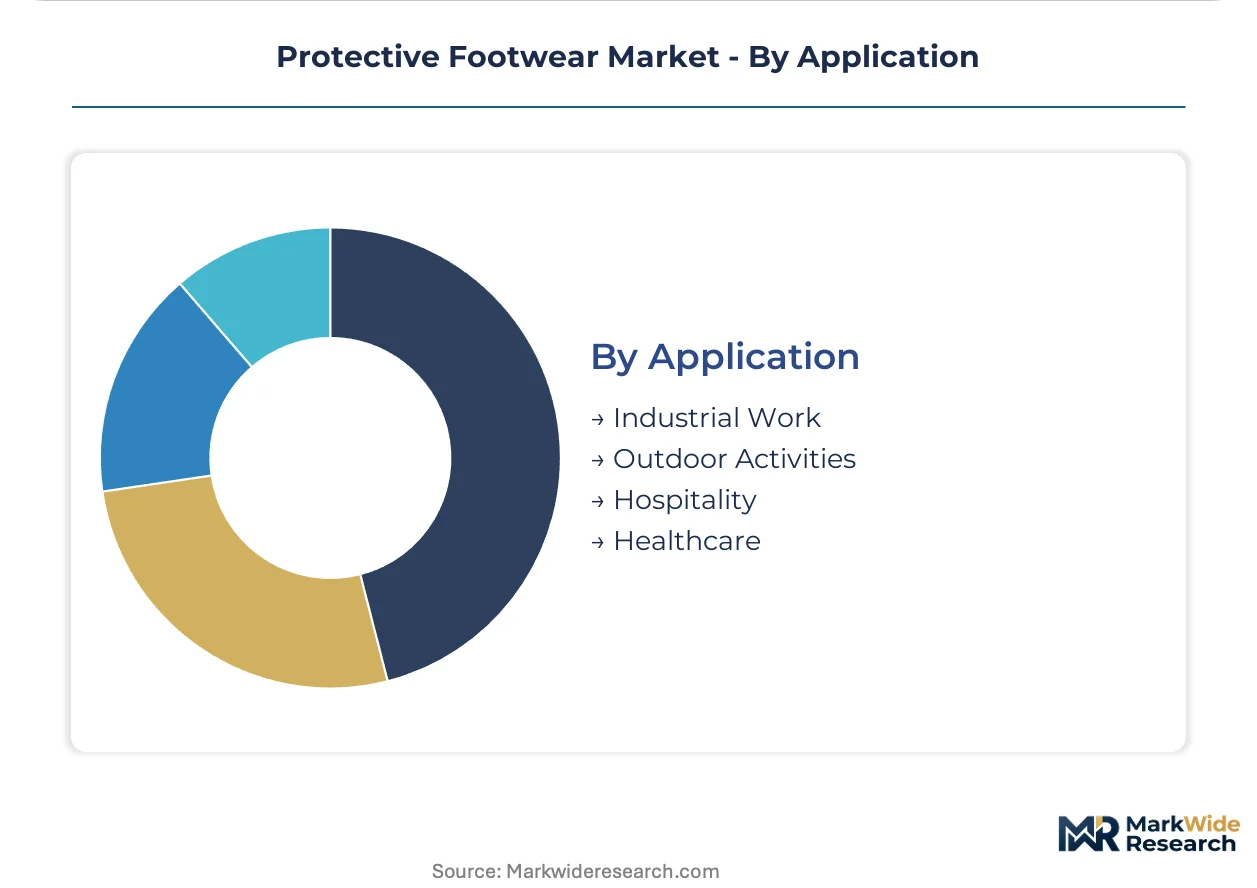
- Industrial Work:Heavy-duty constructions with reinforced toe caps, metatarsal protection, and chemical-resistant outsoles serve manufacturing, mining, and energy operations. OSHA 29 CFR 1910.136 mandates drive employer-funded programs across US facilities.
- Healthcare:Lightweight slip-resistant clogs and athletic-style safety shoes address fatigue and fall prevention in hospital environments.
- Outdoor Activities:Waterproof and insulated variants serve utility line workers, forestry crews, and emergency responders in exposed conditions.
- Hospitality:Oil-resistant outsoles and polished leather uppers balance kitchen safety with front-of-house appearance requirements.
Industrial Work anchors revenue scale. Healthcare is expanding most quickly as hospital systems centralize safety footwear programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial protective footwear manufacturing originated in European tanneries and American rubber factories during the early twentieth century, with Germany and the United States establishing the first standardized safety boot production at scale.
United States
Construction sector procurement dominates volume as contractors implement stricter site safety protocols under OSHA 29 CFR 1910.136 mandates. Federal requirements compel employer-funded protective equipment programs across manufacturing and logistics facilities. Houston's petrochemical corridor drives specification-grade flame-resistant leather boot demand for upstream energy operations.
Germany
Industrial union collective bargaining agreements mandate employer-provided protective equipment upgrades, compressing replacement timelines for certified safety footwear. EU PPE Regulation 2016/425 tightens CE marking requirements and notified body involvement for Category III boots. The Ruhr industrial basin concentrates procurement from automotive and heavy machinery operations with elevated specification standards.
China
Infrastructure investment and manufacturing expansion generate steel-toe and puncture-resistant boot procurement at volume scale. GB standards align with ISO 20345 international benchmarks while maintaining national deviations for domestic certification. Guangdong Province hosts integrated supply chains combining synthetic material production with direct-attach manufacturing for export markets.
India
Urbanization and national infrastructure programs expand the addressable base for construction safety footwear. Bureau of Indian Standards certification requirements create compliance thresholds for domestic market access. Maharashtra's Mumbai-Pune industrial corridor concentrates demand from manufacturing and logistics operations with emerging specification awareness.
Brazil
Agricultural chemical exposure and mining operations drive rubber boot procurement with puncture-resistant specifications. ANVISA regulates occupational health equipment while Mercosur trade agreements facilitate regional supply chain integration. São Paulo state's manufacturing belt anchors distribution networks serving Latin American industrial buyers.
Protective Footwear Market Competitive Environment
Capital-heavy producers compete with asset-light designers across a market consolidating around certified European manufacturers and vertically integrated Asian suppliers. The structure segments into three tiers: multinational conglomerates with global distribution networks, regional specialists with notified body certification capabilities, and emerging-market producers competing on unit economics. Dominant competitive moves include strategic partnerships for European conformity assessment access and portfolio diversification into metal-free composite materials.
Among diversified industrial conglomerates, Honeywell International Inc. and Wolverine World Wide Inc. occupy positions representing global distribution scale and specialized work-boot retail anchoring respectively. Bata Corporation exemplifies emerging-market vertical integration through rubber processing control in Asia and Africa. ELTEN GmbH and Cofra SRL represent European mid-tier specialists with concentrated notified body relationships and regional certification expertise.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Wolverine World Wide Inc. |
| VF Corporation |
| Bata Corporation |
| Dunlop Protective Footwear |
| Protective Industrial Products, Inc. |
| Uvex Group |
| ELTEN GmbH |
| Cofra SRL |
| Others |
Value Chain & Pricing Dynamics
EU ecodesign requirements for material recyclability and chemical content disclosure gate both qualified supply and premium-tier pricing access, as manufacturers with closed-loop production capabilities and transparent supply chains capture specification-grade procurement while importers face conformity assessment barriers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates flame-resistant leather boots for oil and gas from composite safety footwear for electrical hazard applications and synthetic constructions for high-turnover institutional buyers. Certification grade under EU PPE Regulation 2016/425 and volume scale drive price differentiation most acutely. Cost compression in economy-tier synthetic footwear is intensifying because petroleum-based alternatives compete on unit economics alone. Institutional buyers with shorter replacement cycles exhibit highest price sensitivity; oil and gas operators prioritize specification compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Southeast Asian natural rubber harvests exposed to climate-induced variability and supply disruptions. Manufacturing concentrates in China, Vietnam, and Indonesia, where integrated synthetic material production feeds direct-attach assembly for export markets. Raw material dependencies include natural latex soling compounds, full-grain leather hides, and fiberglass-composite toe cap formulations. Tariff exposure on finished footwear imports into the European Union creates structural risk for Asian exporters. Distribution runs through specialized safety equipment distributors and emerging direct-to-industrial digital platforms serving large contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The protective footwear market functions as a regulatory compounder where EU PPE Regulation 2016/425 and OSHA 29 CFR 1910.136 create mandatory replacement demand that compresses procurement cycles and elevates specification thresholds.
For Market Incumbents: Lock in notified body relationships and pre-certification capabilities to defend against Asian exporters relocating testing infrastructure to European conformity assessment bodies. Deepen backward integration into rubber processing to insulate margins from Southeast Asian latex price volatility. Prioritize R&D investment in metal-free composite materials where electrical hazard and airport security requirements expand addressable demand. For New Entrants and Emerging Players: Launch via direct-to-industrial digital platforms targeting India's construction acceleration and infrastructure investment wave. White-space opportunity concentrates in cold-weather insulated footwear for energy utilities extending winter maintenance windows, and in scan-to-fit customization programs for mining operators. Go-to-market angle should emphasize specification-driven purchasing committees with certified performance data over brand heritage. For Investors and Strategic Acquirers: Roll-up economics work for European mid-tier specialists with concentrated notified body relationships because CE marking conformity costs create capital barriers that favor scaled certification expertise. Long-term viability hinges on acquisition of manufacturers with closed-loop production capabilities aligned to EU ecodesign material recyclability rules. Signal to watch: acceleration of employer-mandated protective equipment upgrades under German industrial union collective bargaining agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Certification Investment | EU PPE Regulation 2016/425 compliance enables premium-tier market access for Category III safety boots. |
| Composite Material Manufacturing Scale-Up | Metal-free designs satisfy electrical hazard requirements from Texas energy utilities and Heathrow aviation crews. |
| Direct-to-Industrial Platform Launch | Bulk procurement portals disintermediate traditional safety distributors for large construction contractors. |
| Closed-Loop Production Integration | EU ecodesign recyclability rules favor manufacturers with transparent supply chains and chemical disclosure capabilities. |
| Scan-to-Fit Customization Partnership | 3D-printed midsole lattice structures modularize comfort customization for mining and heavy manufacturing operators. |
Study Parameters
Direct dialogue with safety managers at construction contractors, procurement leads at energy utilities, notified body certification specialists, plant engineers at manufacturing facilities, and distribution channel partners grounded the qualitative foundation. Secondary validation drew from OSHA enforcement data, EU PPE Regulation 2016/425 technical documentation, Bureau of Indian Standards certification records, customs trade databases, and SEC filings from publicly traded footwear manufacturers. Bottom-up segment sizing and top-down macroeconomic cross-checks triangulated market estimates.
Segment-level outputs across product construction, material chemistry, end-use environment, and application setting combined with regional regulatory cluster analysis across the analysis window. CAGRs derived from regression against industrial production indices, construction spending forecasts, and occupational safety mandate implementation timelines. Key inputs included German union collective bargaining agreement schedules and India's infrastructure investment acceleration patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained natural rubber price volatility or abrupt EU chemical substance restriction tightening. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Wedge Boots Market
Footwear
Breathable Mesh Running Shoes Market
Footwear
Cowgirl Boots Market
Footwear
Custom Shoes Market
Footwear
Winter Footwear Market
Footwear
Leather Sneakers Market
Footwear
Slip Resistant Shoes Market
Footwear
Platform Boots Market
Footwear
Casual Shoes Market
Footwear
Sandals Market
Footwear
Europe Athletic Footwear Market
Footwear
Self-Lacing Shoes Market
Footwear
Footwear Manufacturing Machinery Market
Footwear
Sports Shoes Market
Footwear
Sneaker Identification Service Market
Footwear
Cyber-Shoes Market