
 Women's Luxury Footwear Market | 2026-2036
Women's Luxury Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Women's Luxury Footwear Market Analytics
Buyer concentration among high-net-worth individuals is pivoting toward a broader base of aspirational millennials and Gen Z consumers entering through accessible luxury tiers. LVMH Moet Hennessy Louis Vuitton SE leverages its multi-brand architecture to capture spend across price tiers. Kering SA anchors its portfolio through direct-to-channel control and sustainability credentials. Chanel Limited differentiates via scarcity-driven distribution and vertical atelier networks.
Women's luxury footwear encompasses artisan-crafted shoes using full-grain leather, hand-stitched welting, and lasted construction methods designed for both aesthetic distinction and extended wear durability. Heels and boots command the largest share of current revenue pools, while sandals represent the fastest-expanding category in warm-climate markets. Leather dominates material value, though exotic skins concentrate margin in ultra-premium collections where supply constraints inflate pricing power.
REACH in Europe and EPA chemical regulations in the United States govern tanning agents, dyes, and finishing compounds, forcing reformulation of traditional processes. BIS standards in India and GB standards in China impose additional compliance layers for imported finished goods. Stakeholders must monitor regulatory divergence across sourcing hubs and retail destinations to preempt supply disruption and certification gaps.
Market Dynamics
Aspirational millennials and Gen Z consumers are compressing the traditional luxury entry barrier, forcing heritage houses to recalibrate tier architecture and material sourcing to capture spend across accessible and ultra-premium segments simultaneously.
Growth Catalysts
- REACH chemical reformulation mandates:European ECHA pressure on tanning agents and dyes accelerates bio-based alternative R&D, creating first-mover certification advantages for compliant suppliers.
- Tier-one city consumption clusters:Domestic luxury appetite in Shanghai, Beijing, and Shenzhen concentrates demand velocity for limited-edition drops and atelier-crafted collections.
- Hand-stitched welting revival:Artisan construction methods command price premiums as durability narratives displace fast-fashion footwear cycles among conscious aspirational buyers.
Market Restraints
- Exotic skin supply concentration:CITES-regulated python and crocodile sourcing funnels through a narrow base of certified tanneries in Italy and France, inflating input cost volatility.
- Full-grain leather price sensitivity:Premium hide costs track cattle commodity cycles and tanning chemical compliance expenses, squeezing margin at accessible luxury price points.
- Lasted construction skill scarcity:Master cordwainers capable of bespoke wooden last shaping concentrate in aging European ateliers, constraining production scale-up.
Strategic Opportunities
- India BIS standard alignment:Early certification to Bureau of Indian Standards for imported finished goods opens distribution in Mumbai and Delhi luxury corridors before competitor saturation.
- Warm-climate sandal white space:Underdeveloped artisan sandal collections for Dubai, Singapore, and Miami represent the fastest-expanding category with margin structures matching heels.
- Direct-to-channel control:Owned retail and digital flagship integration captures full customer data and margin that wholesale partnerships currently dilute.
Industry Challenges
- Atelier talent pipeline gaps:Multi-year apprenticeship requirements for hand-finishing and patina application clash with compressed product calendar demands.
- Dual certification timelines:Simultaneous REACH, EPA, and GB standard compliance for cross-border collections extends go-to-market lead times.
- Legacy ERP integration friction:Supply chain traceability requirements for ESG disclosure strain existing inventory management architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Women's Luxury Footwear Market |
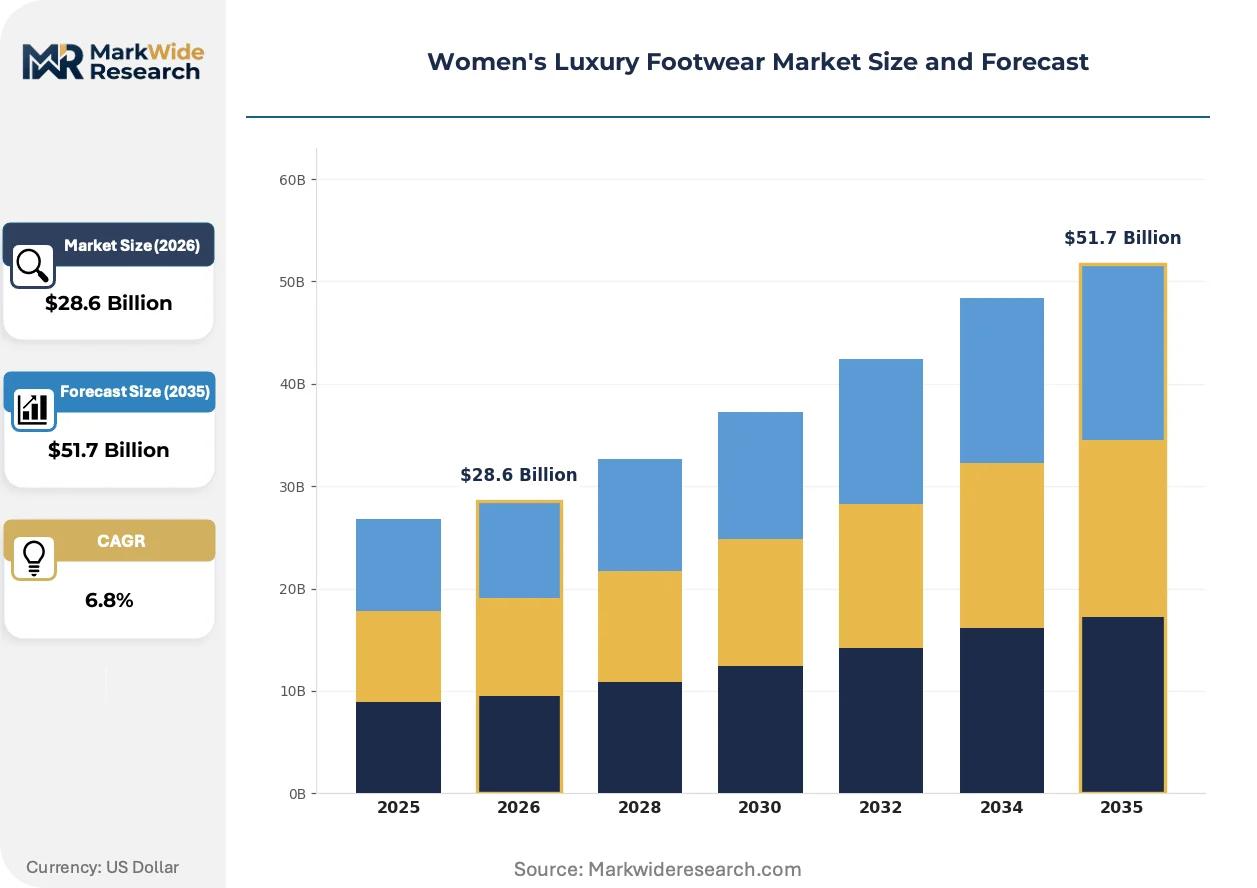
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sandals, Heels, Boots, Flats Material: Leather, Suede, Patent, Exotic Skins End User: Lifestyle, High Fashion, Occasion, Working Professionals Price Tier: Premium, Affordable Luxury, High-End, Entry Luxury |
| Companies Covered | Hermes International SA, Prada SpA, LVMH Moet Hennessy Louis Vuitton SE, Christian Louboutin, Jimmy Choo, Kering SA, Guccio Gucci SpA, Burberry Group plc, Chanel Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Women's Luxury Footwear Market Evolving Landscape
Bio-engineered materials and digital craftsmanship tools are compressing the traditional trade-off between artisan heritage and production scalability, while regulatory chemical bans force material science pivots across European and North American sourcing.
Mylo mycelium leather is integrating fungal-based textile alternatives into heel and boot uppers previously reserved for calf and exotic skins. Aspirational luxury buyers in Copenhagen and Amsterdam are adopting these materials at parity price points. This integration is compressing the stigma gap between sustainable alternatives and heritage materials in entry-luxury tier positioning.
EPA chemical standards for tanning effluents are tightening discharge limits on chromium and formaldehyde-based processes. US-based manufacturers face reformulation costs or offshore sourcing shifts to maintain finish quality. Small-batch atelier producers in Maine and Texas are most affected, responding with vegetable-tanning revival partnerships.
Digital atelier appointments are displacing traditional trunk show circuits as primary customer acquisition channels. Flagship stores in Milan and Paris now dedicate square footage to 3D foot scanning and virtual try-on infrastructure. This channel compression is most visible among Gen Z entrants in Seoul and Tokyo, where appointment-to-purchase conversion rates exceed legacy wholesale benchmarks.
Women's Luxury Footwear Market Segmentation
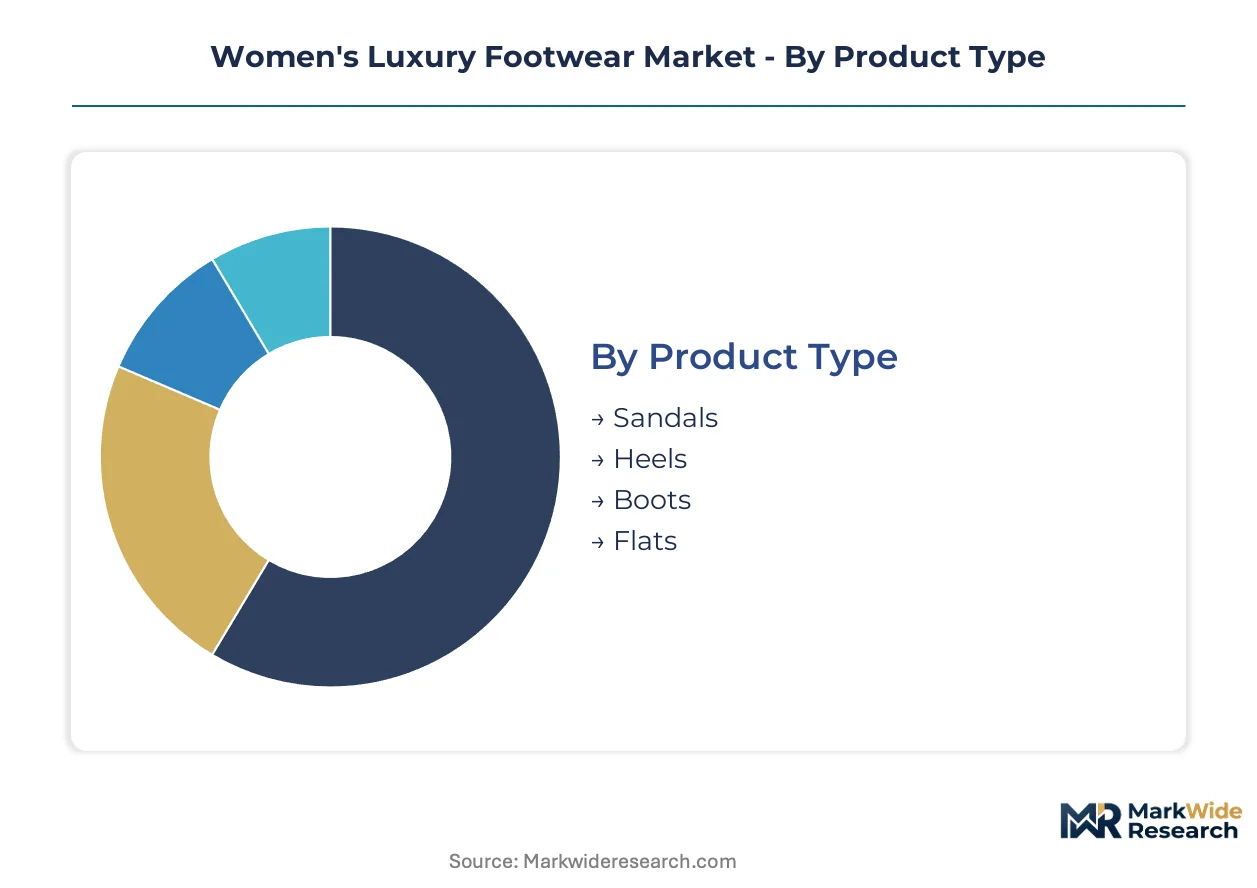
Segmentation in women's luxury footwear reveals how certification burdens, material sourcing constraints, and construction complexity fragment production economics across product architectures. Each dimension carries distinct margin profiles and regulatory exposure that reshape competitive positioning.
Product Type:
REACH chemical mandates and CITES wildlife trade certifications apply differentially across construction methods, with hand-finished welting triggering stricter ECHA documentation than cemented assembly.
- Heels:Stiletto and block-heel constructions utilizing steel shanks, leather-wrapped platforms, and lasted uppers dominate atelier output in Milan and Paris. Demand concentrates among occasion and working professional end users in Shanghai and Dubai, where vertical heel heights above 85mm command scarcity premiums.
- Boots:Ankle and knee-high silhouettes requiring extended pattern cutting, reinforced counters, and weather-resistant finishing. Construction complexity drives certification layering across REACH-compliant tanning and GB standard import documentation for Chinese domestic retail.
- Sandals:Open-toe architectures with minimal upper coverage and strap-based construction. Warm-climate markets in Miami and Singapore drive adoption, though simplified assembly reduces per-unit certification overhead relative to closed footwear.
- Flats:Ballerina and loafer profiles emphasizing all-day wearability through cushioned insoles and flexible outsoles. Entry-luxury positioning in accessible tiers attracts aspirational millennial buyers seeking heritage branding at reduced price points.
Leading the category by volume: Heels. Growing fastest: Sandals.
Material:
Raw material selection determines regulatory jurisdiction overlap, with exotic skins triggering multilateral CITES permits and REACH chemical testing simultaneously.
- Leather:Full-grain and top-grain bovine hides processed through chrome or vegetable tanning constitute the volume foundation. Italian tanneries in Tuscany and Veneto supply heritage houses, with ECHA reformulation mandates accelerating bio-based tanning agent R&D.
- Exotic Skins:Python, crocodile, and ostrich leathers regulated under CITES Appendix II trade restrictions. Supply funnels through certified French and Italian tanneries, inflating input costs and extending lead times for ultra-premium collections.
- Suede:Split-grain leather with napped surface finish requiring specialized tanning and dyeing protocols. Nubuck variants in neutral palettes anchor seasonal collections for lifestyle end users.
- Patent:High-gloss coated leather produced through resin or lacquer finishing. Formal occasion demand in Tokyo and Seoul sustains niche positioning despite plasticized aesthetic limitations.
Volume leader: Leather. Patent shows steepest expansion trajectory among occasion-focused subsegments.
End User:
Customer archetype segmentation aligns construction investment with wear-frequency economics, separating daily-use durability requirements from statement-piece craftsmanship.
- High Fashion:Runway-caliber silhouettes emphasizing avant-garde proportions, experimental materials, and limited production runs. Editorial visibility in Paris and Milan drives halo effects for accessible tier conversion.
- Lifestyle:Versatile daily-wear designs balancing comfort engineering with heritage branding. Copenhagen and Amsterdam aspirational buyers prioritize mycelium leather and traceable sourcing credentials.
- Occasion:Event-specific footwear for weddings, galas, and ceremonial functions. Satin, crystal embellishment, and metallic finishes concentrate margin in seasonal drops.
- Working Professionals:Boardroom-appropriate pumps and loafers emphasizing 8-hour wearability through arch support and heel stability. Tokyo and London financial district demand sustains replenishment cycles.
Category volume concentrates in Lifestyle. Occasion segment gains share fastest among Gen Z entrants.
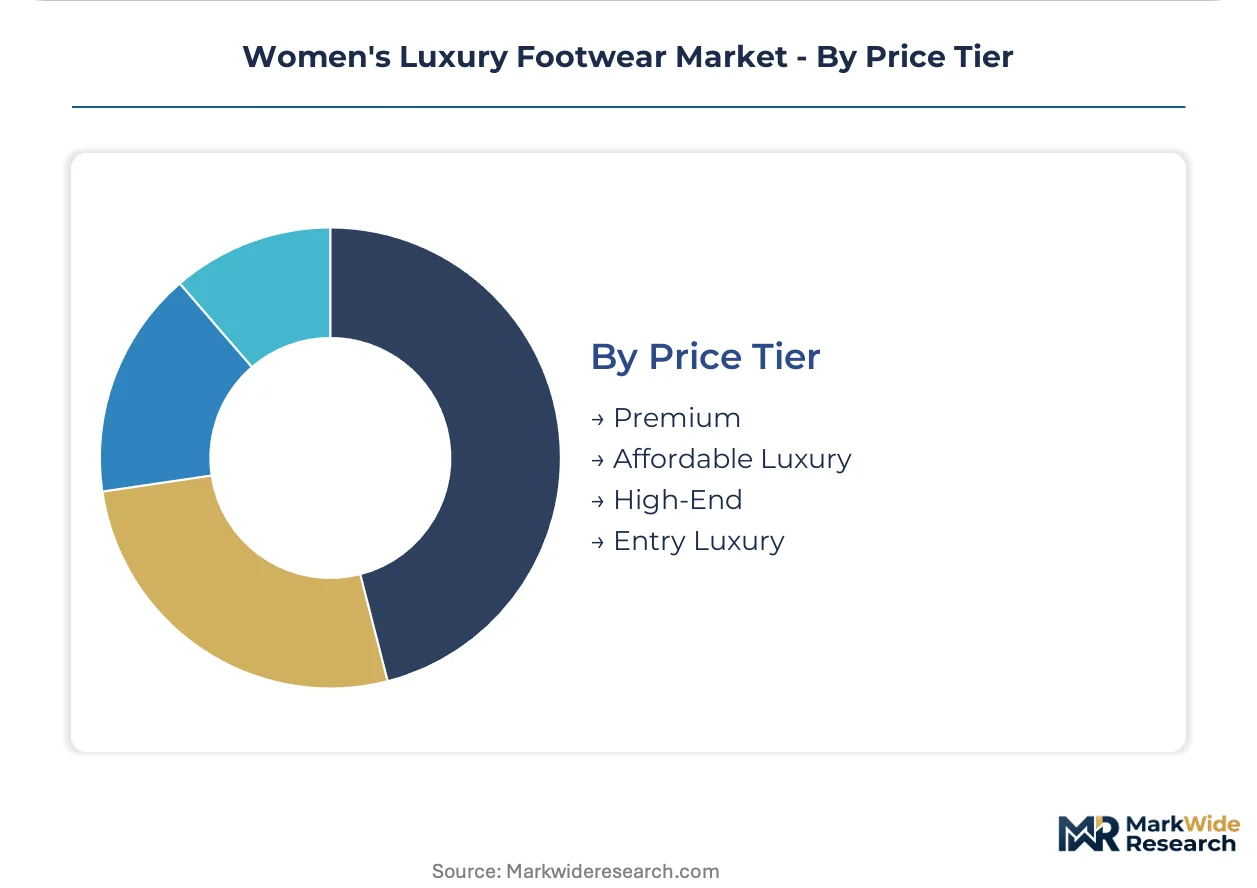
Price Tier:
Tier architecture reflects material grade, construction method, and distribution channel control, with direct-to-consumer penetration compressing traditional wholesale markups.
- Premium:Ultra-luxury positioning utilizing exotic skins, hand-painted patina, and bespoke last shaping. Master cordwainer labor scarcity in aging European ateliers constrains production scale.
- High-End:Full-grain leather constructions with Blake or Goodyear welting, limited distribution through owned retail. Direct channel capture in Milan and Paris flagships preserves margin integrity.
- Affordable Luxury:Quality leather uppers with cemented construction and accessible price architecture. Multi-brand retail partnerships in tier-one Chinese cities drive volume velocity.
- Entry Luxury:Diffusion lines and capsule collections introducing aspirational buyers to heritage branding. Digital flagship integration captures Gen Z acquisition at reduced customer acquisition cost.
Premium tier leads absolute margin contribution. Entry Luxury expands most quickly through digital channel penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates domestic luxury footwear demand through tier-one city clusters, while European ateliers anchor artisan production capacity. Regulatory divergence across REACH, EPA, and GB standards fragments certification requirements for cross-border collections.
China
Shanghai, Beijing, and Shenzhen drive velocity for limited-edition drops and atelier-crafted collections as domestic luxury appetite accelerates. GB standards impose compliance layers for imported finished goods entering Chinese retail channels. The Yangtze River Delta manufacturing corridor supplies component leathers to European heritage houses while domestic brands build direct-to-consumer flagships in Chengdu and Hangzhou.
France
Paris anchors ultra-premium positioning through scarcity-driven distribution and vertical atelier networks. ECHA REACH mandates govern tanning agents and finishing compounds, forcing reformulation of traditional chrome-based processes. The Île-de-France region concentrates master cordwainer talent for bespoke wooden last shaping, though aging demographics constrain apprenticeship pipeline expansion.
Italy
Milan and Florence sustain heel and boot production through Tuscan and Veneto tannery supply chains. REACH chemical reformulation accelerates bio-based tanning agent R&D among certified suppliers. The Lombardy industrial cluster integrates hand-stitched welting revival partnerships with vegetable-tanning cooperatives responding to EPA-aligned export requirements.
United States
New York and Los Angeles concentrate aspirational millennial and Gen Z entry-luxury acquisition through digital flagship integration. EPA chemical standards tighten discharge limits on chromium and formaldehyde-based tanning effluents. Small-batch atelier producers in Maine and Texas face reformulation costs or offshore sourcing shifts to maintain finish quality for domestic collections.
United Kingdom
London financial district demand sustains working professional replenishment cycles for boardroom-appropriate pumps and loafers. Post-Brexit regulatory divergence from REACH creates dual certification burdens for collections serving both UK and EU retail. British heritage houses leverage Savile Row adjacent craftsmanship narratives to differentiate in accessible luxury tiers.
Women's Luxury Footwear Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-engineered materials and digital craftsmanship integration. The vendor base concentrates among multi-brand luxury conglomerates and independent heritage houses with vertical atelier control. Three archetypes dominate: conglomerate portfolio players with tiered price architecture, independent houses with scarcity-driven distribution, and material science specialists commercializing mycelium alternatives. Competitive moves center on direct-to-channel expansion and sustainability certification acquisition.
Within the conglomerate tier, LVMH Moet Hennessy Louis Vuitton SE and Kering SA exemplify multi-brand architecture strategies capturing spend across accessible and ultra-premium segments simultaneously. Chanel Limited occupies a position defined by vertical atelier networks and controlled distribution scarcity. Among independent heritage houses, Christian Louboutin and Jimmy Choo represent specialist positioning anchored in signature silhouette recognition and occasion-focused collection architecture.
| Leading Market Players |
|---|
| Hermes International SA |
| Prada SpA |
| LVMH Moet Hennessy Louis Vuitton SE |
| Christian Louboutin |
| Jimmy Choo |
| Kering SA |
| Guccio Gucci SpA |
| Burberry Group plc |
| Chanel Limited |
| Others |
Value Network & Pricing Analysis
Hand-stitched welting revival across European ateliers simultaneously inflates labor cost structures and concentrates production capacity in aging Italian and French cordwainer networks, reshaping margin economics for heritage houses competing against cemented-construction accessible luxury tiers. This production-method bifurcation forces tiered pricing architectures that separate artisan-crafted scarcity premiums from volume-driven entry-luxury positioning.
Pricing Analysis
Volume-mass accessible luxury tiers compress margin through full-grain leather commodity cycles and multi-brand retail markup sharing, while ultra-premium exotic skin collections sustain pricing power via CITES-regulated supply scarcity. Price differentiation rests on construction method certification and direct-to-channel control intensity. Pricing pressure intensifies in entry-luxury segments as aspirational millennial buyers trade down amid full-grain hide cost volatility. Working professionals in tier-one cities show highest price sensitivity; ultra-high-net-worth collectors demonstrate inelastic demand for bespoke atelier output.
Supply Chain Analysis
Master cordwainer scarcity in Milan, Paris, and Florence constrains production scale-up for hand-lasted constructions, tethering artisan output to aging European talent pools. Raw material flows draw from Tuscan and Veneto tanneries for bovine hides, French certified facilities for CITES-regulated exotic skins, and Yangtze River Delta component suppliers for hardware and linings. Supply chain risk centers on single-source vulnerability for python and crocodile sourcing through narrow Italian and French tannery bases. Distribution runs through owned flagship integration in tier-one cities, displacing wholesale dependency for margin capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bio-engineered mycelium leather is displacing heritage calf and exotic skin positioning in aspirational tiers, compressing the technology-transition window for incumbent material science investments and new entrant white-space entry.
For Market Incumbents: Hedge against bio-based material displacement by securing captive supply partnerships with mycelium cultivators in Denmark and the Netherlands before competitor lock-in. Deepen backward integration into vegetable-tanning cooperatives responding to EPA-aligned export requirements. Channel control intensification through digital flagship expansion in Chengdu and Hangzhou reduces customer acquisition cost erosion from wholesale markup sharing. For New Entrants and Emerging Players: Aspirational Gen Z buyers in warm-climate corridors represent the most penetrable archetype for sandal-focused artisan positioning with margin structures matching traditional heel categories. White-space concentration in Dubai, Singapore, and Miami permits category creation without incumbent saturation. Go-to-market execution through appointment-based digital atelier infrastructure in Seoul and Tokyo bypasses capital-intensive flagship buildout. For Investors and Strategic Acquirers: Exit pathways concentrate in material science specialists with commercialized mycelium scale and ESG certification moats. Long-term viability across the analysis window favors targets with dual REACH and GB standard compliance already operationalized. The inflection signal to watch is CITES regulatory tightening on python and crocodile trade permits, which would accelerate bio-alternative valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Mycelium Leather Integration | Bio-engineered alternatives from Bolt Threads and Ecovative capture aspirational buyers in Copenhagen and Amsterdam at parity pricing. |
| Direct-to-Channel Flagship Expansion | Owned retail in Chengdu and Hangzhou captures full customer data and margin that wholesale partnerships currently dilute. |
| REACH-GB Dual Certification Investment | Early compliance to ECHA and Chinese standards preempts supply disruption for cross-border collections. |
| Master Cordwainer Apprentice Pipeline | Multi-year training programs in Île-de-France and Lombardy address atelier talent scarcity constraining production scale. |
| Warm-Climate Sandal Collection Launch | Underdeveloped artisan positioning in Dubai and Miami represents fastest-expanding category with margin structures matching heels. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across heritage house atelier directors, multi-brand luxury retail buyers, tannery procurement leads, and sustainability certification officers. Secondary validation drew from ECHA REACH documentation, CITES trade permit databases, Bureau of Indian Standards filings, and tier-one city customs import records. Bottom-up unit economics triangulated against top-down category spend estimates to reconcile volume and value outputs.
Granularity-level modeling operated at product type, material grade, construction method, price tier, and end-user archetype dimensions across the projection horizon. CAGRs derived from segment-level growth rate assumptions weighted by revenue contribution and regulatory exposure intensity. Forecast inputs incorporated REACH chemical reformulation timelines, GB standard implementation phases, and aspirational buyer cohort penetration curves without year-specific anchoring.
Revisions become necessary when CITES regulatory tightening, REACH chemical ban acceleration, or master cordwainer talent pipeline collapse materialize beyond baseline assumptions. Forecasts reflect documented assumptions on regulatory implementation velocity and substitution elasticity for bio-engineered materials. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Flip Flops Market
Footwear
Europe Barefoot Shoes Market
Footwear
White Sneakers Market
Footwear
Driving Footwear Market
Footwear
Cyber-Shoes Market
Footwear
Sandals Market
Footwear
Trail Running Shoes Market
Footwear
Sports Shoes Market
Footwear
UK Lifestyle Sneakers Market
Footwear
Leather Footwear Market
Footwear
Duck Boots Market
Footwear
Sneaker Identification Service Market
Footwear
Orthopedic Footwear Market
Footwear
Platform Boots Market
Footwear
Winter Footwear Market
Footwear
Casual Shoes Market