
 Leather Footwear Market | 2026-2036
Leather Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Leather Footwear Market Outlook
Multi-source leather procurement is realigning how major brands manage tannery relationships and finished-goods assembly. Nike leverages its direct supplier engagement programs to trace hide origins across multiple continents. ECCO Sko A/S anchors its competitive position through in-house tanning facilities and vertically controlled production in the Netherlands and Asia. Wolverine World Wide Inc. competes by sustaining heritage brand portfolios that command premium positioning in North American work-boot segments.
Leather footwear comprises shoes, boots, and sandals constructed from tanned animal hides, typically cattle, sheep, or goat skin processed through chrome or vegetable tanning to achieve durability, breathability, and aesthetic grain patterns; the material's tensile strength and moisture-wicking properties make it suitable for protective work applications, formal occasions, and performance sports. The men's end-user segment retains the largest volume share, though the women's category is generating faster value growth as professional and luxury casual lines expand. Boots dominate cold-climate and occupational demand, while loafers and Oxfords concentrate margin pools in formal channels where full-grain construction commands sustained price premiums.
REACH in Europe restricts chromium VI and certain azo dyes in leather processing, pushing tanneries toward vegetable and synthetic alternatives that alter cost structures and supplier qualification timelines. The EPA in the United States monitors wastewater discharge from tanning operations, affecting where concentration facilities locate and which hides enter domestic supply chains. ISO 17072 standards for leather chemical testing shape export eligibility for manufacturers serving multiple jurisdictions. Stakeholders must monitor how evolving biodegradability requirements and traceability mandates reshape material sourcing decisions and factory certification investments.
Market Dynamics
REACH compliance in Europe is forcing tanneries to abandon chrome tanning for vegetable and synthetic alternatives, compressing margins and extending supplier qualification timelines across the value chain.
Growth Catalysts
- Professional women's footwear expansion:Luxury fashion houses are building dedicated leather collections targeting women in corporate and creative industries, creating new SKU density in premium channels.
- Artisan cluster concentration:Manufacturing gravity is concentrating in Italy's Florence and Milan corridors, where skilled labor pools and heritage tooling sustain small-batch premium output.
- Traceability mandates:ISO 17072 standards for leather chemical testing are becoming export prerequisites, pushing integrated tanneries to capture market share from non-compliant competitors.
Market Restraints
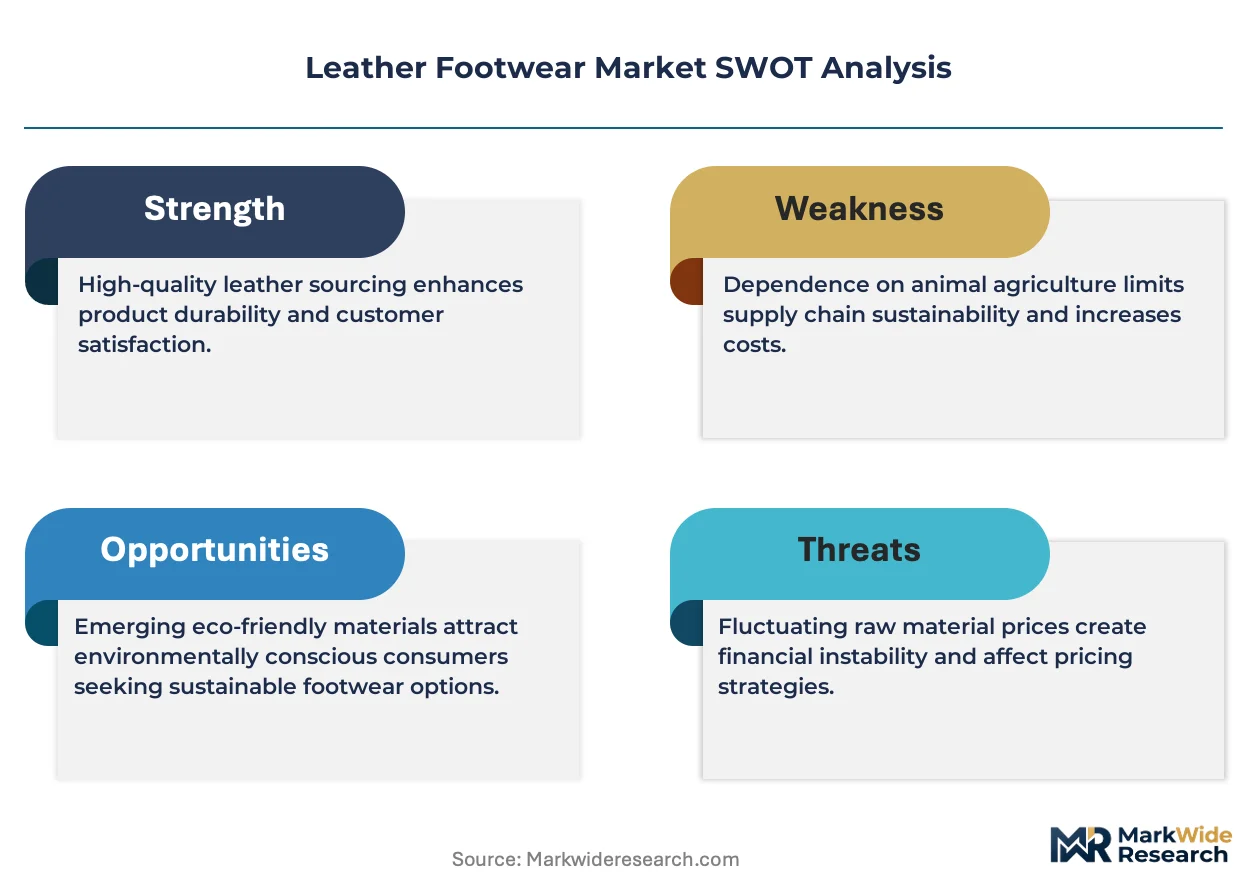
- Raw material cost volatility:Cattle hide prices fluctuate with meat consumption cycles and drought patterns in Brazil and Australia, squeezing tannery margins unpredictably.
- Supplier concentration risk:Chrome tanning chemical production concentrates in China and India, exposing European and North American tanneries to supply disruption and tariff exposure.
- Biodegradable substitute threat:Mycelium-based leather alternatives from biotechnology startups are capturing pilot orders from fashion brands seeking carbon-neutral positioning.
Strategic Opportunities
- Underpenetrated occupational segments:Healthcare and hospitality sectors in Germany and France still rely on synthetic safety footwear, presenting conversion potential for breathable full-grain leather designs.
- Direct-to-consumer channel expansion:Made-to-measure digital platforms are collapsing traditional wholesale markups, enabling artisan producers to capture full retail value.
- EU Green Deal alignment:Circular economy action plan incentives for biodegradable materials and carbon footprint labeling are creating first-mover advantages for vegetable-tanned product lines.
Industry Challenges
- Master craftsperson scarcity:Hand-lasting and hand-welting skills are disappearing as aging Italian and Portuguese artisans retire without trained successors.
- Multi-jurisdiction certification complexity:Simultaneous compliance with REACH, EPA wastewater rules, and California Proposition 65 extends product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leather Footwear Market |
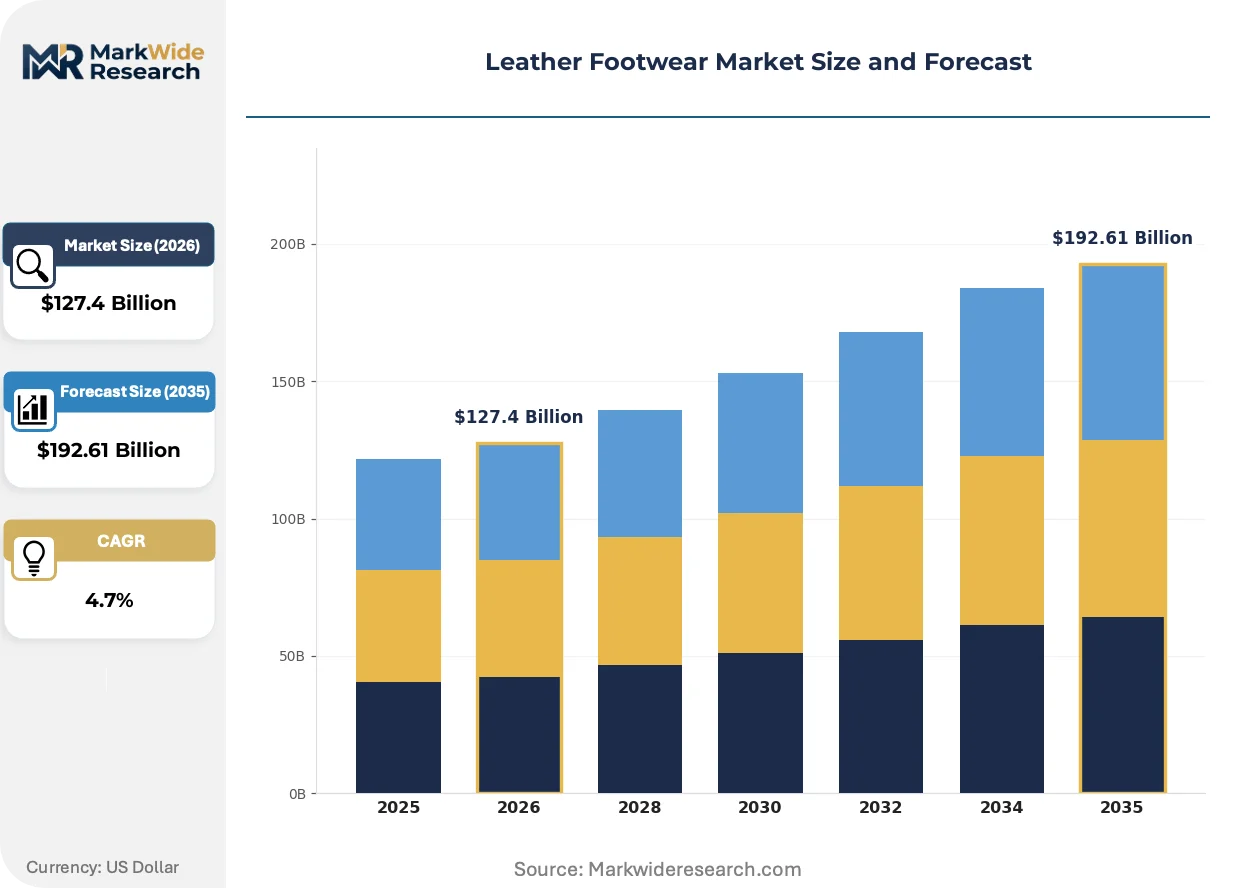
| Market Size in 2026 | $127.4 Billion |
| Market Size in 2035 | $192.61 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boots, Sandals, Loafers, Oxfords End User: Men, Women, Children, Unisex Application: Casual, Formal, Sports, Outdoor Distribution Channel: Online, Retail Stores, Supermarkets, Specialty Shops |
| Companies Covered | ASICS Corporation, Wolverine World Wide Inc., Nike Inc., ECCO Sko A/S, Caleres, adidas AG, Deckers Brands, Geox S.p.A, Puma SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leather Footwear Market Strategic Shifts
Digital traceability infrastructure and bio-based material science are converging to redefine how leather footwear is sourced, certified, and sold across price tiers.
Laser engraving technology is converging with blockchain-based provenance tracking to create immutable hide-to-shoe documentation. Premium brands in Italy and France are adopting these combined systems to satisfy retailer and consumer transparency demands. This convergence is compressing the competitive window for suppliers lacking capital to deploy dual-layer verification infrastructure.
REACH restrictions on chromium VI and azo dyes are forcing tanneries to reformulate wet-blue processing or exit European supply chains entirely. The industrial consequence is a bifurcation between compliant vegetable-tan specialists and non-compliant exporters redirecting volume to Middle Eastern and African markets. Formal footwear segments in Germany and the Netherlands are absorbing the steepest cost pass-throughs as brands prioritize certification maintenance over margin protection.
Corporate buyers are consolidating vendor relationships around single-source accountability for ESG compliance. Multi-brand retail groups in France and the United Kingdom are replacing fragmented supplier panels with integrated partners who control tanning through finished-goods assembly. This concentration is most visible in professional uniform contracts, where procurement teams now require full supply chain disclosure as a mandatory bid qualification.
Leather Footwear Market Segmentation
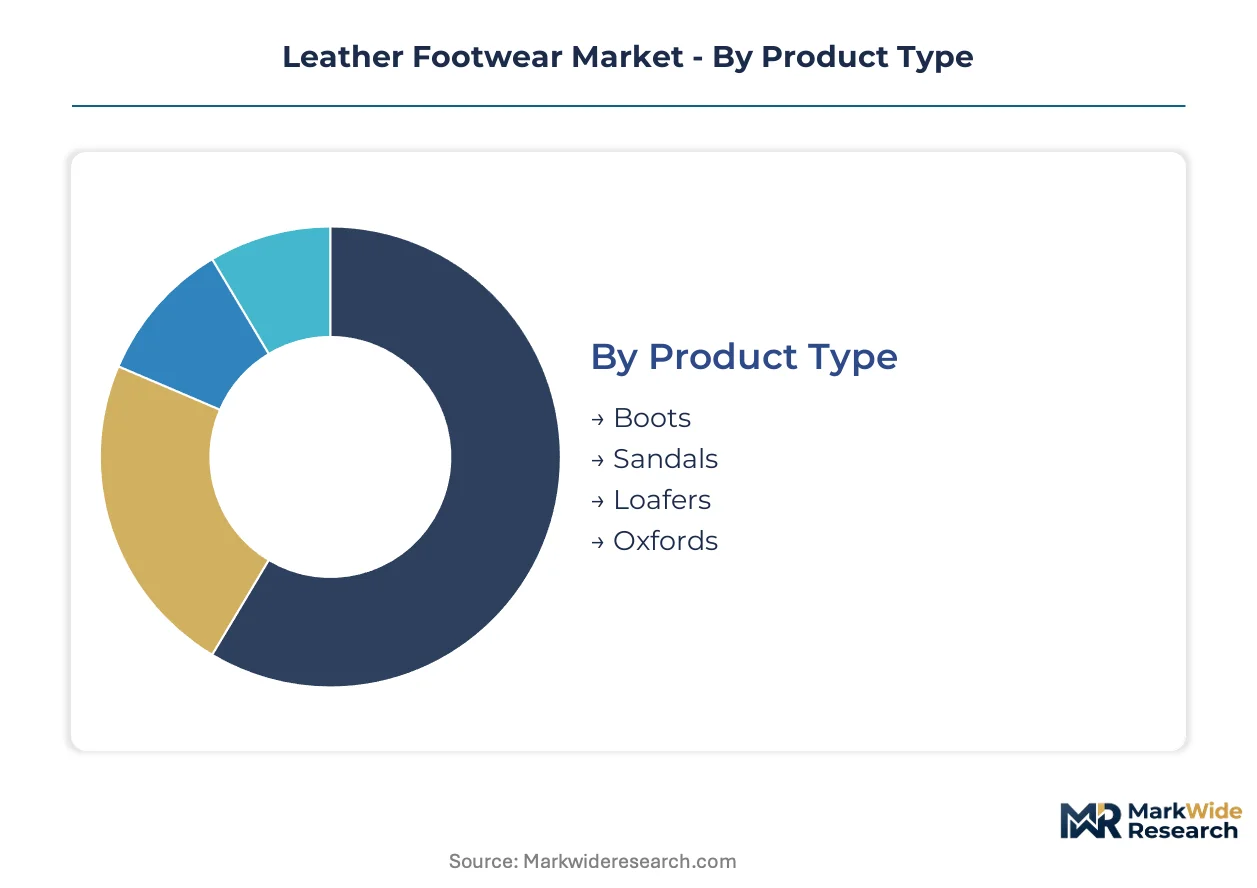
Leather footwear segmentation reveals how certification requirements, material specifications, and channel economics split demand across distinct buyer profiles. Understanding these divides exposes where REACH compliance costs concentrate and where vegetable-tan premiums command pricing power.
Product Type:
REACH chemical restrictions and ISO 17072 testing protocols apply unevenly across construction formats, with formal styles facing the steepest compliance burdens.
- Boots:Heavy-gauge full-grain construction dominates cold-climate occupational demand in Germany and France. Safety-toe specifications for industrial buyers trigger mandatory CE marking and steel-cap testing protocols that extend factory certification timelines.
- Loafers:Slip-on construction concentrates margin pools in Italian premium channels where hand-lasted moccasin techniques justify price premiums. Florence artisans command waiting lists for unlined vegetable-tan specimens that satisfy corporate dress codes.
- Sandals:Open construction reduces material intensity but exposes stitch lines to accelerated wear testing under ISO standards.
- Oxfords:Closed-lace formal specification requires flawless grain selection and welted construction that skilled Portuguese workshops struggle to scale.
Boots sit at the top of the volume ranking, with loafers climbing the fastest as professional women expand work-appropriate casual wardrobes.
End User:
Gender-based purchasing patterns split sharply between volume-driven replacement cycles and value-driven wardrobe investment behaviors.
- Men:Conservative replacement schedules concentrate volume in durable work-boot and formal-occasion segments. German and British buyers prioritize resoleable construction that extends product lifecycles beyond synthetic alternatives.
- Women:Professional and luxury casual lines generate faster value growth as fashion houses build dedicated corporate collections. Milan design studios now staff women-specific lasts that address anatomical fit differences ignored by unisex lasts.
- Children:Rapid size turnover limits material investment, with parents prioritizing adjustable closures and growth-accommodating designs over leather grade.
- Unisex:Sneaker-influenced silhouettes appeal to younger demographics seeking gender-neutral styling that collapses traditional retail floor segmentation.
Men retain the largest volume position, though women are expanding most quickly as luxury houses target professional wardrobes.
Application:
Use-case requirements determine tanning chemistry selection, with formal and sports applications imposing the strictest material performance standards.
- Formal:Full-grain box calf and cordovan dominate boardroom and ceremonial demand in London and Paris financial districts. Chrome-tanned finishes remain preferred for mirror shine maintenance despite REACH pressure on chromium VI.
- Casual:Relaxed construction tolerates softer vegetable-tanned suedes and nubucks that biodegrade more readily under EU Green Deal criteria.
- Sports:Performance requirements for moisture management and flex resistance drive specialized tanning treatments that few Italian tanneries can certify.
- Outdoor:Waterproof membrane integration and aggressive lug outsoles compete with synthetic hiking boots on weight and break-in speed.
Formal applications command the steepest pricing tiers, with casual segments gaining share fastest as remote work dilutes dress code enforcement.
Distribution Channel:
Channel economics determine how traceability costs and artisan premiums flow to end buyers, with direct platforms collapsing traditional wholesale markups.
- Online:Made-to-measure digital platforms enable Portuguese and Italian artisans to capture full retail value without showroom overhead. Blockchain provenance verification justifies price transparency that wholesale channels obscure.
- Retail Stores:Multi-brand groups in France and the United Kingdom now mandate full supply chain disclosure as a mandatory bid qualification, consolidating vendor relationships around integrated partners.
- Specialty Shops:Narrow assortments and trained fitting staff sustain premium positioning for bespoke and small-batch production.
- Supermarkets:Volume-driven private-label programs prioritize cost engineering over material provenance, sourcing predominantly from non-European tanneries.
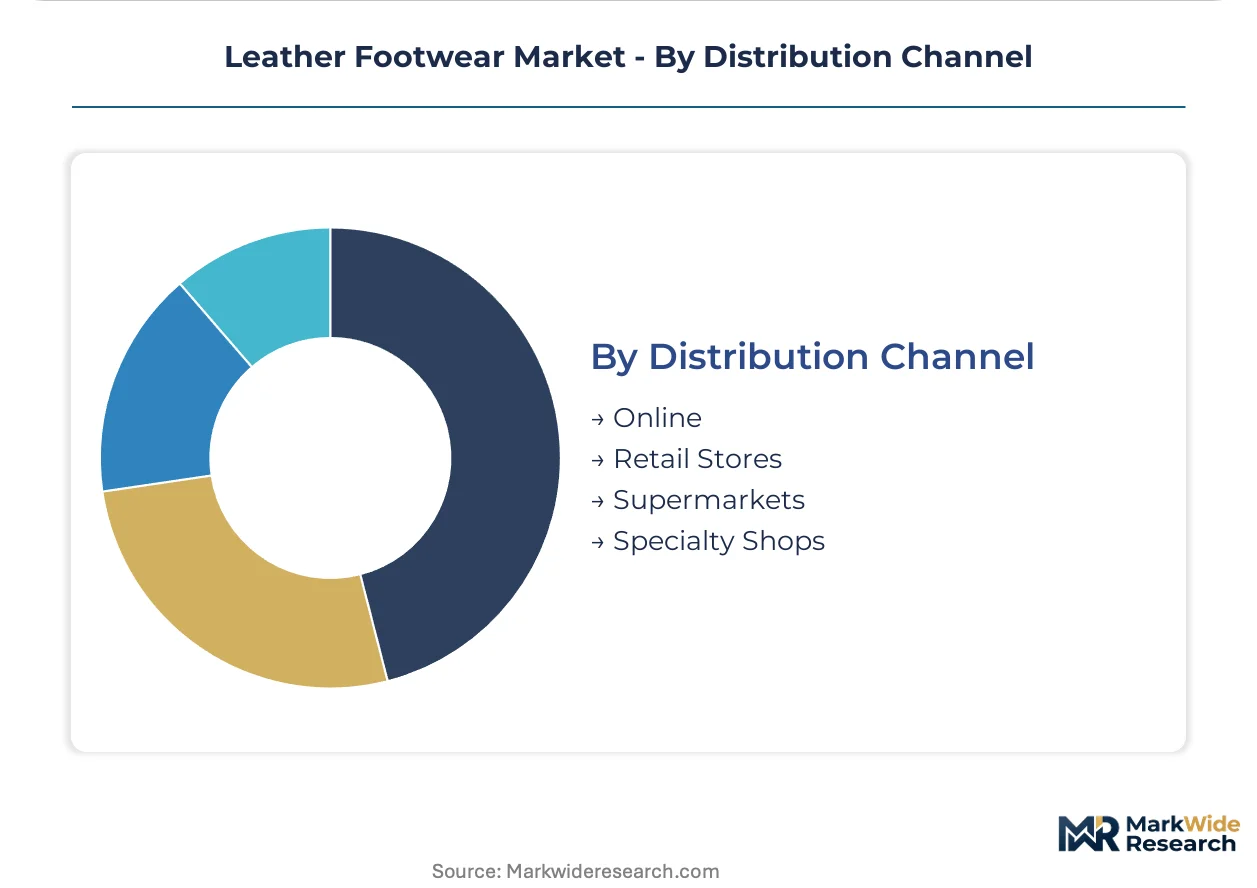
Retail stores still handle the largest volume flows, with online channels expanding most quickly as direct-to-consumer infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where leather footwear production concentrates, as REACH compliance costs in Europe push non-compliant tanneries toward Middle Eastern and African markets while compliant vegetable-tan specialists capture premium positioning in Germany and France.
Italy
Artisan manufacturing clusters in Florence and Milan sustain small-batch premium output for luxury fashion houses targeting professional women. REACH restrictions on chromium VI have accelerated vegetable-tan adoption among Tuscan tanneries, with Florence workshops commanding waiting lists for unlined formal specimens that satisfy corporate dress codes.
Germany
Industrial safety-boot demand and formal boardroom footwear in Frankfurt and Munich financial districts drive full-grain consumption. The country's national environmental regulator enforces strict wastewater discharge standards that compress margins for chrome-tan operations, pushing procurement teams toward integrated suppliers controlling tanning through finished-goods assembly.
United States
Heritage work-boot segments and conservative replacement cycles concentrate volume in durable occupational categories. EPA monitoring of tanning facility discharge affects where concentration facilities locate, with Wolverine World Wide Inc. sustaining premium positioning in North American markets through heritage brand portfolios.
China
Chrome tanning chemical production concentrates supply-side exposure for European and North American tanneries, with the country's national standards administration governing industrial chemical output. Guangdong and Zhejiang manufacturing bases serve both domestic consumption and export markets, though traceability mandates are compressing competitive windows for suppliers lacking verification infrastructure.
Brazil
Cattle hide supply fluctuates with meat consumption cycles and drought patterns, squeezing tannery margins unpredictably. São Paulo and Rio Grande do Sul host processing facilities that redirect non-European compliant volume toward Middle Eastern and African markets as REACH qualification timelines extend.
Leather Footwear Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue bio-based material alternatives and direct-to-consumer channel expansion. The vendor base organizes around three archetypes: integrated tannery-manufacturers controlling hide-to-shoe workflows, heritage brand stewards leveraging portfolio diversification across price tiers, and athletic specialists applying performance material science to casual leather categories. Dominant competitive moves include backward integration into captive tanning capacity and strategic partnerships with biotechnology startups developing mycelium substitutes.
Among integrated specialists, ECCO Sko A/S and Wolverine World Wide Inc. exemplify divergent scale strategies. The Danish entity anchors its position through in-house tanning facilities and vertically controlled production networks, while the Michigan-based portfolio company sustains heritage brand equity across multiple North American work-boot lines. Nike Inc. occupies a distinct tier as an athletic specialist tracing hide origins through direct supplier engagement programs across multiple continents.
| Leading Market Players |
|---|
| ASICS Corporation |
| Wolverine World Wide Inc. |
| Nike Inc. |
| ECCO Sko A/S |
| Caleres |
| adidas AG |
| Deckers Brands |
| Geox S.p.A |
| Puma SE |
| Others |
Value Chain & Pricing Dynamics
Captive tanning capacity in the Netherlands and Denmark anchors both supply security and pricing power for integrated European manufacturers. ECCO Sko A/S controls wet-blue processing through finished-goods assembly, insulating margin pools from raw hide volatility that fragments non-integrated competitors.
Pricing Analysis
Retailer markup compression in multi-brand channels is intensifying as procurement teams consolidate vendor panels around integrated partners. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and traceability depth, with ISO 17072-compliant vegetable-tan specimens commanding sustained premiums. Price erosion runs through supermarket private-label tiers sourcing from non-European tanneries. Industrial safety-boot buyers in Germany exhibit lowest price sensitivity, prioritizing CE marking and resoleable construction over unit cost.
Supply Chain Analysis
REACH compliance in Europe is reshaping sourcing toward vegetable-tan specialists in Italy and Portugal while redirecting chrome-tan volume to Middle Eastern markets. Raw material flows draw from cattle hide suppliers in Brazil and Australia, with chemical inputs for chrome tanning concentrated in China and India. Single-source vulnerability in chromium VI chemical production exposes European tanneries to tariff exposure and supply disruption. Distribution runs through integrated tannery-manufacturers controlling hide-to-shoe workflows for corporate uniform contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory value as REACH chemical restrictions and EU Green Deal circular economy incentives reshape procurement priorities. ECHA enforcement timelines drive demand concentration toward compliant vegetable-tan specialists.
For Market Incumbents: To counter mycelium-based leather alternatives from biotechnology startups, secure captive tanning capacity in Italy or Portugal and accelerate blockchain provenance verification deployment. Certification investment in ISO 17072 testing infrastructure captures market share from non-compliant exporters exiting European supply chains. For New Entrants and Emerging Players: EU Green Deal alignment in Germany and France opens a window for biodegradable vegetable-tan product lines targeting corporate professional uniform contracts. Healthcare and hospitality safety footwear in German industrial zones presents the most penetrable conversion opportunity from synthetic alternatives. Direct-to-consumer made-to-measure digital platforms collapse wholesale markups and enable full retail value capture. For Investors and Strategic Acquirers: Roll-up economics work for integrated tannery-manufacturers because master craftsperson scarcity in Florence and Milan corridors creates irreplaceable asset value. Long-term viability hinges on circular economy credentialing and carbon footprint labeling compliance. Watch for mycelium leather pilot orders scaling to commercial volume as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Tanning | ECCO's Netherlands facilities demonstrate margin insulation from raw hide cost volatility. |
| Blockchain Provenance Deployment | Laser engraving convergence with immutable documentation satisfies French retailer transparency mandates. |
| Vegetable-Tan Product Line Expansion | Florence workshops command waiting lists for REACH-compliant corporate dress code specimens. |
| Direct-to-Consumer Platform Launch | Portuguese artisans capture full retail value without showroom overhead through made-to-measure digital channels. |
| Mycelium Material R&D Partnership | Biotechnology startup alliances position first-movers for carbon-neutral positioning under EU Green Deal criteria. |
Study Parameters
Bottom-up end-user modeling reconciled against top-down tannery capacity tracking forms the analytical core of this study. Primary interviews with Italian artisan workshop owners, German industrial safety-boot procurement managers, French multi-brand retail category buyers, and Portuguese tannery technical directors combined with secondary validation from ECHA regulatory filings, Italian leather association production statistics, customs trade data, and ISO certification databases. Supply-side triangulation against hide-to-shoe workflow documentation verified demand estimates.
Input-output matrices mapped tanning chemistry selection to finished-goods pricing tiers across product type, end-user gender, application use-case, and distribution channel dimensions. CAGRs were derived from segment-level volume trajectories and value-per-unit trends across the projection horizon. Forecast inputs incorporated REACH compliance cost pass-through rates and artisan labor pool retirement timelines.
Revisions become necessary when ECHA enforcement intensity shifts, mycelium leather achieves cost parity, or Brazilian drought patterns disrupt hide supply. Forecasts reflect documented assumptions on certification adoption curves and circular economy incentive durability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Tactical Footwear Market
Footwear
Tennis Shoes Market
Footwear
Casual Shoes Market
Footwear
Chunky Sneaker Market
Footwear
Refurbished Running Shoes Market
Footwear
Trail Running Shoes Market
Footwear
Snow Boots for Women Market
Footwear
Lace Up Boots Market
Footwear
Duck Boots Market
Footwear
Second Hand Designer Shoes Market
Footwear
Ankle Boots Market
Footwear
Men Formal Shoe Market
Footwear
Asia-Pacific Athletic Footwear Market
Footwear
Refurbished Sneaker Market
Footwear
Athletic Footwear Market
Footwear
Global Espadrille Flats Market