
 Leather Sneakers Market | 2026-2036
Leather Sneakers Market Size, Share, and Industry Trends Forecast 2026-2036
Leather Sneakers Market Foresight
Digital-first customization platforms is reconfiguring how leather sneakers move from design to delivery, collapsing traditional seasonal cycles into on-demand production workflows. Nike, Inc. leverages proprietary flyleather blends to reduce material waste while maintaining tensile performance. Adidas AG anchors its European supply base with automated cutting systems that trim pattern inefficiencies. Puma SE competes through modular construction techniques that accelerate style-to-shelf timelines.
Leather sneakers are footwear constructed from tanned animal hides or engineered leather substrates, typically featuring rubber outsoles and reinforced stitching for daily wear durability; the upper material must achieve minimum tensile strength thresholds to qualify for premium grading. Low-Top designs dominate volume across casual and commuter applications where versatility drives repeat purchase. High-Top constructions command margin concentration in streetwear and limited-release channels where scarcity mechanics inflate per-unit economics. The Unisex end-user segment expands fastest as gender-neutral sizing and neutral color palettes attract younger demographics across direct-to-consumer platforms.
REACH and RoHS frameworks in the European Union restrict chromium VI and restricted substance lists in leather tanning inputs, forcing reformulation of chemical finishing processes. The U.S. EPA and California's Proposition 65 impose parallel disclosure burdens on brands distributing across American wholesale and retail channels. Stakeholders must monitor evolving biomaterial certification standards and traceability mandates that will determine which suppliers retain shelf access in regulated markets.
Market Dynamics
On-demand manufacturing platforms are collapsing traditional seasonal production cycles, forcing tanneries and assembly plants to retool for micro-batch workflows rather than volume forecasting.
Growth Catalysts
- REACH chemical disclosure mandates:European Union reformulation requirements for chromium-free tanning are accelerating investment in vegetable-tanning infrastructure across Italian industrial districts.
- Professional-casual workplace dress codes:Hybrid office policies in the United States and United Kingdom are expanding daily-wear leather sneaker adoption beyond weekend use into five-day rotation patterns.
- Biomaterial substrate innovation:Engineered mycelium and pineapple leaf fiber alternatives are opening premium positioning for brands seeking differentiation from conventional bovine leather sourcing.
Market Restraints
- Raw hide supply concentration:Premium full-grain leather availability tightens as Brazilian and Argentinian cattle ranching faces climate volatility and pasture conversion pressures.
- Chrome tanning regulatory friction:California's Proposition 65 litigation exposure limits wholesale distribution options for brands dependent on chromium VI finishing processes.
- Performance textile substitution:Knitted synthetic uppers from running and basketball categories are capturing commuter segments previously loyal to leather constructions.
Strategic Opportunities
- Indian domestic market underpenetration:Organized retail expansion in Mumbai and Bangalore creates shelf space for mid-premium leather sneaker lines previously unavailable outside export channels.
- EU Green Deal circularity incentives:Take-back and refurbishment program subsidies in Germany and France enable resale platform partnerships that extend product lifecycle revenue.
- AI-driven size-matching convergence:3D foot-scanning integration with direct-to-consumer platforms is collapsing return rates and enabling made-to-order margin structures.
Industry Challenges
- Artisan pattern-making skill scarcity:Vietnamese and Portuguese manufacturing clusters face recruitment gaps for hand-cutting specialists capable of luxury-grade consistency.
- Multi-certification timeline compression:Simultaneous pursuit of LWG (Leather Working Group) audit grades and B Corp status strains compliance bandwidth at mid-scale brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leather Sneakers Market |
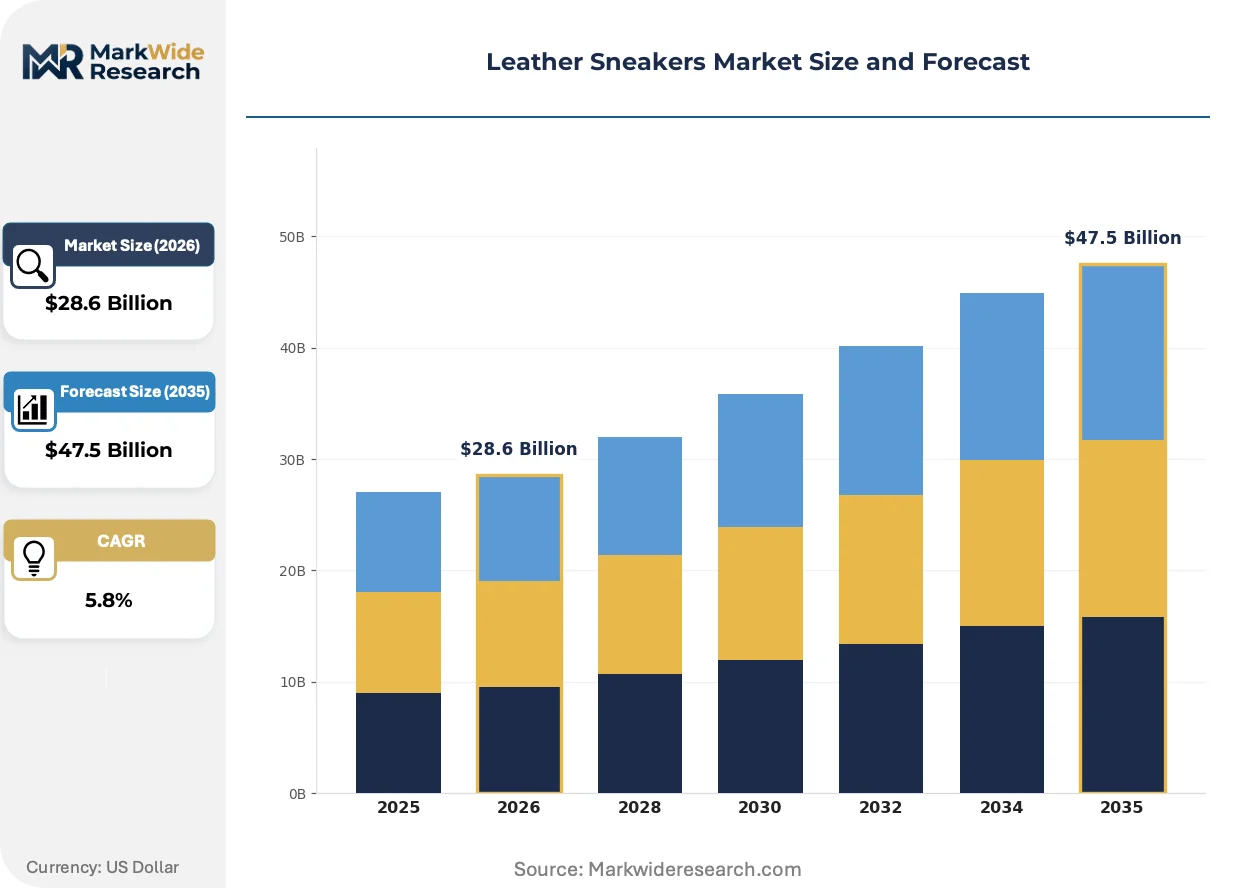
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Top, High-Top, Slip-On, Athletic End User: Men, Women, Children, Unisex Distribution Channel: Online, Specialty Stores, Department Stores, Supermarkets Price Tier: Premium, Mid-Range, Budget, Discount |
| Companies Covered | Nike, Inc., Adidas AG, Puma SE, New Balance Athletics, Inc., Gucci, Golden Goose, Veja, Common Projects, Axel Arigato, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leather Sneakers Market Shifts & Advancements
Digital production workflows are dismantling the traditional calendar-driven model, compressing design-to-shelf timelines from months to weeks while fragmenting demand signals into actionable micro-trends.
Blockchain-enabled hide traceability is collapsing opacity in multi-tier leather supply chains. Italian tanneries in Tuscany and Veneto are deploying distributed ledger systems to document farm-to-finish provenance for European luxury houses. The technology is collapsing the information asymmetry that previously allowed mixing grades across batches, forcing upstream consolidation around verified sourcing cooperatives.
REACH Annex XVII restrictions on chromium VI compounds are tightening enforcement across EU member states. The European Chemicals Agency is expanding testing protocols for imported leather components, forcing Asian suppliers to accelerate vegetable-tanning capacity buildouts. German and Dutch distribution hubs are now rejecting shipments lacking SCIP database registration, shifting compliance costs to export-oriented manufacturers.
Direct-to-consumer subscription models are displacing seasonal wholesale purchasing among younger demographics. Digital-native brands are offering quarterly curation services that replace traditional retail discovery, compressing the replacement cycle from annual to quarterly frequency. This pattern concentrates in United Kingdom and United States urban markets where closet rotation apps normalize continuous acquisition over durable investment.
Leather Sneakers Market Segmentation
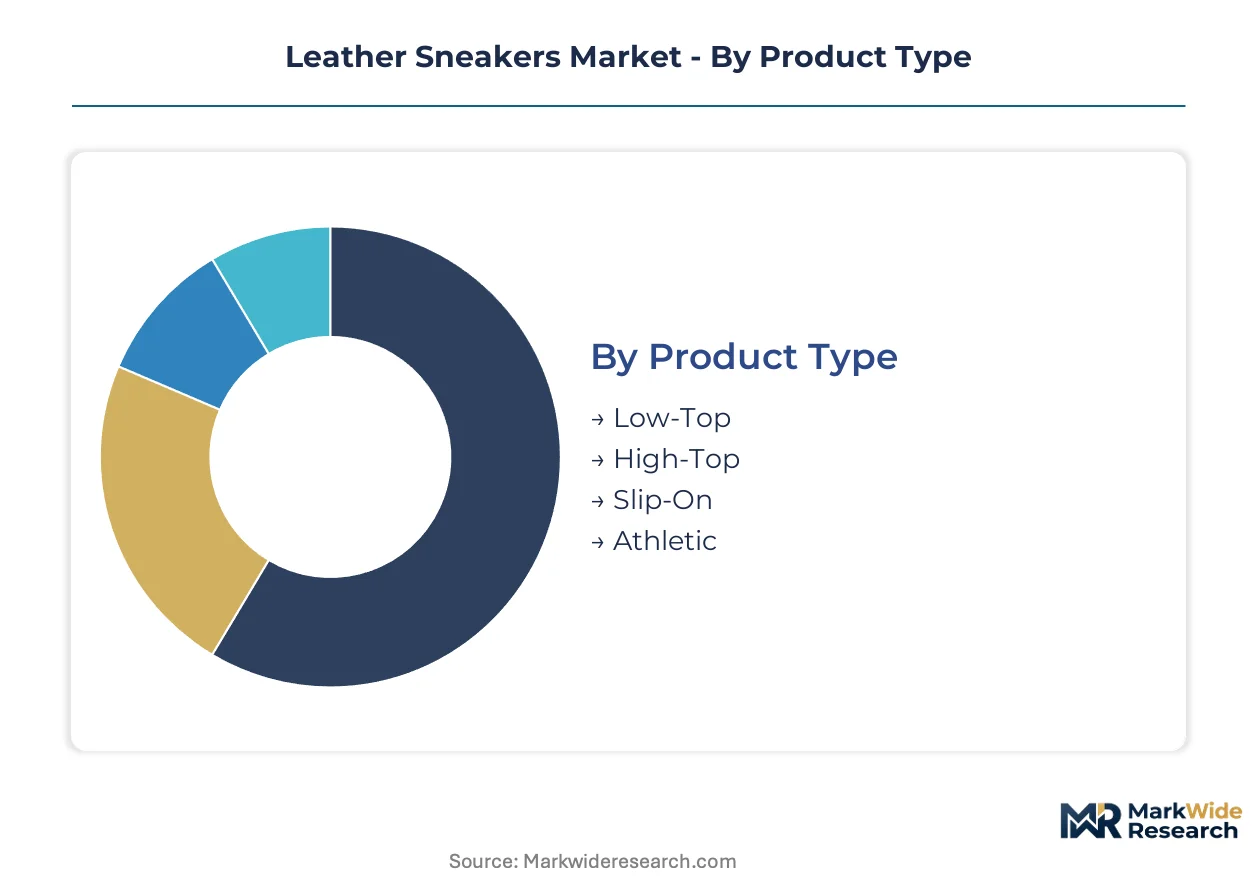
Leather sneaker segmentation reveals how construction geometry, user identity, channel access, and price anchoring fragment demand into distinct commercial battlegrounds. Each dimension carries specific margin implications and supply chain requirements that determine competitive viability.
Product Type:
Mature silhouettes dominate volume while emerging constructions reshape production workflows and inventory risk profiles.
- Low-Top:Ankle-below construction with minimal collar padding maximizes versatility across casual, commuter, and relaxed workplace environments. Demand concentrates in United States and United Kingdom urban corridors where hybrid dress codes normalize daily rotation; supply chains favor Vietnamese cut-and-sew clusters for speed-to-market responsiveness.
- High-Top:Extended collar with reinforced eyestay construction commands scarcity premiums through limited-release streetwear channels. Italian artisan districts supply European luxury houses with hand-finished uppers; authentication infrastructure and resale platform integration sustain per-unit economics above mass-market tiers.
- Slip-On:Elasticized goring or stretch leather eliminates lacing for convenience-focused commuter segments.
- Athletic:Performance-tuned lasts with cushioned midsole stacks compete against technical running crossovers in fitness-adjacent occasions.
Low-Top retains volume leadership; Athletic holds the steepest expansion curve as wellness positioning blurs casual-performance boundaries.
End User:
Customer identity segmentation maps directly to sizing complexity, color palette breadth, and marketing channel efficiency.
- Unisex:Gender-neutral lasts and desaturated colorways collapse SKU proliferation while capturing younger demographic purchasing patterns. Direct-to-consumer platforms in United Kingdom and Germany report strongest traction; modular construction enables rapid style iteration without last-specific tooling investments.
- Men:Traditional lasts with wider forefoot dimensions anchor heritage brand positioning and workplace-adjacent purchasing.
- Women:Narrower heel-to-ball ratios and expanded metallic or pastel finishing options drive seasonal refresh cycles.
- Children:Growth-accommodating construction with reinforced toe caps addresses durability concerns in school and activity contexts.
Men retains volume leadership; Unisex gains share fastest as gender-fluid merchandising displaces traditional department store aisle segmentation.
Distribution Channel:
Channel mix determines working capital intensity, return rate exposure, and brand control over pricing architecture.
- Online:Direct-to-consumer platforms and marketplace aggregators collapse discovery friction through algorithmic personalization. United States and United Kingdom markets concentrate highest penetration; AI-driven size-matching tools reduce return processing costs while enabling made-to-order margin structures.
- Specialty Stores:Curated assortments with trained fitting staff sustain premium positioning and authentication trust.
- Department Stores:Multi-brand environments with seasonal promotional calendars drive volume clearance exposure.
- Supermarkets:Mass-market price points with minimal service interaction capture impulse and replacement purchasing.
Specialty Stores retains volume leadership; Online climbs the fastest as platform infrastructure matures beyond early-adopter demographics.
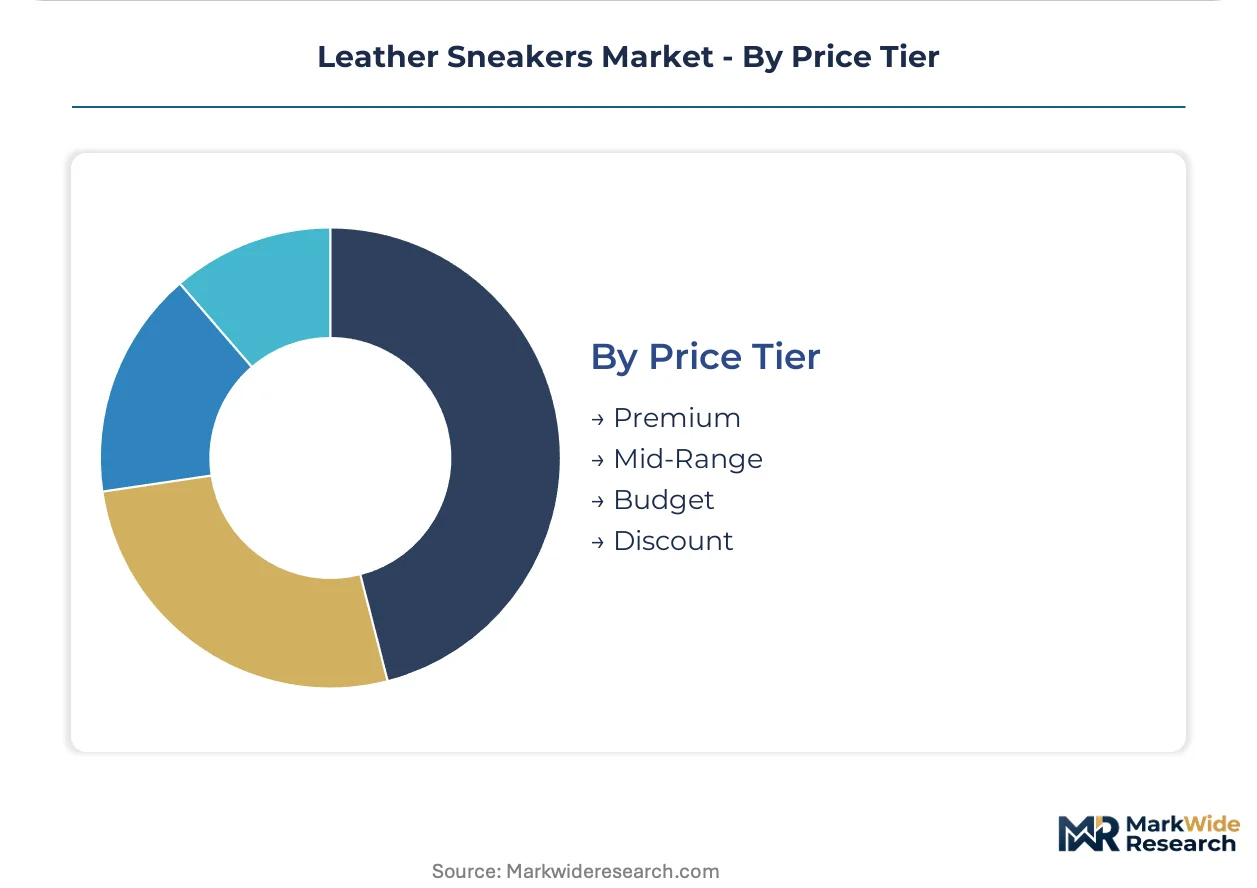
Price Tier:
Price architecture reflects material grade transparency, certification burden, and manufacturing geography cost structures.
- Premium:Full-grain uppers with LWG-certified tannery sourcing and hand-finished details justify three-digit price anchoring. Italian and Portuguese manufacturing clusters supply European and United States luxury wholesale channels; REACH and Proposition 65 compliance documentation adds fixed cost layers that exclude smaller competitors.
- Mid-Range:Corrected-grain or split leather with automated construction balances quality signaling and accessibility.
- Budget:Bonded leather or engineered substrates with simplified pattern engineering serve price-sensitive replacement purchasing.
- Discount:Closeout inventory and off-grade materials through outlet and liquidation channels.
Mid-Range retains volume leadership; Premium demonstrates the steepest expansion trajectory as certification transparency becomes a purchasable attribute.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam exports finished leather sneakers to United States and European Union wholesale channels, while Italian tanneries supply premium hides to luxury houses across Germany, France, and the United Kingdom. Trade corridors concentrate manufacturing in Southeast Asian cut-and-sew clusters and European artisan districts.
United States
Hybrid workplace dress codes in New York, Los Angeles, and Chicago drive daily-wear adoption beyond weekend use. California's Proposition 65 imposes chromium VI disclosure burdens on brands distributing through West Coast ports. Domestic assembly concentrates in Portland, Oregon, where athletic footwear R&D clusters anchor design-to-production workflows.
Germany
Direct-to-consumer platform penetration in Berlin, Munich, and Hamburg accelerates quarterly replacement cycles among younger demographics. The EU Green Deal circularity incentives subsidize take-back programs in Frankfurt and Düsseldorf distribution hubs. Bavarian manufacturing clusters deploy automated cutting systems to trim pattern inefficiencies in mid-premium production lines.
Italy
Luxury wholesale demand from Milan, Florence, and Rome sustains hand-finished premium tier economics. REACH Annex XVII restrictions on chromium VI compounds force Tuscan and Veneto tanneries to accelerate vegetable-tanning capacity buildouts. Artisan manufacturing clusters in Marche document farm-to-finish provenance through blockchain-enabled hide traceability systems.
Vietnam
Export-oriented production zones in Ho Chi Minh City and Binh Duong Province supply North American and European retail channels with speed-to-market responsiveness. The country's national environmental regulator tightens wastewater discharge standards for tanneries supplying assembly plants. Da Nang manufacturing clusters face recruitment gaps for hand-cutting specialists capable of luxury-grade consistency.
United Kingdom
Gender-neutral sizing demand in London, Manchester, and Birmingham collapses traditional department store aisle segmentation. The country's national consumer protection framework enforces chemical disclosure requirements parallel to EU REACH standards. Direct-to-consumer subscription models in Greater London concentrate highest penetration of quarterly curation services displacing seasonal wholesale purchasing.
Leather Sneakers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered price architecture. Consolidation concentrates around vertically integrated athletic houses and Italian luxury ateliers, while digital-native entrants fragment mid-premium positioning. Three archetypes dominate: scale-driven athletic manufacturers, heritage European luxury houses, and direct-to-consumer sustainability platforms. Competitive moves center on M&A for tannery access and strategic partnerships with resale platforms extending product lifecycle revenue.
Within the scale-driven tier, Nike, Inc. and Adidas AG exemplify channel-controlling archetypes with captive R&D infrastructure and automated production systems. Puma SE occupies a position between athletic scale and fashion-forward positioning. Among European luxury specialists, Gucci and Golden Goose represent heritage atelier models anchoring premium tier economics through scarcity mechanics and hand-finished construction.
| Leading Market Players |
|---|
| Nike, Inc. |
| Adidas AG |
| Puma SE |
| New Balance Athletics, Inc. |
| Gucci |
| Golden Goose |
| Veja |
| Common Projects |
| Axel Arigato |
| Others |
Supply & Pricing Matrix
REACH Annex XVII enforcement against chromium VI compounds operates as a regulatory chokepoint that simultaneously widens price spreads between vegetable-tanned premium tiers and chrome-finished economy grades while forcing supply chain consolidation around compliant Italian and Portuguese tanneries.
Pricing Analysis
The pricing gap between current-generation bioengineered leather substrates, established full-grain constructions, and emerging mycelium alternatives determines tier anchoring across the market. Three-tier pricing structure across premium, standard, and economy levels stratifies by LWG certification grade and hand-finished detail intensity. Cost compression in mid-range tiers is intensifying because Vietnamese automated cutting systems reduce pattern waste and labor hours. Direct-to-consumer subscription buyers exhibit lowest price sensitivity; supermarket channel purchasers show highest elasticity to promotional discounting.
Supply Chain Analysis
Raw hide sourcing draws from Brazilian and Argentinian cattle ranching, Italian vegetable-tanning cooperatives, and Vietnamese cut-and-sew export zones. Full-grain leather, engineered mycelium substrates, and rubber outsole compounds constitute the critical input trinity. Single-source vulnerability concentrates in Tuscan tannery districts supplying European luxury houses. Distribution runs through direct-to-consumer platforms, specialty retail boutiques, and department store wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating around digital-native direct-to-consumer platforms and subscription curation services, fragmenting traditional wholesale purchasing concentration that previously favored scale-driven athletic manufacturers.
For Market Incumbents: Entrench LWG-certified tannery relationships through captive supply agreements or equity stakes in Italian and Portuguese artisan clusters. Accelerate AI-driven size-matching deployment to collapse return rates and defend margin position against digitally native entrants with lower logistics overhead.
For New Entrants and Emerging Players: Build out unisex gender-neutral sizing architectures and desaturated color palettes targeting United Kingdom and German direct-to-consumer platforms. Indian organized retail expansion in Mumbai and Bangalore offers the most penetrable geography for mid-premium positioning without legacy wholesale channel obligations.
For Investors and Strategic Acquirers: The market sits at a compliance-investment phase that favors vertically integrated manufacturers with in-house vegetable-tanning capacity and blockchain traceability infrastructure. Long-term viability over the next decade hinges on circular economy program participation and resale platform partnership density. Monitor EU Green Deal subsidy allocation velocity as the inflection signal for circularity economics tipping toward profitability.
| Strategic Initiative | Industry Significance |
|---|---|
| Vegetable-Tanning Capacity Expansion | REACH compliance secures shelf access in German and French distribution hubs. |
| Blockchain Hide Traceability Deployment | Tuscan tanneries document farm-to-finish provenance for European luxury houses. |
| Direct-to-Consumer Platform Launch | AI size-matching tools collapse return rates and enable made-to-order margins. |
| Resale Platform Partnership | German take-back subsidies extend product lifecycle revenue through refurbishment. |
| Mycelium Substrate R&D Investment | Bioengineered alternatives differentiate from conventional bovine leather sourcing. |
Research Methodology
A spread of perspectives from brand sourcing directors, Italian tannery operators, Vietnamese factory managers, and direct-to-consumer platform executives converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against customs records, LWG audit databases, and EU SCIP registration filings. Bottom-up triangulation across product type, end user, distribution channel, and price tier segmentation anchored volume estimates against top-down trade corridor analysis.
Demand-supply balance modeling across the projection horizon integrated hybrid workplace dress code adoption curves, REACH enforcement trajectory, and biomaterial substitution elasticity. Segmentation dimensions included construction geometry, user identity, channel access, and price anchoring. CAGRs derived from regression against historical premium footwear category performance and parallel category analogs. Forecast inputs incorporated tannery capacity buildout timelines and digital platform penetration rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated athletic manufacturers or luxury house acquisition strategies would shift outcomes. Cross-checking against EU ECHA enforcement bulletins and California Proposition 65 litigation filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Middle East and Africa Athletic Footwear Market
Footwear
Equestrian Footwear Market
Footwear
Golf Footwear Market
Footwear
PU Sole (Footwear Polyurethane) Market
Footwear
Formal Shoes Market
Footwear
Second Hand Designer Shoes Market
Footwear
Sandals Market
Footwear
Europe Barefoot Shoes Market
Footwear
Women's Non-Athletic Footwear Market
Footwear
Ankle Boots Market
Footwear
Football Shoes Market
Footwear
Barefoot Shoes Market
Footwear
Light Up Shoes Market
Footwear
Global Footwear Market
Footwear
Trail Running Shoes Market
Footwear
Riding Boots Market