
 Lace Up Boots Market | 2026-2036
Lace Up Boots Market Size, Share, and Industry Trends Forecast 2026-2036
Lace Up Boots Market Foresight
Direct-to-consumer channels is fragmenting as heritage manufacturers and digital-native entrants compete for loyalty-driven buyers. Timberland leverages its outdoor heritage to sustain premium positioning in lifestyle and work segments. Red Wing Shoe Company anchors its reputation on domestic craftsmanship and resoleable construction. Dr. Martens differentiates through subcultural branding that extends into fashion-forward lace up collections.
Lace up boots are closed footwear systems utilizing eyelets, hooks, or speed laces to secure the upper around the foot and ankle, typically constructed with welted or cemented soles rated for specific slip, puncture, or electrical hazard resistance. Their primary commercial purpose spans occupational protection, military and tactical operations, outdoor recreation, and fashion expression. Work boots dominate procurement volume across industrial end users, while hiking boots command higher unit margins in outdoor specialty retail. Fashion boots are accelerating fastest among women and unisex buyers as seasonal collections integrate lug soles and heritage silhouettes. Leather remains the margin-dense material tier, though synthetic uppers are gaining share in vegan-certified and price-accessible lines.
ASTM International sets protective footwear standards in the United States, while the EU's PPE Regulation and CE marking requirements govern market access for safety-rated boots in Europe. These frameworks compel manufacturers to certify impact resistance, compression, and metatarsal protection, filtering out uncertified competitors. Stakeholders must monitor how proposed updates to ISO 20345 and regional sustainability disclosure rules reshape material sourcing decisions and factory audit requirements.
Market Dynamics
ASTM International's proposed updates to protective footwear standards are compressing certification timelines while REACH compliance in Europe forces material substitution across tannery networks, creating simultaneous specification pressure on manufacturers serving dual jurisdictions.
Growth Catalysts
- OSHA enforcement expansion:Warehouse and logistics operators in the United States are accelerating boot replacement cycles as workplace safety inspections intensify, particularly for slip-resistant and composite toe specifications.
- Material science advancement:Bio-based polyurethane midsoles derived from castor oil are penetrating work boot lines, satisfying vegan certification requirements while maintaining ASTM-rated compression resistance.
- Military procurement cycles:United States defense contracts for temperate and jungle combat boots are sustaining volume demand for full-grain leather uppers with welted construction.
Market Restraints
- Hide cost volatility:Cattle ranching disruptions in Brazil and Argentina are transmitting price instability through tannery supply tiers, compressing margins on leather-dominant product lines.
- Chinese synthetic dominance:Concentration of waterproof membrane and synthetic upper production in Zhejiang and Guangdong provinces creates geographic supply risk for brands lacking alternative sourcing.
- Replacement cycle extension:Cemented sole construction techniques have shortened average boot lifespan in fashion segments, eroding brand loyalty and repeat purchase velocity.
Strategic Opportunities
- Resoleable service infrastructure:Direct-to-consumer repair networks and mail-in resoling programs are capturing lifetime value from heritage boot owners in the United States and United Kingdom.
- EU Green Deal alignment:The Sustainable Products Regulation's forthcoming ecodesign requirements for footwear create first-mover advantage for manufacturers with certified circular material flows and take-back systems.
- Women's technical outdoor:Underdeveloped last engineering and fit specification for female hikers in Germany and France presents white space for anatomically differentiated hiking boot launches.
Industry Challenges
- Metatarsal guard integration:Incorporating advanced composite or aluminum metatarsal protection without compromising boot flexibility requires specialized pattern engineering that exceeds standard footwear technician skill sets.
- Multi-standard certification lag:Simultaneous pursuit of ASTM F2413, EN ISO 20345, and CSA Z195 approvals extends product development timelines by eight to fourteen months, delaying market entry.
- ERP integration with tannery traceability:Mapping individual hides through wet-blue processing to finished upper requires blockchain or serialized tracking investments that legacy manufacturing software cannot accommodate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lace Up Boots Market |
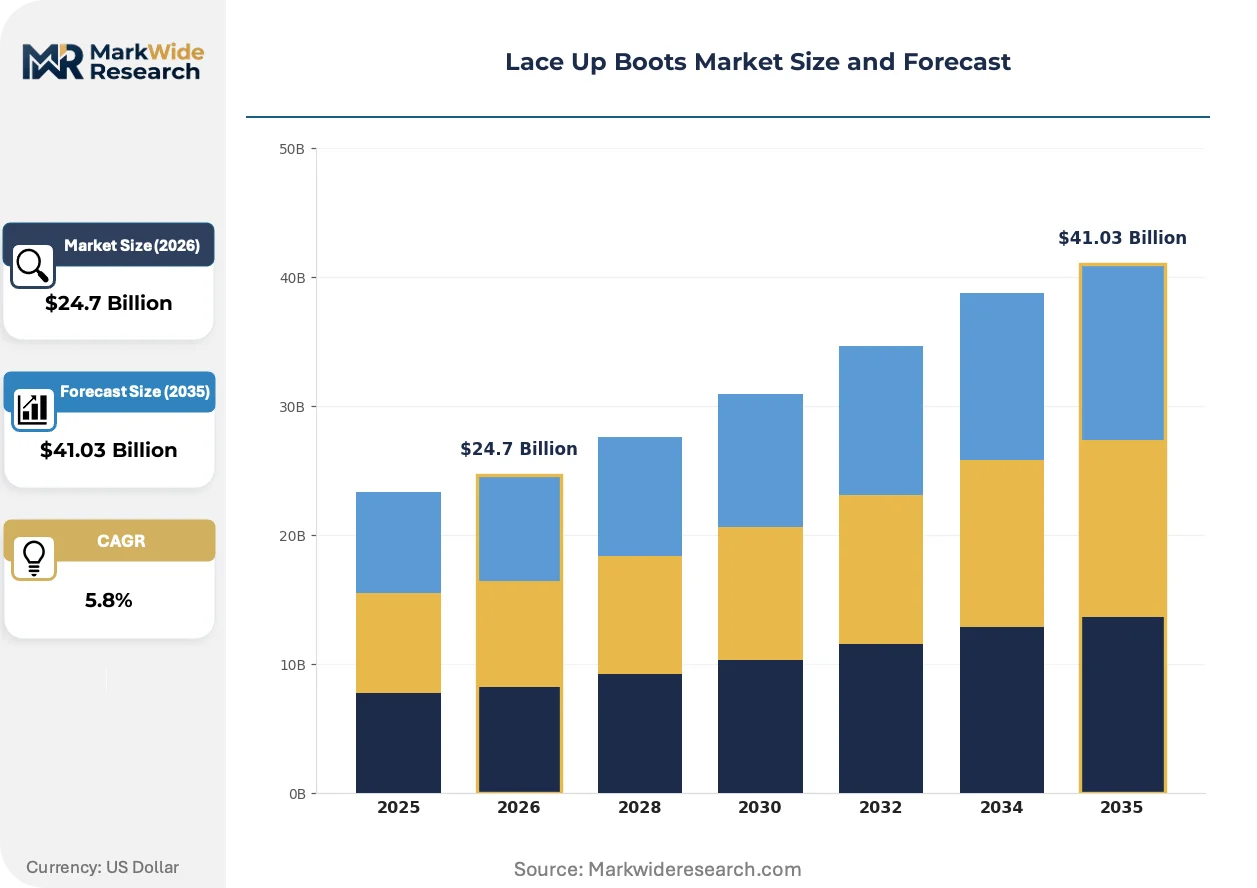
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $41.03 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hiking Boots, Fashion Boots, Work Boots, Combat Boots Material: Leather, Synthetic, Rubber, Canvas End User: Men, Women, Children, Unisex Usage Type: Casual, Outdoor, Industrial, Tactical |
| Companies Covered | Dr. Martens, Clarks, Timberland, Wolverine Worldwide, Red Wing Shoe Company, Danner, Georgia Boot, Thorogood, Rocky Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lace Up Boots Market Shifts & Advancements
Digital measurement and automated production systems are compressing the traditional made-to-measure pipeline for protective and outdoor boots, while regulatory disclosure requirements force transparency through previously opaque material supply tiers.
3D foot scanning combined with parametric last design software is digitizing the custom boot fitting process that once required physical casting and manual pattern adjustment. Industrial safety coordinators at mining and construction firms are piloting fleet-wide sizing programs that reduce misfit-related injury claims. This compression of measurement-to-production workflows is digitizing the economics of small-batch manufacturing, enabling regional micro-factories to compete with centralized Asian volume production on total landed cost for certified work boots.
REACH Annex XVII restrictions on chromium VI compounds in leather tanning are forcing tanneries across Italy and Spain to transition to vegetable or synthetic tanning agents. The industrial consequence is altered leather performance characteristics—reduced water resistance and modified break-in behavior—that require boot manufacturers to redesign conditioning recommendations and warranty terms. Hiking and heritage work boot lines marketed in Germany and France are most affected, with brands reformulating care product bundles and updating retail training to address consumer confusion over changed leather aesthetics.
Subscription-based boot replacement programs are emerging among United States employers with high workforce turnover in distribution and light manufacturing. Safety managers at third-party logistics providers are unbundling boot provision from uniform services, contracting directly with manufacturers for quarterly replacement cycles tied to wear-indicator monitoring. This reconfiguration of procurement authority—shifting from individual employee purchase to enterprise fleet management—is most visible in the southeastern United States, where warehouse employment concentration and tight labor markets make safety equipment retention a competitive variable in staffing.
Lace Up Boots Market Segmentation
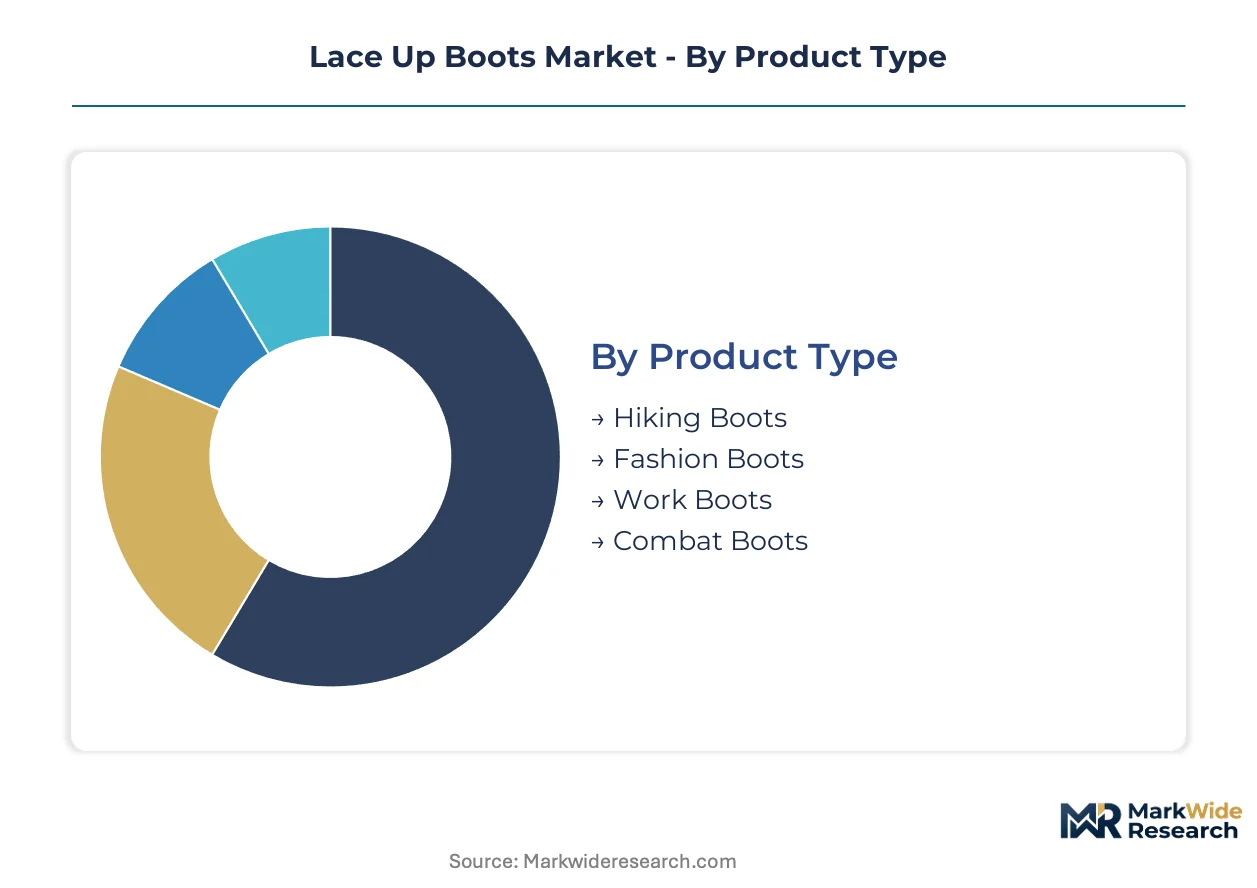
Segmentation in the lace up boots market reveals how procurement authority, material specifications, and end-use requirements fragment demand across distinct technical and commercial profiles. Manufacturers must align product architecture with the specific certification, durability, and aesthetic priorities of each segment cluster.
Product Type:
Mature industrial and military specifications coexist with emerging fashion-forward silhouettes as demand bifurcates between protective function and style expression.
- Hiking Boots:Technical uppers combine waterproof membranes with aggressive lug outsoles rated for multi-terrain traction. Demand concentrates in Germany and France among female hikers where anatomical last engineering remains underdeveloped, creating white space for differentiated fit specifications.
- Work Boots:Welted or cemented construction with ASTM-rated composite toes and puncture-resistant midsoles dominates industrial procurement. United States warehouse operators accelerate replacement cycles as OSHA enforcement intensifies, particularly for slip-resistant specifications in southeastern distribution hubs.
- Fashion Boots:Heritage silhouettes with lug sole integration target seasonal collections. Lighter cemented construction shortens lifespan but enables rapid style rotation.
- Combat Boots:Full-grain leather uppers with welted construction meet military temperate and jungle specifications. United States defense contracts sustain volume demand through formal procurement cycles.
Work boots handle the majority of throughput; fashion boots are the fastest mover on share.
Material:
Cost tiers separate margin-dense natural materials from price-accessible synthetics as regulatory pressure reshapes tanning chemistry.
- Leather:Full-grain and top-grain hides deliver abrasion resistance and mold-to-foot characteristics prized in heritage work and hiking lines. REACH Annex XVII restrictions on chromium VI compounds force Italian and Spanish tanneries toward vegetable tanning, altering water resistance and break-in behavior.
- Synthetic:Polyurethane and microfiber uppers satisfy vegan certification requirements while reducing unit cost. Bio-based polyurethane midsoles derived from castor oil penetrate work boot lines, maintaining ASTM-rated compression resistance.
- Rubber:Waterproof compounds form outsoles and protective toe caps in industrial and outdoor specifications. Zhejiang and Guangdong province concentration creates geographic supply risk for brands lacking alternative sourcing.
- Canvas:Breathable cotton or hemp uppers serve casual and warm-weather tactical applications. Lower durability limits penetration in certified protective footwear.
Leather commands the highest margin tier; synthetic materials are expanding most quickly as vegan certification gains procurement priority.
End User:
Volume distribution skews toward male industrial workers while female and unisex segments drive design innovation.
- Men:Traditional sizing standards dominate work, combat, and hiking categories. Industrial safety coordinators pilot fleet-wide fitting programs to reduce misfit-related injury claims.
- Women:Underdeveloped last engineering in technical outdoor creates opportunity for anatomically differentiated launches. Fashion boots accelerate fastest among female buyers as seasonal collections integrate heritage silhouettes.
- Children:Growth-accommodating designs with adjustable lacing systems serve school and casual outdoor use. Lower price points and rapid size turnover compress brand loyalty.
- Unisex:Extended size runs and neutral aesthetics target fashion and casual outdoor segments. Simplified inventory management appeals to direct-to-consumer channels.
Men's specifications handle the majority of throughput; women's technical outdoor is climbing the fastest as fit engineering gaps persist.
Usage Type:
Application-driven certification requirements separate industrial and tactical procurement from discretionary casual purchases.
- Casual:Style-forward designs prioritize aesthetic flexibility over protective ratings. Cemented sole construction enables cost compression and rapid trend response.
- Outdoor:Multi-terrain traction and waterproofing specifications serve hiking and recreational demand. German and French retailers reformulate care product bundles as vegetable-tanned leather performance characteristics shift.
- Industrial:ASTM F2413, EN ISO 20345, and CSA Z195 certifications mandate impact resistance, compression, and metatarsal protection. Simultaneous multi-standard pursuit extends development timelines by eight to fourteen months.
- Tactical:Military and law enforcement specifications require flame resistance, puncture protection, and rapid-dry linings. United States defense contracts anchor volume with welted construction durability requirements.
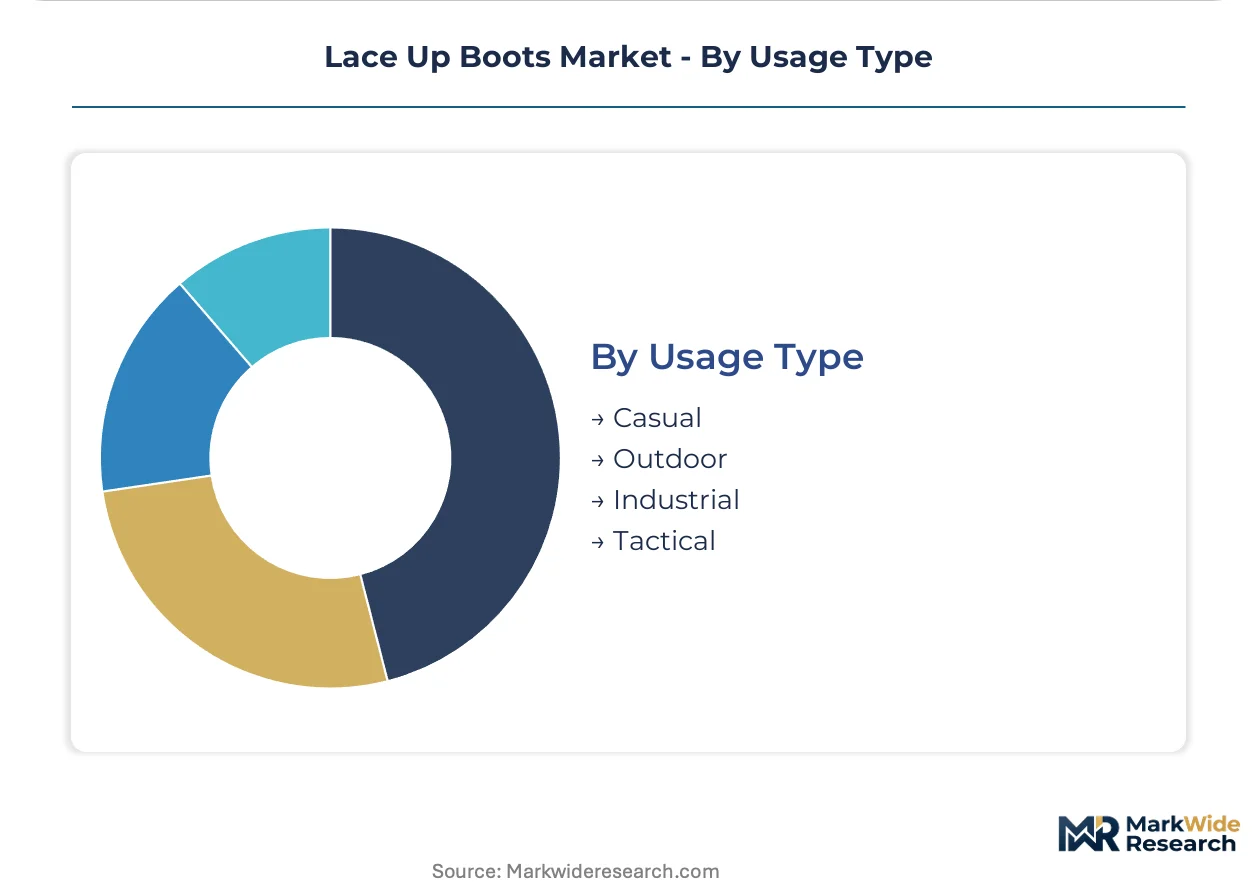
Industrial usage handles the majority of throughput; outdoor recreation is gaining share fastest as participation rates climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Savannah's container throughput expansion underpins United States distribution capacity for protective footwear, while Rhine River logistics corridors connect German industrial clusters to tannery networks across Italy and Spain.
United States
OSHA enforcement expansion in southeastern warehouse corridors accelerates boot replacement cycles for slip-resistant specifications. The Department of Defense sustains temperate and jungle combat boot procurement through formal military contracting. Nashville and Atlanta distribution hubs concentrate third-party logistics provider safety equipment procurement.
Germany
REACH Annex XVII compliance deadlines force tanneries toward vegetable tanning agents, altering leather performance characteristics for hiking boot lines. The EU Green Deal's Sustainable Products Regulation creates first-mover advantage for circular material flows. Bavarian outdoor retailers reformulate care product bundles to address consumer confusion over changed leather aesthetics.
France
Underdeveloped anatomical last engineering for female hikers creates white space for differentiated technical outdoor launches. CE marking requirements under the EU's PPE Regulation govern safety-rated boot market access. Lyon and Grenoble alpine equipment clusters drive demand for multi-terrain traction specifications.
Italy
Vegetable tanning transitions across Tuscan and Veneto tannery districts reshape water resistance and break-in behavior for heritage work boot uppers. ECHA enforcement of chromium VI restrictions compresses certification timelines. Milan fashion houses integrate lug sole heritage silhouettes into seasonal collections.
China
Concentration of waterproof membrane and synthetic upper production in Zhejiang and Guangdong provinces creates geographic supply risk for brands lacking alternative sourcing. GB standards alignment with ISO 20345 facilitates export certification. Shenzhen and Dongguan manufacturing clusters dominate bio-based polyurethane midsole component supply.
Lace Up Boots Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The vendor base organizes around three tiers: heritage manufacturers with resoleable construction infrastructure, digital-native entrants pursuing direct-to-consumer loyalty, and private-label assemblers serving enterprise fleet procurement. Consolidation pressure concentrates among mid-scale specialists lacking certified multi-standard capacity. Dominant competitive moves include geographic sourcing diversification away from Zhejiang-Guangdong concentration and repair-service infrastructure buildout to capture lifetime value.
Within the heritage manufacturer tier, Red Wing Shoe Company and Dr. Martens exemplify divergent positioning strategies—one anchoring reputation on domestic craftsmanship and resoleable construction, the other differentiating through subcultural branding extending into fashion-forward collections. Timberland occupies a position leveraging outdoor heritage across lifestyle and work segments. Wolverine Worldwide sits within the scale-driven portfolio architecture, representing diversified brand holdings across price-accessible and premium specifications.
| Leading Market Players |
|---|
| Dr. Martens |
| Clarks |
| Timberland |
| Wolverine Worldwide |
| Red Wing Shoe Company |
| Danner |
| Georgia Boot |
| Thorogood |
| Rocky Brands |
| Others |
Supply & Pricing Matrix
Zhejiang and Guangdong province manufacturing clusters anchor global synthetic upper and waterproof membrane capacity, concentrating pricing leverage among component suppliers serving brands without alternative sourcing footprints. Hide cost volatility from Brazilian and Argentine cattle ranching disruptions transmits through Italian and Spanish tannery networks, compressing margins on leather-dominant lines while bio-based polyurethane alternatives gain procurement traction.
Pricing Analysis
Volume-discount tiering structures dominate enterprise fleet procurement, with quarterly replacement cycles commanding lower per-unit rates than individual retail purchases. Three-tier pricing structure across premium, standard, and economy levels separates ASTM-certified work boots with composite toe and metatarsal protection from fashion-oriented cemented construction. Cost compression in the standard tier is intensifying because Chinese synthetic dominance enables rapid style rotation at reduced unit economics. Third-party logistics providers exhibit highest price sensitivity due to workforce turnover economics, while military procurement contracts demonstrate lowest sensitivity given durability specifications and domestic content requirements.
Supply Chain Analysis
Upstream feedstock dynamics center on full-grain hides from Brazilian and Argentine ranching operations, castor oil derivatives for bio-based polyurethane midsoles, and synthetic textile precursors from petrochemical complexes. Manufacturing capacity concentrates in China, Italy, and the United States, with welted construction craftsmanship anchored in domestic American workshops and precision synthetic component production feeding from Zhejiang injection-molding clusters. Single-source vulnerability persists for waterproof membrane supply from Guangdong province facilities. Distribution runs through Nashville and Atlanta third-party logistics hubs for United States industrial end users, Bavarian outdoor retail clusters for German hiking demand, and Lyon-Grenoble alpine equipment networks for French technical outdoor procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Annex XVII chromium VI restrictions and bio-based material certification requirements are accelerating specification turnover, creating first-mover advantage for manufacturers with compliant supply chain infrastructure already operational.
For Market Incumbents: Entrench resoleable service infrastructure through direct-to-consumer repair networks and mail-in programs, capturing lifetime value from heritage boot owners in the United States and United Kingdom. Deepen backward integration into vegetable-tanned leather supply from Tuscan and Veneto tannery districts to secure REACH-compliant material flows ahead of ECHA enforcement compression. Prioritize multi-standard certification capacity—ASTM F2413, EN ISO 20345, CSA Z195—to defend against mid-scale specialists lacking simultaneous approval timelines. For New Entrants and Emerging Players: Build out anatomically differentiated hiking boot lines targeting female hikers in Germany and France, where underdeveloped last engineering creates penetrable white space against established outdoor brands. Deploy subscription-based replacement programs for United States distribution and light manufacturing employers, unbundling boot provision from uniform services through wear-indicator monitoring. Pursue direct-to-consumer digital-native positioning with vegan-certified synthetic lines to bypass heritage brand distribution lock-in. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with certified circular material flows and take-back systems aligned with EU Green Deal Sustainable Products Regulation ecodesign requirements. Five-to-ten year viability hinges on ERP integration with blockchain-enabled tannery traceability, separating investable platforms from legacy software-constrained operators. Monitor ECHA enforcement intensity across Italian and Spanish tanning districts as inflection indicator for margin compression timeline in leather-dominant holdings.| Strategic Initiative | Industry Significance |
|---|---|
| Resoleable Service Infrastructure Buildout | Captures lifetime value from Red Wing and Dr. Martens heritage owners through direct repair networks. |
| Vegetable Tanning Supply Integration | Secures REACH-compliant leather flows from Tuscan tanneries ahead of ECHA chromium VI deadlines. |
| Women's Anatomical Last Engineering | Addresses fit specification gaps for female hikers in German and French outdoor retail channels. |
| Subscription Fleet Procurement Programs | Aligns quarterly replacement cycles with OSHA enforcement expansion in southeastern United States warehouses. |
| Multi-Standard Certification Investment | Compresses ASTM-EN-CSA approval timelines that currently extend development cycles by eight to fourteen months. |
Research Methodology
Initial hypotheses were tested against primary input from safety equipment procurement managers at third-party logistics providers, tannery operations directors in Italy and Spain, outdoor retail category buyers in Germany and France, and military contracting officers at United States defense procurement commands, then refined against secondary validation from customs trade databases, SEC footwear manufacturer filings, ECHA regulatory enforcement records, and OSHA workplace safety inspection reports. Bottom-up unit economics from component cost structures were triangulated against top-down market sizing from end-use demand aggregation.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling volume and value outputs through segmentation dimensions spanning product type, material tier, end-user demographic, and usage certification requirements. CAGRs were derived from replacement cycle dynamics, regulatory compliance timelines, and military procurement cycle visibility. Industry-specific forecast inputs incorporated hide cost volatility transmission from Brazilian and Argentine ranching operations and bio-based polyurethane penetration rates in ASTM-rated work boot lines.
Stress conditions across cattle hide supply disruptions, REACH enforcement intensity, and Chinese synthetic component export constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding OSHA inspection expansion trajectory and EU Green Deal implementation pacing. Cross-checking against United States Department of Defense procurement disclosure databases and ECHA substance restriction update notices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Loafers Market
Footwear
E-Commerce Footwear Market
Footwear
Casual Shoes Market
Footwear
Cowgirl Boots Market
Footwear
Sports Shoes Market
Footwear
Women's Sneakers Market
Footwear
Desert Boots Market
Footwear
Athletic Footwear Market
Footwear
UGG Boots Market
Footwear
Shoe Insoles Market
Footwear
Sustainable Footwear Market
Footwear
Formal Shoes Market
Footwear
Leather Footwear Market
Footwear
Global Footwear Market
Footwear
Global Espadrille Flats Market
Footwear
South America Athletic Footwear Market