
 Latin America Online Grocery Market | 2026-2036
Latin America Online Grocery Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Online Grocery Market Intelligence
Multi-sourced fulfillment is expanding across Latin America as platforms diversify beyond single-warehouse dependency. Mercado Libre anchors its position through proprietary logistics networks spanning major Brazilian corridors. Rappi S.A.S. differentiates via on-demand rider fleets that penetrate dense urban zones. Cornershop Limited leverages localized shopper networks to sustain rapid delivery promises in Mexican metropolitan areas.
Online grocery commerce encompasses digital ordering, payment processing, and coordinated last-mile distribution of perishable and packaged food items through platform-mediated supply chains. Cold-chain integrity demands temperature-controlled handling from picker to doorstep, with shelf-life sensitivity dictating fulfillment speed thresholds. Home Delivery occupies the dominant share of transaction volume, while Subscription Services capture recurring revenue pools from urban households seeking predictable replenishment. Digital Wallets displace Cash on Delivery as the preferred settlement layer, reducing friction and enabling real-time transaction reconciliation for platform operators.
Brazil's consumer protection regulator and Mexico's data privacy authority enforce disclosure and consent standards that elevate platform compliance costs. Argentina's central bank oversight of digital payment providers shapes wallet integration requirements across cross-border operators. Stakeholders must monitor evolving perishable goods labeling mandates and rider classification rulings as enforcement intensifies across Mercosur and Pacific Alliance jurisdictions.
Market Dynamics
Multi-sourced fulfillment networks are compressing delivery windows across Brazilian and Mexican metropolitan corridors, forcing platforms to integrate dark-store density with third-party logistics partnerships.
Growth Catalysts
- Digital Wallet Penetration:PIX instant-payment infrastructure from Brazil's central bank eliminates cash-handling friction, accelerating transaction velocity for platform operators.
- Urban Household Density:São Paulo and Mexico City residential clustering enables route-optimization algorithms to achieve sub-60-minute delivery economics.
- Data Privacy Frameworks:Mexico's data protection authority mandates consent standards that build consumer trust, reducing checkout abandonment for first-time digital grocery buyers.
Market Restraints
- Perishable Cold-Chain Costs:Refrigerated last-mile fulfillment consumes 18-25% of order value in Argentina's energy-price-volatile environment.
- Interstate Logistics Fragmentation:Mercosur customs inefficiencies block seamless cross-border inventory pooling between Brazilian and Argentine warehouses.
- Substitute Channel Persistence:Traditional neighborhood mercados in Mexico City maintain price competitiveness on staple produce through cash-only, no-delivery overhead structures.
Strategic Opportunities
- Colombian Market Entry:Bogotá and Medellín display underpenetrated online grocery adoption with comparable urban density to São Paulo's 2021 baseline.
- Subscription Replenishment Models:Chile's affluent Santiago households demonstrate willingness to pre-commit to weekly delivery slots for predictable consumption categories.
- Regulatory Tailwinds:Brazil's consumer protection code enforcement creates compliance moats that favor capitalized platforms over informal competitors.
Industry Challenges
- Picker Productivity Variance:In-store fulfillment accuracy rates fluctuate 12-18 percentage points across Mexican supermarket partner locations, eroding margin on substitution-heavy orders.
- Rider Classification Uncertainty:Brazilian labor courts issue conflicting rulings on gig-worker employment status, exposing platforms to retroactive benefit liabilities.
- Legacy POS Integration:Argentine supermarket chains operate on 1990s-era inventory systems that lack real-time stock visibility for online channel synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Online Grocery Market |
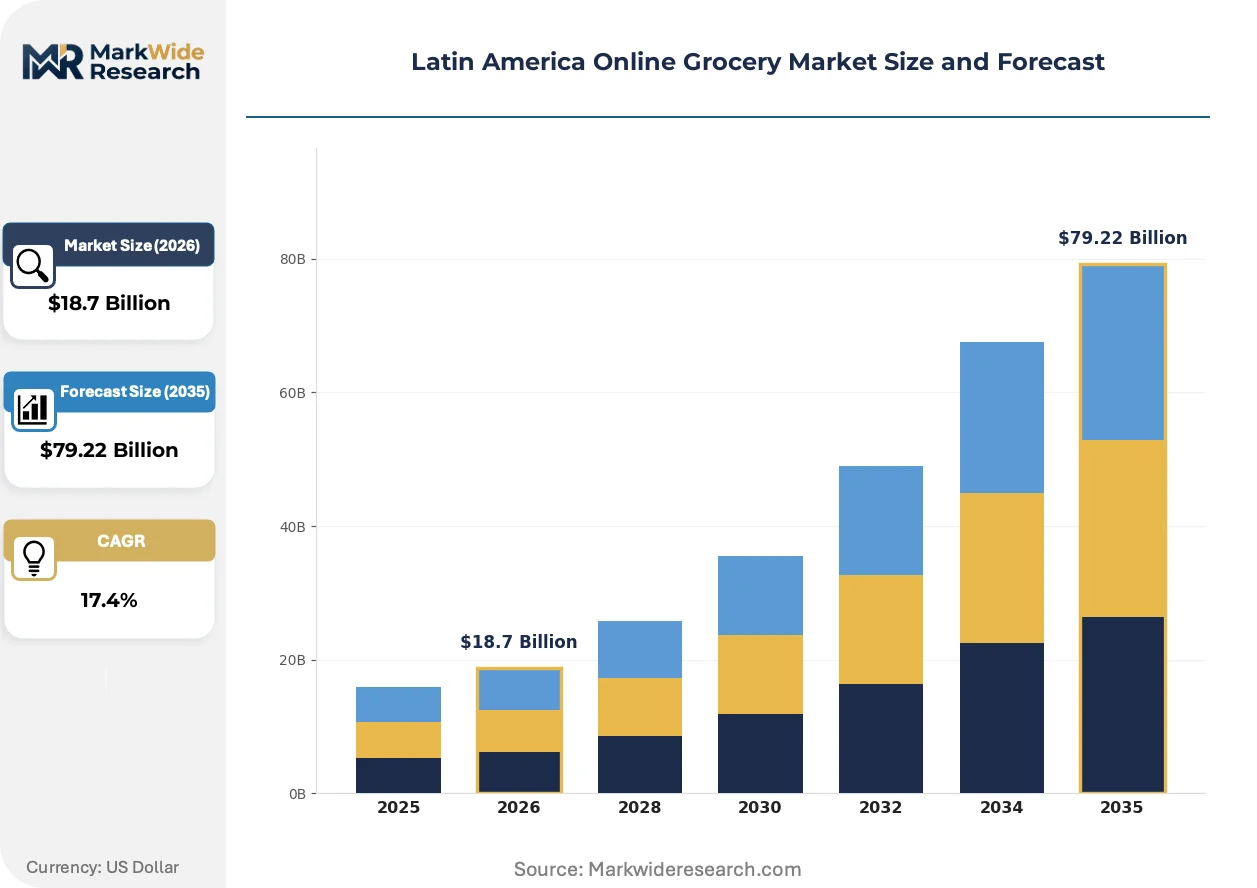
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $79.22 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Dairy, Snacks Customer Type: Households, Restaurants, Meal Kit Services, Businesses Delivery Method: Home Delivery, Click & Collect, Subscription Services, On-Demand Payment Method: Credit Card, Digital Wallets, Bank Transfer, Cash on Delivery |
| Companies Covered | Amazon Grocery, Mercado Libre, Inc., Glovo, Cornershop Limited, PedidosYa SA, iFood S.A., Walmart Grocery, Carrefour Brasil, Rappi S.A.S., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Online Grocery Market Strategic Shifts & Innovations
Platform operators are weaponizing fulfillment speed as the primary competitive differentiator, compressing delivery promises while expanding private-label penetration to capture margin.
AI-powered demand forecasting is expanding into perishable inventory management across Brazilian distribution centers. Retailers deploy machine-learning models that predict neighborhood-level consumption patterns 48-72 hours forward. This capability is expanding into automated purchase-order generation that reduces spoilage write-offs by aligning procurement with actual velocity rather than historical averages.
Brazil's consumer protection regulator enforces strict perishable goods labeling standards that mandate origin disclosure and expiration clarity. Platforms must redesign supplier onboarding workflows to capture granular product data. Full-service operators absorb compliance costs directly while marketplace models push verification burdens onto third-party sellers, creating a structural divergence in catalog depth.
Urban households are consolidating weekly grocery spend into fewer, larger digital baskets rather than incremental store visits. São Paulo apartment-dwellers substitute convenience-store trips with scheduled same-day delivery windows. This concentration pattern is most visible in dual-income professional segments where time scarcity outweighs modest per-item premiums.
Latin America Online Grocery Market Segmentation
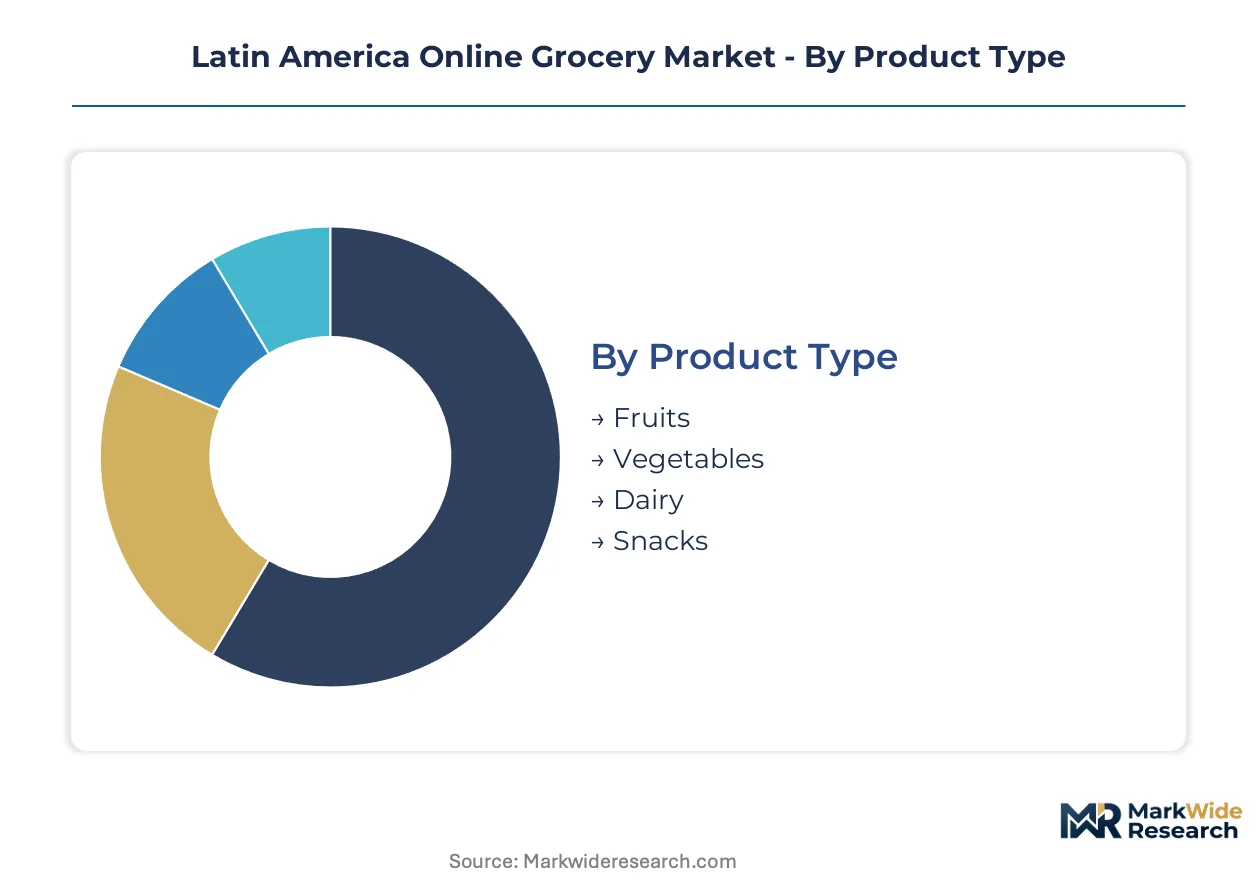
Segmentation in Latin America's online grocery sector reveals how fulfillment infrastructure and payment ecosystems shape platform economics. Understanding these divides exposes where cold-chain investments concentrate and which customer relationships generate recurring revenue.
Product Type:
Fresh categories demand embedded temperature control throughout fulfillment, while packaged goods operate through standalone ambient networks.
- Fruits:Temperature-sensitive produce requires continuous cold-chain integrity from farm-gate sourcing through last-mile delivery. São Paulo households drive disproportionate demand for tropical varieties, with platform operators absorbing spoilage risk on bruise-prone inventory.
- Vegetables:Leafy greens and delicate herbs command premium slotting fees in dark-store configurations due to rapid quality degradation. Mexican metropolitan clusters show highest per-capita velocity for organic vegetable subscriptions, forcing localized procurement partnerships.
- Dairy:Refrigerated SKUs dominate Argentine platform baskets despite energy-price volatility compressing margins.
- Snacks:Ambient storage requirements allow centralized distribution economics with extended shelf-life buffers.
Volume placements concentrate in Snacks; the faster expansion belongs to Fruits.
Customer Type:
Customer relationships stratify by order frequency predictability and basket size concentration, separating recurring revenue pools from transactional volume.
- Households:Dual-income urban apartments in Brazil's southeast corridor generate weekly replenishment patterns with above-average basket values. Time-scarcity dynamics override price sensitivity for scheduled delivery slots.
- Restaurants:Commercial buyers demand pre-dawn delivery windows and invoice-grade documentation for tax compliance. São Paulo's independent eatery density creates concentrated demand zones with specialized procurement workflows.
- Meal Kit Services:Pre-portioned ingredient bundles require precise component synchronization across multiple supplier touchpoints.
- Businesses:Corporate pantry replenishment operates on monthly billing cycles with consolidated procurement authority.
Households anchor current transaction density; Restaurants are climbing the fastest as platform operators build dedicated B2B fulfillment lanes.
Delivery Method:
Delivery modality selection reflects trade-offs between immediacy premiums and planning horizons, with infrastructure requirements varying dramatically across the spectrum.
- Home Delivery:Scheduled window fulfillment dominates Brazilian transaction volume, leveraging route-density algorithms to achieve unit-economic viability in São Paulo's high-rise corridors. Dark-store proximity to residential clusters determines competitive positioning.
- Click & Collect:Curbside pickup reduces last-mile cost exposure for platforms while capturing time-flexible customers. Mexican supermarket chains deploy dedicated parking infrastructure to defend against pure-play digital competitors.
- Subscription Services:Pre-committed weekly slots enable demand forecasting precision and inventory pre-positioning. Santiago households demonstrate willingness to lock in recurring delivery patterns for staple categories.
- On-Demand:Sub-60-minute promises require rider fleet density that concentrates in dense urban cores.
Home Delivery maintains dominant share; Subscription Services gain share fastest as platforms weaponize predictability for margin expansion.
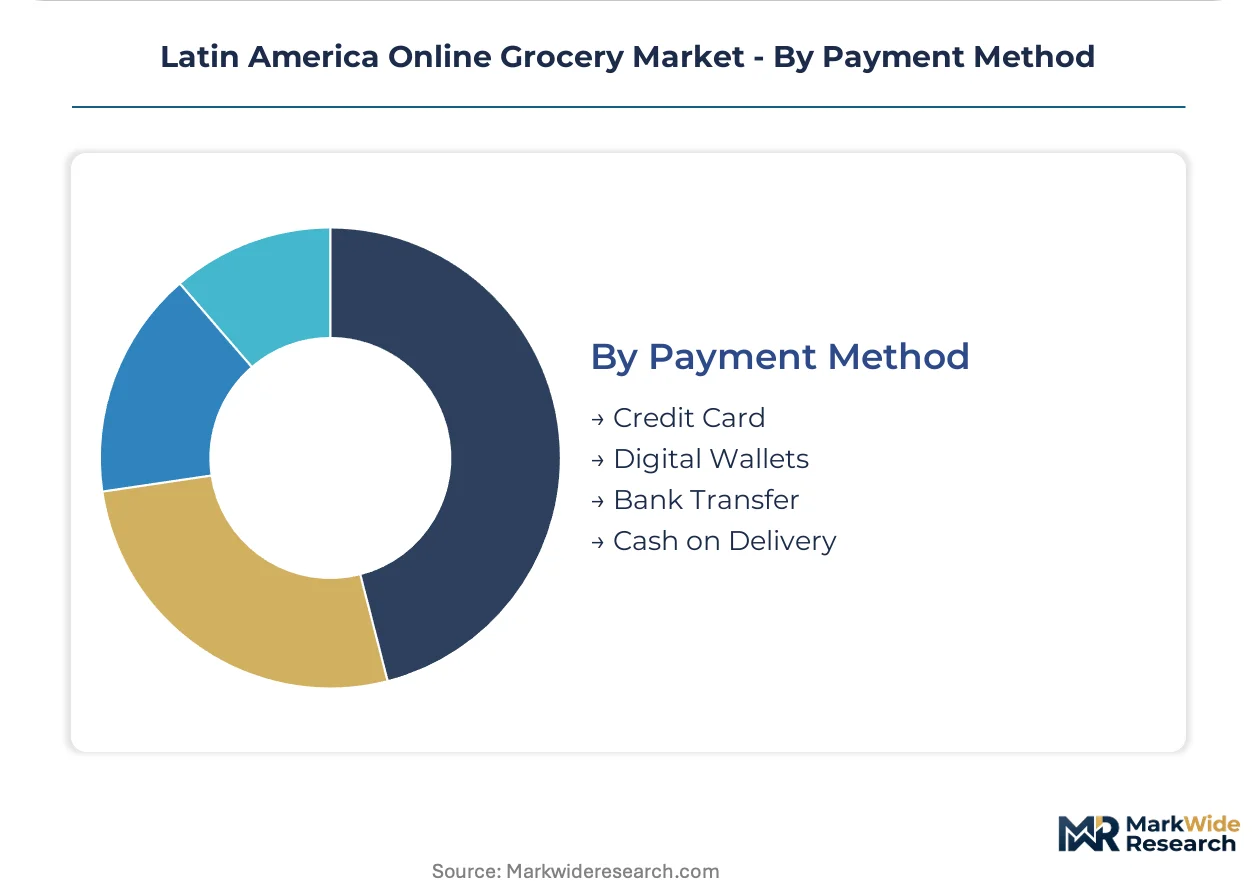
Payment Method:
Settlement layer selection shapes transaction friction, reconciliation speed, and platform working capital requirements across different customer trust thresholds.
- Credit Card:Revolving credit instruments dominate Argentine platform transactions despite central bank interest rate volatility. Installment plans (cuotas) embedded at checkout drive conversion for higher basket values.
- Digital Wallets:Brazil's PIX infrastructure eliminates settlement delays and cash-handling overhead, accelerating platform cash conversion cycles. Real-time confirmation reduces checkout abandonment versus legacy methods.
- Bank Transfer:Direct debit arrangements appeal to risk-averse first-time buyers in markets with limited card penetration.
- Cash on Delivery:Persistent in Mexican informal settlements where banking exclusion intersects with delivery trust deficits.
Digital Wallets are displacing legacy methods fastest; Credit Card volume remains concentrated in premium customer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban logistics corridors and digital payment infrastructure anchor geographic expansion across Latin America. Brazil's southeastern industrial belt feeds fulfillment networks while Mexican metropolitan clusters concentrate demand density. Argentine cold-chain investments and Chilean subscription adoption patterns complete the regional mosaic.
Brazil
São Paulo's high-rise residential corridors generate weekly replenishment velocity exceeding other metropolitan baselines. Brazil's consumer protection regulator enforces strict perishable goods labeling standards that elevate platform compliance costs. Mercado Libre anchors proprietary logistics networks across the southeastern corridor, compressing delivery windows through dark-store density.
Mexico
Mexico City residential clustering enables route-optimization algorithms to achieve sub-60-minute delivery economics. The country's data privacy authority mandates consent standards that build consumer trust and reduce checkout abandonment. Cornershop Limited leverages localized shopper networks to sustain rapid delivery promises across metropolitan zones.
Argentina
Refrigerated SKU demand persists despite energy-price volatility compressing margins for platform operators. The central bank oversees digital payment providers, shaping wallet integration requirements for cross-border operators. Buenos Aires apartment-dwellers consolidate weekly grocery spend into larger digital baskets, substituting convenience-store visits with scheduled delivery windows.
Chile
Santiago households demonstrate willingness to pre-commit to weekly delivery slots for predictable consumption categories. The national consumer protection framework elevates disclosure requirements for subscription service operators. Affluent metropolitan segments drive adoption of recurring replenishment models that enable inventory pre-positioning.
Colombia
Bogotá and Medellín display underpenetrated online grocery adoption with comparable urban density to São Paulo's earlier baseline. The national financial regulator supervises digital wallet proliferation, reducing cash-handling friction for platform transactions. Emerging logistics partnerships concentrate fulfillment investment in Andean metropolitan corridors.
Latin America Online Grocery Market Key Industry Players
Dark-store expansion dominates the current landscape as platforms compress delivery windows through proprietary fulfillment density. The vendor base stratifies between full-service operators with captive logistics and marketplace models reliant on third-party partnerships. Three archetypes define positioning: vertically integrated regional champions, on-demand delivery specialists, and multinational retail incumbents. Capacity expansion and strategic partnerships represent the dominant competitive vectors as operators seek route-density economics.
Within the vertically integrated tier, Mercado Libre, Inc. and Rappi S.A.S. exemplify divergent fulfillment philosophies. Mercado Libre anchors Brazilian logistics corridors through proprietary infrastructure investments. Rappi S.A.S. occupies a position emphasizing on-demand rider fleet density for sub-60-minute delivery promises. Cornershop Limited sits within the localized shopper network archetype, sustaining rapid fulfillment through gig-economy labor pools rather than fixed asset bases.
| Leading Market Players |
|---|
| Amazon Grocery |
| Mercado Libre, Inc. |
| Glovo |
| Cornershop Limited |
| PedidosYa SA |
| iFood S.A. |
| Walmart Grocery |
| Carrefour Brasil |
| Rappi S.A.S. |
| Others |
Cost & Logistics Intelligence
Cold-chain fuel price indices cascade through Latin American online grocery fulfillment networks, compressing margins on refrigerated last-mile delivery while pushing platforms toward unbundled service tiers that separate temperature-controlled handling from ambient logistics.
Pricing Analysis
Service-bundling choices separate full-service operators from marketplace models, with the former absorbing cold-chain compliance costs directly while the latter push verification burdens onto third-party sellers. Three-tier pricing structure across premium, standard, and economy levels reflects delivery speed guarantees and temperature-control investments. Cost compression in the premium tier is intensifying because São Paulo's dark-store density wars force sub-60-minute delivery promises at thinning margins. Restaurant buyers demonstrate lowest price sensitivity due to invoice-grade documentation requirements, while cash-constrained households in Mexican informal settlements remain most price-elastic.
Supply Chain Analysis
Single-source vulnerability sits with Brazilian refrigerated trucking networks that dominate cross-state produce distribution into São Paulo metropolitan clusters. Sourcing concentrates in Brazil, Mexico, and Argentina for fresh categories, with Chilean fruit exports feeding seasonal inventory windows. Cold-chain equipment, insulated packaging, and last-mile rider fleets constitute critical input dependencies. Tariff exposure runs through Mercosur customs inefficiencies that block seamless cross-border inventory pooling. Distribution feeds from dark-store nodes into hyperlocal rider networks for final-leg fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America's online grocery sector functions as a vertical-integration race where proprietary logistics networks and captive cold-chain infrastructure determine pricing power and delivery-speed positioning.
For Market Incumbents: Lock in dark-store density advantages across São Paulo and Mexico City corridors before Colombian market entry accelerates. Absorb Brazil's consumer protection code compliance costs to create regulatory moats against informal competitors. Expand proprietary rider fleet coverage to defend sub-60-minute delivery promises against on-demand specialists.
For New Entrants and Emerging Players: Social commerce integration offers the lowest customer-acquisition-cost pathway into Mexican and Colombian metropolitan zones. Target Bogotá and Medellín for first-mover positioning given comparable urban density to São Paulo's earlier baseline. Pursue white-label fulfillment partnerships with traditional supermarket chains to bypass legacy POS integration barriers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated regional champions with captive logistics networks in Brazilian southeastern corridors. Long-term viability hinges on subscription replenishment model penetration that locks in recurring revenue pools and enables inventory pre-positioning. Watch Santiago household willingness to pre-commit to weekly delivery slots as the signal for subscription model scalability across the region.
| Strategic Initiative | Industry Significance |
|---|---|
| Dark-Store Network Expansion | Proprietary fulfillment density in São Paulo compresses delivery windows below competitor reach. |
| Subscription Service Launch | Santiago pre-commitment patterns demonstrate recurring revenue potential for staple categories. |
| PIX Wallet Integration | Brazil's central bank infrastructure eliminates settlement delays and cash-handling overhead. |
| B2B Fulfillment Lane Development | São Paulo independent eatery density creates concentrated demand zones with specialized workflows. |
| AI-Powered Demand Forecasting | Machine-learning models align perishable procurement with neighborhood-level consumption velocity. |
Research Approach
Independent corroboration across platform operations executives, supermarket chain digital leads, cold-chain logistics directors, and central bank payment specialists underwrites the qualitative findings. Primary interviews with dark-store operators, rider fleet managers, and consumer protection regulators combined with secondary validation from ANVISA filings, Banco Central do Brasil PIX disclosures, and Mexican data protection authority consent standards. Bottom-up transaction volume modeling and top-down macroeconomic triangulation anchor the analytical framework.
Comparable-period anchoring to São Paulo's 2021 baseline urban density metrics and Mexico City's route-optimization algorithm deployment timelines structured the forecast window. Segmentation dimensions span product type, customer relationship predictability, delivery modality trade-offs, and payment settlement layers across the projection horizon. CAGRs derive from logistics network maturity curves and digital wallet penetration trajectories. Cold-chain spoilage rates and dark-store slotting fees constitute industry-specific forecast inputs.
The model holds under sustained urban household density growth and regulatory enforcement continuity; deviation in energy price volatility or labor court rulings on rider classification would shift margin assumptions. Forecasts reflect documented assumptions about PIX adoption velocity and perishable labeling mandate compliance costs. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Restaurant Takeout Market
Food Service
Charbroiler Market
Food Service
Online Food Delivery Market
Food Service
United States Cafes & Bars Market
Food Service
Food Service Pasta Market
Food Service
Global Food Platform-To-Consumer Delivery Market
Food Service
Europe Vending Machine Market
Food Service
Commercial Grills Market
Food Service
Instant Noodle Vending Machine Market
Food Service
Food Away from Home Market
Food Service
Asia Pacific Food Platform-To-Consumer Delivery Market
Food Service
Commercial Tableware Services Market
Food Service
Saudi Arabia Out of Home (OOH) Delivery Market
Food Service
Global Waffle Maker Market
Food Service
South Korea Foodservice Market
Food Service
A La Carte Market