
 Ylang Ylang Extract Market | 2026-2036
Ylang Ylang Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Ylang Ylang Extract Market Analytics
ISO 9235 certification for natural aromatic raw materials is collapsing the supplier base for ylang ylang extract, forcing distillers to invest in traceable supply chains. Givaudan SA leverages its Madagascar sourcing infrastructure to secure consistent flower harvests. Symrise AG anchors its position through integrated distillation partnerships with Comorian cooperatives. Robertet Group differentiates via proprietary low-temperature extraction protocols that preserve volatile ester profiles.
Ylang ylang extract comprises essential oil and absolute fractions derived from Cananga odorata flowers through steam distillation or solvent extraction, with linalool and geranyl acetate constituting the principal aromatic compounds responsible for its sweet-floral odor character. Steam distilled grades dominate commercial volume due to lower production cost and broader cosmetic formulation compatibility, while CO2 extract commands premium positioning in high-end aromatherapy applications where supercritical fluid processing yields cleaner terpene profiles. The cosmetics application segment sustains the largest value share as formulators incorporate ylang ylang oil into skin and hair care products for both fragrance and purported sebum-balancing properties.
EMA botanical drug guidelines and EU REACH substance registration requirements impose rigorous documentation burdens on European importers of ylang ylang extract, while FDA cosmetic ingredient safety assessments shape compliance expectations for products entering the United States. Madagascar's national essential oils quality standards and organic certification protocols administered by Ecocert influence export eligibility for distillers serving French and German buyers. Stakeholders must monitor evolving pesticide residue thresholds and geolocation traceability mandates that will determine which origin suppliers retain market access.
Market Dynamics
ISO 9235 certification requirements for natural aromatic raw materials are forcing distillers to abandon fragmented sourcing networks and invest in traceable supply chains, reshaping competitive viability across the ylang ylang extract sector.
Growth Catalysts
- EU REACH substance registration:Compliance mandates are filtering out non-compliant suppliers, creating market share openings for certified distillers in Madagascar and the Comoros Islands.
- Premium cosmetics formulators:French and United States beauty brands are expanding certified organic procurement for fragrance portfolios, pulling volume through validated channels.
- Steam distillation infrastructure:Lower processing costs versus solvent extraction are enabling broader cosmetic formulation compatibility and volume scalability.
Market Restraints
- Raw material concentration risk:Over 80% of Cananga odorata flower supply originates from Madagascar and the Comoros Islands, exposing buyers to climate and political disruption.
- Input cost volatility:Organic certification and pesticide residue testing requirements are elevating compliance costs for smallholder cooperative distillers.
- Substitution pressure:Synthetic linalool and geranyl acetate compounds are capturing mid-market fragrance applications where natural provenance carries less premium.
Strategic Opportunities
- CO2 extraction technology:Supercritical fluid processing yields cleaner terpene profiles for high-end aromatherapy segments willing to pay certification premiums.
- Ecocert organic protocols:German and French buyer eligibility requirements are creating first-mover advantages for cooperatives achieving dual organic-traceable certification.
- Direct distiller-brand partnerships:Bypassing traditional commodity brokers allows capture of margin previously lost to opaque trading layers.
Industry Challenges
- Geolocation traceability implementation:Mapping smallholder plots to export batches requires capital investment in digital tagging systems that strain cooperative balance sheets.
- Skilled distiller scarcity:Traditional steam distillation expertise for preserving volatile ester profiles is concentrated among aging practitioners in the Comoros Islands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ylang Ylang Extract Market |
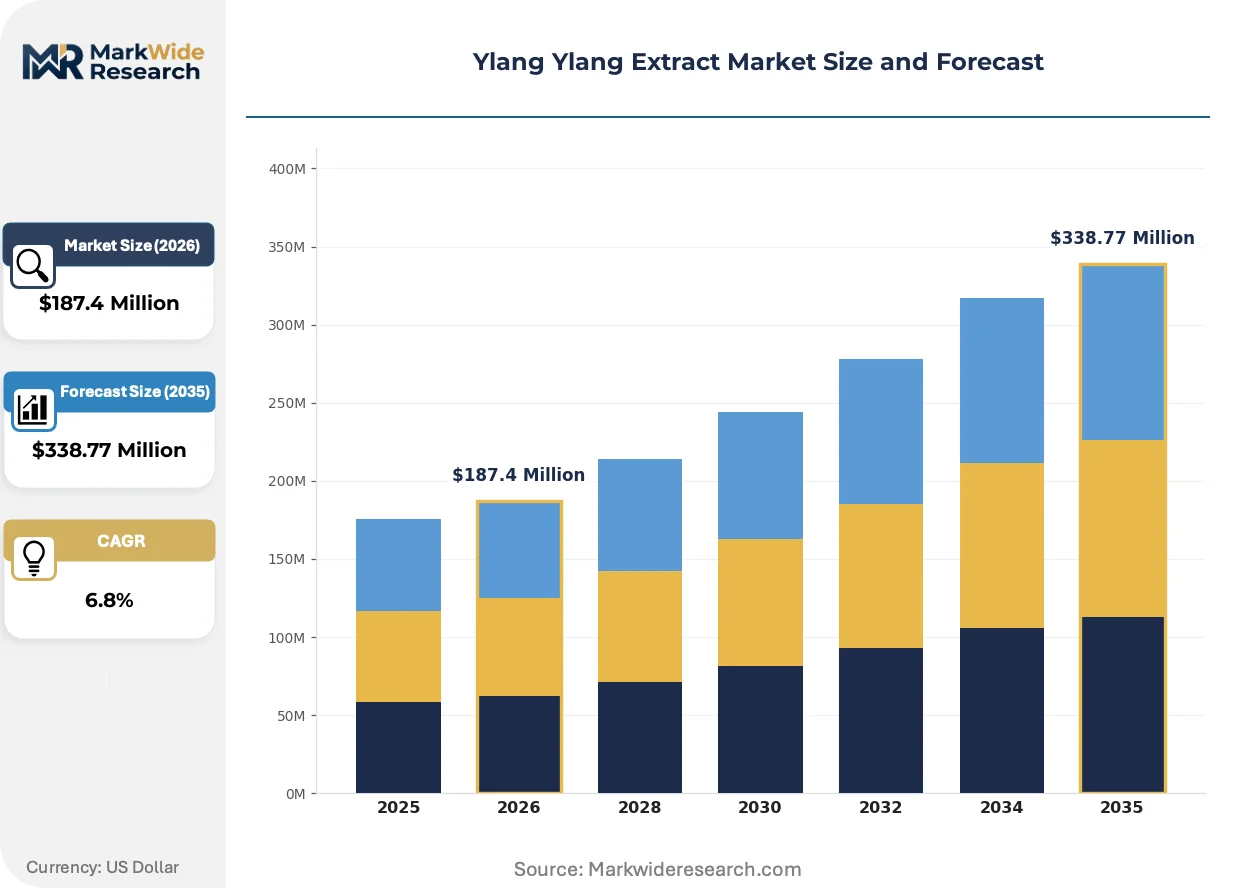
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steam Distilled, Solvent Extract, CO2 Extract, Absolute Application: Cosmetics, Aromatherapy, Flavoring, Pharmaceuticals Form: Oil, Powder, Liquid, Solid, Concentrate Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Distributors |
| Companies Covered | Albert Vieille SAS, Givaudan SA, Symrise AG, Mountain Rose Herbs, Natura-Tec, Young Living Essential Oils, Robertet Group, Plant Therapy, doTERRA International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ylang Ylang Extract Market Evolving Landscape
Processing technology and procurement transparency are converging to redefine value capture in ylang ylang extract, with certification systems and extraction methods determining which suppliers retain access to premium cosmetic and aromatherapy channels.
Supercritical CO2 extraction is displacing conventional solvent-based absolute production in high-end fragrance applications. Niche aromatherapy brands and luxury cosmetic houses are adopting CO2-derived grades despite 40-60% cost premiums. The technology is displacing hexane-extracted absolutes in formulations where residual solvent concerns drive consumer rejection.
EMA botanical drug guidelines are tightening documentation burdens on European importers of ylang ylang extract. The framework requires comprehensive substance characterization and stability data that many Madagascar-based distillers cannot currently supply. French and German cosmetic ingredient distributors are responding by pre-qualifying smaller supplier pools and absorbing compliance costs through exclusive sourcing agreements.
Certification-driven procurement is compressing supplier selection cycles among premium cosmetics formulators. Beauty brands are replacing spot-market purchasing with multi-year contracts tied to Ecocert and ISO 9235 validation. France and the United States exhibit the most pronounced shift, where procurement teams now exclude non-certified origins from fragrance development pipelines entirely.
Ylang Ylang Extract Market Segmentation
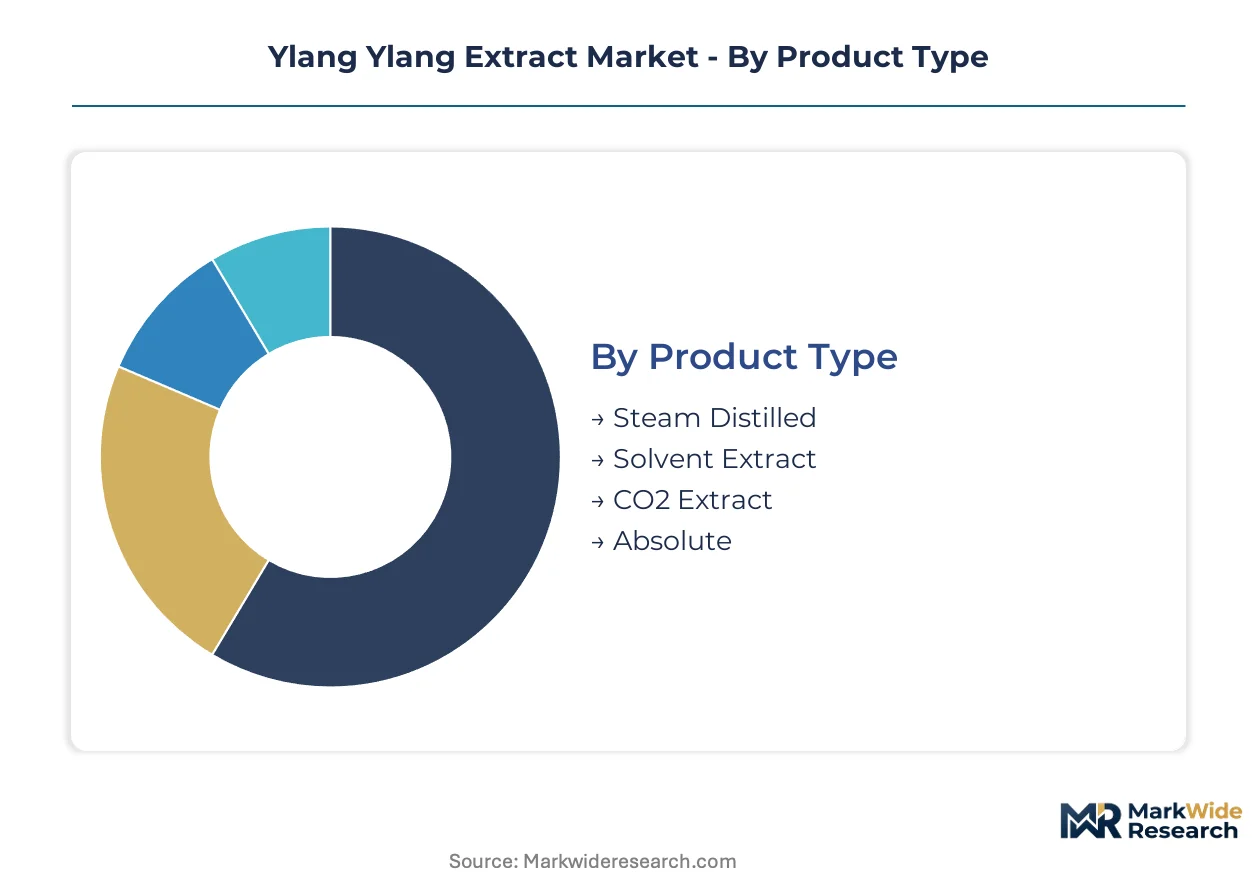
Certification requirements and extraction technology costs are fragmenting the ylang ylang extract market into sharply tiered segments. Formulators now select grades based on traceability documentation rather than aroma profile alone.
Product Type:
Synthetic linalool and geranyl acetate substitutes exert the strongest pressure on commodity-grade segments where natural provenance commands minimal premium.
- Steam Distilled:The dominant commercial grade produced through hydrodistillation of Cananga odorata flowers. Steam distilled oil concentrates demand from mass-market cosmetic manufacturers in France and the United States due to formulation compatibility and cost efficiency. Compliance with ISO 9235 certification requirements is filtering supplier pools and elevating procurement costs for uncertified origins.
- CO2 Extract:Supercritical fluid extraction yields terpene profiles free from thermal degradation. Premium aromatherapy brands in Germany absorb 40-60% cost premiums for CO2 grades where residual solvent concerns drive consumer rejection of conventional absolutes. The technology captures margin in therapeutic applications requiring documented purity.
- Solvent Extract:Hexane-based extraction produces absolutes for fine fragrance compounding. Madagascar distillers face margin compression from rising organic certification and pesticide residue testing costs.
- Absolute:Highly concentrated aromatic material obtained through multi-stage solvent extraction. Luxury perfume houses specify absolutes for fixative properties in high-end formulations.
Steam distilled grades anchor the volume base while CO2 extract gains share at the steepest rate.
Application:
Cost tier stratification separates pharmaceutical-grade documentation requirements from commodity fragrance applications.
- Cosmetics:Skin and hair care formulators incorporate ylang ylang oil for fragrance and sebum-balancing properties. EMA botanical drug guidelines and FDA cosmetic ingredient safety assessments impose documentation burdens that pre-qualify smaller supplier pools in Madagascar and the Comoros Islands.
- Aromatherapy:Therapeutic-grade specifications demand supercritical CO2 processing and Ecocert organic validation. German and French distributors absorb compliance costs through exclusive sourcing agreements with certified cooperatives.
- Flavoring:Food-grade extracts require additional safety testing for oral exposure applications. Madagascar's national essential oils quality standards influence export eligibility for distillers serving European buyers.
- Pharmaceuticals:Botanical drug applications demand comprehensive substance characterization and stability data. Many Comorian cooperatives cannot currently supply EMA-mandated documentation without distributor intermediation.
Cosmetics applications generate the largest revenue concentration while aromatherapy climbs the fastest on certification premiums.
Form:
Volume scale separates industrial concentrate procurement from artisanal oil retail formats.
- Oil:The standard commercial format for cosmetic formulation and aromatherapy diffusion. Oil concentrates procurement from premium beauty brands requiring Ecocert and ISO 9235 validation.
- Liquid:Pre-diluted preparations for direct consumer application. Liquid formats expand accessibility in online retail channels serving home-use aromatherapy segments.
- Concentrate:High-potency extracts for industrial fragrance compounding. Concentrate demand concentrates among Givaudan SA and Symrise AG for captive formulation use.
- Powder:Encapsulated formats for solid cosmetic applications. Powder processing requires additional capital investment that strains cooperative balance sheets.
- Solid:Wax-based or resinous preparations for niche ritual and spa applications. Solid formats capture minimal commercial volume relative to fluid extracts.
Oil dominates procurement volumes while concentrate formats expand most quickly among integrated fragrance houses.
Distribution Channel:
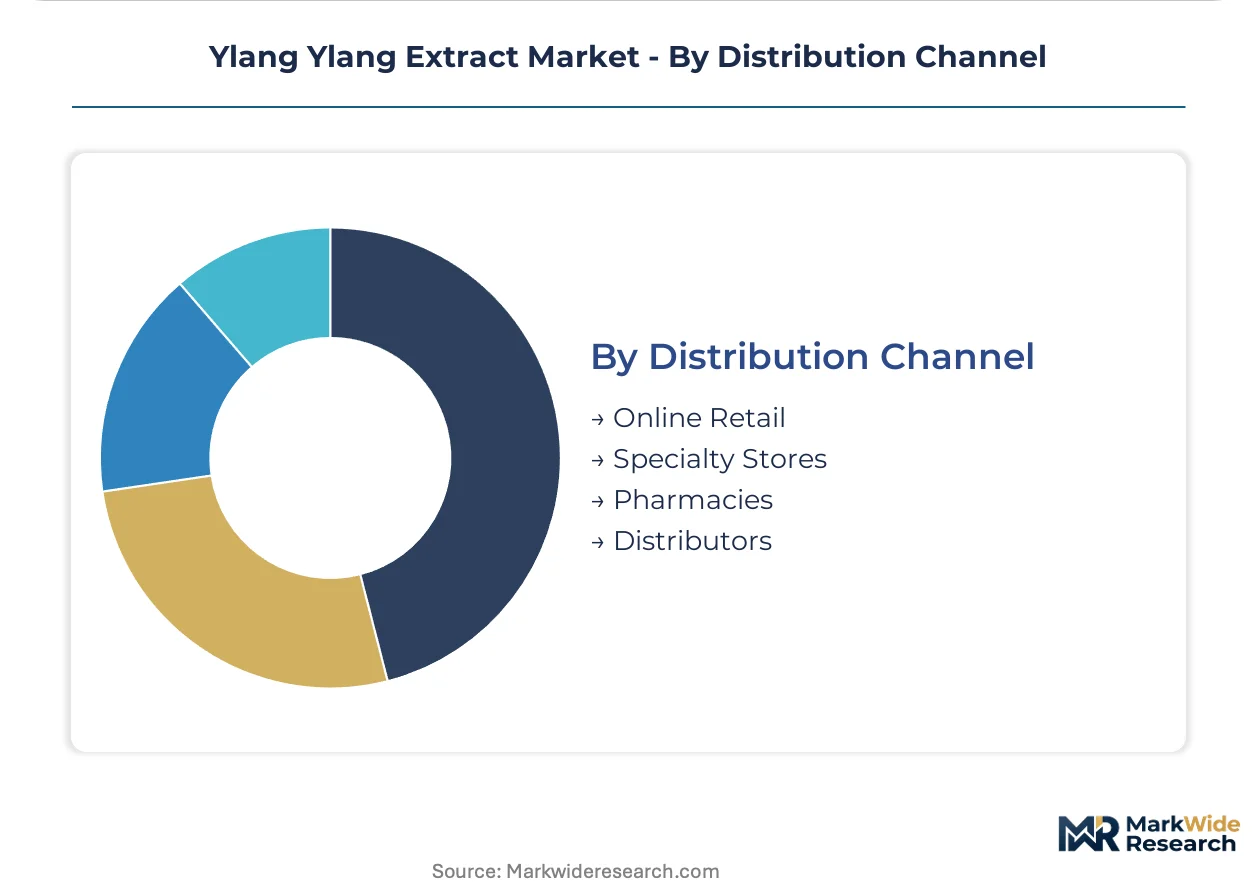
Customer type bifurcation separates bulk industrial procurement from authenticated retail purchase.
- Distributors:Commodity brokers traditionally intermediated between Comorian cooperatives and European formulators. Certification-driven procurement is compressing distributor relevance as brands pursue direct distiller partnerships.
- Specialty Stores:Boutique retailers serving aromatherapy practitioners and natural cosmetics consumers. Specialty channels validate provenance through Ecocert and organic certification display.
- Online Retail:E-commerce platforms enable traceable supply chain storytelling for certified origins. Online channels expand access for Madagascar-based distillers bypassing traditional commodity layers.
- Pharmacies:Regulated retail for therapeutic-grade extracts meeting pharmaceutical documentation standards. Pharmacy eligibility requires stability data that many origin suppliers cannot independently supply.
Distributors retain bulk volume flows while online retail expands most rapidly on direct-to-consumer authentication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium cosmetics formulators in France and the United States concentrate procurement of certified organic ylang ylang extract, while Madagascar and the Comoros Islands anchor raw material supply through Cananga odorata cultivation clusters.
France
Paris-based fragrance houses drive demand for Ecocert-validated organic grades. ANSM cosmetic ingredient oversight aligns with EU REACH substance registration requirements. Grasse perfume manufacturing cluster integrates direct sourcing partnerships with Comorian cooperatives for traceable supply chains.
United States
FDA cosmetic ingredient safety assessments shape compliance expectations for ylang ylang oil entering skin and hair care formulations. Premium beauty brands in New York and Los Angeles mandate ISO 9235 certification for fragrance development pipelines. Direct-to-consumer aromatherapy retailers expand online channels for authenticated organic origins.
Germany
Therapeutic-grade aromatherapy distributors absorb compliance costs through exclusive sourcing agreements with certified Madagascar distillers. EMA botanical drug guidelines impose documentation burdens that pre-qualify smaller supplier pools. Hamburg and Frankfurt trading hubs intermediate between origin cooperatives and European formulators.
Madagascar
National essential oils quality standards and organic certification protocols administered by Ecocert influence export eligibility for distillers serving French and German buyers. Antalaha and Sambava cultivation zones concentrate Cananga odorata flower harvesting. Climate vulnerability and infrastructure gaps challenge consistent volume delivery.
Comoros Islands
Traditional steam distillation expertise for preserving volatile ester profiles concentrates among aging practitioners on Anjouan and Grande Comore islands. Skilled distiller scarcity threatens output quality consistency. Integrated distillation partnerships with European fragrance houses provide capital for organic certification compliance.
Ylang Ylang Extract Market Competitive Landscape
Player mix skews toward integrated fragrance houses with captive sourcing infrastructure and specialty botanical extractors with proprietary processing protocols. Market structure consolidates around three strategic archetypes: Madagascar-based distillers with direct cooperative relationships, European fragrance houses with backward integration into origin supply chains, and North American direct-to-consumer wellness brands with certified organic positioning. Dominant competitive moves include exclusive multi-year procurement contracts tied to certification validation and technology licensing for supercritical CO2 extraction capabilities.
Within the integrated fragrance house tier, Givaudan SA and Symrise AG exemplify archetypes leveraging origin infrastructure for supply security. Robertet Group occupies a position representing proprietary low-temperature extraction specialists. Among North American wellness-focused operators, Young Living Essential Oils and doTERRA International sit within the direct-to-consumer certified organic segment. Albert Vieille SAS anchors the French botanical extraction tradition. These named entities collectively illustrate how certification compliance and sourcing control separate viable competitors from marginal suppliers.
| Leading Market Players |
|---|
| Albert Vieille SAS |
| Givaudan SA |
| Symrise AG |
| Mountain Rose Herbs |
| Natura-Tec |
| Young Living Essential Oils |
| Robertet Group |
| Plant Therapy |
| doTERRA International |
| Others |
Value Network & Pricing Analysis
Smallholder cooperative capacity utilization in Madagascar and the Comoros Islands anchors cost structures across steam distillation grades, compressing margins for uncertified origins while elevating price floors for Ecocert-validated supply. This scale concentration funnels procurement power toward integrated fragrance houses with backward integration into origin infrastructure, forcing commodity brokers to absorb compliance cost inflation or exit.
Pricing Analysis
Cost-plus contracts indexed to organic certification and pesticide residue testing thresholds dominate procurement between European fragrance houses and Comorian cooperatives. Three-tier pricing structure across premium CO2 extract, standard steam distilled, and economy solvent grades reflects certification tier and extraction technology cost differentials. Price compression runs through commodity solvent grades as synthetic linalool substitutes capture mid-market fragrance applications. Mass-market cosmetic manufacturers exhibit highest price sensitivity, while German therapeutic-grade distributors absorb premiums for documented purity.
Supply Chain Analysis
Madagascar and the Comoros Islands anchor global Cananga odorata flower harvesting, with Antalaha and Sambava cultivation zones feeding distillation infrastructure. Supply rests on aged steam distillation expertise concentrated among practitioners on Anjouan and Grande Comore, with no pipeline of skilled replacements. Single-source vulnerability intensifies as climate disruption threatens consistent volume delivery from origin islands. Distribution runs through exclusive multi-year contracts tying certified cooperatives to Givaudan SA and Symrise AG sourcing infrastructure, compressing traditional commodity broker relevance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification-as-a-service layers expand faster than raw extract throughput, with Ecocert validation and geolocation traceability emerging as recurring-revenue attachments that capture margin from compliance-uncertain buyers.
For Market Incumbents: Fortify captive supply chains through direct distiller partnerships in Madagascar that bypass opaque trading layers, while accelerating ISO 9235 certification pre-qualification to defend against synthetic substitute encroachment in mid-market fragrance tiers. Capacity addition in Sambava cultivation zones with integrated organic certification infrastructure represents the priority defensive lever against origin supply disruption. For New Entrants and Emerging Players: Documentation service gaps where Madagascar-based distillers cannot independently supply EMA-mandated stability data present white-space entry points. Target pharmaceutical-grade botanical drug applications with distributor intermediation models that absorb compliance burdens, leveraging exclusive sourcing agreements with aging Comorian practitioners before expertise scarcity accelerates. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors supercritical CO2 extraction specialists with proprietary terpene preservation protocols and established German aromatherapy distribution. Long-term viability across the projection horizon hinges on traceability technology integration rather than commodity volume scale. The signal to watch is geolocation mandate enforcement tightening that would strand non-compliant origin suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Ecocert Organic Certification Program | Dual organic-traceable validation secures French and German buyer eligibility against REACH compliance filtering. |
| Supercritical CO2 Extraction Scale-Up | Cleaner terpene profiles command 40-60% premiums in German therapeutic-grade aromatherapy channels. |
| Direct Distiller-Brand Partnership | Bypassing commodity brokers captures margin previously lost to opaque trading layers in Madagascar-France corridors. |
| Geolocation Traceability Implementation | Digital tagging systems satisfy emerging EU mandates that will determine which origin suppliers retain market access. |
| Skilled Distiller Apprenticeship Pipeline | Preserving volatile ester expertise on Anjouan protects output quality consistency against practitioner aging. |
Research Methodology
Operator-level perspectives from distillation cooperative managers, Ecocert certification auditors, fragrance house procurement directors, and German aromatherapy distributors anchored the qualitative base for this study. Primary field engagement with Madagascar-based distillers and Comorian practitioners combined with secondary validation from EU REACH registration databases, EMA botanical drug guideline filings, and organic certification protocol documentation. Customs trade data for essential oil exports and SEC filings from integrated fragrance houses provided demand-side triangulation against bottom-up supply estimates from origin cultivation surveys.
Sensitivity analysis across certification compliance scenarios, climate disruption probabilities, and synthetic substitution rates informed the analytical framework. Segmentation dimensions modeled include extraction technology tier, application end-use, certification status, and regional regulatory cluster. CAGRs were derived from volume trajectory reconciliation against value capture patterns in premium versus commodity grades. Forecast inputs incorporated organic certification cost inflation curves and skilled distiller replacement timelines.
Underlying assumptions cover sustained EU REACH enforcement intensity and Madagascar infrastructure stability, with deviation risk concentrated in climate-driven harvest volatility and EMA documentation requirement acceleration. Recalibration cycles align with material shifts in pesticide residue threshold revisions and geolocation traceability mandate implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Citrus-Based Sugar-Reduction Flavor Modulators Market
Flavorings and Food Additives
Italy Food Colorants Market
Flavorings and Food Additives
Hops Essential Oil Market
Flavorings and Food Additives
Cocoa Extract Market
Flavorings and Food Additives
Synthetic Food Colors Market
Flavorings and Food Additives
Cholic Acid Market
Flavorings and Food Additives
South America Flavors and Fragrances Market
Flavorings and Food Additives
Menthol Market
Flavorings and Food Additives
Global Ginger Extract Market
Flavorings and Food Additives
Flavor and Flavor Enhancers Market
Flavorings and Food Additives
Russia Food Flavor and Enhancer Market
Flavorings and Food Additives
Bitter Apricot Extract Market
Flavorings and Food Additives
Liquid Flavors Market
Flavorings and Food Additives
Global Natural Food Colorants Market
Flavorings and Food Additives
Cheese Flavor Market
Flavorings and Food Additives
Asia-Pacific Food Flavor Market