
 Food Processing Uniforms Market | 2026-2036
Food Processing Uniforms Market Size, Share, and Industry Trends Forecast 2026-2036
Food Processing Uniforms Market Analytics
Rental and managed uniform programs is pivoting the commercial model from transactional garment sales to recurring service revenue. Cintas Corporation controls extensive North American route-based logistics for industrial laundry and garment replenishment. Aramark leverages its institutional foodservice footprint to bundle uniform provisioning with facility management contracts. Chef Works specializes in chef jackets and culinary apparel for front-of-house and back-of-house hybrid environments.
Food processing uniforms are engineered garments designed to prevent biological and physical contamination during food handling, typically constructed from tightly woven cotton-polyester blends or fluid-resistant synthetics with sealed seams and minimal pocketing. These garments must withstand industrial laundering at temperatures exceeding 160°F while maintaining dimensional stability and colorfastness through hundreds of cycles. Coveralls and smocks lead volume demand in protein and dairy processing facilities where full-body coverage requirements are strictest. Blended fabrics are displacing pure cotton in high-throughput operations because polyester content improves stain release and reduces drying energy. Water-resistant and stain-resistant finishes command premium positioning as processors face intensified customer audit protocols.
FDA regulations under the Food Safety Modernization Act mandate preventive controls for human food, directly influencing uniform design specifications for allergen control and pathogen barrier performance. OSHA workplace safety standards and state-level health department codes further shape garment visibility, slip resistance, and thermal protection requirements in cold storage environments. Stakeholders should monitor how third-party audit standards from SQF and BRCGS evolve their personal protective equipment clauses, as these private certifications increasingly determine supplier qualification beyond baseline regulatory compliance.
Market Dynamics
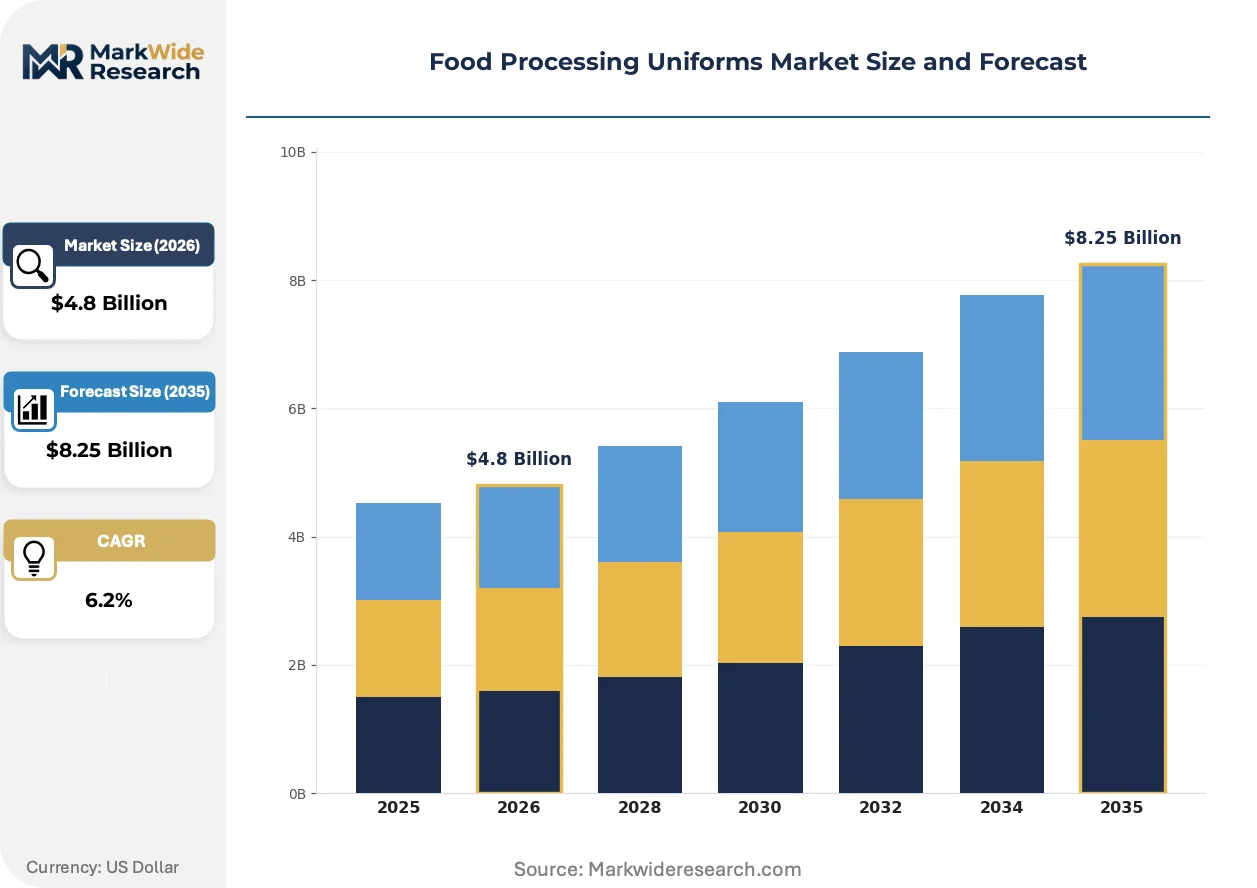
Rental and managed uniform programs are restructuring commercial relationships in food processing apparel, converting one-time garment transactions into recurring service revenue anchored by industrial laundry logistics and compliance monitoring.
Growth Catalysts
- FDA Food Safety Modernization Act:Preventive control mandates for human food production are tightening specifications for allergen barrier performance and pathogen containment in garment design.
- Polyester-cotton blends:Fabric engineering advances are improving stain release properties and reducing industrial drying energy consumption in high-throughput protein processing facilities.
- Midwest protein processing clusters:Geographic concentration of large-scale slaughter and further-processing operations in Nebraska, Iowa, and Kansas is driving volume procurement of coveralls and smocks.
Market Restraints
- Petrochemical feedstock volatility:Polyester content dependence exposes fabric costs to crude oil price swings, compressing margin stability for synthetic garment producers.
- Industrial laundering infrastructure concentration:Route-based service networks cluster in metropolitan corridors, leaving rural processing plants underserved for managed uniform programs.
- Sealed seam durability limitations:Current heat-sealing technologies degrade after repeated 160°F wash cycles, forcing premature garment replacement in dairy sanitation environments.
Strategic Opportunities
- Ready-to-eat meal manufacturing expansion:Prepared foods sector growth is opening uniform procurement programs at co-packers and central kitchens requiring HACCP-aligned apparel.
- SQF and BRCGS audit integration:Third-party certification schemes are embedding personal protective equipment clauses that exceed baseline regulatory compliance, creating premium positioning for audit-ready suppliers.
- Antimicrobial fiber convergence:Silver-ion and copper-infused yarn technologies are converging with fluid-resistant synthetics to address extended-wear requirements in cold storage operations.
Industry Challenges
- Industrial laundry technician shortage:Specialized knowledge of HACCP-validated wash chemistry and temperature monitoring is scarce in regional service operations.
- Multi-standard certification complexity:Simultaneous compliance with OSHA workplace safety, state health department codes, and customer audit protocols extends qualification timelines for new garment suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Processing Uniforms Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aprons, Lab Coats, Coveralls, Chef Jackets Material: Cotton, Polyester, Blended Fabrics, Nylon End User: Food Manufacturers, Restaurants, Catering Services, Bakeries Feature: Water-Resistant, Stain-Resistant, Breathable, Lightweight |
| Companies Covered | Chef Works, Cintas Corporation, Aramark, Bragard Uniforms, Aussie Chef, 3M Co., Alsico, Carhartt, VF Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Processing Uniforms Market Evolving Landscape
Smart textile integration and service-based commercial models are reconfiguring how food processors source, maintain, and track protective apparel across their operations.
Embedded RFID tracking is modularizing uniform lifecycle management for large protein processors. JBS and Tyson Foods pilot programs are tagging individual garments to monitor wash cycle counts and contamination exposure. This technology is modularizing inventory control, compressing loss rates and enabling predictive replacement scheduling.
REACH chemical restrictions in the European Union are phasing out per- and polyfluoroalkyl substances in stain-resistant fabric finishes. The industrial consequence is accelerated development of silicone-based and bio-based alternatives that maintain hydrophobic performance. German dairy cooperatives and Dutch poultry processors are most affected, demanding reformulated garment specifications from their suppliers.
Consolidated procurement at national foodservice distributors is compressing supplier margins while expanding volume commitments. Sysco and US Foods are bundling uniform provisioning with broadline food and equipment contracts, displacing direct mill relationships for regional processors. This pattern is most visible in the Southeast, where institutional foodservice penetration into healthcare and education channels drives bundled sourcing decisions.
Food Processing Uniforms Market Segmentation
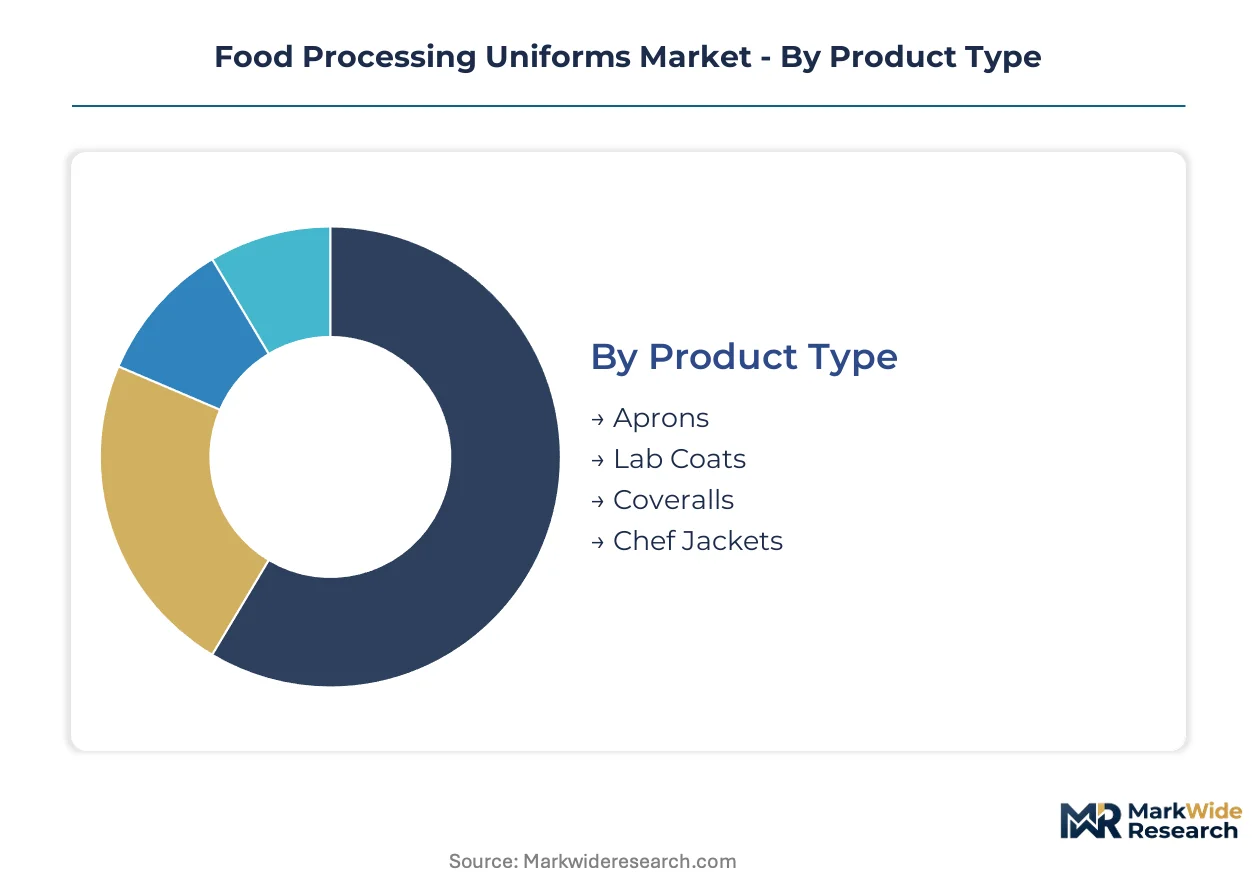
Uniform specification varies sharply across food processing environments, with protein processors demanding full-body barrier protection while front-of-house operations prioritize visual presentation. Segmentation reveals how fabric engineering, end-use contamination risk, and regulatory exposure shape procurement decisions and supplier margins.
Product Type:
Capital intensity escalates dramatically with garment complexity and coverage area, from simple waist aprons to sealed-seam coveralls requiring specialized manufacturing equipment.
- Coveralls:One-piece garments with sealed seams and minimal pocketing dominate protein and dairy facilities where pathogen barrier requirements are strictest. Nebraska and Iowa slaughterhouses drive volume procurement of industrial-grade coveralls engineered for 160°F wash cycles.
- Chef Jackets:Double-breasted cotton or cotton-poly constructions with knotted buttons serve back-of-house and front-of-house hybrid environments where visual standards compete with spill protection. Ready-to-eat meal manufacturers are expanding jacket procurement for central kitchen operations.
- Aprons:Waist and bib styles offer lower-cost entry points for bakeries and light processing tasks.
- Lab Coats:Knee-length coats serve quality control and R&D functions in food manufacturing plants.
Coveralls absorb the bulk of installed capacity; chef jackets are expanding most quickly.
Material:
Raw material selection determines laundering durability, energy consumption, and compliance with evolving chemical safety standards.
- Blended Fabrics:Cotton-polyester combinations between 65/35 and 80/20 ratios balance absorbency with stain release performance. High-throughput protein processors in Kansas and the Southeast are displacing pure cotton to reduce drying energy and extend garment life.
- Polyester:100% synthetic constructions offer superior fluid resistance and dimensional stability through industrial laundering. REACH restrictions on perfluoroalkyl substances are forcing reformulation of stain-resistant polyester finishes in EU-serving suppliers.
- Cotton:Natural fiber retains preference in artisan baking and premium culinary applications.
- Nylon:Lightweight strength suits disposable or limited-use protective layers.
Blended fabrics command the largest production footprint; polyester is climbing the fastest as fluid-resistant specifications tighten.
End User:
Customer scale and compliance exposure create divergent procurement patterns, from national managed programs to single-location purchases.
- Food Manufacturers:Large-scale processors operate under FDA Food Safety Modernization Act preventive controls and third-party audit schemes. JBS and Tyson Foods pilot RFID tracking programs to monitor garment lifecycle and contamination exposure.
- Restaurants:Full-service and quick-service chains bundle uniform provisioning with broadline distribution contracts. Sysco and US Foods compress supplier margins while expanding volume commitments in the Southeast.
- Catering Services:Event-based and institutional caterers face intermittent demand spikes and hybrid front-of-house requirements.
- Bakeries:Flour dust exposure and lower pathogen risk drive preference for breathable cotton constructions.
Food manufacturers absorb the bulk of installed capacity; catering services are gaining share fastest as institutional foodservice penetrates healthcare and education channels.
Feature:
Performance finishes command premium positioning as customer audit protocols intensify and chemical safety regulations evolve.
- Stain-Resistant:Hydrophobic surface treatments reduce cross-contamination risk and extend visual acceptability between washes. ECHA REACH phase-out of per- and polyfluoroalkyl substances is accelerating silicone-based and bio-based alternative development.
- Water-Resistant:Fluid barrier properties protect against hot liquid splash and biological contamination in slaughter and further-processing operations.
- Breathable:Moisture vapor transmission rates become critical in hot kitchen environments and extended-wear cold storage operations.
- Lightweight:Reduced garment mass improves worker mobility and reduces heat stress in high-temperature processing areas.
Stain-resistant finishes absorb the bulk of premium positioning investment; breathable constructions are expanding most quickly as antimicrobial fiber convergence addresses extended-wear requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in textile manufacturing centers while consumption gravitates toward protein processing clusters and institutional foodservice corridors. The United States absorbs the largest procurement volumes, though Germany and China anchor manufacturing supply for export markets.
United States
Midwest slaughterhouses in Nebraska, Iowa, and Kansas drive bulk procurement of industrial coveralls engineered for 160°F wash cycles. FDA Food Safety Modernization Act preventive controls mandate allergen barrier specifications that exceed baseline OSHA requirements. Georgia and North Carolina poultry processing corridors are expanding managed uniform program adoption as third-party audit protocols intensify.
Germany
Dairy cooperatives and meat processors in Bavaria and Lower Saxony command premium-grade garments with REACH-compliant stain-resistant finishes. ECHA restrictions on per- and polyfluoroalkyl substances are accelerating silicone-based alternative development among fabric finishers. The Ruhr industrial corridor hosts concentrated industrial laundry infrastructure serving cross-border Dutch and Belgian processors.
China
Export-oriented garment manufacturing in Guangdong and Zhejiang provinces supplies blended fabric coveralls to North American and European processors. Domestic food safety regulators under SAMR are aligning facility hygiene standards with ISO 22000, lifting uniform specifications for cold-chain logistics and central kitchens. Yangtze River Delta meat and seafood processors are piloting antimicrobial fiber integration.
Brazil
Beef and poultry exporters in São Paulo and Paraná states face intensified EU and US customer audit requirements for personal protective equipment. ANVISA sanitary surveillance protocols govern garment cleanability standards in federally inspected facilities. Southern Brazil dairy clusters are displacing pure cotton with polyester-cotton blends to reduce laundering energy costs.
India
Contract manufacturing for global brands concentrates in Tamil Nadu and Gujarat textile belts. FSSAI licensing requirements for food businesses are tightening hygiene apparel specifications for domestic quick-service restaurant chains. Maharashtra and Karnataka institutional caterers are expanding chef jacket procurement as corporate foodservice penetrates IT campuses and healthcare facilities.
Food Processing Uniforms Market Competitive Landscape
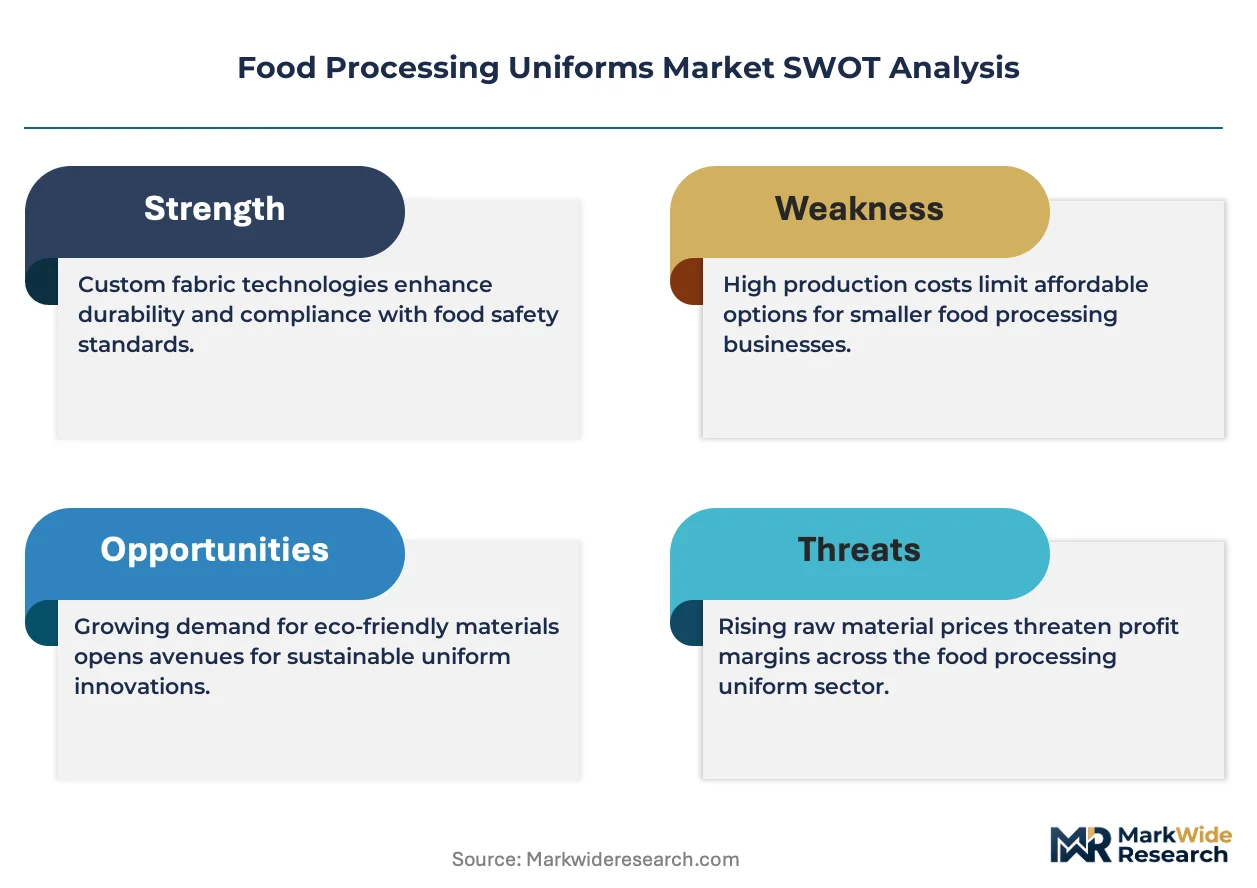
Capital-heavy producers compete with asset-light designers and service orchestrators across divergent commercial models. Route-based industrial laundry operators anchor recurring revenue streams through garment rental and compliance monitoring, while direct-sale manufacturers compete on fabric engineering and wash durability specifications. Two strategic archetypes dominate: integrated service platforms bundling logistics with garment provision, and specialized textile engineers focused on barrier performance and chemical safety compliance. Competitive moves concentrate on geographic route density expansion and antimicrobial fiber technology licensing.
Within the integrated service tier, Cintas Corporation and Aramark exemplify the rental-managed program archetype, leveraging North American logistics footprints to convert transactional garment sales into recurring facility service contracts. Chef Works occupies a position among culinary apparel specialists, anchoring front-of-house and back-of-house hybrid demand from ready-to-eat meal manufacturers and institutional foodservice operators. These three entities represent the spectrum from industrial-scale service platforms to segment-focused design houses.
| Leading Market Players |
|---|
| Chef Works |
| Cintas Corporation |
| Aramark |
| Bragard Uniforms |
| Aussie Chef |
| 3M Co. |
| Alsico |
| Carhartt |
| VF Corporation |
| Others |
Value Network & Pricing Analysis
Managed uniform program procurement by JBS, Tyson Foods, and Sysco is consolidating buyer power and forcing suppliers toward industrial laundry service bundling that compresses per-garment margins while extending contract tenors.
Pricing Analysis
Cost-down pressure on standard coveralls accelerates because Sysco and US Foods bundle uniform provisioning with broadline food contracts, displacing direct mill relationships. Three-tier pricing structure across premium, standard, and economy levels separates HACCP-validated garments with RFID tracking from basic polyester-cotton blends and entry-level cotton aprons. Price differentiation traces to certification grade and volume scale, with national food manufacturers extracting steepest discounts while regional bakeries show highest price sensitivity.
Supply Chain Analysis
Direct-to-processor channels handle hyperscale slaughterhouse demand in Nebraska and Iowa, while distributor-mediated flows serve fragmented restaurant and catering accounts. Raw cotton draws from India and the United States; polyester chips feed from China and South Korea; industrial laundry chemicals hinge on German and Belgian specialty chemical suppliers. Tariff exposure on Chinese synthetic fiber imports poses structural risk. Distribution runs through Cintas route-based networks in metropolitan corridors and Aramark facility management bundles in institutional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The food processing uniforms sector is becoming a vertical-integration race where control over industrial laundry infrastructure and antimicrobial fiber technology licensing determines margin capture.
For Market Incumbents: Deepen captive industrial laundry capacity in Midwest protein processing corridors to defend against rental-program competitors. Secure exclusive silver-ion and copper-infused yarn supply agreements before antimicrobial fiber convergence accelerates. Cintas and Aramark route density expansion represents the primary competitive threat. For New Entrants and Emerging Players: Rural dairy processors in Kansas and Wisconsin present underserved demand for HACCP-validated managed uniform programs beyond metropolitan laundry networks. Ready-to-eat meal co-packers offer penetrable entry points with hybrid front-of-house and back-of-house requirements. Lead with silicone-based stain-resistant finishes that anticipate REACH chemical restrictions. For Investors and Strategic Acquirers: The window for entry favors industrial laundry operators with established route density in protein processing clusters. Long-term viability centers on recurring service revenue conversion rather than transactional garment sales. Watch for FDA enforcement patterns on Food Safety Modernization Act preventive controls as inflection indicator for compliance-driven procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Industrial Laundry Capacity Expansion | Route density in Nebraska and Iowa slaughterhouse corridors secures recurring revenue streams against distributor bundling. |
| Antimicrobial Fiber Technology Licensing | Silver-ion yarn integration addresses extended-wear cold storage requirements at JBS and Tyson Foods pilot programs. |
| REACH-Compliant Finish Development | Silicone-based hydrophobic coatings replace perfluoroalkyl substances for German dairy cooperative supply contracts. |
| RFID Tracking Platform Integration | Predictive replacement scheduling reduces garment loss rates in large-scale protein processing facilities. |
| Backward Integration into Polyester Fiber | Captive synthetic fiber production insulates margin stability from petrochemical feedstock volatility exposure. |
Research Methodology
SEC 10-K filings, customs trade records, and FDA enforcement data formed the secondary backbone, cross-referenced with primary interviews involving industrial laundry operations directors, protein processing facility managers, foodservice distributor procurement leads, and textile chemical R&D directors. Bottom-up and top-down triangulation validated volume estimates across product type, material composition, and end-user segments.
Bottom-up modeling aggregated facility-level uniform procurement patterns by protein processing cluster density, while top-down analysis tracked broadline foodservice distributor contract disclosures. Segmentation dimensions included garment complexity tier, fabric blend ratio, contamination risk exposure level, and regional regulatory framework cluster. CAGRs were derived from elasticity-adjusted demand projections incorporating wash cycle durability specifications and managed program adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH chemical restriction timelines and industrial laundry technician shortage severity. Forecasts reflect assumptions on FDA enforcement intensity and third-party audit protocol evolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Equestrian Helmets Market
Protective Gear
Helmet Lining Market
Protective Gear
Waterproof Cases Market
Protective Gear
Military Boots Market
Protective Gear
Mobile Handset Protection Market
Protective Gear
Tactical Boots Market
Protective Gear
Waterproof Shoe Covers Market
Protective Gear
Helmets Market
Protective Gear
Safety Shoes Market
Protective Gear
Pet Control Devices Market
Protective Gear
Flavored Condoms Market
Protective Gear
Europe Protective Footwear Market
Protective Gear
Mobile Phone Protective Cover Market
Protective Gear
Combat Boots Market
Protective Gear
Heated Goggles Market
Protective Gear
Mobile Protective Cases Market