
 Flavor Emulsions Market | 2026-2036
Flavor Emulsions Market Size, Share, and Industry Trends Forecast 2026-2036
Flavor Emulsions Market Foresight
India is fragmenting as new flavor compound capacity comes online through domestic ingredient houses. Cargill Incorporated leverages its integrated supply chain from agricultural inputs to finished emulsions. Firmenich sustains technology leadership in encapsulation science for volatile aromatic stability. Gold Coast Ingredients anchors North American production with specialized bakery and confectionery emulsion portfolios.
Flavor emulsions are colloidal dispersions of immiscible liquid phases stabilized by emulsifiers and hydrocolloids, typically ranging from 0.1 to 100 micrometers in droplet diameter, engineered to deliver uniform taste release and visual stability in processed foods. Oil-in-water emulsions dominate volume as carriers for water-soluble flavor systems in soft drinks and dairy alternatives. Nanoemulsions represent the fastest-expanding product type as sub-200 nanometer droplets enable transparent beverage applications and enhanced bioavailability for nutraceutical delivery. The beverages application segment commands premium pricing due to stringent clarity and shelf-life requirements that demand advanced homogenization equipment.
FDA food additive regulations and FEMA GRAS determinations govern flavor ingredient approvals in the United States, while REACH and EU Food Information to Consumers Regulation dictate disclosure and safety thresholds across European markets. India's FSSAI standards for flavoring substances create compliance layers for imported emulsion concentrates entering processed food channels. Stakeholders must monitor evolving clean-label definitions as regulatory bodies tighten restrictions on synthetic emulsifiers and mandate front-of-pack nutritional signaling.
Market Dynamics
Beverage manufacturers are consolidating emulsion procurement around nanoemulsion technology to meet clean-label mandates while maintaining shelf stability, forcing ingredient houses to reconfigure formulation chemistry and capital deployment.
Growth Catalysts
- REACH Phase-Down Schedules:The EU F-Gas Regulation and ECHA restrictions on synthetic stabilizers accelerate replacement demand for plant-derived hydrocolloids in European beverage processing.
- Nutraceutical Infusion:Functional beverage brands adopt nanoemulsion carriers for cannabinoid and vitamin bioavailability, expanding addressable applications beyond traditional flavor delivery.
- India PLI Incentives:Domestic production-linked incentive schemes attract capital investment into flavor compound manufacturing, reducing import dependency for processed food channels.
Market Restraints
- Emulsifier Input Volatility:Gum arabic supply interruptions from Sudan and acacia sourcing constraints in the Sahel region destabilize cost structures for hydrocolloid-dependent formulations.
- Clean-Label Definition Drift:Divergent regulatory interpretations between FDA GRAS determinations and EU Food Information to Consumers Regulation create compliance fragmentation for multinational formulations.
- Homogenization Equipment Concentration:High-pressure processing technology suppliers cluster in Germany and Switzerland, creating geographic bottlenecks for capacity expansion in emerging markets.
Strategic Opportunities
- Sub-Saharan Africa:Underpenetrated carbonated soft drink and dairy alternative markets present first-mover positioning for emulsion suppliers establishing localized blending operations.
- Precision Fermentation Convergence:Integration of bioengineered lipid production with emulsion formulation enables customized carrier oils without agricultural commodity exposure.
- FSSAI Harmonization:India's alignment of flavoring substance standards with Codex Alimentarius reduces technical barriers for imported concentrate penetration into organized retail channels.
Industry Challenges
- Encapsulation Talent Scarcity:Formulation chemists with expertise in volatile aromatic stabilization remain concentrated in Swiss and French research clusters, constraining R&D scaling.
- Legacy Equipment Retrofit Costs:Dairy processors face capital intensity in upgrading homogenization lines to achieve sub-200 nanometer droplet specifications required for transparent beverage applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flavor Emulsions Market |
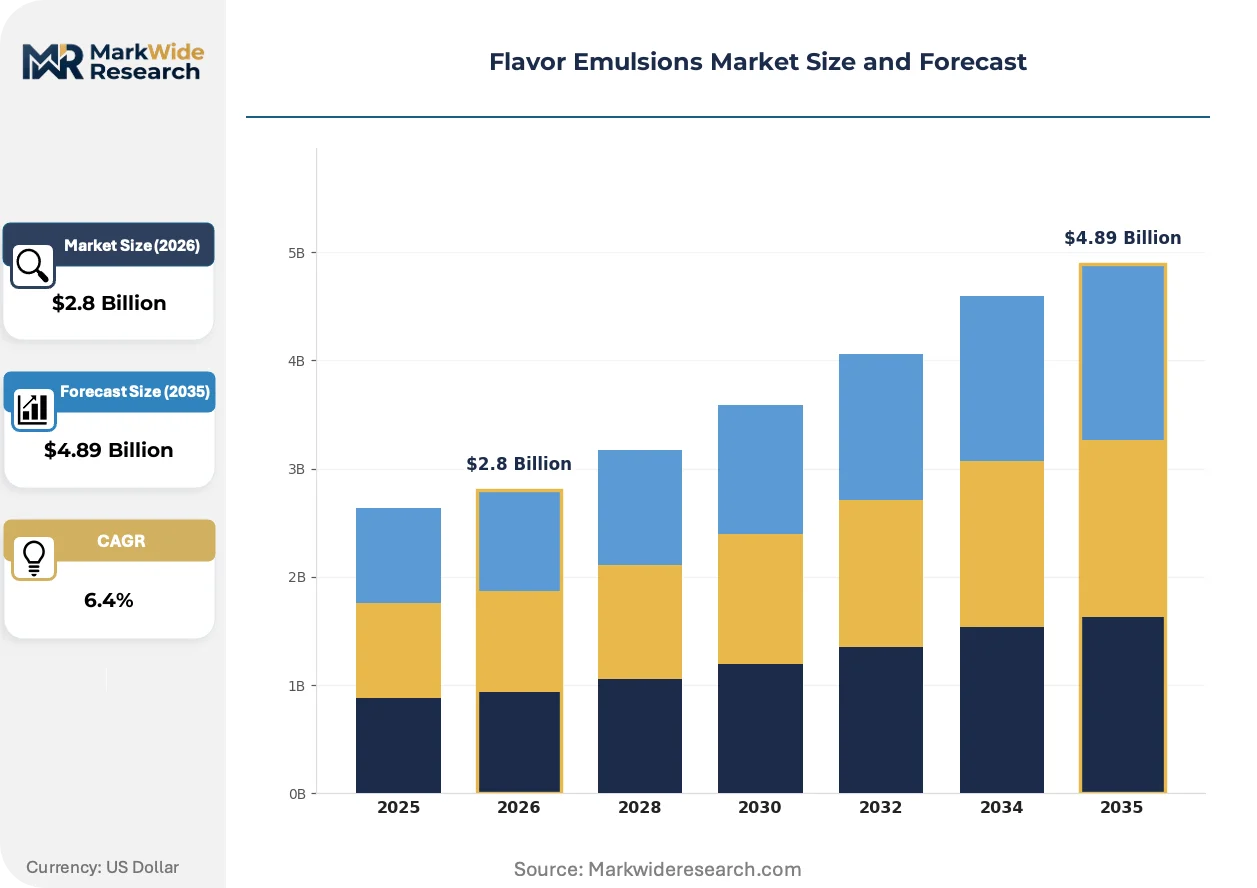
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil-in-Water, Water-in-Oil, Double Emulsions, Microemulsions, Nanoemulsions Application: Bakery, Confectionery, Beverages, Dairy Alternatives, Savory Foods, Nutraceuticals End User: Food Processors, Beverage Manufacturers, Flavor Houses, Nutraceutical Companies, Culinary Institutes Packaging Type: Bottles, Pouches, Drums, Tins, Sachets |
| Companies Covered | Cargill Incorporated, Firmenich, Gold Coast Ingredients, LorAnn Oils, Keva Flavours, FLAVAROMA, Cape Food Ingredients, Jamsons Industries, Flavorcon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flavor Emulsions Market Shifts & Advancements
Formulation science is converging with precision biotechnology to reshape how flavor compounds are stabilized, released, and labeled across beverage and confectionery applications.
High-pressure microfluidization is hybridizing with ultrasonic emulsification to achieve narrower droplet size distributions at lower energy inputs. Beverage manufacturers in Japan and South Korea are piloting these hybrid systems for clear-format functional drinks. The technology is compressing minimum efficient scale thresholds, enabling mid-tier producers to access nanoemulsion capabilities previously reserved for multinationals.
REACH authorization requirements for synthetic surfactants are tightening disclosure thresholds for emulsifier compositions in European food contact applications. Reformulation costs are diverting R&D budgets toward enzymatic esterification processes that generate label-friendly emulsifiers. Dairy alternative brands in Germany and the Netherlands face the most immediate compliance pressure, accelerating supplier audits and raw material traceability investments.
Ingredient procurement is consolidating around vertically integrated flavor houses capable of delivering encapsulated systems with certified supply chain documentation. Mid-sized beverage brands are bypassing traditional distributor networks to establish direct technical partnerships with emulsion specialists. This channel compression is most pronounced in North American craft beverage segments, where batch flexibility and rapid formulation iteration outweigh volume pricing advantages.
Flavor Emulsions Market Segmentation
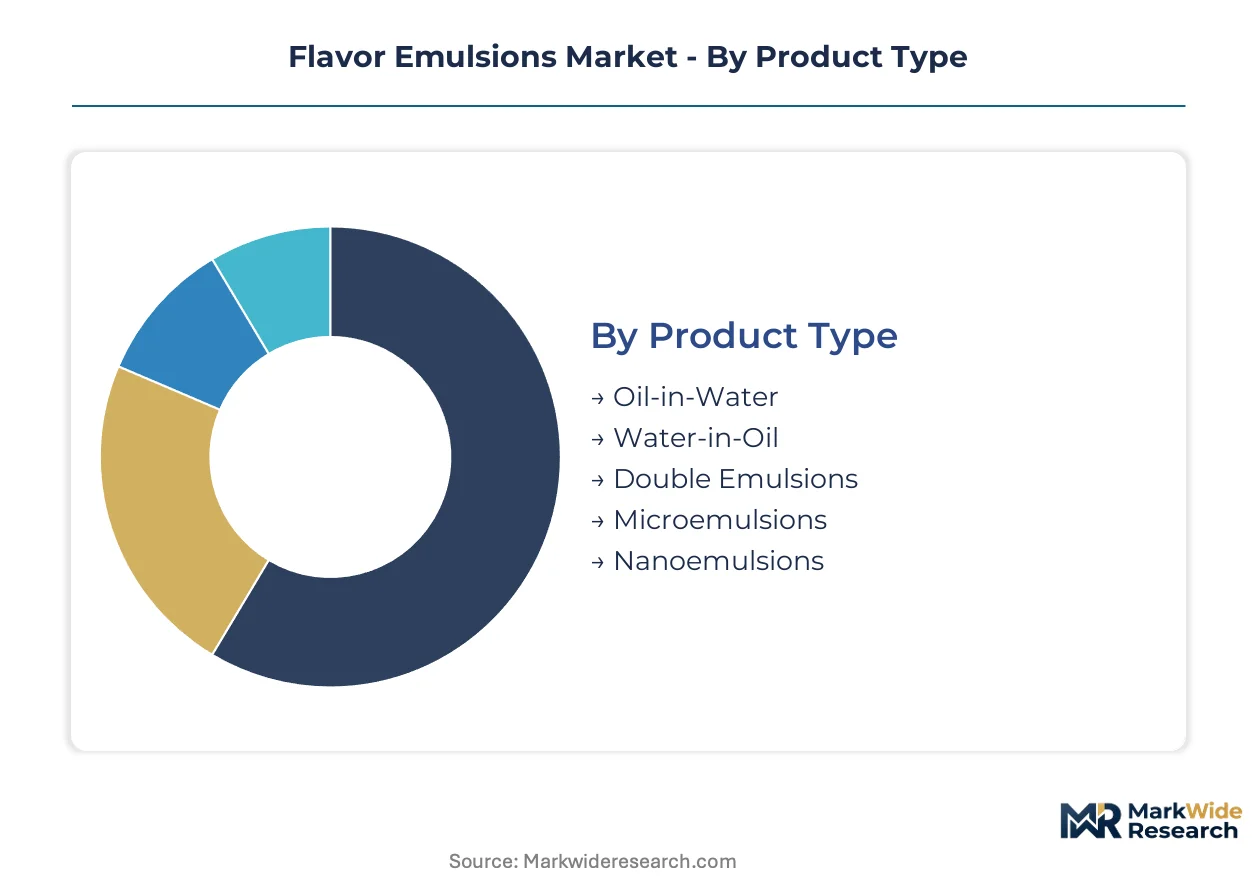
Segmentation in flavor emulsions reveals how formulation chemistry, application requirements, and procurement patterns create distinct competitive arenas. Suppliers configure capabilities around droplet size specifications, regulatory compliance thresholds, and customer technical service intensity rather than pursuing undifferentiated volume.
Product Type:
Cost tier stratification separates commodity emulsion platforms from precision-engineered nano-scale systems commanding formulation premiums.
- Oil-in-Water:These systems disperse lipophilic flavor compounds within an aqueous continuous phase using hydrocolloid stabilizers. Beverage manufacturers in India and Germany concentrate procurement here for soft drink and dairy alternative applications where clarity standards remain moderate.
- Nanoemulsions:Sub-200 nanometer droplet architectures deliver transparent beverage formats and enhanced bioavailability for functional ingredients. Japanese and South Korean functional drink brands are expanding adoption fastest as clean-label mandates tighten across Asia-Pacific markets.
- Water-in-Oil:Inverted phase systems carry hydrophilic actives into fat-based confectionery and savory coatings.
- Double Emulsions:Water-in-oil-in-water structures enable controlled release and fat reduction in processed foods.
- Microemulsions:Thermodynamically stable systems serve specialized pharmaceutical and high-clarity beverage niches.
Oil-in-Water holds installed capacity. Nanoemulsions are rotating up the share rankings.
Application:
Application segmentation tracks how shelf-stability requirements and visual clarity standards reshape procurement priorities across food processing verticals.
- Beverages:Stringent transparency specifications and extended shelf-life demands drive nanoemulsion adoption. German and Dutch dairy alternative brands face immediate REACH compliance pressure for surfactant disclosure, accelerating supplier consolidation around encapsulated systems with certified documentation.
- Confectionery:Fat-based delivery systems require water-in-oil architectures for heat-stable flavor release. Swiss and Belgian chocolate manufacturers maintain premium positioning through proprietary emulsion formulations that prevent fat bloom and flavor fade.
- Bakery:Heat-stable emulsions withstand proofing and baking temperatures without phase separation.
- Dairy Alternatives:Plant-based milk and yogurt applications demand neutral-flavored emulsion carriers compatible with oat, almond, and soy protein matrices.
- Savory Foods:Dressings, sauces, and ready meals utilize emulsions for mouthfeel modification and flavor impact.
- Nutraceuticals:Functional ingredient delivery prioritizes bioavailability enhancement over taste masking.
Beverages commands premium positioning. Dairy Alternatives is climbing the fastest as plant-based formulations proliferate.
End User:
Customer type segmentation captures divergent technical service needs between formulation-capable multinationals and specification-dependent mid-tier processors.
- Beverage Manufacturers:These buyers consolidate procurement around nanoemulsion technology to satisfy clean-label mandates while maintaining shelf stability. Direct technical partnerships with emulsion specialists are displacing traditional distributor relationships in North American craft segments.
- Flavor Houses:Integrated suppliers like Firmenich leverage encapsulation science expertise to deliver finished emulsion systems rather than raw compounds. Swiss and French research clusters concentrate formulation chemists with volatile aromatic stabilization capabilities.
- Food Processors:Mid-tier bakery and savory manufacturers purchase standardized emulsion concentrates for operational simplicity.
- Nutraceutical Companies:Cannabinoid and vitamin brands adopt nanoemulsion carriers for bioavailability claims.
- Culinary Institutes:Specialized training programs require small-batch emulsion systems for educational demonstration.
Flavor Houses control upstream formulation IP. Beverage Manufacturers are rotating up the share rankings through direct sourcing.
Packaging Type:
Volume and handling requirements segment packaging formats across industrial-scale production and artisanal batch applications.
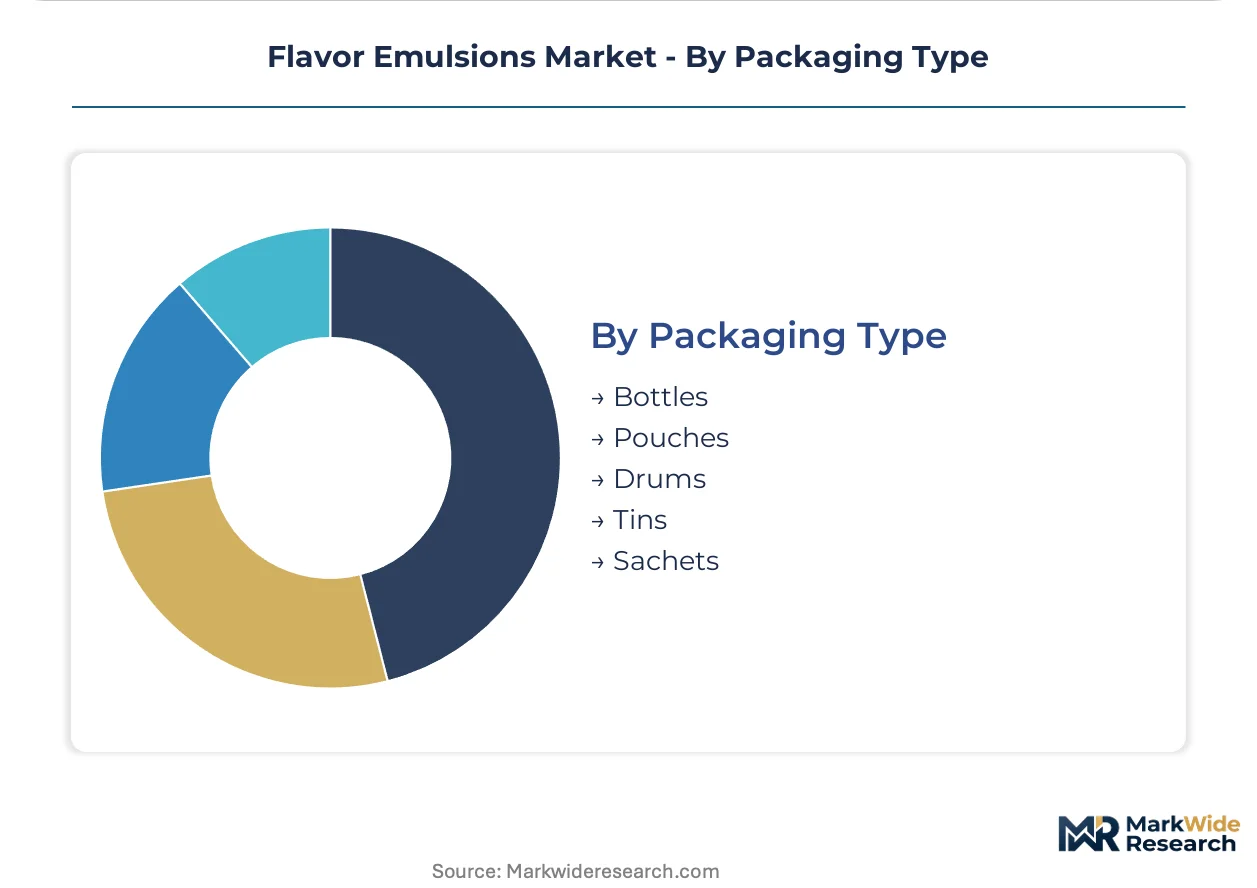
- Drums:Bulk liquid handling dominates beverage and dairy alternative manufacturing where continuous processing lines consume high volumes. German homogenization equipment suppliers configure drum-fed systems for sub-200 nanometer specifications.
- Pouches:Flexible format adoption accelerates in food service and quick-service restaurant channels seeking portion control and reduced waste. Indian organized retail expansion favors pouch formats for price-accessible emulsion concentrates.
- Bottles:Retail-ready packaging serves culinary and small-batch food processor segments.
- Tins:Metal containers protect oxygen-sensitive emulsions in traditional confectionery applications.
- Sachets:Single-serve units target institutional food service and airline catering channels.
Drums holds installed capacity. Pouches is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between beverage-dominant Western markets and processed-food-heavy emerging economies, with nanoemulsion adoption concentrated in Japan and South Korea while India and Brazil prioritize cost-optimized oil-in-water systems for soft drink manufacturing.
United States
Beverage manufacturers in California and the Pacific Northwest drive nanoemulsion procurement for transparent functional drinks. FDA GRAS determinations and FEMA safety assessments govern flavor ingredient approvals, creating compliance clarity for domestic formulators. Chicago and New Jersey host concentrated blending operations serving craft beverage segments seeking rapid formulation iteration.
Germany
Dairy alternative brands in Bavaria and North Rhine-Westphalia face immediate pressure from REACH authorization requirements for synthetic surfactants. The EU F-Gas Regulation and ECHA disclosure mandates accelerate supplier consolidation around plant-derived hydrocolloids. Hamburg anchors specialized homogenization equipment distribution serving sub-200 nanometer specification requirements.
India
Domestic soft drink and processed dairy channels absorb expanding oil-in-water emulsion capacity from new ingredient houses in Maharashtra and Gujarat. FSSAI standards for flavoring substances create compliance layers for imported concentrates entering organized retail. The PLI scheme attracts capital investment into flavor compound manufacturing, reducing import dependency.
Japan
Functional beverage brands in Tokyo and Osaka pilot hybrid high-pressure microfluidization systems for clear-format nutraceutical delivery. METI industrial standards support precision processing technology adoption. The Kansai region concentrates formulation partnerships between mid-tier producers and emulsion specialists seeking batch flexibility.
Brazil
Carbonated soft drink manufacturers in São Paulo and Minas Gerais represent underpenetrated demand for advanced emulsion stabilization. ANVISA food additive regulations shape import requirements for concentrated flavor systems. Local blending operations remain limited, creating positioning opportunities for suppliers establishing regional production.
Flavor Emulsions Market Competitive Landscape
Capability concentration sits with encapsulation science specialists; scale advantage sits with agricultural input integrators. The vendor base separates into three functional tiers: multinational flavor houses controlling upstream formulation IP, mid-sized regional blenders serving batch-flexible customers, and commodity emulsion producers competing on volume pricing. Strategic moves cluster around backward integration into hydrocolloid sourcing and direct technical partnerships displacing traditional distribution channels.
Within the multinational tier, Firmenich exemplifies the encapsulation science archetype, while Cargill Incorporated represents agricultural supply chain integration. Gold Coast Ingredients anchors North American production specialization. These three occupy distinct positioning vectors—technology leadership, input control, and regional manufacturing depth—rather than competing head-to-head for identical customer relationships.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Firmenich |
| Gold Coast Ingredients |
| LorAnn Oils |
| Keva Flavours |
| FLAVAROMA |
| Cape Food Ingredients |
| Jamsons Industries |
| Flavorcon Corporation |
| Others |
Supply & Pricing Matrix
Hamburg-Rotterdam container corridors transmit cost volatility from German homogenization equipment suppliers directly into nanoemulsion pricing tiers, while Sudanese gum arabic disruptions force beverage manufacturers to arbitrage between long-term hydrocolloid contracts and spot markets for plant-derived stabilizers.
Pricing Analysis
Long-term offtake agreements dominate procurement between multinational flavor houses and beverage manufacturers, locking in volume commitments for nanoemulsion concentrates against volatile gum arabic and acacia pricing. Three-tier pricing structure across premium encapsulation systems, standard oil-in-water platforms, and economy-grade commodity emulsions separates formulation complexity tiers. Price differentiation hinges on droplet size certification and REACH-compliant documentation depth. Cost compression in standard emulsion tiers is intensifying because Indian domestic capacity expansion under PLI incentives floods mid-market channels. Craft beverage brands in North America exhibit highest price sensitivity, while Japanese functional drink manufacturers accept formulation premiums for bioavailability claims.
Supply Chain Analysis
Extended payment terms from German equipment suppliers to Indian ingredient houses compress working capital cycles across the emulsion value chain. Manufacturing gravity centers on Germany for homogenization technology, India for expanding oil-in-water capacity, and Switzerland for encapsulation R&D. Raw material flows draw from Sudanese acacia belts, Sahel-region gum arabic harvests, and Brazilian citrus terpene extraction. Single-source vulnerability concentrates in high-pressure microfluidization equipment where Swiss and German suppliers control sub-200 nanometer specifications. Distribution runs through direct technical partnerships displacing traditional flavor distributors, particularly in North American craft segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label mandate fragmentation across FDA, REACH, and FSSAI jurisdictions creates specialized formulation niches where mid-tier emulsion houses capture share from undifferentiated commodity suppliers.
For Market Incumbents: Build regulatory compliance moats by certifying encapsulation systems against evolving EU F-Gas and REACH disclosure thresholds before competitors complete reformulation cycles. Cargill Incorporated and Firmenich should anchor backward integration into hydrocolloid sourcing to insulate margins from Sudanese supply interruptions. Channel control through direct technical partnerships with beverage manufacturers displaces distributor relationships in craft segments. For New Entrants and Emerging Players: Pursue white-space positioning in Brazilian carbonated soft drink channels where ANVISA regulations favor localized blending operations over import-dependent supply. Sub-Saharan Africa dairy alternative markets present penetrable demand with minimal incumbent encapsulation expertise. Precision fermentation convergence offers go-to-market differentiation through bioengineered lipid carriers without agricultural commodity exposure. For Investors and Strategic Acquirers: Encapsulation-science specialists with volatile aromatic stabilization IP command scarcity premiums in a market where Swiss and French research clusters concentrate formulation talent. Long-term viability frames around clean-label chemistry convergence with functional ingredient delivery. Monitor FSSAI-Codex harmonization progress as inflection signal for imported concentrate penetration into Indian organized retail.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrocolloid Sourcing | Captive supply of gum arabic and acacia insulates margins from Sahel-region climate volatility. |
| Nanoemulsion Certification Investment | REACH-compliant sub-200 nanometer documentation unlocks German and Dutch dairy alternative procurement. |
| Direct Technical Partnership Programs | Bypassing distributors captures North American craft beverage formulation iteration demand. |
| Precision Fermentation Convergence | Bioengineered lipid production eliminates agricultural commodity price exposure in carrier oils. |
| Sub-Saharan Africa Blending Localization | ANVISA-aligned operations capture Brazilian and regional carbonated soft drink expansion. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, FEMA GRAS determination filings, ECHA REACH authorization registers, and FSSAI flavoring substance notifications. The analysis combines structured interviews with beverage formulation directors, procurement leads at flavor houses, plant managers at Indian ingredient houses, and R&D heads at encapsulation specialists. Bottom-up volume modeling from emulsion concentrate production capacities triangulates against top-down expenditure flows from beverage manufacturer procurement disclosures.
Forecast inputs span product type segmentation by droplet size architecture, application segmentation by shelf-stability requirements, end-user segmentation by technical service intensity, and regional segmentation by regulatory compliance thresholds. CAGRs derive from modeled volume trajectories across the projection horizon, incorporating PLI scheme capacity addition timelines, REACH phase-down schedules for synthetic stabilizers, and nanoemulsion adoption curves in functional beverage channels. Homogenization equipment deployment rates and hydrocolloid price elasticity inform industry-specific forecast sensitivity.
Sensitivities concentrate around gum arabic supply interruptions, REACH authorization delays for plant-derived alternatives, and FSSAI standard harmonization pace with Codex Alimentarius. Forecasts reflect documented assumptions on clean-label definition convergence and equipment supplier geographic concentration. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
United States Food Flavor Market
Flavorings and Food Additives
China Food Flavor and Enhancer Market
Flavorings and Food Additives
Shelf-Stable Mezze Fermentation Ingredient Systems Market
Flavorings and Food Additives
Soy Sauce Powder Market
Flavorings and Food Additives
Food-Grade Gellan Gum Market
Flavorings and Food Additives
Vanilla Extract Market
Flavorings and Food Additives
Keto Friendly Flavors Market
Flavorings and Food Additives
Beverage Flavoring Market
Flavorings and Food Additives
Natural and Organic Flavors Market
Flavorings and Food Additives
North America Food Flavor Market
Flavorings and Food Additives
Oleoresin Market
Flavorings and Food Additives
Nature Identical Flavorings Market
Flavorings and Food Additives
Orange Essential Oil Market
Flavorings and Food Additives
Smoked Condensates Market
Flavorings and Food Additives
China Food Colorants Market
Flavorings and Food Additives
Global Beverage Flavoring Systems Market