
 UK Food Testing Market | 2026-2036
UK Food Testing Market Size, Share, and Industry Trends Forecast 2026-2036
UK Food Testing Market Analytics
Plant-based protein substitutes are pivoting food testing economics as manufacturers verify novel ingredient safety profiles. Eurofins Scientific leverages its UK laboratory network to anchor large-scale microbiological screening for alternative protein producers. Intertek Group plc differentiates through specialized allergen validation services that sustain premium positioning among retail-facing clients.
UK food testing encompasses analytical verification of food safety, nutritional composition, chemical residues, and biological contaminants using standardized sampling protocols and instrument-based detection methods, with PCR amplification achieving pathogen identification at sensitivity thresholds below ten colony-forming units per gram. The primary purpose is ensuring consumer protection and supply chain integrity across commercial food production. Microbiological testing occupies the largest volume share due to persistent regulatory mandates for Salmonella and Listeria screening, while mass spectrometry-based chemical testing commands superior margins from pesticide and veterinary drug residue analysis. Allergen testing demonstrates the fastest expansion trajectory as Natasha's Law enforcement compels detailed labeling verification across packaged food segments.
The Food Standards Agency enforces retained EU hygiene regulations while the UK Health Security Agency coordinates national foodborne illness surveillance, collectively mandating expanded pathogen testing frequencies across processing facilities. Trading Standards services at local authority level conduct frontline compliance verification that shapes market access requirements for domestic and imported food products. Stakeholders must monitor divergence between UK-specific standards and evolving EU regulatory frameworks to anticipate testing protocol adjustments and accreditation requirements.
Market Dynamics
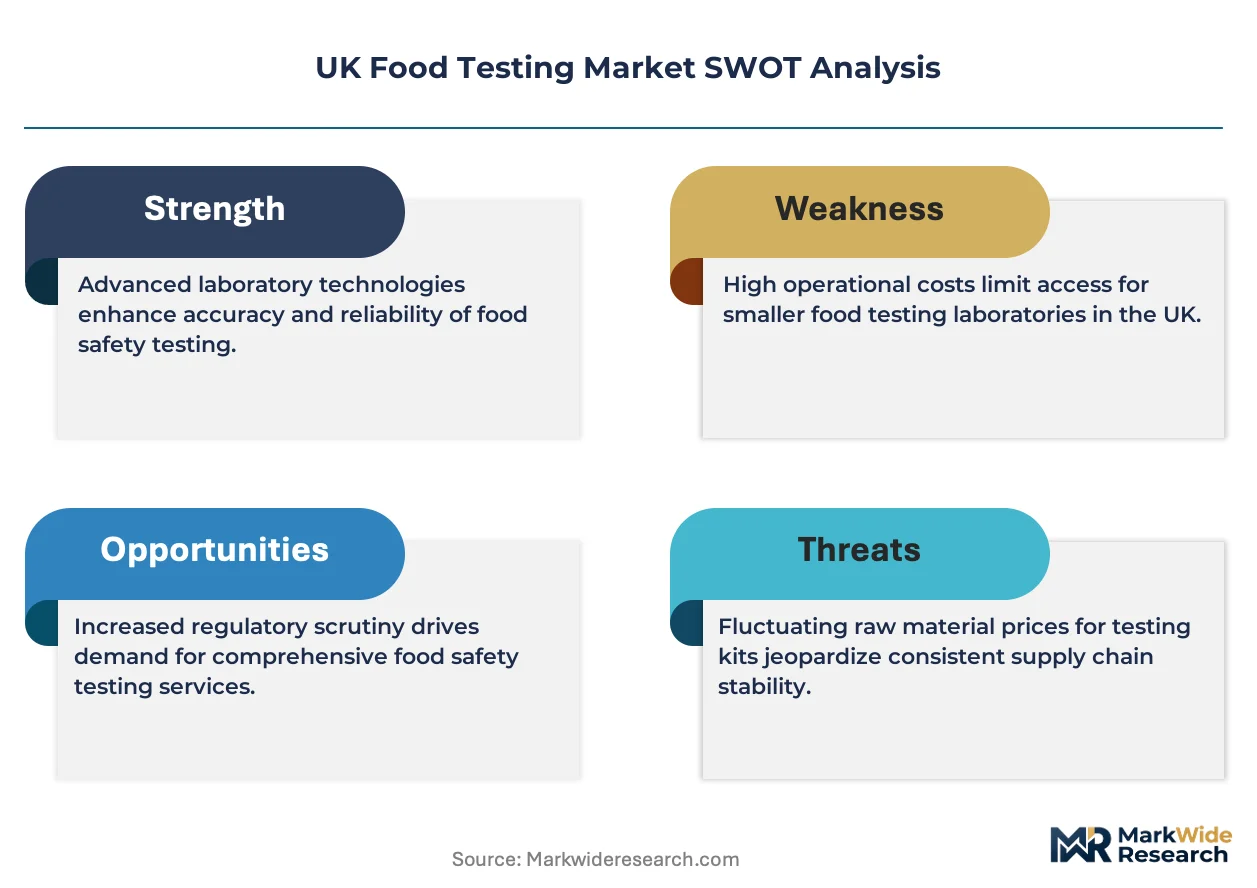
Natasha's Law enforcement is compressing testing timelines across UK packaged food manufacturing, forcing producers to validate allergen declarations through accelerated laboratory turnaround protocols.
Growth Catalysts
- Retained EU Law Act divergence:The UK Health Security Agency is expanding pathogen surveillance mandates beyond baseline EU hygiene requirements, creating incremental testing volume at processing facilities.
- Plant protein ingredient proliferation:Novel mycoprotein and pea-protein formulations require full safety-profile validation, generating specialized analytical demand that legacy meat-testing protocols cannot satisfy.
- Midlands manufacturing corridor concentration:England's food production belt around Birmingham and Leicester generates dense laboratory service demand that supports dedicated regional testing infrastructure investment.
Market Restraints
- Accreditation cost escalation:ISO 17025 certification renewal and UKAS audit fees have risen substantially, compressing margins for independent testing laboratories serving mid-tier food manufacturers.
- Reference material supply concentration:Certified allergen and mycotoxin reference standards rely heavily on continental European suppliers, exposing UK laboratories to post-Brexit customs friction and extended lead times.
- Skilled analyst shortage:Mass spectrometry and PCR platform operation requires specialized technical training that UK technical education pipelines currently undersupply.
Strategic Opportunities
- Scotland aquaculture testing expansion:Salmon and shellfish producers around the Scottish Highlands face intensifying export verification requirements that regional laboratories can capture through proximity.
- Digital chain-of-custody integration:Blockchain-linked sampling documentation is enabling real-time compliance verification that premium retail buyers now specify in supplier contracts.
- Natasha's Law secondary enforcement:Local authority Trading Standards teams are extending allergen verification to foodservice and catering segments previously exempt from packaged-goods labeling rules.
Industry Challenges
- LIMS integration complexity:Legacy laboratory information management systems at established UK facilities resist seamless integration with automated PCR and sequencing platforms, delaying workflow optimization.
- Multi-site accreditation maintenance:Laboratory networks operating across England, Scotland, and Wales must maintain separate UKAS assessments for each location, multiplying administrative overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Food Testing Market |
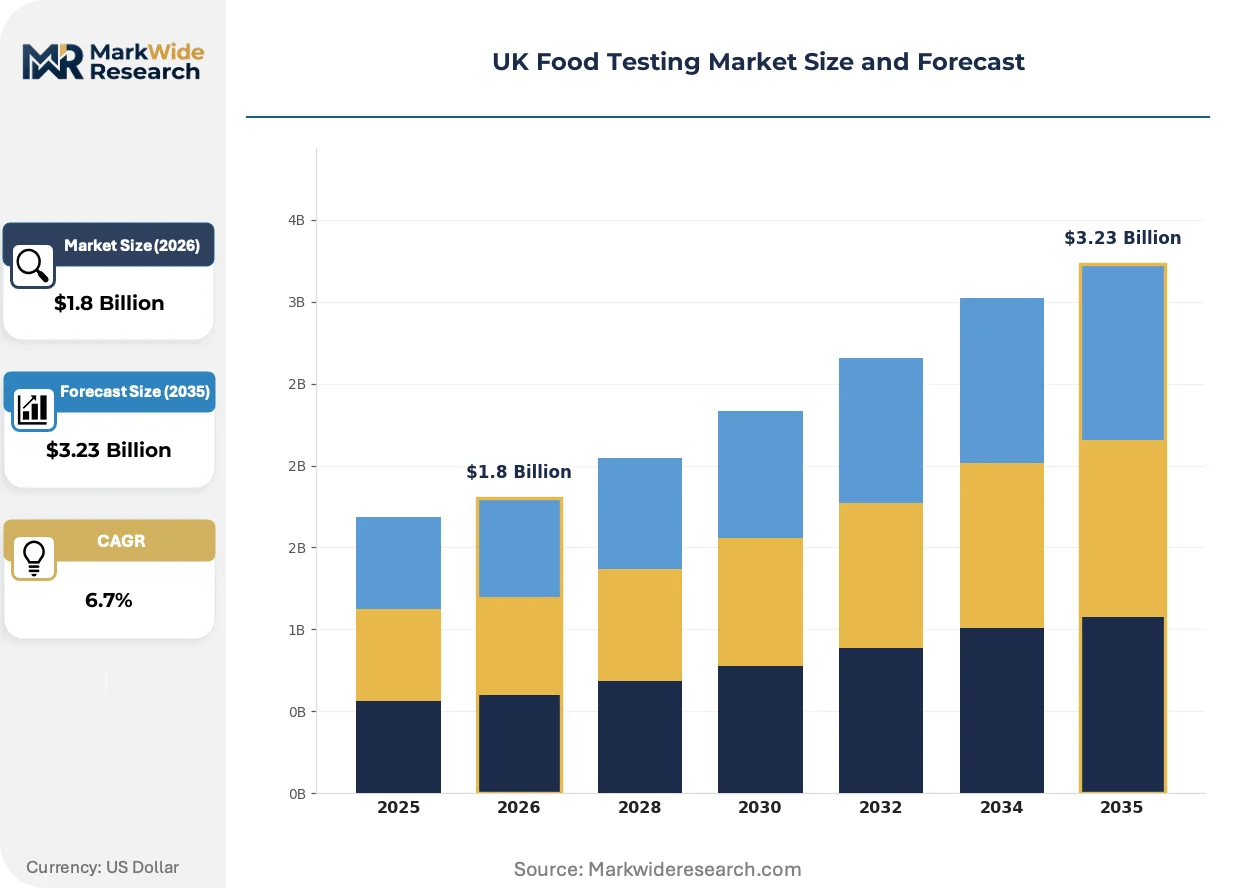
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbiological Testing, Chemical Testing, Nutritional Analysis, Allergen Testing Technology: PCR, ELISA, Chromatography, Mass Spectrometry End User: Food Manufacturers, Retailers, Food Service Providers, Regulatory Bodies Application: Quality Control, Compliance Testing, Research & Development, Risk Assessment |
| Companies Covered | Eurofins Scientific, Intertek Group plc, SGS SA, ALS Limited, Bureau Veritas, Thermo Fisher Scientific, TÜV SÜD, NSF International, Mérieux NutriSciences, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Food Testing Market Evolving Landscape
Next-generation sequencing and portable diagnostic hardware are compressing pathogen identification from days to hours, reshaping how UK food manufacturers manage batch-release decisions and supply chain risk.
Whole-genome sequencing is automating Salmonella and Listeria strain differentiation at sensitivity thresholds below traditional culture methods. Major dairy and ready-meal processors in Yorkshire and Lancashire are adopting these platforms for routine environmental monitoring. The technology is automating traceback investigations that previously required weeks of manual epidemiological correlation.
The UK Retained EU Law Act is triggering divergence from EFSA guidance on novel food ingredient safety assessment. Domestic manufacturers of cell-cultured and precision-fermented proteins now face dual-track validation requirements. England-based alternative protein startups are responding by front-loading toxicology studies to preempt regulatory uncertainty.
Retail-led supplier consolidation is compressing approved laboratory lists. Tesco, Sainsbury's, and Marks & Spencer have each reduced their third-party testing panels to pre-qualified providers with national coverage and dedicated account management. This concentration is most visible in Greater London, where headquarters procurement teams enforce centralized compliance protocols across dispersed manufacturing estates.
UK Food Testing Market Segmentation
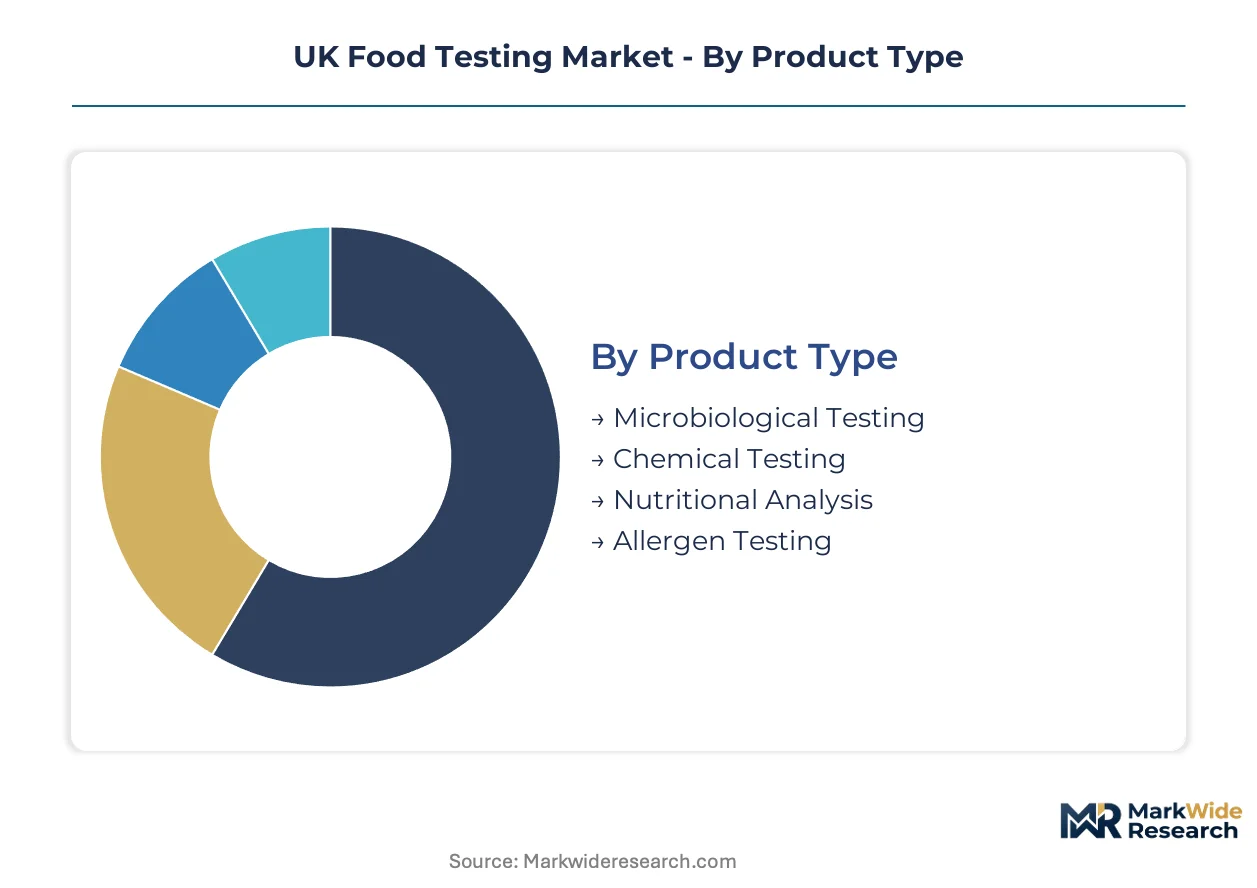
Food testing laboratories in the United Kingdom calibrate service portfolios across four distinct dimensions. Each segmentation axis reveals where capital investment concentrates and which regulatory mandates reshape procurement priorities for food manufacturers and retailers.
Product Type:
Equipment upgrade cycles in UK food testing laboratories now compress from seven-year intervals toward four-year replacement windows as detection sensitivity requirements tighten.
- Microbiological Testing:Culture-based and rapid molecular methods detect Salmonella, Listeria, and E. coli in dairy, ready-meal, and fresh produce matrices. Yorkshire and Lancashire dairy processors drive sustained volume for environmental monitoring programs that the UK Health Security Agency mandates at expanded frequencies.
- Allergen Testing:ELISA and PCR-based protocols validate gluten, peanut, and milk protein declarations for packaged goods compliance. Natasha's Law enforcement across England's Midlands manufacturing corridor accelerates turnaround requirements that specialized laboratories now guarantee within 24-hour windows.
- Chemical Testing:Pesticide and veterinary drug residue screening supports export certification for UK meat and grain producers.
- Nutritional Analysis:Macronutrient and micronutrient quantification underpins health claim substantiation for functional food launches.
Microbiological Testing sits at the top of the volume ranking, with Allergen Testing climbing the fastest.
Technology:
Platform selection in UK laboratories now hinges on throughput economics rather than capital cost alone, with automation compatibility determining three-year total cost of ownership.
- PCR:Polymerase chain reaction amplification achieves pathogen identification below ten colony-forming units per gram sensitivity thresholds. Birmingham and Leicester food manufacturing clusters demand real-time PCR systems that integrate with laboratory information management systems for batch-release documentation.
- Mass Spectrometry:LC-MS and GC-MS platforms deliver definitive identification of chemical residues and contaminants at parts-per-billion detection limits. Premium pricing for pesticide and veterinary drug analysis sustains margin structures that chromatography methods cannot match.
- ELISA:Enzyme-linked immunosorbent assays provide cost-effective allergen screening for high-throughput production environments.
- Chromatography:HPLC and GC separations support nutritional profiling and additive verification for label compliance.
PCR commands the highest installed base, with Mass Spectrometry expanding most quickly as multi-residue panels replace single-analyte methods.
End User:
Procurement consolidation among UK food industry buyers now favors testing providers with national accreditation coverage and dedicated account management infrastructure.
- Food Manufacturers:Processors of dairy, meat, bakery, and ready-meal products maintain in-house laboratories or contracted testing schedules that align with Hazard Analysis Critical Control Point protocols. The Food Standards Agency's retained EU hygiene regulations mandate minimum testing frequencies that mid-tier manufacturers increasingly outsource.
- Retailers:Tesco, Sainsbury's, and Marks & Spencer enforce approved laboratory lists with pre-qualified national providers. Centralized procurement at Greater London headquarters compresses supplier panels to three or four accredited partners per testing category.
- Food Service Providers:Catering and hospitality operators face emerging allergen verification requirements as Trading Standards extends Natasha's Law enforcement beyond packaged goods.
- Regulatory Bodies:Local authority Trading Standards services and the UK Health Security Agency coordinate surveillance sampling that shapes market access requirements.
Food Manufacturers generate the largest testing volume, with Retailers consolidating supplier relationships fastest.
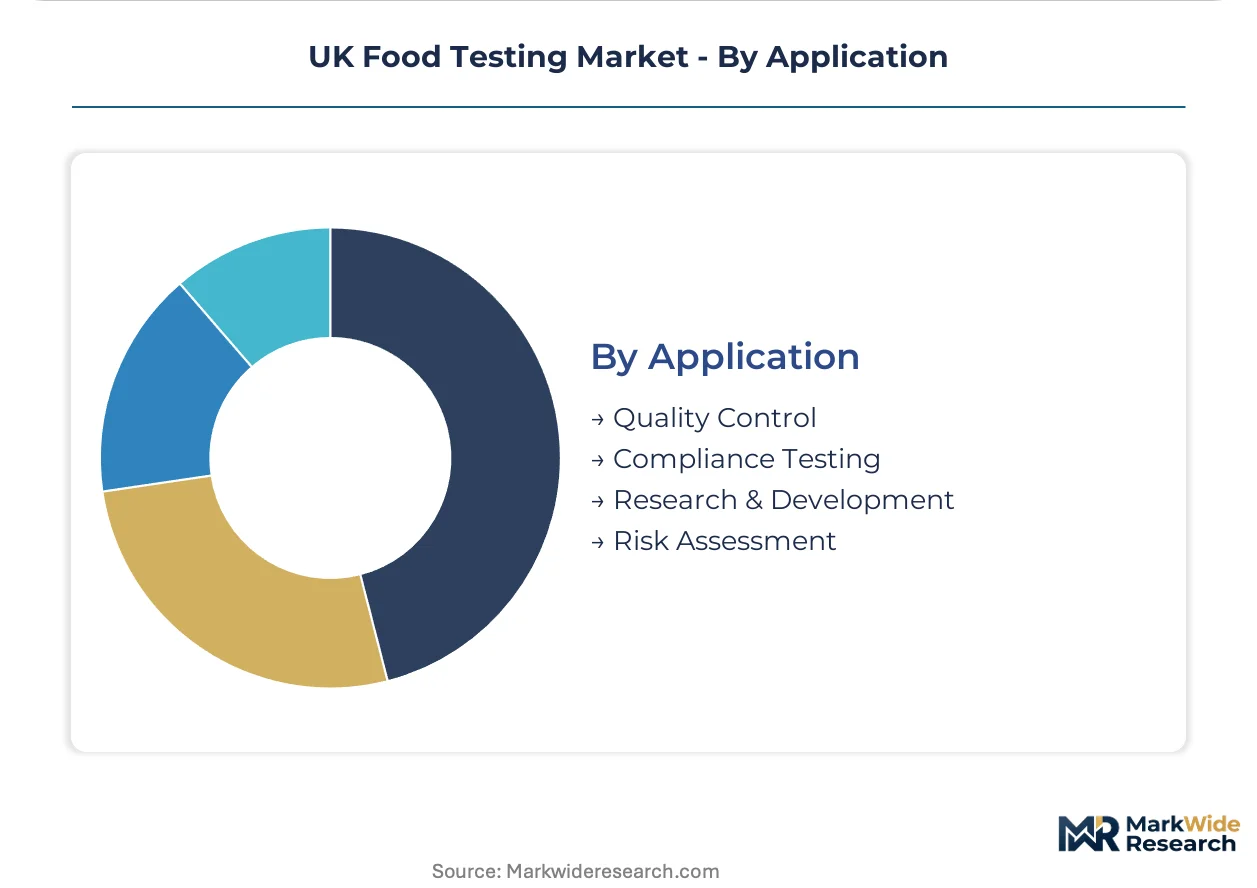
Application:
Testing purpose determines protocol complexity and pricing tier, with compliance mandates commanding premium rates over internal quality benchmarks.
- Compliance Testing:Regulatory-mandated verification for export certification, import clearance, and enforcement sampling requires UKAS-accredited methods with full chain-of-custody documentation. Scottish salmon and shellfish exporters around the Highlands depend on compliance testing for EU and Asian market access.
- Quality Control:In-process and finished-product testing supports manufacturing consistency and batch release decisions. Ready-meal processors in England's manufacturing belt integrate rapid microbiological methods into daily production schedules.
- Research & Development:Novel ingredient safety profiling for plant-based and cell-cultured protein formulations demands customized analytical protocols.
- Risk Assessment:Supply chain vulnerability mapping and contamination source tracing support insurance and liability management.
Compliance Testing anchors revenue concentration, with Research & Development showing the steepest expansion trajectory as alternative protein startups front-load toxicology studies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Midlands manufacturing corridor anchors UK food testing demand through dense concentrations of dairy, ready-meal, and bakery processors around Birmingham and Leicester. Regional laboratory networks have co-located near these production clusters to compress turnaround times for microbiological and allergen screening. The Food Standards Agency's retained EU hygiene regulations enforce minimum testing frequencies that sustain baseline volume across England's food production belt.
London and the Southeast
Headquarters procurement teams at Tesco, Sainsbury's, and Marks & Spencer enforce centralized compliance protocols from Greater London. Retail-led supplier consolidation has compressed approved laboratory lists to pre-qualified national providers with dedicated account management. The UK Health Security Agency coordinates surveillance sampling from London-based facilities that shape market access requirements for imported food products.
Scotland
Salmon and shellfish exporters around the Scottish Highlands depend on compliance testing for EU and Asian market access. The country's aquaculture sector faces intensifying export verification requirements that regional laboratories capture through proximity. Scottish salmon producers maintain environmental monitoring programs that exceed baseline regulatory mandates to satisfy premium retail buyer specifications.
Yorkshire and Lancashire
Dairy processors across these northern counties drive sustained volume for environmental monitoring programs mandated at expanded frequencies. Major ready-meal manufacturers have adopted whole-genome sequencing platforms for routine pathogen surveillance. The region's dairy cooperatives integrate rapid microbiological methods into daily production schedules that support batch-release documentation.
Wales
Food manufacturers in South Wales maintain contracted testing schedules aligned with Hazard Analysis Critical Control Point protocols. Local authority Trading Standards services conduct frontline compliance verification that shapes domestic market access. Welsh lamb and beef exporters depend on residue testing for veterinary drug clearance into continental European markets.
UK Food Testing Market Competitive Landscape
Global majors compete with regional champions across accreditation coverage and specialized service portfolios. The UK food testing market structures around three tiers: multinational laboratory networks with national coverage, mid-scale independents with regional specialization, and niche consultancies focused on single testing categories. Strategic archetypes include premium-positioned allergen validators, scale-driven microbiological screeners, and technology-forward sequencing adopters. Competitive moves concentrate on multi-site accreditation maintenance and digital chain-of-custody integration.
Among the multinational tier, Eurofins Scientific and Intertek Group plc exemplify contrasting specialization strategies. Eurofins leverages its UK laboratory network to anchor large-scale screening capacity. Intertek occupies a premium positioning through dedicated allergen validation services. SGS SA represents the diversified inspection and certification model with broad analytical capabilities spanning food safety, environmental, and industrial applications.
| Leading Market Players |
|---|
| Eurofins Scientific |
| Intertek Group plc |
| SGS SA |
| ALS Limited |
| Bureau Veritas |
| Thermo Fisher Scientific |
| TÜV SÜD |
| NSF International |
| Mérieux NutriSciences |
| Others |
Value Network & Pricing Analysis
Captive laboratory networks at Eurofins Scientific and Intertek Group plc anchor supply positions and pricing power through multi-site UKAS accreditation coverage that independent competitors cannot replicate. This integration pattern compresses procurement timelines for retail buyers while sustaining premium rate structures for allergen validation services that Natasha's Law enforcement has made non-negotiable.
Pricing Analysis
Input-cost pass-through from ISO 17025 certification renewal and UKAS audit fees intensifies pricing pressure across mid-tier independent laboratories serving England's food manufacturing belt. Contract-based long-term service agreements dominate procurement between major retailers and national laboratory networks, with price differentiation anchored in certification grade and geographic coverage density. Cost compression runs through the independent laboratory tier as reference material supply friction from continental European suppliers extends lead times and inflates working capital requirements. Food manufacturers with in-house testing capabilities exhibit lowest price sensitivity, while mid-tier processors without captive laboratory capacity face acute margin pressure from accelerated turnaround demands.
Supply Chain Analysis
Single-source vulnerability sits with continental European suppliers of certified allergen and mycotoxin reference standards that UK laboratories draw from for method validation and quality control. The supply chain rests on Germany, the Netherlands, and France for these critical analytical inputs, with post-Brexit customs procedures creating structural risk of extended lead times and batch-to-batch variability. Distribution runs through direct manufacturer-to-laboratory channels for high-value reference materials, supplemented by specialized scientific distributors for routine consumables. Equipment procurement for PCR and mass spectrometry platforms concentrates with Thermo Fisher Scientific and similar instrumentation majors, creating additional concentration risk for capital-intensive laboratory expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK food testing market functions as a regulatory compounder where Natasha's Law enforcement and Retained EU Law Act divergence continuously expand mandatory testing volumes. Food manufacturers, retailers, and regulatory surveillance programs collectively sustain demand growth that outpaces general laboratory services.
For Market Incumbents: Anchor multi-site accreditation coverage across England, Scotland, and Wales to defend against retail procurement consolidation that has compressed approved laboratory lists at Tesco, Sainsbury's, and Marks & Spencer. Invest in whole-genome sequencing platform integration to preempt substitution threat from rapid molecular methods that compress pathogen identification timelines. Prioritize digital chain-of-custody documentation to meet emerging blockchain-linked supplier contract requirements.
For New Entrants and Emerging Players: Scotland's aquaculture testing corridor around the Highlands represents an underserved buyer archetype with intensifying export verification requirements for salmon and shellfish producers. Foodservice and catering operators facing extended Natasha's Law enforcement beyond packaged goods offer additional white-space penetration. Pursue proximity-based service models with guaranteed turnaround commitments rather than competing on national coverage.
For Investors and Strategic Acquirers: Roll-up economics work for regional independent laboratories with specialized allergen or microbiological capabilities because multi-site accreditation maintenance creates scale advantages that fragmented competitors cannot match. Target acquisition archetypes include mid-scale independents in Yorkshire, Lancashire, and the Midlands with established retailer relationships and UKAS credentials. Watch for inflection signals in Trading Standards enforcement intensity that would accelerate outsourcing from in-house manufacturer laboratories.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Site UKAS Accreditation Expansion | Retail procurement consolidation at Greater London headquarters demands national coverage with dedicated account management infrastructure. |
| Whole-Genome Sequencing Platform Deployment | Major dairy and ready-meal processors in Yorkshire and Lancashire adopt these systems for routine environmental monitoring programs. |
| Digital Chain-of-Custody Integration | Blockchain-linked sampling documentation enables real-time compliance verification that premium retail buyers now specify in contracts. |
| Scotland Aquaculture Testing Proximity | Scottish Highlands salmon and shellfish exporters depend on regional laboratory access for EU and Asian market certification. |
| Alternative Protein Safety Profile Validation | Cell-cultured and precision-fermented protein startups front-load toxicology studies to preempt regulatory uncertainty from UK-EU divergence. |
Research Methodology
Bottom-up food manufacturer and retailer procurement modeling reconciled against top-down laboratory capacity and accreditation tracking forms the analytical core of this study. Primary interviews with laboratory operations directors, Food Standards Agency compliance officers, retail category buyers, and Trading Standards enforcement teams combined with secondary validation from UKAS accreditation registers, Food Standards Agency enforcement data, and UK Health Security Agency surveillance reports. Cross-referencing bottom-up testing volume estimates from England's Midlands manufacturing corridor against top-down laboratory revenue aggregation confirmed segmentation integrity.
Historical trendline analysis of microbiological and allergen testing volumes across dairy, ready-meal, and bakery processing facilities established baseline growth patterns. The analytical framework models demand across product type, technology platform, end-user category, and application purpose throughout the forecast period, with CAGRs derived from regression-adjusted trend extrapolation and regulatory mandate impact assessment. Forecast inputs incorporate Natasha's Law enforcement timeline assumptions and Retained EU Law Act divergence scenarios for novel food ingredient validation requirements.
Underlying measurement precision varies by segment; compliance testing and retail-facing quality control carry tighter precision than research and development applications where protocol customization introduces variability. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and reference material supply stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Global Meat Speciation Testing Market
Food Safety Testing
Testing, Inspection, and Certification in Consumer Goods and Retail Market
Food Safety Testing
Food Traceability Solutions Market
Food Safety Testing
UAE Product Testing Lab Services Market
Food Safety Testing
Food Pathogen Testing Market
Food Safety Testing
Europe Food Safety Testing Market
Food Safety Testing
Beverage Tester Market
Food Safety Testing
Rapid Microbiology Testing Market
Food Safety Testing
US Consumer Product Safety Testing Market
Food Safety Testing
Global Food Diagnostics Market
Food Safety Testing
US Legionella Testing Market
Food Safety Testing
Food Testing, Inspection, and Certification Market
Food Safety Testing
Global Inline Metal Detector Market
Food Safety Testing
Gum Content Tester Market
Food Safety Testing
US Food Allergen Testing Market
Food Safety Testing
Amylase Testing Market