
 Global Food Diagnostics Market | 2026-2036
Global Food Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Food Diagnostics Market Intelligence
The scarcity of trained microbiologists and data analysts capable of interpreting complex genomic test results is bifurcating the market's service model. Large-scale providers like Eurofins Scientific and SGS SA leverage their global network of accredited laboratories to centralize this expertise. Technology-focused firms such as bioMérieux specialize in automated systems that reduce the need for skilled operators on-site. Thermo Fisher Scientific Inc. sustains its market position by offering a comprehensive portfolio of both instruments and supporting services.
Food diagnostics involves the application of analytical methods to detect contaminants, verify food authenticity, and assess nutritional composition. These methods include modern polymerase chain reaction (PCR) assays that identify specific DNA sequences of pathogens like Salmonella, and traditional ELISA for protein detection. Test kits for pathogen detection and allergen testing represent the largest product segments, essential for routine quality control in food processing units. Analytical instruments, while a larger capital investment, provide higher throughput and accuracy for dedicated quality control labs.
Regulatory frameworks from the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) mandate stringent testing protocols for contaminants and allergens. Concurrently, standards set by bodies like China's SAMR and India's FSSAI influence testing requirements for market access in those key geographies. Stakeholders must continually adapt testing strategies to address emerging contaminants, food fraud, and evolving international trade standards.
Market Dynamics
The market's structure is defined by the tension between centralized, high-throughput laboratory testing and the push for decentralized, rapid diagnostics at the point of processing. This dynamic influences technology adoption, service models, and cost structures across the food supply chain.
Growth Catalysts
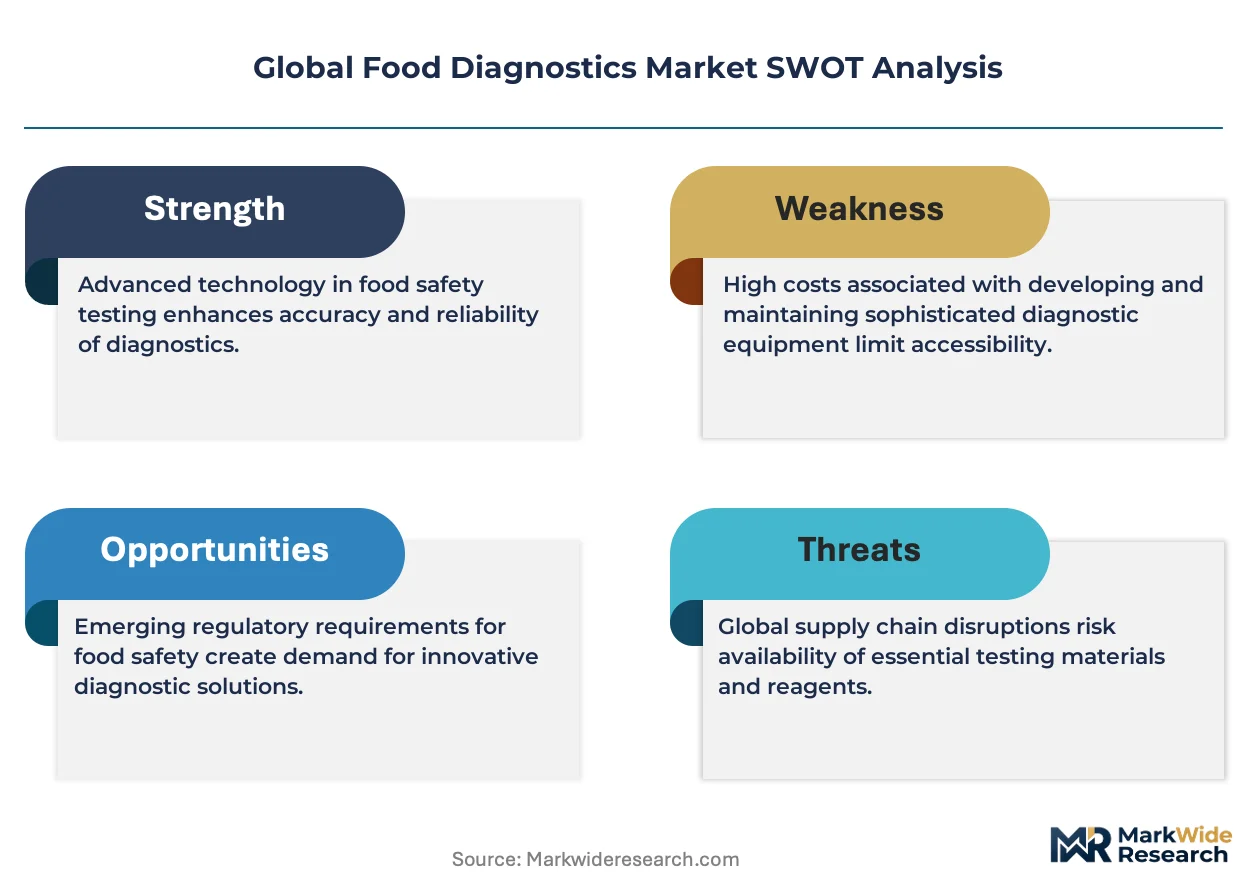
- Stricter Regulations:The US Food Safety Modernization Act (FSMA) and similar global mandates increase the required frequency and scope of testing, directly driving test volume.
- Food Processing Sector Needs:Demand from food processors for rapid pathogen detection methods is high, driven by the need to minimize production downtime and prevent costly recalls.
- Asia-Pacific Quality Initiatives:National programs in China and India, enforced by regulators like SAMR and FSSAI, are elevating food safety standards and expanding testing requirements.
Market Restraints
- High Instrument Cost:The significant capital investment for advanced analytical instruments like PCR and mass spectrometers remains a barrier for small and medium-sized food enterprises.
- Food Matrix Complexity:The inherent variability in food composition, known as matrix effects, can interfere with test accuracy and requires extensive validation for different products.
- Reagent Supply Concentration:A dependency on a limited number of global suppliers for critical enzymes, antibodies, and other reagents creates vulnerability to price volatility and supply disruptions.
Strategic Opportunities
- Food Fraud Detection:Growing concern over economic adulteration creates an opportunity for tests that verify food authenticity, such as species identification in meat or origin analysis for premium oils.
- Portable Biosensors:The convergence of microfluidics and smartphone connectivity offers a pathway for developing low-cost, on-site testing devices for real-time quality checks in the field or on the factory floor.
- Emerging Market Adoption:Countries in Southeast Asia and Latin America are progressively adopting international food safety standards, opening new markets for diagnostic products and services.
Industry Challenges
- Specialized Talent Scarcity:A shortage of trained microbiologists and data analysts capable of operating advanced systems and interpreting complex genomic data limits the adoption of next-generation technologies.
- Method Harmonization:The lack of globally harmonized and validated testing methods for emerging contaminants and allergens can create technical barriers to international trade and complicate compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Food Diagnostics Market |
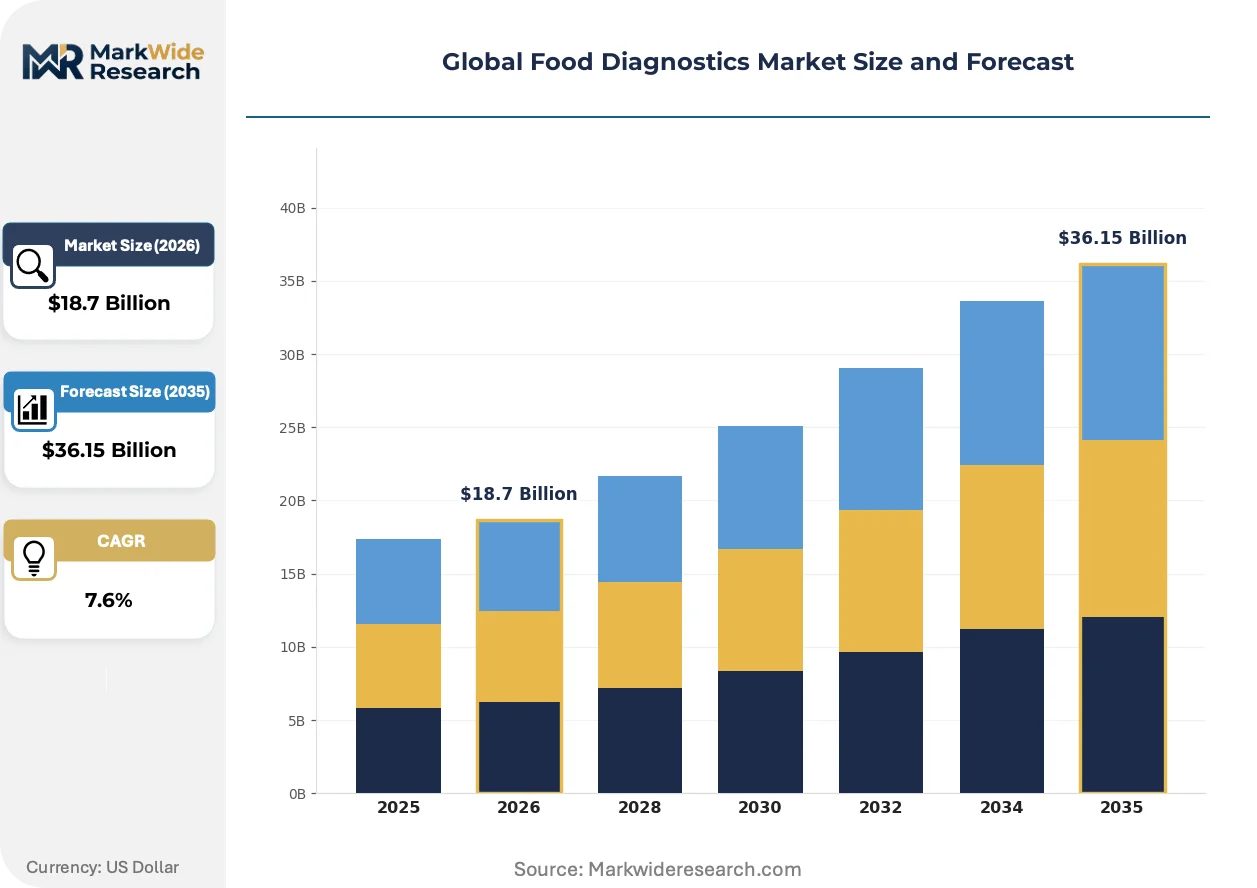
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $36.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Test Kits, Analytical Instruments, Reagents, Software Solutions, Services Application: Pathogen Detection, Residue Analysis, Allergen Testing, GMO Testing, Nutritional Analysis End User: Food Processing Units, Quality Control Labs, Regulatory Bodies, Research Institutes, Food Retailers Distribution Channel: Direct Sales, Distributors, Online Platforms, Third-Party Vendors, Food Safety Consultants |
| Companies Covered | SGS SA, Agilent Technologies Inc., Thermo Fisher Scientific Inc., PerkinElmer Inc., bioMérieux, Eurofins Scientific, 3M, ALS, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Food Diagnostics Market Strategic Shifts & Innovations
Technology is enabling a fundamental shift from reactive contaminant detection to proactive food safety assurance. This transition prioritizes predictive analytics and real-time data integration, moving diagnostics further upstream into the production process.
Next-Generation Sequencing (NGS) provides whole-genome data for comprehensive pathogen identification and source tracking. Large food safety laboratories and regulatory bodies are adopting NGS for complex outbreak investigations. This technology is displacing traditional single-pathogen PCR methods for epidemiological surveillance and environmental monitoring, offering greater resolution.
The European Union's updated food information regulations mandate stricter allergen labeling and cross-contamination controls. This requirement compels food manufacturers to implement more frequent and sensitive testing protocols for allergens like nuts, gluten, and soy. The bakery and confectionery segments are most impacted, driving demand for validated ELISA and PCR test kits.
A move towards subscription-based service models is altering how smaller food processors access diagnostic capabilities. This disrupts traditional capital equipment sales by bundling instruments, consumables, and analytical support into a recurring operational expense. The shift is most prominent in North America, where service providers cater to businesses lacking in-house expertise.
Global Food Diagnostics Market Segmentation
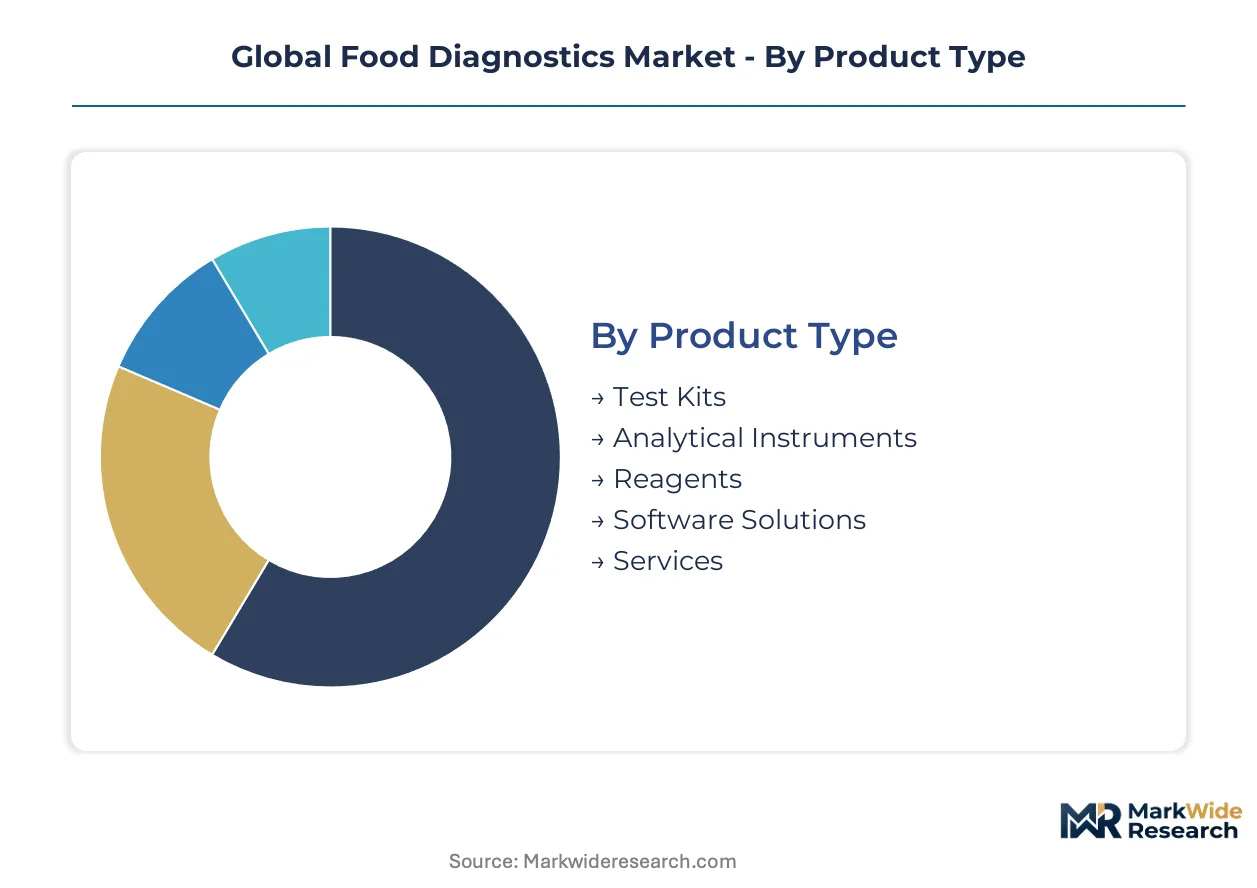
The Global Food Diagnostics Market exhibits diverse segmentation across product types, applications, end-users, and distribution channels. This granular breakdown reveals how diagnostic solutions are delivered and consumed throughout the food supply chain. Understanding these segments helps stakeholders identify key investment areas and optimize their market penetration strategies.
Product Type:
The various product types within food diagnostics are distributed through distinct channels, reflecting their complexity and end-user requirements.
- Test Kits:These self-contained units offer rapid, qualitative or semi-quantitative results for contaminants. Demand is high among small to medium-sized food processors in China and India for on-site quality checks.
- Analytical Instruments:PCR thermocyclers and mass spectrometers provide highly accurate, quantitative data for complex analyses. Large food safety laboratories in the US and Europe use these for high-throughput screening.
- Reagents:This category encompasses essential chemicals and biological components required for various diagnostic assays.
- Software Solutions:These platforms manage data, automate reporting, and integrate diagnostic results with quality management systems.
- Services:This segment includes outsourced testing, method development, and expert consultation from accredited laboratories.
Test Kits dominates installed base. Analytical Instruments is where expansion concentrates.
Application:
Regulatory focus dictates the primary applications for food diagnostics, influencing testing protocols across various food industries.
- Pathogen Detection:This application identifies harmful microorganisms like Salmonella and E. coli using PCR and immunoassay methods. Food processors in North America prioritize rapid detection to prevent recalls.
- Allergen Testing:This involves detecting common food allergens such as gluten and nuts, often using ELISA or PCR. The bakery and confectionery segments in the EU face increased demand due to stricter labeling.
- Residue Analysis:This segment focuses on identifying unwanted chemical residues, including pesticides and veterinary drugs.
- GMO Testing:This application verifies the presence or absence of genetically modified organisms in agricultural products.
- Nutritional Analysis:This determines the precise composition of food items for accurate labeling and product development.
Food processors primarily invest in Pathogen Detection and Allergen Testing for compliance, while Nutritional Analysis supports product development initiatives.
End User:
The diverse end-user base for food diagnostics presents varying volume and throughput requirements, shaping technology adoption.
- Food Processing Units:These facilities conduct routine testing for raw materials, in-process samples, and finished products. Their demand for rapid, on-site pathogen detection minimizes downtime and ensures compliance with US FSMA.
- Quality Control Labs:These dedicated laboratories perform comprehensive analyses using advanced analytical instruments for product release. They serve internal company needs and external clients, particularly in Germany and Japan.
- Regulatory Bodies:Government agencies utilize diagnostics for surveillance, enforcement, and outbreak investigation, setting national food safety standards.
- Research Institutes:Academic and private research entities develop new diagnostic methods and investigate emerging food safety challenges.
- Food Retailers:Supermarkets and food service providers increasingly implement rapid testing to verify product integrity at the point of sale.
Food Processing Units represent the largest segment by volume, with Quality Control Labs driving demand for advanced instrumentation.
Distribution Channel:
Supply concentration within the food diagnostics market dictates the reach and efficiency of different distribution channels.
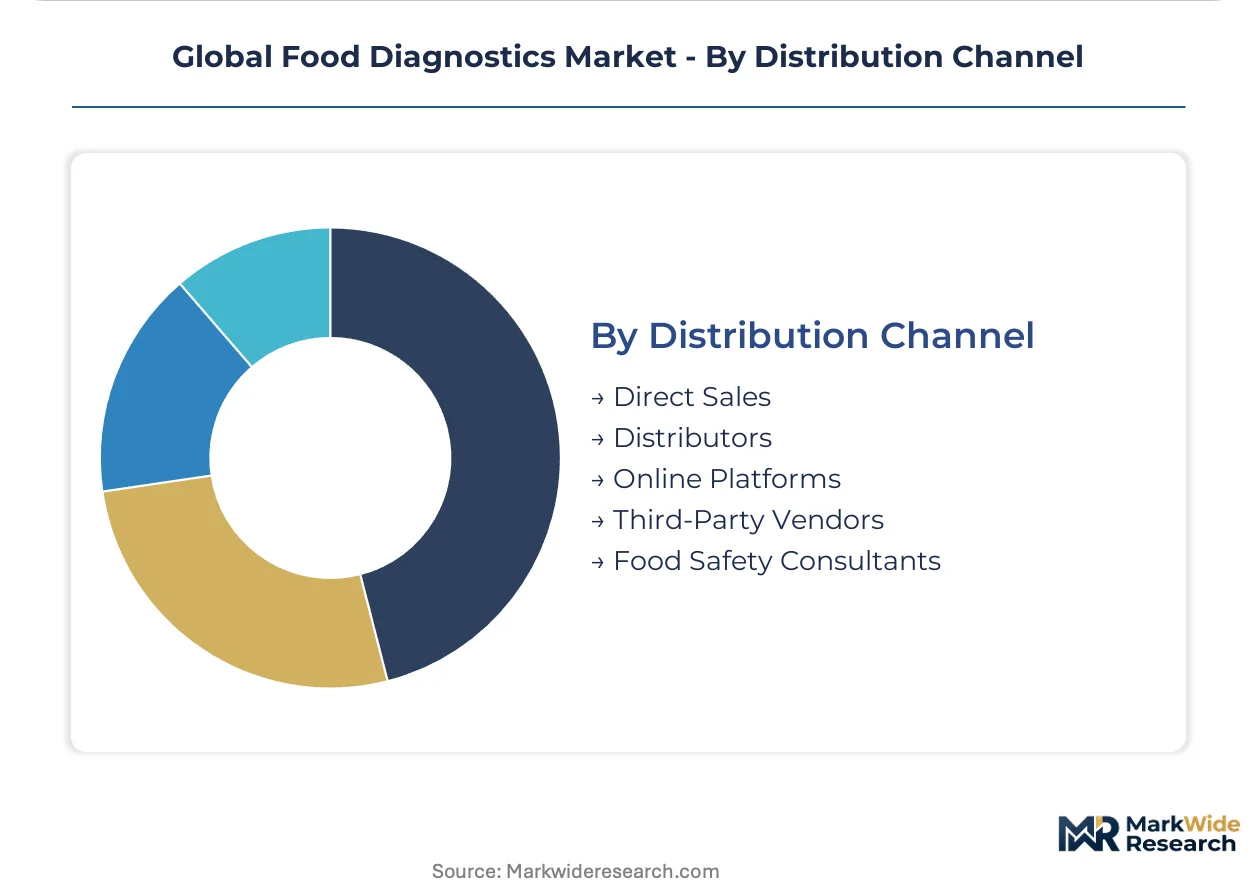
- Direct Sales:Manufacturers directly engage with large enterprise clients, offering customized solutions and service contracts. This channel is favored for high-value analytical instruments in the United States and Western Europe.
- Distributors:These intermediaries provide regional coverage and localized support, supplying a broad range of test kits and reagents. Distributors are critical for market penetration in fragmented markets and emerging economies like Brazil.
- Online Platforms:E-commerce sites facilitate the sale of standardized test kits and consumables, offering convenience and broader accessibility.
- Third-Party Vendors:These entities often bundle diagnostic products with other services, like equipment maintenance or laboratory management.
- Food Safety Consultants:Consultants advise on testing strategies and may recommend or procure specific diagnostic products.
Large enterprises prefer Direct Sales for strategic partnerships, while Distributors serve as the primary conduit for reaching a wider customer base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption patterns for food diagnostics vary significantly by geography, reflecting diverse market maturity and regulatory landscapes. North America and Europe prioritize advanced analytical instruments for high-throughput laboratory testing. Conversely, countries in Asia, particularly China and India, show higher demand for rapid, on-site test kits for routine quality checks.
United States
Demand for rapid pathogen detection drives the market, especially within food processing units. The Food Safety Modernization Act (FSMA) mandates frequent testing, increasing overall test volume. Major food manufacturing hubs in the Midwest utilize advanced diagnostics to ensure product integrity and minimize recalls.
China
National food quality improvement programs bolster the need for food diagnostics across the food supply chain. Regulators like SAMR enforce stricter testing requirements, expanding market access for diagnostic products. Coastal regions with high food processing activity, such as the Yangtze River Delta, adopt on-site quality checks.
India
Food safety standards are elevating due to initiatives enforced by the Food Safety and Standards Authority of India (FSSAI). This creates a substantial market for rapid test kits, particularly for small to medium-sized food processors. Large food production clusters in Maharashtra increasingly integrate diagnostic solutions for compliance.
Germany
Quality control laboratories drive demand for highly accurate analytical instruments and comprehensive testing services. European Food Safety Authority (EFSA) directives compel rigorous testing protocols for contaminants and allergens. Specialized food research centers in Bavaria focus on developing new diagnostic methods for emerging threats.
Japan
Advanced quality control labs utilize sophisticated instruments for precise nutritional analysis and contaminant detection. Strict national food safety regulations ensure high standards for food product release and consumer protection. Major metropolitan areas like Tokyo host dedicated laboratories performing high-throughput screening and method development.
Global Food Diagnostics Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the food diagnostics market. This tiered structure sees global conglomerates offering comprehensive portfolios alongside niche technology providers focusing on specific analytical challenges. Strategic archetypes include full-service laboratory networks, automated system developers, and specialized reagent suppliers. Companies pursue portfolio diversification and strategic partnerships, often through mergers and acquisitions, to expand their market reach and technological capabilities.
Companies specializing in comprehensive analytical solutions exemplify different market approaches and strategic positions. For instance, Eurofins Scientific, a European-based entity, represents the large-scale service providers leveraging extensive accredited laboratory networks globally. Thermo Fisher Scientific Inc. anchors the integrated instrument and service model, sustaining its market position with a broad portfolio of both instruments and consumables. bioMérieux, a French company, focuses on automated systems that reduce the need for on-site skilled operators. These players collectively address diverse customer needs across the food safety landscape, from routine checks to complex genomic analysis.
| Leading Market Players |
|---|
| SGS SA |
| Agilent Technologies Inc. |
| Thermo Fisher Scientific Inc. |
| PerkinElmer Inc. |
| bioMérieux |
| Eurofins Scientific |
| 3M |
| ALS |
| Merck KGaA |
| Others |
Cost & Logistics Intelligence
The US Food Safety Modernization Act (FSMA) and similar global mandates gate both supply qualification for diagnostic products and influence price differentiation based on compliance levels. This regulatory environment necessitates robust supply chains capable of delivering certified products while also shaping the cost structures for various testing solutions.
Pricing Analysis
Long-term service contracts and subscription models define pricing for advanced analytical instruments and outsourced laboratory services. Price differentiation stems from the level of accreditation (e.g., ISO 17025 certification) and the volume of testing required by large food processing units. Pricing softness exists within the commoditized test kit segment, driven by competition among regional suppliers. Small and medium-sized food enterprises exhibit the highest price sensitivity for basic pathogen detection kits.
Supply Chain Analysis
Concentration of critical reagents production in a few key countries, including Germany and China, underwrites the global food diagnostics supply chain. Essential components like specialized enzymes and antibodies for PCR assays and ELISA kits represent significant dependencies. Single-source vulnerability for these highly specialized biological inputs poses a structural risk to the entire market. Downstream distribution relies on a hybrid model, with direct sales for high-value instruments and extensive distributor networks for test kits and consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The food diagnostics market presents a strong service-attach opportunity, with recurring analytical support and software subscriptions expanding faster than instrument sales.
For Market Incumbents: Consolidate market share through strategic acquisitions of specialized software firms or reagent developers. Expand accredited laboratory networks in emerging markets to counteract the threat from localized, low-cost testing solutions. Invest in R&D for next-generation sequencing automation to maintain a technological lead against new entrants.
For New Entrants and Emerging Players: Differentiate on rapid, on-site testing capabilities using portable biosensors or microfluidic platforms. Target underpenetrated segments such as small-scale food producers in Southeast Asia and Latin America. A viable go-to-market angle involves offering bundled subscription services that include basic operator training and real-time data integration.
For Investors and Strategic Acquirers: Carve-out targets emerge from larger diversified life science conglomerates seeking to divest non-core food safety divisions. The long-term viability of this market is strong, driven by increasing global food safety regulations over the next decade. A key signal to watch is the adoption rate of AI-driven data analytics platforms for interpreting complex genomic test results.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquire niche software providers | Integrates data analytics with diagnostic workflows for enhanced insights. |
| Expand accredited laboratory networks | Broadens geographic reach and ensures compliance with diverse regulatory standards. |
| Invest in portable biosensor R&D | Enables real-time, on-site testing, reducing production downtime for processors. |
| Develop subscription-based service models | Lowers capital expenditure barriers for small and medium-sized enterprises. |
| Focus on food fraud detection technologies | Addresses growing consumer concern and regulatory demand for authenticity verification. |
Research Approach
Initial hypotheses were tested against primary input from food safety managers, quality control directors, regulatory compliance officers, and diagnostic R&D scientists, then refined. This approach integrated insights from key industry stakeholders with secondary validation from sources such as FDA guidance documents, EFSA scientific opinions, national food safety reports, and company financial filings, ensuring a comprehensive understanding through bottom-up and top-down triangulation.
The analytical framework employs variance decomposition to project market trajectory across the analysis window. Segmentation dimensions modeled include product type, application, end-user, geographic region, and technology readiness level. Compound annual growth rates were derived through a combination of regression analysis and expert consensus. Industry-specific forecast inputs include regulatory enforcement trends and food processing investment cycles.
Material uncertainties — such as the emergence of new pathogens or geopolitical trade disputes — sit outside the modeled envelope. Forecasts reflect assumptions regarding technological stability and consistent regulatory enforcement. Practitioners should keep alternative scenarios live as food safety standards and supply chain dynamics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Screening Equipment Market
Food Safety Testing
Water Activity Meter Market
Food Safety Testing
Italy Food Safety Testing Market
Food Safety Testing
Food Allergen Testing Market
Food Safety Testing
Gum Content Tester Market
Food Safety Testing
Food and Beverage Protective Cultures Market
Food Safety Testing
Rapid Microbiology Testing Market
Food Safety Testing
Inline Beverage Gas and Microbial Load Monitoring Test Systems Market
Food Safety Testing
Salmonella Testing Market
Food Safety Testing
Food Tester Market
Food Safety Testing
Dairy Testing Services Market
Food Safety Testing
Salt Meter Market
Food Safety Testing
Testing, Inspection, and Certification in Consumer Goods and Retail Market
Food Safety Testing
Animal Feed Safety Testing Equipment Market
Food Safety Testing
North America Food Safety Testing Market
Food Safety Testing
Food Pathogen Testing Market