
 Meat Speciation Testing Service Market | 2026-2036
Meat Speciation Testing Service Market Size, Share, and Industry Trends Forecast 2026-2036
Meat Speciation Testing Service Market Insights
Turnkey laboratory outsourcing revenue is tilting away from in-house quality departments toward specialized service providers with accredited platforms. Eurofins Scientific leverages its pan-European laboratory network to anchor multi-site contracts with protein processors. ALS Limited competes through geographic reach across Asia-Pacific testing hubs. Neogen Corporation specializes in rapid PCR-based workflows that reduce turnaround times for slaughterhouse clients.
Meat speciation testing service denotes the analytical verification of animal species identity in raw, processed, or commingled meat products using DNA, protein, or mass-spectral methods, typically achieving detection thresholds below one percent adulterant concentration to satisfy commercial and regulatory thresholds for label accuracy. Polymerase Chain Reaction dominates routine screening due to its sensitivity and standardization across ISO 17025 laboratories. ELISA retains cost advantages for high-volume slaughter floor applications where speed outweighs genomic precision. Mass Spectrometry occupies the premium tier for complex mixtures and species differentiation in heavily processed matrices where DNA degradation limits PCR efficacy.
The FDA enforces species labeling through the Federal Food, Drug, and Cosmetic Act while the USDA Food Safety and Inspection Service mandates verification for imported meat shipments. EFSA coordinates member-state reference laboratories under harmonized analytical protocols that shape cross-border trade acceptance criteria. Stakeholders must monitor evolving genomic database expansions and accreditation reciprocity agreements that determine which laboratories can issue export-valid certificates without redundant testing.
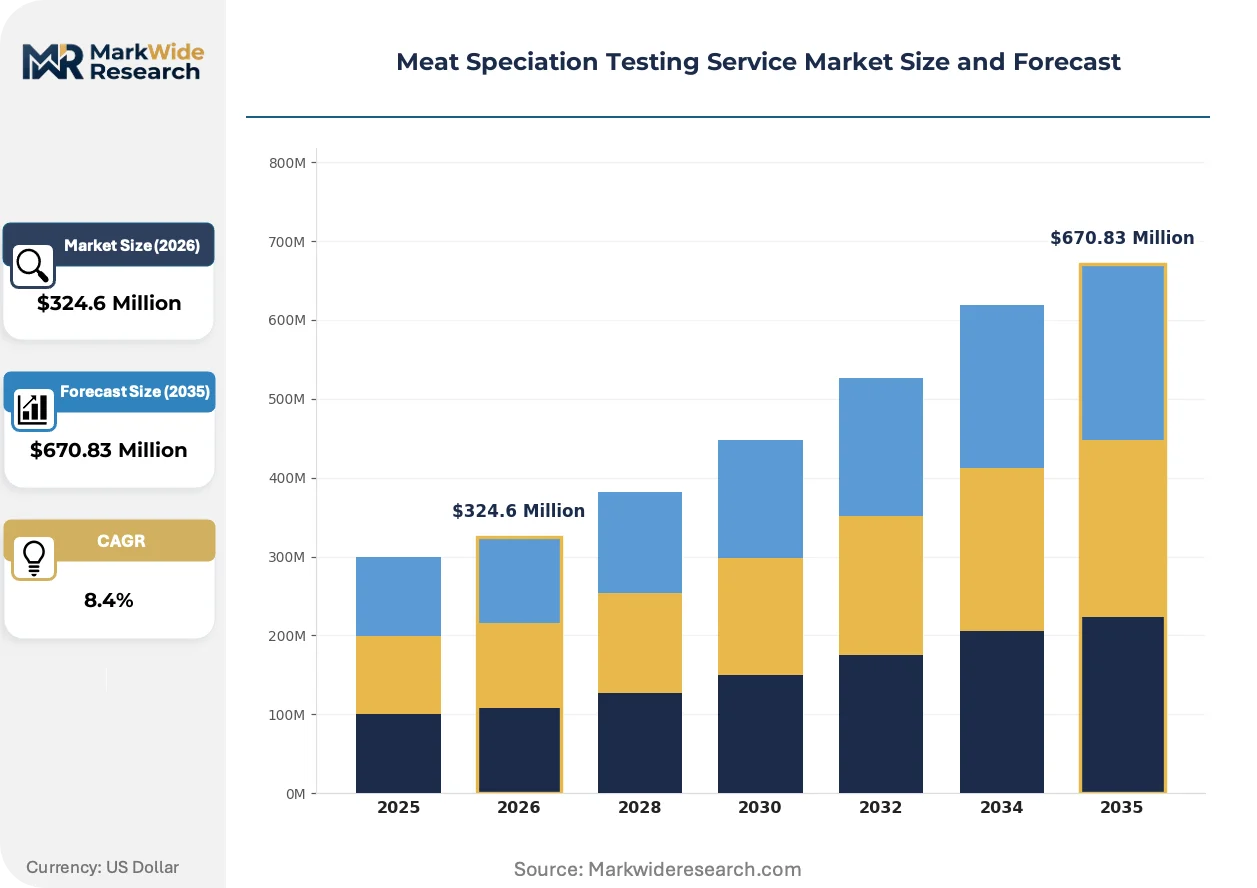
Market Dynamics
Turnkey laboratory outsourcing is displacing in-house quality departments as protein processors face escalating FDA and EFSA enforcement on species mislabeling, forcing reliance on accredited third-party platforms.
Growth Catalysts
- Regulatory Enforcement Intensification:The FDA's Federal Food, Drug, and Cosmetic Act and USDA FSIS import verification mandates are compelling slaughterhouses to document species identity through ISO 17025-certified laboratories.
- PCR Standardization:Polymerase Chain Reaction protocols achieve detection thresholds below one percent adulterant concentration, satisfying commercial label accuracy requirements for export-oriented supply chains.
- Brand Integrity Protection:Large-scale meat processors in the United States, Germany, and China are expanding third-party testing contracts to prevent reputational damage from species substitution incidents.
Market Restraints
- High Capital Equipment Costs:Mass spectrometry platforms for complex mixture analysis require substantial upfront investment, limiting adoption among mid-tier service laboratories.
- DNA Degradation in Processed Matrices:Heavily processed meat products degrade genomic material, forcing reliance on protein-based methods with higher detection thresholds.
- Accreditation Reciprocity Fragmentation:Divergent national recognition of ISO 17025 certificates creates redundant testing requirements for cross-border meat shipments.
Strategic Opportunities
- Asia-Pacific Testing Hub Expansion:China's export-oriented meat processing sector demands rigorous documentation for international shipments, creating laboratory capacity gaps.
- Rapid ELISA Workflow Integration:Slaughterhouse floor applications prioritize speed over genomic precision, opening cost-advantaged service tiers for high-volume screening.
- Genomic Database Convergence:Expanding reference libraries enable next-generation sequencing differentiation of closely related species in commingled products.
Industry Challenges
- Specialized Technician Shortage:Molecular biology expertise for PCR-based workflows remains scarce in secondary testing markets, constraining laboratory scale-up.
- Legacy System Integration Friction:Slaughterhouse clients face operational disruption when connecting third-party laboratory data management systems to existing quality control infrastructure.
- Accreditation Timeline Compression:ISO 17025 certification processes extend 12-18 months, delaying market entry for emerging service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meat Speciation Testing Service Market |
| Market Size in 2026 | $324.6 Million |
| Market Size in 2035 | $670.83 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymerase Chain Reaction, ELISA, Mass Spectrometry, NGS Application: Food Safety, Quality Control, Regulatory Compliance, Supply Chain Verification End User: Food Manufacturers, Testing Laboratories, Regulatory Agencies, Retailers Technology: Molecular Biology, Biochemical Assays, Genomics, Microbial Analysis |
| Companies Covered | Eurofins Scientific, ALS Limited, Neogen Corporation, LGC Limited, VWR International LLC, Thermo Fisher Scientific, Intertek Group, SGS, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meat Speciation Testing Service Market Trends and Innovations
Next-generation sequencing and digital PCR platforms are compressing detection timelines while regulatory harmonization efforts reshape cross-border certificate acceptance criteria.
Real-time PCR instrumentation is migrating from centralized reference laboratories toward satellite facilities embedded within major protein processing clusters. Slaughterhouse operators in the United States and Germany are adopting portable thermocycler units for same-day screening decisions. This geographic decentralization is compressing turnaround times from days to hours for routine species verification.
EFSA's coordination of member-state reference laboratories under harmonized analytical protocols is standardizing cross-border trade acceptance criteria. Protein processors exporting from the European Union now face unified documentation requirements rather than fragmented national standards. German and French laboratories are consolidating multi-site contracts under pan-European accreditation reciprocity agreements.
Outcome-based service contracts are displacing per-test pricing structures among large-volume meat processors. Major protein exporters in China and the United States now negotiate annual retainer agreements with guaranteed turnaround service levels. This procurement evolution locks in laboratory capacity during peak slaughter seasons and stabilizes revenue predictability for service providers.
Meat Speciation Testing Service Market Segmentation
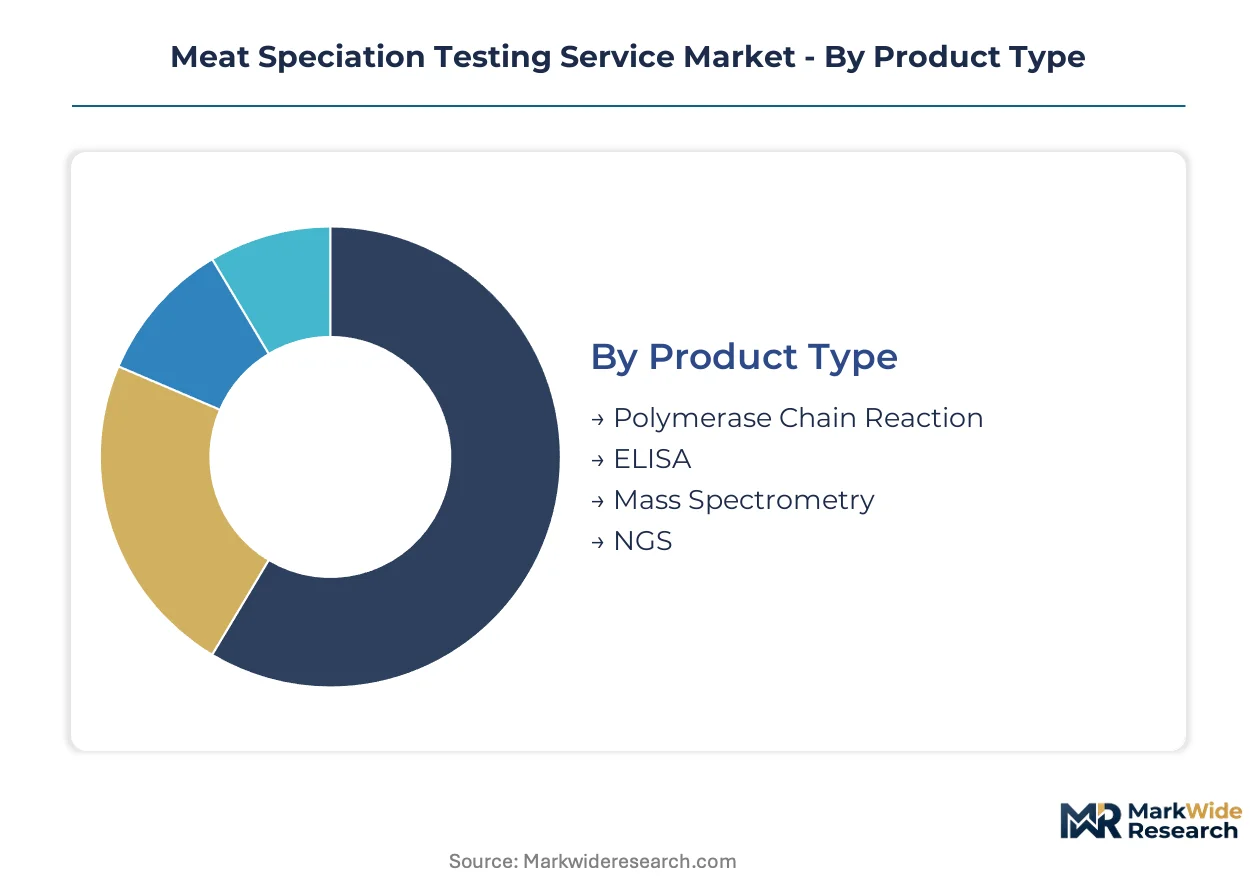
Meat speciation testing services fragment across method platforms, use cases, and customer workflows that each demand distinct service level agreements, turnaround commitments, and technical accreditation. Segmentation clarity enables laboratories to align capacity investments with the highest-margin verification demands across slaughterhouse, processor, and export documentation chains.
Product Type:
After-sales calibration intensity varies sharply across analytical platforms, with PCR and mass spectrometry requiring continuous reagent standardization and instrument qualification that locks clients into multi-year service relationships.
- Polymerase Chain Reaction:DNA amplification achieves detection thresholds below one percent adulterant concentration through species-specific primer sets. United States slaughterhouses deploy PCR for same-day export certificate generation where USDA FSIS mandates ISO 17025 documentation. The platform dominates high-value contract structures due to regulatory acceptance breadth.
- ELISA:Antibody-based protein detection offers cost advantages for high-volume screening where speed outweighs genomic precision. German meat processors integrate ELISA workstations directly onto slaughter floors for real-time species verification during peak production windows. The method sacrifices sensitivity for operational throughput.
- Mass Spectrometry:Peptide fingerprinting resolves complex mixtures in heavily processed matrices where DNA degradation limits PCR efficacy.
- NGS:Next-generation sequencing enables untargeted species identification in commingled products without prior sequence knowledge.
PCR holds the largest share; momentum sits with NGS as reference database expansion reduces per-sample analysis costs.
Application:
Margin profiles diverge across application types, with regulatory compliance commanding premium pricing due to certificate liability exposure and audit trail requirements.
- Food Safety:Pathogen co-detection protocols combine species verification with microbiological screening for integrated hazard analysis. Chinese export processors face dual documentation requirements from SAMR and destination country regulators, consolidating testing spend with accredited multi-service laboratories.
- Quality Control:Routine incoming material inspection prevents species substitution before commingling obscures traceability. United States protein manufacturers embed third-party testing into supplier qualification programs to protect brand integrity against mislabeling incidents.
- Regulatory Compliance:Export certificate generation demands ISO 17025 accreditation recognized by destination country authorities.
- Supply Chain Verification:Blockchain-linked testing creates immutable species documentation for premium product claims.
Regulatory compliance generates the highest revenue per test; supply chain verification is climbing fastest as traceability investments accelerate.
End User:
Procurement sophistication separates customer tiers, with testing laboratories negotiating volume commitments that food manufacturers cannot match individually.
- Food Manufacturers:Slaughterhouses and processors outsource verification to avoid capital expenditure on analytical infrastructure while accessing accredited expertise. German meatpackers consolidate multi-site contracts under pan-European service agreements to harmonize documentation across EFSA member-state requirements.
- Testing Laboratories:Reference laboratories subcontract overflow capacity to satellite facilities during peak slaughter seasons. China's export-oriented testing hubs face capacity constraints as international shipment volumes expand.
- Regulatory Agencies:Government enforcement laboratories require method standardization for legal defensibility.
- Retailers:Private-label programs mandate species verification to mitigate reputational risk from supplier non-conformance.
Testing laboratories represent the largest addressable spend; retailers are expanding contract fastest as private-label meat portfolios proliferate.
Technology:
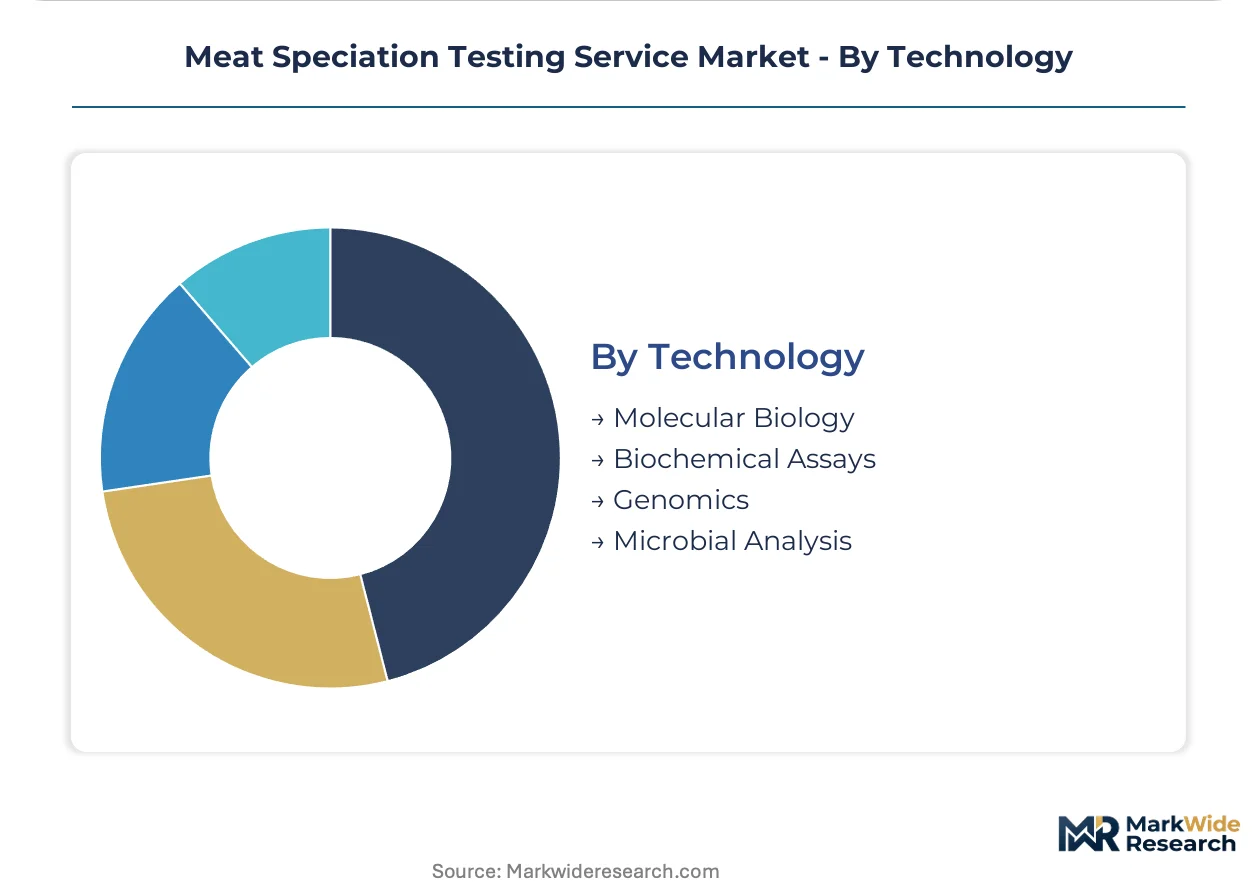
Maturity curves separate technology categories, with molecular biology approaching commoditization while genomics retains differentiation through database depth.
- Molecular Biology:PCR workflows achieve standardization across ISO 17025 laboratories that simplifies client procurement and reduces qualification burden. United States service providers compete on turnaround time compression rather than methodological differentiation.
- Genomics:Next-generation sequencing differentiation depends on proprietary reference library construction and bioinformatics pipeline optimization. Chinese laboratories invest in domestic species genome sequencing to reduce reliance on Western genomic databases.
- Biochemical Assays:ELISA retains cost positioning for applications where detection threshold relaxation is commercially acceptable.
- Microbial Analysis:Species-specific microbiome profiling offers emerging differentiation for fermented meat product verification.
Molecular biology commands dominant share; genomics is expanding most quickly as sequencing costs decline and database coverage broadens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. United States slaughterhouses absorb premium PCR pricing for USDA certificate compliance. German processors negotiate volume discounts under pan-European contracts. Chinese exporters face the steepest cost pressure as dual domestic and destination-country testing erodes margins.
United States
USDA Food Safety and Inspection Service mandates ISO 17025 documentation for all imported meat shipments, forcing processors to maintain accredited laboratory relationships. FDA enforcement under the Federal Food, Drug, and Cosmetic Act intensifies species mislabeling penalties. Nebraska and Iowa slaughterhouse clusters embed satellite PCR facilities for same-day export certificate generation during peak beef production seasons.
Germany
EFSA-coordinated reference laboratory protocols standardize cross-border documentation for protein processors exporting across the European Union. The country's federal food safety authority enforces harmonized analytical methods that reduce redundant testing burdens. Bavarian and North Rhine-Westphalian meatpacking corridors consolidate multi-site contracts under pan-European accreditation reciprocity agreements.
China
SAMR and destination-country regulators impose dual documentation requirements on export-oriented processors, consolidating testing spend with accredited multi-service laboratories. The national genomic database expansion program reduces reliance on Western reference libraries. Shandong Peninsula and Yangtze River Delta processing hubs face acute laboratory capacity constraints as international shipment volumes accelerate.
United Kingdom
Post-EU regulatory divergence forces UK processors to maintain parallel accreditation pathways for EU and non-EU export destinations. The Food Standards Agency enforces species verification standards that diverge incrementally from EFSA protocols. Midlands and Eastern England meat processing belts negotiate outcome-based service contracts with guaranteed turnaround commitments during seasonal slaughter peaks.
Brazil
ANVISA coordinates with destination-country regulators to align export certificate requirements for beef and poultry shipments. The federal agricultural inspection service mandates species documentation for processed meat products entering regulated markets. São Paulo and Paraná protein processing corridors invest in third-party laboratory outsourcing to avoid capital expenditure on analytical infrastructure.
Meat Speciation Testing Service Market Competitive Landscape
Pan-European laboratory networks and Asia-Pacific testing hubs split the market between regulatory proximity and geographic reach. Consolidation pressure intensifies as protein processors demand multi-site contract harmonization. Three archetypes dominate: accredited reference laboratories with ISO 17025 platforms, rapid-turnover specialists with embedded slaughterhouse workflows, and diversified testing conglomerates with cross-border certificate reciprocity. M&A activity targets regional capacity gaps while strategic partnerships lock in annual retainer agreements with volume guarantees.
Within the reference laboratory tier, Eurofins Scientific and LGC Limited exemplify pan-European accreditation breadth. ALS Limited anchors Asia-Pacific geographic coverage. Neogen Corporation occupies a position among rapid-turnover specialists serving slaughterhouse floor applications.
| Leading Market Players |
|---|
| Eurofins Scientific |
| ALS Limited |
| Neogen Corporation |
| LGC Limited |
| VWR International LLC |
| Thermo Fisher Scientific |
| Intertek Group |
| SGS |
| Bio-Rad Laboratories |
| Others |
Pricing and Supply Chain Analysis
Shandong Peninsula laboratory clusters anchor capacity expansion for China's export-oriented meat processors, translating acute demand into premium pricing power for ISO 17025-accredited service providers during peak slaughter seasons.
Pricing Analysis
After-sales calibration revenue locks clients into multi-year service relationships through continuous reagent standardization and instrument qualification. Three-tier pricing structure across premium, standard, and economy levels separates regulatory compliance certificates from routine quality control screening and rapid ELISA floor testing. Cost compression in economy-tier ELISA services is intensifying because slaughterhouse operators prioritize throughput over genomic precision. Small-scale processors in secondary markets exhibit the highest price sensitivity, while export-oriented protein manufacturers absorb premium PCR pricing for USDA and EFSA documentation.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for reagent and instrument procurement. Analytical platform manufacturing concentrates in the United States, Germany, and Japan, while specialty reagent production draws from Singapore and South Korea. Single-source vulnerability in thermocycler component supply threatens turnaround commitments during seasonal demand spikes. Distribution runs through accredited laboratory networks with embedded satellite facilities rather than centralized reference hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Next-generation sequencing cost compression is disrupting established PCR-dominant workflows, creating acceleration windows for laboratories with proprietary genomic database depth.
For Market Incumbents: Pre-empt emerging NGS specialists by consolidating multi-site contracts under pan-European accreditation reciprocity agreements before database convergence commoditizes species differentiation. Eurofins Scientific and ALS Limited should anchor capacity expansion in China's Yangtze River Delta processing corridor, where export documentation demand outstrips laboratory supply. Defensive certification investment in SAMR-recognized ISO 17025 platforms protects against regulatory divergence between Chinese and Western acceptance criteria. For New Entrants and Emerging Players: Mid-tier slaughterhouses in Brazil's São Paulo protein corridor represent the most penetrable entry point, where ANVISA export requirements are tightening without proportional laboratory capacity expansion. Portable PCR workstation leasing for same-day screening decisions offers a differentiated go-to-market angle against established reference laboratory contracts. Target German meatpacking cooperatives seeking to disaggregate pan-European service agreements into regional satellite relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors laboratories with hybrid PCR-NGS platform flexibility over pure-play genomic specialists facing reference database capital intensity. Long-term viability across the analysis window hinges on accreditation reciprocity breadth rather than methodological differentiation alone. Watch for EFSA-USDA mutual recognition agreement progress as the signal indicating consolidation timing for cross-border certificate-issuing laboratories.| Strategic Initiative | Industry Significance |
|---|---|
| Accreditation Reciprocity Expansion | Pan-European ISO 17025 mutual recognition reduces redundant testing costs for German exporters under EFSA coordination. |
| Portable PCR Workstation Deployment | Embedded thermocycler units in Nebraska and Iowa slaughterhouse clusters compress turnaround from days to hours. |
| Domestic Genomic Database Construction | Chinese national genome sequencing programs reduce Western reference library dependency for SAMR export documentation. |
| Outcome-Based Service Contract Migration | Annual retainer agreements with volume guarantees stabilize revenue predictability during seasonal slaughter peaks. |
| NGS Platform Integration | Next-generation sequencing differentiation captures premium pricing for commingled product verification where PCR fails. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across laboratory directors, protein processor quality managers, regulatory affairs specialists at accreditation bodies, and reagent procurement leads. Secondary validation drew from USDA FSIS enforcement records, EFSA reference laboratory protocols, SAMR export documentation requirements, ISO 17025 accreditation databases, and customs trade data for analytical instrument imports. Bottom-up testing volume estimates triangulated against top-down market sizing through accredited laboratory capacity assessments.
Calibration against historical regulatory enforcement intensity and laboratory outsourcing adoption curves anchored projections across the analysis window. Segmentation dimensions modeled include method platform, application type, end-user procurement sophistication, and geographic regulatory cluster. CAGRs derived from testing volume elasticity to export shipment growth and accreditation mandate expansion. Industry-specific inputs incorporated PCR reagent cost decline curves and NGS per-sample analysis cost convergence timelines.
Stress conditions across SAMR-USDA mutual recognition progress, thermocycler component supply disruption, and genomic database licensing fragmentation were modeled; outcomes outside those bands fall beyond the analytical envelope. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Water Quality Testing Market
Food Safety Testing
Chromatography Food Testing Market
Food Safety Testing
Central & South America Food Safety Testing Market
Food Safety Testing
Food and Beverage Protective Cultures Market
Food Safety Testing
Gum Content Tester Market
Food Safety Testing
Edible Oil Adulteration Testing Chemicals Market
Food Safety Testing
North America Consumer Product Safety Testing Market
Food Safety Testing
UK Food Testing Market
Food Safety Testing
Global Food Authenticity Testing Market
Food Safety Testing
US Legionella Testing Market
Food Safety Testing
Meat Species Identification Kits Market
Food Safety Testing
Ireland Food Testing Market
Food Safety Testing
Food and Beverages Disinfection Market
Food Safety Testing
Food Testing Services Market
Food Safety Testing
Adulteration Tester Market
Food Safety Testing
US Food Safety Testing Market