
 Food Certification Market | 2026-2036
Food Certification Market Size, Share, and Industry Trends Forecast 2026-2036
Food Certification Market Intelligence
Subscription-based access to digital auditing and compliance management platforms is shifting the service delivery model for food certification. SGS leverages its vast global testing infrastructure to support multi-country certifications for large food manufacturers. Bureau Veritas specializes in risk management and compliance for complex agricultural and food processing supply chains. Intertek Group plc competes through its comprehensive testing, inspection, and certification service portfolio.
Food certification is a third-party conformity assessment process that verifies a food product, process, or system meets predetermined standards. This involves rigorous auditing, testing, and inspection to confirm claims such as adherence to ISO 22000 for food safety management or specific compositional attributes. Within certification types, Organic and Non-GMO certifications command significant volume, driven by consumer demand for transparency. The beverages and processed meat product categories show high demand for specialized certifications like Gluten-Free to appeal to health-conscious demographics.
Regulatory frameworks established by bodies like the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) mandate baseline safety and labeling accuracy. In China, the State Administration for Market Regulation (SAMR) enforces stringent food laws, creating a market for voluntary certifications as a mark of quality. Stakeholders must now decide whether to invest in digital traceability systems or risk losing market access as proof-of-origin becomes a standard expectation.
Market Dynamics
The imperative for verifiable supply chain transparency acts as the central structural force in the food certification market. This pressure arises from heightened consumer demand in key markets like China for validated proof of food safety and quality claims.
Growth Catalysts
- Regulatory Enforcement:Stringent food laws enforced by bodies like China's SAMR create a strong pull for voluntary certifications as a competitive differentiator beyond baseline compliance, especially for imported goods.
- Clean-Label Demand:Consumer preference for clean-label products, particularly within the global beverages sector, necessitates third-party certifications such as Non-GMO or Organic to validate marketing claims and build trust.
- Digital Traceability:The adoption of blockchain technology provides an immutable and auditable record of a product's journey, offering certification bodies a powerful tool to verify origin and handling claims efficiently.
Market Restraints
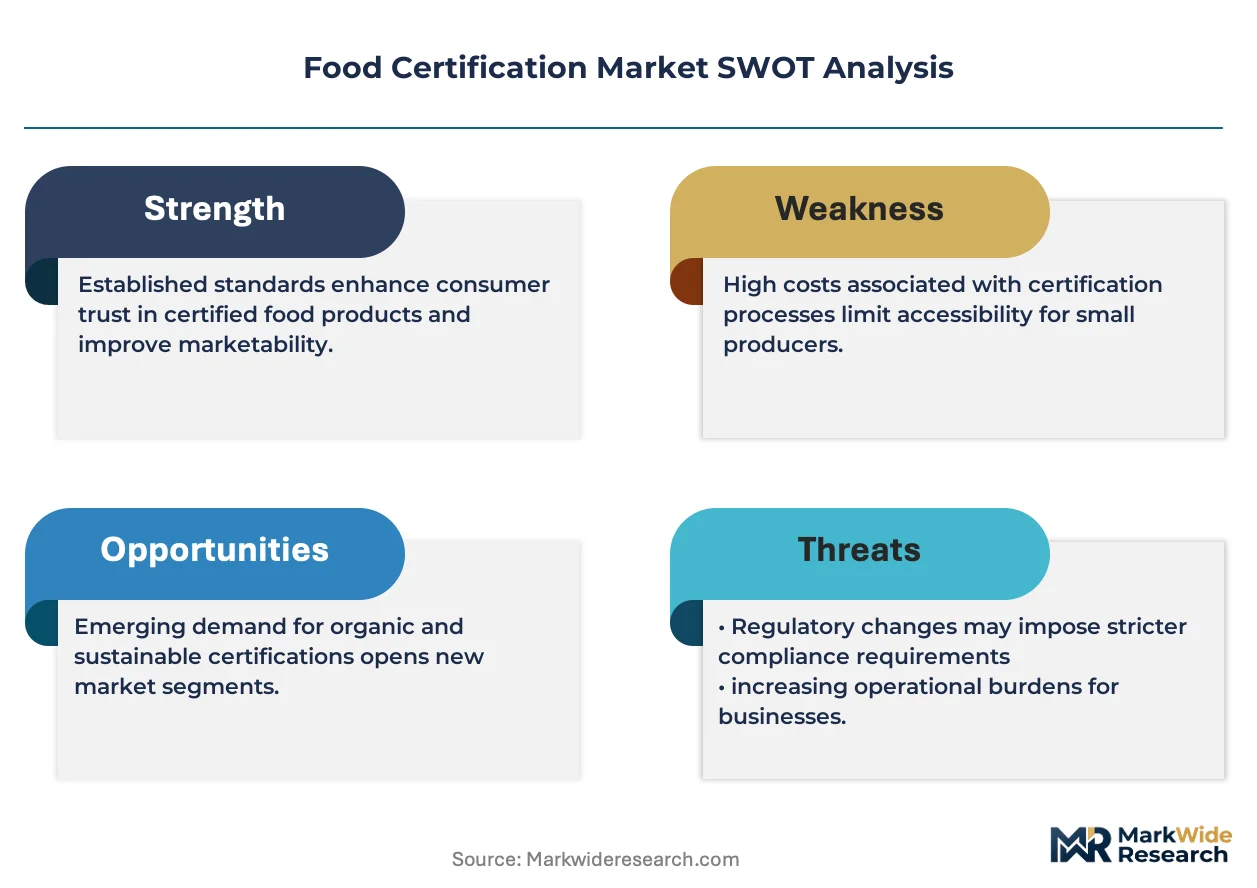
- High Implementation Cost:The significant capital investment required to deploy digital traceability systems and meet rigorous certification standards presents a substantial barrier for small and medium-sized food producers.
- Navigational Complexity:Divergent and complex regulatory frameworks, such as those from the US FDA and the European EFSA, increase the cost and difficulty of securing multi-country certifications for global food exporters.
- Audit Process Duration:The lengthy and resource-intensive nature of on-site audits and laboratory testing for certifications like ISO 22000 can delay product launches and create operational bottlenecks for manufacturers.
Strategic Opportunities
- Subscription-Based Platforms:The development of digital auditing and compliance management platforms offered on a subscription basis creates a new, recurring revenue stream and lowers the entry barrier for clients.
- Alternative Protein Certification:The expanding market for plant-based and alternative protein products opens a new frontier for specialized certifications related to ingredient sourcing, processing methods, and allergen-free claims.
- Emerging Market Expansion:Rising disposable incomes and food safety concerns in Southeast Asian and Latin American nations present untapped geographic markets for certification services beyond established regions.
Industry Challenges
- Auditor Talent Scarcity:A persistent shortage of qualified auditors possessing dual expertise in food science and emerging digital technologies like blockchain limits the capacity of certification bodies to scale their services.
- Legacy System Integration:Integrating modern digital auditing platforms with the disparate and often outdated IT infrastructure of large, established food manufacturers poses a significant technical and operational challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Certification Market |
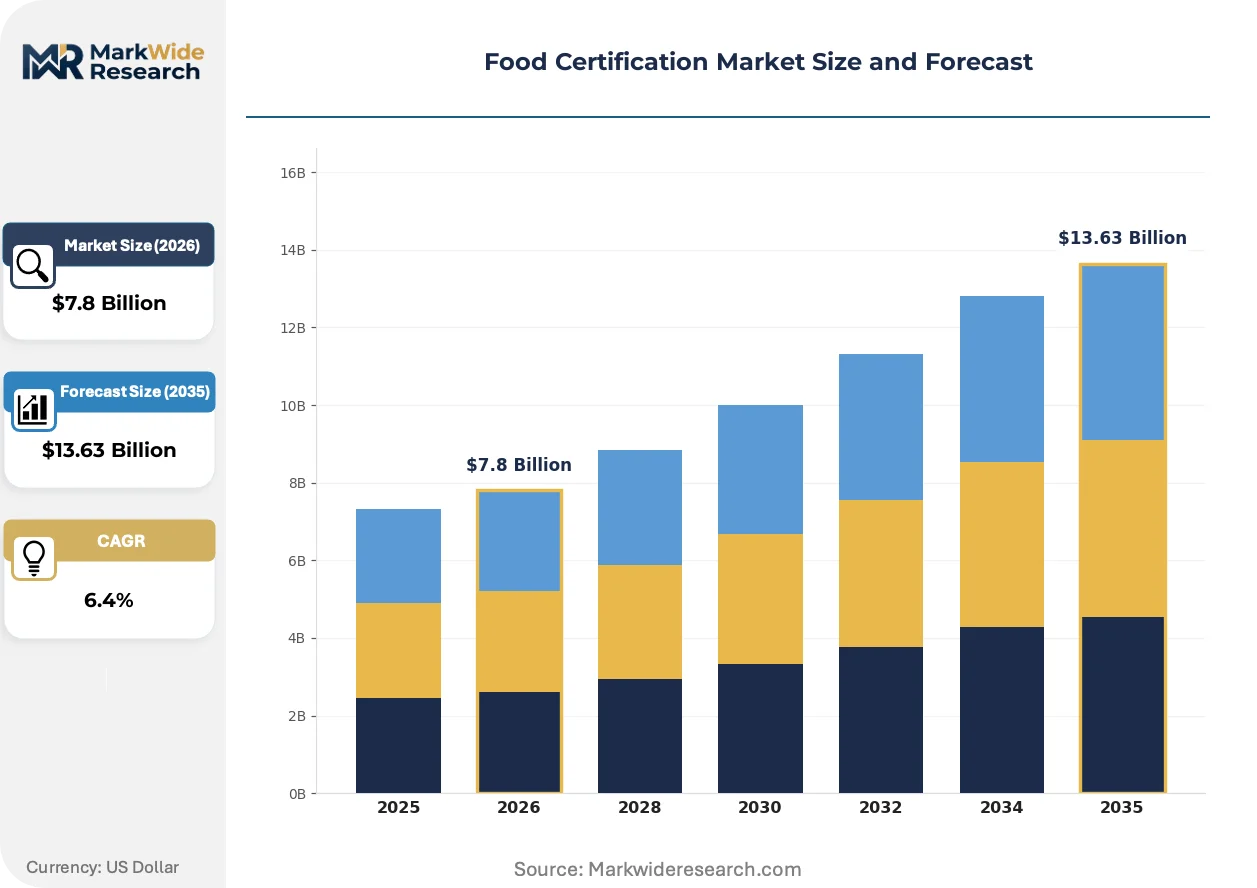
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Certification Type: Organic, Gluten-Free, Non-GMO, Fair Trade Product Category: Dairy, Meat, Vegetables, Beverages End User: Consumers, Retailers, Food Manufacturers, Wholesalers Market Channel: Online, Supermarkets, Specialty Stores, Food Service |
| Companies Covered | DEKRA, TÜV SÜD, SGS, Kiwa, LRQA, Bureau Veritas, DNV, ALS Limited, Intertek Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Certification Market Strategic Shifts & Innovations
The food certification market is transitioning from periodic, manual audits to a model of continuous, data-driven assurance. This evolution is driven by the digitalization of compliance verification and a demand for more dynamic proof of product integrity throughout the supply chain.
Digital auditing platforms that integrate with a client's existing enterprise resource planning systems represent a significant product evolution. Large manufacturers in the processed meat and dairy sectors are adopting these tools to streamline data submission for compliance. This technology is automating the collection and cross-referencing of supply chain data, reducing the administrative burden of preparing for an audit.
Regulatory mandates for greater transparency are becoming more stringent, with a notable example being the European Food Safety Authority's (EFSA) enhanced requirements for proof-of-origin. This forces exporters to adopt more robust traceability systems to maintain access to the EU market. The seafood and specialty agricultural product categories are most impacted, investing in digital tracking to comply with import controls.
Consumer purchasing decisions are increasingly influenced by a product's entire ethical and environmental footprint, moving beyond single-attribute claims. This behavioral shift disrupts the traditional, siloed certification model, favoring providers who can offer bundled audits for sustainability, fair trade, and animal welfare. The trend is most visible in the coffee, cocoa, and palm oil supply chains.
Food Certification Market Segmentation
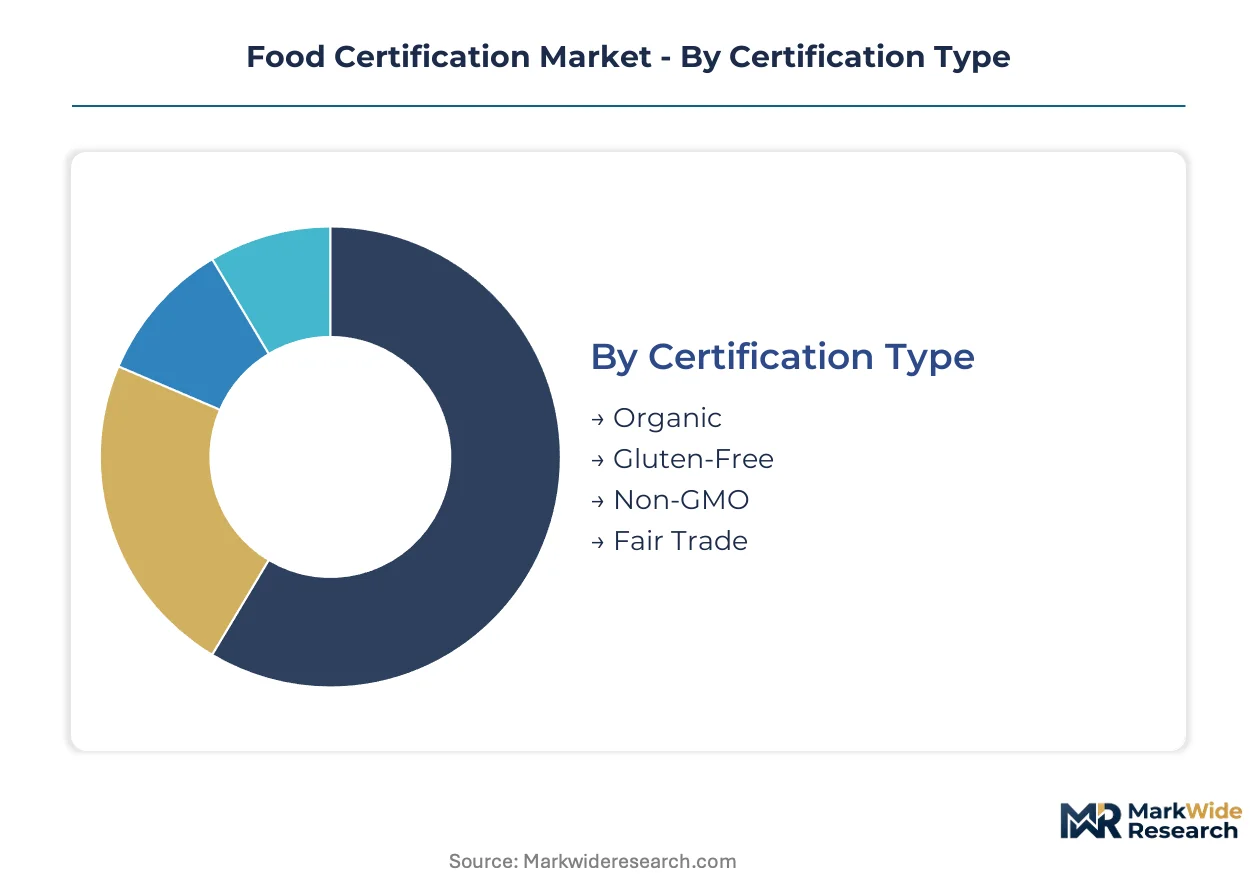
The Food Certification Market exhibits diverse demand patterns, driven by varying consumer preferences and regulatory requirements. Analyzing these distinct categories provides a clearer understanding of specific compliance burdens and market opportunities. This granular view helps stakeholders tailor service offerings and investment strategies effectively.
Certification Type:
Different certification types impose distinct auditing and verification burdens on food producers, directly influencing market access and consumer trust.
- Organic:This certification verifies products are produced without synthetic pesticides, fertilizers, or genetically modified organisms, adhering to strict national and international standards. Demand concentrates in European and North American markets, driven by health-conscious consumers seeking natural food options and transparent production methods.
- Non-GMO:This certification confirms that food products are free from genetically modified ingredients, requiring rigorous testing and supply chain documentation. Consumer demand for Non-GMO verification is strong in the United States and China, where transparency regarding ingredient origin drives purchasing decisions.
- Gluten-Free:This certification assures consumers that products contain no detectable gluten, crucial for individuals with celiac disease or gluten sensitivities.
- Fair Trade:This certification ensures ethical sourcing and equitable compensation for producers, particularly in commodities like coffee, cocoa, and sugar.
Organic certification sits at the top of the volume ranking, with Non-GMO climbing the fastest.
Product Category:
Product categories dictate the specific food safety protocols and quality attributes requiring third-party verification, influencing certification complexity.
- Beverages:This category includes a wide array of drinks, from juices to plant-based milks, often requiring certifications for clean-label claims and allergen management. Demand is pronounced in global markets, where consumers prioritize health-focused options and ingredient transparency.
- Meat:This category encompasses fresh, frozen, and processed meat products, necessitating stringent certifications for animal welfare, origin, and foodborne pathogen control. China and Europe exhibit high demand for certified meat, driven by food safety concerns and regulatory oversight.
- Dairy:This category covers milk, cheese, and yogurt, requiring certifications for quality, origin, and allergen management, especially for organic variants.
- Vegetables:This category includes fresh and processed produce, where certifications verify organic status, pesticide residue limits, and sustainable farming practices.
Beverages and meat products drive significant demand for specialized certifications.
End User:
Each end-user segment has distinct motivations for seeking certified products, influencing the adoption rate and type of certification required.
- Food Manufacturers:These entities require certifications to ensure compliance with regulatory standards, validate product claims, and gain market access for their processed goods. They seek external verification to mitigate risk and enhance brand reputation with both retailers and end consumers.
- Retailers:These businesses demand certified products to build consumer trust, meet private label standards, and differentiate their offerings in competitive markets. They often leverage certifications to assure customers of quality, safety, and ethical sourcing.
- Consumers:These individuals drive demand for certifications that validate health claims, ethical sourcing, and environmental impact, influencing purchasing decisions.
- Wholesalers:These intermediaries require certifications to ensure product quality and regulatory compliance for bulk distribution to diverse downstream clients.
Food manufacturers and retailers increasingly rely on certifications to assure product integrity.
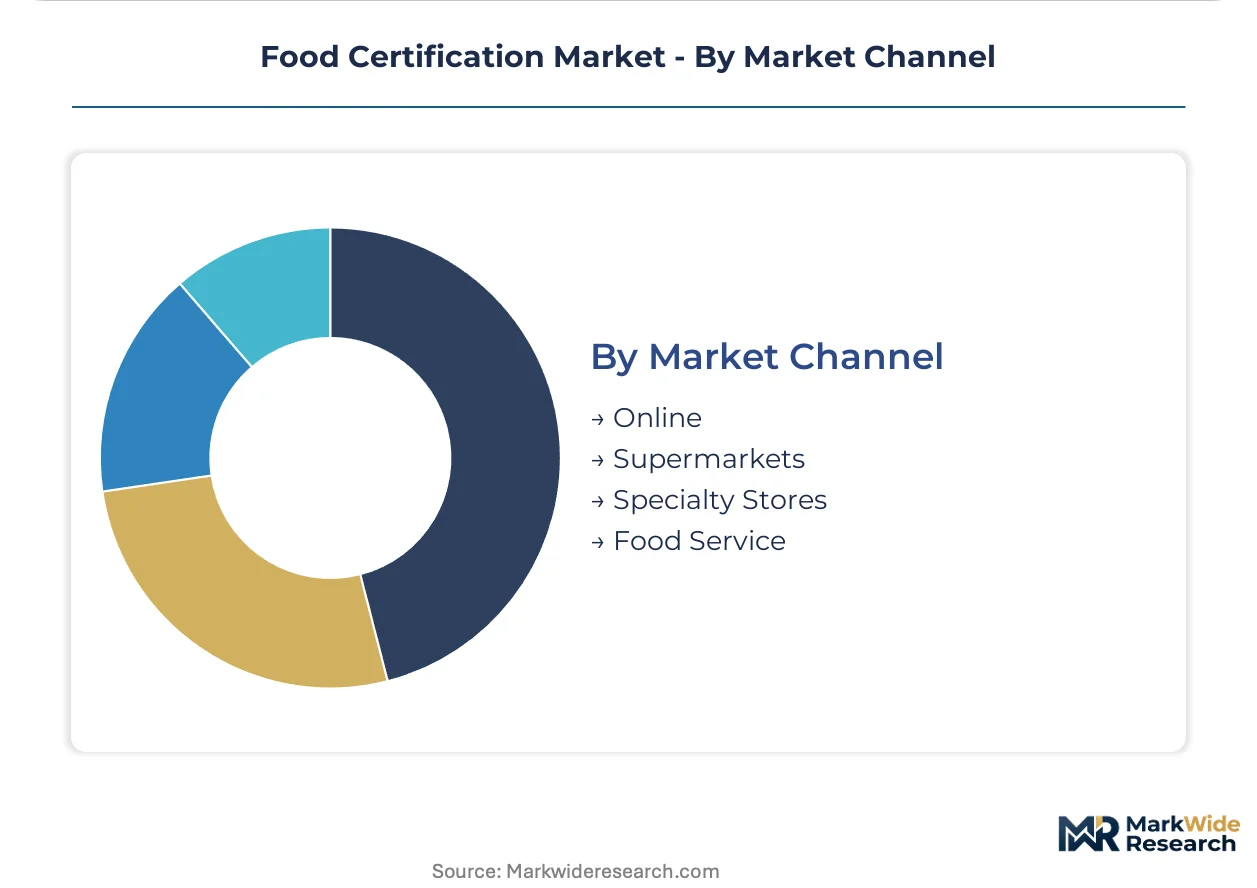
Market Channel:
Market channels influence the visibility and importance of certifications, as different platforms cater to varying consumer expectations and purchasing behaviors.
- Supermarkets:These large-format retail outlets represent a primary distribution channel for certified food products, appealing to a broad consumer base with diverse needs. They often feature dedicated sections for organic or specialty items, driving significant volume for certified goods.
- Online:This channel leverages digital platforms for direct-to-consumer sales, where detailed product information and certifications are critical for building trust and transparency. E-commerce platforms facilitate direct access for niche certified products to a global audience.
- Specialty Stores:These outlets focus on niche markets, offering premium certified products that cater to specific dietary preferences or ethical consumer values.
- Food Service:This segment includes restaurants, cafes, and institutional caterers, requiring certified ingredients to meet health regulations and consumer dietary demands.
Supermarkets remain a high-volume channel, while online platforms gain share for certified goods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's stringent food safety laws drive significant demand for certification, contrasting with the United States where consumer health preferences largely shape market adoption. This global market for food certification shows varied regional dynamics. Regulatory frameworks and consumer expectations across different continents influence market growth.
China
China's consumers increasingly demand validated proof of food safety and quality claims. The State Administration for Market Regulation (SAMR) enforces stringent food laws, creating a market for voluntary certifications. The Yangtze River Delta region sees increasing investment in digital traceability systems by food manufacturers.
United States
Consumer preference for clean-label products necessitates third-party certifications like Non-GMO and Organic. The US Food and Drug Administration (FDA) mandates baseline safety and labeling accuracy for all food products. California's agricultural sector actively seeks organic and sustainable farming certifications for export markets.
Germany
Germany's market prioritizes high standards for food quality, organic products, and sustainability. European Food Safety Authority (EFSA) requirements for proof-of-origin significantly impact food exporters. Bavaria's prominent dairy industry focuses on certifications for quality, origin, and allergen management for its premium offerings.
India
Rising disposable incomes and increasing food safety concerns are driving demand for certified products in India. The Food Safety and Standards Authority of India (FSSAI) strengthens food safety regulations across the country. Maharashtra's processed food sector is adopting international certifications to meet export standards.
Brazil
Brazil's large agricultural and meat export sectors require extensive certifications for global market access. ANVISA, the national health surveillance agency, enforces rigorous food safety and quality standards. São Paulo's major meat processing facilities often seek certifications for animal welfare and origin for international distribution.
Food Certification Market Key Industry Players
Top-tier vendors anchor the global food certification market, while specialized regional players cater to niche demands. The market exhibits a tiered structure, with a few large multinational corporations dominating comprehensive service offerings. Strategic archetypes include global testing, inspection, and certification providers, risk management consultants, and emerging digital compliance platform developers. Geographic expansion into new markets and the adoption of advanced digital traceability solutions represent dominant competitive moves.
At the scale-driven end, SGS, a Swiss-based company, exemplifies the global testing, inspection, and certification giant archetype. Bureau Veritas, a French-headquartered corporation, represents a specialist in risk management and compliance for complex food supply chains. Intertek Group plc, a UK-based entity, occupies a position offering comprehensive testing, inspection, and certification services. These entities leverage their vast infrastructure and expertise to support multi-country certifications for large food manufacturers.
| Leading Market Players |
|---|
| DEKRA |
| TÜV SÜD |
| SGS |
| Kiwa |
| LRQA |
| Bureau Veritas |
| DNV |
| ALS Limited |
| Intertek Group plc |
Cost & Logistics Intelligence
Blockchain technology integration for supply chain transparency simultaneously reshapes cost economics for verification processes and concentrates auditable proof for certification bodies. This digital transformation influences how services are priced and where expertise is sourced globally.
Pricing Analysis
Capacity additions in digital auditing platforms are reshaping price floors for compliance services. The dominant pricing model is evolving towards subscription-based access for digital auditing and compliance management platforms. Price differentiation stems from the certification level, such as ISO 22000 adherence, and the volume scale of food manufacturers. Pricing softness reflects the increasing competition among digital solution providers. Small and medium-sized food producers exhibit the highest price sensitivity, while large multinational corporations prioritize comprehensive service integration.
Supply Chain Analysis
Auditor talent availability in key manufacturing geographies like China and the United States significantly impacts service delivery. The supply of certification services draws from a global network of testing laboratories and inspection personnel. Raw material dependencies include specialized software for digital auditing platforms and a skilled workforce proficient in food science and blockchain technologies. Single-source vulnerability in niche technological expertise represents a structural risk. Distribution of certification services runs through direct engagement with food manufacturers and partnerships with digital platform providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a geographic-arbitrage play, with China's stringent food safety laws creating a higher compliance cost differential compared to less regulated markets.
For Market Incumbents: Anchor global testing infrastructure to support multi-country certifications for large food manufacturers. Invest in advanced digital traceability systems to counter emerging digital compliance platform developers. Leverage existing client relationships to bundle new sustainability and ethical sourcing audits. Capacity additions in digital auditing platforms in Europe will reinforce market leadership against regulatory shifts like EFSA's proof-of-origin requirements.
For New Entrants and Emerging Players: China's SAMR enforcement opens a window for specialized certifications focusing on imported goods. Target the alternative protein market with tailored certifications for ingredient sourcing and processing methods. Focus on subscription-based digital auditing platforms to lower entry barriers for small and medium-sized food producers. Expand into Southeast Asian nations, leveraging rising disposable incomes and food safety concerns with a cost-effective digital go-to-market angle.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional certification bodies with strong local market penetration but limited digital capabilities. Long-term viability rests on the essential role of third-party verification for market access and consumer trust. Target specialized digital platform developers offering blockchain-enabled traceability solutions. The adoption rate of continuous, data-driven assurance models serves as a critical signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Platform Integration | Streamlines compliance data submission for food manufacturers, reducing audit duration. |
| Alternative Protein Certification | Captures a rapidly expanding market segment driven by health-conscious consumer demand. |
| Emerging Market Expansion | Accesses untapped geographic markets with growing food safety concerns and disposable incomes. |
| Auditor Talent Development | Addresses the persistent shortage of qualified auditors with dual technical and digital expertise. |
| Multi-Country Certification Bundling | Offers comprehensive solutions to large food manufacturers navigating complex global regulations. |
Research Approach
Bottom-up food manufacturer modeling reconciled against top-down certification body tracking forms the analytical core. This approach combined primary interviews with industry stakeholders and secondary validation from diverse sources. We engaged food manufacturers, retailers, certification body executives, and regulatory experts. Secondary data sources included FDA filings, EFSA reports, SAMR regulations, and relevant industry association publications.
The input-output matrix framing guided our analytical framework across the analysis window. We modeled segmentation dimensions including certification type, product category, end user, market channel, and regional regulatory frameworks. Compound annual growth rates were derived from historical data and projected market dynamics. Key forecast inputs included consumer demand for clean labels and digital traceability adoption rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant regulatory shifts or technological disruption. Forecasts reflect assumptions documented through extensive research. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety and Standards
Global Cold Chain Monitoring Market
Food Safety and Standards
Cold-Chain Friendly Post-Harvest Sanitizing Mist Market
Food Safety and Standards
Natural Antimicrobials Market
Food Safety and Standards
GMO Labeled Food Market
Food Safety and Standards
Quality Assurance and Quality Control Market
Food Safety and Standards
Automatic Distillation Analyzer Market
Food Safety and Standards
Testing, Inspection, and Certification Market
Food Safety and Standards
Food Grade Biofilms Market
Food Safety and Standards
Blockchain Food Traceability Market
Food Safety and Standards
Nutritional Labeling Market
Food Safety and Standards
Food Authenticity Market
Food Safety and Standards
Bakery Cleaning and Disinfection Products Market
Food Safety and Standards
Food Irradiation Market
Food Safety and Standards
Food and Beverage Air Filtration Market
Food Safety and Standards
Precision Food Thermometers Market
Food Safety and Standards
Food and Beverage Industrial Disinfection and Cleaning Market