
 North America Consumer Product Safety Testing Market | 2026-2036
North America Consumer Product Safety Testing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Consumer Product Safety Testing Market Analytics
Buyer concentration among large-format retailers is decoupling from traditional supplier relationships as direct-to-consumer brands fragment the client base. Bureau Veritas S.A. leverages its North American laboratory network to anchor multi-industry contracts. Intertek Group PLC sustains competitive positioning through specialized toy and electronics safety protocols. Eurofins Scientific SE differentiates via advanced chemical analysis capabilities for food and personal care segments.
Consumer product safety testing encompasses mechanical, chemical, and performance evaluation protocols designed to verify compliance with hazard thresholds and material safety standards before market release. The discipline employs destructive and non-destructive methodologies to identify structural failures, toxic substance migration, and flammability risks across finished goods. Chemical analysis services command premium positioning due to complex substrate testing for restricted substances under evolving EPA and state-level frameworks. Laboratory testing dominates volume flows, while in situ inspection protocols capture faster growth as brands seek supply-chain-embedded verification. Electronics and personal care verticals drive margin expansion through recurring certification cycles and shorter product refresh timelines.
The CPSC maintains mandatory testing and certification requirements for children's products, while FDA oversight governs food contact materials and cosmetic safety substantiation. ASTM standards and ISO 17025 accreditation shape laboratory eligibility for retailer-accepted test reports across the United States, Canada, and Mexico. State-level regulations, including California Proposition 65 enforcement, create additional compliance layers that expand testing scope beyond federal minimums. Stakeholders must monitor harmonization gaps between CPSC, Health Canada, and Mexican consumer protection standards as cross-border e-commerce volumes rise.
Market Dynamics
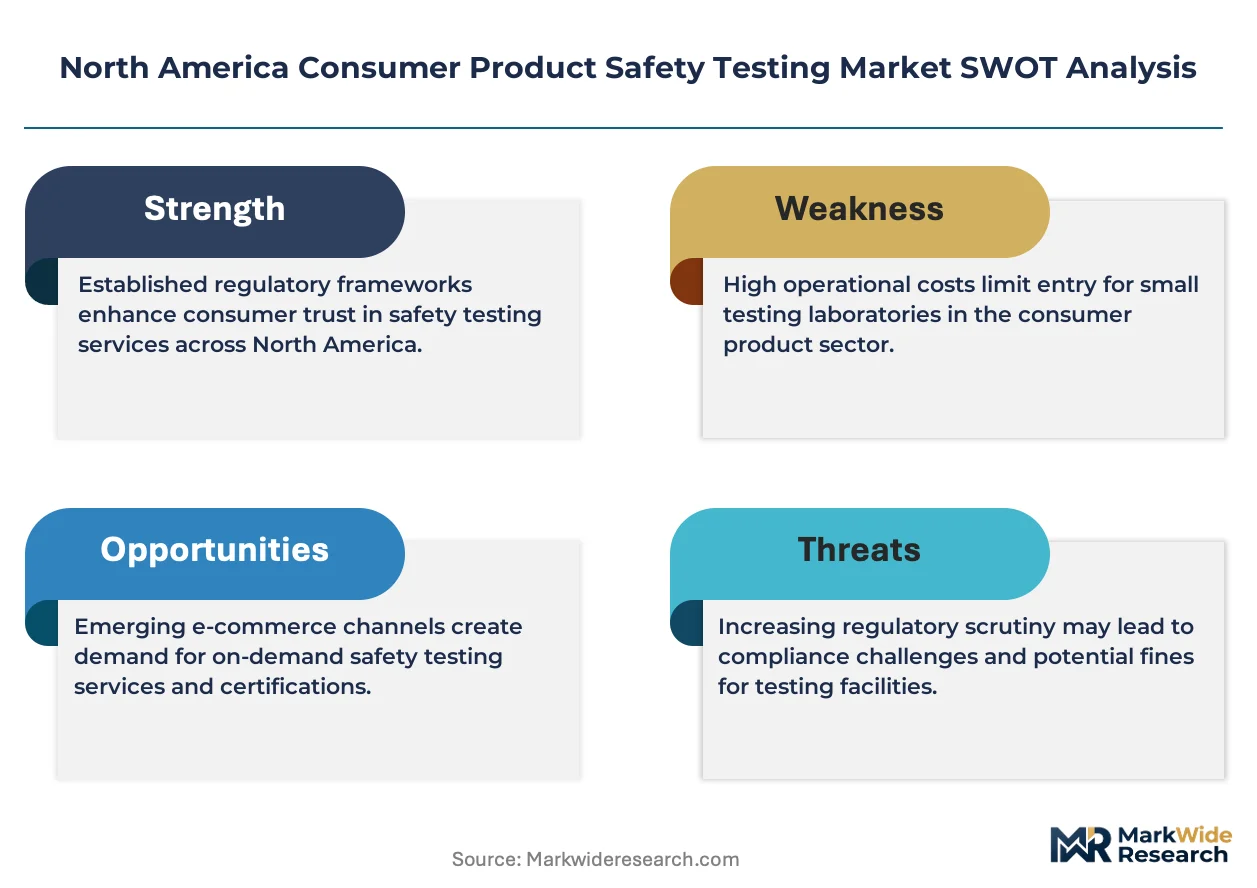
Fragmentation among direct-to-consumer brands is decoupling testing demand from traditional retailer gatekeepers, forcing laboratories to restructure client acquisition around smaller, faster-certification accounts rather than multi-year anchor contracts.
Growth Catalysts
- CPSC Children's Product Mandates:Federal requirements for third-party testing of toys and juvenile goods sustain baseline laboratory utilization regardless of economic cycles.
- California Proposition 65 Enforcement:Private attorney general actions drive chemical analysis volumes for consumer goods sold into the state, expanding substrate testing scope beyond federal minimums.
- Electronics Refresh Cycles:Shortened product lifespans in personal devices and wearables compress recertification intervals, generating recurring revenue streams for electromagnetic compatibility and battery safety protocols.
Market Restraints
- Skilled Analyst Scarcity:Mass spectrometry and chromatography expertise concentrates in Texas and California corridors, creating regional bottlenecks for complex chemical characterization.
- Equipment Capex Burden:ICP-MS and GC-MS instrumentation requires seven-figure capital commitments with six-year depreciation horizons, disadvantaging mid-scale laboratory entrants.
- Harmonization Gaps:Divergent substance restriction lists between CPSC, Health Canada, and Mexican consumer protection standards force redundant testing for cross-border e-commerce shipments.
Strategic Opportunities
- Mexico Manufacturing Integration:Nearshoring of consumer goods production to Baja California and Querétaro creates demand for localized pre-shipment inspection and certification services.
- Connected Device Security Convergence:Cybersecurity validation is merging with traditional product safety testing for IoT-enabled appliances, creating bundled service opportunities.
- Subscription Certification Models:SaaS-style recurring testing packages for high-velocity DTC brands replace transactional project billing, improving revenue predictability.
Industry Challenges
- ISO 17025 Auditor Shortage:Accreditation body capacity constraints extend laboratory certification timelines, delaying market entry for new testing facilities.
- Legacy LIMS Integration:Older laboratory information management systems resist API connectivity with client ERP platforms, creating data exchange friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Consumer Product Safety Testing Market |
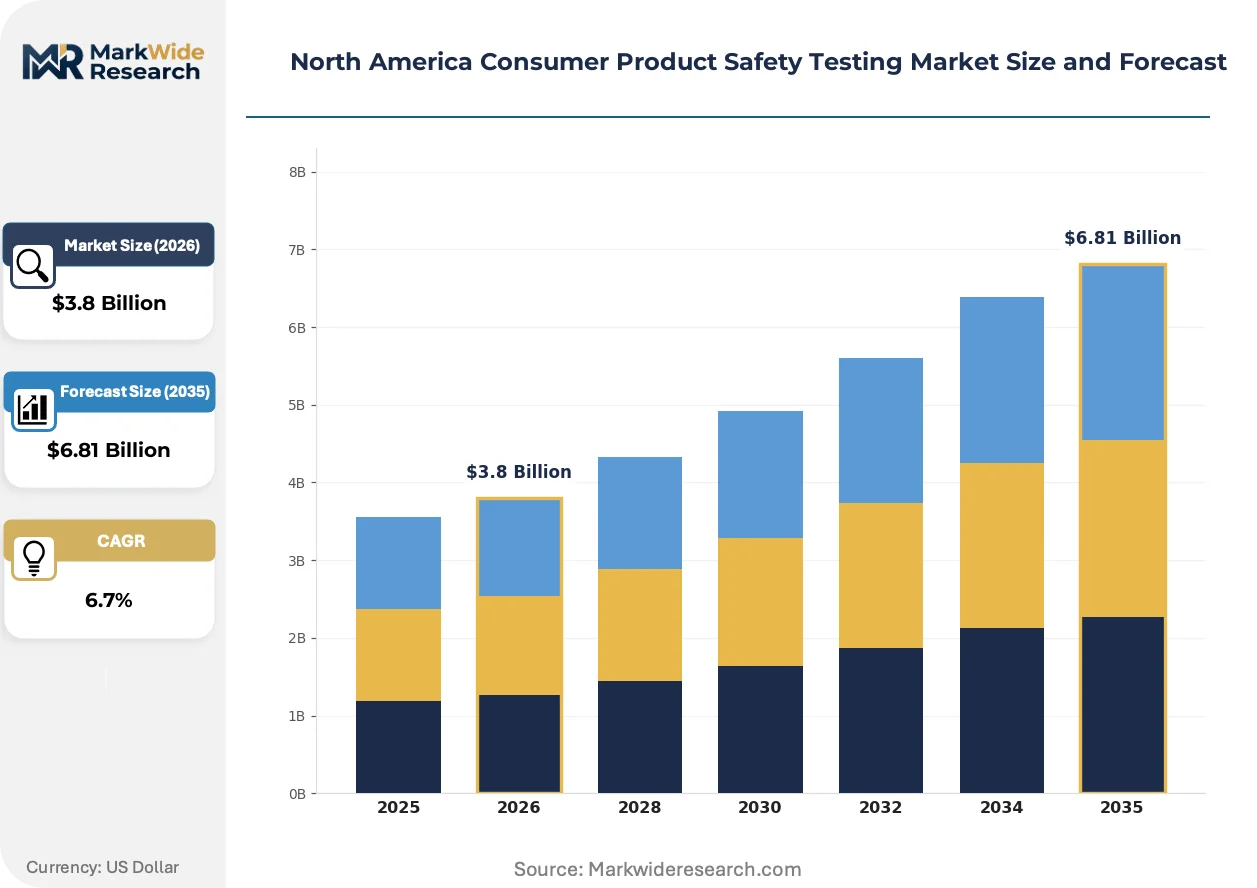
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mechanical Testing, Chemical Analysis, Performance Testing, Safety Inspections Industry Vertical: Electronics, Toys, Food & Beverage, Personal Care Certification Type: ISO, ASTM, EN, CPSC Testing Method: Destructive Testing, Non-Destructive Testing, In Situ Testing, Laboratory Testing |
| Companies Covered | Bureau Veritas S.A., Intertek Group PLC, DEKRA SE, Element Materials Technology, ALS Limited, Eurofins Scientific SE, DNV AS, ABS Group, Applied Technical Services, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Consumer Product Safety Testing Market Evolving Landscape
Digitalization of testing workflows is compressing turnaround times from weeks to days while regulatory expansion into novel substance categories continuously reshapes analytical scope requirements.
Spectroscopic screening platforms are automating preliminary chemical hazard identification, reducing reliance on destructive wet chemistry methods. Mid-size contract laboratories in Illinois and Ohio are deploying these systems to capture DTC brand accounts that prioritize speed over comprehensive characterization. This automation is compressing pricing for routine RoHS and REACH screening, forcing incumbents to differentiate through interpretive consulting rather than raw throughput.
California Proposition 65 settlement patterns are expanding warning label requirements to furniture, apparel, and food contact articles previously outside enforcement scope. Laboratory demand for phthalate and heavy metals testing in textile substrates has intensified accordingly. Children's product manufacturers are responding by front-loading chemical analysis into material qualification stages rather than finished goods validation.
Retailer consolidation among big-box chains is concentrating procurement leverage, while direct-to-consumer brands fragment the opposite end of the client spectrum. Testing providers now maintain parallel service architectures: streamlined self-service portals for high-volume low-margin accounts and dedicated account management for consolidated retail buyers. This bifurcation is most pronounced in consumer electronics and personal care verticals where certification speed directly gates product launch windows.
North America Consumer Product Safety Testing Market Segmentation
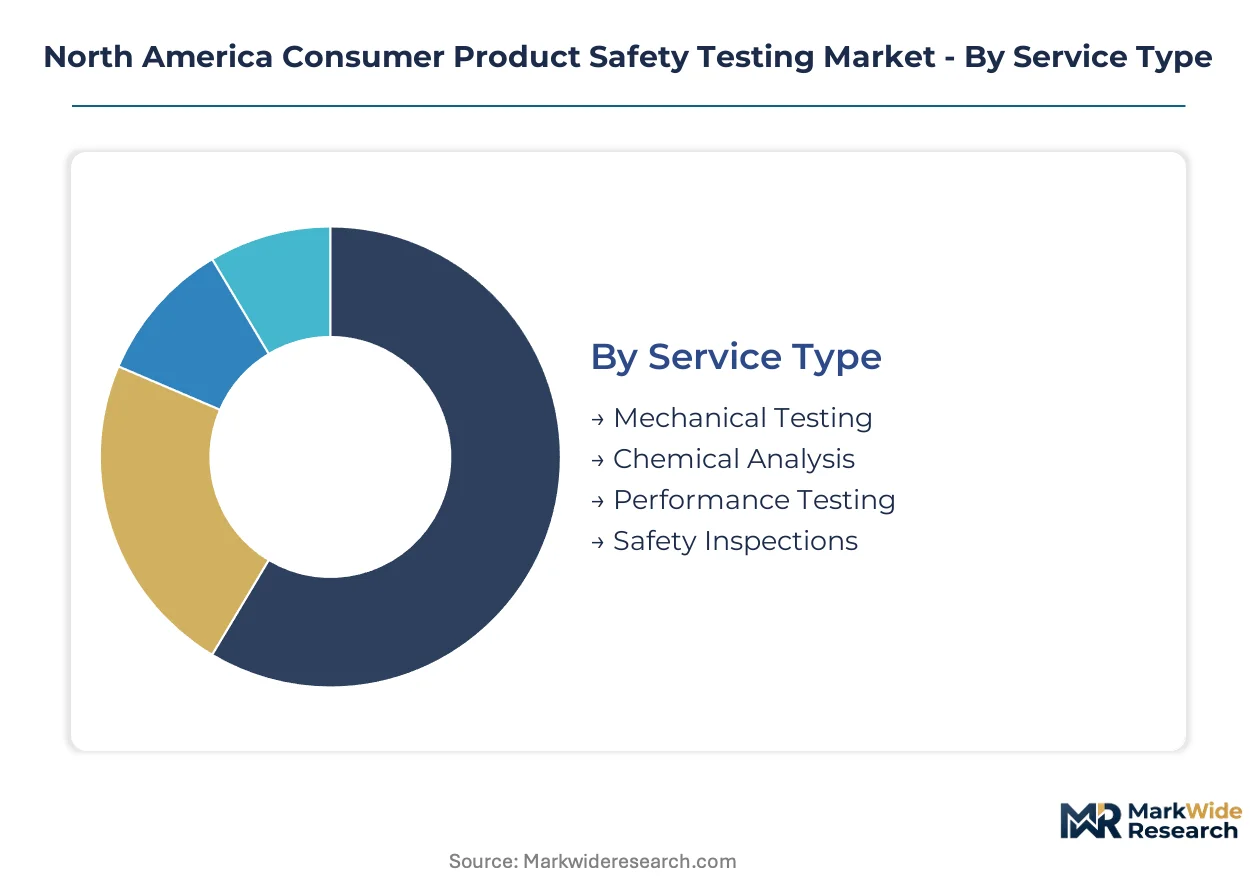
Testing providers structure service portfolios around capital intensity and regulatory specificity. Segment boundaries reflect where specialized equipment investments create defensible positioning versus commoditized throughput competition.
Service Type:
Capital intensity varies sharply across protocols, with chemical analysis requiring seven-figure instrumentation commitments while mechanical testing operates on depreciated universal testing frames.
- Chemical Analysis:Mass spectrometry and chromatography protocols detect restricted substances at parts-per-billion thresholds. Demand concentrates in California for Proposition 65 compliance, where private attorney general actions sustain premium pricing for phthalate and heavy metals characterization.
- Mechanical Testing:Structural integrity evaluation employs tensile, compression, and impact methodologies to verify hazard thresholds. Toy manufacturers in Texas and Illinois drive volume for stress-failure and small-parts choke-hazard protocols under CPSC mandates.
- Performance Testing:Functional validation verifies product claims and durability specifications.
- Safety Inspections:Visual and procedural audits assess manufacturing compliance without destructive sampling.
Most installed capacity flows through Chemical Analysis. Expansion is steepest in Safety Inspections.
Industry Vertical:
End-use concentration determines margin structure, with electronics and personal care commanding recurring certification premiums versus episodic toy testing cycles.
- Electronics:Electromagnetic compatibility and battery safety protocols address FCC and UL requirements for personal devices and wearables. Shortened refresh cycles in consumer electronics compress recertification intervals, generating predictable revenue streams for laboratories with NIST-traceable calibration capabilities.
- Personal Care:Cosmetic safety substantiation combines dermal irritation screening with preservative efficacy testing. FDA oversight of color additives and fragrance allergens drives analytical complexity for formulations sold across California, Texas, and Florida metropolitan corridors.
- Toys:CPSC-mandated third-party testing for mechanical and chemical hazards sustains baseline laboratory utilization.
- Food & Beverage:Food contact material migration testing verifies compliance with FDA indirect food additive regulations.
Electronics captures the highest revenue per test. Personal care is gaining share fastest.
Certification Type:
Accreditation scope determines laboratory eligibility for retailer-accepted reports, with ISO 17025 serving as the baseline gateway credential.
- CPSC:Mandatory third-party testing rules for children's products create legally enforced demand pools. CPSC-accepted laboratory accreditation requires specific mechanical and chemical test method competencies that filter out generalist competitors.
- ISO:ISO 17025 quality management accreditation enables cross-border recognition through ILAC mutual recognition arrangements. Canadian and Mexican market access depends on ISO scope extensions beyond US-only credentials.
- ASTM:Consensus standards for consumer products provide voluntary benchmarks exceeding regulatory minimums.
- EN:European norm adoption supports brands seeking unified North American-European test report acceptance.
ISO accreditation underpins the broadest laboratory eligibility. CPSC scope expansion is climbing the fastest.
Testing Method:
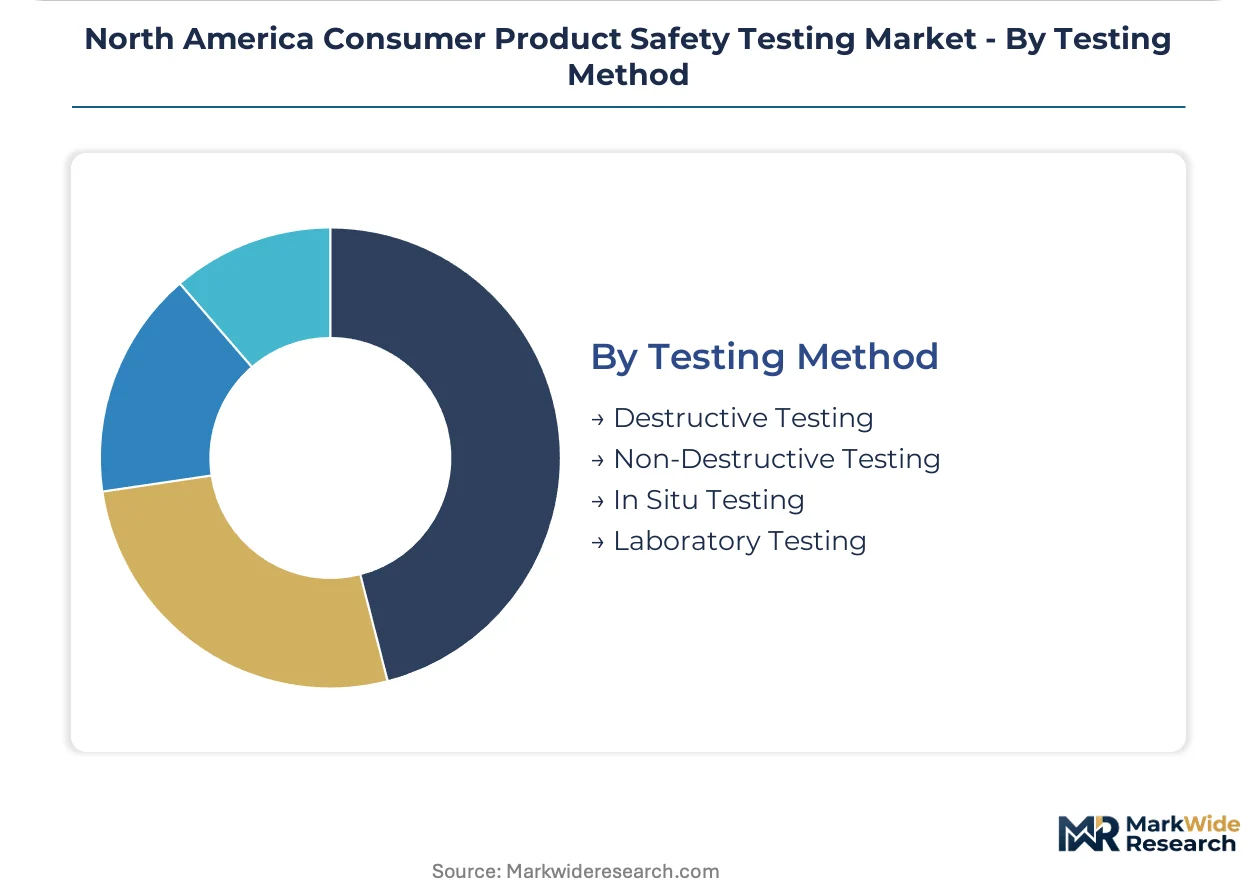
Method selection trades analytical rigor against speed and cost, with laboratory protocols commanding premium positioning over field-based alternatives.
- Laboratory Testing:Controlled-environment analysis under ISO 17025 quality systems delivers defensible legal documentation. California and Texas testing corridors concentrate ICP-MS and GC-MS capacity for complex chemical characterization requiring environmental control.
- In Situ Testing:Supply-chain-embedded verification reduces logistics costs and accelerates turnaround for high-velocity DTC brands. Nearshoring to Baja California and Querétaro creates demand for mobile spectroscopic screening platforms deployed at manufacturing sites.
- Destructive Testing:Sample consumption limits applicability to production-line integration.
- Non-Destructive Testing:X-ray fluorescence and infrared spectroscopy enable rapid preliminary screening without material loss.
Laboratory Testing retains the largest revenue base. In Situ Testing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands the largest share of consumer product safety testing revenue, while Canada and Mexico are expanding faster as nearshoring accelerates cross-border certification demand.
United States
CPSC mandates for children's products and California Proposition 65 enforcement sustain baseline laboratory utilization across all economic cycles. FDA oversight of food contact materials and cosmetic safety substantiation adds complexity for personal care brands. Testing corridors in California and Texas concentrate mass spectrometry capacity for phthalate and heavy metals characterization at parts-per-billion thresholds.
Canada
Health Canada alignment with CPSC standards reduces redundant testing for US-integrated supply chains, though substance restriction lists diverge on specific phthalate compounds. CCPSA enforcement for children's products drives third-party laboratory demand in Ontario and Quebec. Toronto and Vancouver testing clusters serve cross-border e-commerce brands seeking simultaneous US-Canada market access.
Mexico
Nearshoring of consumer goods production to Baja California and Querétaro creates localized demand for pre-shipment inspection and CPSC-accepted certification. PROFECO consumer protection standards lack full harmonization with US requirements, forcing dual testing protocols for finished goods. Tijuana and Monterrey laboratories are expanding in situ testing capacity to serve manufacturing-embedded verification needs.
California
Proposition 65 private attorney general actions sustain premium pricing for chemical analysis services exceeding federal minimums. Furniture, apparel, and food contact articles now face expanded warning label requirements, intensifying substrate testing demand. Los Angeles and San Francisco Bay Area laboratories anchor the highest concentration of ICP-MS and GC-MS instrumentation in North America.
Texas
CPSC-mandated toy testing for mechanical hazards and small-parts choke protocols drives volume for stress-failure evaluation. The Houston-Dallas corridor hosts specialized capacity for battery safety and electromagnetic compatibility certification. Mexican manufacturing integration positions Texas laboratories as bilingual certification hubs for cross-border supply chains.
North America Consumer Product Safety Testing Market Competitive Landscape
European-headquartered testing conglomerates anchor one tier; North American specialists and diversified inspection firms hold complementary positions. The market exhibits tiered concentration, with three global players commanding multi-industry contracts while mid-scale laboratories compete on speed and vertical specialization. Strategic archetypes include: full-service conglomerates with accredited networks, regional specialists with substrate-specific expertise, and technology-forward platforms integrating digital workflows. Dominant competitive moves encompass geographic expansion through laboratory acquisitions and portfolio diversification into cybersecurity-converged testing for connected devices.
Within the full-service tier, Bureau Veritas S.A., Intertek Group PLC, and Eurofins Scientific SE exemplify the conglomerate archetype. Bureau Veritas occupies a position anchored by its North American laboratory network serving multi-industry accounts. Intertek exemplifies specialization-driven positioning through dedicated protocols for toy and electronics safety. Eurofins represents advanced chemical analysis differentiation for food and personal care segments. These three entities collectively illustrate how capital-intensive instrumentation investments and ISO 17025 accreditation breadth create defensible market positioning against fragmented regional competitors.
| Leading Market Players |
|---|
| Bureau Veritas S.A. |
| Intertek Group PLC |
| DEKRA SE |
| Element Materials Technology |
| ALS Limited |
| Eurofins Scientific SE |
| DNV AS |
| ABS Group |
| Applied Technical Services, LLC |
| Others |
Value Network & Pricing Analysis
ICP-MS and GC-MS instrumentation capital costs cascade through laboratory pricing tiers, compressing margins for mid-scale entrants while concentrating premium positioning among California and Texas testing corridors with depreciated seven-figure equipment bases.
Pricing Analysis
Capacity additions in Illinois and Ohio are reshaping price floors for routine RoHS and REACH screening as mid-scale laboratories deploy spectroscopic automation to capture DTC brand accounts. Three-tier pricing structure across premium, standard, and economy levels separates CPSC-accepted certification with full legal defensibility from rapid preliminary screening and basic compliance documentation. Cost compression in standard-tier chemical analysis is intensifying because spectroscopic platforms reduce destructive wet chemistry labor hours. Direct-to-consumer brands exhibit highest price sensitivity, prioritizing turnaround speed over comprehensive characterization, while consolidated retail buyers accept premium pricing for multi-year anchor contracts with dedicated account management.
Supply Chain Analysis
Reverse-logistics flows for failed certification batches and retest samples concentrate laboratory operational overhead in California and Texas corridors where ICP-MS and GC-MS capacity clusters. Instrument manufacturing draws from Germany, Japan, and the United States for mass spectrometry and chromatography components. Single-source vulnerability sits with specialized detector assemblies and rare-earth magnet suppliers for high-resolution instrumentation. Distribution runs through accredited laboratory networks with ISO 17025 scope extensions, while in situ testing platforms bypass traditional sample logistics through manufacturing-embedded deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where CPSC children's product mandates and California Proposition 65 enforcement create demand inelasticity regardless of economic cycles.
For Market Incumbents: Cement defensible positioning through backward integration into specialized instrumentation maintenance and captive supply of NIST-traceable reference standards. Expand ISO 17025 scope extensions into Mexican PROFECO alignment before nearshoring volumes accelerate. Capacity additions by mid-scale competitors in Illinois and Ohio threaten margin compression in routine screening tiers.
For New Entrants and Emerging Players: Spectroscopic screening platforms with API-connected client dashboards offer a technology-first wedge into high-velocity DTC brand accounts underserved by legacy LIMS architectures. White-space targets include subscription certification models for electronics refresh cycles and cybersecurity-converged testing for IoT-enabled appliances. Nearshoring corridors in Baja California and Querétaro represent the most penetrable geography. Go-to-market through bilingual certification partnerships with Texas-based laboratories serving cross-border supply chains.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists possessing substrate-specific expertise in phthalate and heavy metals characterization under California Proposition 65 enforcement. Long-term viability hinges on recurring revenue predictability from SaaS-style testing packages replacing transactional project billing. Target acquisition archetype: mid-scale laboratories with depreciated ICP-MS bases and established DTC brand relationships. Monitor ISO 17025 auditor shortage resolution and CPSC-accepted laboratory expansion timelines as inflection indicators for competitive intensity.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Scope Extension | Enables cross-border recognition through ILAC mutual recognition arrangements for Canadian and Mexican market access. |
| Spectroscopic Automation Deployment | Compresses turnaround times from weeks to days for DTC brands prioritizing speed over comprehensive characterization. |
| Nearshoring Certification Partnership | Captures pre-shipment inspection demand in Baja California and Querétaro manufacturing corridors. |
| Subscription Certification Model | Replaces transactional project billing with recurring revenue streams from high-velocity electronics refresh cycles. |
| Cybersecurity-Converged Testing | Bundles traditional product safety with IoT validation as connected device security merges with physical hazard protocols. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with laboratory operations directors, CPSC regulatory affairs specialists, retail category buyers, DTC brand supply chain managers, and ISO 17025 accreditation auditors with secondary validation. Secondary sources encompassed CPSC enforcement databases, California Attorney General Proposition 65 settlement records, FDA food contact material guidance documents, and ISO accreditation body scope directories. Bottom-up laboratory capacity modeling and top-down end-use demand estimation were triangulated against trade flow data for testing equipment imports.
Segment-weighting approaches distributed value and volume across service type, industry vertical, certification type, and testing method dimensions. Chemical analysis, mechanical testing, performance testing, and safety inspections were modeled with differential growth assumptions based on capital intensity and regulatory enforcement patterns. Electronics, personal care, toys, and food and beverage verticals carried distinct recertification cycle frequencies. CAGRs were derived from regression analysis of historical laboratory utilization rates against regulatory expansion milestones and manufacturing relocation trends.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to harmonization gaps between CPSC, Health Canada, and Mexican consumer protection standards. Forecasts reflect documented assumptions about nearshoring velocity, ISO 17025 auditor supply constraints, and spectrometry equipment replacement cycles. Practitioners should monitor CPSC scope expansion timelines, California Proposition 65 settlement pattern shifts, and skilled analyst scarcity resolution in Texas and California corridors for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Vitamin Test Market
Food Safety Testing
North America Food Safety Testing Market
Food Safety Testing
US Consumer Product Safety Testing Market
Food Safety Testing
Gum Content Tester Market
Food Safety Testing
Amylase Testing Market
Food Safety Testing
South Africa Food Safety Testing Market
Food Safety Testing
Water Activity Instrumentation Market
Food Safety Testing
Global Inline Metal Detector Market
Food Safety Testing
Carbohydrates Testing Services Market
Food Safety Testing
Food Traceability Solutions Market
Food Safety Testing
Rapid Microbiology Testing Market
Food Safety Testing
Testing, Inspection, and Certification in Consumer Goods and Retail Market
Food Safety Testing
Inline Beverage Gas and Microbial Load Monitoring Test Systems Market
Food Safety Testing
Water Quality Testing Market
Food Safety Testing
Global Bacteriological Testing Market
Food Safety Testing
Global Lipid Testing Market