
 US Food Safety Testing Market | 2026-2036
US Food Safety Testing Market Size, Share, and Industry Trends Forecast 2026-2036
US Food Safety Testing Market Insights
Subscription-based pathogen monitoring programs is shifting how laboratories monetize food safety relationships, moving from per-test billing to annual compliance retainers. Eurofins Scientific leverages this model through multi-site contracts with protein processors across the South and Great Plains. Thermo Fisher Scientific anchors its position with integrated instrument-reagent-service bundles that lock in recurring revenue from dairy cooperatives. NEOGEN Corporation differentiates through rapid diagnostic platforms deployed directly at slaughterhouse receiving bays.
Food safety testing encompasses analytical procedures that detect biological, chemical, and physical hazards in consumable products, employing methods such as polymerase chain reaction amplification with detection thresholds below ten colony-forming units per gram and mass spectrometry for pesticide residue quantification at parts-per-billion sensitivity. Its primary purpose is verifying that food products meet federally mandated safety thresholds before reaching consumers. Microbial testing commands the largest share of laboratory capacity due to persistent Salmonella and Listeria regulatory pressure, while rapid testing technology captures the fastest expansion as processors seek same-shift release decisions. Chemical analysis maintains stable margins among ingredient suppliers validating supply chain purity.
FDA, USDA-FSIS, and state agriculture departments collectively enforce testing protocols that determine which laboratories qualify for official regulatory sampling and which methods achieve regulatory acceptance. FSIS directive revisions routinely expand pathogen testing frequencies for beef trim and poultry carcasses, directly driving volume through approved third-party labs. Stakeholders must track how FDA's New Era of Smarter Food Safety initiative integrates whole genome sequencing into outbreak traceback protocols, as this will reshape laboratory capability requirements and capital investment priorities.
Market Dynamics
Whole genome sequencing adoption by FDA is compressing outbreak response timelines from weeks to days, forcing laboratories to retool capital equipment and bioinformatics pipelines or exit regulatory sampling contracts entirely.
Growth Catalysts
- FSIS Directive Expansion:USDA-FSIS mandates increased Salmonella testing frequencies for beef trim and poultry carcasses, routing mandatory volume through approved third-party laboratories in the Midwest meatpacking belt.
- California Agricultural Density:The Central Valley's concentrated fruit and vegetable processing operations generate sustained demand for pesticide residue and pathogen verification services.
- Rapid PCR Platforms:Same-shift pathogen detection capabilities allow protein processors to release lots without holding inventory, converting capital costs into operational savings.
Market Restraints
- Reference Material Scarcity:Certified pathogen strains and matrix-matched controls for emerging serovars face supply bottlenecks from limited domestic producers.
- Equipment Capital Intensity:Mass spectrometry and sequencing instruments require seven-figure investments with five-year depreciation cycles, concentrating capability among large contract laboratories.
- Interstate Licensing Friction:State agriculture departments maintain non-uniform laboratory accreditation requirements, forcing multi-site operators to maintain redundant quality systems.
Strategic Opportunities
- Slaughterhouse Point-of-Receiving Deployment:Portable diagnostic platforms positioned at cattle and hog receiving bays capture testing volume before samples enter logistics networks.
- FSMA Import Safety Mandates:Foreign Supplier Verification Programs create compliance service demand for importers sourcing from high-risk jurisdictions.
- Blockchain-Sequencing Integration:Immutable chain-of-custody records paired with genomic fingerprints enable premium pricing for traceability-verified supply chains serving retail private label programs.
Industry Challenges
- Bioinformatics Talent Scarcity:Shortage of analysts capable of interpreting whole genome sequencing data and constructing phylogenetic trees delays report turnaround times.
- Multi-Site Integration Complexity:Enterprise laboratory information management systems struggle to harmonize data formats across acquired facilities with legacy instrument fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Food Safety Testing Market |
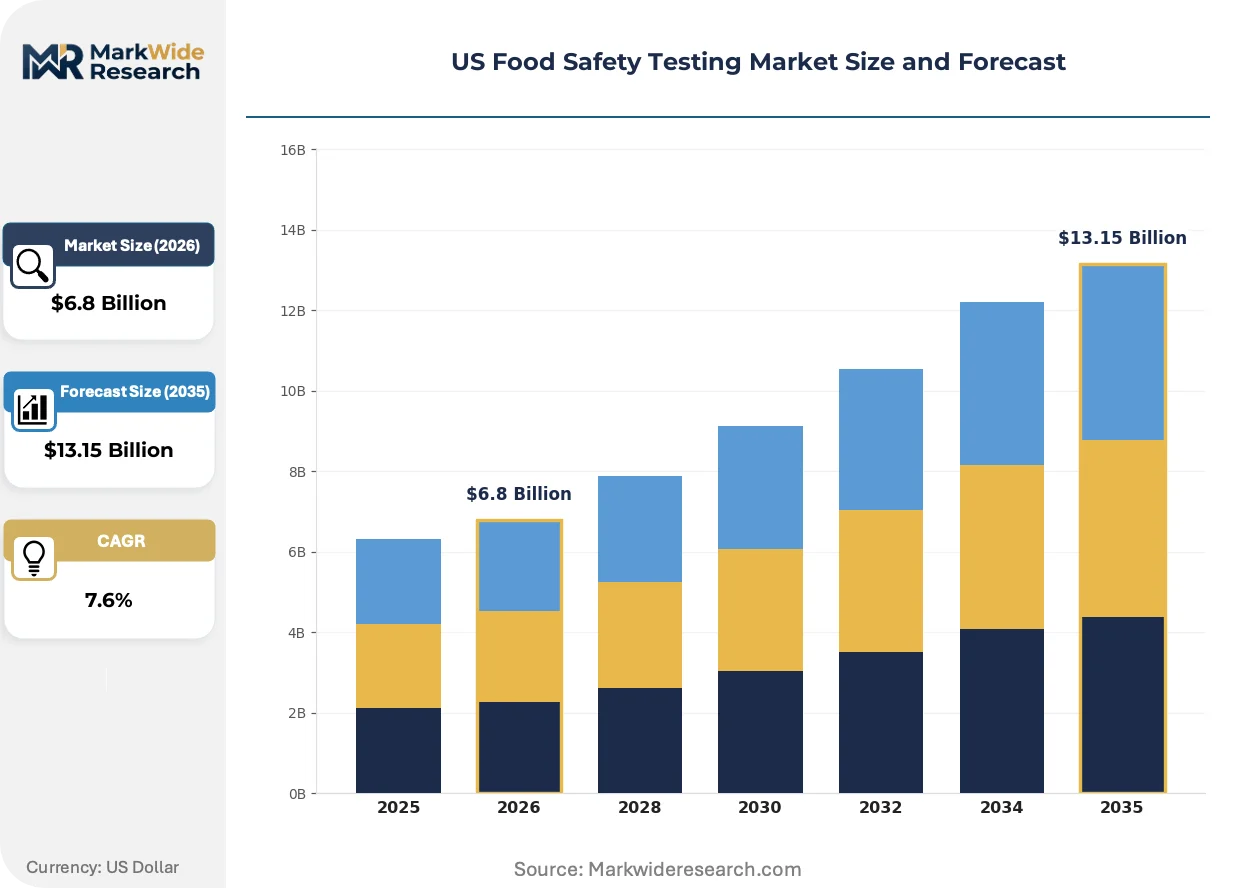
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Microbial Testing, Chemical Testing, Residue Testing, Nutritional Testing Sample Type: Meat, Dairy, Fruits, Vegetables End User: Food Manufacturers, Retailers, Laboratories, Regulatory Authorities Technology: Chemical Analysis, PCR, Immunoassay, Rapid Testing |
| Companies Covered | Eurofins Scientific, Thermo Fisher Scientific, NEOGEN Corporation, Mérieux NutriSciences, Bio-Rad Laboratories, Microbac Laboratories, FoodChain ID, IDEXX Laboratories, Charm Sciences, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Food Safety Testing Market Trends and Innovations
Testing economics are inverting as speed supersedes sensitivity in purchasing criteria, compressing the viable technology set toward platforms delivering actionable results within production shift windows.
Next-generation sequencing is converging with cloud-based bioinformatics pipelines to deliver serotype-level pathogen identification in under eight hours. Large protein processors in the Great Plains are deploying these systems at central laboratories serving multiple slaughter facilities. The technology is converging with traditional culture-based methods to create tiered testing protocols where rapid screening triggers confirmatory sequencing.
FDA's New Era of Smarter Food Safety initiative mandates whole genome sequencing integration into outbreak traceback protocols by 2026. This regulatory pressure forces laboratories to acquire sequencing capability or subcontract to specialized genomic service providers. High-complexity molecular diagnostic laboratories in Maryland and Massachusetts are capturing this outsourced volume from regional competitors lacking capital reserves.
Annual compliance retainers are displacing per-test billing as the dominant commercial structure between laboratories and mid-sized food manufacturers. Protein cooperatives in the South negotiate multi-site contracts bundling routine surveillance with crisis-response surge capacity. This shift concentrates purchasing power among buyers with multi-facility footprints and penalizes single-site laboratories unable to offer geographic coverage.
US Food Safety Testing Market Segmentation
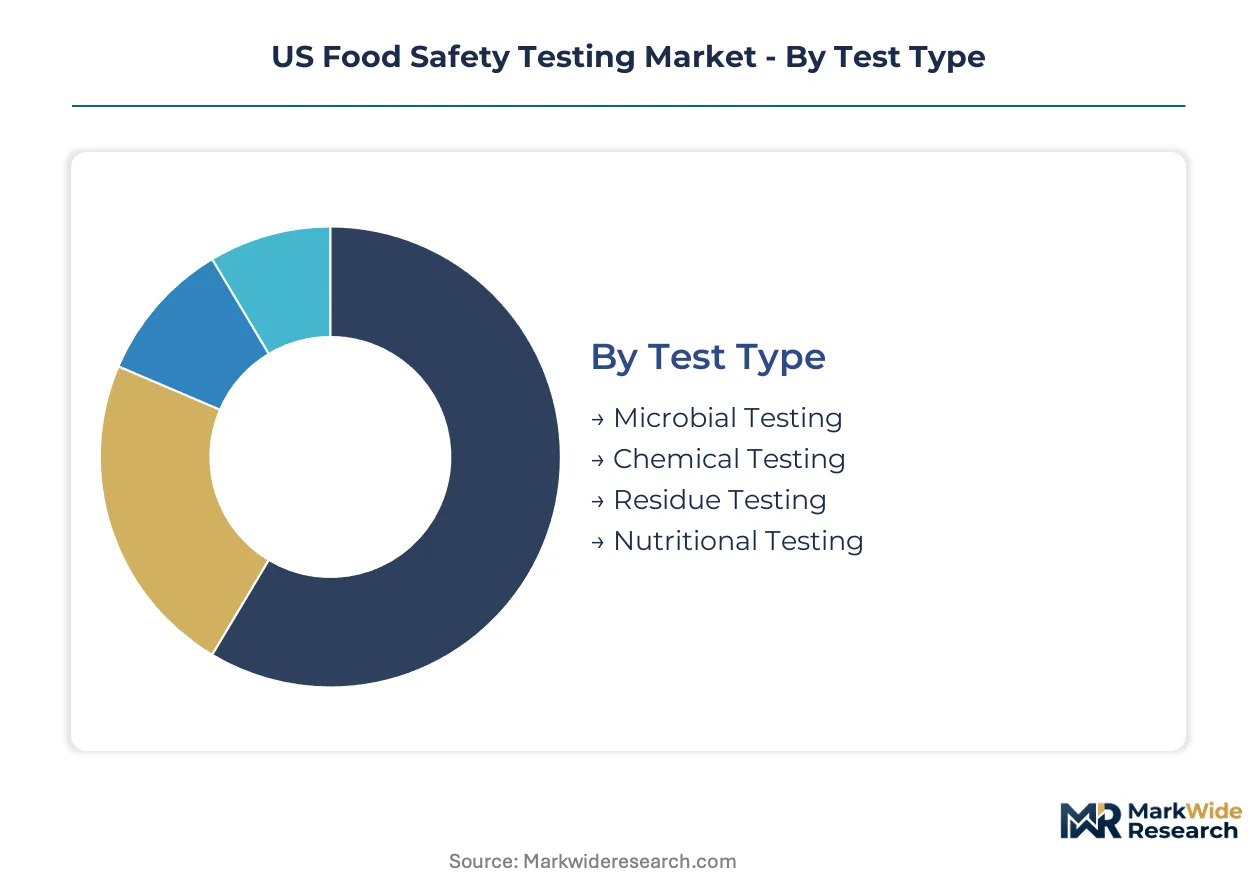
Segmentation in the US food safety testing market reveals how capital deployment, regulatory pressure, and processing economics concentrate demand across distinct technical and customer dimensions. Laboratories and manufacturers allocate resources differently depending on which hazard category, sample matrix, or detection platform drives their compliance exposure.
Test Type:
Capital intensity varies sharply across hazard categories, with molecular infrastructure demanding seven-figure sequencing investments while chemical workflows run on depreciated chromatography suites.
- Microbial Testing:Polymerase chain reaction and culture-based methods detect Salmonella, Listeria, and E. coli with detection thresholds below ten colony-forming units per gram. Demand clusters in the Midwest meatpacking belt where USDA-FSIS mandates intensified pathogen surveillance for beef trim and poultry carcasses.
- Chemical Testing:Mass spectrometry and chromatography quantify pesticide residues, mycotoxins, and veterinary drug metabolites at parts-per-billion sensitivity. California's Central Valley agricultural corridor generates sustained volume as fruit and vegetable processors validate supply chain purity for export and retail private label programs.
- Residue Testing:Specialized extraction protocols detect antibiotic and hormone traces in animal-derived products.
- Nutritional Testing:Label verification and fortification analysis supports processed food manufacturers.
Microbial testing absorbs the bulk of installed capacity; rapid molecular platforms within this category are expanding most quickly as processors seek same-shift release decisions.
Sample Type:
Protein matrices command premium pricing due to pathogen regulatory burden, while produce testing scales through volume economics in concentrated growing regions.
- Meat:Beef, pork, and poultry carcasses require USDA-FSIS-mandated Salmonella and Campylobacter screening with specified sampling frequencies. Great Plains slaughterhouses and Midwest processing plants route mandatory volume through approved third-party laboratories.
- Dairy:Raw milk and finished products face antibiotic residue screening plus pathogen surveillance. Dairy cooperatives in Wisconsin and New York deploy integrated instrument-reagent-service bundles that lock in recurring testing relationships.
- Fruits:Pesticide residue panels and pathogen verification for fresh and processed categories.
- Vegetables:Pre-harvest and post-harvest testing for microbial and chemical hazards in leafy greens and row crops.
Meat samples drive the highest revenue per test; dairy is climbing the fastest as fluid milk processors adopt rapid screening for operational efficiency.
End User:
Purchasing sophistication diverges between integrated manufacturers with captive laboratories and outsourced operators dependent on contract service pricing.
- Food Manufacturers:Protein processors and ingredient suppliers maintain in-house capabilities for routine surveillance while outsourcing confirmatory sequencing. Mid-sized manufacturers in the South negotiate multi-site annual compliance retainers replacing per-test billing.
- Laboratories:Contract service providers capture regulatory sampling contracts and crisis-response surge capacity. Eurofins Scientific and similar operators leverage geographic coverage to consolidate purchasing power from multi-facility clients.
- Retailers:Private label programs and supplier verification requirements.
- Regulatory Authorities:FDA and state agriculture departments qualify laboratories for official sampling and determine method acceptance.
Food manufacturers dominate absolute testing spend; contract laboratories are gaining share fastest as mid-sized processors exit in-house capabilities.
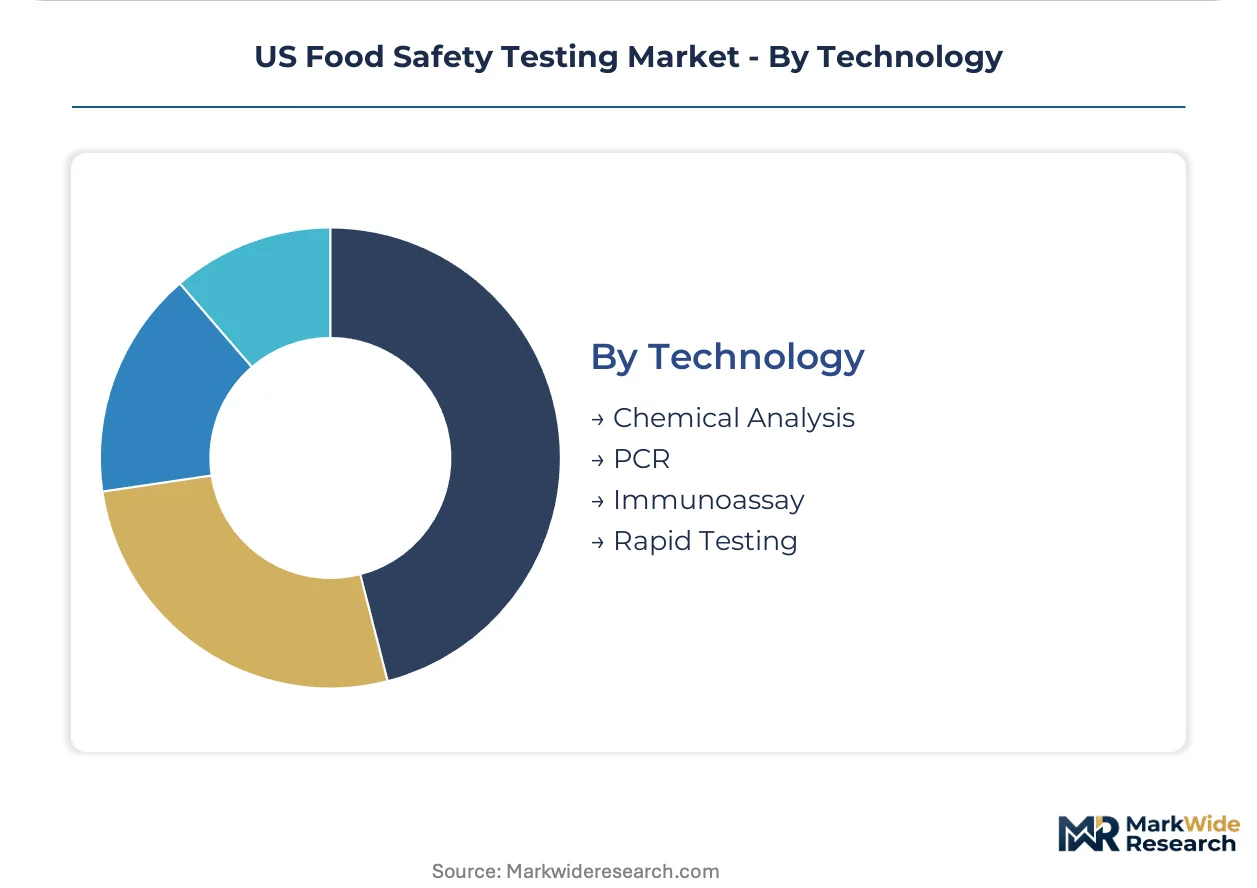
Technology:
Platform selection trades sensitivity against speed, with rapid methods compressing turnaround at the cost of higher per-sample reagent spend.
- PCR:Amplification-based detection delivers serotype-level identification in under eight hours when paired with next-generation sequencing. Large protein processors in the Great Plains deploy these systems at central laboratories serving multiple slaughter facilities.
- Rapid Testing:Lateral flow and automated immunoassay platforms enable same-shift pathogen screening at receiving bays and production lines. NEOGEN Corporation positions portable diagnostics directly at slaughterhouse entry points.
- Chemical Analysis:Chromatography and spectrometry for residue and contaminant quantification.
- Immunoassay:Antibody-based detection for allergen and toxin screening.
PCR holds the largest installed base; rapid testing platforms are expanding most quickly as speed supersedes sensitivity in purchasing criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Testing demand concentrates where agricultural production density meets regulatory enforcement intensity. The Midwest and California dominate volume, while the Southeast and Great Plains emerge as growth corridors for slaughterhouse-deployed diagnostics.
California
The Central Valley's concentrated fruit and vegetable processing generates sustained demand for pesticide residue panels and pathogen verification. FDA's Food Safety Modernization Act enforcement intensifies testing mandates for leafy greens and nut processors. Fresno and Salinas clusters host contract laboratories serving export-oriented growers validating supply chain purity for retail private label programs.
Midwest
USDA-FSIS directive expansions mandate increased Salmonella testing frequencies for beef trim and poultry carcasses across Iowa, Nebraska, and Kansas. The meatpacking belt routes mandatory volume through approved third-party laboratories. Omaha and Sioux Falls processing hubs deploy rapid PCR platforms for same-shift release decisions, converting capital costs into operational savings.
Texas
Gulf Coast seafood processors and Panhandle cattle feedlots drive dual-pathogen and chemical testing demand. State agriculture department licensing requirements create compliance friction for multi-site operators. Houston and Amarillo industrial corridors concentrate contract laboratory capacity for protein exporters serving Asian markets.
New York
Dairy cooperatives in the Finger Lakes and Hudson Valley deploy integrated instrument-reagent-service bundles for antibiotic residue screening. The state's Department of Agriculture and Markets maintains non-uniform accreditation standards. Rochester and Syracuse dairy processing clusters anchor recurring testing relationships with rapid diagnostic platforms.
Georgia
Poultry slaughterhouses in the Gainesville corridor generate volume for third-party pathogen verification under FSIS mandates. Foreign Supplier Verification Programs create compliance service demand for importers sourcing from high-risk jurisdictions. Atlanta logistics hubs position laboratories to capture pre-shipment testing for export-bound protein products.
US Food Safety Testing Market Competitive Landscape
Capital-heavy producers compete with asset-light designers as instrument manufacturers face off against contract service providers. The market structure concentrates capability among large multi-site laboratories while specialized diagnostic developers occupy niche positions. Three archetypes dominate: integrated conglomerates bundling hardware-reagent-service offerings, pure-play contract laboratories capturing regulatory sampling contracts, and rapid diagnostic specialists deploying portable platforms at production entry points. Consolidation through acquisition and geographic expansion represents the primary competitive vector, with technology licensing agreements forming secondary defensive moats.
Within the integrated conglomerate tier, Thermo Fisher Scientific anchors recurring revenue relationships through bundled offerings. Eurofins Scientific exemplifies the contract laboratory archetype with multi-site geographic coverage. NEOGEN Corporation occupies the rapid diagnostic specialist position with slaughterhouse point-of-receiving deployment. These three entities represent distinct capital deployment strategies: captive instrument lock-in versus regulatory contract volume versus operational speed advantages.
| Leading Market Players |
|---|
| Eurofins Scientific |
| Thermo Fisher Scientific |
| NEOGEN Corporation |
| Mérieux NutriSciences |
| Bio-Rad Laboratories |
| Microbac Laboratories |
| FoodChain ID |
| IDEXX Laboratories |
| Charm Sciences |
| Others |
Pricing and Supply Chain Analysis
Captive instrument-reagent bundling by Thermo Fisher Scientific and Eurofins Scientific anchors both supply security and pricing power for dairy cooperatives and protein processors seeking locked-in testing relationships. This integration pattern insulates incumbent laboratories from spot-price volatility while concentrating procurement leverage among multi-site buyers.
Pricing Analysis
Margin tightening in rapid diagnostic platforms reflects reagent cost escalation and same-shift speed premiums. Annual compliance retainers displace per-test billing as the dominant pricing model, with volume scale and geographic coverage serving as primary price differentiation drivers. Cost-down pressure accelerates among mid-sized manufacturers consolidating purchasing through multi-site contracts. Single-site laboratories exhibit highest price sensitivity; integrated conglomerates with captive bundles command premium positioning.
Supply Chain Analysis
Dual-sourcing requirements for certified pathogen strains and matrix-matched controls force laboratories to qualify multiple domestic producers amid reference material scarcity. Supply concentrates in the United States for regulatory-compliant reagents, with Germany and Switzerland anchoring specialized chromatography and spectrometry instrument production. Critical dependencies include PCR thermal cyclers, mass spectrometry consumables, and genomic sequencing flow cells. Single-source vulnerability persists for next-generation sequencing platforms. Distribution runs through direct manufacturer relationships with large contract laboratories and regional distributors serving mid-tier processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into bioinformatics pipelines and point-of-receiving diagnostics defines the competitive race, with laboratories capturing upstream sequencing capability or downstream slaughterhouse deployment to lock in recurring revenue.
For Market Incumbents: Deepen geographic coverage through acquisition of regional laboratories in the Southeast and Great Plains to defend against Eurofins Scientific's multi-site consolidation. Invest in FDA-recognized whole genome sequencing capability before the regulatory deadline forces subcontracting relationships. Lock in dairy cooperative relationships through expanded instrument-reagent-service bundles. For New Entrants and Emerging Players: Contract slaughterhouse operators represent the most penetrable channel partner type for portable diagnostic platforms, with Gainesville and Amarillo corridors showing under-served rapid testing demand. Target mid-sized poultry processors seeking same-shift release decisions without capital-intensive laboratory buildouts. Pursue FSMA Import Safety compliance services for Houston-based seafood importers sourcing from high-risk jurisdictions. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated conglomerates seeking geographic fill-in or bioinformatics capability. Long-term viability favors laboratories with sequencing infrastructure and multi-site regulatory contracts. Watch FDA enforcement intensity for whole genome sequencing integration as the inflection indicator for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Sequencing Capability Acquisition | Positions laboratories for FDA whole genome sequencing mandates without subcontracting dependency. |
| Slaughterhouse Point-of-Receiving Deployment | Captures testing volume before samples enter logistics networks at Great Plains receiving bays. |
| Multi-Site Annual Retainer Conversion | Concentrates purchasing power among protein cooperatives across Southern processing corridors. |
| Bioinformatics Pipeline Development | Reduces report turnaround times amid analyst scarcity for phylogenetic tree construction. |
| Blockchain-Sequencing Integration | Enables premium pricing for traceability-verified supply chains serving retail private label programs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with laboratory operations directors, FSIS compliance officers, dairy cooperative procurement managers, and diagnostic platform engineers. FDA guidance documents, USDA-FSIS directive revisions, state agriculture department accreditation standards, and instrument manufacturer technical specifications supplied additional validation. Bottom-up testing volume estimates and top-down market sizing triangulated across these sources.
Granularity-level modeling tracked test type, sample matrix, technology platform, and end-user sophistication across the projection horizon. Hazard category segmentation captured microbial, chemical, residue, and nutritional testing workflows. Technology segmentation distinguished PCR, rapid testing, chromatography, and immunoassay platforms. CAGRs derived from regulatory mandate expansion rates and processor adoption curves for same-shift diagnostics. Forecast inputs incorporated FSIS sampling frequency directives and FDA sequencing integration timelines.
Caveats apply where FDA enforcement delays, reference material supply disruptions, or bioinformatics talent shortages could materially shift the outlook. Deviation in whole genome sequencing regulatory deadlines or interstate licensing harmonization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Middle East and Africa Food Safety Testing Market
Food Safety Testing
UK Food Testing Market
Food Safety Testing
US Legionella Testing Market
Food Safety Testing
Testing, Inspection, and Certification in Consumer Goods and Retail Market
Food Safety Testing
Italy Food Safety Testing Market
Food Safety Testing
Screening Equipment Market
Food Safety Testing
Fruit & Vegetable Wash Market
Food Safety Testing
Food Traceability Solutions Market
Food Safety Testing
Food Authentication Testing Market
Food Safety Testing
Food Tester Market
Food Safety Testing
Water Activity Meter Market
Food Safety Testing
Salmonella Testing Market
Food Safety Testing
Water Quality Testing Market
Food Safety Testing
Food Traceability Market
Food Safety Testing
US Consumer Product Safety Testing Market
Food Safety Testing
Food Allergen Testing Market