
 Middle East and Africa Food Safety Testing Market | 2026-2036
Middle East and Africa Food Safety Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Food Safety Testing Market Foresight
Food retailers are bifurcating from food manufacturers as the fastest-growing buyer archetype in the Middle East and Africa Food Safety Testing Market, driven by private-label expansion and direct sourcing from regional farms. Eurofins Scientific leverages its pan-African laboratory network to anchor contract testing relationships with multinational grocery chains. SGS Société Générale de Surveillance SA competes through integrated inspection-certification services at major Gulf ports. Bureau Veritas SA specializes in halal authentication protocols that unlock access to Saudi and UAE retail channels.
Food safety testing encompasses the analytical verification of food products for biological contaminants, chemical residues, and nutritional composition using methods that detect pathogens at thresholds as low as one colony-forming unit per gram. Its primary commercial purpose is to prevent foodborne illness outbreaks, ensure trade compliance, and protect brand equity across supply chains. Microbiological testing dominates contract volumes due to persistent salmonella and listeria risks in ambient-temperature distribution corridors. PCR testing captures the fastest expansion as laboratories replace culture-based methods with same-day pathogen identification. Dairy products generate concentrated margin pools because Gulf import standards mandate comprehensive hormone and antibiotic residue panels.
SFDA import regulations and UAE MOHAP food control standards mandate pre-shipment testing for high-risk categories, directly shaping laboratory accreditation requirements and equipment procurement cycles across the region. ISO 17025 certification has become a de facto market access condition for any testing facility serving Saudi Aramco catering contracts or Dubai airline catering suppliers. Stakeholders must monitor how Gulf Cooperation Council harmonization of maximum residue limits reshapes cross-border testing reciprocity and capital allocation priorities.
Market Dynamics
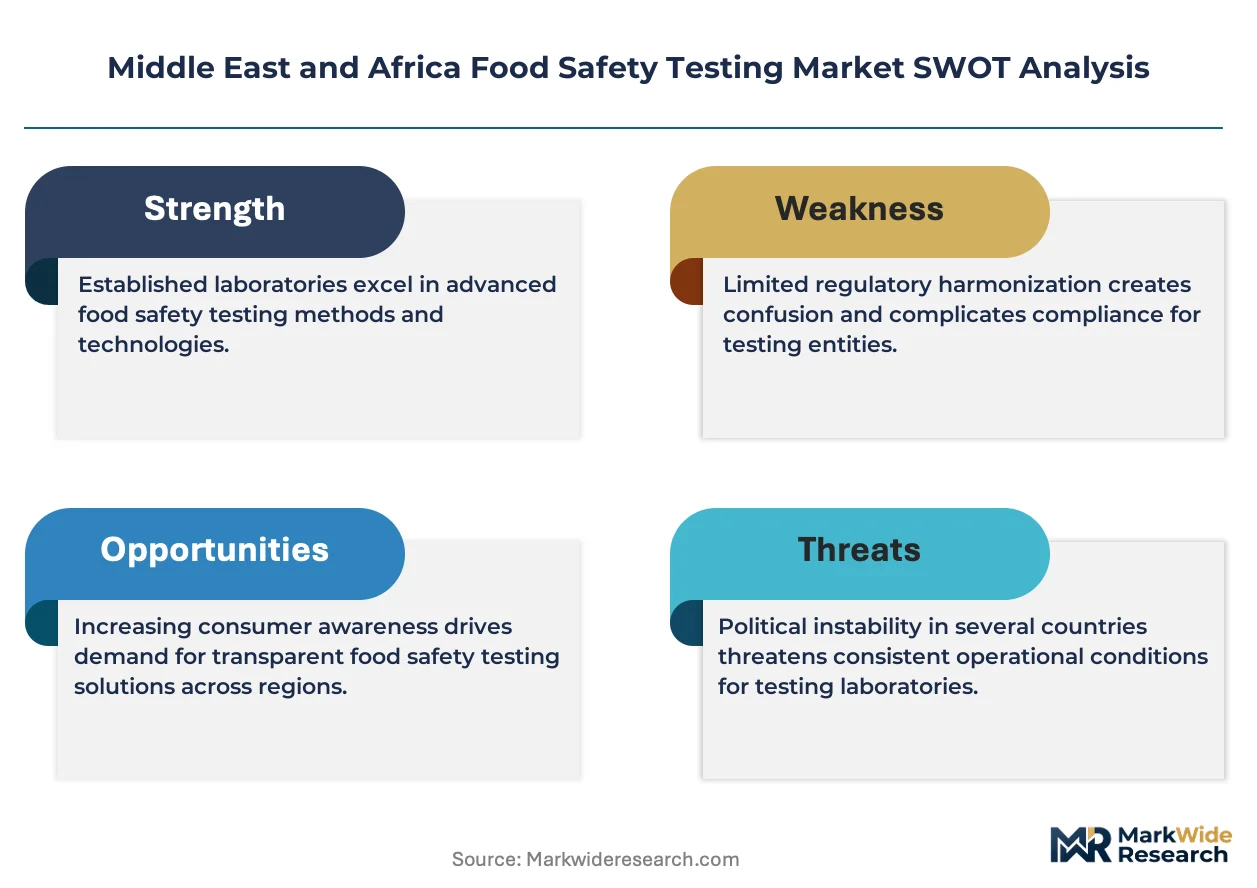
Gulf food retailers are building captive laboratory capacity to bypass third-party testing delays and secure direct control over private-label certification timelines. This vertical integration is compressing contract testing margins while redistributing capital toward rapid-detection instrumentation.
Growth Catalysts
- SFDA Pre-Shipment Mandates:Saudi Arabia's tightened import screening for perishables forces suppliers to obtain accredited laboratory certification before container loading, creating guaranteed testing demand at Gulf ports.
- PCR Platform Adoption:Same-day pathogen identification is replacing culture-based methods in South African dairy processing facilities, accelerating equipment replacement cycles and reagent consumption.
- Private-Label Expansion:Regional supermarket chains sourcing directly from farms in Kenya and Ethiopia require comprehensive residue panels that exceed baseline regulatory minimums.
Market Restraints
- Reference Material Scarcity:Certified reference standards for halal authentication markers remain concentrated in European suppliers, creating input cost volatility and procurement delays for African laboratories.
- Accreditation Backlogs:ISO 17025 certification queues at South African National Accreditation System stretch beyond fourteen months, freezing facility expansion timelines.
- Power Infrastructure Gaps:Unreliable grid supply in Nigerian testing facilities forces investment in redundant generator capacity, elevating fixed cost structures against European competitors.
Strategic Opportunities
- East African Laboratory Networks:Kenya and Tanzania lack accredited facilities for mycotoxin testing in grain exports, presenting first-mover positioning for portable rapid-test platforms.
- Blockchain-Linked Verification:Integration of immutable chain-of-custody records with PCR results is opening premium pricing tiers for high-value halal meat exports to Gulf retail channels.
- MOHAP Digital Submission Pathways:The UAE's electronic certificate upload system rewards laboratories with automated approval workflows, favoring capital investment in LIMS integration over manual reporting competitors.
Industry Challenges
- Specialized Technician Shortages:Gulf laboratories competing for molecular biology-trained analysts face recruitment pressure from pharmaceutical manufacturing wages in Dubai Science Park.
- Multi-Jurisdiction Compliance Burden:Testing facilities serving both Saudi Aramco catering and Ethiopian airline suppliers must maintain parallel quality manual systems for SFDA and ISO 22000 requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Food Safety Testing Market |
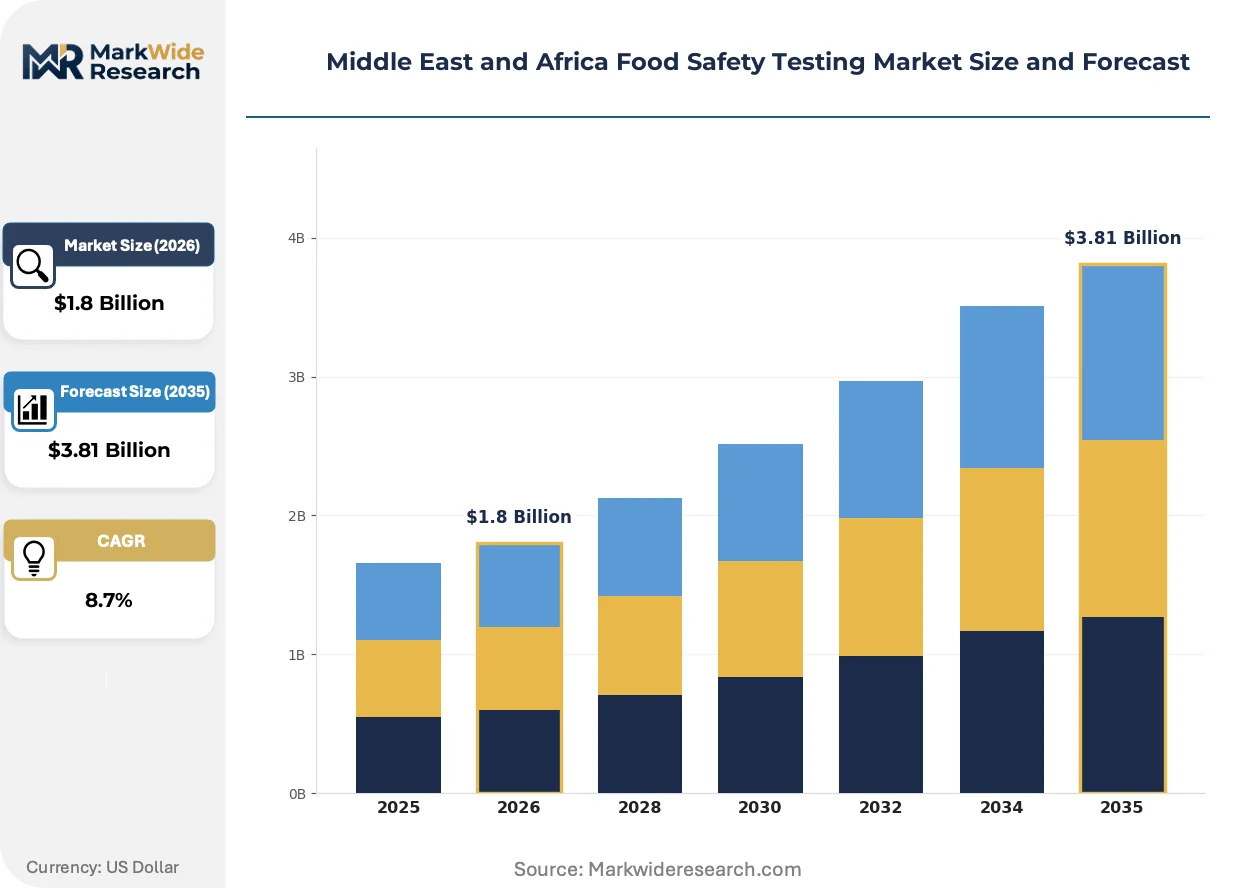
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Testing Type: Microbiological Testing, Chemical Testing, Residue Testing, Nutritional Analysis Product Type: Dairy Products, Meat Products, Fruits & Vegetables, Seafood End User: Food Manufacturers, Food Retailers, Testing Laboratories, Regulatory Agencies Technology: PCR Testing, Immunoassay, Chromatography, Mass Spectrometry |
| Companies Covered | Eurofins Scientific, SGS Société Générale de Surveillance SA, ALS Limited, Intertek Group plc, Bureau Veritas SA, TÜV SÜD AG, Thermo Fisher Scientific Inc., PerkinElmer Inc., Mérieux NutriSciences, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Food Safety Testing Market Shifts & Advancements
Next-generation sequencing platforms and artificial intelligence-assisted spectral analysis are compressing detection timelines while expanding the range of analytes verifiable in single workflows. These capabilities are redrawing competitive boundaries between centralized reference laboratories and distributed rapid-testing networks.
Multiplex PCR panels capable of simultaneous detection of salmonella, listeria, and E. coli in a single reaction are fragmenting the traditional microbiological testing market. Large Gulf retail chains are deploying these platforms in regional distribution centers, bypassing centralized laboratory queues. This decentralization is compressing contract testing volumes for legacy culture-based service providers while expanding reagent and instrumentation revenue streams.
SFDA and MOHAP alignment on maximum residue limit harmonization is eliminating redundant testing requirements for cross-border shipments between Saudi Arabia and the UAE. Processed food manufacturers are consolidating certification budgets toward single-laboratory dual-jurisdiction approvals. This regulatory convergence is disadvantaging smaller national laboratories lacking bilateral accreditation scope.
Airline catering procurement departments are unbundling safety testing from ingredient supply contracts, mandating independent third-party verification regardless of supplier certification status. Emirates Flight Catering and Saudi Catering Company now require separate laboratory reports for each production batch. This verification layering is visible most acutely in Dubai and Jeddah, where hub airport volumes justify dedicated on-site testing facilities.
Middle East and Africa Food Safety Testing Market Segmentation
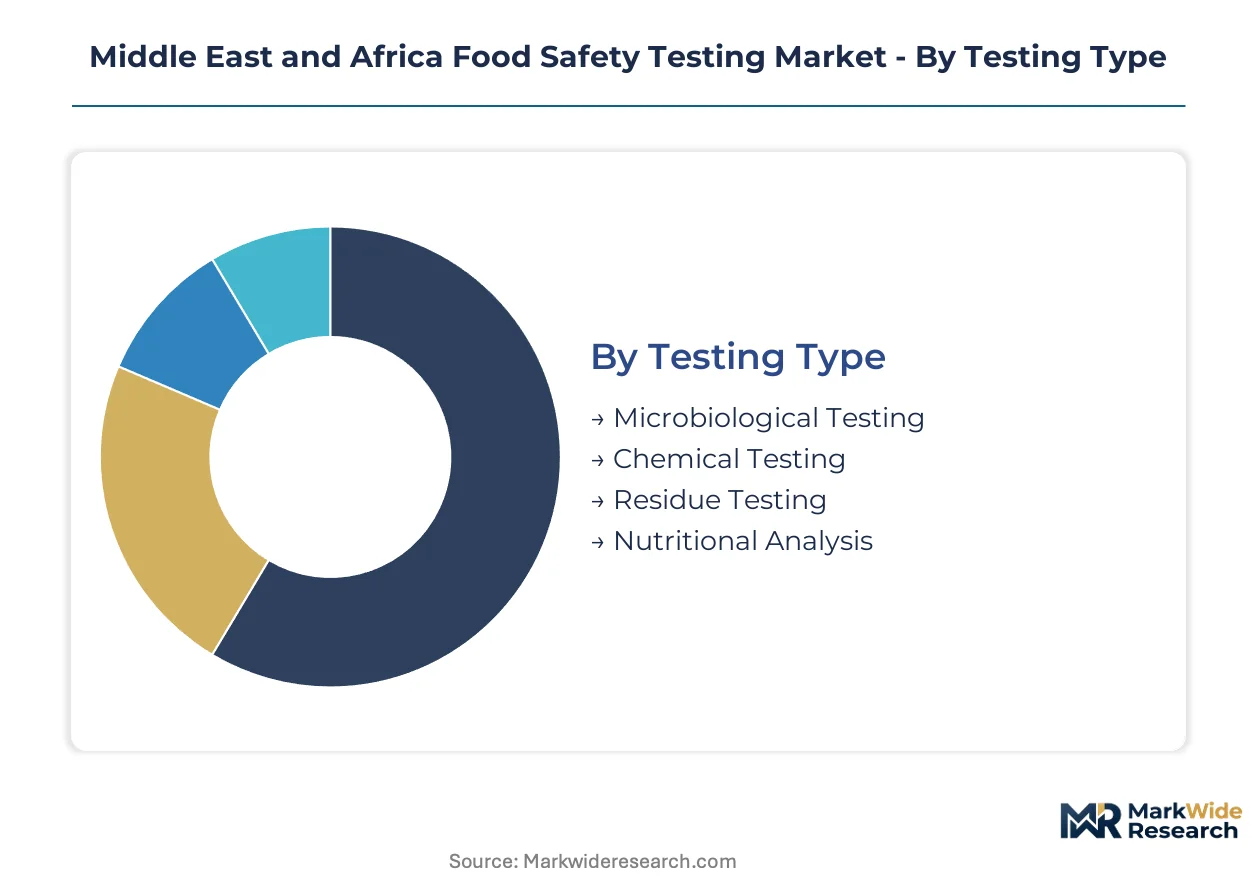
Segmentation in the Middle East and Africa Food Safety Testing Market reveals distinct procurement patterns between Gulf import corridors and domestic African supply chains. Testing intensity varies sharply across these boundaries, with export-facing segments demanding higher certification tiers than locally consumed production.
Testing Type:
Domestic African laboratories concentrate on microbiological screening for ambient-distribution risks, while Gulf-facing facilities prioritize chemical residue panels for import compliance.
- Microbiological Testing:Culture-based and rapid molecular methods detect salmonella, listeria, and E. coli in perishable shipments. South African dairy processors and UAE airline caterers sustain the highest contract volumes due to cold-chain vulnerability and batch-release mandates.
- Chemical Testing:Chromatographic and spectroscopic techniques verify additive compliance and contaminant thresholds. Saudi Aramco catering contracts and Dubai hotel procurement departments drive premium pricing for expedited turnaround times.
- Residue Testing:Hormone and antibiotic panels dominate Kenyan and Ethiopian farm export certifications to Saudi Arabia.
- Nutritional Analysis:Label-claim verification supports private-label expansion across Gulf supermarket chains.
Microbiological testing commands the established base. The steepest expansion runs through chemical testing as SFDA tightens additive screening protocols.
Product Type:
Margin concentration follows import dependency, with products facing the strictest Gulf entry requirements generating the highest testing premiums per unit.
- Dairy Products:Comprehensive hormone, antibiotic, and pathogen panels are mandatory for UAE and Saudi import clearance. Large South African processors operate captive laboratories to bypass third-party queues for UHT milk and cheese exports.
- Meat Products:Halal authentication protocols require parallel safety testing and religious certification. Saudi and UAE retail channels demand blockchain-linked chain-of-custody documentation alongside PCR pathogen results.
- Fruits & Vegetables:Pesticide residue screening concentrates at Kenyan and Tanzanian export hubs serving Dubai wholesale markets.
- Seafood:Histamine and heavy metal testing dominates Moroccan and Egyptian shipments to Jeddah and Dammam ports.
Dairy products anchor revenue concentration. Meat products are climbing the fastest as halal authentication layers additional verification requirements.
End User:
Laboratory capacity allocation tilts toward buyer archetypes building in-house capabilities versus those relying on contract services.
- Food Retailers:Private-label expansion and direct farm sourcing are compressing third-party testing margins as chains deploy multiplex PCR platforms in regional distribution centers. Carrefour UAE and Lulu Group have established captive laboratories for private-brand certification.
- Food Manufacturers:Processed food producers consolidate certification budgets toward dual-jurisdiction approvals as SFDA and MOHAP harmonize maximum residue limits.
- Testing Laboratories:Eurofins and SGS anchor contract relationships with multinational grocery chains through pan-African networks and Gulf port inspection services.
- Regulatory Agencies:SFDA and MOHAP accreditation requirements shape equipment procurement cycles and facility expansion timelines.
Food retailers are gaining share fastest. Food manufacturers retain the deepest established relationships with centralized reference laboratories.
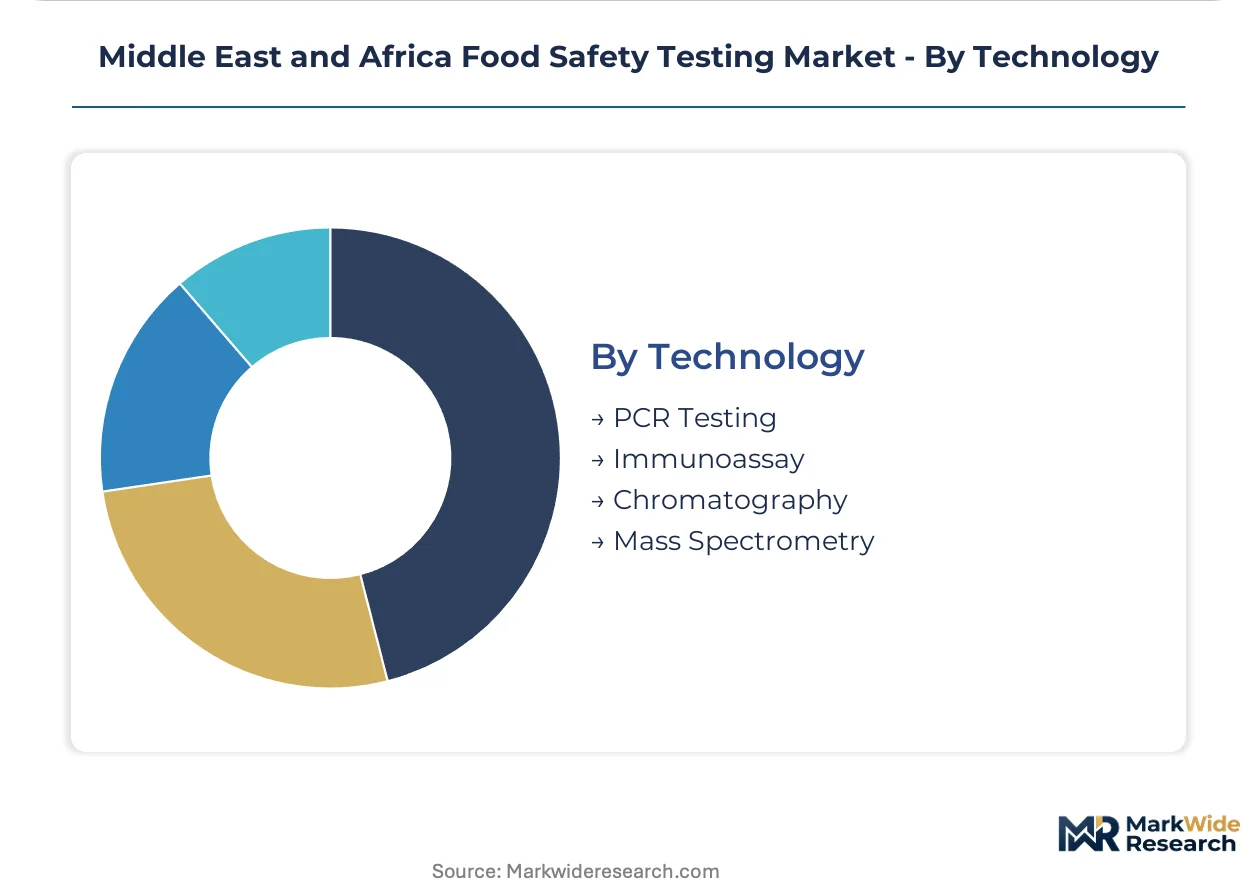
Technology:
Capital deployment diverges between rapid-detection instrumentation for distributed networks and high-sensitivity platforms for centralized reference facilities.
- PCR Testing:Same-day pathogen identification is displacing culture-based methods in South African dairy facilities and Gulf retail distribution centers. Multiplex panels detecting salmonella, listeria, and E. coli simultaneously are fragmenting traditional microbiological service markets.
- Chromatography:HPLC and GC systems anchor chemical residue and nutritional analysis workflows at ISO 17025-accredited facilities serving Saudi Aramco and Emirates Flight Catering.
- Immunoassay:Lateral flow and ELISA formats support rapid screening at Kenyan grain export terminals lacking full laboratory infrastructure.
- Mass Spectrometry:LC-MS/MS platforms enable multi-residue pesticide panels required for UAE fruit and vegetable import clearance.
Chromatography holds the installed base. PCR testing is expanding most quickly as equipment replacement cycles accelerate across South African and Gulf facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kenya's grain exports to Dubai wholesale markets drive pesticide residue screening demand at Mombasa and Nairobi testing hubs. Ethiopian dairy and meat shipments to Saudi Arabia require parallel halal authentication and pathogen verification. South Africa's processed food sector sustains the region's deepest laboratory infrastructure.
Saudi Arabia
SFDA pre-shipment mandates for perishable imports create guaranteed testing demand at Jeddah and Dammam ports. The regulator's tightened screening protocols force suppliers to obtain accredited laboratory certification before container loading. Riyadh-based food retailers are building captive PCR capacity to bypass third-party delays for private-label certification.
United Arab Emirates
MOHAP food control standards and electronic certificate upload systems reward laboratories with automated approval workflows. Dubai's Emirates Flight Catering and Saudi Catering Company procurement departments mandate independent third-party verification for each production batch. The Dubai Science Park cluster faces recruitment pressure for molecular biology-trained analysts from pharmaceutical manufacturing wages.
South Africa
Mature laboratory infrastructure and large processed-food sector sustain higher testing volumes than elsewhere in the region. ISO 17025 certification queues at South African National Accreditation System stretch beyond fourteen months, freezing facility expansion timelines. Cape Town and Johannesburg dairy processors operate captive laboratories to bypass third-party queues for UHT milk and cheese exports.
Kenya
Direct farm sourcing by Gulf supermarket chains requires comprehensive residue panels exceeding baseline regulatory minimums. Kenyan grain export terminals lack accredited facilities for mycotoxin testing, presenting first-mover positioning for portable rapid-test platforms. Nairobi and Mombasa testing hubs concentrate pesticide residue screening for fruits and vegetables bound for Dubai wholesale markets.
Nigeria
Unreliable grid supply in testing facilities forces investment in redundant generator capacity, elevating fixed cost structures against European competitors. The country's national food safety regulator shapes laboratory accreditation requirements through import screening protocols. Lagos and Abuja clusters see demand concentration for microbiological screening in ambient-distribution corridors.
Middle East and Africa Food Safety Testing Market Competitive Landscape
Player mix skews toward multinational inspection conglomerates with pan-regional laboratory networks. Market structure concentrates around three global testing groups holding bilateral accreditation scope across SFDA and MOHAP jurisdictions. Two strategic archetypes dominate: integrated inspection-certification providers anchoring Gulf port relationships, and specialized halal authentication laboratories unlocking Saudi and UAE retail channels. Competitive moves center on ISO 17025 accreditation expansion and multiplex PCR platform deployment in regional distribution centers.
Within the integrated inspection tier, Eurofins Scientific and SGS Société Générale de Surveillance SA exemplify archetypes competing through geographic coverage and port-based service integration. Bureau Veritas SA occupies a specialist position in halal authentication protocols. These three entities represent the accreditation-heavy competitive vector where dual-jurisdiction approvals determine contract access for Saudi Aramco catering and Dubai airline suppliers.
| Leading Market Players |
|---|
| Eurofins Scientific |
| SGS Société Générale de Surveillance SA |
| ALS Limited |
| Intertek Group plc |
| Bureau Veritas SA |
| TÜV SÜD AG |
| Thermo Fisher Scientific Inc. |
| PerkinElmer Inc. |
| Mérieux NutriSciences |
| Others |
Supply & Pricing Matrix
Fourteen-day ISO 17025 certification queues at South African National Accreditation System compress pricing power for expedited testing tiers, concentrating margin capture among laboratories with pre-accredited Gulf port relationships. Pre-shipment mandates from SFDA and MOHAP force suppliers to absorb certification costs upstream, redistributing value toward integrated inspection-certification providers.
Pricing Analysis
PCR platform pricing gaps separate same-day pathogen identification premiums from legacy culture-based economy tiers, with multiplex panel deployments commanding standard-tier positioning. Three-tier pricing structure across premium, standard, and economy levels differentiates by accreditation scope and turnaround guarantee, with ISO 17025 dual-jurisdiction certification extracting maximum premiums from Saudi Aramco and Emirates Flight Catering contracts. Pricing pressure stems from Gulf retailers building captive laboratory capacity, compressing third-party contract margins. Food manufacturers exhibit highest price sensitivity due to consolidated certification budgets, while airline catering procurement departments remain least sensitive given batch-release mandate rigidity.
Supply Chain Analysis
European suppliers concentrate certified reference standards for halal authentication markers, while South Africa anchors the region's deepest laboratory infrastructure for processed food testing. Reagent supply draws from German chromatography specialists and American PCR platform manufacturers, with African facilities facing procurement delays and input cost volatility. Single-source vulnerability concentrates in reference material scarcity for mycotoxin and hormone panels. Distribution runs through pan-African laboratory networks anchored at Gulf ports, with Eurofins and SGS maintaining bilateral accreditation scope across SFDA and MOHAP jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Gulf supermarket chains deploying captive PCR capacity, fragmenting contract testing relationships that previously anchored centralized reference laboratory revenues.
For Market Incumbents: Compound accreditation breadth across SFDA and MOHAP jurisdictions to defend against retailer vertical integration, while accelerating multiplex PCR platform deployment in regional distribution centers to capture reagent revenue streams displaced from culture-based service contracts. Threat substitution from blockchain-linked verification protocols demands LIMS integration investment to maintain automated approval workflow access. For New Entrants and Emerging Players: Differentiate on portable rapid-test platforms for East African grain export terminals lacking mycotoxin infrastructure, targeting Kenya and Tanzania as the most penetrable geographies. Halal authentication specialization unlocks Saudi and UAE retail channel access. Go-to-market through direct farm sourcing relationships with Gulf supermarket chains requiring comprehensive residue panels exceeding baseline regulatory minimums. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational inspection conglomerates divesting non-core African laboratory assets, particularly facilities with latent ISO 17025 accreditation capacity. Long-term viability rests on regulatory convergence between Gulf Cooperation Council maximum residue limits consolidating certification demand. Signal to watch: SFDA-MOHAP harmonization implementation pace as inflection indicator for dual-jurisdiction approval value.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Accreditation Expansion | Dual-jurisdiction certification unlocks Saudi Aramco and Dubai airline catering contracts. |
| Multiplex PCR Platform Deployment | Same-day pathogen identification displaces culture-based methods in South African dairy facilities. |
| Blockchain-Linked Verification Integration | Immutable chain-of-custody records open premium pricing tiers for halal meat exports. |
| East African Laboratory Network Buildout | Kenya and Tanzania mycotoxin testing gaps present first-mover positioning for rapid-test platforms. |
| LIMS Integration Investment | MOHAP digital submission pathways reward automated approval workflow capabilities. |
Research Methodology
The analysis maps microbiological testing, chemical residue screening, nutritional analysis, and halal authentication protocols, each validated through laboratory directors, regulatory compliance officers, airline catering procurement managers, and Gulf supermarket chain quality executives. Primary interview findings triangulate against SFDA import screening protocols, MOHAP food control standards, ISO 17025 accreditation databases, and customs pre-shipment certification records. Bottom-up testing volume estimates reconcile with top-down market sizing across the projection horizon.
Consistency checks validate volume and value outputs against equipment procurement cycles, reagent consumption patterns, and accreditation expansion timelines reported by South African National Accreditation System and Gulf port inspection authorities. Segmentation dimensions span testing type, product category, end-user archetype, and technology platform. CAGRs derive from laboratory capacity utilization trends and regulatory mandate implementation schedules, with PCR platform adoption curves and private-label expansion rates serving as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained SFDA-MOHAP regulatory convergence or stable reference material supply chains would require recalibration. Forecasts reflect assumptions regarding accreditation queue durations, equipment replacement cycles, and Gulf retailer captive laboratory buildout pace. Recalibration cycles align with material shifts in maximum residue limit harmonization, blockchain verification protocol adoption, and East African export corridor infrastructure development.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Residual Lactose Analyzer Market
Food Safety Testing
UK Food Testing Market
Food Safety Testing
Gum Content Tester Market
Food Safety Testing
Global Food Authenticity Testing Market
Food Safety Testing
Amylase Testing Market
Food Safety Testing
North America Food Safety Testing Market
Food Safety Testing
Carbohydrates Testing Services Market
Food Safety Testing
Beverage Tester Market
Food Safety Testing
Global Bacteriological Testing Market
Food Safety Testing
Salmonella Testing Market
Food Safety Testing
Water Activity Meter Market
Food Safety Testing
Testing, Inspection, and Certification in Consumer Goods and Retail Market
Food Safety Testing
Dairy Testing Services Market
Food Safety Testing
US Legionella Testing Market
Food Safety Testing
Global Meat Speciation Testing Market
Food Safety Testing
Water Activity Instrumentation Market