
 Form-Fill-Seal (FFS) Packaging Machine Market | 2026-2036
Form-Fill-Seal (FFS) Packaging Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Form-Fill-Seal (FFS) Packaging Machine Market Foresight
Polyethylene film is consolidating its position as the dominant packaging substrate in horizontal FFS systems for snack and bakery applications, displacing multilayer laminates on total cost grounds. Syntegon Technology GmbH leverages integrated servo-drive architectures to sustain throughput leadership in pharmaceutical-grade vertical systems. ProMach Inc. anchors North American aftermarket service revenue through regional spare-parts distribution. SACMI Imola S.C. competes in ceramic-tile-adjacent flexible packaging with rotary FFS platforms engineered for abrasive filling environments.
Form-fill-seal packaging machines execute synchronized unwinding, forming, filling, and sealing operations in continuous or intermittent motion cycles, typically achieving output rates from 30 to 600 packages per minute depending on format and product viscosity. Vertical FFS configurations dominate free-flowing granular applications where gravity-assisted filling minimizes product giveaway, while horizontal FFS systems capture premium margin pools in pillow-bag and gusseted formats for fragile or irregular products. Biodegradable film compatibility represents the fastest-growing machine specification segment as converters retrofit sealing-bar temperature controls and modified atmosphere capabilities to handle starch-based and polylactic acid substrates with narrower heat-sealing windows.
FDA food-contact notification requirements and EU MDR technical documentation obligations compel machine builders to validate hygienic design standards and material traceability across stainless-steel contact surfaces and polymer sealing jaws. China's SAMR implements GB standards for food machinery safety that restrict market access for non-compliant imported equipment. Stakeholders must monitor evolving extended producer responsibility frameworks in the European Union and individual US state legislation, as these will determine which film-substrate machine configurations retain long-term commercial viability without downstream recycling infrastructure penalties.
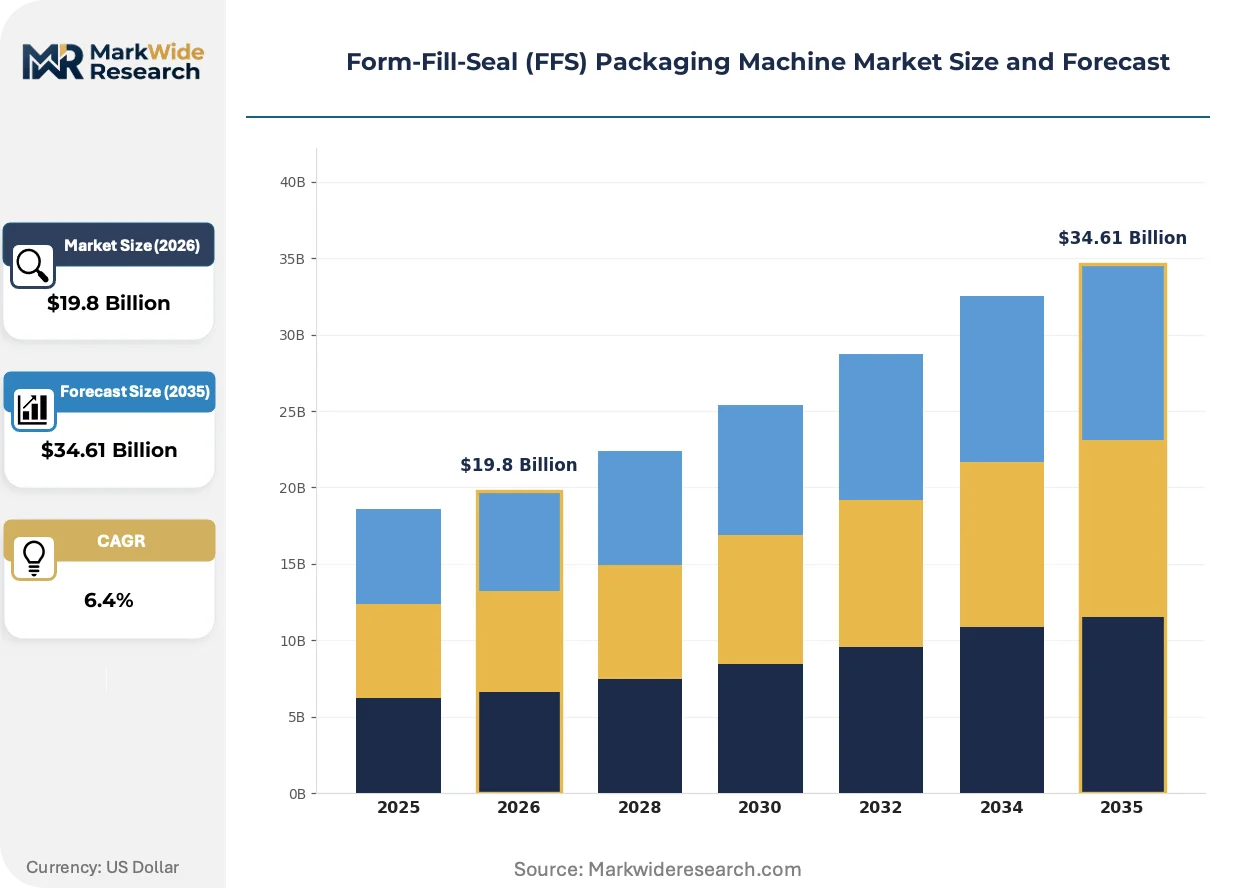
Market Dynamics
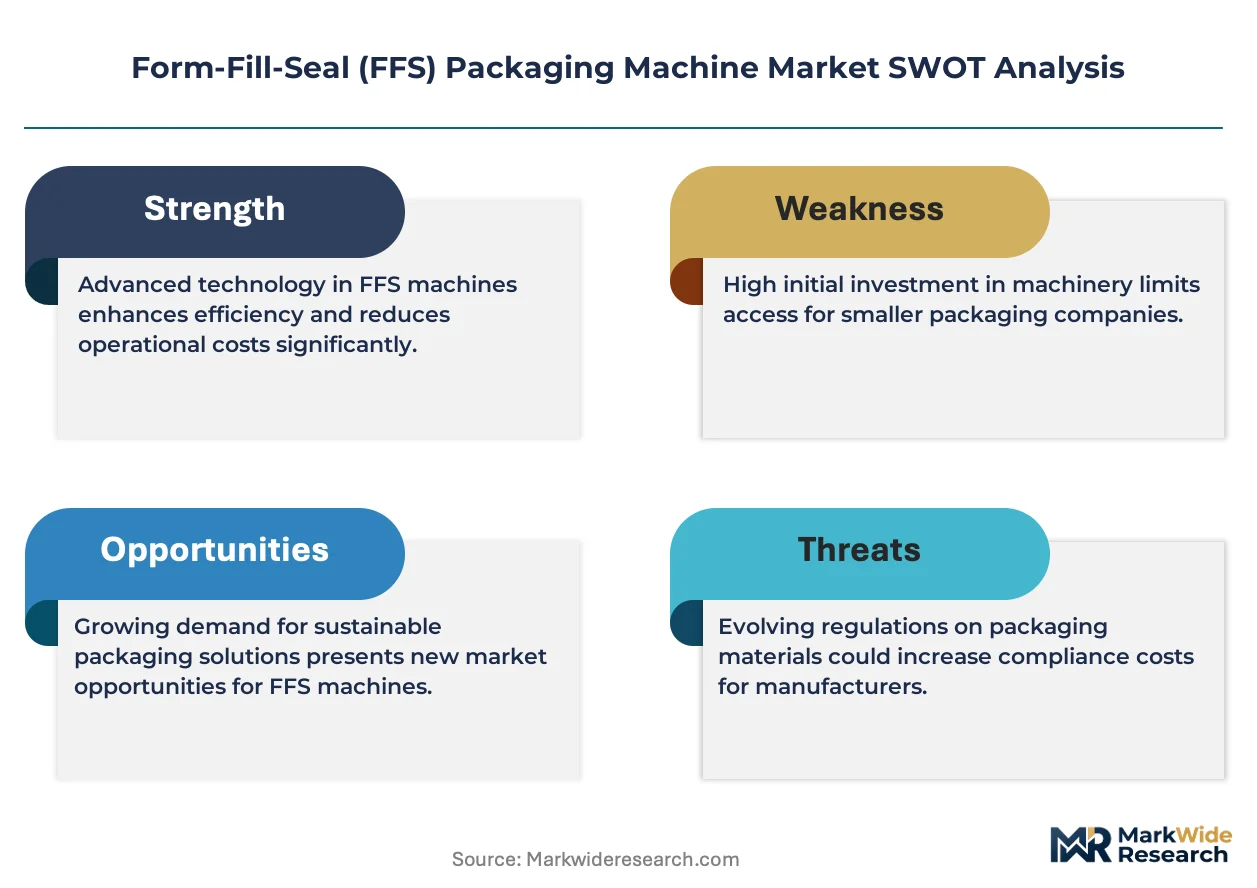
Biodegradable film compatibility requirements are forcing machine builders to reengineer sealing systems around starch-based and polylactic acid substrates with narrower thermal windows, compressing equipment refresh cycles across installed bases.
Growth Catalysts
- EU MDR technical documentation obligations:Pharmaceutical-grade vertical FFS systems face mandatory hygienic design validation and material traceability for stainless-steel contact surfaces, pulling replacement demand from aging European installed bases.
- China's SAMR GB standards:Food machinery safety regulations restrict market access for non-compliant imported equipment, creating captive demand for locally certified or retrofitted systems in Chinese food processing clusters.
- Gravity-assisted filling technology:Vertical FFS configurations capture accelerating automation budgets in free-flowing granular applications where product giveaway minimization justifies capital expenditure against labor arbitrage.
Market Restraints
- Sealing-bar component volatility:Precision heating elements and ceramic-coated polymer sealing jaws face concentrated supply from German and Japanese specialty metallurgy suppliers, exposing lead-time risk.
- Extended producer responsibility frameworks:EU and individual US state legislation on downstream recycling infrastructure penalties threaten commercial viability of multilayer laminate machine configurations without compatible waste streams.
- Biodegradable substrate technical limitation:Starch-based and polylactic acid films exhibit heat-sealing windows 40-60% narrower than polyethylene, requiring temperature control retrofits that extend commissioning timelines.
Strategic Opportunities
- Modified atmosphere capability convergence:Integration of gas-flushing systems with biodegradable film handling creates premium positioning in European fresh-produce and ready-meal packaging lines.
- Rotary FFS abrasive filling environments:Ceramic-tile-adjacent flexible packaging applications in Italy and Spain present white space for platforms engineered around dust-heavy, high-wear operational conditions.
- US state-level EPR legislation tailwind:California and Oregon extended producer responsibility frameworks accelerate converter investment in monomaterial-compatible equipment ahead of compliance deadlines.
Industry Challenges
- Servo-drive integration complexity:Pharmaceutical-grade vertical systems require synchronization between integrated servo architectures and legacy pneumatic forming stations, extending commissioning and validation timelines.
- IP fragmentation around biodegradable sealing:Proprietary temperature control algorithms and ceramic jaw coatings create licensing friction between European machine builders and Asian component suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Form-Fill-Seal (FFS) Packaging Machine Market |
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $34.61 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Machine Type: Vertical FFS, Horizontal FFS, Rotary FFS, Modular FFS, Multi-lane FFS Packaging Material: Polyethylene, Polypropylene, Aluminum Foil, Paper Laminates, Biodegradable Films End Application: Food Processing, Pharmaceutical Products, Personal Care, Household Chemicals, Agrochemicals Operator Type: Manufacturers, Contract Packers, Co-packers, Brand Owners |
| Companies Covered | Syntegon Technology GmbH, ProMach Inc., SACMI Imola S.C., Robert Bosch GmbH, IMA Group, Coesia S.p.A., Mespack S.L., Winpak Ltd., Duravant, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Form-Fill-Seal (FFS) Packaging Machine Market Shifts & Advancements
Equipment specification is pivoting from throughput maximization toward substrate flexibility and regulatory pre-certification, compressing competitive differentiation around sealing-system engineering rather than mechanical speed.
Servo-driven forming and sealing architectures are absorbing capital allocation from pneumatic systems in pharmaceutical-grade vertical FFS configurations. Multinational CPG manufacturers in Germany and the United States are specifying integrated servo-drive platforms for new line installations despite 15-25% capital cost premiums. This technology is absorbing market share from intermittent-motion legacy equipment by enabling real-time seal-parameter adjustment for biodegradable substrates.
EU MDR technical documentation obligations are reshaping machine design specifications across export markets. FDA food-contact notification requirements compel parallel validation of hygienic design standards and material traceability, extending product development cycles for builders serving dual jurisdiction customers. Pharmaceutical-grade vertical systems face the most intensive documentation burden, driving consolidation among builders with dedicated regulatory affairs capabilities.
After-sales service unbundling is disrupting traditional bundled maintenance contracts in North American installed bases. Regional spare-parts distribution networks are capturing margin pools previously held by original equipment manufacturers, with large-scale CPG operators in the United States negotiating direct procurement of critical wear components. This pattern is most visible in horizontal FFS snack and bakery applications where standardized sealing-bar geometries enable third-party component supply.
Form-Fill-Seal (FFS) Packaging Machine Market Segmentation
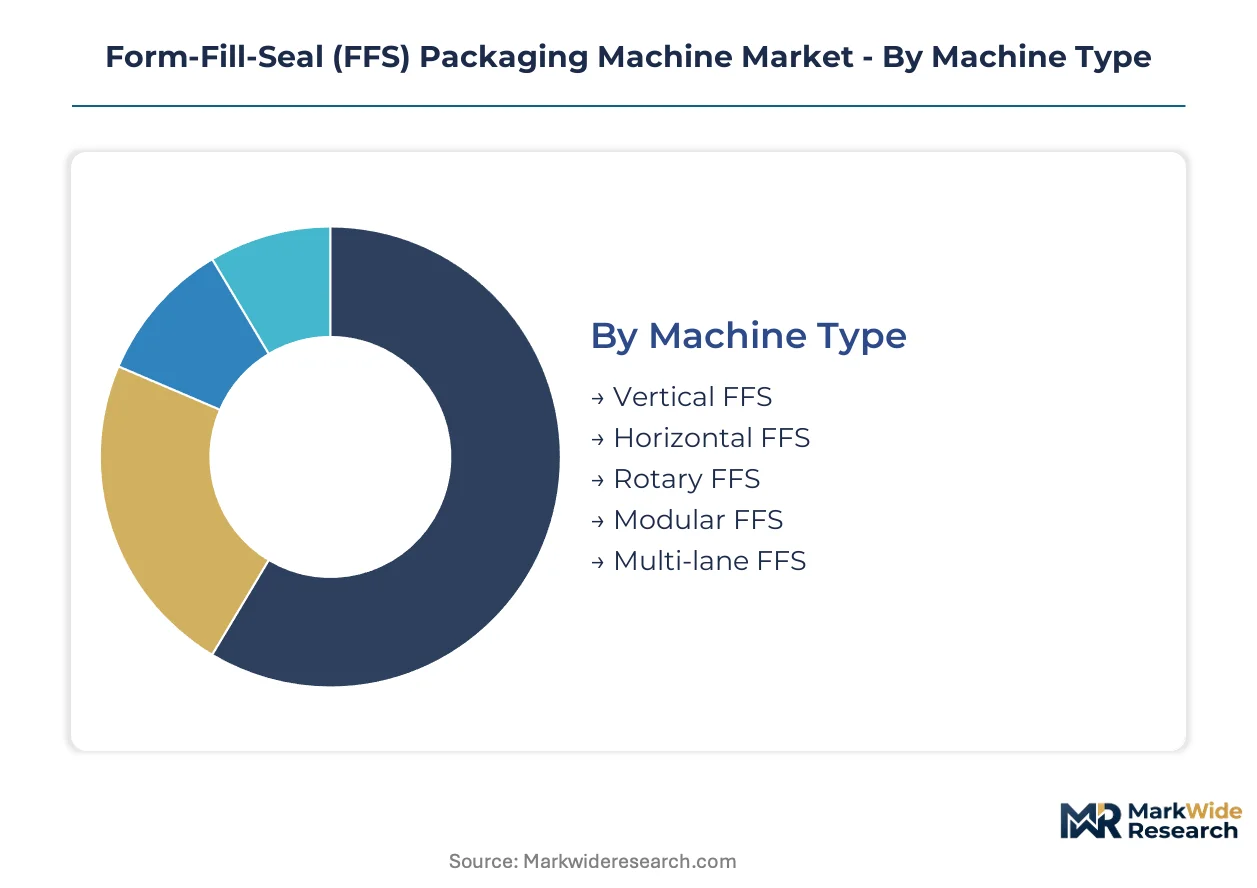
FFS machine segmentation reflects divergent capital deployment strategies across substrate flexibility, regulatory compliance intensity, and production scale requirements. Equipment specification choices cascade through sealing-system engineering, aftermarket service structures, and regional certification pathways.
Machine Type:
Customization intensity spans purpose-built pharmaceutical systems at one extreme to standardized snack-food platforms at the other, with rotary configurations occupying a specialized middle ground for abrasive environments.
- Vertical FFS:Gravity-assisted filling architectures dominate free-flowing granular applications in food processing clusters across Germany and China. Product giveaway minimization justifies capital expenditure against labor arbitrage, particularly in rice, sugar, and salt packaging lines where throughput exceeds 400 packages per minute.
- Horizontal FFS:Pillow-bag and gusseted format capabilities capture premium margin pools for fragile or irregular products. Demand concentrates in United States snack and bakery operations where polyethylene film displacement of multilayer laminates accelerates equipment refresh cycles.
- Rotary FFS:Engineered for dust-heavy, high-wear operational conditions in ceramic-tile-adjacent flexible packaging.
- Modular FFS:Reconfigurable forming stations enable substrate switching without line replacement.
- Multi-lane FFS:Parallel processing arrays target high-volume pharmaceutical stick-pack and sachet applications.
Leading the category by volume: Vertical FFS. Expanding most quickly: Modular FFS.
Packaging Material:
Material specification determines sealing-bar temperature control requirements, with narrow heat-sealing window substrates demanding precision engineering investments.
- Polyethylene:Consolidating dominance in horizontal systems for snack and bakery applications on total cost grounds. Simpler thermal profiles reduce commissioning complexity and spare-parts inventory breadth compared to multilayer alternatives.
- Biodegradable Films:Starch-based and polylactic acid substrates exhibit heat-sealing windows 40-60% narrower than conventional films. EU extended producer responsibility frameworks and California state legislation accelerate converter investment in compatible equipment ahead of compliance deadlines.
- Polypropylene:Higher clarity and barrier properties target premium food and personal care segments.
- Aluminum Foil:Retort and aseptic applications in pharmaceutical and ready-meal packaging.
- Paper Laminates:Sustainability-driven substitution in dry goods and confectionery formats.
Widest installed base: Polyethylene. Steepest expansion trajectory: Biodegradable Films.
End Application:
Regulatory burden intensity separates pharmaceutical validation requirements from food-contact notification pathways, with agrochemicals presenting specialized corrosion-resistance specifications.
- Food Processing:FDA food-contact regulations and China's SAMR GB standards reshape machine design specifications across export markets. Gravity-assisted vertical configurations dominate free-flowing granular automation budgets where product giveaway minimization drives capital allocation.
- Pharmaceutical Products:EU MDR technical documentation obligations compel hygienic design validation and material traceability for stainless-steel contact surfaces. Servo-drive architectures absorb capital allocation despite 15-25% cost premiums over pneumatic legacy systems.
- Personal Care:Cosmetic and hygiene product lines prioritize format flexibility for promotional packaging.
- Household Chemicals:Chemical resistance specifications govern polymer sealing jaw selection.
- Agrochemicals:Abrasive filling environments require specialized rotary platform engineering.
Dominant revenue concentration: Food Processing. Gaining share fastest: Pharmaceutical Products.
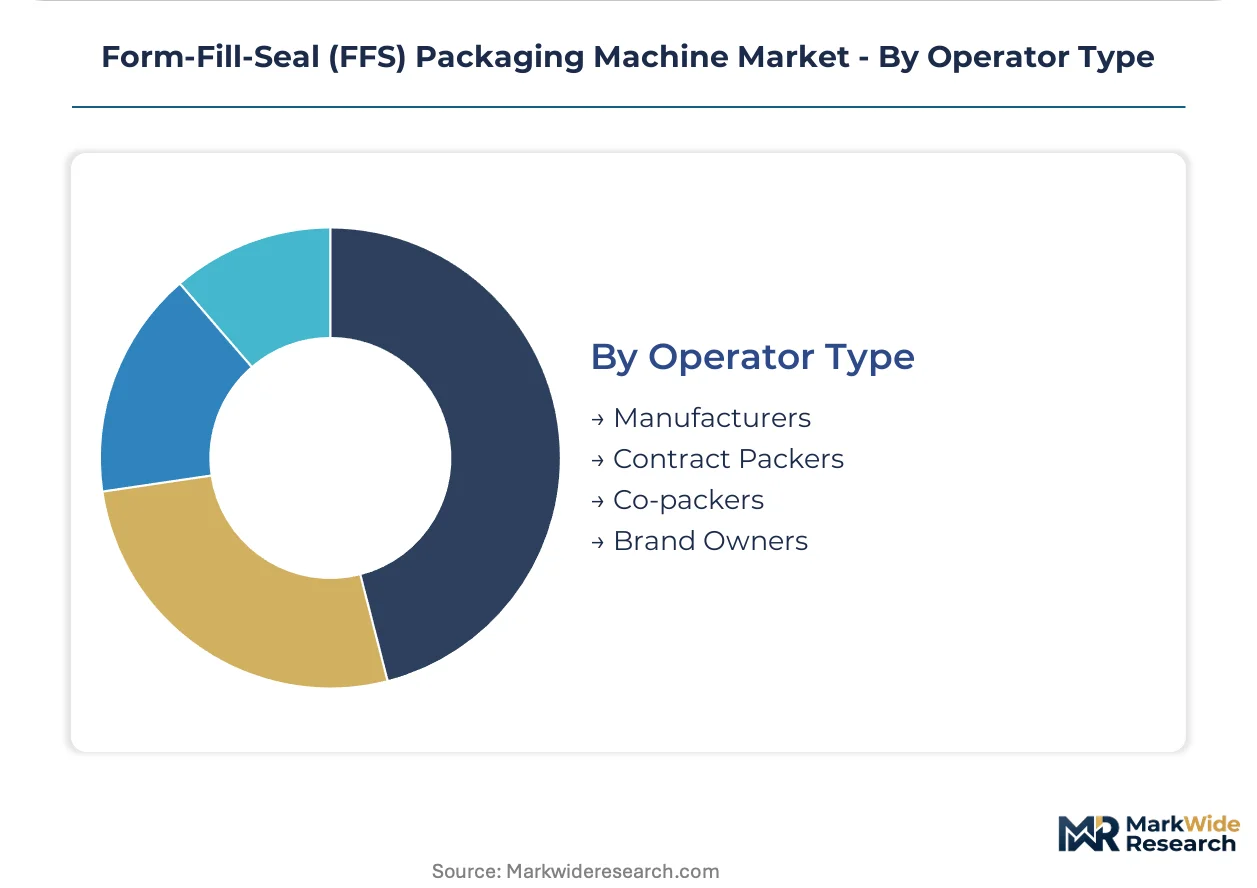
Operator Type:
Asset ownership models differentiate captive manufacturing from outsourced packaging services, with implications for equipment financing and maintenance contract structures.
- Manufacturers:Direct capital deployment enables integrated servo-drive specification and regulatory pre-certification. Large-scale CPG operators in Germany and the United States negotiate direct procurement of critical wear components, unbundling aftermarket service from original equipment manufacturers.
- Contract Packers:Volume volatility demands substrate flexibility and rapid format changeover capabilities. Equipment refresh cycles compress as biodegradable film compatibility becomes a competitive bidding requirement.
- Co-packers:Seasonal demand peaks drive rental and lease financing preferences.
- Brand Owners:Marketing-driven packaging innovation prioritizes format differentiation over throughput maximization.
Highest equipment ownership concentration: Manufacturers. Fastest-growing procurement segment: Contract Packers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Guangdong and Bavaria concentrate FFS equipment manufacturing through tax incentives and bonded logistics facilities. These zones anchor regional supply chains serving food processing and pharmaceutical packaging clusters.
United States
California and Oregon extended producer responsibility frameworks accelerate converter investment in monomaterial-compatible equipment ahead of compliance deadlines. FDA food-contact notification requirements compel hygienic design validation for stainless-steel contact surfaces. Chicago and Minneapolis manufacturing corridors host large-scale CPG operators negotiating direct procurement of critical wear components.
Germany
EU MDR technical documentation obligations pull replacement demand from aging European installed bases in pharmaceutical-grade vertical systems. Bavarian industrial zones concentrate servo-drive architecture production for premium equipment lines. Stuttgart and Munich engineering clusters sustain aftermarket service revenue through regional spare-parts distribution networks.
China
SAMR GB standards for food machinery safety restrict market access for non-compliant imported equipment, creating captive demand for locally certified systems. Yangtze River Delta food processing clusters drive gravity-assisted vertical FFS automation in free-flowing granular applications. Shanghai and Suzhou manufacturing hubs concentrate export-oriented equipment assembly for Southeast Asian markets.
Italy
Ceramic-tile-adjacent flexible packaging applications in Emilia-Romagna present specialized demand for rotary FFS platforms engineered around dust-heavy, high-wear operational conditions. REACH compliance requirements reshape machine design specifications for export-oriented builders. Bologna and Modena industrial districts anchor abrasive filling environment equipment development.
India
FSSAI food safety regulations and BIS certification requirements reshape import specifications for European and East Asian equipment suppliers. Maharashtra and Gujarat pharmaceutical manufacturing corridors drive demand for servo-driven forming architectures in stick-pack applications. Mumbai-Pune industrial belt concentrates contract packaging services requiring rapid format changeover capabilities.
Form-Fill-Seal (FFS) Packaging Machine Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade vertical systems consolidating around integrated servo-drive providers while horizontal snack-food platforms fragment across regional fabricators. The vendor base organizes into three strategic archetypes: European precision-engineering houses with regulatory pre-certification capabilities, North American aftermarket service aggregators, and Asian cost-optimized volume producers. Consolidation pressures intensify through technology licensing partnerships and geographic expansion into captive demand zones created by SAMR and FDA compliance barriers.
Within the European precision-engineering tier, Syntegon Technology GmbH and Robert Bosch GmbH exemplify integrated servo-drive architectures serving pharmaceutical validation requirements. Among North American service-anchored players, ProMach Inc. occupies a position emphasizing regional spare-parts distribution networks. SACMI Imola S.C. represents specialized rotary platform engineering for abrasive filling environments in ceramic-adjacent applications.
| Leading Market Players |
|---|
| Syntegon Technology GmbH |
| ProMach Inc. |
| SACMI Imola S.C. |
| Robert Bosch GmbH |
| IMA Group |
| Coesia S.p.A. |
| Mespack S.L. |
| Winpak Ltd. |
| Duravant |
| Others |
Supply & Pricing Matrix
Captive servo-drive manufacturing in Germany and Japan anchors pricing power for pharmaceutical-grade vertical systems, while outsourced sealing-bar component sourcing exposes mid-tier horizontal platforms to margin compression from specialty metallurgy suppliers.
Pricing Analysis
Volume-driven snack-food horizontal systems trade at commodity margins against premium-priced pharmaceutical vertical configurations with integrated servo architectures. Pricing stratifies across FDA-validated, CE-marked, and standard economy tiers based on hygienic design certification and material traceability documentation. Cost compression in standard horizontal equipment intensifies as polyethylene film compatibility becomes table stakes. Contract packers exhibit highest price sensitivity; multinational CPG operators in Germany and the United States absorb 15-25% capital premiums for regulatory pre-certification.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese specialty metallurgy suppliers for precision heating elements and ceramic-coated polymer sealing jaws. Component manufacturing concentrates in Germany, Japan, and China, with stainless-steel contact surface fabrication feeding from Bavarian industrial zones. Supply chain risk centers on concentrated lead-time exposure for sealing-bar assemblies. Distribution runs through regional spare-parts networks that are unbundling from original equipment manufacturer maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Servo-drive architectures are displacing pneumatic legacy systems across pharmaceutical-grade installations, compressing competitive differentiation toward sealing-system engineering rather than mechanical throughput.
For Market Incumbents: Hedge against biodegradable substrate commoditization by deepening in-house production of temperature control algorithms and ceramic jaw coatings. Lock in regulatory pre-certification capabilities across FDA and EU MDR jurisdictions before Asian component suppliers resolve IP licensing friction. Prioritize backward integration into servo-drive manufacturing to defend margin position against European precision-engineering houses.
For New Entrants and Emerging Players: Direct-to-contract-packer digital channels bypass entrenched OEM aftermarket service relationships in North American snack and bakery corridors. Target rotary FFS abrasive filling environments in Italy and Spain where dust-heavy operational conditions create white space beyond standardized horizontal platforms. Lead with rapid format changeover capabilities and biodegradable film compatibility as competitive bidding differentiators.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational CPG operators seeking captive regulatory affairs capabilities and regional spare-parts distribution networks. Long-term viability favors builders with integrated servo-drive architectures serving pharmaceutical validation requirements rather than commodity horizontal platforms facing polyethylene film margin erosion. Watch California and Oregon extended producer responsibility compliance deadlines as inflection indicators for monomaterial-compatible equipment demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Sealing-System Engineering Investment | Biodegradable film compatibility with narrower heat-sealing windows demands precision temperature control retrofits. |
| Regulatory Pre-Certification Pathway | EU MDR technical documentation and FDA food-contact notification requirements extend product development cycles for compliant builders. |
| Aftermarket Service Unbundling | Regional spare-parts distribution networks capture margin pools previously held by original equipment manufacturers. |
| Backward Integration into Servo-Drive Manufacturing | Integrated architectures absorb capital allocation despite premiums over pneumatic legacy systems in pharmaceutical applications. |
| Geographic Expansion into SAMR-Certified Production | China's GB standards for food machinery safety create captive demand for locally certified or retrofitted systems. |
Research Methodology
Trade association filings, customs and trade data, and SEC 10-K disclosures formed the secondary backbone, cross-referenced against primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and regulatory affairs leads at multinational CPG operators. Bottom-up and top-down triangulation validated equipment shipment volumes and capital expenditure patterns across food processing and pharmaceutical manufacturing clusters.
Bottom-up modeling aggregated segment-level outputs across machine type, packaging material specification, end application intensity, and operator ownership structure; top-down validation checked aggregate market evolution against macroeconomic indicators and industry association benchmarks. CAGRs derived from regression analysis of historical capital equipment cycles and forward projection of regulatory compliance deadlines. Forecast inputs incorporated SAMR certification timelines, EU MDR implementation phases, and US state-level extended producer responsibility legislation progression.
The model holds under stable regulatory implementation schedules; deviation in compliance deadline acceleration or biodegradable substrate technical breakthroughs would shift equipment refresh cycle assumptions. Forecasts reflect documented assumptions about sealing-system engineering investment trajectories and aftermarket service unbundling velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Paper Slitting Machine Market
Packaging Machinery
Global Filling Machines Market
Packaging Machinery
Liquid Filling Machines Market
Packaging Machinery
Corrugated Box Making Machine Market
Packaging Machinery
Tray Sealer Machines Market
Packaging Machinery
Foil Embossing Machine Market
Packaging Machinery
Automatic Banding Machine Market
Packaging Machinery
Bag in Box Packaging Machine Market
Packaging Machinery
Product Dispensing Machinery Market
Packaging Machinery
LAMEA Printing Machinery Market
Packaging Machinery
Global Food and Beverage Packaging Machinery Market
Packaging Machinery
Bottle Filling Machine Market
Packaging Machinery
Puffer Machines Market
Packaging Machinery
Medicine Decoction and Packing Machines Market
Packaging Machinery
Air Cushion Machine Market
Packaging Machinery
Shrink Label Machine Market