
 Bottle Filling Machine Market | 2026-2036
Bottle Filling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Bottle Filling Machine Market Intelligence
The European Union's Single-Use Plastics Directive, mandating increased recycled content in bottles, is recalibrating equipment design priorities for manufacturers. This shift demands machines that handle material variations and lighter-weight preforms without compromising speed. Krones AG leverages its engineering depth to offer flexible filling systems for these new materials. Sidel Group differentiates with integrated line solutions, while KHS GmbH competes on the efficiency of its resource-saving technologies.
Bottle filling machines are automated or semi-automated systems designed to dispense a precise quantity of liquid or semi-liquid product into containers. These systems ensure high volumetric accuracy and consistent fill levels, critical for production lines in various industries. Volumetric filling technologies command a significant share due to their versatility across different product viscosities. The beverages application segment remains the largest, but pharmaceutical applications are expanding, demanding aseptic filling capabilities and stringent validation.
Equipment compliance is governed by a matrix of international standards and regional regulations. In the United States, the FDA dictates standards for food contact materials, while in Europe, machines must carry the CE marking, signifying adherence to health and safety requirements. Good Manufacturing Practices (GMP) guide the design of fillers for the pharmaceutical sector globally. Ultimately, a manufacturer's choice between rotary and inline systems hinges on balancing line speed requirements against capital expenditure constraints.
Market Dynamics
The imperative to use more recycled content, driven by regulations like the EU's Single-Use Plastics Directive, is the central force shaping the bottle filling machine market. This pressure forces a redesign of fillers to handle lighter, less consistent PET bottles without sacrificing the high-speed performance demanded by beverage and consumer goods producers.
Growth Catalysts
- Recycled Content Mandates:European Union regulations requiring specific percentages of recycled PET in beverage bottles are compelling producers to invest in new or upgraded filling lines capable of handling material variability.
- Beverage Sector Expansion:Demand from Southeast Asia's food processing industry, particularly in Vietnam and Indonesia, for filling ready-to-drink teas, functional waters, and dairy alternatives stimulates equipment sales.
- Aseptic Technology Adoption:The pharmaceutical and premium beverage sectors are driving adoption of aseptic and ultra-clean filling systems to ensure product safety, extend shelf life, and meet stringent health standards without using preservatives.
Market Restraints
- High Capital Expenditure:The significant upfront investment required for high-speed rotary fillers and complex aseptic lines acts as a major barrier for small and medium-sized enterprises, limiting their capacity expansion.
- Material Handling Complexity:Lighter-weight bottles and those with high recycled content exhibit lower top-load strength and inconsistent physical properties, creating stability challenges on high-speed lines and risking production stoppages.
- Component Lead Times:Extended lead times for critical components, such as precision-engineered filling valves, servo motors, and custom control systems, can delay new line installations and impact project timelines.
Strategic Opportunities
- Modular and Flexible Systems:There is a significant opportunity for machines with modular designs that allow for quick changeovers between different bottle sizes, product types, and cap formats, catering to the trend of product customization.
- Emerging Economies:Developing markets in Africa and Latin America represent untapped regions for mid-range, robust, and easy-to-maintain inline fillers, particularly for water, juices, and edible oils.
- Digitalization Services:Offering integrated digital services, such as remote monitoring, predictive maintenance, and Overall Equipment Effectiveness (OEE) analytics, creates new recurring revenue streams beyond initial equipment sales.
Industry Challenges
- Skilled Technician Scarcity:A shortage of technicians with the mechatronics and software skills needed to install, operate, and service highly automated and networked filling systems poses a significant operational challenge for end-users.
- Legacy System Integration:Integrating new, state-of-the-art filling machines into existing production lines with older upstream and downstream equipment can create communication bottlenecks and limit overall line efficiency.
- Validation and Compliance:The process of validating equipment to meet the distinct regulatory requirements of different end markets, such as GMP for pharmaceuticals and FDA food contact rules, is time-consuming and costly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bottle Filling Machine Market |
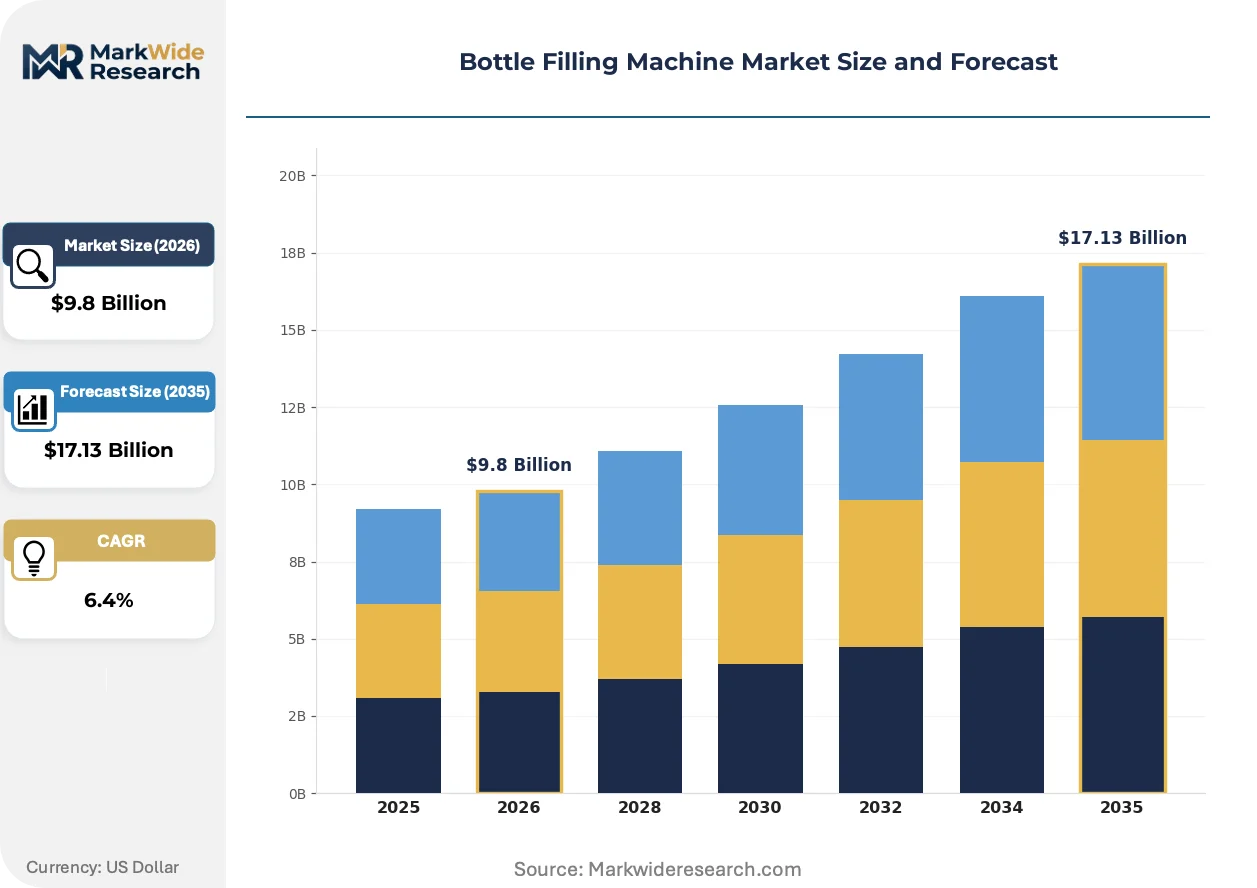
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inline Fillers, Rotary Fillers, Overflow Fillers, Gravity Fillers, Pressure Fillers Technology: Piston Filling, Volumetric Filling, Time Pressure Filling, Vacuum Filling, Net Weight Filling Application: Beverages, Pharmaceuticals, Personal Care, Chemicals, Household Liquids End User: Bottling Plants, Contract Manufacturers, Packagers, Filling Machinery Suppliers |
| Companies Covered | Krones AG, KHS GmbH, GEA Group, Sidel Group, Tetra Pak International S.A., Accutek Packaging Equipment, Coesia Group, Sacmi Imola S.C., Barry-Wehmiller Companies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bottle Filling Machine Market Strategic Shifts & Innovations
Innovation in the bottle filling machine market is defined by the push for greater flexibility and intelligence. Equipment design is evolving to handle a wider array of sustainable materials and to provide data that optimizes production, responding directly to both regulatory pressures and shifting consumer preferences for product diversity.
Robotic handling within filling lines provides unprecedented flexibility in container management. Beverage and pharmaceutical manufacturers are adopting these systems to manage small-batch production runs and frequent format changes efficiently. This advanced automation is converging with digital twin technology, allowing for virtual simulation of line changeovers and predictive maintenance, thereby reducing physical downtime and optimizing asset utilization.
Traceability mandates, such as the US FDA's Food Safety Modernization Act (FSMA), are influencing equipment specifications. These regulations require robust product tracking and data logging throughout the production process, compelling equipment to feature integrated serialization capabilities. The pharmaceutical and infant nutrition segments are most directly impacted, driving investment in fillers that can embed unique codes on each container and verify them in-line.
End-user procurement models are evolving from one-time capital purchases toward more flexible, usage-based arrangements. This shift disrupts the traditional sales cycle for equipment manufacturers, especially when serving contract packers and startup brands that lack the capital for large upfront investments. The trend is most prominent in North America and Europe, where a dynamic craft beverage and niche consumer goods market favors operational expenditure models over capital expenditure.
Bottle Filling Machine Market Segmentation
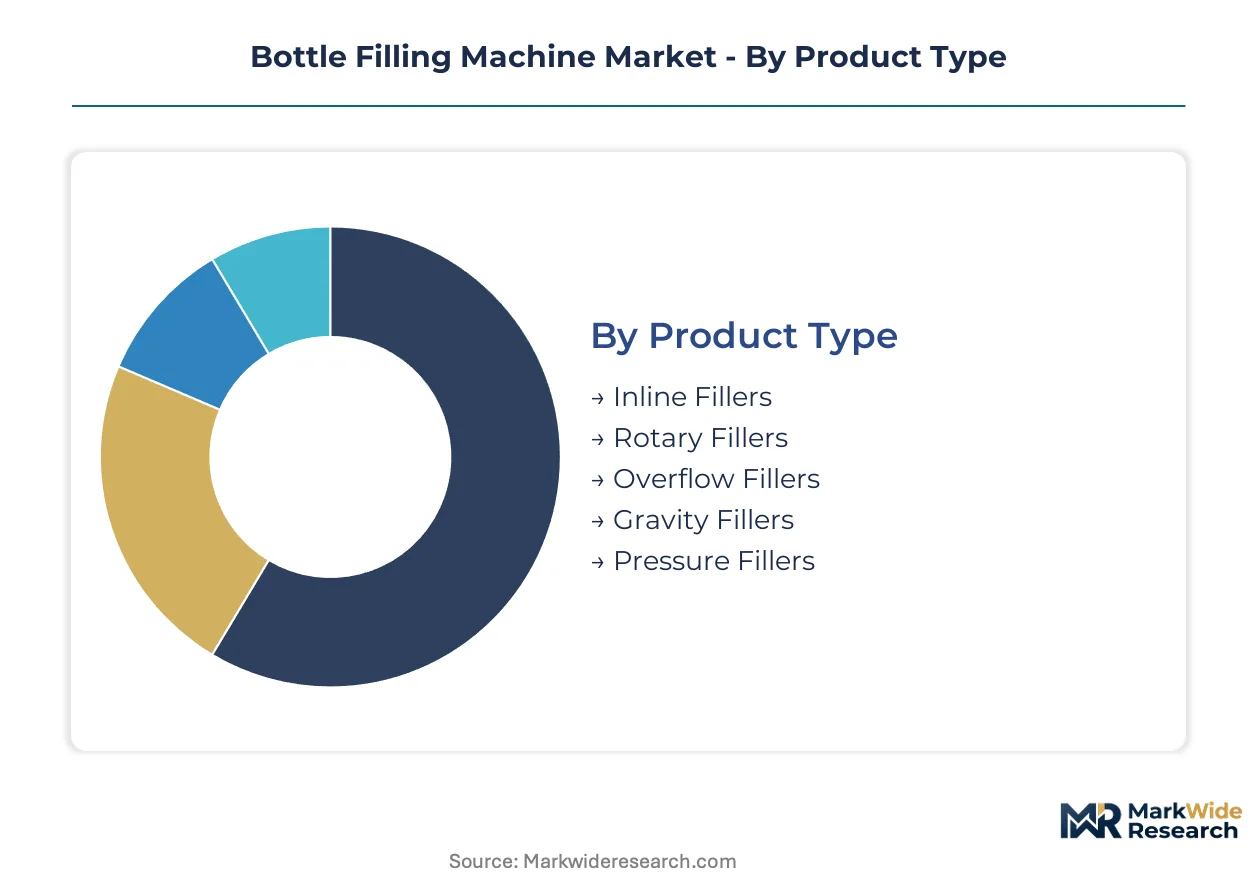
The bottle filling machine market's segmentation reflects the diverse requirements across industries for precision, speed, and material compatibility. Each segment addresses specific production challenges, from high-volume beverage lines to stringent pharmaceutical applications, influencing equipment design and operational parameters.
Product Type:
The regulatory landscape significantly influences the choice of bottle filling machine product types, particularly concerning precision and material handling.
- Rotary Fillers:These continuous-motion machines feature multiple filling heads arranged on a rotating carousel, designed for ultra-high-speed production lines. Demand concentrates in the beverage sector for mass-produced items like soft drinks and functional waters, where high throughput is essential and material variations from directives like the EU's Single-Use Plastics Directive are managed.
- Inline Fillers:Operating with intermittent motion, these systems fill bottles sequentially as they move along a conveyor, offering greater flexibility for diverse container sizes and product types. Demand is prominent in pharmaceutical and personal care industries for varied product runs, requiring specific validation to FDA and EMA standards.
- Overflow Fillers:These machines fill containers to a consistent cosmetic level, ideal for products sold by volume where visual uniformity is critical, such as certain personal care items.
- Gravity Fillers:Utilizing gravity to dispense free-flowing, non-foaming liquids, these simple and cost-effective machines are suitable for water, juices, and thin oils.
- Pressure Fillers:Employing pressure to force product into containers, these systems are effective for thicker liquids and can achieve faster fill rates than gravity fillers.
Rotary Fillers sit at the top of the volume ranking, with Inline Fillers climbing the fastest.
Technology:
The choice of filling technology directly correlates with the viscosity and required precision of the product being dispensed.
- Volumetric Filling:This technology dispenses a precise volume of product into each container, regardless of density fluctuations, ensuring consistent fill levels. Demand is strong across the beverage and personal care sectors, where product consistency and accurate dosing are critical for consumer satisfaction.
- Net Weight Filling:Machines employing net weight filling dispense product based on a target weight, compensating for density changes and offering high accuracy for valuable or high-precision liquids. Demand is concentrated in pharmaceutical applications and for expensive chemical products, where stringent regulatory compliance and minimal product giveaway are paramount.
- Piston Filling:These systems use a piston to draw and dispense a measured amount of product, making them ideal for highly viscous liquids like sauces, creams, and gels.
- Time Pressure Filling:Product is dispensed for a set duration under pressure, making this a cost-effective solution for uniform, non-foaming liquid products.
- Vacuum Filling:This technology draws product into bottles using a vacuum, preventing drips and ensuring clean fills, particularly effective for thin liquids.
Volumetric filling technologies maintain a dominant share, while Net Weight Filling is gaining traction for high-value applications.
Application:
Different application segments impose varying levels of regulatory stringency and aseptic requirements on filling machine design.
- Beverages:This segment encompasses the high-speed filling of a vast array of liquids, including water, carbonated soft drinks, juices, and ready-to-drink teas. Demand from Southeast Asia's expanding food processing industry, particularly in Vietnam and Indonesia, for functional waters and dairy alternatives, drives equipment sales, influenced by directives like the EU's Single-Use Plastics Directive.
- Pharmaceuticals:Requires aseptic filling capabilities and stringent validation to ensure product safety, sterility, and compliance with global standards such as Good Manufacturing Practices (GMP) and regulations from the FDA and EMA. Demand is expanding due to the need for precise dosing and extended shelf life for medicines and vaccines.
- Personal Care:Involves filling cosmetics, shampoos, lotions, and other beauty products, often requiring aesthetic fill levels and versatile handling of different viscosities.
- Chemicals:Handles a diverse range of industrial and specialty chemicals, necessitating machines built with corrosion-resistant materials and safety features for hazardous liquids.
- Household Liquids:Encompasses the filling of cleaning agents, detergents, and other domestic products, often in larger volumes and requiring robust, high-throughput systems.
The Beverages segment continues to drive the largest volume, with Pharmaceutical applications showing significant expansion.
End User:
End-user procurement models are evolving, influencing the demand for both capital equipment and flexible service solutions.
- Bottling Plants:These large-scale operations are typically dedicated to high-volume production of specific products, requiring significant capital investment in high-speed rotary fillers and integrated lines. Demand is driven by major beverage and food corporations seeking maximum efficiency and throughput for their core products.
- Contract Manufacturers:These facilities produce goods for multiple brands, necessitating versatile, quick-changeover systems to handle diverse product types, bottle sizes, and packaging formats. Demand from North America and Europe's dynamic craft beverage and niche consumer goods markets favors operational expenditure models over large capital outlays.
- Packagers:These end-users focus on comprehensive packaging solutions, integrating filling machines with capping, labeling, and secondary packaging equipment to deliver a complete product.
- Filling Machinery Suppliers:This segment comprises the manufacturers of the filling equipment itself, serving the other end-user categories directly or through distribution channels.
Bottling Plants remain the primary purchasers of high-volume systems, while Contract Manufacturers are rapidly increasing their equipment investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering and technical talent concentrations across key manufacturing hubs anchor the global bottle filling machine market. These regions drive both demand for advanced filling solutions and the innovation required for next-generation equipment. Regulatory frameworks and expanding consumer markets significantly influence regional investment patterns and technology adoption.
Germany
German engineering expertise drives innovation in high-speed rotary fillers and aseptic systems. The country's strong manufacturing base supports demand for precision machinery across beverage and pharmaceutical sectors. CE marking requirements ensure equipment adherence to stringent health and safety standards for European distribution. Industrial clusters in Bavaria and Baden-Württemberg lead in developing modular and resource-efficient filling technologies.
United States
The United States market demands high-volume filling solutions for its vast beverage and consumer goods industries. Pharmaceutical applications require advanced aseptic capabilities and strict validation to meet FDA regulations. Investment in automation and digital services is strong, particularly in the Midwest and Southeast regions, optimizing production lines. California's food processing sector also drives demand for flexible filling systems.
Vietnam
Vietnam's expanding food processing industry creates significant demand for bottle filling machines, particularly for ready-to-drink teas and functional waters. Government initiatives support industrial modernization, encouraging investment in efficient packaging solutions. The Ho Chi Minh City metropolitan area sees concentrated investment in new filling capacity to serve growing domestic and export markets. This region focuses on mid-range, robust inline fillers.
Indonesia
Indonesia's large and growing consumer base fuels demand for beverage and personal care filling equipment. Investment is concentrating in new production facilities to meet local consumption trends for dairy alternatives and packaged water. The country's national food and drug agency (BPOM) sets standards for product safety and packaging integrity. Jakarta and Surabaya serve as key industrial centers for bottle filling machine deployment.
Bottle Filling Machine Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the bottle filling machine market. The industry exhibits a tiered structure, with established global manufacturers dominating the high-speed rotary segment. Specialized providers cater to niche applications requiring stringent precision or material handling capabilities. Strategic partnerships and technology licensing agreements are prevalent, alongside targeted capacity expansion initiatives.
European-based industrial conglomerates like Krones AG and KHS GmbH exemplify the premium-tier segment, offering comprehensive, integrated filling line solutions. Sidel Group, with its focus on packaging equipment, occupies a position emphasizing flexible and sustainable material handling. These entities anchor the market's technological advancement, particularly in addressing challenges posed by recycled content mandates. Their offerings often include advanced automation and digital integration services for end-users.
| Leading Market Players |
|---|
| Krones AG |
| KHS GmbH |
| GEA Group |
| Sidel Group |
| Tetra Pak International S.A. |
| Accutek Packaging Equipment |
| Coesia Group |
| Sacmi Imola S.C. |
| Barry-Wehmiller Companies Inc. |
| Others |
Cost & Logistics Intelligence
Bottling Plants' procurement concentration influences a project-based pricing model for high-speed rotary fillers. This structure reflects the specialized engineering and integration services required for large-scale production lines.
Pricing Analysis
Project-based pricing models dominate the bottle filling machine market, reflecting the custom engineering and integration required for complex systems. Price differentiation stems from the machine's throughput capacity and its compliance with stringent certifications like FDA or CE marking. Pricing pressure stems from increased competition among European and Asian manufacturers for mid-range inline fillers. Contract Manufacturers exhibit higher price sensitivity compared to large Bottling Plants, which prioritize long-term operational efficiency.
Supply Chain Analysis
Reverse logistics for bottle filling machines primarily involve refurbishment programs for major components and end-of-life recycling for metals. Geographic supply concentration for critical components rests in Germany, Italy, and China, which produce precision-engineered valves and advanced control systems. Raw material dependencies include specialized stainless steel, high-performance plastics, and complex electronic components. A structural supply chain risk is the single-source vulnerability for custom servo motors. Distribution runs through a network of direct sales teams and regional distributors, offering installation and after-sales support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bottle filling machine market functions as a stable compounder, driven by continuous global demand for packaged beverages and pharmaceuticals. Regulatory mandates for sustainable packaging further ensure steady equipment upgrades.
For Market Incumbents:
Anchor market leadership by investing heavily in R&D for flexible material handling systems, addressing the challenge of lighter-weight, recycled PET bottles. Consolidate market share through strategic acquisitions of specialized component manufacturers, mitigating supply chain risks. Expand aseptic filling capabilities in emerging pharmaceutical hubs to counter competition from regional players. Focus on digital twin technology to offer predictive maintenance services and enhance customer loyalty.
For New Entrants and Emerging Players:
Enter via niche applications, such as small-batch craft beverage lines or specialized pharmaceutical compounding, leveraging modular inline fillers. Target markets in Africa and Latin America, where demand for robust, easy-to-maintain equipment for water and juices remains high. A go-to-market angle involves offering flexible, lease-to-own models for SMEs lacking large capital expenditure budgets. Focus on localized service and support to build trust and market presence.
For Investors and Strategic Acquirers:
Industrial conglomerates are the most active acquirers in this space, seeking to expand their integrated line solutions. Long-term viability over a 5-10 year window remains strong due to essential end-use applications and regulatory tailwinds. Target acquisition archetypes include specialized manufacturers of aseptic filling technologies or advanced robotics for container handling. The signal to watch is the pace of adoption for usage-based procurement models across key regions.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop modular filling platforms | Enables quick changeovers for diverse product portfolios and smaller batch sizes. |
| Invest in advanced material handling R&D | Addresses challenges with recycled content and lighter-weight bottle preforms without compromising speed. |
| Expand digital service offerings | Creates recurring revenue streams through remote monitoring, predictive maintenance, and OEE analytics. |
| Target emerging economies' mid-range demand | Captures growth in regions like Vietnam and Indonesia for robust, cost-effective inline filling solutions. |
| Acquire specialized aseptic technology firms | Strengthens capabilities for pharmaceutical and premium beverage applications requiring stringent sterility. |
Research Approach
Direct dialogue with plant managers, procurement leads, and R&D directors across the beverage, pharmaceutical, and personal care sectors formed the primary research backbone. This qualitative grounding was triangulated with secondary validation from FDA filings, CE marking guidelines, and industry association reports. A bottom-up and top-down approach ensured comprehensive market sizing and validation.
A bottom-up analytical lens aggregated market data from various product types, technologies, and applications, while a top-down approach validated total market figures across the analysis window. Segmentation dimensions modeled included machine type, filling technology, end-use application, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical trends and projected demand forecasts, with inputs from packaging material innovations and consumer preference shifts.
Inputs from equipment manufacturers, end-users, and regulatory bodies were available through the study window; gaps in detailed regional investment data introduce uncertainty bands. Forecasts reflect assumptions regarding global economic stability and continued regulatory pressure for sustainable packaging solutions. Practitioners should monitor material science breakthroughs and evolving packaging formats for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Cup Fill and Seal Machine Market
Packaging Machinery
Automatic Banding Machine Market
Packaging Machinery
Binding & Lamination Machines Market
Packaging Machinery
Toilet Roll Converting Lines Market
Packaging Machinery
Corrugated Paper Machine Market
Packaging Machinery
Polyester Strapping Machines Market
Packaging Machinery
Corrugated Box Printer Slotter Machine Market
Packaging Machinery
Sack Filling Machine Market
Packaging Machinery
Powder Auger Fillers Market
Packaging Machinery
Food Packaging Machinery Market
Packaging Machinery
Global Volumetric Cup Fillers Market
Packaging Machinery
Tray Former Machines Market
Packaging Machinery
Bottle Blowing Machine Market
Packaging Machinery
Meter-Mix Dispensing Machine Market
Packaging Machinery
Beverage Can Seamers Market
Packaging Machinery
Oral Dosage Powder Packaging Machines Market