
 Asia-Pacific Modular Kitchen Market | 2026-2036
Asia-Pacific Modular Kitchen Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Modular Kitchen Market Outlook
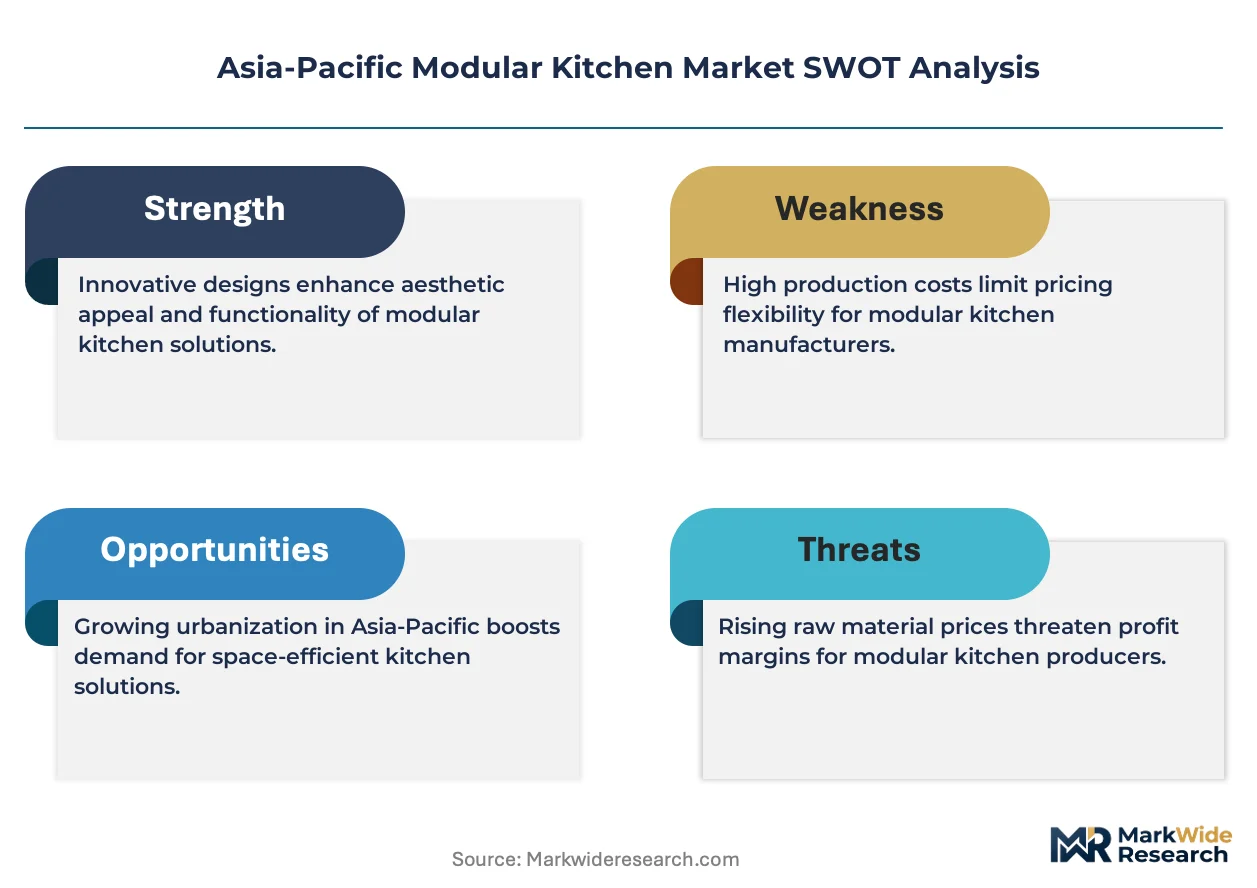
The EU Green Deal's extraterritorial influence on supply chains is broadening the addressable market for low-emission kitchen materials across Asia-Pacific export corridors. IFB Industries Ltd. leverages its integrated appliance-cabinet bundling to capture full-kitchen contracts in Indian metropolitan developments. Godrej & Boyce Mfg. Co. Ltd. anchors its position through captive timber processing and nationwide retail distribution. Hettich Holding GmbH & Co. competes on hardware technology leadership, supplying hinge and drawer systems to regional OEMs.
A modular kitchen comprises prefabricated cabinet carcasses, countertops, and storage units engineered for site assembly using standardized dimensions and connector hardware, typically employing moisture-resistant particleboard with PVC edge banding and 0.8–1.0 mm laminate surfacing to withstand thermal cycling and humidity loads in tropical climates. Cabinet and countertop configurations dominate value capture due to their bulk material intensity and customization complexity, while storage solutions represent the fastest-expanding margin pool as pull-out organizers and corner units command premium positioning. Wood and laminate materials sustain volume leadership across residential end users, whereas stainless steel gains traction in commercial hospitality installations where sanitation codes mandate non-porous surfaces.
India's BIS standards for furniture safety and China's GB standards for indoor air quality constrain adhesive and substrate formulations, compelling manufacturers to reformulate resins and source certified timber. Japan's METI energy-efficiency labeling for built-in appliances shapes product bundling strategies. Australia's TGA-equivalent building product certification creates parallel compliance tracks for export-oriented suppliers. Stakeholders must monitor divergence between national certification regimes and the accelerating consolidation of city-level green building codes that specify low-VOC material thresholds.
Market Dynamics
Prefabricated construction timelines in Southeast Asian residential developments are compressing from months to weeks, forcing kitchen suppliers to synchronize manufacturing with just-in-time site delivery schedules.
Growth Catalysts
- India's BIS certification mandates:Formaldehyde emission caps for furniture materials are accelerating reformulation toward low-VOC laminates and certified engineered wood substrates across manufacturing bases.
- Apartment completions in tier-two Indian cities:Pune and Ahmedabad are outpacing metro saturation, generating concentrated demand clusters for standardized modular kitchen configurations.
- Moisture-resistant particleboard technology:Tropical climate engineering with PVC edge banding and thermal cycling resistance is expanding addressable markets into high-humidity zones previously unserved.
Market Restraints
- Captive timber processing concentration:Supply security depends on backward integration into plantation forestry, which remains geographically concentrated in specific Indian and Southeast Asian states.
- Stainless steel cost volatility:Nickel and chromium input price swings compress margins for commercial hospitality suppliers facing fixed-price sanitation-mandated contracts.
- Adhesive reformulation lag:BIS and GB standard compliance timelines for resin chemistry extend product development cycles by 8-14 months versus conventional formulations.
Strategic Opportunities
- Vietnamese and Indonesian secondary cities:Underpenetrated residential construction markets lack established kitchen supplier networks, creating first-mover positioning for integrated appliance-cabinet bundlers.
- Japan's METI energy-efficiency labeling:Built-in appliance certification requirements are creating bundling incentives that favor full-kitchen contractors over component specialists.
- Digital configuration platforms:Direct-to-developer sales channels are displacing traditional distributor networks in Australian and Singaporean project markets.
Industry Challenges
- Skilled installation technician scarcity:Site assembly precision for standardized connector hardware requires trained crews that outpace vocational pipeline output in expanding Indian and Southeast Asian markets.
- Parallel certification tracking:Australia's TGA-equivalent building product standards and city-level green building codes create overlapping compliance documentation burdens for export-oriented suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Modular Kitchen Market |
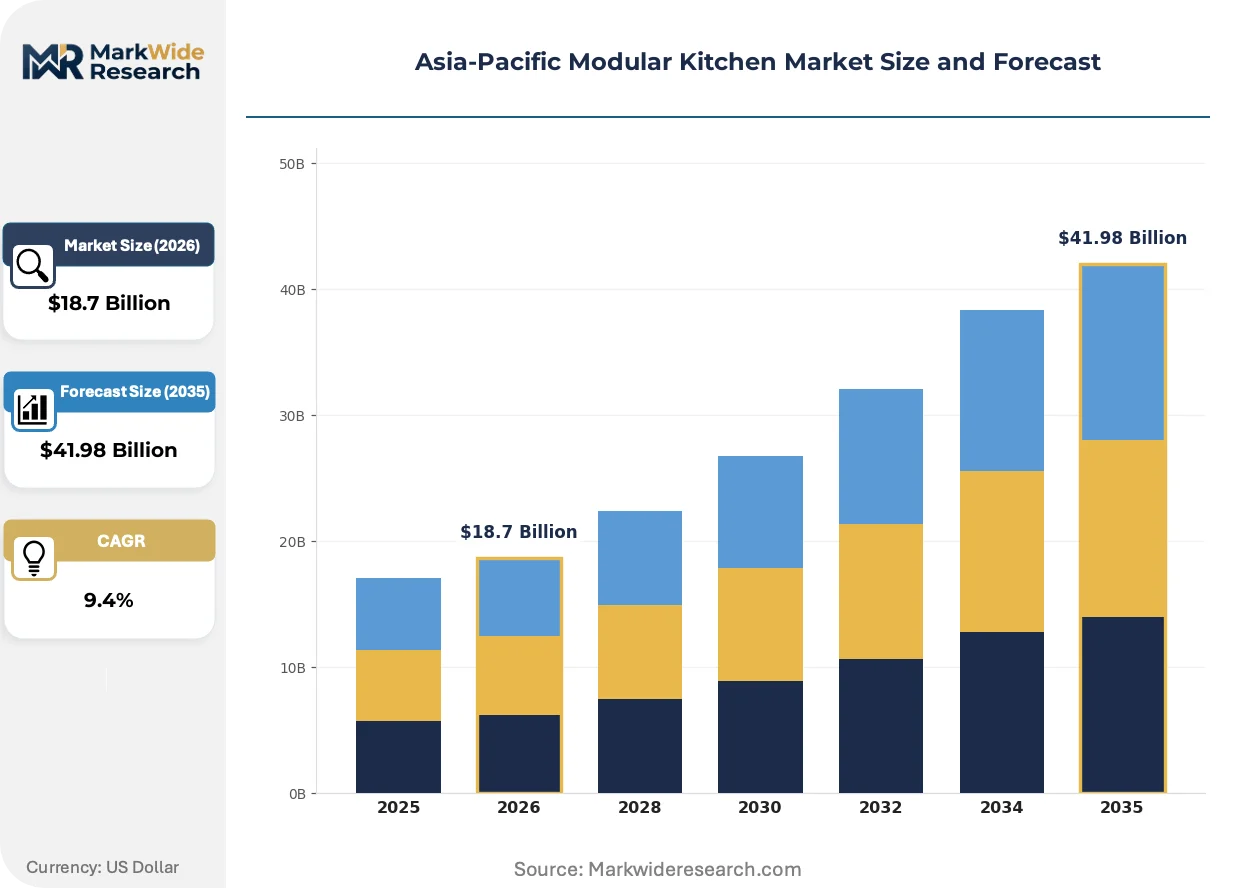
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cabinets, Countertops, Storage Solutions, Accessories Material: Wood, Laminate, Stainless Steel, Glass End User: Residential, Commercial, Hospitality, Retail Design Style: Modern, Traditional, Contemporary, Minimalist |
| Companies Covered | IFB Industries Ltd., Oppein Kitchen Cabinet, Godrej & Boyce Mfg. Co. Ltd., Zuari Furniture, Spacewood, Sleek International Pvt. Ltd., Hettich Holding GmbH & Co., Kajiwara Inc, Hafele Gmbh & Co KG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Modular Kitchen Market Strategic Shifts
Hardware-software convergence in kitchen systems is redefining value capture from material sales to integrated solution contracts. Suppliers are repositioning around data-enabled maintenance and energy optimization services.
Smart hinge and drawer systems with embedded sensor arrays are modularizing cabinet functionality into upgradeable component tiers. High-rise residential developers in Singapore and Hong Kong are specifying these configurations as standard to differentiate premium units. The technology is modularizing traditional hardware margins into recurring sensor-subscription revenue streams.
China's GB standards for indoor air quality are tightening adhesive emission thresholds for kitchen installations in new construction. Manufacturers are accelerating water-based resin adoption to preempt compliance deadlines. Commercial hospitality segments in Shanghai and Beijing are retrofitting existing stock to meet anticipated enforcement waves.
Developer procurement teams are consolidating vendor relationships around full-kitchen system integrators capable of appliance-cabinet-hardware bundling. Traditional component distributors in Indian metropolitan markets are losing share to direct manufacturer-developer contracting. This concentration is most visible in Mumbai and Delhi NCR luxury residential towers where single-source accountability reduces project risk.
Asia-Pacific Modular Kitchen Market Segmentation
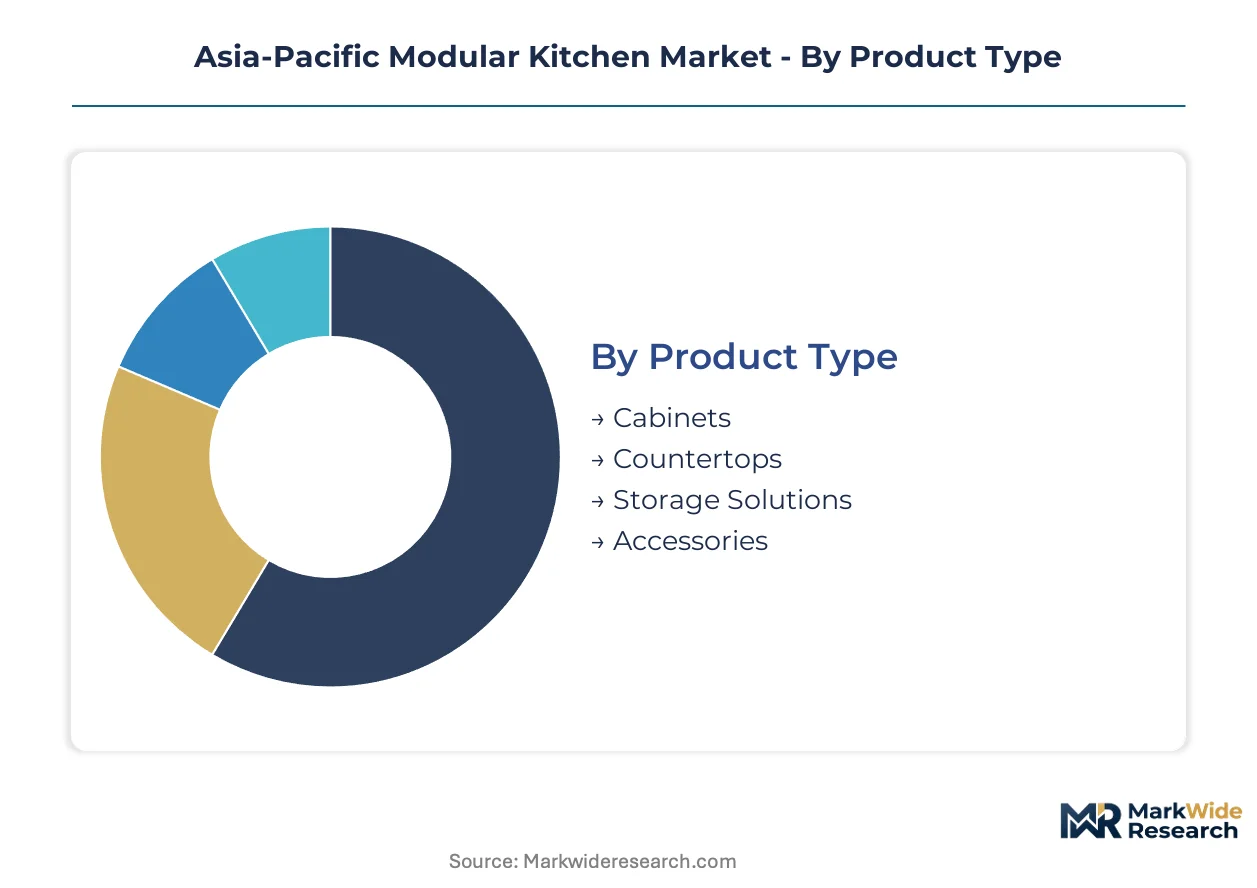
Modular kitchen procurement decisions cascade through material specifications, installation complexity, and end-use compliance requirements. Segmentation clarity enables suppliers to align manufacturing investments with the highest-margin configuration clusters across tropical climate zones and urban density gradients.
Product Type:
Capital intensity peaks in cabinet carcass manufacturing due to CNC routing infrastructure and moisture-resistant substrate processing requirements.
- Cabinets:Engineered from moisture-resistant particleboard with PVC edge banding and 0.8–1.0 mm laminate surfacing to withstand thermal cycling. Demand concentrates in Indian tier-two cities including Pune and Ahmedabad where apartment completions outpace metro saturation. BIS certification mandates for formaldehyde-free substrates extend product development cycles.
- Countertops:Fabricated from engineered stone, quartz composites, or high-pressure laminates requiring precision cutting equipment and templating software. Installation in Southeast Asian high-rise developments demands just-in-time site delivery synchronization with compressed construction timelines.
- Storage Solutions:Pull-out organizers and corner units command premium positioning in Singapore and Hong Kong luxury residential towers.
- Accessories:Hardware components including handles, lighting strips, and organizational inserts sourced from regional OEM supply chains.
Most installed capacity flows through Cabinets. Expansion is steepest in Storage Solutions.
Material:
Raw material sourcing geography determines supply security and emission compliance burden across the region.
- Wood:Plantation timber from captive processing operations in specific Indian and Southeast Asian states supplies engineered substrates. India's BIS standards constrain adhesive formulations toward low-VOC resins.
- Laminate:High-pressure decorative surfaces dominate residential volume due to cost-performance ratio and tropical humidity resistance. China's GB standards for indoor air quality are tightening emission thresholds for new construction installations.
- Stainless Steel:Nickel and chromium input price volatility compresses margins for commercial hospitality suppliers facing fixed-price sanitation-mandated contracts.
- Glass:Tempered and back-painted panels serve premium aesthetic specifications in metropolitan luxury developments.
Wood and laminate sustain volume leadership. Stainless steel is gaining share fastest in commercial segments.
End User:
Compliance stringency and contract structure vary sharply across installation environments.
- Residential:Standardized configurations serve mass apartment deployments across Indian tier-two cities and Vietnamese secondary markets. Developer procurement consolidation favors full-kitchen system integrators over component distributors.
- Commercial:Corporate cafeteria and food-service installations require durability specifications and rapid replacement part availability.
- Hospitality:Sanitation codes in Shanghai and Beijing mandate non-porous stainless steel surfaces with retrofit demand accelerating ahead of anticipated enforcement waves.
- Retail:Display kitchen environments in appliance showrooms and home centers drive visual-impact specifications with shorter replacement cycles.
Residential captures the largest installation base. Hospitality exhibits the steepest specification upgrade trajectory.
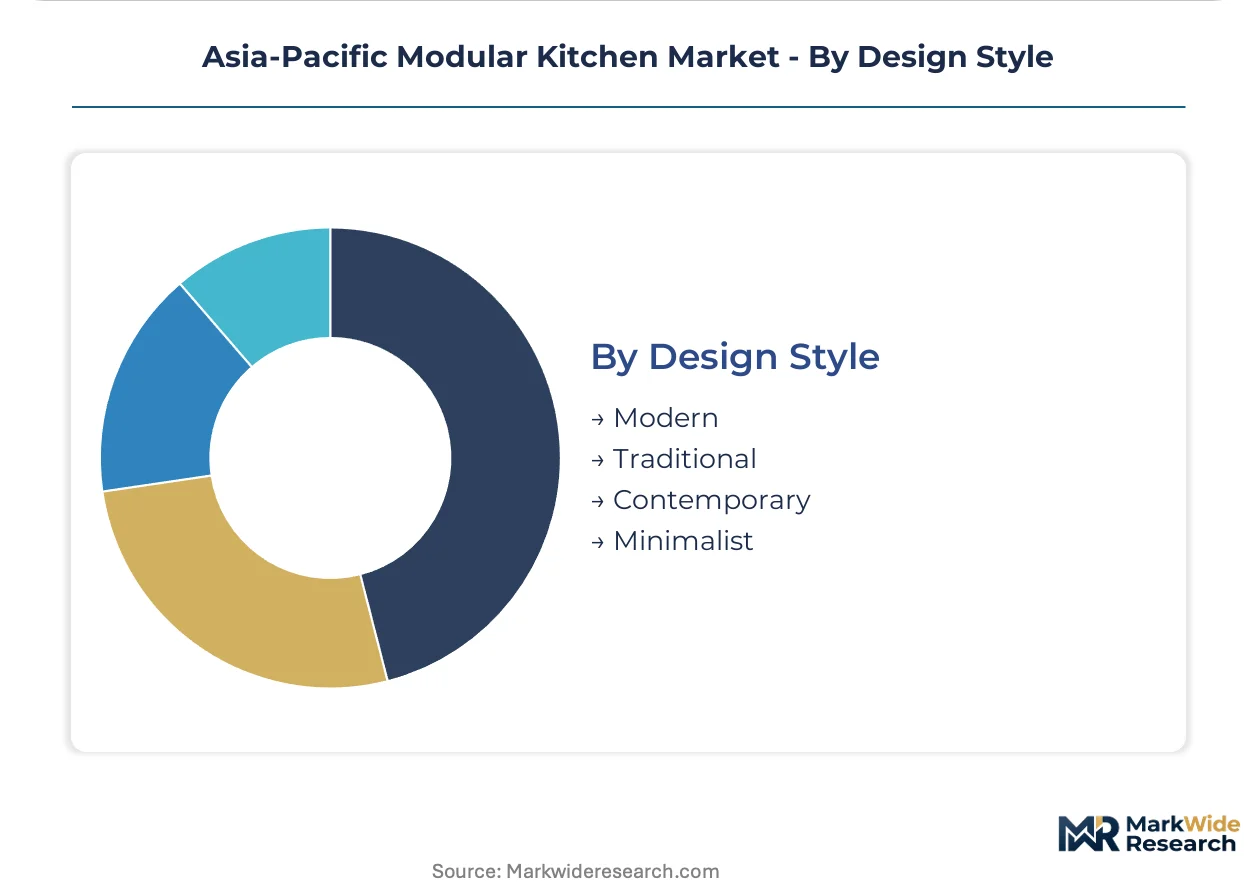
Design Style:
Aesthetic positioning correlates with appliance bundling strategies and developer premium-tier pricing.
- Modern:Clean lines and integrated handle-less systems align with METI energy-efficiency labeling requirements for built-in appliance certification in Japan.
- Traditional:Ornate detailing and wood-grain prominence serve heritage-conscious segments in Indian metropolitan markets.
- Contemporary:Transitional aesthetics bridge mass-market acceptance and premium positioning across Southeast Asian developments.
- Minimalist:Concealed storage and monochromatic palettes differentiate premium units in Singapore and Hong Kong high-rise towers.
Modern styling dominates current procurement specifications. Minimalist configurations are climbing fastest in luxury segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modular kitchen manufacturing first achieved industrial scale in Japan during the 1960s post-war housing boom, with standardized unit bath and kitchen systems pioneered by construction conglomerates. This prefabrication lineage diffused through South Korea and Taiwan before reaching Southeast Asian and South Asian markets in the 1990s.
India
Tier-two cities including Pune and Ahmedabad are generating concentrated demand clusters as apartment completions outpace metro saturation. BIS certification mandates for furniture safety constrain adhesive formulations toward formaldehyde-free laminates and certified engineered wood substrates. Manufacturing bases in Gujarat and Maharashtra are reformulating resins to meet extended compliance timelines.
China
GB standards for indoor air quality are tightening emission thresholds for kitchen installations in Shanghai and Beijing new construction. Commercial hospitality segments in these cities are retrofitting existing stock ahead of anticipated enforcement waves. The Yangtze River Delta and Pearl River Delta retain concentration in engineered substrate processing and decorative laminate production.
Japan
METI energy-efficiency labeling for built-in appliances shapes product bundling strategies favoring full-kitchen contractors. Kanto region developers specify smart hinge and drawer systems with embedded sensor arrays as standard in premium high-rise units. Osaka-based fabricators supply hardware-software convergent systems to regional OEMs.
Vietnam
Secondary cities including Da Nang and Can Tho present underpenetrated residential construction markets lacking established supplier networks. Prefabricated construction timelines are compressing from months to weeks, forcing synchronization of manufacturing with just-in-time site delivery. Ho Chi Minh City serves as the distribution hub for Mekong Delta expansion.
Australia
TGA-equivalent building product certification creates parallel compliance tracks for export-oriented suppliers targeting the market. Digital configuration platforms are displacing traditional distributor networks in Sydney and Melbourne project markets. Green building codes at city level specify low-VOC material thresholds beyond federal minimums.
Asia-Pacific Modular Kitchen Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification compliance and captive timber access. The vendor base organizes into three tiers: integrated appliance-cabinet bundlers commanding full-kitchen contracts, captive timber processors with backward integration into plantation forestry, and hardware technology specialists supplying hinge and drawer systems to regional OEMs. Consolidation pressure favors M&A among distributors losing share to direct manufacturer-developer contracting, alongside capacity expansion in moisture-resistant substrate processing.
Among India-based integrated manufacturers, IFB Industries Ltd. and Godrej & Boyce Mfg. Co. Ltd. occupy positions as appliance-cabinet bundlers, while Hettich Holding GmbH & Co. anchors the hardware technology specialist tier originating from German engineering lineage. These three exemplify the strategic archetypes reshaping procurement consolidation: full-system integrators capable of single-source accountability versus component specialists facing margin compression from direct contracting channels.
| Leading Market Players |
|---|
| IFB Industries Ltd. |
| Oppein Kitchen Cabinet |
| Godrej & Boyce Mfg. Co. Ltd. |
| Zuari Furniture |
| Spacewood |
| Sleek International Pvt. Ltd. |
| Hettich Holding GmbH & Co. |
| Kajiwara Inc |
| Hafele Gmbh & Co KG |
| Others |
Value Chain & Pricing Dynamics
Residential developer procurement consolidation in Indian metropolitan and tier-two markets anchors project-based contract pricing with volume-scaled discounts. Full-kitchen system integrators command premium positioning through single-source accountability, while component distributors face margin compression from direct manufacturer-developer contracting channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and after-sales bundling intensity. Price differentiation separates BIS-certified formaldehyde-free configurations from conventional laminate substrates, with METI-labeled appliance bundles commanding additional premiums. Cost compression in commercial hospitality stainless steel installations is intensifying because nickel and chromium input volatility compresses margins on fixed-price sanitation-mandated contracts. Mass-market residential developers in Pune and Ahmedabad exhibit highest price sensitivity, while Singapore luxury high-rise developers prioritize specification compliance over unit cost.
Supply Chain Analysis
Skilled installation technician scarcity in Gujarat and Maharashtra manufacturing belts constrains just-in-time delivery synchronization with compressed Southeast Asian construction timelines. Geographic supply concentration centers on plantation timber processing in specific Indian states, engineered substrate production in China's Yangtze River Delta, and hardware component fabrication in Japan's Kanto region. Raw material dependencies draw from certified engineered wood, moisture-resistant particleboard resins, and nickel-chromium alloy feedstocks. Single-source vulnerability in captive timber operations creates supply security exposure. Distribution runs through direct manufacturer-developer contracting channels displacing traditional distributor networks in Australian and Singaporean project markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where India's BIS formaldehyde emission caps and China's GB indoor air quality standards are accelerating material reformulation investments across manufacturing bases.
For Market Incumbents: Hedge against adhesive reformulation lag by accelerating water-based resin R&D ahead of compliance deadlines. Backward integration into plantation forestry in specific Indian and Southeast Asian states secures substrate supply against captive processing concentration. Defensive capacity expansion in moisture-resistant particleboard infrastructure captures tier-two city demand clusters before competitor positioning solidifies. For New Entrants and Emerging Players: Vietnamese and Indonesian secondary city residential developers represent the most penetrable buyer archetype lacking established supplier networks. First-mover positioning in Da Nang and Can Tho leverages compressed prefabricated construction timelines requiring just-in-time delivery partnerships. Digital configuration platforms enabling direct-to-developer sales displace traditional distributor relationships with lower customer acquisition cost. For Investors and Strategic Acquirers: Appliance-cabinet bundlers are the most active acquirer in this space, consolidating component distributors losing share to direct contracting channels. Acquisition targets with captive timber access and BIS-compliant substrate processing command valuation premiums. Watch for divergence between national certification regimes and city-level green building code consolidation as inflection indicator for compliance-cost trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Forestry | Captive timber supply secures BIS-compliant substrate sourcing against geographic concentration risk. |
| Water-Based Resin Reformulation | Accelerated R&D preempts India's BIS and China's GB standard compliance deadlines. |
| Digital Configuration Platform Deployment | Direct-to-developer channels displace distributor networks in Australian project markets. |
| Smart Hardware-System Integration | Sensor-embedded hinge arrays create recurring revenue streams in Singapore premium towers. |
| Just-in-Time Delivery Infrastructure | Synchronized manufacturing matches compressed Southeast Asian construction timelines. |
Study Parameters
Direct dialogue with residential development procurement heads, modular kitchen manufacturing plant managers, hardware technology R&D directors, and vocational training institute administrators grounded qualitative insights. Secondary validation drew from BIS certification registries, China's GB standard enforcement notices, Japan's METI labeling databases, and Australian TGA-equivalent building product certifications. Bottom-up demand modeling across product type, material, end user, and design style segments triangulated with top-down market sizing.
Segment-level value and volume trajectories across the projection horizon reflect installation base expansion in Indian tier-two cities, retrofit cycles in Shanghai and Beijing hospitality, and premium high-rise specifications in Singapore and Hong Kong. Modeled dimensions spanned cabinet carcass, countertop, storage solution, and accessory categories crossed with wood, laminate, stainless steel, and glass material tiers. CAGRs derived from historical completion data, appliance bundling penetration curves, and regulatory compliance cost pass-through assumptions.
Inputs from BIS certification timelines and GB standard enforcement schedules were available through the study window; gaps in city-level green building code adoption rates introduce uncertainty bands around low-VOC material demand forecasts. Material deviation in adhesive reformulation cost curves or plantation timber supply disruptions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Stove Cover Market
Kitchen and Dining
Range Hood and Cooktop Market
Kitchen and Dining
Sweden Household Electric Grills Market
Kitchen and Dining
Kitchen Sinks Market
Kitchen and Dining
Kitchen Faucets Market
Kitchen and Dining
Kuwait Kitchen Hoods Market
Kitchen and Dining
Kitchen Cabinets Market
Kitchen and Dining
Skillets and Frying Pans Market
Kitchen and Dining
Brightwood Tray Market
Kitchen and Dining
Hobs Market
Kitchen and Dining
Egypt Kitchen Hood Market
Kitchen and Dining
Banquet Carts and Heated Cabinets Market
Kitchen and Dining
Global Wooden Tableware Market
Kitchen and Dining
Bahrain Kitchen Hoods Market
Kitchen and Dining
Kitchen Furniture and Fixtures Market
Kitchen and Dining
Opalware Dinnerware and Crockery Market