
 Saudi Arabia Flexible Packaging Market | 2026-2036
Saudi Arabia Flexible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Flexible Packaging Market Analytics
Premium multilayer barrier films and commodity-grade polyethylene wraps is rebalancing as Saudi food brands demand longer shelf life without accepting imported European price levels. Gulf Packaging Industries Co. leverages domestic blown film capacity to anchor mid-tier supply for dairy and bakery clients. Napco National CJSC differentiates through in-house printing and lamination, controlling design-to-delivery cycles for personal care exporters. Flex Pack competes on volume turnaround for retail-ready pouches, occupying a niche in quick-service restaurant supply chains.
Flexible packaging denotes pliable material constructions—typically laminates of polyethylene, polypropylene, paper, or aluminum between 50 and 250 microns—engineered to protect contents from moisture, oxygen, and mechanical damage during distribution and display. The primary purpose centers on extending product integrity while minimizing material weight versus rigid alternatives. Bags and pouches lead volume throughput due to snack and grain filling lines across Saudi Arabia's food sector, though pharmaceutical-grade films command superior margin pools through barrier precision requirements. Polyethylene sustains raw material dominance by tonnage, yet aluminum-laminate demand accelerates in infant formula and sensitive pharmaceutical applications where oxygen transmission rates must fall below 0.1 cc per square meter daily.
SFDA and SASO standards govern food-contact safety and labeling legibility, compelling converters to validate migration limits and barcode print durability under Gulf climate conditions. MOHAP pharmaceutical packaging rules further restrict substrate composition for sterile and semi-permeable drug applications, creating a dual-track compliance burden. Stakeholders must monitor how Saudi Vision 2030 localization incentives reshape raw material sourcing rules and whether domestic resin expansion alters import dependency for polypropylene feedstock.
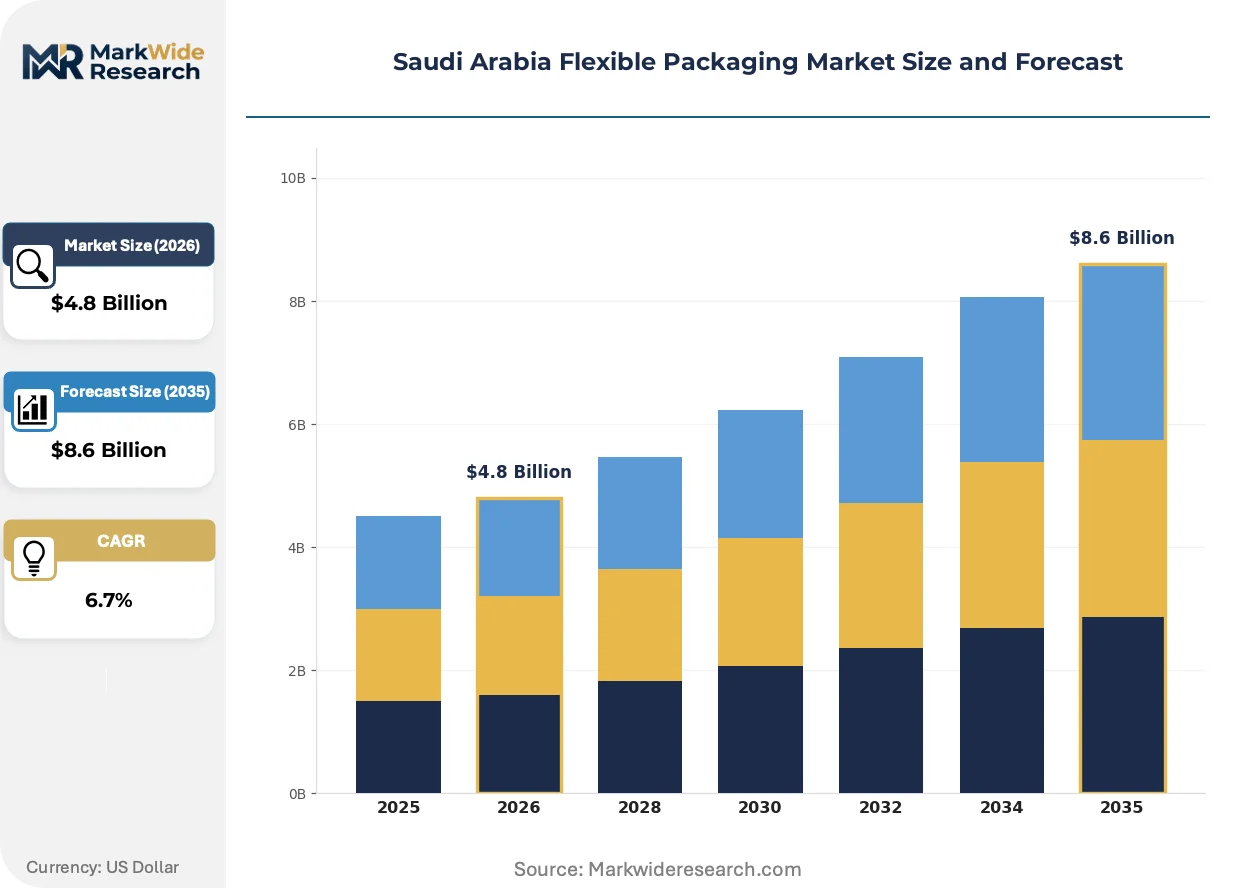
Market Dynamics
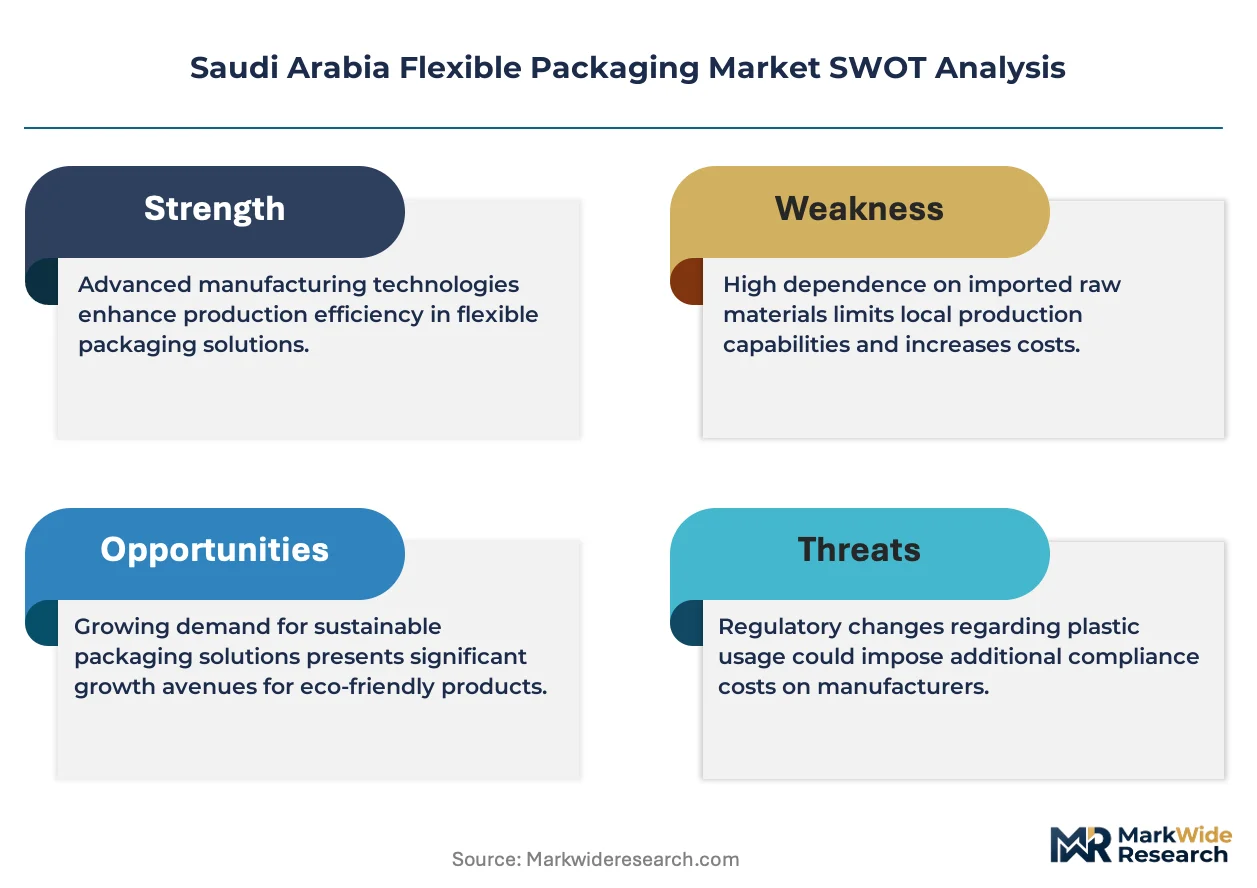
SFDA labeling mandates and MOHAP food-contact standards are compressing design-to-production timelines for Saudi converters while simultaneously raising the technical barrier for imported substrate suppliers. Domestic resin capacity expansion under Vision 2030 localization incentives is gradually altering polypropylene sourcing patterns, though import dependency persists for specialty grades.
Growth Catalysts
- High-barrier pouch demand:Shelf-stable dairy and snack segments are expanding orders for multilayer films that extend shelf life without refrigeration infrastructure. Food manufacturers across Riyadh's industrial corridor are retrofitting filling lines to accommodate stand-up pouch formats.
- SFDA compliance upgrades:Migration limit validations and barcode print durability requirements under Gulf climate conditions are forcing substrate standardization that favors established domestic converters with in-house testing laboratories.
- Pharmaceutical-grade film specifications:Infant formula and sensitive drug applications require oxygen transmission rates below 0.1 cc per square meter daily, creating premium margin pools for aluminum-laminate specialists serving MOHAP-regulated sterile packaging segments.
Market Restraints
- Polypropylene feedstock import concentration:Domestic resin expansion remains insufficient for specialty coextrusion grades, leaving converters exposed to GCC petrochemical pricing volatility and shipping delays through Jeddah's port corridors.
- European price level resistance:Saudi food brands demand barrier performance matching imported European films while rejecting corresponding cost structures, squeezing converter margins on multilayer constructions.
- Aluminum supply chain rigidity:Rolled foil for high-barrier laminates sources primarily from limited GCC smelter capacity, creating input bottlenecks when pharmaceutical demand surges.
Strategic Opportunities
- Western Province converter clustering:Jeddah's port-centric manufacturing zones offer underutilized industrial land for integrated film-to-pouch operations serving Red Sea export corridors.
- Recyclable mono-material constructions:Polyethylene-only pouches that satisfy SASO recyclability guidelines while maintaining barrier performance are capturing design wins from multinational FMCG brands with regional sustainability mandates.
- Digital printing integration:Hybrid flexo-inkjet systems enabling short-run customization for seasonal promotions and regulatory label variants are penetrating Riyadh-based personal care exporter supply chains.
Industry Challenges
- Migration testing capacity scarcity:SFDA food-contact validation protocols require specialized chromatography equipment and trained analytical chemists that remain concentrated in Riyadh and Dammam laboratory clusters.
- Lamination adhesive qualification timelines:MOHAP pharmaceutical packaging rules mandate extended stability testing for solvent-free and water-based adhesive systems, extending new product introduction cycles by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Flexible Packaging Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Pouches, Films, Labels Material: Polyethylene, Polypropylene, Paper, Aluminum Application: Food, Beverages, Personal Care, Pharmaceuticals End User: Manufacturers, Retailers, Distributors, E-commerce |
| Companies Covered | Gulf Packaging Industries Co., Flex Pack, Napco National CJSC, Gulf East Paper and Plastic Industries, Saudi Paper Manufacturing, Saudi Printing & Packaging Company, Printopack Co. Ltd., Integrated Plastics Packaging, Obeikan Flexible & Film Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Flexible Packaging Market Evolving Landscape
Digital workflow integration and sustainable material transitions are compressing traditional converter competitive advantages while opening technical differentiation pathways for mid-tier players with capital deployment discipline.
High-speed digital inkjet printing for flexible packaging is electrifying short-run production economics by eliminating plate costs and enabling same-day design revisions. Snack and confectionery brands in Riyadh's retail sector are adopting this technology for limited-edition promotional cycles. The elimination of cylinder engraving lead times is compressing competitive response windows for conventional gravure-dependent converters.
MOHAP pharmaceutical packaging rules are tightening substrate composition restrictions for sterile and semi-permeable drug applications, forcing converters to requalify existing laminate structures. The industrial consequence is accelerated migration toward certified clean-room production environments with documented batch traceability. Infant formula packaging lines in Jeddah's pharmaceutical manufacturing zones are most affected, with several facilities completing ISO 15378 certification upgrades.
Buyer consolidation among Saudi dairy processors is shifting procurement toward annual volume contracts with integrated design-to-delivery partners. The spot-market spot pouch purchasing that historically dominated mid-tier bakery supply chains is contracting. This pattern is most visible in the Central Region, where Almarai and Nadec procurement integration has reduced the active converter base serving UHT milk pouch segments.
Saudi Arabia Flexible Packaging Market Segmentation
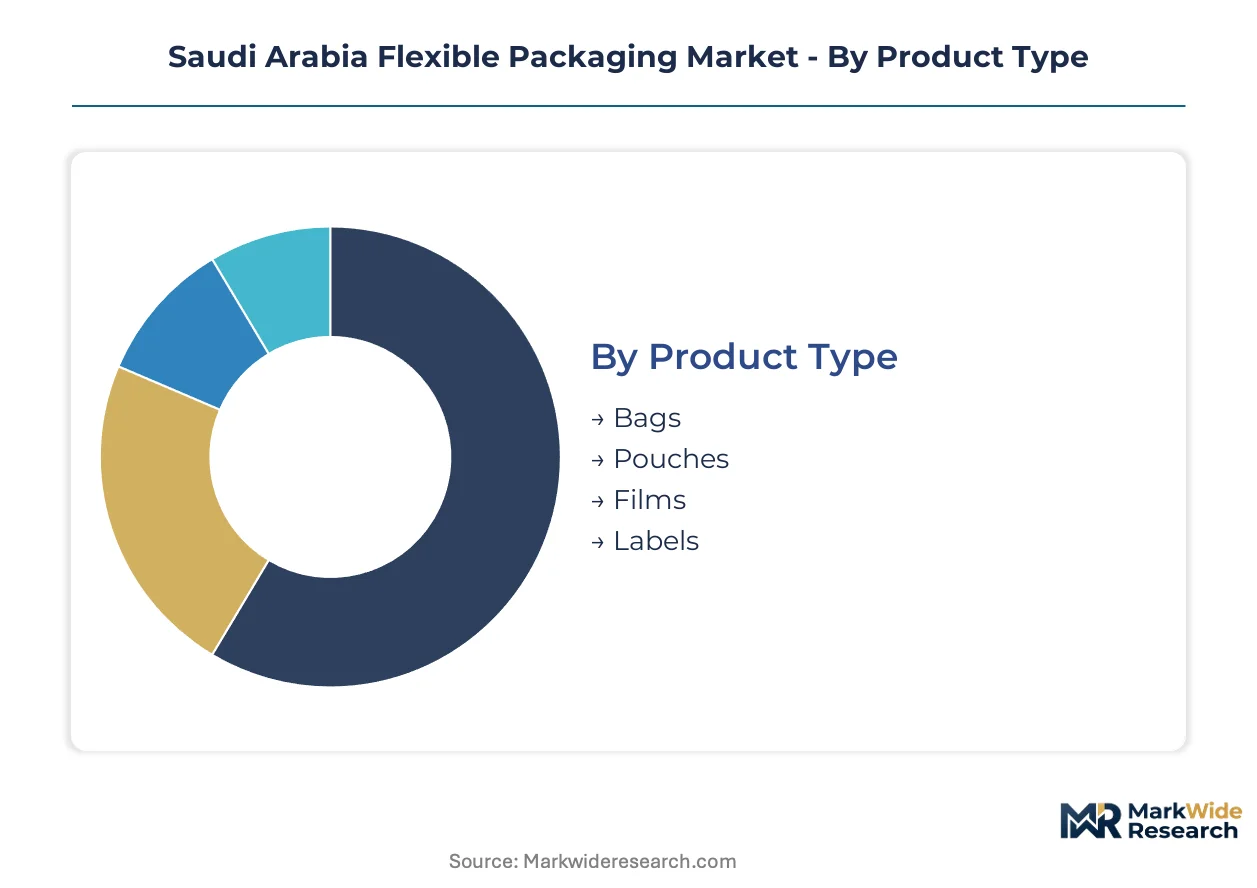
Saudi converters configure production lines around distinct performance tiers rather than universal specifications. Segmentation discipline separates commodity polyethylene wraps from pharmaceutical-grade barrier laminates with diverging margin profiles and qualification timelines.
Product Type:
Customization intensity varies sharply across this category, from standardized roll stock to engineered pouch geometries with integrated reseal features.
- Bags:Side-gusseted and wicketed configurations dominate grain and bakery filling lines across Riyadh's industrial corridor. Almarai procurement integration has shifted volume toward annual contracts with integrated suppliers capable of SFDA migration validation.
- Pouches:Stand-up and spouted formats with multilayer oxygen barriers are displacing rigid containers in shelf-stable dairy. Retrofitting costs for horizontal form-fill-seal lines concentrate demand among converters with captive blown film capacity.
- Films:Cast and oriented substrates serve lidding and overwrap applications with thinner gauge requirements.
- Labels:Pressure-sensitive and shrink-sleeve formats attach to rigid containers in beverage and personal care segments.
Most installed capacity flows through Bags. Expansion is steepest in Pouches.
Material:
Cost tier stratification mirrors feedstock sourcing patterns, from domestic polyethylene resin to import-dependent aluminum foil.
- Polyethylene:Blown and cast grades from SABIC and domestic petrochemical complexes anchor commodity production. Dairy and bakery segments absorb volume at price points European barrier films cannot match.
- Polypropylene:Biaxially oriented and cast films offer stiffness and clarity for snack lidding and confectionery overwrap. Specialty coextrusion grades remain import-dependent, exposing converters to GCC pricing volatility.
- Paper:Grease-resistant and kraft substrates serve quick-service restaurant packaging with SASO recyclability compliance.
- Aluminum:Rolled foil laminates achieve sub-0.1 cc oxygen transmission rates for infant formula and sterile pharmaceutical applications. GCC smelter capacity constraints create input bottlenecks when MOHAP-regulated demand surges.
Polyethylene commands the largest tonnage position. Aluminum-laminate applications are climbing the fastest.
Application:
Margin concentration aligns with regulatory stringency, from standardized food-contact migration limits to pharmaceutical clean-room certification.
- Food:Snack, grain, and UHT dairy segments drive volume through Riyadh and Jeddah converter clusters. High-barrier pouch adoption accelerates as brands extend shelf life without cold chain infrastructure.
- Beverages:Aseptic carton lidding and label substrates serve juice and dairy drink bottlers in Jeddah's port-centric zones.
- Personal Care:Printed laminates for shampoo and cosmetic sachets require gravure or digital workflow integration for design-to-delivery speed.
- Pharmaceuticals:Sterile and semi-permeable drug packaging operates under MOHAP substrate composition rules with extended adhesive qualification timelines. Infant formula applications command premium positioning through ISO 15378 certification requirements.
Food absorbs the majority of converter throughput. Pharmaceuticals deliver the steepest margin expansion trajectory.
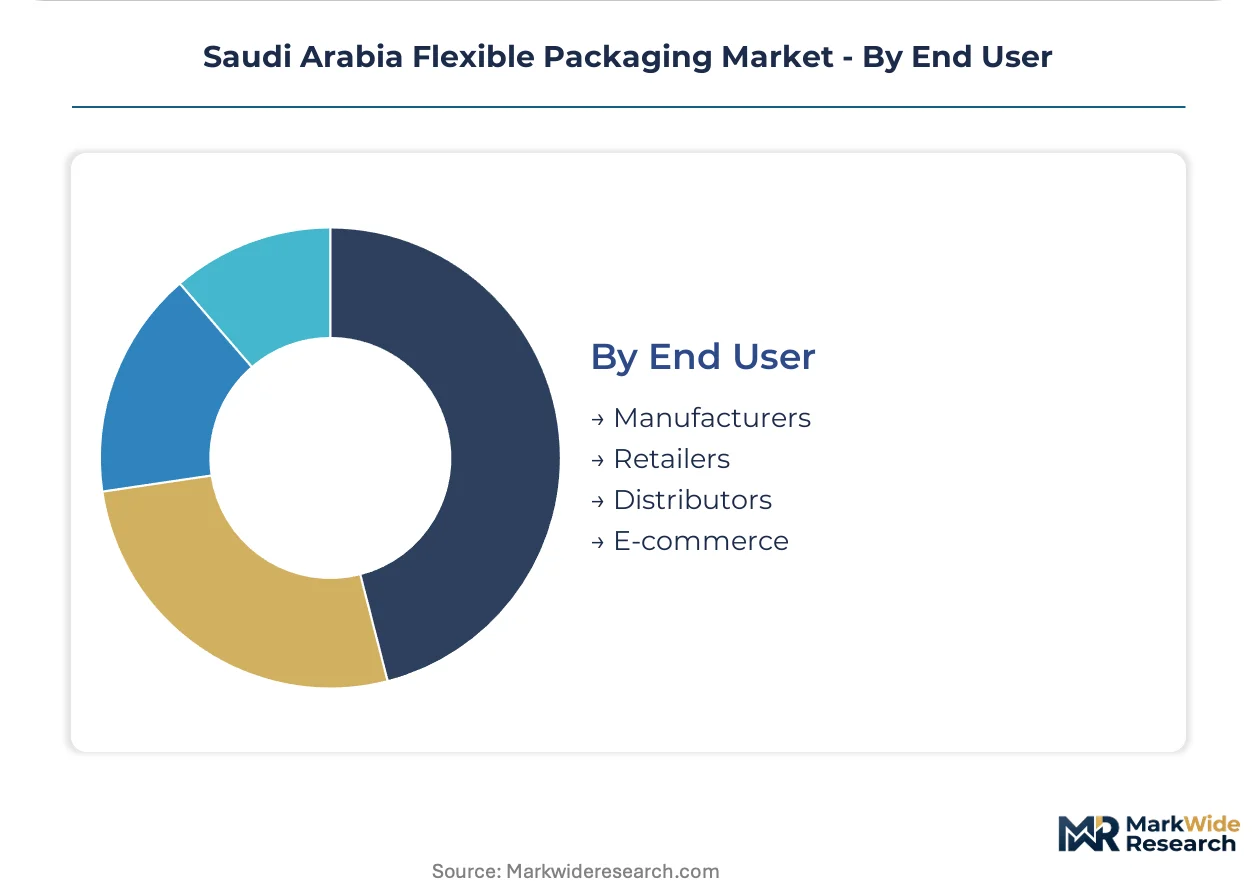
End User:
Procurement pattern differentiation separates integrated design-to-delivery partnerships from spot-market spot purchasing.
- Manufacturers:Dairy processors and pharmaceutical firms specify barrier performance and batch traceability with direct converter relationships. Annual volume contracts are displacing transactional purchasing in consolidated buyer segments.
- Retailers:Private-label programs for hypermarket chains require short-run flexibility and seasonal promotional versioning.
- Distributors:Inventory-carrying intermediaries serve fragmented bakery and confectionery accounts with standardized pouch formats.
- E-commerce:Protective mailer and void-fill demand from logistics platforms introduces cushioning and puncture-resistance specifications distinct from retail-display priorities.
Manufacturers direct the largest contract value. E-commerce channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized converter talent clusters around Riyadh's industrial corridor and Jeddah's port zones, anchoring domestic capacity for high-barrier laminates and food-grade pouch production.
Riyadh
UHT dairy and shelf-stable snack manufacturers drive multilayer pouch demand across the Central Region. SFDA migration testing protocols require converters to maintain in-house chromatography laboratories for food-contact validation. The Riyadh industrial corridor concentrates blown film extrusion and form-fill-seal line retrofitting activity as Almarai and Nadec consolidate procurement.
Eastern Province
Petrochemical feedstock proximity attracts polyethylene resin processing and cast film operations serving regional dairy processors. SABIC's domestic resin supply anchors commodity-grade production at price points below European imports. Dammam's laboratory clusters host specialized analytical chemists supporting SFDA compliance documentation for cross-regional shipments.
Western Region
Jeddah's port-centric manufacturing zones enable integrated film-to-pouch operations with Red Sea export access. Pharmaceutical-grade aluminum-laminate demand concentrates here for infant formula packaging requiring MOHAP sterile certification. Underutilized industrial land supports converter clustering for quick-service restaurant supply chains.
NEOM Northwest
Saudi Vision 2030 localization incentives are redirecting packaging investment toward this greenfield development zone. Recyclable mono-material construction pilots target SASO sustainability guidelines for multinational FMCG brands. Emerging converter capacity focuses on digital printing integration for short-run promotional versioning.
Saudi Arabia Flexible Packaging Market Competitive Landscape
Top-tier vendors anchor integrated design-to-delivery partnerships, while mid-tier converters compete on volume turnaround and spot-market responsiveness. The vendor base separates between blown film specialists with captive resin supply and laminators controlling printing workflows. Three archetypes dominate: petrochemical-integrated extruders, full-service design-to-delivery partners, and niche pharmaceutical-grade barrier specialists. Capacity expansion and digital printing technology licensing represent the dominant competitive moves reshaping positioning.
Within the integrated extrusion tier, Gulf Packaging Industries Co. exemplifies domestic blown film capacity anchoring mid-tier dairy and bakery supply. Napco National CJSC represents the design-to-delivery archetype through in-house printing and lamination control. Flex Pack occupies the volume-turnover position for retail-ready pouch production serving quick-service restaurant chains.
| Leading Market Players |
|---|
| Gulf Packaging Industries Co. |
| Flex Pack |
| Napco National CJSC |
| Gulf East Paper and Plastic Industries |
| Saudi Paper Manufacturing |
| Saudi Printing & Packaging Company |
| Printopack Co. Ltd. |
| Integrated Plastics Packaging |
| Obeikan Flexible & Film Co. Ltd. |
| Others |
Value Network & Pricing Analysis
Barrier-performance certification tiers separate pharmaceutical-grade aluminum laminates from commodity polyethylene wraps, and this stratification manifests in divergent supply chain configurations across Riyadh's industrial corridor and Jeddah's port zones. SFDA migration validation requirements concentrate premium pricing power with domestic converters possessing in-house chromatography laboratories, while spot-market polyethylene sourcing dominates bakery and grain segments where barrier specifications remain standardized.
Pricing Analysis
Bundled design-to-delivery contracts command premiums over unbundled roll-stock transactions, particularly among consolidated dairy processors seeking annual volume commitments with integrated partners. Price differentiation hinges on SFDA compliance certification tier and captive blown film capacity, with converters lacking in-house testing facilities absorbing margin compression. Cost compression in multilayer pouch segments is intensifying as Saudi food brands demand European barrier performance without accepting corresponding price levels. Quick-service restaurant supply chains exhibit highest price sensitivity, while pharmaceutical manufacturers prioritize oxygen transmission rate guarantees over unit cost.
Supply Chain Analysis
Workforce availability for specialized analytical chemists concentrates in Riyadh and Dammam laboratory clusters, constraining SFDA validation capacity expansion to these geographies. Raw material sourcing draws from domestic SABIC polyethylene resin, GCC aluminum smelter output, and import-dependent specialty polypropylene coextrusion grades. Single-source vulnerability runs through Jeddah's port corridors for European barrier film substrates. Distribution runs through integrated converter partnerships with direct manufacturer relationships, displacing inventory-carrying distributors in consolidated buyer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Saudi Arabia Flexible Packaging Market functions as a regulatory compounder where SFDA labeling mandates and MOHAP pharmaceutical packaging rules continuously escalate compliance barriers, converting regulatory adherence into sustainable competitive differentiation for prepared converters.
For Market Incumbents: Cement dominance in UHT dairy pouch segments by securing annual volume contracts with Almarai and Nadec procurement integration, while investing in ISO 15378 clean-room certification to capture infant formula barrier laminate demand. Threat of digital printing disruption from hybrid flexo-inkjet specialists demands preemptive technology licensing to defend design-to-delivery speed advantages. Backward integration into captive blown film capacity remains the critical lever for margin defense against European price-level resistance. For New Entrants and Emerging Players: E-commerce protective mailer channels offer the most penetrable entry vector, with logistics platforms introducing cushioning and puncture-resistance specifications distinct from established retail-display priorities. NEOM Northwest greenfield zones provide underutilized industrial land for recyclable mono-material construction pilots targeting SASO sustainability guidelines. A direct go-to-market angle through seasonal promotional versioning for personal care exporters exploits incumbent gravure-dependent converters' cylinder engraving lead time disadvantages. For Investors and Strategic Acquirers: Consolidation pressure builds where migration testing capacity scarcity concentrates validation power in Riyadh and Dammam laboratory clusters. Long-term viability favors vertically integrated converters with captive resin supply and in-house printing workflows over pure-play laminators exposed to feedstock volatility. Acquisition targets should display dual-track SFDA and MOHAP compliance capabilities. The signal to watch is domestic polypropylene specialty grade capacity expansion under Vision 2030 localization incentives, which would reshape import dependency economics.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Printing Technology Licensing | Hybrid flexo-inkjet systems compress design-to-delivery cycles for Riyadh personal care exporters. |
| ISO 15378 Clean-Room Certification | Pharmaceutical-grade barrier laminates for Jeddah infant formula lines command premium positioning. |
| Backward Integration into Blown Film | Captive polyethylene extrusion insulates margins from GCC petrochemical pricing volatility. |
| Recyclable Mono-Material Construction | Polyethylene-only pouches capture multinational FMCG sustainability mandates under SASO guidelines. |
| Western Province Converter Clustering | Jeddah port-centric integration serves Red Sea export corridors with underutilized industrial land. |
Research Methodology
Bottom-up food and pharmaceutical application modeling reconciled against top-down converter capacity tracking forms the analytical core of this study. Primary interviews with blown film extrusion plant managers, SFDA regulatory affairs leads, dairy procurement directors, pharmaceutical packaging engineers, and quick-service restaurant supply chain heads combined with secondary validation from SASO technical regulations, SFDA food-contact guidelines, MOHAP pharmaceutical packaging directives, SABIC resin supply disclosures, and customs import data for specialty polypropylene grades.
Historical trendline analysis of pouch adoption rates and barrier film qualification timelines informed projection framework construction across the analysis window. Segmentation dimensions modeled include product type, material grade tier, application regulatory stringency, and end-user procurement pattern. CAGRs were derived from converter capacity expansion announcements, filling line retrofitting activity, and buyer consolidation patterns. Industry-specific forecast inputs incorporated Vision 2030 localization incentive implementation pace and domestic resin capacity buildout schedules.
The model assumes a particular technology adoption path; alternative pathways for digital inkjet printing penetration would alter the outlook for conventional gravure-dependent converters. Forecasts reflect assumptions regarding SFDA enforcement consistency, GCC aluminum smelter capacity stability, and Red Sea shipping corridor reliability. Practitioners should monitor domestic specialty polypropylene commissioning announcements, MOHAP adhesive qualification timeline revisions, and multinational FMCG sustainability mandate regionalization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Nigeria Flexible Packaging Market
Flexible Packaging
Thailand Flexible Packaging Market
Flexible Packaging
Flexible Lid Stock Packaging Market
Flexible Packaging
Morocco Flexible Plastic Packaging Market
Flexible Packaging
Flex Pack Coatings Market
Flexible Packaging
Flexible Intermediate Bulk Container Market
Flexible Packaging
Latin America Flexible Packaging Market
Flexible Packaging
UAE Flexible Packaging Market
Flexible Packaging
France Flexible Plastic Packaging Market
Flexible Packaging
Benelux Flexible Plastic Packaging Market
Flexible Packaging
Flexible Containers Market
Flexible Packaging
Saudi Arabia Flexible Plastic Packaging Market
Flexible Packaging
Middle East and Africa Flexible Plastic Packaging Market
Flexible Packaging
Argentina Flexible Plastic Packaging Market
Flexible Packaging
United Arab Emirates Flexible Plastic Packaging Market
Flexible Packaging
Nigeria Flexible Plastic Packaging Market