
 Flexible Paper for Food & Beverages Packaging Market | 2026-2036
Flexible Paper for Food & Beverages Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Paper for Food & Beverages Packaging Market Foresight
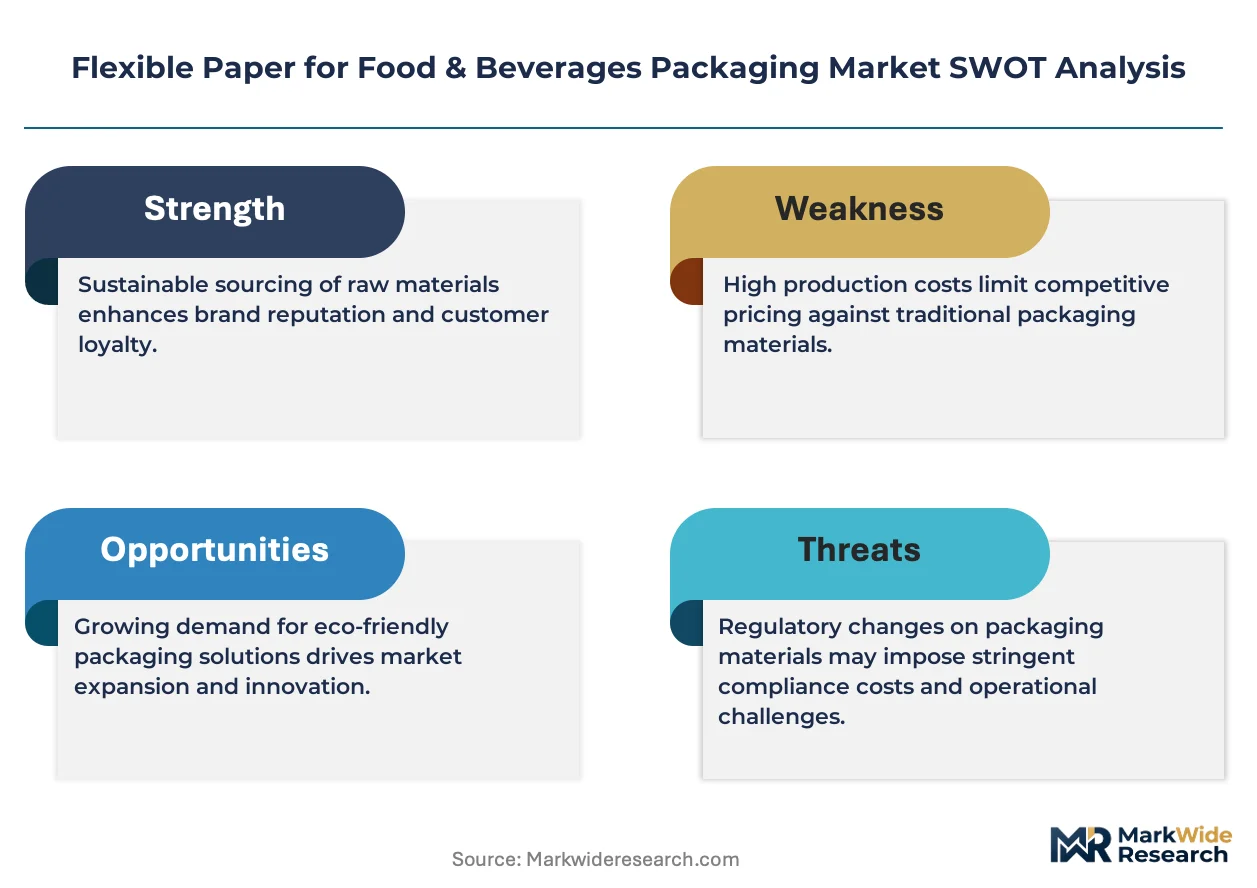
FSC chain-of-custody certification is bifurcating the competitive landscape into qualified suppliers and excluded producers. Mondi Group leverages integrated pulp-to-paper operations across European forestry assets to secure certified feedstock. WestRock Company anchors its position through containerboard and consumer packaging integration in North American mills. Smurfit Kappa Group competes via recycled fiber expertise and European corrugated network density.
Flexible paper for food and beverages packaging comprises kraft, sulfite, or glassine substrates treated with barrier coatings or laminates to resist moisture, grease, and oxygen transmission, typically ranging from 30 to 80 grams per square meter in basis weight. Its primary commercial purpose is to replace plastic films and rigid containers in primary and secondary food contact applications while maintaining shelf stability and printability. Coated paper and laminated paper command the largest volume positions due to established barrier performance in dairy and ready-to-eat meal segments, while greaseproof paper generates premium pricing in bakery applications where oil resistance differentiates performance. Pouches and wraps are gaining format share against bags as beverage producers and food manufacturers seek portion-control and resealability features.
FDA food contact substance notifications govern barrier coating approvals in the United States, while EU REACH and the Packaging and Packaging Waste Regulation set substance restrictions and extended producer responsibility thresholds across European markets. EFSA evaluations of mineral oil saturated hydrocarbons in recycled paperboard are reshaping migration limit discussions and coating reformulation priorities. Stakeholders must monitor how regulatory divergence between FDA notification pathways and EU hazard-based restrictions will fragment compliance costs and supplier qualification timelines.
Market Dynamics
FSC chain-of-custody certification is bifurcating supplier access as EU Packaging and Packaging Waste Regulation enforcement tightens material recovery mandates for single-use food contact applications.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility thresholds are mandating certified compostable substrates across German retail and food service supply chains.
- Barrier coating chemistry advances:Water-based and bio-derived moisture barriers are achieving oxygen transmission rates comparable to conventional polyethylene laminates in dairy applications.
- Bakery chain expansion:North American and European artisan bread and pastry segments are consolidating paper-based primary packaging specifications.
Market Restraints
- Pulp feedstock volatility:Nordic softwood supply concentration exposes coated paper producers to periodic fiber cost spikes and freight arbitrage pressures.
- Mineral oil migration limits:EFSA evaluations of saturated hydrocarbons in recycled fiber are constraining post-consumer content ratios in food-contact grades.
- Plastic film residual competitiveness:Polypropylene and polyethylene laminates retain cost advantages in high-moisture frozen food segments where paper barrier performance degrades.
Strategic Opportunities
- India food service penetration:Quick-service restaurant chains and organized retail in Maharashtra and Karnataka are piloting certified compostable wraps for ready-to-eat meals.
- Digital printing convergence:Hybrid flexo-inkjet systems are enabling short-run variable graphics on greaseproof substrates for craft beverage micro-lots.
- Reuse-system integration:Returnable container schemes in French and Dutch retail are creating demand for durable paper-based outer sleeves with multi-trip barrier integrity.
Industry Challenges
- FSC certification timeline compression:Chain-of-custody audits and documentation requirements are extending supplier qualification cycles by four to six months.
- Coating equipment retrofit costs:Converting solvent-based lamination lines to aqueous or extrusion coating systems demands capital outlays that mid-scale converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Paper for Food & Beverages Packaging Market |
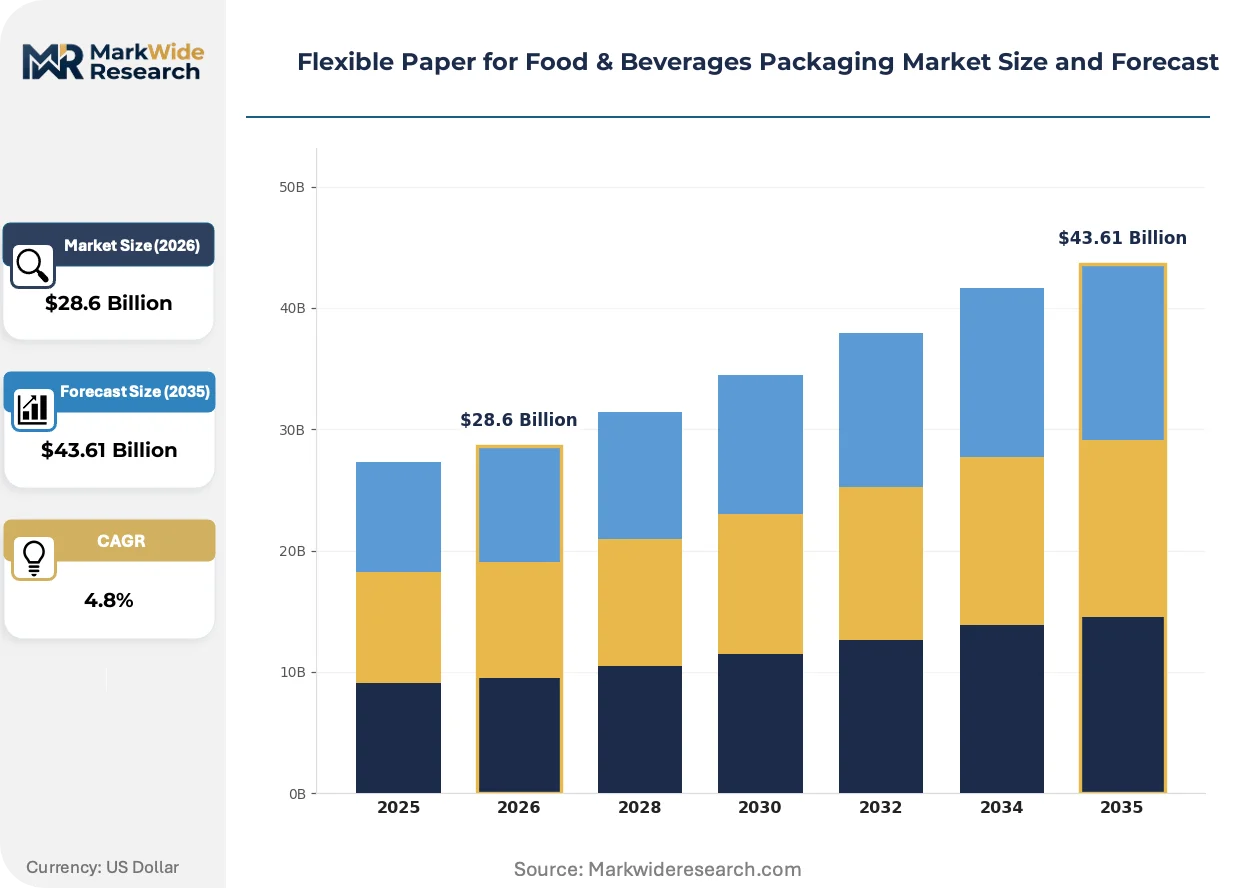
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Paper, Laminated Paper, Printed Paper, Waxed Paper, Greaseproof Paper Packaging Format: Bags, Pouches, Wraps, Trays, Sleeves Application Segment: Bakery, Confectionery, Dairy, Ready-to-Eat Meals, Beverages End User Category: Food Manufacturers, Beverage Producers, Catering Services, Retail Chains, Food Service Providers |
| Companies Covered | International Paper Company, Mondi Group, WestRock Company, Smurfit Kappa Group, Amcor Plc, Sonoco Products Company, DS Smith, Stora Enso Oyj, Nippon Paper Industries Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Paper for Food & Beverages Packaging Market Shifts & Advancements
Active coating reformulation and substrate lightweighting are compressing material intensity per package while regulatory migration limits are forcing chemistry suppliers to validate novel barrier polymers.
Cellulose nanofiber-reinforced coatings are supplanting conventional polyethylene extrusion layers in premium bakery and confectionery wraps. French and Italian artisan chocolate producers are specifying these substrates for direct oil-contact applications. The technology is compressing plastic content thresholds in EU circular economy reporting metrics.
REACH substance restrictions and EFSA migration limit proposals are forcing coating suppliers to retire mineral oil-based additives and accelerate bio-based polymer validation. German dairy processors are reformulating lidding specifications preemptively. The regulatory friction is advantaging integrated pulp-to-paper operators with captive R&D capacity over merchant coating houses.
Consolidated procurement by retail private-label managers is compressing supplier rosters and extending contract durations. Discounters in Germany and Benelux are mandating three-year supply agreements with volume guarantees. The pattern concentrates volume with FSC-certified integrated producers and marginalizes non-certified regional converters.
Flexible Paper for Food & Beverages Packaging Market Segmentation
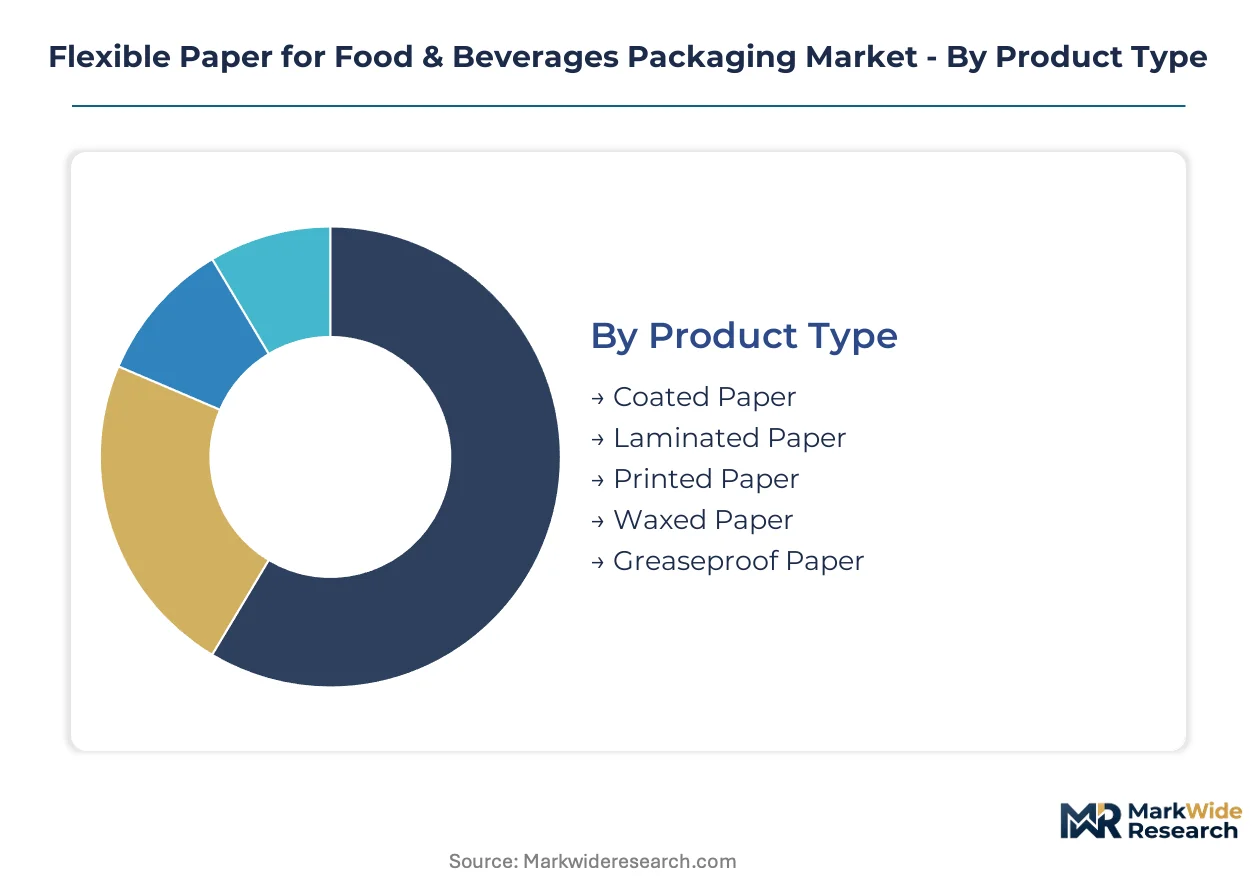
Flexible paper packaging segments diverge sharply on barrier performance requirements and regulatory compliance intensity. Coated and laminated substrates face distinct FDA notification pathways versus EU REACH substance restrictions, while format selection hinges on moisture sensitivity and shelf-life targets.
Product Type:
REACH substance restrictions and FDA food contact notifications create divergent qualification burdens across barrier technologies.
- Coated Paper:Water-based acrylic or bio-derived barrier layers applied to kraft substrates achieve oxygen transmission rates matching polyethylene laminates in dairy lidding applications. German dairy processors are consolidating procurement around these specifications to preempt EFSA migration limit revisions.
- Laminated Paper:Extrusion-bonded polyethylene or aluminum oxide layers deliver the highest moisture resistance for frozen food segments. Nordic softwood fiber supply concentration exposes producers to periodic cost volatility and freight arbitrage pressures.
- Printed Paper:Flexographic or gravure ink systems on greaseproof substrates serve craft beverage micro-lots with short-run variable graphics.
- Waxed Paper:Paraffin or vegetable-based wax coatings retain niche positions in artisan cheese and charcuterie wrapping where moisture breathability controls ripening.
- Greaseproof Paper:Dense sulfite or glassine structures provide direct oil-contact performance for premium confectionery and fried food applications.
Coated paper handles the majority of throughput; laminated paper is the fastest mover on share.
Packaging Format:
Format selection tracks directly to portion-control needs and resealability requirements in food service and retail channels.
- Pouches:Stand-up and flat pouch configurations with zipper or spout closures are displacing rigid containers in ready-to-eat meal and beverage segments. Quick-service restaurant chains in Maharashtra and Karnataka are piloting certified compostable pouch formats for grab-and-go applications.
- Wraps:Single-sheet greaseproof or waxed substrates dominate artisan bakery and confectionery presentation where direct food contact and printability converge. French and Italian chocolate producers specify cellulose nanofiber-reinforced wraps for oil resistance.
- Bags:Side-gusseted and pinch-bottom constructions retain volume in bulk dry goods and coffee segments where barrier demands are moderate.
- Trays:Molded pulp or paperboard tray formats with flexible paper liners serve prepared meal and produce applications requiring structural rigidity.
- Sleeves:Band or full-enclosure sleeves provide secondary branding and tamper evidence for beverage bottles and confectionery multipacks.
Pouches command the largest volume position; wraps are expanding most quickly in premium segments.
Application Segment:
Moisture sensitivity and fat content dictate barrier specification intensity across food categories.
- Dairy:Yogurt lids, butter wraps, and cheese papers require oxygen and moisture barriers to prevent rancidity and mold. Water-based coating advances are displacing conventional laminates as German retailers mandate compostable certifications.
- Ready-to-Eat Meals:Microwaveable and ambient-stable meal pouches demand multi-layer barrier performance with seal integrity. Organized retail consolidation in Benelux discounters is extending contract durations and compressing supplier rosters.
- Bakery:Bread bags, pastry wraps, and cake boards balance moisture retention with mold prevention. North American artisan chain expansion is standardizing paper-based primary packaging specifications.
- Confectionery:Chocolate and candy wraps require fat resistance and aroma barrier properties. Cellulose nanofiber coatings are supplanting mineral oil-based additives under REACH pressure.
- Beverages:Bottle labels, carrier sleeves, and straw wraps prioritize wet strength and printability over oxygen barrier.
Dairy absorbs the highest coating technology investment; ready-to-eat meals are gaining share fastest on format conversion.
End User Category:
Procurement scale and certification requirements stratify supplier access across customer types.
- Retail Chains:Private-label managers in Germany and Benelux are mandating three-year supply agreements with FSC chain-of-custody guarantees and volume commitments.
- Food Manufacturers:Branded packaged food producers specify custom barrier formulations with documented migration testing for export compliance.
- Food Service Providers:Contract caterers and institutional kitchens prioritize cost efficiency and operational consistency over premium barrier performance.
- Beverage Producers:Craft and mainstream beverage companies leverage digital printing for seasonal and regional label variations.
- Catering Services:Event and corporate catering operators source standardized wraps and trays through group purchasing organizations.
Retail chains concentrate the highest contract values; food service providers are expanding most quickly on away-from-home consumption trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extended producer responsibility mandates and compostable certification requirements are restructuring procurement patterns across major flexible paper packaging markets. National regulations diverge sharply on migration limits and chain-of-custody documentation, creating compliance complexity for multinational suppliers.
Germany
Retail chains and food service operators are consolidating supplier contracts around certified compostable flexible paper solutions. The EU Packaging and Packaging Waste Regulation tightens material recovery targets for single-use food contact materials, forcing coating reformulation timelines. Manufacturing concentration in North Rhine-Westphalia supports rapid specification changes for dairy and ready-to-eat meal segments.
United States
Bakery chains across metropolitan markets are expanding paper-based packaging specifications for artisan breads and pastries. FDA food contact substance notifications govern barrier coating approvals, creating distinct qualification pathways from European standards. Containerboard integration in southeastern mill complexes anchors domestic supply security for consumer packaging converters.
France
Artisan chocolate producers are specifying cellulose nanofiber-reinforced substrates for direct oil-contact applications. REACH substance restrictions accelerate retirement of mineral oil-based additives in coating formulations. Returnable container schemes in Paris and Lyon retail corridors generate demand for durable paper-based outer sleeves with multi-trip barrier integrity.
India
Quick-service restaurant chains and organized retail in Maharashtra and Karnataka are piloting certified compostable wraps for ready-to-eat meals. FSSAI food safety standards and state-level plastic bans create regulatory momentum for paper alternatives. Mumbai and Bangalore urban clusters concentrate pilot deployment capacity for grab-and-go pouch formats.
Italy
Premium confectionery producers drive specification intensity for greaseproof substrates with aroma barrier performance. EFSA evaluations of mineral oil saturated hydrocarbons reshape migration limit discussions for recycled fiber content. Emilia-Romagna packaging districts specialize in short-run variable graphics for craft beverage micro-lots using hybrid flexo-inkjet systems.
Flexible Paper for Food & Beverages Packaging Market Competitive Landscape
Player mix skews toward integrated pulp-to-paper operators with captive forestry assets and merchant converters dependent on spot fiber markets. Market structure concentrates volume with FSC-certified producers holding chain-of-custody documentation, while mid-scale regional converters face exclusion from retail procurement rosters. Two strategic archetypes dominate: backward-integrated forestry operators controlling feedstock quality, and specialized coating houses with formulation agility for barrier chemistry advances. Competitive moves center on certification acquisition timelines and aqueous coating line retrofits to displace solvent-based lamination systems.
Within the integrated forestry tier, Mondi Group and Stora Enso Oyj represent archetypes of European operators with captive pulp supply and certified chain-of-custody coverage. WestRock Company occupies a position among North American containerboard-integrated producers with consumer packaging mill networks. These three entities exemplify how geographic asset positioning and certification status determine supplier qualification access under tightening EU enforcement.
| Leading Market Players |
|---|
| International Paper Company |
| Mondi Group |
| WestRock Company |
| Smurfit Kappa Group |
| Amcor Plc |
| Sonoco Products Company |
| DS Smith |
| Stora Enso Oyj |
| Nippon Paper Industries Co., Ltd. |
| Others |
Supply & Pricing Matrix
Water-based barrier coatings displacing polyethylene extrusion layers are redrawing feedstock procurement geographies and compressing margin structures across converter tiers. The substitution shifts cost anchors from petrochemical indices toward Nordic softwood fiber markets and aqueous chemistry supply chains.
Pricing Analysis
Certification grade creates the primary spread between qualified suppliers and excluded producers. Three-tier pricing structure across FSC-certified premium, standard chain-of-custody, and uncertified economy levels stratifies contract values. Cost compression in standard tiers is intensifying because coating equipment retrofits demand capital outlays mid-scale converters struggle to finance. Retail chains in Germany exhibit the lowest price sensitivity due to volume guarantees and extended contract durations, while food service providers in emerging markets remain highly price-sensitive.
Supply Chain Analysis
Inventory cycles for barrier-coated substrates extend lead times by four to six months during FSC audit windows. Manufacturing concentrates in Germany, Finland, and Sweden where integrated pulp-to-paper operators control captive forestry assets. Raw material dependencies center on Nordic softwood pulp, water-based acrylic resins, and bio-derived barrier polymers. Single-source vulnerability runs through concentrated softwood fiber supply in the Baltic region. Distribution runs through consolidated retail procurement rosters and food service group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation mandates a high-growth disruption as extended producer responsibility thresholds force certified compostable substrate adoption across European supply chains.
For Market Incumbents: Compound certification advantages by accelerating aqueous coating line retrofits ahead of REACH substance restriction deadlines. Backward integration into captive pulp supply secures feedstock quality against Nordic softwood volatility. Defend procurement access by extending FSC chain-of-custody coverage to marginalize non-certified regional converters from retail rosters. For New Entrants and Emerging Players: Anchor in Maharashtra and Karnataka food service corridors where quick-service restaurant chains pilot certified compostable wraps with limited incumbent penetration. Target ready-to-eat meal pouch formats for grab-and-go applications. Pursue hybrid flexo-inkjet digital printing capabilities to serve craft beverage micro-lots with short-run variable graphics. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed merchant coating houses lacking integrated forestry positions. Five-to-ten year viability hinges on aqueous chemistry R&D capacity and certification documentation infrastructure. Acquisition targets should demonstrate documented barrier polymer validation for EU migration limit compliance. Monitor EFSA mineral oil saturated hydrocarbon evaluations as the critical inflection signal for recycled fiber content viability.| Strategic Initiative | Industry Significance |
|---|---|
| FSC Chain-of-Custody Certification | Qualification access for EU retail procurement rosters tightens supplier pools. |
| Aqueous Coating Line Retrofit | REACH substance restrictions accelerate retirement of solvent-based lamination systems. |
| Cellulose Nanofiber Coating Development | French and Italian chocolate producers specify substrates for direct oil-contact applications. |
| Digital Printing Convergence | Hybrid flexo-inkjet systems enable short-run variable graphics for craft beverage micro-lots. |
| Reuse-System Integration | French and Dutch returnable container schemes create demand for durable multi-trip barrier sleeves. |
Research Methodology
A spread of perspectives from packaging procurement managers, coating R&D directors, FSC certification auditors, and retail private-label directors converged on the working assumptions. Primary fieldwork with paper mill operations heads and barrier chemistry suppliers combined with secondary validation from EU regulatory filings, EFSA scientific opinions, customs trade data, and SEC packaging sector disclosures. Bottom-up volume modeling and top-down value triangulation anchored the analytical framework.
Segmentation dimensions modeled include barrier technology type, packaging format, application segment, and end-user procurement scale across the projection horizon. CAGRs derived from historical trajectory analysis and substitution elasticity parameters for plastic-to-paper conversion. Forecast inputs incorporated EFSA migration limit revision timelines and EU Packaging and Packaging Waste Regulation enforcement intensity.
Decision-makers should treat outputs as directional under base assumptions of sustained EU regulatory enforcement and stable Nordic softwood fiber supply; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Thermoform Packaging Market
Flexible Packaging
Vietnam Flexible Plastic Packaging Market
Flexible Packaging
Spain Flexible Plastic Packaging Market
Flexible Packaging
Bakery Flexible Packaging Market
Flexible Packaging
Thailand Flexible Packaging Market
Flexible Packaging
Flexible Food Packaging Market
Flexible Packaging
Flexible Lid Stock Packaging Market
Flexible Packaging
Flexible Detergent Packaging Market
Flexible Packaging
Canada Multilayer Flexible Packaging Market
Flexible Packaging
Global Flexible Packaging Market
Flexible Packaging
Global Breathable Films Market
Flexible Packaging
Litho Laminated Packaging Market
Flexible Packaging
Germany Flexible Plastic Packaging Market
Flexible Packaging
India Flexible Packaging Market
Flexible Packaging
Metalized Flexible Packaging Market
Flexible Packaging
Flexible Intermediate Bulk Container Market