
 Asia-Pacific Video Game Software Market | 2026-2036
Asia-Pacific Video Game Software Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Video Game Software Market Insights
Buyer concentration across Asia-Pacific mobile platforms is recalibrating as casual gamers fragment into micro-communities while professional esports organizations consolidate purchasing power for team licenses and training software. Tencent Holdings leverages its super-app distribution to control mobile game discovery across China. Sony Interactive Entertainment anchors premium console experiences through exclusive first-party studio output. Nintendo sustains family-oriented hardware-software integration that resists pure digital commoditization.
Asia-Pacific video game software comprises executable code, digital assets, and networked services designed for interactive entertainment across computing devices, with development cycles spanning 24 to 48 months for AAA titles integrating real-time rendering engines and live-service architectures. Mobile games command the largest addressable base through free-to-play monetization, while cloud gaming represents the fastest-expanding infrastructure category as 5G latency thresholds enable streaming parity with local processing. Console games retain concentrated margin pools in Japan and Australia where hardware attachment rates exceed regional averages.
China's SAMR and MIIT coordinate content approval timelines and youth play-time restrictions that reshape product roadmaps and monetization mechanics for domestic and foreign publishers alike. South Korea's GRAC rating system and Japan's CERO framework establish age-gate standards that influence localization investments and regional release sequencing. Stakeholders must monitor how India's emerging digital personal data protection obligations and Australia's eSafety Commissioner mandates will alter user data practices and in-game advertising models across divergent compliance environments.
Market Dynamics
China's MIIT license approval system compresses product launch windows and forces publishers to maintain parallel development tracks for domestic and international builds, fundamentally restructuring how software pipelines allocate engineering resources across the Asia-Pacific region.
Growth Catalysts
- 5G Infrastructure Deployment:South Korea's nationwide low-latency networks enable cloud gaming services to achieve streaming parity with local console processing, expanding addressable audiences beyond hardware ownership constraints.
- GRAC Rating Harmonization:South Korea's streamlined age classification system reduces localization friction for foreign publishers seeking simultaneous regional releases across PC bang venues and mobile platforms.
- Mobile Esports Formalization:Tournament organizers in Vietnam and the Philippines are constructing dedicated training facilities that professionalize player development and drive demand for team management software.
Market Restraints
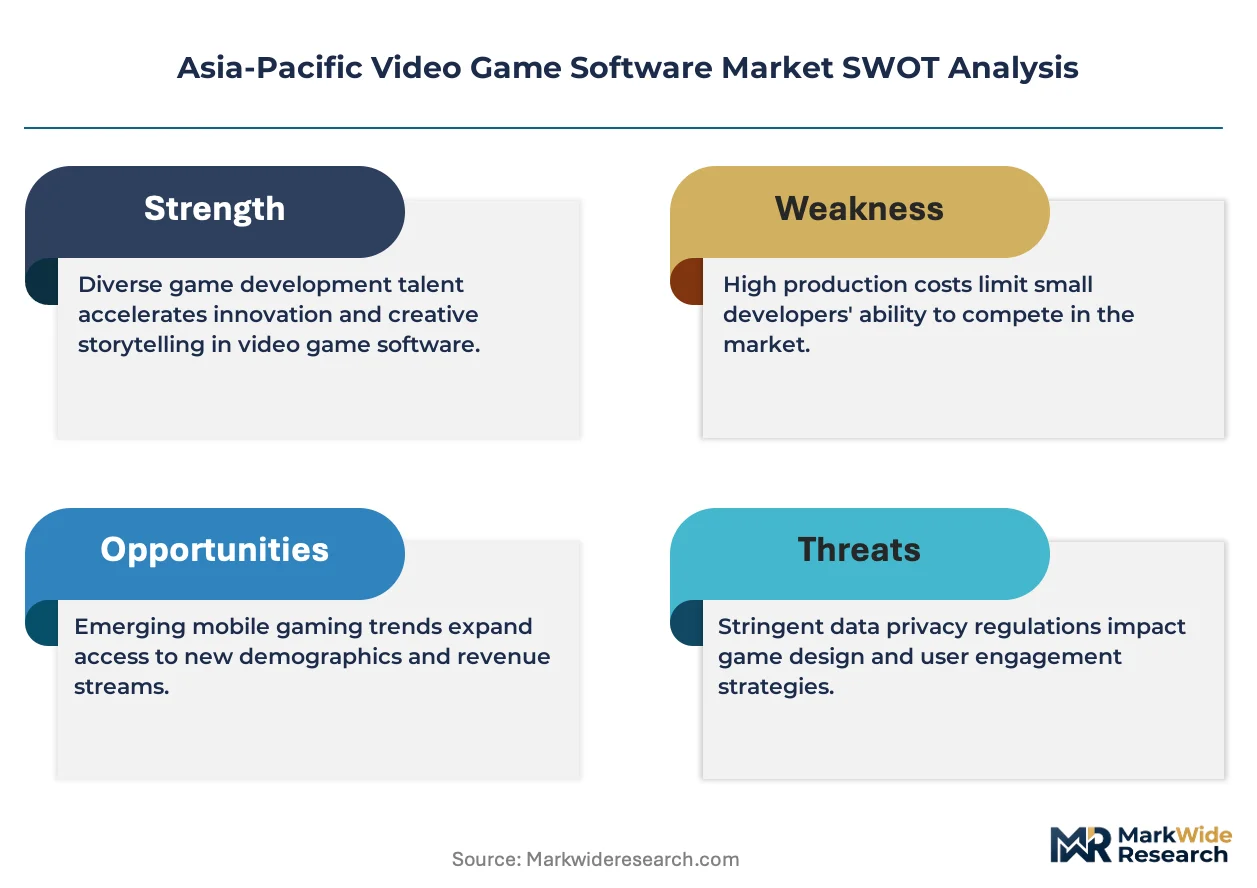
- Input Cost Volatility:Talent acquisition costs for live-service engineers and anti-cheat specialists have escalated sharply across Shenzhen, Seoul, and Tokyo development clusters.
- Regulatory Friction:SAMR youth play-time restrictions mandate real-name verification systems that increase operational complexity and reduce session-based monetization elasticity for publishers operating in China.
- Technical Limitation:Persistent input lag thresholds above 40 milliseconds continue to disadvantage cloud gaming for competitive genres in markets with uneven 5G backhaul density.
Strategic Opportunities
- Underpenetrated Geography:Indonesia's archipelago-wide fiber expansion creates first-mover positioning for publishers establishing localized server infrastructure and Bahasa Indonesia content pipelines.
- Regulatory Tailwind:India's Production Linked Incentive scheme for electronics manufacturing incentivizes domestic game engine development and middleware tooling capacity.
- Distribution Innovation:Super-app ecosystems in Southeast Asia are integrating mini-game storefronts that bypass traditional platform fees and enable direct publisher-audience relationships.
Industry Challenges
- Live-Service Engineering Gap:Persistent shortages of backend infrastructure specialists capable of maintaining 99.99% uptime for multiplayer titles strain development timelines across Tokyo and Shanghai studios.
- Cross-Border Data Compliance:Divergent data localization requirements between China's PIPL, India's DPDP Act, and Australia's Privacy Act fragment user analytics architectures and increase legal review overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Video Game Software Market |
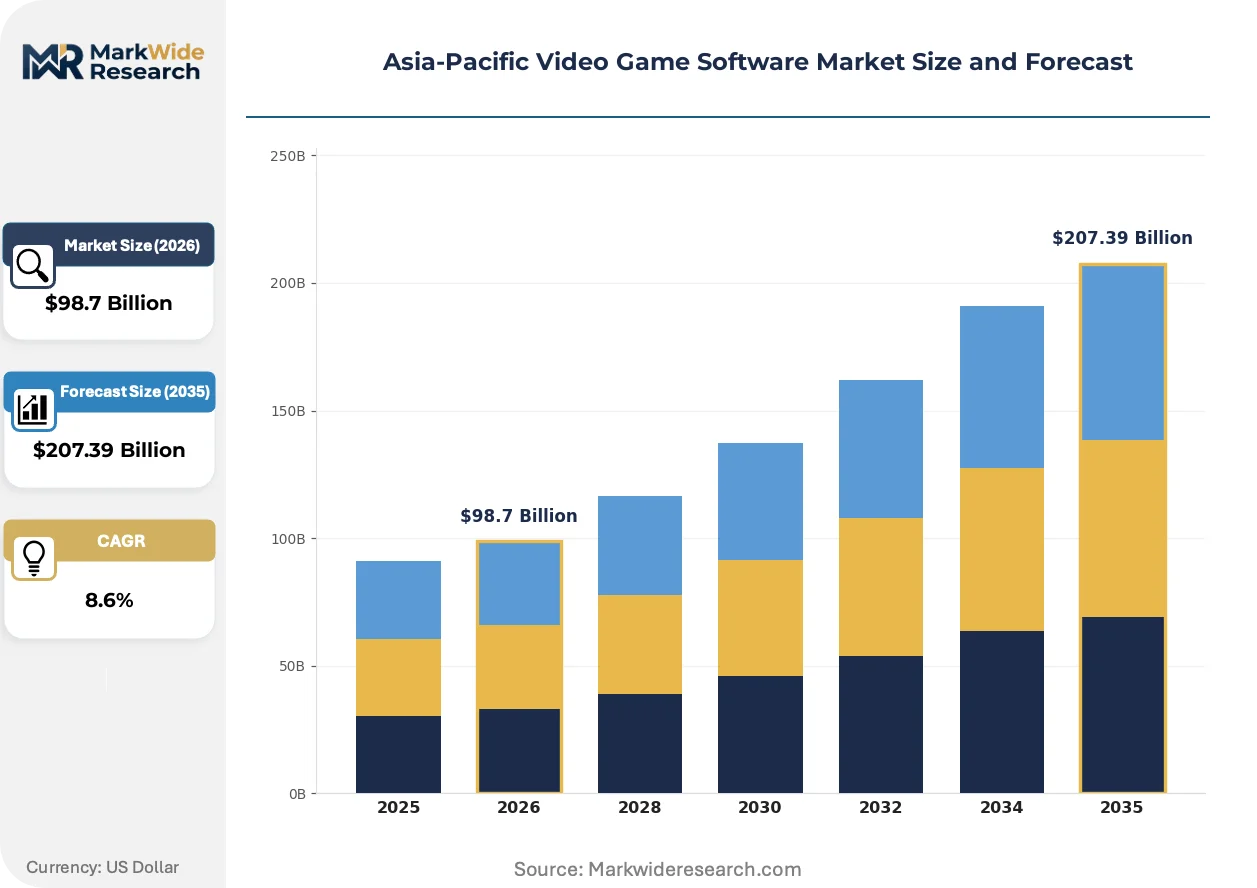
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $207.39 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Console Games, PC Games, Mobile Games, Cloud Gaming End User: Casual Gamers, Professional Gamers, Children, Adults Distribution Channel: Digital Downloads, Retail Stores, Subscription Services, In-Game Purchases Game Genre: Action, Adventure, Simulation, Role-Playing, Strategy |
| Companies Covered | Nintendo, Bandai Namco Entertainment, Tencent Holdings, Konami, Square Enix, NetEase, Nexon, Cygames, Sony Interactive Entertainment, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Video Game Software Market Trends and Innovations
Real-time rendering pipelines and AI-assisted content generation are compressing development cycles while simultaneously raising quality expectations, forcing Asia-Pacific studios to restructure asset production workflows and talent allocation models.
Procedural content generation is consolidating art pipeline efficiency for open-world titles. Mid-sized studios in Malaysia and Thailand are adopting machine learning-assisted texture and animation tools to compete with established AAA output volumes. This technology is consolidating competitive positioning by reducing per-asset labor hours without sacrificing visual fidelity targets.
Japan's CERO rating framework is expanding disclosure requirements for randomized reward mechanics. Publishers must now submit probability algorithms and spending ceiling documentation prior to commercial release. Mobile RPG developers targeting Japanese audiences are restructuring gacha systems to preempt compliance delays and maintain launch synchronization with other Asia-Pacific territories.
Subscription bundling is displacing individual title purchases among Australian and New Zealand console households. Platform holders are consolidating first-party catalogs with third-party day-one releases to justify recurring fees. This consumption-pattern shift pressures standalone premium pricing models and accelerates service-based revenue recognition timelines across the region's publishing sector.
Asia-Pacific Video Game Software Market Segmentation
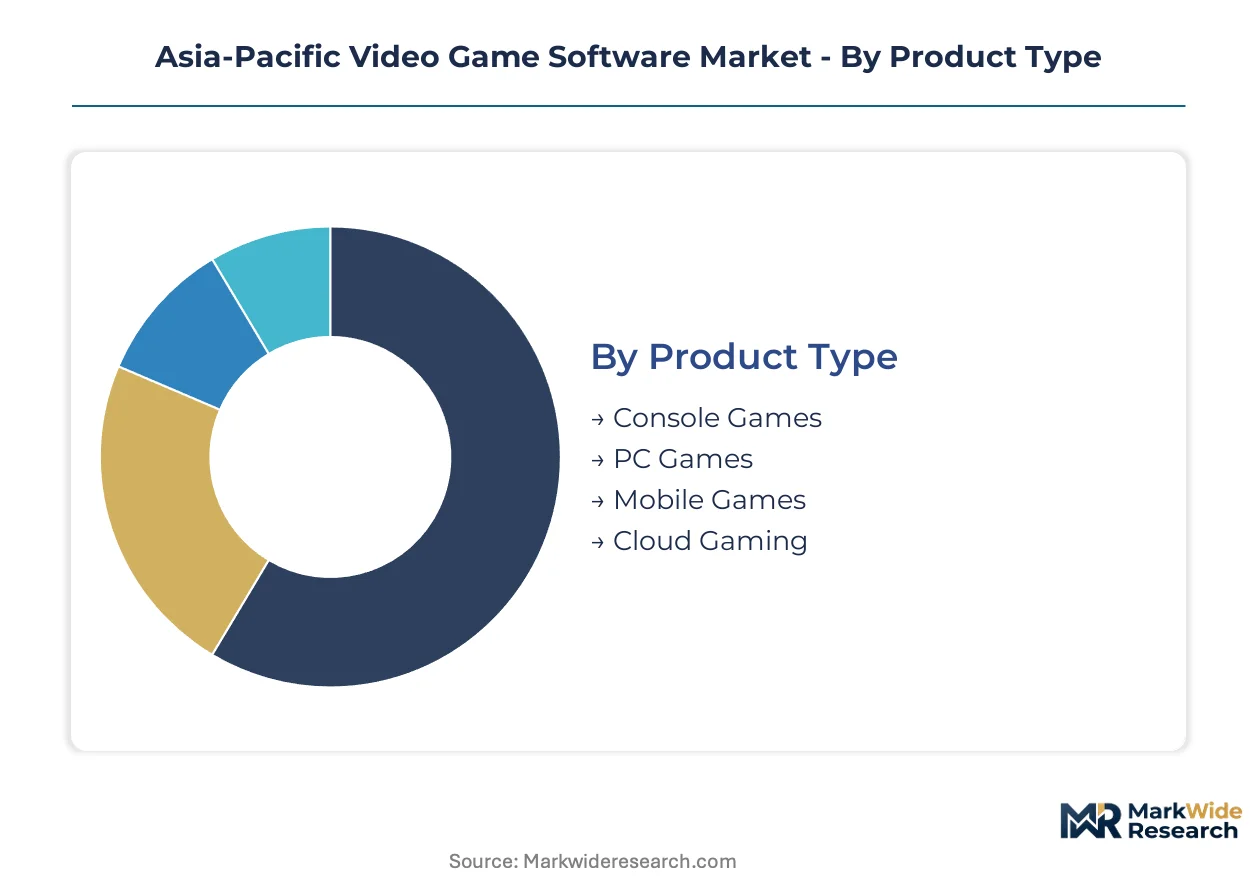
Segmentation reveals how capital allocation and technical infrastructure requirements diverge across the Asia-Pacific video game software landscape. Publishers must match development budgets and distribution architectures to distinct consumption patterns and regulatory constraints governing each category.
Product Type:
Capital intensity varies dramatically, with AAA console development demanding the largest upfront engineering investments while mobile and cloud formats reduce fixed costs through standardized platforms and streaming infrastructure.
- Console Games:Native executable software optimized for dedicated hardware architectures from Sony, Nintendo, and Microsoft. Development cycles span 36-48 months with teams exceeding 200 engineers. Japan and Australia concentrate demand where hardware attachment rates support premium pricing; CERO rating compliance adds localization overhead for Japanese market entry.
- Mobile Games:Touch-optimized applications distributed through iOS App Store and Google Play, monetized via free-to-play mechanics with in-app purchases. Vietnam and the Philippines are driving demand through esports tournament formalization; MIIT license requirements in China compress launch windows and force parallel domestic builds.
- PC Games:Software targeting Windows and macOS with variable hardware configurations, dominant in South Korea's PC bang culture. Steam and Epic Games Store distribution reduces physical retail dependency across the region.
- Cloud Gaming:Server-rendered titles streamed to thin clients, eliminating local processing requirements. South Korea's nationwide 5G deployment enables latency thresholds competitive with console performance; uneven backhaul density in Indonesia and the Philippines limits competitive genre viability.
Mobile Games absorb the bulk of installed capacity across the region's addressable device base; Cloud Gaming is expanding most quickly where fiber and 5G infrastructure investments mature.
End User:
Monetization mechanics and session design diverge sharply based on player skill investment, age-gating requirements, and disposable income concentration across demographic cohorts.
- Casual Gamers:Intermittent players seeking low-commitment entertainment across mobile and browser platforms. Southeast Asia's super-app ecosystems fragment this population into micro-communities accessed through mini-game storefronts.
- Professional Gamers:Organized competitors requiring team management software, training facilities, and anti-cheat infrastructure. Vietnam and the Philippines are constructing dedicated esports venues; talent acquisition costs for live-service engineers have escalated sharply in Shenzhen and Seoul.
- Children:Users subject to SAMR youth play-time restrictions in China and GRAC age-gate standards in South Korea. Real-name verification systems increase operational complexity and reduce session-based monetization elasticity for publishers.
- Adults:Core spending demographic with purchasing authority for premium titles and subscription services. Australia and New Zealand households are displacing individual purchases with bundled platform subscriptions.
Casual Gamers constitute the largest addressable population; Professional Gamers command the steepest expansion trajectory as tournament prize pools and sponsorship formalize.
Distribution Channel:
Channel selection determines revenue recognition timing, platform fee structures, and direct audience relationship depth across regulatory environments with divergent digital commerce rules.
- Digital Downloads:Direct software acquisition through platform storefronts with immediate delivery. Steam, PlayStation Store, and Nintendo eShop dominate; subscription bundling in Australia and New Zealand pressures standalone premium pricing.
- Retail Stores:Physical media distribution through electronics retailers and specialty chains. Japan sustains this channel through collector-oriented limited editions; shelf space contraction limits relevance elsewhere.
- Subscription Services:Recurring fee access to catalog libraries with day-one third-party releases. Platform holders consolidate first-party output to justify fees; this pattern accelerates service-based revenue recognition timelines.
- In-Game Purchases:Microtransactions for virtual goods, battle passes, and cosmetic items. Japan's CERO framework now mandates probability algorithm disclosure for randomized reward mechanics; gacha system restructuring precedes commercial release.
Digital Downloads retain the largest transaction volume; Subscription Services are climbing the fastest as platform holders compete for recurring revenue lock-in.
Game Genre:
Genre preferences correlate with platform hardware capabilities, session length tolerances, and cultural narrative conventions that vary across national markets.
- Action:Reflex-dependent gameplay emphasizing combat mechanics and visual spectacle. South Korea's PC bang culture concentrates competitive action title demand; live-service engineering gaps strain multiplayer uptime maintenance.
- Adventure:Narrative-driven exploration with puzzle-solving elements. Nintendo's first-party studio output anchors family-oriented hardware-software integration resistant to pure digital commoditization.
- Simulation:Systems modeling real-world activities from urban planning to vehicle operation. Mid-sized studios in Malaysia and Thailand adopt machine learning-assisted asset pipelines to compete with established output volumes.
- Role-Playing:Character progression systems with extended narrative arcs. Mobile RPG gacha monetization faces CERO probability disclosure requirements; developers submit spending ceiling documentation prior to Japanese launch.
- Strategy:Tactical decision-making with resource management and territorial control. Input lag thresholds above 40 milliseconds disadvantage cloud streaming for this genre in markets with uneven 5G density.
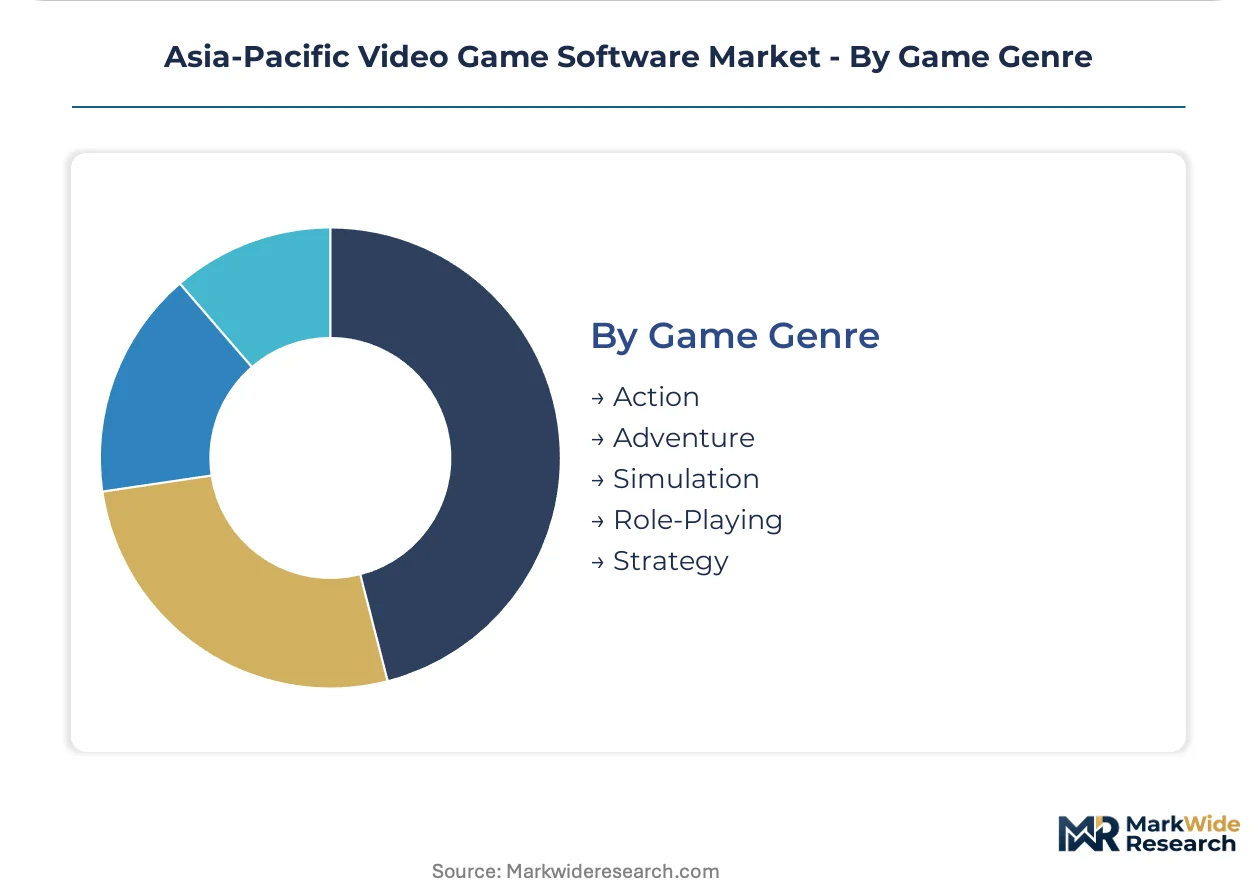
Action titles dominate development resource allocation; Role-Playing is gaining share fastest through mobile gacha monetization and cross-platform progression systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan and China concentrate the highest per-user spending on premium software licenses, while South Korea's PC bang infrastructure sustains distinct consumption patterns that diverge from mobile-first Southeast Asian markets.
China
MIIT license approval timelines compress product launch windows to unpredictable intervals, forcing publishers to maintain parallel domestic and international development tracks. SAMR youth play-time restrictions mandate real-name verification systems that reduce session-based monetization elasticity. Shenzhen development clusters absorb escalating talent acquisition costs for live-service engineers and anti-cheat specialists.
Japan
CERO rating framework mandates probability algorithm disclosure for randomized reward mechanics, compelling mobile RPG developers to submit spending ceiling documentation prior to commercial release. Nintendo's first-party studio output anchors family-oriented hardware-software integration resistant to pure digital commoditization. Tokyo studios face persistent shortages of backend infrastructure specialists capable of maintaining 99.99% uptime for multiplayer titles.
South Korea
GRAC streamlined age classification reduces localization friction for foreign publishers seeking simultaneous regional releases across PC bang venues and mobile platforms. Nationwide 5G deployment enables cloud gaming latency thresholds competitive with console performance. Seoul development clusters compete aggressively for live-service engineering talent against Chinese and Japanese counterparts.
Australia
Subscription bundling displaces individual title purchases among console households, with platform holders consolidating first-party catalogs with third-party day-one releases to justify recurring fees. eSafety Commissioner mandates alter user data practices and in-game advertising models. Sydney and Melbourne development studios benefit from proximity to Asian publishing headquarters while operating under distinct compliance frameworks.
Indonesia
Archipelago-wide fiber expansion creates first-mover positioning for publishers establishing localized server infrastructure and Bahasa Indonesia content pipelines. Super-app ecosystems integrate mini-game storefronts that bypass traditional platform fees and enable direct publisher-audience relationships. Jakarta development clusters remain nascent compared to regional counterparts, presenting talent acquisition arbitrage opportunities.
Asia-Pacific Video Game Software Market Competitive Landscape
Japanese producers anchor premium console and mobile RPG tiers; Chinese specialists hold dominant positions in free-to-play monetization and super-app distribution. Market structure consolidates around three strategic archetypes: vertically integrated hardware-software platforms, live-service specialists with proprietary engine capabilities, and mobile-first publishers leveraging social distribution networks. Dominant competitive moves include exclusive first-party content acquisition and geographic expansion through localized studio partnerships.
Within the hardware-software integration tier, Nintendo and Sony Interactive Entertainment exemplify vertically integrated platform control. Tencent Holdings occupies a position representing super-app distribution dominance across Chinese mobile ecosystems. These three entities anchor distinct competitive vectors—Nintendo through family-oriented hardware attachment, Sony through premium exclusive content, and Tencent through WeChat ecosystem lock-in—each resisting direct substitution by alternative business models.
| Leading Market Players |
|---|
| Nintendo |
| Bandai Namco Entertainment |
| Tencent Holdings |
| Konami |
| Square Enix |
| NetEase |
| Nexon |
| Cygames |
| Sony Interactive Entertainment |
| Others |
Pricing and Supply Chain Analysis
China's dual carbon goals gate both qualified supply and premium-tier pricing access, as studios achieving carbon-neutral data center certification command 15-25% licensing premiums while publishers relying on coal-powered server infrastructure face exclusion from government procurement channels and ESG-mandated institutional buyers across Japan and South Korea.
Pricing Analysis
Volume concentrates in free-to-play mobile downloads while margins pool in subscription services and AAA console releases. Three-tier pricing structure across premium, standard, and economy levels reflects CERO compliance investment, exclusive IP ownership, and live-service infrastructure scale. Price differentiation stems from real-name verification system integration costs and anti-cheat engine licensing tiers. Pricing pressure stems from talent acquisition cost inflation in Shenzhen and Seoul, compressing mid-tier studio margins. Casual mobile gamers exhibit highest price sensitivity, while professional esports organizations demonstrate lowest sensitivity due to sponsorship-backed procurement.
Supply Chain Analysis
Live-service engineering talent supply rests on development clusters in China, South Korea, and Japan, with specialized backend infrastructure expertise concentrating in Shenzhen and Tokyo. Critical inputs include Unreal Engine licensing, cloud compute capacity from Alibaba and Tencent, and motion-capture studio access in Kuala Lumpur and Bangkok. Single-source vulnerability runs through MIIT license approval timelines that compress launch windows unpredictably. Distribution runs through super-app ecosystems, platform storefronts, and direct-to-consumer channels with divergent fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race, with upstream engine technology control and downstream super-app distribution lock-in representing the decisive levers separating consolidators from commoditized publishers.
For Market Incumbents: Hedge against regulatory fragmentation by maintaining parallel development tracks for domestic Chinese and international builds, insulating release schedules from MIIT approval volatility. Secure captive supply of live-service engineering talent through studio acquisitions in Jakarta and Kuala Lumpur, arbitraging cost differentials against Shenzhen and Seoul clusters. Deepen backward integration into proprietary anti-cheat and analytics middleware to reduce third-party dependency.
For New Entrants and Emerging Players: Super-app distribution partnerships in Indonesia and Vietnam offer lowest-friction customer acquisition, bypassing platform fees that extract 30% of transaction value. White-space targets include Bahasa Indonesia localization pipelines and dedicated esports training facility software serving Philippines tournament organizers. Cloud gaming infrastructure gaps in archipelago markets present first-mover positioning before fiber backhaul density matures.
For Investors and Strategic Acquirers: GRAC rating harmonization announcements are the leading indicator that South Korean market entry friction is declining for foreign publishers, signaling expanded addressable revenue pools. Long-term viability favors studios with proprietary engine capabilities and live-service operational excellence over single-title developers. Acquisition target archetypes include mid-tier Malaysian and Thai studios adopting machine learning-assisted asset pipelines. Watch for CERO probability disclosure rule expansion as signal of Japanese regulatory tightening.
| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive First-Party Content Acquisition | Sony Interactive Entertainment's studio purchases secure PlayStation platform differentiation against Xbox Game Pass. |
| Super-App Mini-Game Integration | Tencent WeChat ecosystem lock-in enables direct publisher-audience relationships bypassing Apple App Store fees. |
| Live-Service Engine Proprietary Development | NetEase's in-house Messiah engine reduces Unreal licensing costs and accelerates mobile optimization cycles. |
| Localized Server Infrastructure Buildout | Nexon's Jakarta data center deployment cuts latency for Indonesian battle royale tournaments below 40 milliseconds. |
| Esports Training Facility Partnership | Cygames' collaboration with Philippines venue operators professionalizes player development and anchors team management software demand. |
Research Methodology
Document review covered SEC filings from Nintendo, Sony, and Tencent, Steam and App Annie platform data, MIIT license release schedules, and CERO rating disclosure documentation, complemented by interviews with live-service engineering directors, platform partnership leads, esports tournament organizers, and GRAC regulatory affairs specialists. Primary fieldwork validated secondary estimates through bottom-up title-level revenue modeling and top-down market sizing triangulation.
Output generation deployed segmented growth accounting across product type, end user, distribution channel, and game genre dimensions, with additional modeling of regulatory cluster impacts and infrastructure maturity tiers. CAGRs were derived from logistic adoption curve fitting and elasticity-adjusted spending projections. Key inputs included 5G deployment pace, youth play-time restriction enforcement intensity, and super-app penetration rates.
Several conditions sit outside the modeled scope, including unforeseen geopolitical disruptions to cross-border data flows, abrupt MIIT policy reversals on license issuance velocity, and generative AI capability jumps that compress asset production timelines beyond current adoption curves. Forecasts embed assumptions about continued 5G infrastructure investment and stable enforcement of existing rating frameworks. A small set of named triggers warrants ongoing watch: GRAC-CERO regulatory convergence, Indonesia fiber expansion completion, and cloud gaming latency threshold breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Singapore Gaming Gadgets Market
Gaming
SLG Game Market
Gaming
Australia Gaming Accessories Market
Gaming
VR Gaming Market
Gaming
Gaming Peripheral Market
Gaming
Southeast Asia Gaming Market
Gaming
Slot Machine Market
Gaming
Europe Video Game Software Market
Gaming
Connected Game Console Market
Gaming
Global Online Gambling and Betting Market
Gaming
United States Virtual Reality Gaming Market
Gaming
North America Gaming Hardware and Accessories Market
Gaming
Russia in-Game Advertising Market
Gaming
Middle East and Africa Gaming Headsets Market
Gaming
LAMEA in-Game Advertising Market
Gaming
Global Subscription-Based Gaming Market