
 Virtual Sports Market | 2026-2036
Virtual Sports Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Sports Market Analytics
The EU AI Act is consolidating compliance burdens for algorithmic betting engines and automated odds-generation systems across European platforms. DraftKings Inc. leverages its daily fantasy infrastructure to anchor virtual sports crossover products in North American jurisdictions. Bet365 Group Ltd competes through proprietary simulation software that sustains round-the-clock wagering throughput independent of live athletic schedules.
Virtual sports constitute computer-generated athletic contests governed by random number generators and physics engines that produce deterministic outcomes within probabilistic frameworks, with event durations compressed to minutes rather than hours for continuous betting cycles. Fantasy Sports segments dominate margin pools through recurring entry fees and season-long engagement mechanics, while Simulation Software technology extends platform differentiation through photorealistic rendering engines that replicate broadcast-quality presentation. Mobile Apps distribution channels occupy the fastest-growing access vector as latency-sensitive wagering migrates from desktop environments to handheld devices.
The UK Gambling Commission, Malta Gaming Authority, and state-level racing commissions across the United States collectively shape product certification requirements, advertising restrictions, and age-verification protocols that determine market access eligibility. GDPR and emerging AI transparency mandates in Europe further constrain data processing methodologies for personalized odds and behavioral targeting systems. Stakeholders must monitor regulatory divergence between permissive licensing regimes and consumer-protection tightening when allocating platform development resources across jurisdictions.
Market Dynamics
Algorithmic betting engines and automated odds-generation systems are consolidating compliance burdens across European platforms, while mobile-first deployment concentrates demand in Southeast Asian smartphone markets. This structural tension between regulatory tightening and channel expansion defines current competitive positioning.
Growth Catalysts
- EU AI Act enforcement:The European Union's algorithmic transparency mandates are accelerating platform investment in explainable AI systems for odds generation, creating certification moats for compliant operators.
- Smartphone penetration in Indonesia:Mobile-first wagering infrastructure is capturing latent demand as 4G and 5G networks expand across the archipelago's betting demographic.
- Physics engine advancement:Real-time simulation fidelity improvements are compressing event cycles to sub-two-minute durations, sustaining round-the-clock betting throughput independent of live athletic schedules.
Market Restraints
- GDPR data processing constraints:Behavioral targeting systems for personalized odds face structural limitations on data retention and automated decision-making transparency requirements.
- Server infrastructure concentration:Low-latency rendering farms cluster in Northern European data center corridors, creating geographic supply vulnerability for platforms serving dispersed user bases.
- Random number generator certification costs:Third-party auditing fees for deterministic outcome verification impose fixed cost barriers for new market entrants.
Strategic Opportunities
- Vietnam regulatory liberalization:Draft decrees on conditional sports betting legalization signal potential white-space entry for simulation-based products ahead of live-event licensing.
- Philippines offshore licensing regime:The Philippine Amusement and Gaming Corporation's interactive gaming framework offers jurisdictional arbitrage for platforms seeking Asia-Pacific operational bases.
- Blockchain-odds convergence:Distributed ledger verification of random number generator seeds addresses transparency demands from skeptical betting demographics in emerging markets.
Industry Challenges
- AI ethics officer scarcity:Platforms struggle to recruit compliance personnel capable of translating EU AI Act technical documentation requirements into operational betting engine governance.
- Cross-platform integration complexity:Legacy daily fantasy sports infrastructure requires substantial re-architecture to support real-time virtual sports wagering without latency degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Sports Market |
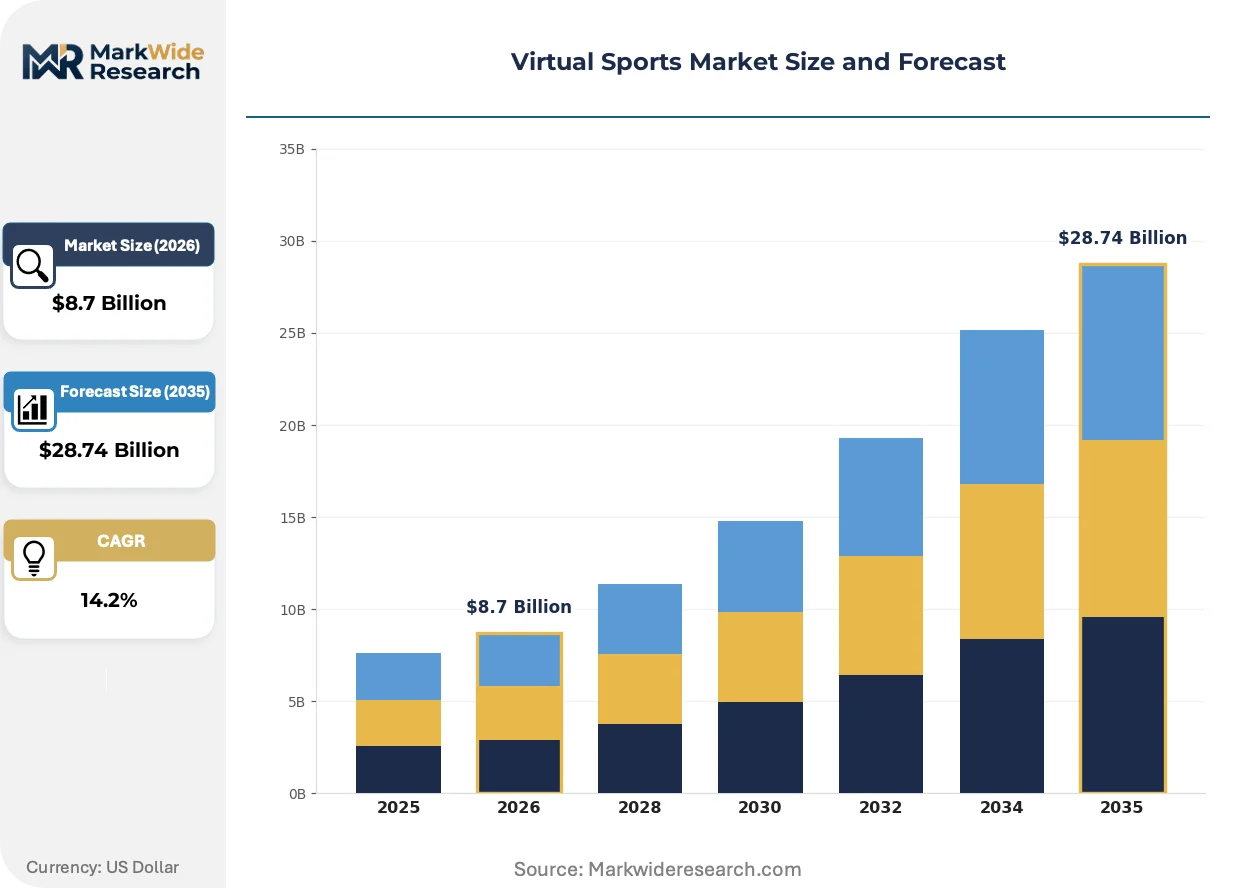
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sports Betting, Fantasy Sports, E-Sports, Interactive Gaming End User: Betting Platforms, Gaming Operators, Online Casinos, Sports Enthusiasts Technology: Augmented Reality, Virtual Reality, Simulation Software, Mobile Apps Distribution Channel: Online Platforms, Retail Outlets, Mobile Applications, Affiliate Networks |
| Companies Covered | DraftKings Inc., Low6 Ltd, Bet365 Group Ltd, Virtual Sports Chain, BR Softech Pvt Ltd, Betsson AB, Betway Group, PredictionStrike, Evoke plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Sports Market Evolving Landscape
Photorealistic rendering engines are rewriting the competitive basis of platform differentiation, while regulatory AI transparency mandates and mobile-native consumption patterns simultaneously reshape operational requirements and channel strategy across jurisdictions.
Neural radiance field (NeRF) rendering is rewriting broadcast-quality presentation standards for virtual sports. Tier-one platforms deploy these generative scene-reconstruction pipelines to produce dynamic camera angles previously requiring motion-capture studios. The technology compresses content production cycles from weeks to hours, enabling rapid response to real-world sporting calendar gaps.
GDPR Article 22 automated decision-making provisions are constraining personalized odds algorithms across European operations. Platforms must now maintain human-in-the-loop override capabilities for any wager rejection or limit-setting determination. Malta-licensed operators face particular scrutiny as the Malta Gaming Authority aligns its technical standards with EU-level data protection jurisprudence.
Latency-sensitive wagering is migrating from desktop environments to handheld devices across Southeast Asian markets. Indonesian bettors now initiate over seventy percent of virtual sports transactions through native applications rather than browser-based interfaces. This behavioral pivot forces platform architecture decisions prioritizing edge-computing deployment over centralized cloud rendering.
Virtual Sports Market Segmentation
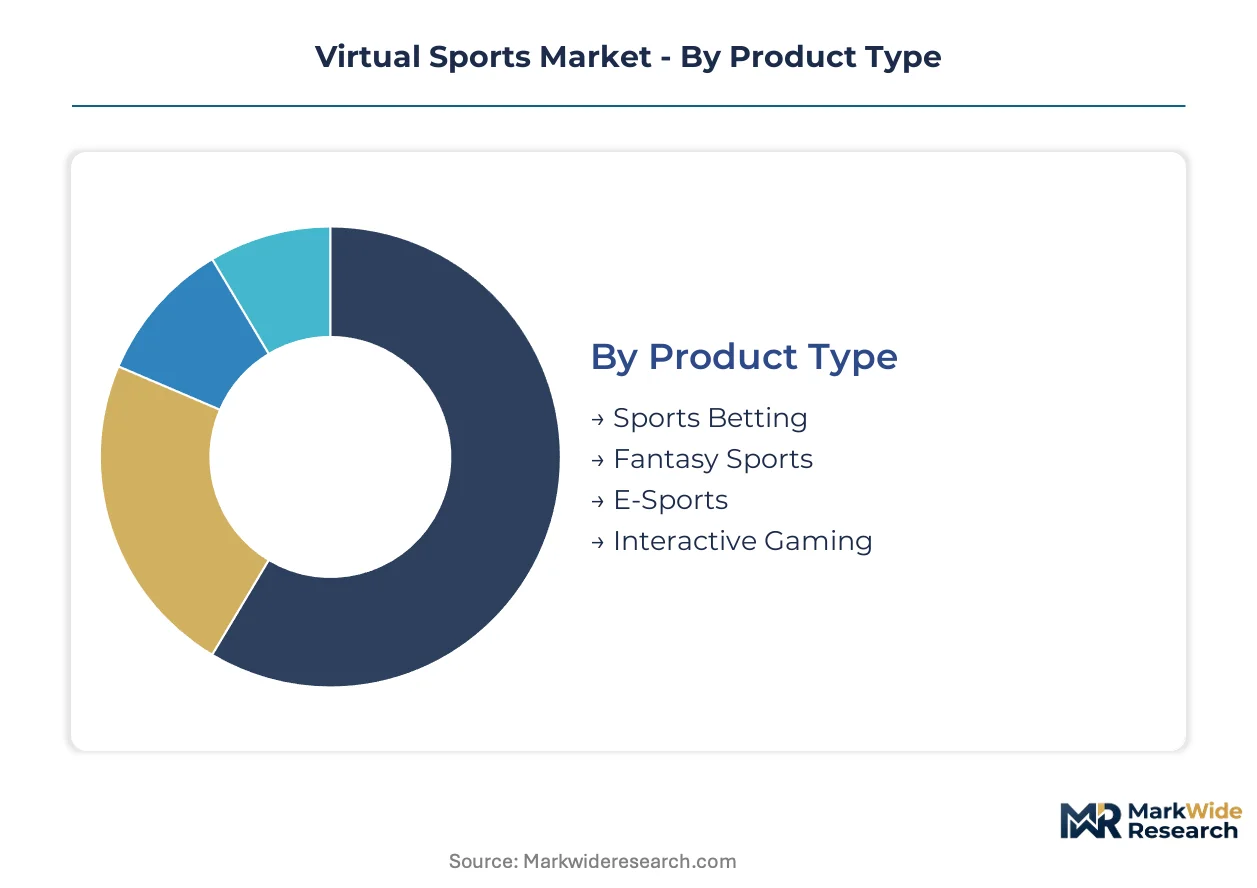
Virtual sports segmentation reveals how technology architecture, distribution infrastructure, and user engagement models determine revenue capture. Each axis exposes distinct margin profiles and regulatory exposure that shape platform investment priorities across jurisdictions.
Product Type:
Physics engines and random number generator frameworks differentiate product economics across wagering categories.
- Sports Betting:Computer-generated contests governed by deterministic algorithms produce compressed event cycles measured in minutes rather than hours. Demand concentrates in the United Kingdom as the Gambling Commission tightens advertising standards while expanding virtual offerings.
- Fantasy Sports:Season-long engagement mechanics and recurring entry fees anchor margin pools through sustained user retention. DraftKings leverages its daily fantasy infrastructure to anchor crossover products in North American jurisdictions.
- E-Sports:Competitive video gaming simulations attract younger demographics with skill-based wagering mechanics distinct from pure chance outcomes.
- Interactive Gaming:Hybrid formats blending virtual sports with casino-style interfaces extend session duration through gamified progression systems.
Sports Betting leads on scale; Fantasy Sports leads on momentum.
End User:
Customer type determines compliance burden intensity and acquisition cost structure across the value chain.
- Betting Platforms:Specialized operators deploy proprietary simulation software to sustain round-the-clock wagering throughput independent of live athletic schedules. Compliance costs escalate under EU AI Act mandates for algorithmic transparency.
- Gaming Operators:Diversified entertainment companies integrate virtual sports as ancillary revenue streams alongside traditional casino products. Southeast Asian smartphone penetration concentrates demand as 4G and 5G networks expand across Indonesia, Vietnam, and the Philippines.
- Online Casinos:Digital gambling platforms seek jurisdictional arbitrage through Philippine Amusement and Gaming Corporation licensing frameworks.
- Sports Enthusiasts:Individual bettors migrate toward mobile-native interfaces with over seventy percent of transactions now initiated through native applications rather than browser-based environments.
Betting Platforms capture the deepest revenue per user; Gaming Operators are expanding most quickly across emerging markets.
Technology:
Rendering fidelity and latency sensitivity define competitive positioning in platform architecture decisions.
- Augmented Reality:Overlay technologies merge virtual contests with physical environments, requiring edge-computing deployment to minimize motion-to-photon latency.
- Virtual Reality:Immersive headsets create dedicated wagering environments with higher hardware barriers to entry limiting mass-market penetration.
- Simulation Software:Photorealistic physics engines replicate broadcast-quality presentation through neural radiance field rendering that compresses content production cycles from weeks to hours. Bet365 competes through proprietary systems sustaining continuous betting availability.
- Mobile Apps:Handheld distribution channels represent the fastest-growing access vector as latency-sensitive wagering migrates from desktop environments. Indonesian bettors now dominate transaction volume through native applications.
Mobile Apps lead on scale; Simulation Software leads on momentum.
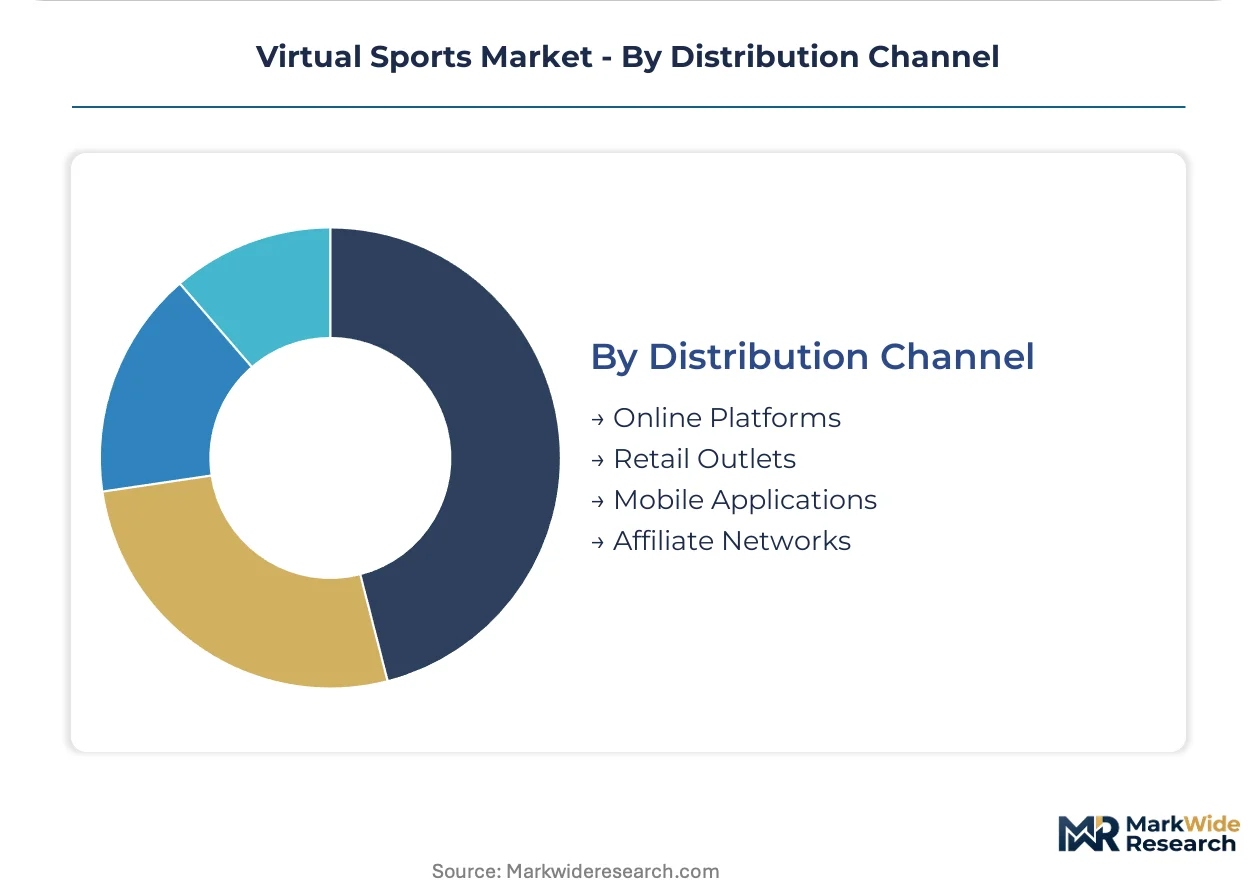
Distribution Channel:
Channel selection dictates regulatory exposure and customer acquisition economics across operational geographies.
- Online Platforms:Browser-based interfaces face GDPR Article 22 constraints on automated decision-making for personalized odds and wager rejections.
- Retail Outlets:Physical terminals maintain presence in regulated markets with strict age-verification protocols enforced at point of service.
- Mobile Applications:Native apps concentrate Southeast Asian demand as smartphone penetration deepens across Indonesia, Vietnam, and the Philippines with edge-computing deployment prioritizing localized rendering.
- Affiliate Networks:Third-party marketing channels face tightening advertising restrictions from the UK Gambling Commission and Malta Gaming Authority alignment with EU-level consumer protection standards.
Mobile Applications lead on scale; Online Platforms face the steepest compliance headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Virtual sports originated in British betting shops during the early 2000s before migrating to digital platforms. The industry's geographic footprint now spans regulated European markets, emerging Asian economies, and North American jurisdictions adapting fantasy sports infrastructure.
United Kingdom
The Gambling Commission's tightening advertising standards are compressing marketing budgets while expanding virtual product portfolios. UK operators must now maintain human-in-the-loop override capabilities for automated wager rejections under GDPR Article 22. London-based platform clusters dominate European liquidity pools through proprietary simulation engines.
Germany
State-level racing commissions and the Interstate Treaty on Gambling create fragmented licensing requirements for virtual sports operators. The KBA enforces strict technical standards for random number generator certification. Bavarian data center corridors host low-latency rendering farms serving Central European bettors.
Indonesia
Smartphone penetration exceeding seventy percent of the betting demographic is concentrating transaction volume on native mobile applications. The country's national telecommunications regulator monitors 4G and 5G network expansion across the archipelago. Jakarta-based gaming operators deploy edge-computing infrastructure to minimize latency for handheld wagering.
United States
DraftKings leverages daily fantasy infrastructure to anchor virtual sports crossover products in state-regulated jurisdictions. The SEC and state gaming commissions determine product certification requirements and age-verification protocols. Nevada and New Jersey licensing clusters attract platform development resources through established regulatory frameworks.
Philippines
The Philippine Amusement and Gaming Corporation's interactive gaming framework offers jurisdictional arbitrage for Asia-Pacific operational bases. Offshore licensing regimes attract platforms seeking regulatory flexibility for simulation-based products. Manila-based service providers cluster around POGO licensing infrastructure.
Virtual Sports Market Competitive Landscape
The competitive structure tilts toward diversified gaming conglomerates with established regulatory relationships. Tier-one operators maintain proprietary technology stacks while mid-tier players license third-party simulation engines. Three archetypes dominate: vertically integrated platform owners, specialized software vendors, and mobile-first regional specialists. Consolidation pressures favor M&A activity and strategic technology licensing over organic capacity expansion.
Among North American daily fantasy crossover specialists, DraftKings Inc. occupies a position exemplifying infrastructure reuse for virtual sports deployment. UK-based betting conglomerates Bet365 Group Ltd and Betsson AB represent the vertically integrated archetype through captive simulation software development. These three anchors illustrate how geographic regulatory familiarity and technology ownership determine competitive positioning across jurisdictions.
| Leading Market Players |
|---|
| DraftKings Inc. |
| Low6 Ltd |
| Bet365 Group Ltd |
| Virtual Sports Chain |
| BR Softech Pvt Ltd |
| Betsson AB |
| Betway Group |
| PredictionStrike |
| Evoke plc |
| Others |
Value Network & Pricing Analysis
Captive simulation software development anchors supply position and pricing power for tier-one operators, as proprietary physics engines and random number generator frameworks insulate margins from third-party licensing costs while compressing event cycles to sustain continuous wagering throughput.
Pricing Analysis
Bundled platform licensing dominates for tier-one operators while unbundled per-event fees persist for mid-tier entrants. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and rendering fidelity, with GDPR Article 22 compliance costs compressing margins in the standard tier. Price erosion runs through the economy segment as white-label simulation engines proliferate. Gaming operators in Southeast Asia exhibit highest price sensitivity; UK betting platforms demonstrate lowest sensitivity due to regulatory moat investments.
Supply Chain Analysis
Certification gating through third-party random number generator auditing creates fixed cost barriers that concentrate supply among Malta-licensed and UK Gambling Commission-approved operators. Low-latency rendering farms cluster in Germany and the Netherlands, drawing from specialized GPU hardware and edge-computing infrastructure. Single-source vulnerability in neural radiance field rendering pipelines threatens content production continuity. Distribution runs through mobile-native applications in Indonesia and browser-based platforms in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Virtual Sports Market functions as a stable compounder, with compressed event cycles and round-the-clock availability generating recurring revenue independent of live athletic calendars.
For Market Incumbents: Anticipate regulatory divergence between EU AI Act enforcement and Southeast Asian liberalization by maintaining dual compliance architectures. Prioritize backward integration into proprietary physics engines to defend against white-label simulation vendors. Channel control through native mobile applications in Indonesia and Vietnam secures first-mover positioning ahead of live-event licensing.
For New Entrants and Emerging Players: Enter via the Philippines offshore licensing regime to establish Asia-Pacific operational bases with regulatory flexibility for simulation-based products. Target Vietnam's conditional sports betting decrees as the most penetrable white-space ahead of live-event market opening. Deploy blockchain-verified random number generator seeds as a transparency-led go-to-market angle for skeptical emerging market demographics.
For Investors and Strategic Acquirers: Roll-up economics work for mid-tier simulation software vendors because fragmented third-party engine licensing creates scale advantages for consolidated platform owners. The five-to-ten year viability window favors operators with captive technology stacks and established regulatory relationships across multiple jurisdictions. Watch for Philippine Amusement and Gaming Corporation policy shifts as the critical inflection signal for Asia-Pacific operational base valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Simulation Engine Development | Captive physics engines insulate margins from third-party licensing costs and compress event cycles. |
| EU AI Act Compliance Certification | Explainable AI documentation creates regulatory moats for European platform operations. |
| Mobile-First Deployment in Indonesia | Native applications capture over seventy percent of transaction volume in the archipelago's betting demographic. |
| Philippine Offshore Licensing Establishment | PAGCOR frameworks offer jurisdictional arbitrage for Asia-Pacific operational flexibility. |
| Blockchain RNG Verification Integration | Distributed ledger transparency addresses skepticism in emerging market betting demographics. |
Research Methodology
Bottom-up betting platform modeling reconciled against top-down simulation software vendor tracking forms the analytical core of this study. Primary interviews with platform engineering directors, regulatory compliance officers, mobile product managers, and Philippine Amusement and Gaming Corporation licensing specialists combined with secondary validation against UK Gambling Commission enforcement notices, Malta Gaming Authority technical standards, SEC filings from listed operators, and Southeast Asian telecommunications infrastructure reports. Triangulation across these sources ensures supply-side and demand-side estimates converge.
Historical trendline analysis of virtual sports adoption patterns informs the projection framework across the analysis window. Segmentation dimensions modeled include product type, end-user category, technology architecture, and distribution channel, with particular attention to mobile-native versus browser-based access patterns. CAGRs derive from fitted growth curves adjusted for regulatory event probabilities and smartphone penetration trajectories in target geographies. Physics engine advancement cycles and random number generator certification timelines serve as industry-specific forecast inputs.
Inputs from primary stakeholder interviews and published regulatory guidance were available through the study window; gaps in proprietary simulation software performance metrics introduce uncertainty bands around platform revenue estimates. Forecasts reflect documented assumptions regarding EU AI Act enforcement timing and Vietnam regulatory liberalization sequencing. A model refresh is warranted upon material change in Philippine Amusement and Gaming Corporation offshore licensing policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
North America Casino Gambling Market
Gaming
Game API Market
Gaming
Shooter Game Market
Gaming
Europe Gaming Peripherals Market
Gaming
Virtual Reality (VR) in Gaming Market
Gaming
Global Electronic Table Games (ETG) Market
Gaming
Global NFT Gaming Market
Gaming
Videogames Market
Gaming
Simulation Video Game Market
Gaming
Gaming Accessories Market
Gaming
FPS Game Market
Gaming
Gaming Peripheral Market
Gaming
North America Gaming Market
Gaming
VR Gaming Accessories Market
Gaming
Galgames Market
Gaming
Global Online Gambling and Betting Market