
 Pet Food Processing Market | 2026-2036
Pet Food Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Food Processing Market Analysis
North American co-manufacturer capacity is restructuring around allergen-segregated lines and cold-extrusion suites. ANDRITZ AG leverages its Austrian engineering base to dominate high-capacity extrusion systems for dry food volumes. Bühler Group sustains technology leadership through integrated grinding-to-packaging workflows. The Middleby Corporation competes via its portfolio of thermal processing brands serving mid-tier co-packers.
Pet food processing encompasses the mechanical and thermal transformation of meat, grain, vegetable, and fruit inputs into shelf-stable nutrition products, typically achieving moisture targets below 10 percent for dry formats and sterility standards for wet retort applications. The primary commercial purpose centers on converting raw agricultural commodities into palatable, nutritionally complete formats that withstand distribution through retail, wholesale, and online channels. Extrusion equipment anchors the largest installed base due to its throughput economics in dry food production, while freeze-drying commands the fastest expansion as premium treat lines multiply. Wet food canning retains mature margin pools tied to entrenched supply contracts with supermarket private-label programs.
FDA Center for Veterinary Medicine oversight of ingredient safety and AAFCO nutrient profiles shapes formulation compliance costs across United States facilities. EPA discharge permits constrain rendering and wastewater outputs from high-volume plants in the Midwest and Southeast. USDA-FSIS residue testing for meat-derived inputs determines supplier qualification protocols. Stakeholders must monitor evolving state-level packaging waste regulations and decide between capital-intensive line retrofits or outsourced toll manufacturing relationships.
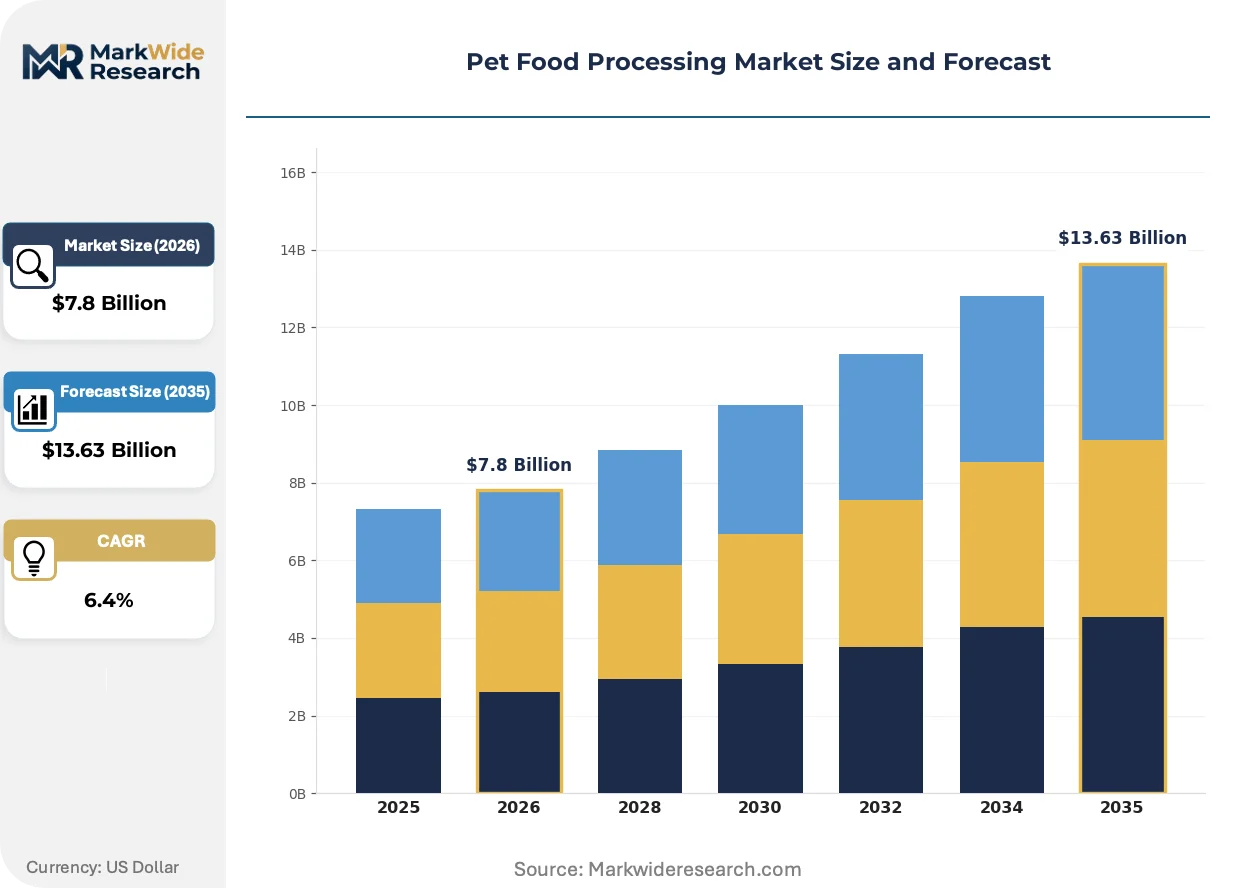
Market Dynamics
Equipment manufacturers face pressure from co-manufacturers demanding allergen-segregated lines and cold-extrusion capabilities that premium pet food brands require for clean-label positioning.
Growth Catalysts
- AAFCO Nutrient Profiles:FDA-aligned state enforcement of complete-and-balanced standards forces facility upgrades across commercial kennels and veterinary clinics, expanding replacement demand for extrusion and thermal processing equipment.
- Freeze-Drying Technology:Premium treat manufacturers adopt lyophilization systems to capture raw nutrition positioning, driving fastest-expanding equipment category within processing portfolios.
- China Domestic Capacity Expansion:Indigenous pet food brands build manufacturing footprint to reduce import dependency, concentrating new equipment orders with extrusion and packaging line suppliers.
Market Restraints
- Rendering Input Volatility:Meat and poultry byproduct pricing fluctuates with livestock cycle swings, compressing margin predictability for wet food canning operations dependent on protein slurry supply contracts.
- EPA Discharge Constraints:Midwest and Southeast high-volume plants face wastewater permit limitations that cap throughput expansion without costly tertiary treatment infrastructure.
- Retort Sterilization Bottlenecks:Wet food canning lines require extended thermal processing cycles that constrain output velocity versus dry extrusion economics.
Strategic Opportunities
- India Manufacturing Emergence:Underpenetrated processing infrastructure creates first-mover positioning for extrusion system providers as FSSAI pet food standards formalize and domestic brands scale.
- Smart Factory Integration:Convergence of IoT sensors with extrusion control systems enables real-time moisture and density optimization, reducing giveaway and energy intensity.
- Veterinary Prescription Channel:Therapeutic diet co-manufacturing contracts expand as clinics seek captive supply relationships for renal, diabetic, and allergy-formulated products.
Industry Challenges
- Extrusion Engineering Talent Scarcity:Specialized knowledge of screw configuration, die design, and thermal profile optimization concentrates with aging workforce cohorts in European equipment headquarters.
- Legacy System Integration Complexity:Brownfield facilities face control architecture mismatches when retrofitting Industry 4.0 monitoring onto 1990s-vintage mechanical extrusion lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Food Processing Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Supplements Ingredient Type: Meat, Grain, Vegetables, Fruits Processing Method: Extrusion, Baking, Canning, Freeze-Drying End User: Retailers, Wholesalers, Online Stores, Supermarkets |
| Companies Covered | ANDRITZ AG, Bühler Group, The Middleby Corporation, GEA Group, Baker Perkins, Clextral S.A.S, Coperion GmbH, Mepaco Group, F.N. Smith Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Food Processing Market Emerging Trajectories
Cold-extrusion and freeze-drying technologies are compressing traditional thermal processing dominance as pet owners reject high-temperature degradation of micronutrients in premium positioning.
High-pressure processing (HPP) for raw and fresh pet food formats is decentralizing production geography by enabling shelf-stable distribution without retort infrastructure. Regional co-manufacturers in secondary markets adopt HPP tolling to serve local fresh pet food brands. This technology is decentralizing capacity concentration away from Midwest rendering corridors toward distributed urban production nodes.
EU Green Deal packaging waste directives and impending extended producer responsibility frameworks force reformulation of multi-layer flexible films. Wet food canners face laminate redesign costs to meet recyclability mandates. The private-label supermarket segment bears highest compliance burden given volume scale and thin margin structures.
Subscription direct-to-consumer models now capture significant share of premium dry food and treat sales, disintermediating traditional wholesale distributor relationships. Specialty retailers respond with private-label exclusives and in-store fresh grinding stations. This channel rotation is most advanced in US coastal metropolitan markets where pet humanization indices peak.
Pet Food Processing Market Segmentation
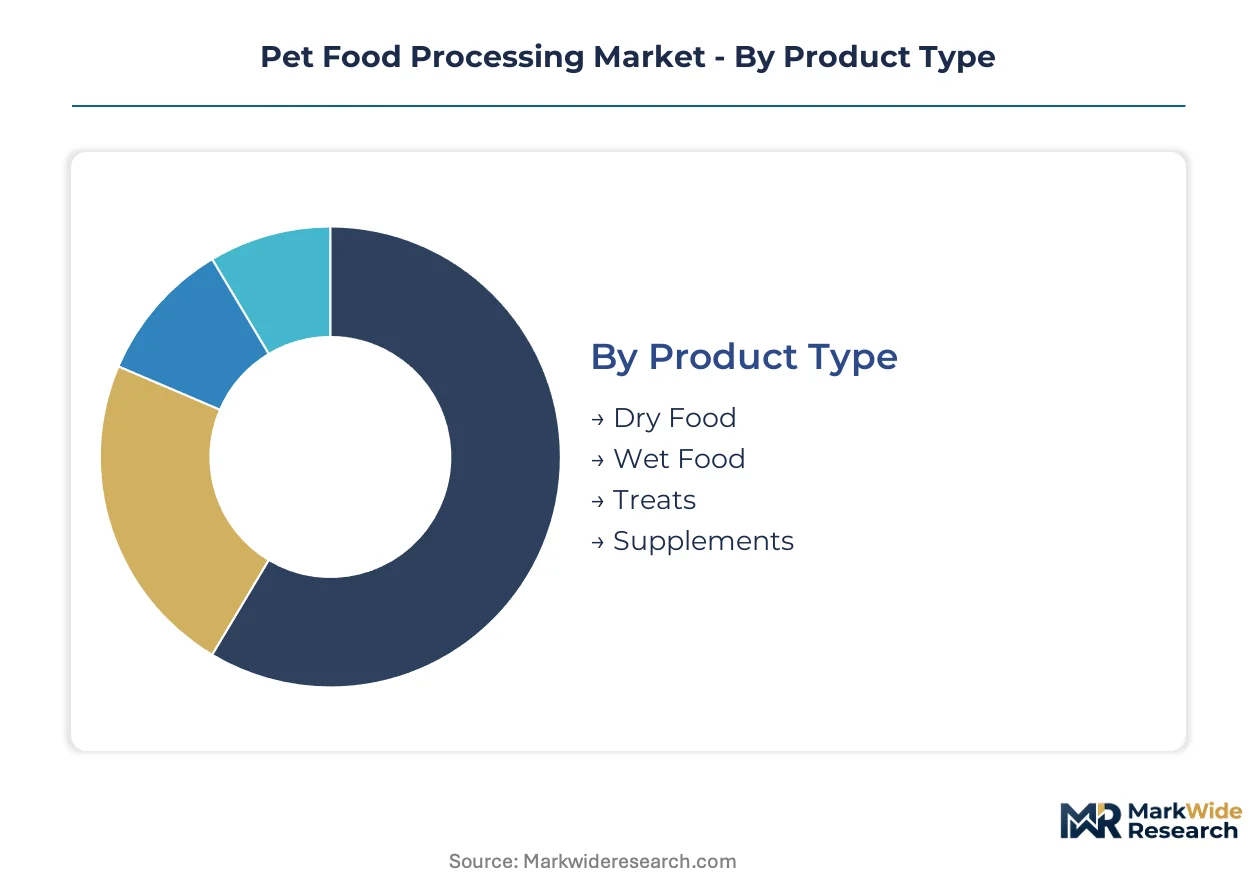
Equipment procurement and facility design diverge sharply across product formats, with extrusion-dominant dry lines demanding continuous-flow capital while wet canning requires batch-sterilization infrastructure. Ingredient handling protocols further stratify investment, as meat-rendering integration contrasts with grain-milling simplicity.
Product Type:
Premiumization intensity dictates equipment sophistication, with human-grade positioning forcing segregated processing environments and cold-extrusion capabilities.
- Dry Food:Extrusion systems achieve moisture targets below 10 percent through high-pressure thermal processing, with screw configuration and die geometry determining kibble density and palatability. Demand concentrates in Midwest US rendering corridors where integrated meat-meal supply chains minimize input logistics costs. FDA-aligned AAFCO complete-and-balanced enforcement drives continuous line upgrades across commercial kennels.
- Wet Food:Retort canning lines subject meat slurry formulations to extended thermal sterilization cycles achieving commercial sterility, with laminate pouch and tray formats displacing traditional metal cans in premium positioning. Supermarket private-label contracts anchor mature margin pools in the US Southeast, though EPA discharge permits constrain Midwest throughput expansion without tertiary wastewater treatment.
- Treats:Freeze-drying and cold-extrusion formats command equipment premium for raw nutrition positioning.
- Supplements:Tablet-coating and powder-blending lines serve veterinary prescription channels with low-volume, high-SKU flexibility.
Dry Food leads on scale; Treats lead on momentum.
Ingredient Type:
Supply security and price volatility shape sourcing strategy, with rendering integration determining wet food economics versus grain-milling simplicity in dry formats.
- Meat:USDA-FSIS residue testing protocols govern supplier qualification for poultry, beef, and fish derivatives, with rendering facility proximity determining logistics costs for high-volume wet canners. China domestic brands accelerate captive rendering investments to reduce import dependency.
- Grain:Corn, wheat, and rice inputs flow through integrated grinding-to-extrusion workflows with established mycotoxin testing protocols.
- Vegetables:Sweet potato and pea protein formulations require modified extrusion thermal profiles to preserve carbohydrate integrity.
- Fruits:Cranberry and blueberry inclusions concentrate in premium treat applications with limited processing complexity.
Meat commands the steepest expansion trajectory as fresh and raw positioning gains share; Grain retains volume dominance in economy formulations.
Processing Method:
Throughput economics versus nutrient preservation creates technology selection tension, with thermal intensity inversely correlated with premium positioning.
- Extrusion:High-capacity twin-screw systems dominate dry food production, with real-time moisture and density optimization via IoT-enabled control systems reducing giveaway and energy intensity. ANDRITZ AG and Bühler Group anchor European engineering concentration for screw configuration expertise.
- Freeze-Drying:Lyophilization preserves raw nutrition integrity for premium treat lines, with batch cycle economics limiting scale versus continuous extrusion.
- Baking:Oven-based processing serves niche natural positioning with lower capital barriers.
- Canning:Retort sterilization bottlenecks constrain output velocity versus dry extrusion economics.
Extrusion leads on scale; Freeze-Drying leads on momentum.
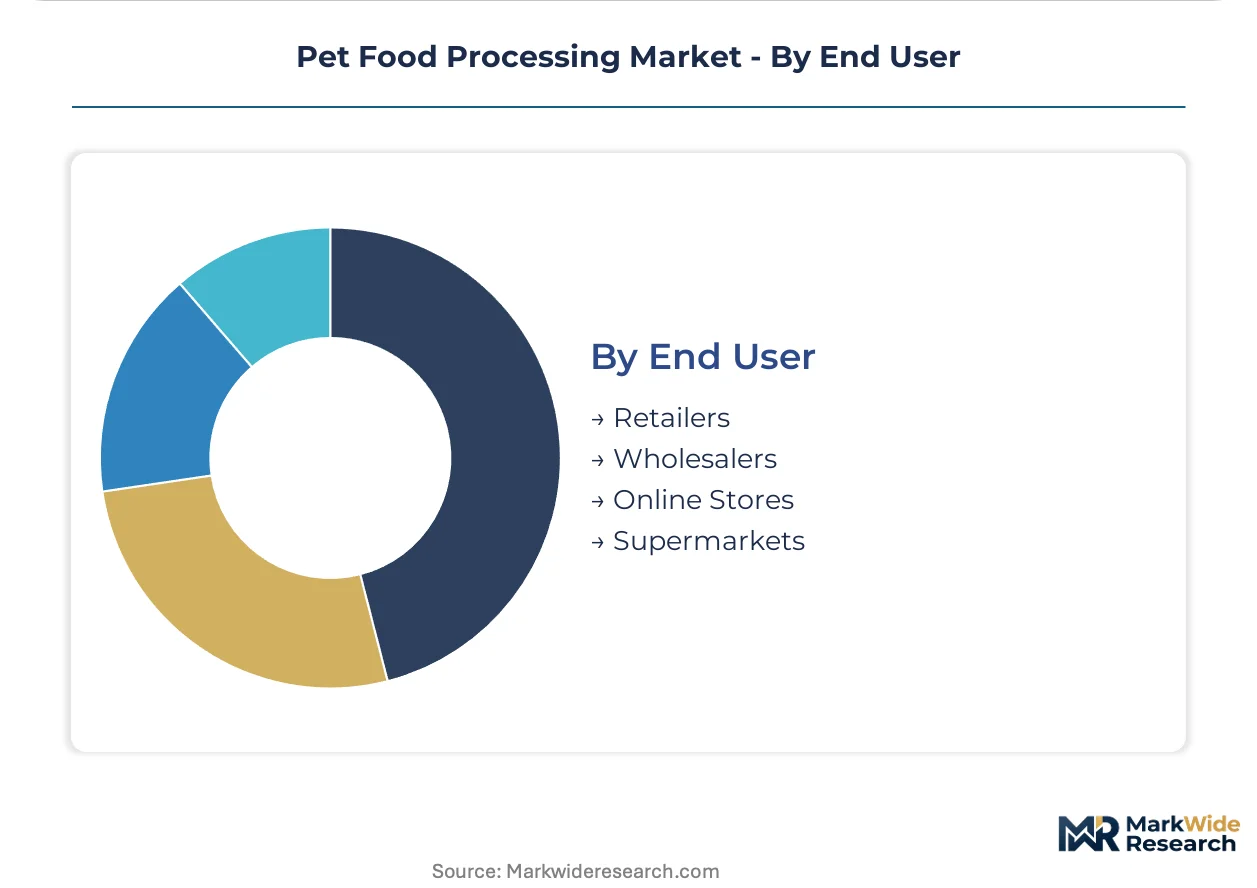
End User:
Channel control and margin capture determine co-manufacturer contract structures, with direct-to-consumer disintermediation reshaping traditional wholesale relationships.
- Online Stores:Subscription models capture premium dry food and treat sales, demanding flexible packaging lines for customized portion configurations. US coastal metropolitan markets show most advanced channel rotation where pet humanization indices peak.
- Supermarkets:Private-label programs anchor wet food volume with entrenched supply contracts, though EU Green Deal packaging waste directives force multi-layer laminate redesign costs.
- Retailers:Specialty pet chains respond with exclusive private-label sourcing and in-store fresh grinding stations.
- Wholesalers:Traditional distributor relationships face compression as brands pursue direct fulfillment.
Supermarkets lead on scale; Online Stores lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where pet food processing capacity locates, with manufacturers migrating toward jurisdictions offering streamlined compliance pathways while maintaining export access to premium markets. Cost-of-compliance gaps between established and emerging regulatory regimes drive investment flows.
United States
Commercial kennel and veterinary clinic equipment upgrades accelerate under FDA-aligned AAFCO enforcement. EPA discharge permits constrain Midwest rendering corridor expansion, pushing new capacity toward Southeast states with tertiary wastewater infrastructure. Kansas and Iowa maintain dense meat-meal supply integration for dry food extrusion economics.
China
Domestic pet food brands build captive manufacturing to reduce import dependency, concentrating equipment orders with extrusion and packaging suppliers. SAMR food safety standards tighten ingredient traceability requirements. Yangtze River Delta cities host fastest capacity buildout as indigenous brands scale production.
Germany
EU Green Deal packaging waste directives force wet food canners toward recyclable laminate redesign. Engineering expertise for high-capacity extrusion systems concentrates in Baden-Württemberg. Bavaria-based equipment fabricators supply integrated grinding-to-packaging workflows across European co-manufacturers.
India
FSSAI pet food standards formalization triggers first-mover positioning for extrusion system providers. Underpenetrated processing infrastructure creates greenfield opportunities as domestic brands emerge. Maharashtra and Gujarat industrial corridors attract initial manufacturing investments from indigenous label owners.
Brazil
Rendering input availability from livestock processing supports wet food canning economics. ANVISA veterinary product oversight shapes import substitution strategies for equipment procurement. São Paulo state anchors co-manufacturer development serving Latin American private-label programs.
Pet Food Processing Market Vendor Landscape
European producers anchor the premium engineering tier; North American specialists hold mid-tier co-packer service positions. Market structure concentrates around three to five integrated equipment families with established rendering-to-packaging workflows. Strategic archetypes include full-line integrators, thermal processing specialists, and regional fabrication houses serving discrete unit operations. Dominant competitive moves center on allergen-segregated line retrofits and cold-extrusion capability additions.
Among European-headquartered engineering groups, ANDRITZ AG exemplifies the high-capacity extrusion archetype through its Austrian engineering base. Bühler Group occupies a position within full-line integration, spanning grinding-to-packaging workflows. The Middleby Corporation represents the North American mid-tier vector through its portfolio of thermal processing brands serving co-packer channels.
| Leading Market Players |
|---|
| ANDRITZ AG |
| Bühler Group |
| The Middleby Corporation |
| GEA Group |
| Baker Perkins |
| Clextral S.A.S |
| Coperion GmbH |
| Mepaco Group |
| F.N. Smith Corporation |
| Others |
Supply Flow & Price Mechanics
Extrusion engineering expertise concentration in Baden-Württemberg and Upper Austria feeds labor-cost differentials that widen pricing-tier spreads between European-engineered premium lines and Asian-fabricated standard equipment.
Pricing Analysis
Distributor margin layers in wet food canning equipment compress as supermarket private-label contracts consolidate procurement volumes. Three-tier pricing structure across premium, standard, and economy levels separates cold-extrusion systems with IoT integration from mechanical legacy lines. Price differentiation hinges on AAFCO-compliant certification tiers and after-sales service bundling. Cost compression in mid-tier thermal processing is intensifying because co-manufacturers demand allergen-segregated line retrofits without commensurate budget expansion. Veterinary prescription channels show least price sensitivity due to captive supply relationships.
Supply Chain Analysis
Regional distribution centers in Kansas and Iowa anchor hub-and-spoke patterns for meat-meal inputs serving Midwest dry food corridors. Manufacturing concentration spans Austria, Germany, and China for extrusion system fabrication. Raw material dependencies include specialty steel alloys for screw configurations, precision die castings, and servo-drive control modules. Single-source vulnerability concentrates in European engineering talent pools for thermal profile optimization. Distribution runs through co-manufacturer networks with integrated rendering-to-packaging workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EPA discharge permit constraints in the US Midwest widen cost differentials against Southeast states with tertiary wastewater infrastructure.
For Market Incumbents: Anchor defensive positioning through backward integration into captive rendering facilities and cold-extrusion capability additions that emerging Asian fabricators cannot replicate. Deepen channel control by locking veterinary prescription co-manufacturing contracts before clinic networks consolidate procurement. Prioritize certification investment in AAFCO-aligned complete-and-balanced validation to raise compliance barriers against mid-tier competitors. For New Entrants and Emerging Players: Capture white-space in India greenfield extrusion deployments as FSSAI standards formalize and domestic brands scale manufacturing footprints. Target wet food canning tolling capacity in secondary US markets where EPA constraints have capped incumbent expansion. Pursue go-to-market angles through high-pressure processing equipment leasing for urban fresh pet food brands seeking distributed production nodes. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabrication houses serving discrete unit operations with limited cold-extrusion or IoT integration capabilities. Long-term viability over the projection horizon favors acquisition of full-line integrators with established grinding-to-packaging workflows. Watch freeze-drying equipment order backlogs as the inflection signal for premium treat line capital deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Allergen-Segregated Line Retrofit | Enables AAFCO-compliant clean-label positioning for premium co-manufacturers. |
| Cold-Extrusion Capability Addition | Preserves micronutrient integrity for raw nutrition market positioning. |
| IoT-Enabled Control System Integration | Reduces energy intensity and giveaway through real-time moisture optimization. |
| Captive Rendering Investment | Secures protein slurry supply chains against livestock cycle volatility. |
| Veterinary Prescription Channel Lock-In | Captures therapeutic diet co-manufacturing contracts with clinic networks. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining equipment manufacturer executives, co-manufacturer operations directors, veterinary clinic procurement managers, and rendering facility supply chain leads with secondary validation. Sources include FDA Center for Veterinary Medicine filings, AAFCO nutrient profile databases, EPA discharge permit records, and customs data on extrusion equipment trade flows. Bottom-up and top-down triangulation cross-validates equipment shipment volumes against facility capacity buildout announcements.
Rate-of-change decomposition separates volume growth from price-mix effects across the modeling period. Segmentation dimensions include product format, processing method, ingredient type, and end-user channel with regional regulatory cluster overlays. CAGRs derive from equipment order backlogs, facility investment pipelines, and replacement cycle analysis. Forecast inputs incorporate AAFCO enforcement timelines and China domestic capacity expansion trajectories.
Underlying measurement precision varies by segment; dry food extrusion equipment carries tighter precision than emerging freeze-drying categories. Forecasts reflect assumptions around regulatory enforcement intensity and protein input cost stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Batter Mixer Machines Market
Food Processing Equipment
Food Waste Shredder Market
Food Processing Equipment
Commercial Mixer Market
Food Processing Equipment
Spray Dryer Market
Food Processing Equipment
Aseptic Processing Market
Food Processing Equipment
Global Food and Beverage Coding and Marking Equipment Market
Food Processing Equipment
USA Commercial Walk-In Refrigeration Market
Food Processing Equipment
Commercial Oven for Bakery Market
Food Processing Equipment
De-Agglomerating Equipment Market
Food Processing Equipment
Global Starch Recovery Systems Market
Food Processing Equipment
Pasty Products Filling Machine Market
Food Processing Equipment
Hot Food Processing Equipment Market
Food Processing Equipment
Pulp Washing Equipment Market
Food Processing Equipment
North America Cold Storage Market
Food Processing Equipment
Spray Drying Market
Food Processing Equipment
Water Pod Soluble Machines Market